
 Wound Closure Market | 2026-2036
Wound Closure Market Size, Share, and Industry Trends Forecast 2026-2036
Wound Closure Market Analysis
The EU Medical Device Regulation is expanding compliance requirements for wound closure products sold across European member states. Johnson & Johnson Services, Inc. leverages its broad sutures portfolio to sustain leadership in acute care settings. Medtronic anchors its position through integrated surgical workflow solutions that bundle closure with energy devices. Baxter competes via specialized hemostasis and sealant technologies that reduce operating room time.
Wound closure encompasses mechanical and adhesive methods for approximating tissue edges to enable healing by primary intention, utilizing materials ranging from braided polyglactin to cyanoacrylate formulations with specified tensile strength retention profiles. Sutures retain the largest revenue share due to universal surgical applicability and established reimbursement pathways, while adhesives represent the fastest-expanding segment driven by demand for needleless closure in cosmetic and pediatric applications. Ambulatory surgical centers are reshaping volume distribution as same-day procedures shift closure product specifications toward faster application and reduced follow-up requirements.
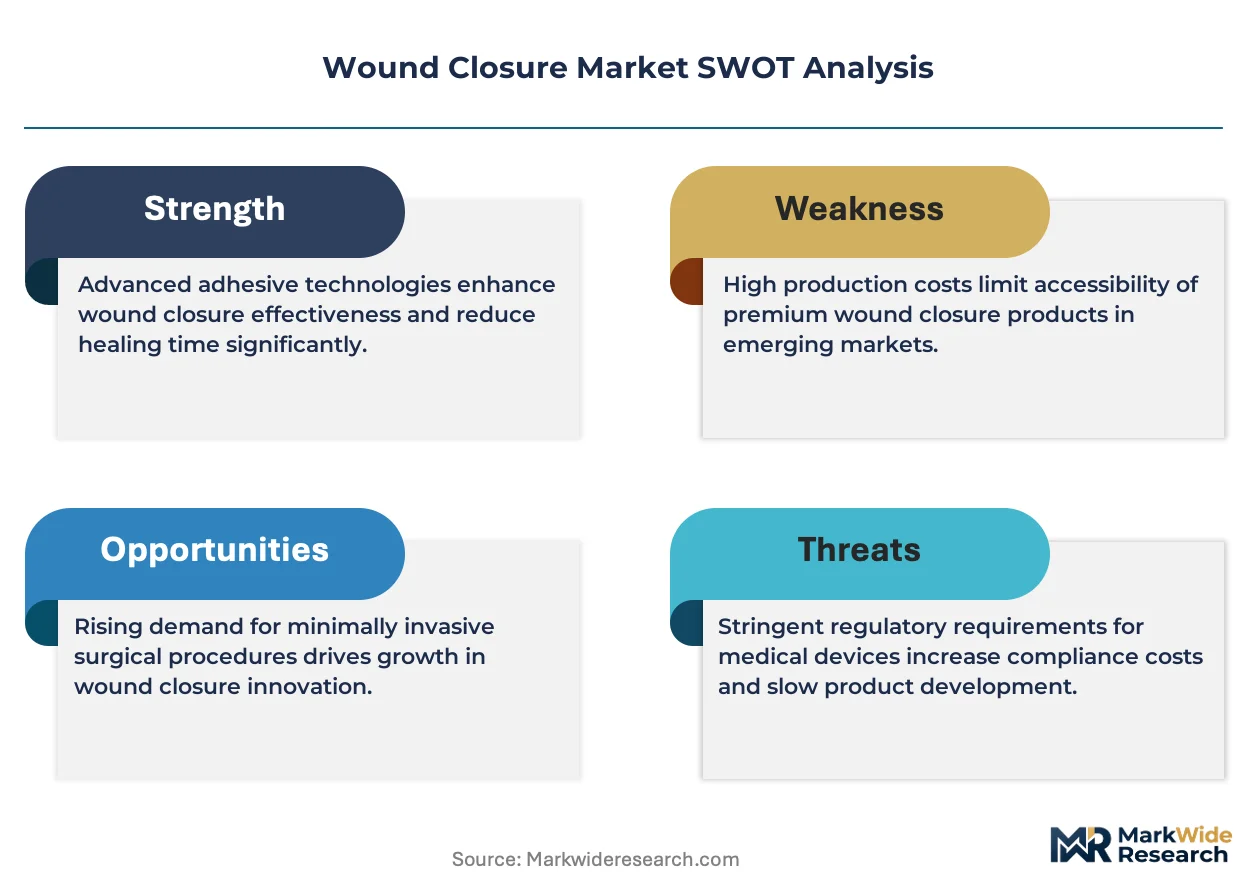
The FDA enforces biocompatibility testing under ISO 10993 for all implantable wound closure devices, while the EU MDR mandates updated clinical evidence and unique device identification for market access renewal. Health Canada and Japan's PMDA maintain parallel but distinct approval frameworks that create incremental compliance costs for multi-region suppliers. Stakeholders must monitor evolving sterilization validation requirements and antimicrobial coating standards as regulators tighten post-market surveillance expectations.
Market Dynamics
Ambulatory surgical centers are compressing closure product specifications toward faster application times and reduced follow-up protocols, forcing manufacturers to redesign sutures and sealants for same-day discharge workflows.
Growth Catalysts
- FDA 510(k) pathway modernization:Streamlined premarket notification for antimicrobial-coated sutures accelerates commercialization timelines for US-based manufacturers targeting hospital outpatient departments.
- Ambulatory surgery volume migration:Medicare reimbursement expansion for same-day procedures in freestanding ASCs creates dedicated demand for needleless adhesive closure systems.
- Bioabsorbable polymer innovation:Next-generation polyglactin formulations with predictable tensile strength degradation profiles reduce foreign body reaction rates in pediatric dermatological applications.
Market Restraints
- Raw material concentration:Polyglycolic acid precursor supply concentrates among three specialty chemical manufacturers in Germany and Japan, exposing converters to input volatility.
- EU MDR clinical evidence burden:Updated technical documentation requirements for Class IIa implantable devices extend renewal timelines and inflate regulatory compliance costs for European market access.
- Substitute modality encroachment:Energy-based vessel sealing devices in laparoscopic procedures reduce suture utilization per case in gynecologic and general surgery segments.
Strategic Opportunities
- Underpenetrated veterinary surgery:Companion animal orthopedic and soft-tissue procedures in Brazil and Mexico utilize commodity-grade sutures with margin expansion potential for USP-compliant product lines.
- Antimicrobial coating mandates:Joint Commission surgical site infection reduction protocols in US acute care hospitals create procurement preference for triclosan-impregnated and silver-ion-embedded closure materials.
- Remote wound monitoring integration:Convergence of absorbable sutures with wireless pH-sensing substrates enables post-discharge healing surveillance via smartphone-connected platforms.
Industry Challenges
- Polymer synthesis expertise scarcity:Specialized knowledge in glycolide-lactide copolymerization kinetics concentrates among retiring cohorts at legacy materials science programs.
- Gamma sterilization validation bottlenecks:ISO 11137 dose mapping requirements for bioresorbable devices extend batch release timelines and constrain contract sterilizer capacity allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wound Closure Market |
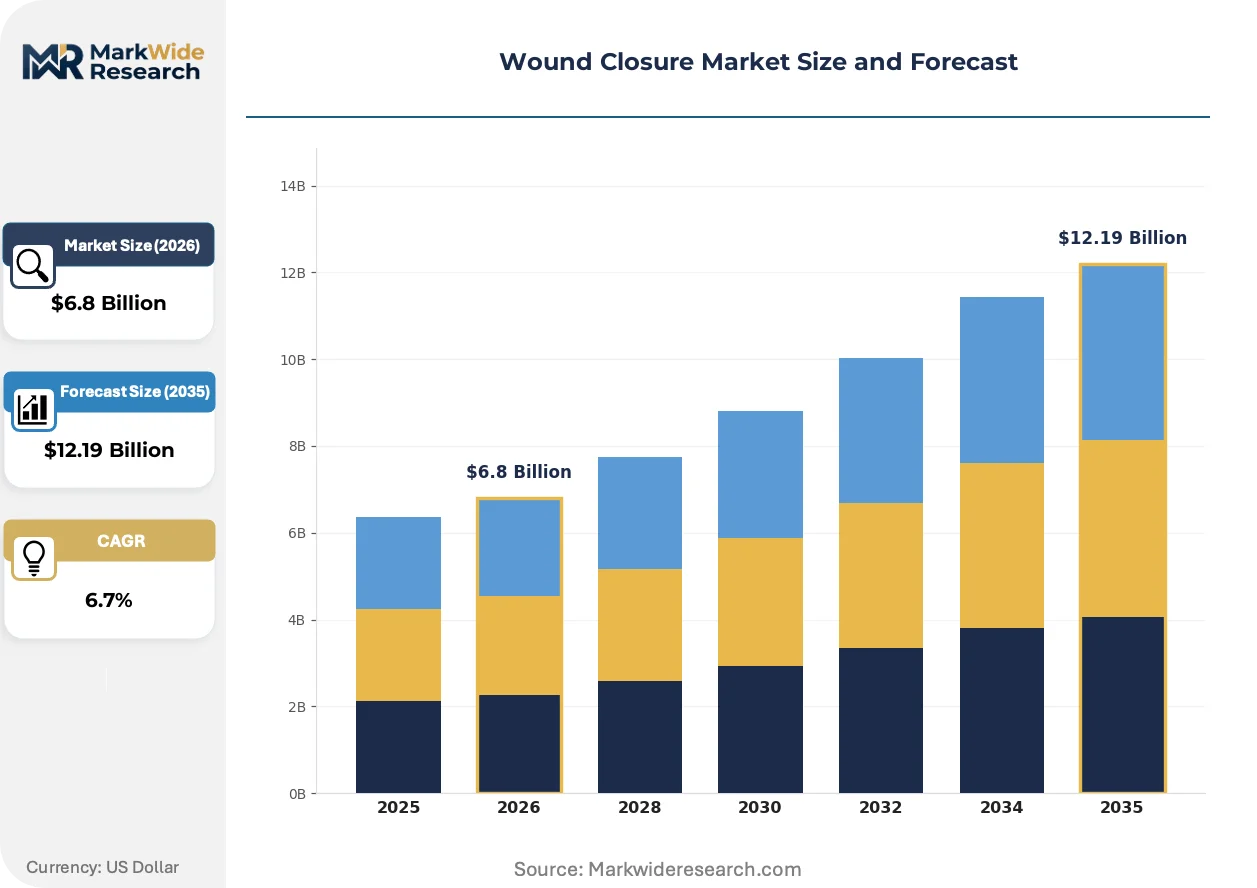
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.19 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sutures, Adhesives, Staples, Dressings Technology: Electrostatic, Photochemical, Biochemical, Thermal End User: Hospitals, Clinics, Home Healthcare, Ambulatory Surgical Centers Application: Trauma, Surgical Wounds, Chronic Wounds, Cosmetic Procedures |
| Companies Covered | Johnson & Johnson Services, Inc., Medtronic, 3M, B. Braun Melsungen AG, Baxter, Smith & Nephew, Stryker, Corza Health, Solventum, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wound Closure Market Emerging Trajectories
Needleless tissue adhesive platforms are displacing mechanical closure in cosmetic and pediatric niches, while regulatory bodies tighten biocompatibility surveillance and procurement centralization reshapes vendor access.
Octyl-2-cyanoacrylate formulations with flexible, high-tensile bond characteristics are consolidating market position in facial laceration repair and minimally invasive incision closure. Dermatology and plastic surgery clinics in the United States and South Korea are adopting these adhesives at accelerating rates for procedures where suture marks compromise aesthetic outcomes. The technology is consolidating demand around single-application dispensers that eliminate needlestick risk and reduce operating room turnover time.
The EU Medical Device Regulation's expanded post-market surveillance requirements for implantable devices are forcing systematic clinical follow-up studies and periodic safety update reporting. Manufacturers must now maintain active implant registries and submit benefit-risk reassessments to notified bodies at defined intervals. Class IIa suture and mesh products face the steepest compliance burden, with mid-cap suppliers diverting R&D budgets toward regulatory infrastructure rather than pipeline expansion.
Hospital system consolidation in the United States is compressing vendor panels and standardizing closure product formularies across multi-facility networks. Group purchasing organizations are bundling sutures, sealants, and hemostats into single-source contracts with price-volume tiers tied to system-wide spend commitments. This concentration is most visible in the Southeast and Midwest, where Catholic health initiatives and for-profit chains have absorbed independent community hospitals and imposed centralized procurement protocols.
Wound Closure Market Segmentation
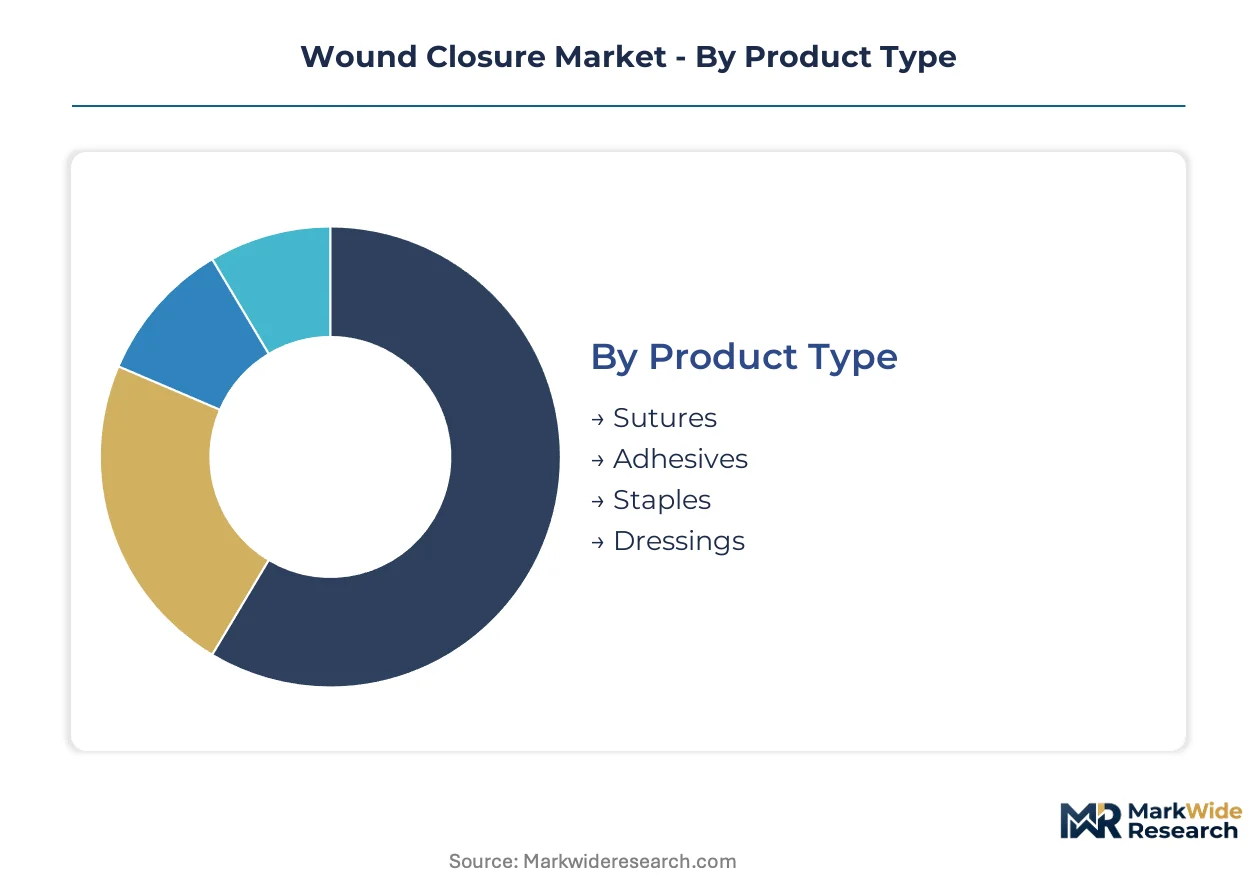
Wound closure segmentation reveals how procedure setting, material science, and patient acuity reshape product specifications across acute and ambulatory channels. Manufacturers align R&D portfolios against these divides to capture volume in high-throughput environments versus premium positioning in specialized applications.
Product Type:
Sutures dominate hospital procurement volumes while adhesives command premium positioning in cosmetic and pediatric niches where scar minimization drives selection.
- Sutures:Braided polyglactin and poliglecaprone formulations provide predictable tensile strength retention across general surgery, orthopedics, and cardiovascular procedures. Demand concentrates in United States hospital systems where group purchasing organizations standardize on USP-compliant braided synthetic lines for cost efficiency.
- Adhesives:Octyl-2-cyanoacrylate and n-butyl-cyanoacrylate platforms enable needleless closure with flexible, high-tensile bonds suited for facial lacerations and minimally invasive incisions. Adoption accelerates in South Korean dermatology clinics and United States ambulatory settings where operating room turnover time reduction justifies unit premium.
- Staples:Stainless steel and titanium devices deliver rapid mechanical closure in abdominal and thoracic procedures where speed outweighs cosmetic outcome.
- Dressings:Advanced hydrocolloid and foam substrates manage exudate in chronic wound protocols across home healthcare channels.
Mature deployment sits with sutures across general surgery suites. Newer deployment is concentrated in adhesives within cosmetic and same-day discharge workflows.
Technology:
Technology segmentation tracks how energy-based and chemical bonding methods compete against traditional mechanical approximation in procedure-specific niches.
- Electrostatic:Charged polymer deposition systems create instant tissue adhesion without thermal damage, finding initial traction in ophthalmic microsurgery where precision exceeds suture capability.
- Photochemical:Light-activated sealants polymerize on demand, enabling controlled application in vascular anastomosis and dural closure where bond strength must match native tissue compliance.
- Biochemical:Enzymatic and protein-based adhesives leverage fibrin and collagen chemistry for hemostatic closure in bleeding-sensitive fields like hepatic and splenic surgery.
- Thermal:Radiofrequency and ultrasonic welding devices fuse tissue edges through controlled protein denaturation, reducing foreign body burden in laparoscopic procedures.
Biochemical platforms retain widest clinical validation. Photochemical methods are gaining share fastest in microsurgical subspecialties.
End User:
End-user segmentation captures how care setting migration—from inpatient wards to freestanding facilities—rewrites product form factor and follow-up requirements.
- Hospitals:Inpatient surgical departments sustain demand for comprehensive suture portfolios spanning absorbable and non-absorbable lines across all surgical specialties.
- Clinics:Dermatology and urgent care sites favor single-use adhesive applicators and rapid-absorbing sutures for laceration management without scheduled removal.
- Home Healthcare:Wound care nurses deploy advanced dressings and topical skin adhesives for chronic ulcer management outside acute settings.
- Ambulatory Surgical Centers:Same-day discharge protocols favor faster-application products with minimal postoperative intervention needs, including barbed sutures and liquid bandages.
Hospital procurement maintains the deepest product breadth. Ambulatory Surgical Centers are expanding most quickly as Medicare reimbursement shifts enable procedure migration.
Application:
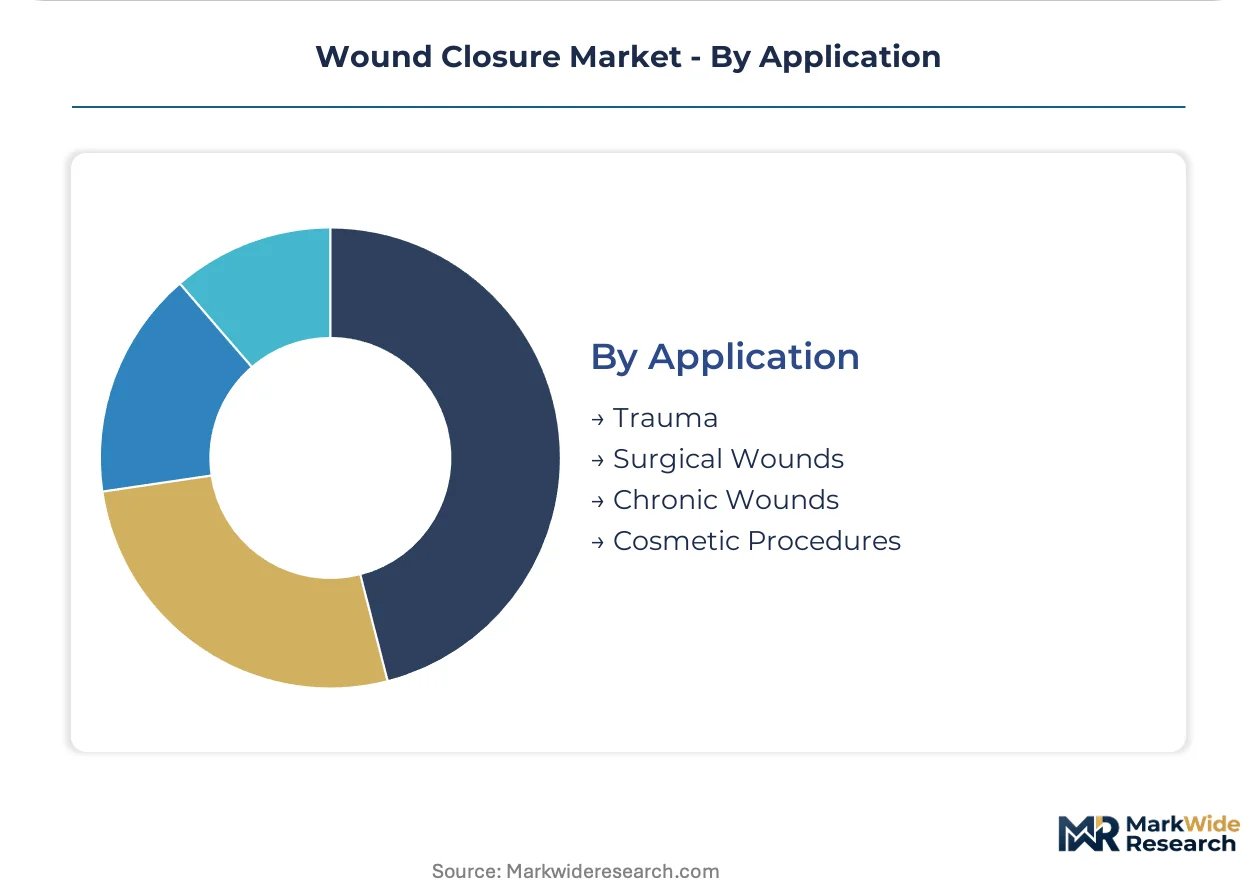
Application segmentation distinguishes between acute traumatic injury, scheduled surgical intervention, and chronic condition management with distinct healing timelines.
- Trauma:Emergency departments require rapid-deploy closure systems for laceration and penetrating wound management under time pressure.
- Surgical Wounds:Planned incisions in general, orthopedic, and cardiovascular surgery drive specification of sutures with calibrated absorption profiles matched to tissue healing rates.
- Chronic Wounds:Diabetic foot ulcers and pressure injuries necessitate moisture-balanced dressings and negative pressure systems rather than primary closure.
- Cosmetic Procedures:Aesthetic surgery and minimally invasive dermatology procedures prioritize adhesives and subcuticular sutures that eliminate external scarring.
Surgical wound closure commands established volume. Cosmetic applications are climbing the fastest as aesthetic procedure demand expands across United States and East Asian markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of absorbable polymer precursors concentrates in Germany and Japan, while procedural demand clusters in the United States and China. This geographic split forces wound closure converters to manage long supply chains and region-specific regulatory dossiers.
United States
Medicare reimbursement expansion for same-day procedures in freestanding ambulatory surgical centers drives adhesive closure adoption. The FDA enforces biocompatibility testing under ISO 10993 for all implantable devices. Hospital consolidation across the Southeast and Midwest compresses vendor panels into standardized formularies.
Germany
Specialty chemical manufacturers in the Rhine-Ruhr and Bavarian regions supply polyglycolic acid precursors to global suture converters. The EU MDR mandates updated clinical evidence and unique device identification for Class IIa implantable renewals. Stuttgart's medical technology cluster houses sterilization validation facilities serving continental European markets.
Japan
PMDA maintains distinct approval frameworks that create incremental compliance costs for multi-region suppliers entering the market. Aging demographics sustain surgical volume in acute care settings. Osaka-Kobe's polymer science institutes retain specialized expertise in glycolide-lactide copolymerization kinetics.
China
NMPA regulatory harmonization efforts accelerate market access for multinational wound closure portfolios. Domestic hospital procurement centralization under volume-based purchasing agreements drives price compression. Shanghai's Pudong medical device zone hosts contract sterilizers serving Asia-Pacific distribution networks.
South Korea
Dermatology clinics in Seoul and Busan adopt octyl-2-cyanoacrylate adhesives at accelerating rates for cosmetic procedures. MFDS maintains parallel but distinct biocompatibility documentation requirements. The Gyeonggi-do biocluster supports local manufacturing of rapid-absorbing suture lines.
Wound Closure Market Vendor Landscape
The competitive structure tilts toward diversified medical technology conglomerates with integrated surgical workflow portfolios. Three to five large-cap players anchor hospital procurement through bundled contracts spanning sutures, energy devices, and hemostasis products. Mid-cap specialists compete via antimicrobial coating differentiation and veterinary segment penetration. Dominant competitive moves include strategic partnerships with group purchasing organizations and geographic licensing arrangements for polymer synthesis IP.
Among diversified health technology conglomerates, Johnson & Johnson Services, Inc. and Medtronic occupy positions reflecting broad surgical portfolio integration, while Baxter sits within the specialized hemostasis and sealant tier. These three entities exemplify contrasting archetypes: the full-line acute care supplier, the integrated surgical workflow bundler, and the niche time-reduction technology specialist. Their collective presence shapes procurement negotiations in United States hospital systems and European acute care networks.
| Leading Market Players |
|---|
| Johnson & Johnson Services, Inc. |
| Medtronic |
| 3M |
| B. Braun Melsungen AG |
| Baxter |
| Smith & Nephew |
| Stryker |
| Corza Health |
| Solventum |
| Others |
Supply Flow & Price Mechanics
Polyglycolic acid precursor costs cascade from three specialty chemical manufacturers in Germany and Japan through braided synthetic suture lines to hospital procurement tiers in the United States, with price stratification tracking input volatility and sterilization validation burden downstream.
Pricing Analysis
Operating room throughput anchors value-based pricing for adhesive closure systems in ambulatory surgical centers, where reduced turnover time justifies unit premiums over mechanical alternatives. Pricing stratifies across premium antimicrobial-coated lines, standard USP-compliant synthetics, and economy-grade commodity sutures used in veterinary applications. Cost compression in the standard tier intensifies as group purchasing organizations consolidate volume commitments across multi-facility networks. Ambulatory surgical centers exhibit highest price sensitivity due to Medicare reimbursement constraints, while cosmetic dermatology clinics absorb premiums for scar-minimizing formulations.
Supply Chain Analysis
Dual-sourcing requirements for absorbable polymer precursors compel wound closure converters to qualify supply from both German and Japanese specialty chemical manufacturers, mitigating single-source vulnerability. Raw material dependencies center on glycolide-lactide copolymers, stainless steel wire feedstock, and cyanoacrylate monomer feedstreams. Tariff exposure on precursor imports from Asia threatens margin stability for US-based converters. Distribution runs through group purchasing organization contracts directly into hospital system formularies, bypassing traditional distributor markups in consolidated procurement networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital system consolidation functions as a consolidation play, with group purchasing organization standardization forcing mid-cap suppliers lacking antimicrobial coating differentiation toward exit or acquisition.
For Market Incumbents: Hedge against energy-based vessel sealing substitution by deepening biochemical adhesive R&D pipelines and securing exclusive group purchasing organization contracts across Southeast and Midwest hospital networks. Backward integration into polyglycolic acid precursor production insulates margin pressure from German and Japanese supply concentration.
For New Entrants and Emerging Players: Capture underpenetrated veterinary surgery demand in Brazil and Mexico through USP-compliant product lines that upgrade commodity-grade sutures already in use. Target companion animal orthopedic procedures with margin expansion potential absent from saturated human acute care procurement.
For Investors and Strategic Acquirers: EU MDR clinical evidence burden spikes is the leading indicator that mid-cap European suture manufacturers face renewal timeline extension and regulatory infrastructure diversion, creating distressed acquisition targets with intact polymer synthesis IP. Focus on specialists with captive sterilization validation capabilities and established notified body relationships.
| Strategic Initiative | Industry Significance |
|---|---|
| Antimicrobial Coating Development | Triclosan-impregnated and silver-ion-embedded formulations align with Joint Commission surgical site infection protocols in US acute care hospitals. |
| EU MDR Technical Documentation Investment | Updated clinical evidence packages and active implant registries secure Class IIa renewal timelines for European market access. |
| Group Purchasing Organization Partnership | Exclusive formulary placement across Catholic health initiatives and for-profit chains locks out competing vendors in consolidated networks. |
| Veterinary Segment Product Line Launch | USP-compliant sutures for companion animal procedures in Latin America capture margin expansion unavailable in human commodity tiers. |
| Remote Wound Monitoring Integration | Absorbable sutures with wireless pH-sensing substrates enable post-discharge surveillance via smartphone-connected platforms. |
Methodological Framework
Document review covered FDA 510(k) filings, EU MDR technical documentation requirements, hospital procurement databases, and group purchasing organization contract disclosures, complemented by interviews with biomedical engineers, GPO contracts managers, sterilization validation specialists, and regulatory affairs leads at notified bodies. Secondary sources included ISO 10993 biocompatibility standards, CMS Medicare reimbursement schedules, and customs records tracking polyglycolic acid precursor trade flows. Bottom-up volume modeling triangulated against top-down market sizing across product type, technology, end user, and application dimensions.
Historical shipment data cross-referenced against expert panel input on ambulatory surgery volume migration and antimicrobial coating adoption curves shaped the analytical framework across the projection horizon. Segmentation modeling captured sutures versus adhesives versus staples, biochemical versus photochemical versus thermal bonding methods, and hospitals versus ambulatory surgical centers versus home healthcare channels. CAGRs derived from procedure volume elasticity, reimbursement rate trajectories, and raw material cost pass-through assumptions.
The model holds under stable EU MDR renewal timelines and continued Medicare same-day procedure reimbursement expansion; deviation in sterilization validation capacity constraints or polymer precursor supply disruptions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Foam Dressing Market
Wound Care
Wound Care Market
Wound Care
Bioactive Wound Dressing Market
Wound Care
Burn Care Centers Market
Wound Care
Venous Ulcer Treatment Market
Wound Care
United States Negative Pressure Wound Therapy Market
Wound Care
Hemostats for Wound Closure Market
Wound Care
Post-Operative Wound Treatment Market
Wound Care
US Wound Care Centers Market
Wound Care
Wound Closure and Advanced Wound Care Market
Wound Care
LAMEA Surgical Dressing Market
Wound Care
Global Negative Pressure Wound Therapy (NPWT) Devices Market
Wound Care
Wound Healing Nutrition Market
Wound Care
Surgical Dressing Market
Wound Care
Advanced Wound Care Market
Wound Care
Europe Advanced Wound Care Market