
 Dental Microsurgery Market | 2026-2036
Dental Microsurgery Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Microsurgery Market Analysis
ISO 13485 certification cycles for medical device quality management is bifurcating the competitive landscape into qualified and non-qualified suppliers. Carl Zeiss Meditec AG leverages its vertically integrated optical manufacturing to sustain premium positioning across surgical microscopes. Hu-Friedy Mfg. Co., LLC anchors its presence through specialized instrument portfolios calibrated for periodontal microsurgery. Dentsply Sirona competes by extending digital imaging workflows into chairside microsurgical applications.
Dental microsurgery encompasses precision operative techniques performed under optical magnification typically ranging from 4x to 25x, employing specialized instruments with tip diameters below 0.5 millimeters for tissue manipulation at submillimeter scales. Its primary purpose is to enhance visual acuity and surgical precision during endodontic retreatments, root-end resections, and soft-tissue grafting procedures that exceed unaided human resolution. Microscopes dominate capital expenditure allocations due to their centrality in optical magnification workflows, while laser systems capture expanding share in soft-tissue applications where thermal precision reduces collateral damage. Consumables generate recurring revenue streams with higher margin stability than equipment sales, particularly suture materials and micro-instrument tips subject to single-use protocols.
FDA 510(k) premarket notification requirements govern device clearance timelines in the United States, while the EU Medical Device Regulation mandates notified body conformity assessments for CE marking access across European member states. Japan's PMDA enforces QMS ministerial ordinances that foreign manufacturers must satisfy through in-country designated marketing authorization holders. Stakeholders must monitor evolving harmonization gaps between FDA digital health guidance and EU MDR software classification rules that could fragment product registration strategies across jurisdictions.
Market Dynamics
ISO 13485 certification cycles for medical device quality management is bifurcating the competitive landscape into qualified and non-qualified suppliers. FDA 510(k) clearance pathways for surgical microscopes and imaging systems are compressing time-to-market for compliant devices.
Growth Catalysts
- Fluorescence-guided protocols:University hospitals in Berlin and Heidelberg anchor adoption of advanced microsurgical visualization techniques that enhance tissue differentiation during periodontal procedures.
- EU Medical Device Regulation:Notified body conformity assessments for CE marking access are standardizing quality benchmarks across European member states, elevating compliant manufacturers.
- Academic medical centers:Oral surgeons in residency programs integrating microsurgical curricula represent expanding demand for precision operative equipment and training platforms.
Market Restraints
- Optical component supply concentration:German and Japanese precision optics manufacturers control critical supply tiers for surgical microscope objectives, creating single-source vulnerability.
- Capital intensity barrier:Surgical microscopes dominate capital expenditure allocations, constraining adoption among independent dental practices without institutional procurement support.
- PMDA QMS ministerial ordinances:Japan's enforcement through in-country designated marketing authorization holders extends regulatory friction for foreign device manufacturers.
Strategic Opportunities
- Consumables recurring revenue:Suture materials and micro-instrument tips subject to single-use protocols generate higher margin stability than equipment sales for qualified suppliers.
- Digital imaging workflow convergence:Chairside integration of microsurgical visualization with CAD/CAM systems creates new application layers in restorative dentistry.
- FDA digital health guidance harmonization:Evolving alignment gaps with EU MDR software classification rules present first-mover advantages for registration strategy optimization.
Industry Challenges
- Microsurgical skill scarcity:Residency programs face compressed timelines to train proficient operators in submillimeter tissue manipulation techniques.
- Legacy system integration:Chairside microsurgical applications require compatibility reconfiguration with existing dental unit infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Microsurgery Market |
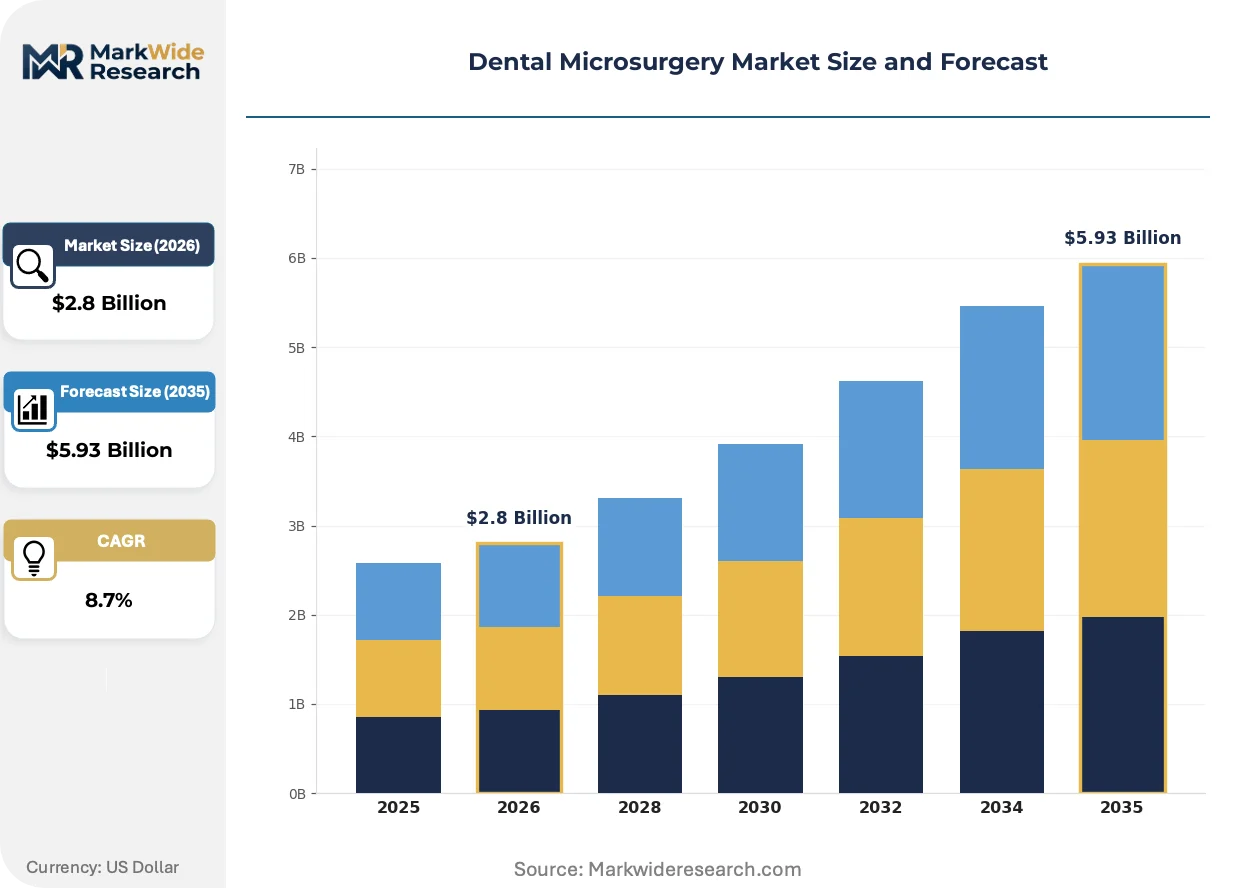
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microscopes, Surgical Instruments, Imaging Systems, Consumables Technology: Laser Systems, Optical Magnification, Ultrasound, Digital Imaging Application: Endodontics, Periodontics, Oral Surgery, Implantology End User: Dentists, Oral Surgeons, Hospitals, Dental Clinics |
| Companies Covered | Carl Zeiss Meditec AG, Global Surgical Corporation, Albert Waeschle Ltd., SYNOVIS MICRO COMPANIES ALLIANCE, INC., Hu-Friedy Mfg. Co., LLC, Dentsply Sirona, Henry Schein, Inc., Institut Straumann AG, KLS Martin Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Microsurgery Market Emerging Trajectories
Optical magnification workflows are fragmenting across multiple technology platforms as thermal precision modalities compete for soft-tissue application share. Three distinct vectors are reshaping how precision operative capabilities deploy across clinical settings.
Micro-instrument engineering is miniaturizing tip diameters below 0.5 millimeters for tissue manipulation at submillimeter scales. Periodontal specialists in academic medical centers are adopting these refined tools at accelerated rates. The technology is miniaturizing operative fields previously requiring open surgical access, compressing procedure invasiveness thresholds.
REACH substance restrictions are constraining optical coating chemistries used in surgical microscope manufacturing. Industrial consequence includes reformulation timelines for anti-reflective lens treatments. German precision optics manufacturers are responding with accelerated R&D allocation to fluoropolymer alternatives ahead of authorization deadlines.
Service unbundling is separating equipment sales from maintenance contracts and training modules. Independent dental practices are favoring subscription-based access to technical support and software updates over traditional capital-plus-service bundled purchases. This pattern concentrates in North American markets where practice consolidation has concentrated buyer negotiating leverage.
Dental Microsurgery Market Segmentation
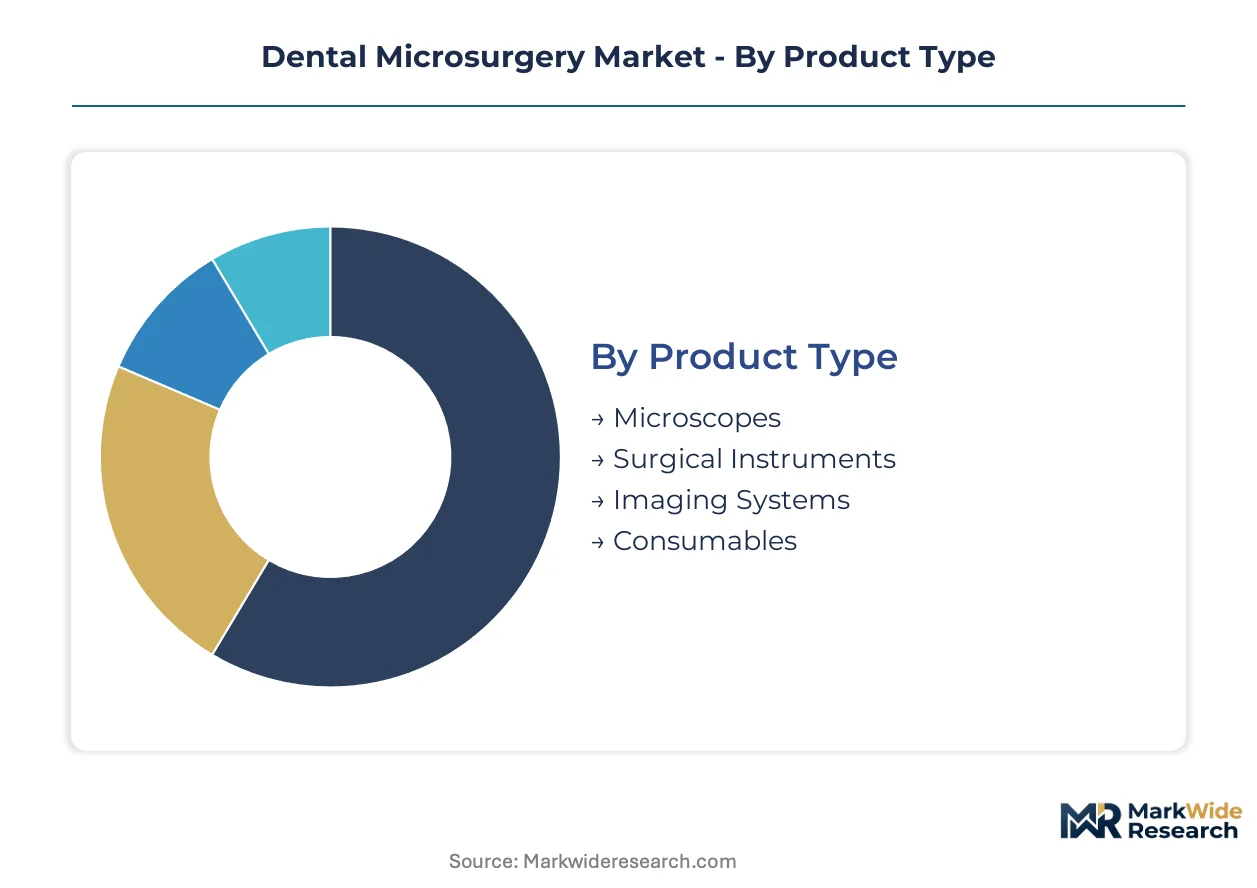
Dental microsurgery equipment fragments across four distinct product architectures, each facing differential substitution pressure from adjacent visualization and precision technologies. Technology platforms compete for procedural share based on thermal precision versus optical resolution trade-offs. Application segments concentrate demand around retreatment complexity and soft-tissue reconstruction volumes.
Product Type:
Laser systems and advanced imaging platforms exert substitution pressure on conventional optical equipment in soft-tissue applications, compressing microscope dominance in specific procedure categories.
- Microscopes:Surgical microscopes deliver magnification ranges from 4x to 25x with integrated LED illumination and ergonomic positioning systems. University hospitals in Berlin and Heidelberg anchor procurement volumes as residency programs integrate fluorescence-guided protocols into standard curricula. Carl Zeiss Meditec AG sustains premium positioning through vertically integrated optical manufacturing.
- Consumables:Suture materials, micro-instrument tips, and single-use protocols generate recurring revenue streams with margin stability superior to capital equipment cycles. Demand concentrates in Germany where regulatory compliance elevates qualified supplier preference.
- Surgical Instruments:Specialized tool portfolios feature tip diameters below 0.5 millimeters calibrated for periodontal microsurgery.
- Imaging Systems:Chairside visualization platforms extend digital workflows into operative fields.
Microscopes anchor the volume base while consumables gain share at the steepest rate through recurring procurement protocols.
Technology:
Cost tier stratification separates premium optical platforms from accessible ultrasound alternatives, with laser systems occupying mid-tier positioning in soft-tissue applications.
- Laser Systems:Thermal precision modalities reduce collateral tissue damage in gingival recontouring and frenectomy procedures. FDA 510(k) clearance pathways compress time-to-market for compliant devices. Adoption accelerates in academic medical centers seeking reduced postoperative morbidity.
- Digital Imaging:CAD/CAM convergence creates new application layers in restorative dentistry workflows. Dentsply Sirona competes by extending digital imaging into chairside microsurgical visualization.
- Optical Magnification:Conventional microscope-based workflows retain dominance in endodontic retreatment and root-end resection procedures.
- Ultrasound:Piezoelectric bone surgery systems offer selective mineralized tissue cutting with soft-tissue preservation.
Optical magnification retains the installed base while digital imaging climbs the fastest in new procurement cycles.
Application:
Procedure volume distribution concentrates in retreatment and reconstruction categories, with implantology presenting the steepest technology upgrade intensity.
- Endodontics:Root canal retreatment and apical surgery demand submillimeter resolution for isthmus identification and debris removal. Residency programs face compressed timelines to train proficient operators in these precision techniques.
- Periodontics:Soft-tissue grafting and regenerative procedures leverage fluorescence-guided visualization for enhanced tissue differentiation. Hu-Friedy Mfg. Co., LLC anchors presence through instrument portfolios calibrated for these applications.
- Oral Surgery:Nerve repositioning and sinus elevation procedures require magnification for anatomical structure preservation.
- Implantology:Guided bone regeneration and immediate loading protocols drive imaging system integration.
Endodontics anchors the volume base while implantology expands most quickly through digital workflow convergence.
End User:
Customer type determines procurement modality, with institutional buyers leveraging consolidated purchasing power against independent practice capital constraints.
- Hospitals:Academic medical centers integrate microsurgical curricula into residency programs, generating bundled equipment and training demand. Oral surgeons in these settings represent the most rapidly expanding buyer segment.
- Dental Clinics:Independent practices favor subscription-based access to technical support over traditional capital-plus-service bundles. This pattern concentrates in North American markets where practice consolidation has elevated buyer negotiating leverage.
- Oral Surgeons:Specialist practitioners drive premium instrument adoption through procedure-specific requirements.
- Dentists:General practitioners represent latent demand as magnification protocols diffuse from specialty to primary care settings.
Hospitals anchor the volume base while dental clinics gain share at the steepest rate through service unbundling preferences.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) pathways, EU MDR conformity assessments, and Japan's PMDA QMS ordinances are compressing clearance timelines while elevating compliance barriers across major jurisdictions. Academic medical centers in Berlin, Heidelberg, and selected US metropolitan clusters anchor procurement volumes as residency programs integrate microsurgical training.
United States
FDA 510(k) premarket notification requirements govern surgical microscope and imaging system clearances, compressing time-to-market for compliant devices. Oral surgeons in academic medical centers represent the most rapidly expanding buyer segment as residency programs integrate microsurgical curricula. Greater Boston and Pacific Northwest metropolitan clusters concentrate procurement through institutional purchasing consortia.
Germany
EU Medical Device Regulation mandates notified body conformity assessments for CE marking access, standardizing quality benchmarks across member states. REACH substance restrictions constrain optical coating chemistries, forcing reformulation timelines for anti-reflective lens treatments. University hospitals in Berlin and Heidelberg anchor adoption of fluorescence-guided microsurgical protocols.
Japan
PMDA enforces QMS ministerial ordinances that foreign manufacturers must satisfy through in-country designated marketing authorization holders. Kanto and Kansai metropolitan areas concentrate demand among specialist oral surgery clinics. Tokyo-based academic medical centers drive premium instrument adoption through procedure-specific requirements.
United Kingdom
MHRA operates under retained EU MDR provisions post-Brexit, maintaining alignment with CE marking standards while developing independent conformity assessment capacity. London and Southeast England clusters concentrate private dental clinic demand. Independent practices in these regions favor subscription-based technical support over traditional capital-plus-service bundles.
China
NMPA medical device registration requirements govern import and domestic manufacturing licensing for surgical microscopes and laser systems. Yangtze River Delta and Pearl River Delta metropolitan clusters concentrate domestic manufacturing capacity for optical components. Shanghai-based university hospitals are expanding microsurgical training programs.
Dental Microsurgery Market Vendor Landscape
Listed leaders compete with private specialists across capital intensity and certification qualification dimensions. The market structure bifurcates between ISO 13485-qualified suppliers capturing institutional procurement and non-qualified vendors serving price-sensitive independent practices. Three archetypes dominate: vertically integrated optical manufacturers, specialized instrument fabricators, and digital workflow integrators. Competitive moves concentrate on M&A for technology portfolio expansion and strategic partnerships for regulatory pathway acceleration.
Within the vertically integrated tier, Carl Zeiss Meditec AG exemplifies premium positioning through captive optical manufacturing. Among specialized instrument fabricators, Hu-Friedy Mfg. Co., LLC and KLS Martin Group occupy positions calibrated for periodontal and oral surgery applications respectively. Dentsply Sirona represents the digital workflow integrator archetype, extending imaging platforms into chairside operative environments.
| Leading Market Players |
|---|
| Carl Zeiss Meditec AG |
| Global Surgical Corporation |
| Albert Waeschle Ltd. |
| SYNOVIS MICRO COMPANIES ALLIANCE, INC. |
| Hu-Friedy Mfg. Co., LLC |
| Dentsply Sirona |
| Henry Schein, Inc. |
| Institut Straumann AG |
| KLS Martin Group |
| Others |
Supply Flow & Price Mechanics
Fluoropolymer alternatives replacing legacy optical coating chemistries under REACH deadlines simultaneously relocate R&D investment toward German precision optics manufacturers and compress margin structures for non-compliant suppliers. This substitution dynamic concentrates pricing power among ISO 13485-qualified vendors while forcing reformulation cost absorption across tier-2 microscope assemblers.
Pricing Analysis
Certification level creates the primary spread between premium and economy tiers, with FDA 510(k) and CE-marked equipment commanding substantial premiums over non-qualified alternatives. Three-tier pricing structure separates institutional procurement bundles from subscription-based clinic access and bare-equipment transactions. Cost compression in the independent practice segment is intensifying because service unbundling allows buyers to strip maintenance and training from capital purchases. Academic medical centers exhibit lowest price sensitivity due to consolidated purchasing power, while solo practitioners in North America demonstrate highest sensitivity to upfront capital requirements.
Supply Chain Analysis
Strategic stockpiling of precision optical components dominates inventory strategy as German and Japanese manufacturers control critical objective lens supply tiers. German and Japanese precision optics manufacturers anchor upstream concentration for surgical microscope assemblies, while Chinese suppliers dominate LED illumination module production. Critical dependencies include fluoropolymer coating formulations, precision-ground glass substrates, and piezoelectric ceramic elements. Single-source vulnerability in German objective lens supply creates structural risk for microscope assemblers lacking captive optical manufacturing. Distribution runs through institutional purchasing consortia in academic medical centers and dental group practice organizations in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Laser thermal precision modalities threaten optical microscope dominance in soft-tissue applications, compelling incumbents to defend procedural share through workflow integration rather than equipment-only positioning.
For Market Incumbents: Compound defensive moats by embedding fluorescence-guided visualization protocols into residency training curricula, locking in future purchasing decisions at the trainee level. Deepen backward integration into precision optical component manufacturing to neutralize German and Japanese supplier leverage. Prioritize CAD/CAM workflow convergence to preempt digital imaging competitors from displacing microscope centrality in restorative applications.
For New Entrants and Emerging Players: Subscription-based technical support and software update services represent the most penetrable white-space as independent dental clinics reject traditional capital-plus-service bundles. Target North American dental group practices with consolidated negotiating leverage seeking predictable operational expenditure structures. Enter through consumables suture and micro-instrument tip supply, establishing recurring revenue relationships before capital equipment displacement.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed dental technology platforms seeking microsurgical capability adjacencies. Five-to-ten year viability hinges on regulatory qualification moats widening rather than harmonizing across FDA, EU MDR, and PMDA jurisdictions. Watch for fluorescence-guided protocol standardization in German university hospitals as inflection indicator for premium equipment demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Qualifies suppliers for institutional procurement in Germany and academic medical center segments. |
| Residency Program Partnership | Locks in trainee familiarity with specific visualization protocols before independent practice entry. |
| Consumables Portfolio Expansion | Generates recurring revenue stability superior to capital equipment cyclicality. |
| Digital Workflow Integration | Extends microscope relevance into CAD/CAM restorative dentistry applications. |
| Fluoropolymer Coating R&D | Ensures REACH compliance continuity for anti-reflective lens treatments ahead of deadlines. |
Methodological Framework
Operator-level perspectives from oral surgeons, residency program directors, hospital purchasing committees, and biomedical engineers anchored the qualitative base. Primary interviews combined with secondary validation from FDA 510(k) filings, EU MDR notified body assessment records, hospital procurement databases, and GPO contract disclosures. Bottom-up equipment shipment analysis and top-down procedure volume estimation provided triangulation across the analysis window.
Sensitivity analysis tested forecast robustness across alternative regulatory harmonization scenarios and substitution elasticity assumptions. Segmentation dimensions modeled include product architecture, technology platform, application procedure type, end-user institutional category, and geographic regulatory cluster. CAGRs derived from procedure volume growth rates, equipment replacement cycles, and consumables per-procedure intensity. Industry-specific inputs encompassed residency program expansion timelines and fluorescence-guided protocol adoption curves.
Forecasts assume regulatory continuity in FDA 510(k), EU MDR, and PMDA QMS regimes; material policy shifts would require re-modeling clearance timeline assumptions. Specific risks include REACH substance restriction expansion constraining coating chemistry options and optical component supply concentration disrupting manufacturing continuity. Revision becomes warranted when laser system substitution rates in soft-tissue applications cross thresholds that materially compress microscope procurement growth.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Global Orthodontic Product Market
Dental Devices
Europe Dental Lab Market
Dental Devices
Dental Suction Systems Market
Dental Devices
China Dental Devices Market
Dental Devices
Titanium Dental Implants Market
Dental Devices
Canada Dental Devices Market
Dental Devices
Global Dental Turbine Market
Dental Devices
Global Dentures Market
Dental Devices
North America Dental Lasers Market
Dental Devices
Netherlands Dental Devices Market
Dental Devices
Dental Caries Market
Dental Devices
North America Dental Aligners Market
Dental Devices
Europe Dental Implants Market
Dental Devices
Dental Irrigation Devices Market
Dental Devices
Global Periodontal Market
Dental Devices
Dental Devices and Consumables Market