
 Acute Care Needleless Connectors Market | 2026-2036
Acute Care Needleless Connectors Market Size, Share, and Industry Trends Forecast 2026-2036
Acute Care Needleless Connectors Market Analysis
Antimicrobial-grade specification tiers is bifurcating the competitive landscape between premium and standard offerings. Becton Dickinson and Company leverages its integrated manufacturing footprint to dominate high-specification segments. Baxter International Inc. anchors North American distribution through longstanding group purchasing organization contracts. ICU Medical Inc. differentiates via proprietary neutral displacement technology that reduces bloodstream infection risk.
Acute care needleless connectors are sterile, luer-activated devices engineered from polycarbonate or ABS housings with silicone or thermoplastic elastomer valve mechanisms, designed to maintain closed intravenous systems during medication administration and sampling. Valved product types command the largest revenue share due to their compatibility with positive-pressure infusion protocols, while antimicrobial technology segments attract premium pricing from oncology and immunocompromised patient settings. Hospitals represent the dominant end-user channel, though home healthcare applications expand as ambulatory infusion therapy protocols mature.
FDA 510(k) clearance requirements and Joint Commission National Patient Safety Goals shape product development timelines and clinical validation burdens for manufacturers. The EU MDR and ISO 80369-7 small-bore connector standards further constrain design freedom while elevating barrier-to-entry economics for new entrants. Stakeholders must monitor evolving state-level mandates for closed-system transfer devices in hazardous drug handling, as these regulations will dictate replacement cadence and specification requirements across acute care delivery networks.
Market Dynamics
Closed-system transfer device mandates for hazardous drug handling are compressing replacement cycles and forcing acute care facilities toward antimicrobial-grade specifications that command premium positioning.
Growth Catalysts
- Joint Commission National Patient Safety Goals:These standards mandate closed intravenous systems in hospital intensive care units, creating compliance-driven refresh demand across accredited facilities.
- Polycarbonate antimicrobial housings:Oncology and immunocompromised patient settings are specifying these materials for their infection control profiles, widening the premium product tier.
- United States chemotherapy administration protocols:State-level hazardous drug handling regulations here are accelerating transitions from open to closed-system transfer devices.
Market Restraints
- Silicone valve raw material concentration:Supply of medical-grade silicone concentrates among specialty chemical producers in Germany and Japan, exposing manufacturers to input volatility.
- FDA 510(k) clearance timelines:These validation requirements extend product development cycles by 12-18 months and elevate capital requirements for clinical testing.
- Thermoplastic elastomer substitution limits:Alternative valve materials lack the compression set resistance needed for positive-pressure infusion compatibility, constraining cost-down options.
Strategic Opportunities
- Home healthcare infusion therapy:Ambulatory protocols are maturing in the United States, creating demand for patient-operable needleless connectors outside hospital settings.
- ISO 80369-7 small-bore convergence:This standard harmonization with EU MDR requirements opens pathway designs that satisfy multiple regulatory jurisdictions simultaneously.
- Neutral displacement technology:Convergence with RFID-enabled inventory tracking is creating smart connector categories for automated medication reconciliation.
Industry Challenges
- Biocompatibility testing capacity:ISO 10993 cytotoxicity and sensitization studies require specialized contract research organizations with 6-9 month queue times.
- Legacy luer-activated system integration:Hospital IT and biomedical engineering teams face complexity when retrofitting neutral displacement connectors into existing infusion pump fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acute Care Needleless Connectors Market |
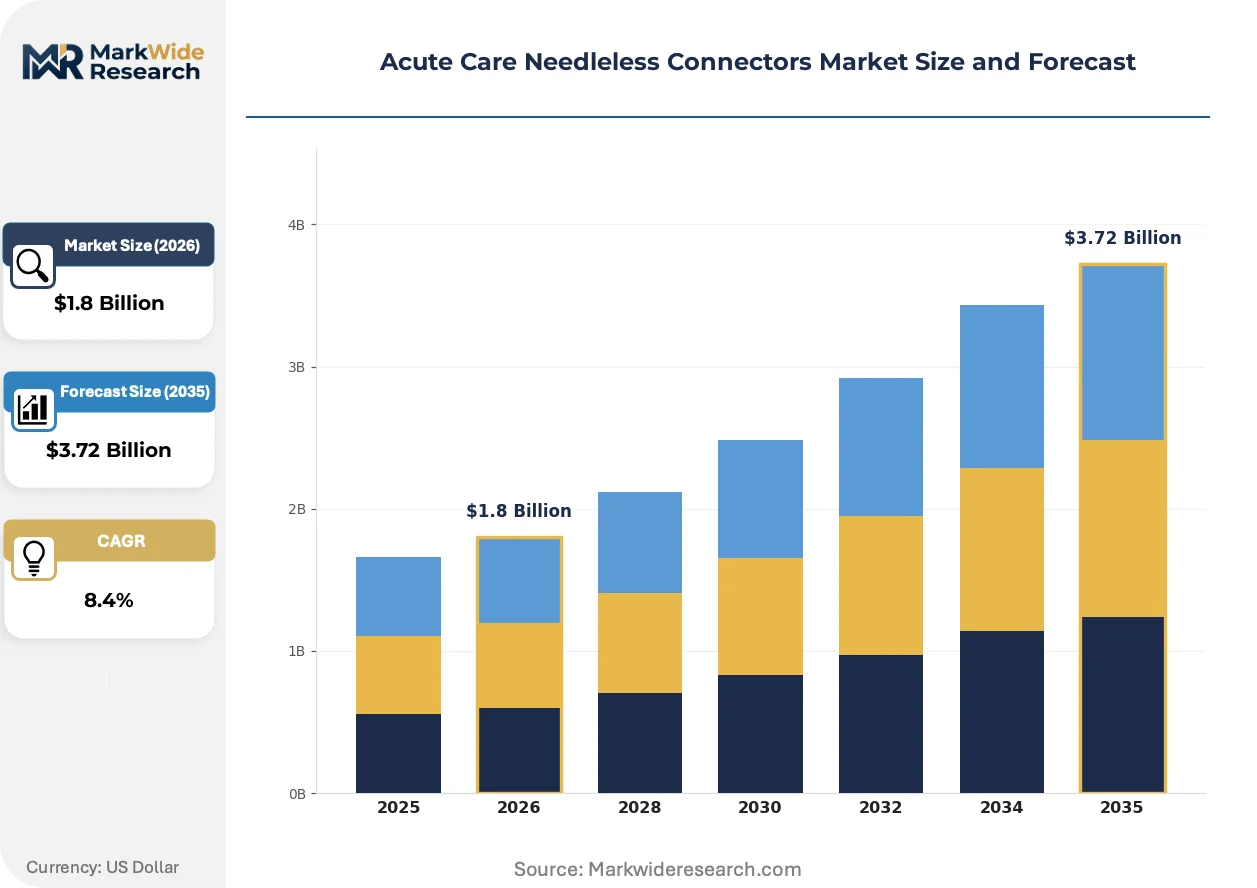
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.72 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Valved, Non-valved, Mechanical, Other End User: Hospitals, Clinics, Home Healthcare, Long-term Care Facilities Technology: Antimicrobial, Non-antimicrobial, Integrated, Passive Application: Intravenous Therapy, Dialysis, Blood Transfusion, Chemotherapy |
| Companies Covered | Becton Dickinson and Company, Baxter International Inc., B. Braun Melsungen AG, ICU Medical Inc., RyMed Technologies LLC, Nexus Medical LLC, Vygon SA, CareFusion Corporation, Cardinal Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acute Care Needleless Connectors Market Emerging Trajectories
Product specification tiers are splintering around antimicrobial performance claims, while regulatory convergence across FDA and EU MDR frameworks is compressing design freedom into narrower compliance pathways.
Antimicrobial silver-ion or chlorhexidine-impregnated polycarbonate housings are bifurcating the competitive landscape between premium infection-control specifications and standard offerings. Oncology units and bone marrow transplant centers are specifying these materials as standard-of-care, displacing conventional ABS housings in high-acuity settings. The technology is bifurcating procurement committees into infection-control-driven and cost-optimization-driven factions with incompatible vendor scorecards.
EU MDR Article 10 technical documentation requirements and FDA 510(k) substantial equivalence pathways are converging toward ISO 80369-7 small-bore connector standards as the baseline design constraint. Manufacturers now face parallel validation burdens that favor incumbent players with established quality management systems. Oncology and hazardous drug handling applications bear the heaviest compliance load, driving consolidation toward integrated device-drug combination product specialists.
Hospital value analysis committees are unbundling needleless connector procurement from legacy group purchasing organization contracts and conducting direct technical evaluations. This disintermediation favors vendors with clinical outcome data and antimicrobial efficacy studies over traditional volume-discount relationships. The pattern is most visible in United States academic medical centers with dedicated vascular access teams and infection control epidemiologists.
Acute Care Needleless Connectors Market Segmentation
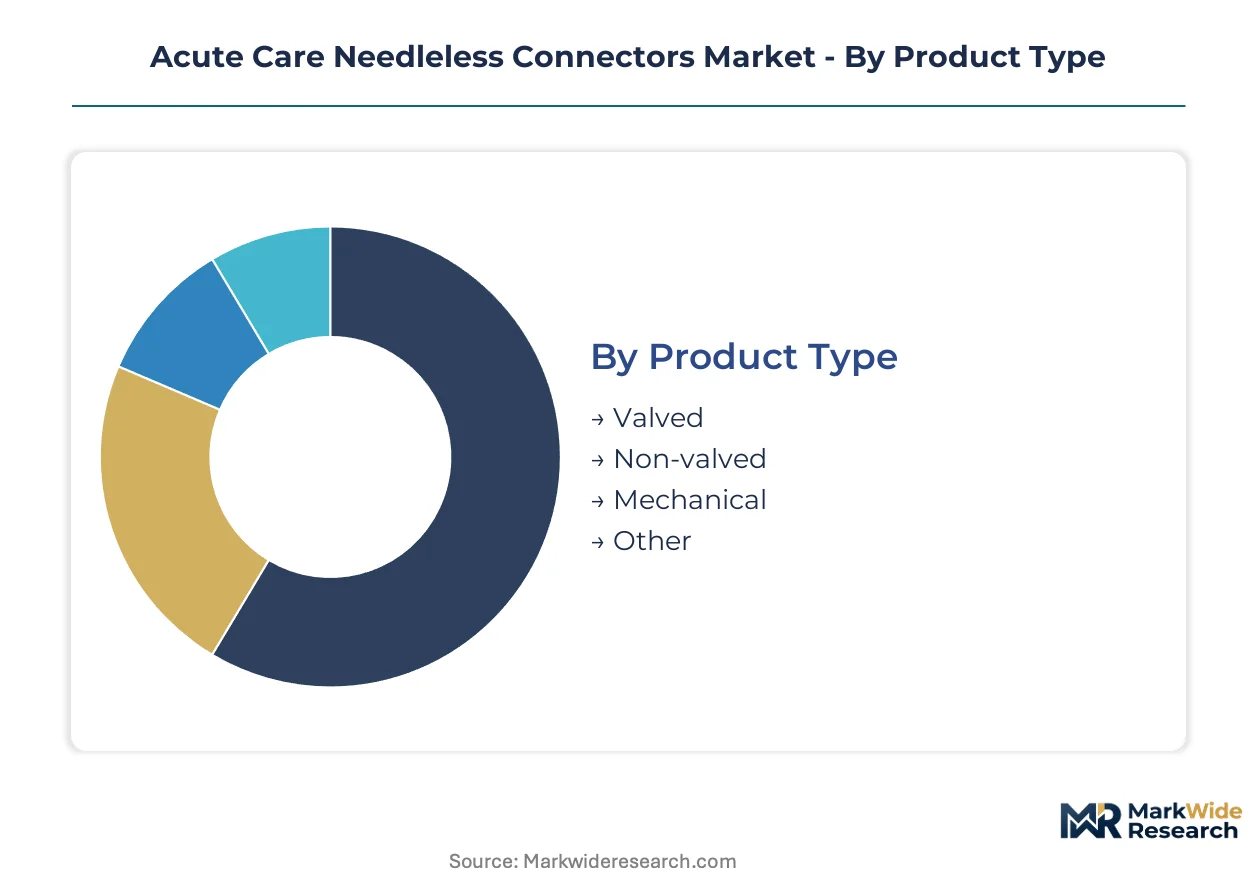
Segmentation in acute care needleless connectors reveals how infection control protocols, therapy modalities, and care settings reshape procurement priorities. Specification tiers diverge sharply between high-acuity hospital units and ambulatory environments, forcing manufacturers to optimize for incompatible performance-cost tradeoffs.
Product Type:
Substitution pressure concentrates in mechanical and non-valved segments, where simpler designs face displacement from closed-system alternatives with superior infection control profiles.
- Valved:These devices incorporate silicone or thermoplastic elastomer valve mechanisms that maintain closed systems during luer activation. Demand concentrates in United States hospital intensive care units where Joint Commission mandates for closed intravenous systems drive compliance-driven replacement cycles.
- Non-valved:Open-channel designs without internal valves offer lower unit costs but expose patients to bloodstream infection risk. Procurement committees in cost-constrained long-term care facilities specify these for low-acuity medication administration despite clinical preference for valved alternatives.
- Mechanical:Spring-loaded or pressure-activated closure systems provide physical barrier protection without elastomer components.
- Other:Hybrid designs combining multiple activation mechanisms serve specialized oncology and pediatric applications.
Valved configurations anchor the volume base while antimicrobial-integrated mechanical designs gain share at the steepest rate.
End User:
Cost tier stratification separates acute inpatient facilities from ambulatory and residential care settings with divergent reimbursement structures and infection control mandates.
- Hospitals:Academic medical centers and community hospitals with dedicated vascular access teams specify premium antimicrobial-grade connectors. FDA 510(k) clearance and Joint Commission accreditation requirements compress vendor selection to established quality management system holders.
- Home Healthcare:Patient-operable designs with simplified activation forces and clear visual confirmation of closed status support ambulatory infusion therapy expansion. United States Medicare reimbursement for home infusion services accelerates demand outside institutional settings.
- Clinics:Outpatient chemotherapy and infusion centers balance infection control with throughput efficiency.
- Long-term Care Facilities:Skilled nursing facilities face lower regulatory scrutiny but rising state-level hazardous drug handling mandates.
Hospitals dominate absolute consumption value while home healthcare applications expand most quickly as ambulatory protocols mature.
Technology:
Application-specific requirements in oncology and immunocompromised patient settings concentrate demand toward antimicrobial specifications with validated efficacy claims.
- Antimicrobial:Silver-ion or chlorhexidine-impregnated polycarbonate housings deliver sustained surface bioburden reduction. Bone marrow transplant centers and oncology units in United States academic medical centers specify these as standard-of-care, displacing conventional materials.
- Non-antimicrobial:Standard ABS or unmodified polycarbonate housings serve cost-optimized general medical-surgical units where infection incidence remains lower.
- Integrated:Pre-attached extension set configurations reduce connection points and contamination risk.
- Passive:Automatic closure mechanisms without manual activation steps minimize user variation in technique.
Non-antimicrobial technology retains the largest installed base while antimicrobial specifications command the steepest pricing premium expansion.
Application:
Volume concentration in intravenous therapy creates scale advantages for suppliers, while hazardous drug handling regulations in chemotherapy reshape specification requirements.
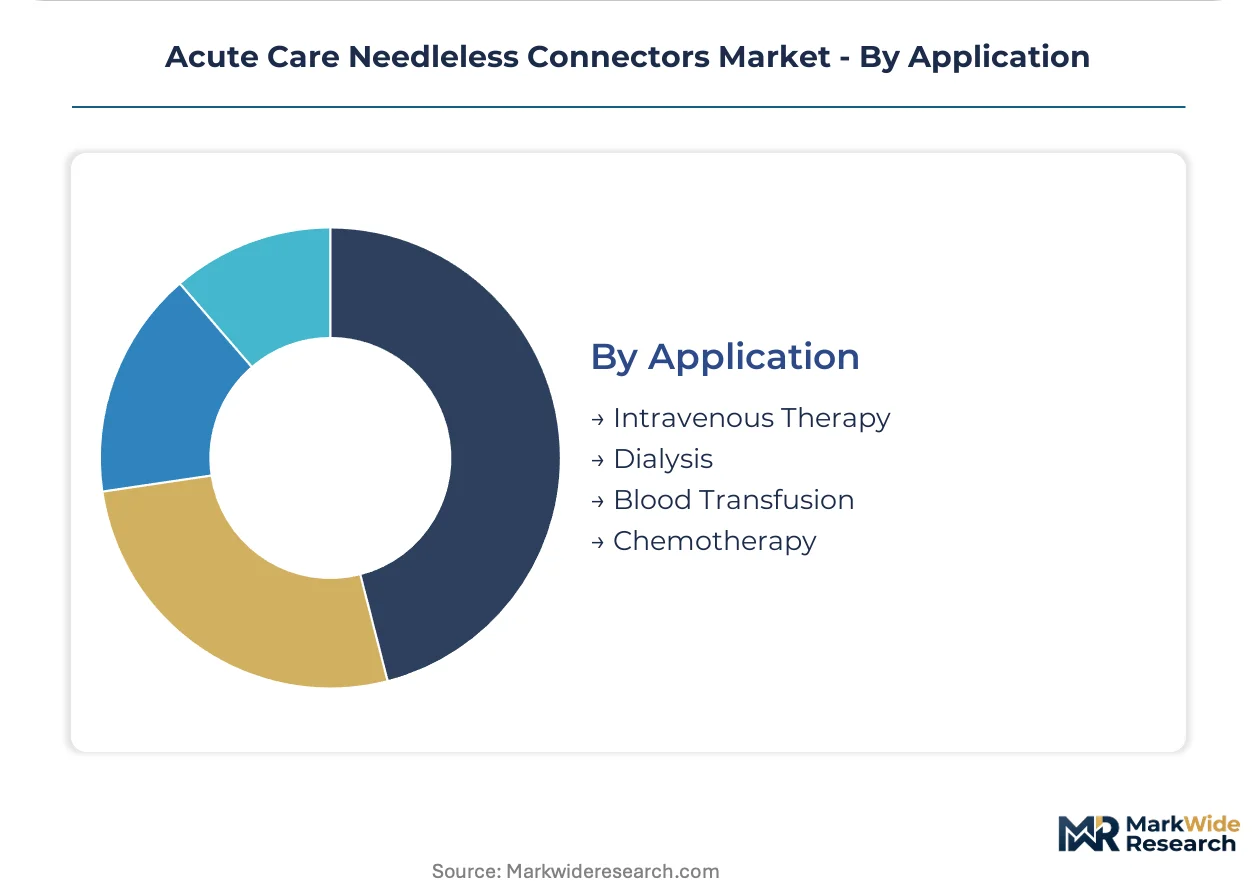
- Intravenous Therapy:General medication administration and fluid replacement account for the highest connection frequency across all acute care settings. Compatibility with positive-pressure infusion pumps and smart pump interoperability standards dominates procurement scorecards.
- Chemotherapy:Closed-system transfer device mandates for hazardous drug handling in United States state regulations force replacement of open connectors. OSHA and NIOSH guidelines for healthcare worker protection elevate specification tiers toward integrated CSTD-needleless connector combinations.
- Dialysis:High-flow requirements and repeated access cycles demand compression set-resistant valve materials.
- Blood Transfusion:Compatibility with blood product warming devices and filter sets constrains design freedom.
Intravenous therapy anchors the volume base while chemotherapy applications drive the steepest specification upgrade trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for medical-grade silicone concentrates supply chains in Germany and Japan against export-oriented device manufacturing in the United States and Switzerland shapes regional trade flows. Net importer positions in high-acuity care settings contrast with concentrated production clusters serving domestic hospital procurement.
United States
Joint Commission accreditation mandates for closed intravenous systems drive replacement cycles across hospital intensive care units. FDA 510(k) clearance requirements compress vendor selection to established quality management system holders. The Minneapolis-St. Paul corridor anchors device manufacturing clusters serving group purchasing organization contract networks.
Germany
Specialty chemical producers in the Rhine-Ruhr region concentrate medical-grade silicone supply for valve mechanisms across European device manufacturers. EU MDR technical documentation requirements elevate barrier-to-entry economics for new entrants. Baden-Württemberg industrial clusters specialize in precision molding for antimicrobial polycarbonate housings.
Japan
PMDA regulatory frameworks align with ISO 80369-7 small-bore connector standards to constrain design freedom for domestic manufacturers. Thermoplastic elastomer formulation expertise concentrates among Osaka-based material suppliers. The Kanto region around Tokyo hosts vascular access device distribution networks serving acute care facilities.
Switzerland
Swissmedic oversight of device-drug combination products elevates validation burdens for oncology-focused connector specifications. Precision manufacturing capabilities in the Basel-Zurich corridor support premium antimicrobial-grade production. The country's export orientation serves EU hospital procurement committees with direct technical evaluation practices.
China
NMPA regulatory harmonization with international standards accelerates domestic manufacturer qualification for export markets. Yangtze River Delta clusters concentrate ABS and polycarbonate resin processing for standard-grade housing production. Shanghai-based contract manufacturers supply cost-optimized alternatives to Southeast Asian hospital systems.
Acute Care Needleless Connectors Market Vendor Landscape
Concentration sits with integrated device specialists and diversified medical technology conglomerates sharing hospital procurement channel access. The vendor base stratifies across premium antimicrobial specifications and standard-grade alternatives with incompatible scorecards. Two archetypes dominate: quality management system incumbents with FDA clearance portfolios, and specialized valve technology developers with proprietary displacement mechanisms. Competitive moves center on antimicrobial material integration and geographic expansion through distribution partnerships.
Among diversified medical technology conglomerates, Becton Dickinson and Company and Baxter International Inc. exemplify scale-driven positions anchored in group purchasing organization contract networks. ICU Medical Inc. occupies a specialist tier focused on proprietary neutral displacement technology. These three represent the concentration of clinical validation capabilities and regulatory clearance portfolios that procurement committees prioritize for high-acuity settings.
| Leading Market Players |
|---|
| Becton Dickinson and Company |
| Baxter International Inc. |
| B. Braun Melsungen AG |
| ICU Medical Inc. |
| RyMed Technologies LLC |
| Nexus Medical LLC |
| Vygon SA |
| CareFusion Corporation |
| Cardinal Health |
| Others |
Supply Flow & Price Mechanics
Ninety-day silicone valve inventory positions at German specialty chemical producers concentrate pricing power among incumbent device manufacturers with captive supply agreements. This lead-time exposure tightens margin structures for mid-tier competitors sourcing on spot markets while antimicrobial-grade specification premiums widen.
Pricing Analysis
Hospital value analysis committees anchor contract pricing through direct technical evaluations that bypass legacy group purchasing organization volume discounts. Three-tier pricing structure across antimicrobial-premium, standard-valved, and non-valved economy levels reflects Joint Commission compliance tiering and FDA 510(k) clearance status. Pricing pressure stems from state-level hazardous drug handling mandates forcing accelerated replacement cycles. Long-term care facilities exhibit highest price sensitivity while academic medical centers prioritize infection control efficacy over unit cost.
Supply Chain Analysis
Rhine-Ruhr medical-grade silicone production and Osaka thermoplastic elastomer formulation expertise constitute dual chokepoints for valve mechanism inputs. Device assembly draws from United States precision molding clusters, Swiss antimicrobial polycarbonate finishing, and Yangtze River Delta ABS resin processing. Single-source vulnerability concentrates in German silicone supply for positive-pressure infusion compatibility. Distribution runs through group purchasing organization contract networks serving hospital procurement committees with consolidated vendor scorecards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from clinical validation support and biomedical engineering integration consulting expands faster than hardware unit sales as hospitals unbundle procurement from traditional volume contracts.
For Market Incumbents: Consolidate antimicrobial material supply through backward integration into German silicone processing or long-term offtake agreements with Rhine-Ruhr specialty chemical producers. Neutral displacement technology patent portfolios and FDA 510(k) clearance backlogs create defensive moats against emerging valve mechanism specialists. Capacity addition in Minneapolis-St. Paul corridor manufacturing clusters reinforces group purchasing organization contract dominance. For New Entrants and Emerging Players: FDA 510(k) substantial equivalence fast-tracks through predicate device referencing open pathways for antimicrobial-integrated mechanical designs targeting home healthcare infusion therapy. White-space concentrates in patient-operable connectors with simplified activation forces for Medicare-reimbursed ambulatory protocols. Go-to-market execution should prioritize direct hospital value analysis committee engagement over legacy group purchasing organization channel dependence. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical technology conglomerates seeking to divest non-core infusion therapy components. Long-term viability centers on integrated device-drug combination product capabilities serving oncology closed-system transfer device mandates. Monitor state-level hazardous drug handling regulation expansion as inflection indicator for specification upgrade cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Antimicrobial Material Integration | Silver-ion polycarbonate housings satisfy Joint Commission mandates in bone marrow transplant centers. |
| Neutral Displacement Patent Expansion | Proprietary valve mechanisms reduce bloodstream infection risk in ICU Medical's installed base. |
| Home Healthcare Product Line Development | Patient-operable designs capture Medicare-reimbursed ambulatory infusion therapy expansion. |
| ISO 80369-7 Convergence Investment | Harmonized small-bore connector standards satisfy FDA and EU MDR validation pathways simultaneously. |
| Hospital System Direct Partnership | Value analysis committee engagement displaces legacy group purchasing organization volume contracts. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, hospital procurement databases, and GPO contract disclosures. Primary interviews engaged vascular access team clinicians, biomedical engineering directors, infection control epidemiologists, and GPO contracts managers across United States academic medical centers and community hospital systems. Secondary validation drew from Joint Commission National Patient Safety Goals documentation, EU MDR technical file repositories, and CMS Medicare reimbursement schedules. Bottom-up unit demand modeling triangulates against top-down hospital bed and infusion pump installed base estimates.
Segmentation dimensions modeled span product type, end user channel, technology tier, and application across the projection horizon. Valved versus non-valved mechanical configurations, antimicrobial versus standard material specifications, and hospital versus home healthcare delivery settings anchor volume and value disaggregation. CAGRs derive from replacement cycle analysis under evolving closed-system transfer device mandates and infection control protocol tightening. Forecast inputs incorporate state-level hazardous drug handling regulation adoption curves and silicone valve raw material supply elasticity assumptions.
Underlying assumptions cover Joint Commission accreditation compliance rates, FDA 510(k) clearance timeline stability, and medical-grade silicone supply concentration persistence, with deviation risk concentrated in accelerated EU MDR enforcement or German specialty chemical producer capacity constraints. Practitioners should keep alternative scenarios live as state-level hazardous drug handling mandates and antimicrobial material efficacy validation requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Equipment
Hydrotherapy Equipment Market
Clinical Equipment
Critical Care Equipment Market
Clinical Equipment
Patient Simulator Market
Clinical Equipment
Global Phototherapy Equipment Market
Clinical Equipment
Middle East and Africa Critical Care Equipment (CCE) Market
Clinical Equipment
Hong Kong Intensive Care Unit (ICU) Beds and Surfaces Market
Clinical Equipment
Patient Handling Equipment Market
Clinical Equipment
Biofeedback Equipment Market
Clinical Equipment
China Intensive Care Unit (ICU) Beds and Surfaces Market
Clinical Equipment
Portable Clinical Analyzer Market
Clinical Equipment
Patient Positioning Equipment Market
Clinical Equipment
Clinical Trial Equipment and Ancillary Solutions Market
Clinical Equipment
Total Lab Automation Market
Clinical Equipment
Acute Care Hospital Bed and Stretcher Market