
 United States Negative Pressure Wound Therapy Market | 2026-2036
United States Negative Pressure Wound Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
United States Negative Pressure Wound Therapy Market Intelligence
The capital-intensity divergence between single-use disposable specialists and capital equipment incumbents is collapsing as reimbursement pressure forces hybrid business models. Smith & Nephew leverages its integrated wound care portfolio to bundle NPWT with advanced dressings. Medela anchors its position through proprietary vacuum technology optimized for home care portability. Cardinal Health competes on distribution density, extending same-day delivery capabilities to outpatient surgical centers.
Negative Pressure Wound Therapy applies sub-atmospheric pressure through sealed dressings to accelerate healing by promoting granulation tissue formation, managing exudate, and reducing edema in acute and chronic wounds. Portable devices lead unit volume as home care migration shifts clinical workflows outside hospital walls, while remote monitoring systems represent the fastest-growing technology segment by attaching digital revenue streams to hardware placements. Fixed devices retain margin concentration in acute care settings where higher suction precision commands premium positioning.
FDA 510(k) clearance pathways govern device commercialization, while CMS national coverage determinations and local contractor pricing directly shape provider adoption economics across Medicare fee-for-service populations. State Medicaid programs in California and New York layer additional prior authorization requirements that fragment access patterns. Stakeholders must monitor CMS innovation center demonstrations for signs of bundled payment expansion into outpatient wound management.
Market Dynamics
CMS reimbursement compression is forcing NPWT vendors to abandon pure hardware sales for hybrid consumable-recurring models, collapsing the traditional capital equipment margin structure across outpatient surgical networks.
Growth Catalysts
- Diabetic wound prevalence:Texas, Florida, and California now account for the majority of chronic wound incidence, with aging demographics expanding addressable patient populations faster than national averages.
- IRAs durable medical equipment provisions:Medicare price transparency mandates and competitive bidding adjustments are accelerating home care vendor consolidation, favoring scaled distributors with same-day logistics.
- Portable suction miniaturization:Lithium-ion battery density improvements and pump efficiency gains enable true ambulatory NPWT, unlocking post-acute settings previously unreachable by fixed-installation systems.
Market Restraints
- Silicone foam supply concentration:Three domestic converters control medical-grade foam substrate production, creating single-source vulnerability for dressing manufacturers.
- FDA 510(k) backlog:Clearance timelines for software-enabled NPWT devices now stretch 14-18 months, delaying remote monitoring feature launches.
- Advanced moist wound dressings:Bioactive alginate and antimicrobial silver technologies capture lower-acuity cases that previously converted to NPWT, compressing entry-tier demand.
Strategic Opportunities
- Rural hospital closures:Texas and Mississippi facility shutdowns displace wound care capacity into home health agencies, creating first-mover advantage for portable device vendors with telehealth integration.
- CMS bundled payment demonstrations:Accountable Care Organization pilot programs in Florida and California now include outpatient wound episodes, aligning provider incentives toward prevention and early NPWT intervention.
- Bluetooth-enabled pressure sensing:Convergence of negative pressure pumps with continuous wound bed monitoring creates subscription revenue streams and adherence data monetization.
Industry Challenges
- Wound care specialist scarcity:Certified wound ostomy continence nurses remain concentrated in urban academic centers, limiting protocol adherence in dispersed home health markets.
- HIPAA-compliant data architecture:Remote monitoring platforms face 12-18 month security validation cycles with hospital IT departments, delaying commercial rollout.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Negative Pressure Wound Therapy Market |
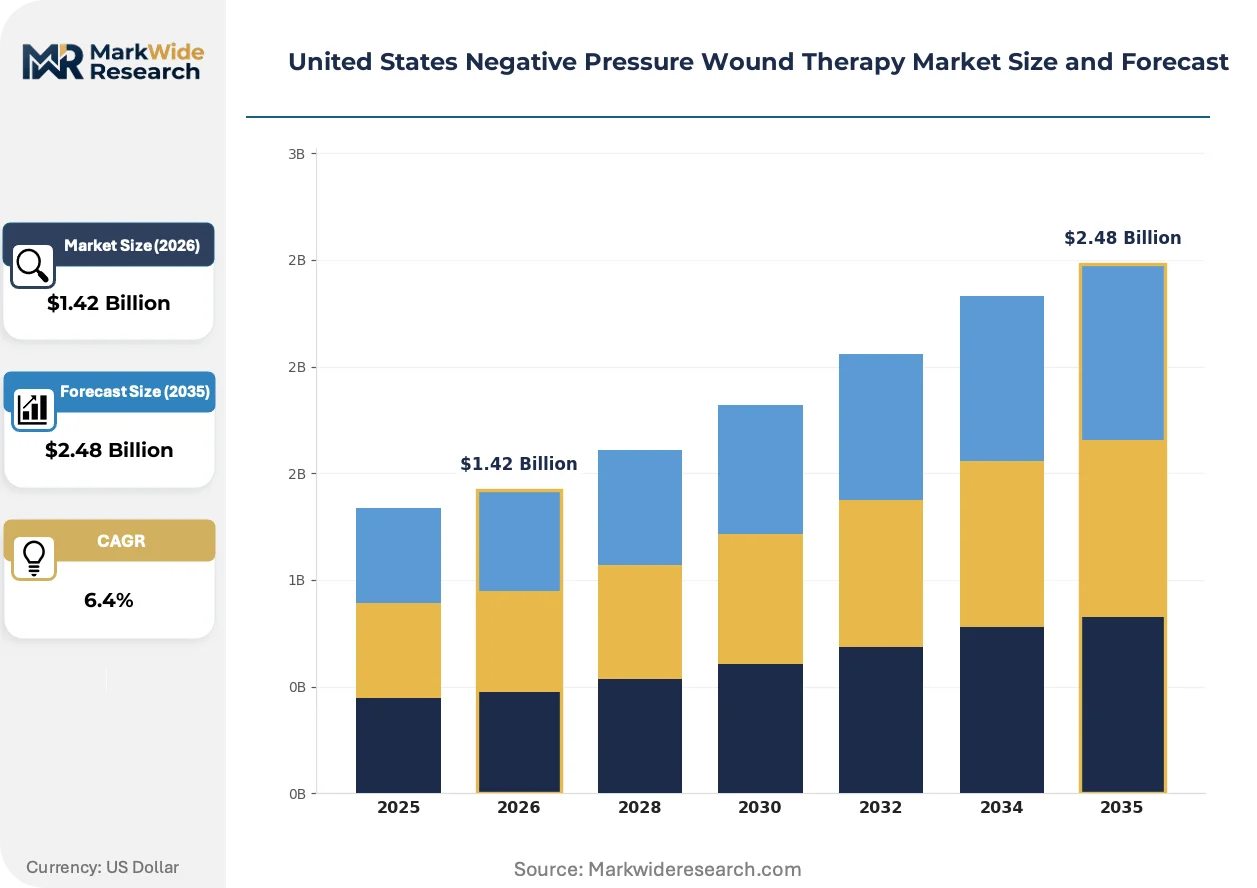
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.48 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Devices, Fixed Devices, Traditional Systems, Disposable Systems Technology: Electromagnetic Technology, Vacuum-Assisted Closure, Pressure Sensor Technology, Remote Monitoring Systems End User: Hospitals, Home Care, Long-term Care Facilities, Rehabilitation Centers Application: Chronic Wounds, Surgical Wounds, Traumatic Wounds, Burns |
| Companies Covered | 3M, Smith & Nephew, ConvaTec, Mölnlycke Health Care, Cardinal Health, Medela, DeRoyal Industries, Talley Group, Paul Hartmann, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Negative Pressure Wound Therapy Market Strategic Shifts & Innovations
Digital attachment strategies and care setting migration are restructuring how NPWT hardware generates returns, with software-enabled service layers now commanding valuation premiums over standalone device sales.
Single-use disposable pump canisters are decomposing the traditional capital-resale model by eliminating sterilization logistics and enabling true rental economics. Outpatient surgical centers in Arizona and Nevada now specify disposable-only contracts, compressing payback periods from 36 months to under 90 days. This shift is decomposing incumbent installed-base advantages and forcing hardware specialists to acquire consumable capabilities.
FDA draft guidance on software-as-medical-device classification now requires cybersecurity documentation for NPWT platforms with cloud connectivity. The agency's 2023 pre-submission meetings have added 4-6 months to development timelines for remote monitoring features. Home care vendors with existing 510(k) clearances for standalone pumps face the steepest compliance burden as they retrofit connectivity modules.
Hospital purchasing committees now unbundle after-sales service contracts from device procurement, awarding preventive maintenance to third-party clinical engineering firms. This fragmentation is visible most acutely in California health systems, where Kaiser Permanente and Sutter Health have centralized NPWT fleet management through independent service organizations, compressing OEM service margins by 40-60 percent.
United States Negative Pressure Wound Therapy Market Segmentation
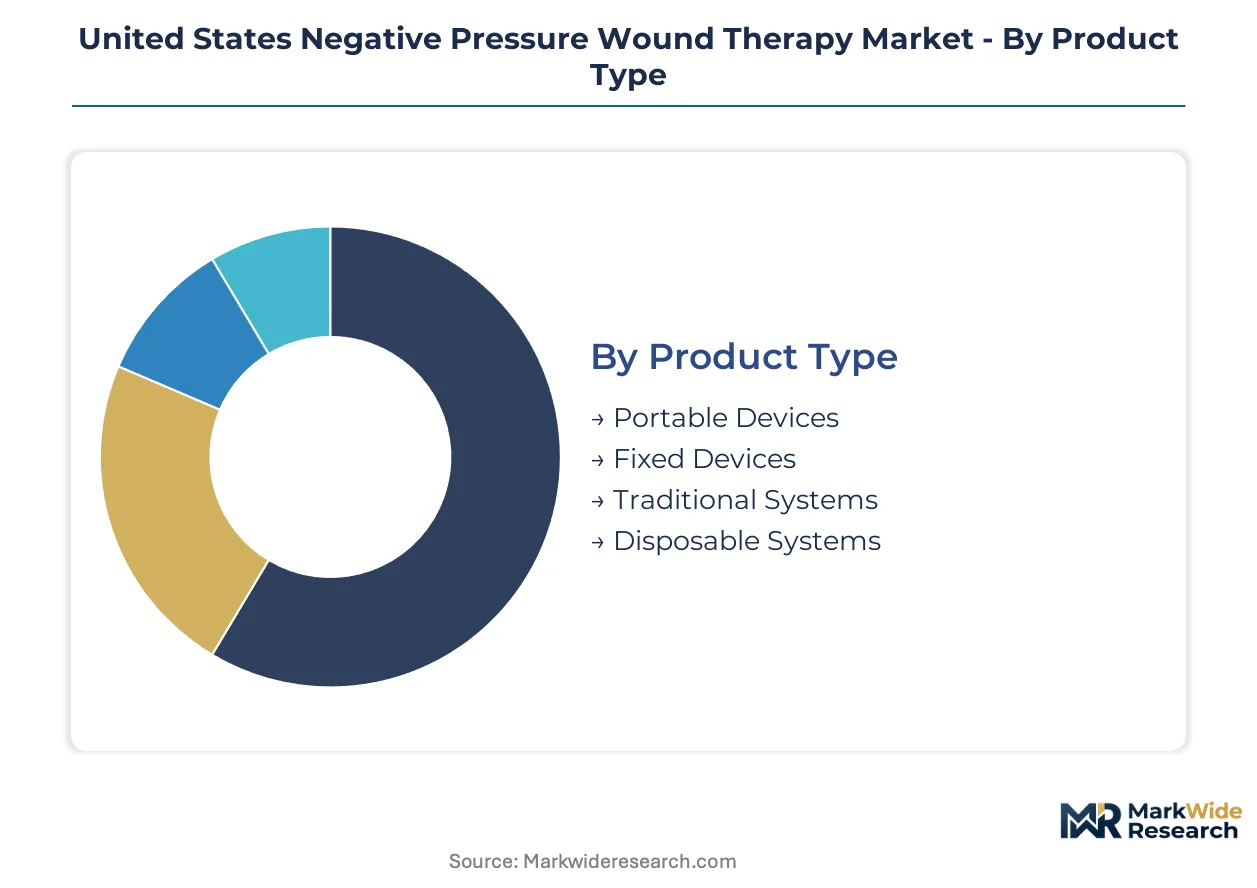
NPWT market segmentation reveals how reimbursement pressure and care setting migration reshape vendor priorities. Product architecture, sensing technology, patient location, and wound etiology each create distinct competitive arenas with diverging margin structures.
Product Type:
Portable devices dominate Texas and Florida home health deployments where rural hospital closures displace wound care capacity. Fixed systems concentrate in California academic medical centers where capital budgets support installed-base contracts.
- Portable Devices:Lithium-ion battery miniaturization enables true ambulatory suction. Demand clusters in Texas, Florida, and California home health agencies where post-acute migration accelerates fastest.
- Fixed Devices:Precision suction control and institutional sterilization protocols define acute care installations. California health systems including Kaiser Permanente and Sutter Health centralize fleet management through independent service organizations.
- Traditional Systems:Reusable pump-canister configurations with established 510(k) clearances.
- Disposable Systems:Single-use pump canisters eliminate sterilization logistics, compressing payback periods from 36 months to under 90 days in Arizona and Nevada outpatient surgical centers.
Portable devices hold the largest share; momentum sits with disposable systems as reimbursement pressure collapses capital-resale economics.
Technology:
Cost tier stratification separates premium sensing platforms from commodity vacuum hardware. Remote connectivity commands subscription revenue premiums while basic electromagnetic pumps compete on acquisition price.
- Electromagnetic Technology:Core vacuum generation architecture with mature component supply chains.
- Vacuum-Assisted Closure:Proprietary sealed dressing interfaces with established clinical evidence bases.
- Pressure Sensor Technology:Continuous wound bed monitoring enables adherence tracking and outcome documentation for Medicare reimbursement justification.
- Remote Monitoring Systems:Bluetooth-enabled platforms with cloud connectivity face FDA 510(k) backlog stretching 14-18 months. HIPAA-compliant data architecture validation with hospital IT departments adds 12-18 month security cycles, delaying commercial rollout.
Remote monitoring systems are gaining share fastest; installed base concentration remains with vacuum-assisted closure platforms.
End User:
Customer type determines procurement channel and service intensity. Hospital committees unbundle service contracts while home health agencies prioritize same-day logistics capability.
- Hospitals:Acute care settings retain fixed-device margin concentration where higher suction precision commands premium positioning.
- Home Care:Post-acute migration shifts clinical workflows outside hospital walls. Medicare reimbursement policy shifts under CMS reshape provider economics for durable medical equipment.
- Long-term Care Facilities:Skilled nursing environments with intermittent wound care protocol oversight.
- Rehabilitation Centers:Post-surgical recovery settings where portable NPWT bridges acute-to-home transitions.
Home care holds the largest share; momentum sits with hospitals as bundled payment demonstrations align provider incentives toward early intervention.
Application:
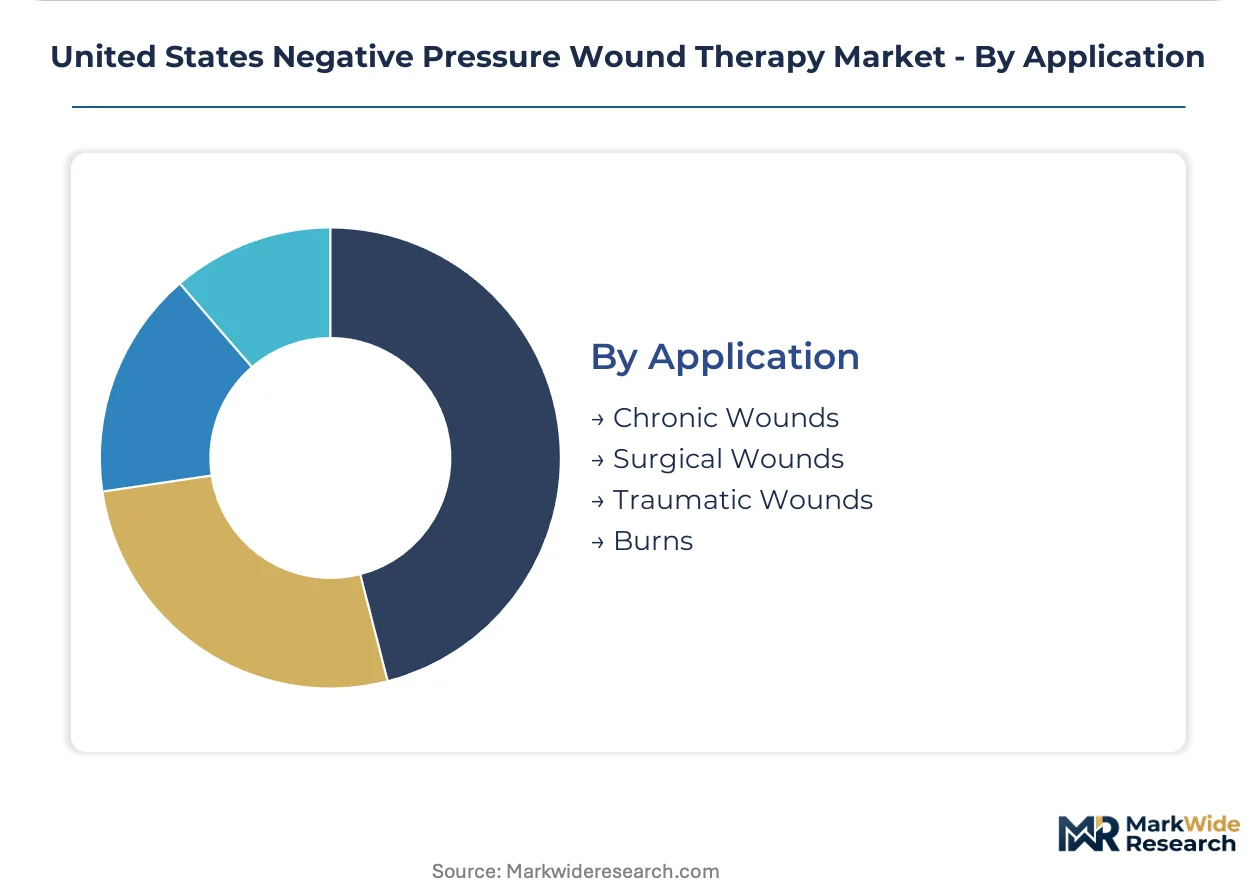
Wound etiology dictates therapy duration, reimbursement coding, and competitive alternatives. Chronic conditions generate recurring revenue streams while acute applications face advanced dressing substitution.
- Chronic Wounds:Diabetic foot ulcers and pressure injuries drive Texas, Florida, and California demand where aging demographics expand addressable populations faster than national averages.
- Surgical Wounds:Post-operative dehiscence prevention in outpatient surgical centers. Bioactive alginate and antimicrobial silver technologies capture lower-acuity cases that previously converted to NPWT.
- Traumatic Wounds:Acute injury management with shorter therapy duration and higher device turnover.
- Burns:Specialized exudate management requirements with dedicated clinical protocols.
Chronic wounds hold the largest share; momentum sits with surgical wounds as outpatient procedure volume expands and disposable systems penetrate ambulatory settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas and Florida command premium pricing power over California due to faster home health agency consolidation and fewer competing wound care centers, while reimbursement rates in California health systems compress margins through centralized fleet management contracts.
Texas
Rural hospital closures in the Permian Basin and Rio Grande Valley displace chronic wound patients into home health networks, expanding portable NPWT addressable populations. CMS competitive bidding adjustments for durable medical equipment accelerate vendor consolidation toward scaled distributors. Dallas-Fort Worth anchors the state's largest concentration of home health agencies deploying disposable pump systems.
Florida
Aging demographics in the Tampa Bay and South Florida corridors generate diabetic foot ulcer incidence exceeding national averages by substantial margins. Accountable Care Organization pilot programs now bundle outpatient wound episodes, aligning provider incentives toward early NPWT intervention. Miami-Dade and Broward counties concentrate the state's highest density of skilled nursing facilities adopting remote monitoring platforms.
California
Kaiser Permanente and Sutter Health centralize NPWT fleet management through independent service organizations, compressing OEM service margins and procurement pricing. State Medicaid prior authorization requirements fragment access patterns across county lines. Los Angeles and San Francisco Bay Area academic medical centers retain fixed-device installations where capital budgets support precision suction contracts.
Arizona
Outpatient surgical centers in Phoenix and Tucson specify disposable-only NPWT contracts, compressing payback periods from 36 months to under 90 days. Medicare price transparency mandates accelerate same-day logistics competition among durable medical equipment suppliers. The state's surgical volume growth outpaces infrastructure expansion, pushing post-acute recovery into home settings.
Nevada
Las Vegas metropolitan surgical centers mirror Arizona's disposable-system procurement preferences, favoring vendors with sterilization-free logistics. Limited wound care specialist availability in rural counties drives telehealth-integrated portable device adoption. Northern Nevada health systems lag Southern Nevada in bundled payment participation, creating a two-speed reimbursement environment.
United States Negative Pressure Wound Therapy Market Key Industry Players
Concentration sits with integrated wound care portfolios and distribution-heavy service models rather than pure-play device manufacturers. The vendor base stratifies across three tiers: multinational health conglomerates with bundled dressing offerings, medical device specialists with proprietary vacuum technology, and scaled distributors competing on logistics density. Competitive moves center on hybrid consumable-recurring model adoption and same-day delivery capability extension into outpatient networks.
Within the integrated health conglomerate tier, 3M and Smith & Nephew exemplify portfolio breadth strategies that bundle NPWT hardware with advanced wound dressing lines. Among distribution-anchored competitors, Cardinal Health occupies a position emphasizing supply chain density and same-day fulfillment infrastructure. Medela represents the specialized vacuum technology archetype, with its positioning reflecting proprietary pump miniaturization optimized for post-acute portability requirements.
| Leading Market Players |
|---|
| 3M |
| Smith & Nephew |
| ConvaTec |
| Mölnlycke Health Care |
| Cardinal Health |
| Medela |
| DeRoyal Industries |
| Talley Group |
| Paul Hartmann |
| Others |
Cost & Logistics Intelligence
Single-use disposable pump canisters replacing reusable sterilizable systems simultaneously relocate manufacturing toward domestic medical-grade foam converters and collapse rental pricing economics from multi-year capital recovery to sub-90-day payback cycles. This substitution dynamic concentrates procurement leverage with outpatient surgical centers in Arizona and Nevada while eroding traditional equipment lessors' margin structures.
Pricing Analysis
The customization-premium spread separates configured-to-order portable systems with Bluetooth-enabled pressure sensing from standard electromagnetic pump configurations. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance tier, after-sales service bundling, and geographic delivery density. Cost compression in the standard tier is intensifying because CMS competitive bidding adjustments for durable medical equipment accelerate vendor consolidation. Home health agencies exhibit highest price sensitivity due to Medicare reimbursement compression, while California academic medical centers show lowest sensitivity where capital budgets support precision suction contracts.
Supply Chain Analysis
Inventory-strategy preferences favor just-in-time logistics for single-use disposables against strategic stockpiling of lithium-ion battery cells and medical-grade silicone foam substrates. Domestic production of pump housings and canister assemblies draws from China, South Korea, and Japan for battery cell supply, while medical-grade foam substrates rest on three domestic converters in Texas and Ohio. Single-source vulnerability concentrates in silicone foam substrate production where medical-grade certification limits qualified suppliers. Distribution runs through scaled durable medical equipment distributors with same-day fulfillment networks anchored in Dallas-Fort Worth, Phoenix, and Miami metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States Negative Pressure Wound Therapy Market constitutes a defensive-moat opportunity anchored in FDA 510(k) regulatory entrenchment, where clearance timelines stretching 14-18 months create durable barriers against fast-follower competition.
For Market Incumbents: Shield installed-base positions by acquiring disposable pump canister manufacturing capabilities and securing captive supply agreements with domestic medical-grade foam converters. Backward integration into silicone foam substrate production mitigates single-source vulnerability threatening Arizona and Nevada outpatient surgical center contracts. Channel control through exclusive same-day logistics partnerships with Dallas-Fort Worth and Miami distribution hubs reinforces switching costs against emerging portable device specialists.
For New Entrants and Emerging Players: FDA 510(k) clearance fast-tracks for software-as-medical-device platforms with pre-submission meeting strategies compress development timelines by 4-6 months. Rural hospital closure displacement zones in Texas Permian Basin and Mississippi Delta offer most penetrable geography where telehealth-integrated portable systems address wound care specialist scarcity. Go-to-market execution through home health agency direct procurement bypasses hospital purchasing committee consolidation.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed durable medical equipment distributors lacking disposable manufacturing capabilities but possessing dense same-day logistics networks. Five-to-ten-year viability hinges on hybrid consumable-recurring model adoption rates and CMS bundled payment demonstration expansion into outpatient wound episodes. Watch CMS Innovation Center pilot program announcements in Florida and California as inflection indicators for provider incentive alignment toward early NPWT intervention.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Cybersecurity documentation for cloud-connected pumps now extends clearance timelines by 4-6 months. |
| Hospital System Partnership | Kaiser Permanente and Sutter Health centralized fleet management contracts compress OEM service margins. |
| Software Companion Development | Bluetooth-enabled pressure sensing platforms create subscription revenue streams and adherence data monetization. |
| Reimbursement Strategy | CMS bundled payment demonstrations in Florida ACO pilots align provider incentives toward prevention. |
| Backward Integration | Captive supply of medical-grade silicone foam mitigates single-source concentration among three domestic converters. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA 510(k) clearance databases, CMS Medicare reimbursement filings, and hospital procurement contract registries. Clinical interviews with wound ostomy continence nurses, biomedical engineers, and GPO contracts managers informed demand-side validation. Supply-side perspectives derived from conversations with durable medical equipment distributors, medical-grade foam converters, and lithium-ion battery suppliers. Bottom-up unit volume estimates triangulated against top-down Medicare claims data and state Medicaid prior authorization records.
Segmentation dimensions modeled span product architecture (portable, fixed, disposable, traditional), sensing technology tier (electromagnetic, vacuum-assisted closure, pressure sensor, remote monitoring), end-user setting (hospitals, home care, long-term care, rehabilitation centers), and wound etiology (chronic, surgical, traumatic, burns). CAGRs derived from regression analysis of historical Medicare reimbursement trends, diabetic wound prevalence projections by state, and lithium-ion battery cost curves. Forecast inputs incorporate rural hospital closure displacement patterns in Texas and Mississippi and CMS competitive bidding adjustment schedules.
Underlying assumptions cover CMS reimbursement stability, silicone foam substrate supply continuity, and lithium-ion battery cost decline trajectories, with deviation risk concentrated in FDA software-as-medical-device classification guidance revisions and HIPAA-compliant data architecture validation delays. Revision becomes warranted when CMS bundled payment demonstration participation thresholds cross 50% of Florida and California ACOs or when medical-grade foam substrate supplier consolidation reduces qualified domestic converters below two.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Europe Negative Pressure Wound Therapy Market
Wound Care
Europe Advanced Wound Care Market
Wound Care
Italy Wound Care Market
Wound Care
North America Wound Care Management Market
Wound Care
Chronic Wound Care Market
Wound Care
Wound Management Market
Wound Care
Global Surgical Drains/Wound Drainage Market
Wound Care
Asia Pacific Advanced Wound Care Market
Wound Care
Wound Closure Market
Wound Care
Surgery Medical Bandage Market
Wound Care
Enzymatic Wound Debridement Market
Wound Care
Philippines Wound Care Market
Wound Care
Burn Care Centers Market
Wound Care
Brazil Wound Care Management Devices Market
Wound Care
Wound Contact Layer Dressing Market
Wound Care
Wound Healing Nutrition Market