
 Global Negative Pressure Wound Therapy (NPWT) Devices Market | 2026-2036
Global Negative Pressure Wound Therapy (NPWT) Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Negative Pressure Wound Therapy (NPWT) Devices Market Foresight
The EU Medical Device Regulation (MDR) is decoupling market access from legacy CE certifications, forcing manufacturers to rebuild technical documentation and clinical evidence portfolios. Smith & Nephew leverages its vertically integrated wound care portfolio to sustain premium positioning across hospital and homecare channels. 3M anchors its competitive stance through advanced dressing materials that integrate with proprietary pump platforms. Mölnlycke Health Care specializes in European market penetration, navigating notified body bottlenecks with established quality management systems.
Negative Pressure Wound Therapy (NPWT) Devices apply controlled sub-atmospheric pressure (typically -50 to -175 mmHg) through sealed wound dressings to promote granulation tissue formation, reduce edema, and accelerate healing in acute and chronic wounds. Portable NPWT systems are capturing share as ambulatory surgical procedures expand and homecare reimbursement broadens, while traditional canister-based systems retain dominance in intensive hospital settings. Electromechanical devices with smart monitoring capabilities represent the fastest-growing technology segment, though disposable single-use systems command margin pools through simplified logistics and reduced infection control overhead. Chronic wounds anchor application demand, with surgical wounds trailing as procedural volumes normalize post-pandemic.
The FDA maintains stringent 510(k) clearance pathways for powered suction devices, while the EU MDR imposes heightened clinical evaluation requirements that extend time-to-market for new entrants. Japan's PMDA enforces separate quality system inspections that filter out manufacturers lacking localized regulatory infrastructure. Stakeholders must monitor evolving homecare reimbursement codes across Medicare, NHS England, and Germany's G-BA, as these determine whether portable NPWT shifts from hospital discharge accessory to standard-of-care continuity treatment.
Market Dynamics
Portable NPWT systems are compressing hospital-centric revenue models as homecare reimbursement frameworks in the United States, Germany, and Japan expand coverage continuity. This shift forces manufacturers to reconfigure service architectures around patient mobility rather than institutional procurement cycles.
Growth Catalysts
- EU MDR compliance deadlines:Manufacturers rebuilding technical documentation under the Medical Device Regulation create openings for suppliers with established quality management systems to capture displaced market share.
- Homecare infrastructure expansion:Medicare's evolving reimbursement codes for portable NPWT transform hospital discharge accessories into standard continuity-of-care treatments across the United States.
- Diabetic patient volume concentration:Aging demographics in Japan and Germany sustain chronic wound prevalence that anchors clinical adoption of sub-atmospheric pressure protocols.
Market Restraints
- Silicone and acrylic adhesive input volatility:Advanced dressing material costs fluctuate with petrochemical feedstock markets, compressing margin pools for disposable single-use system manufacturers.
- Notified body bottleneck concentration:EU MDR implementation strains European certification capacity, extending time-to-market for new electromechanical device entrants lacking established notified body relationships.
- Advanced moist wound therapy substitution:Bioactive dressings and enzymatic debridement systems compete for chronic wound cases where negative pressure offers marginal incremental benefit.
Strategic Opportunities
- India's underpenetrated homecare segment:CDSCO regulatory pathway maturation combined with private insurance expansion creates whitespace for portable NPWT platforms outside institutional settings.
- Smart monitoring convergence:Integration of pressure sensors with wireless telemetry enables remote patient monitoring reimbursement codes that differentiate electromechanical offerings.
- NHS England community care mandates:Policy directives shifting wound management from acute trusts to community nursing services accelerate demand for canister-free disposable systems.
Industry Challenges
- Biocompatibility testing talent scarcity:ISO 10993 evaluation expertise concentrates in contract research organizations, elongating internal R&D timelines for novel dressing materials.
- Legacy hospital procurement system integration:Portable NPWT platforms require API connectivity with electronic health record systems that fragment across Epic, Cerner, and regional installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Negative Pressure Wound Therapy (NPWT) Devices Market |
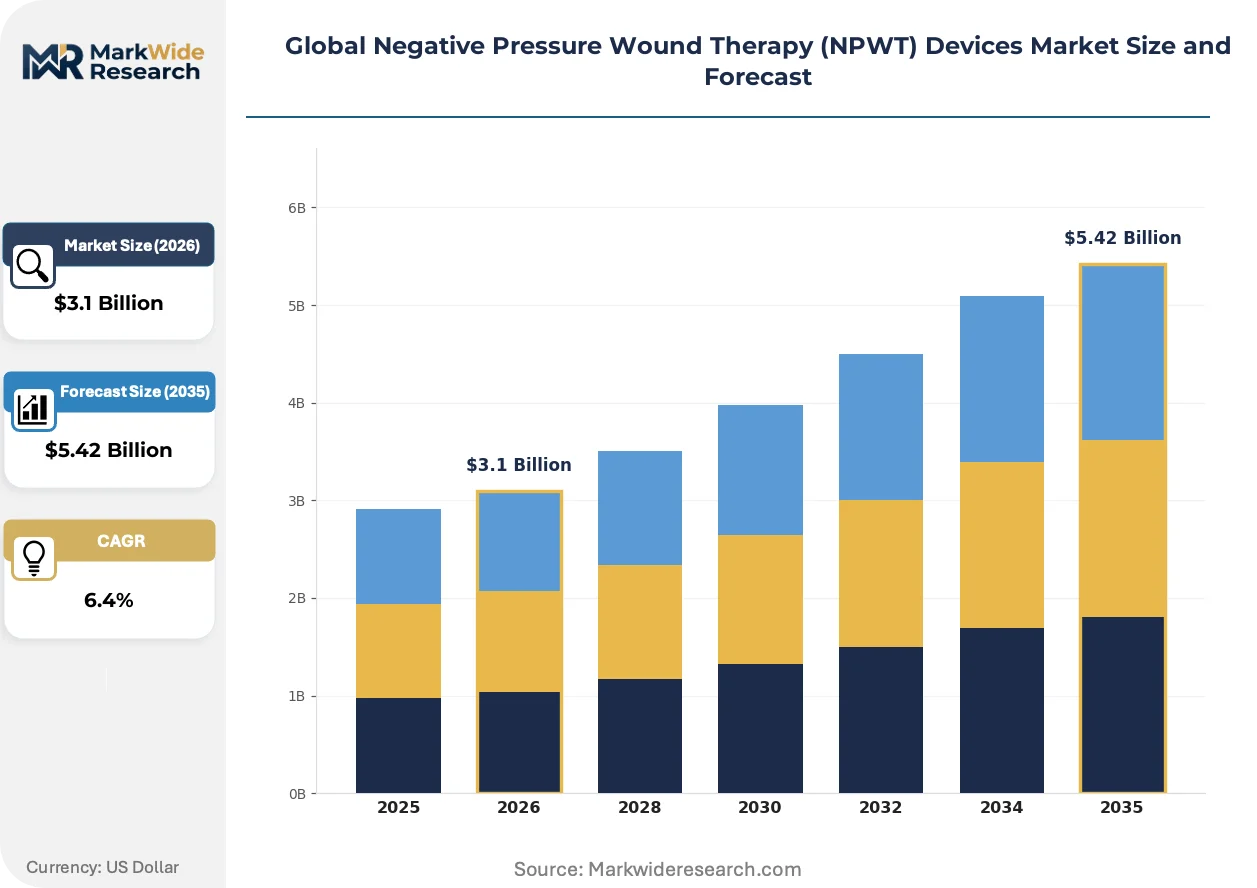
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $5.42 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional NPWT, Single-Use NPWT, Portable NPWT, Mobile NPWT Technology: Vacuum Assists, Electromechanical Devices, Smart Monitoring, Disposable Systems End User: Hospitals, Homecare, Clinics, Surgical Centers Application: Chronic Wounds, Surgical Wounds, Traumatic Wounds, Burn Wounds |
| Companies Covered | Smith & Nephew, 3M, ConvaTec, Mölnlycke Health Care, Cardinal Health, Medela, DeRoyal Industries, Paul Hartmann, Talley Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Negative Pressure Wound Therapy (NPWT) Devices Market Shifts & Advancements
Electromechanical smart pumps are displacing traditional vacuum sources through sensor integration and algorithmic pressure modulation. This technological pivot compresses the service boundary between device and digital health platforms.
Single-use disposable NPWT systems are consolidating market share in ambulatory surgical settings where infection control protocols prioritize elimination of reusable canister handling. Outpatient surgery centers in Germany and Japan adopt these systems to reduce central sterile processing overhead. The technology is consolidating logistics requirements around unit-dose distribution models that bypass traditional durable medical equipment channels.
The EU MDR's heightened clinical evaluation requirements are extending certification timelines for powered suction devices without predicate equivalence pathways. Manufacturers must generate prospective clinical data for granulation tissue formation claims that previously relied on literature reviews. Small and mid-cap entrants lacking European regulatory infrastructure face exclusion as notified body capacity concentrates among established quality system holders.
Hospital procurement committees are unbundling device acquisition from dressing supply contracts that historically locked purchasers into proprietary ecosystems. Group purchasing organizations in the United States negotiate separate agreements for pump hardware and consumable components. This fragmentation enables multi-source dressing strategies that commoditize adhesive foam and film layers while preserving premium positioning for algorithm-enabled pump platforms.
Global Negative Pressure Wound Therapy (NPWT) Devices Market Segmentation
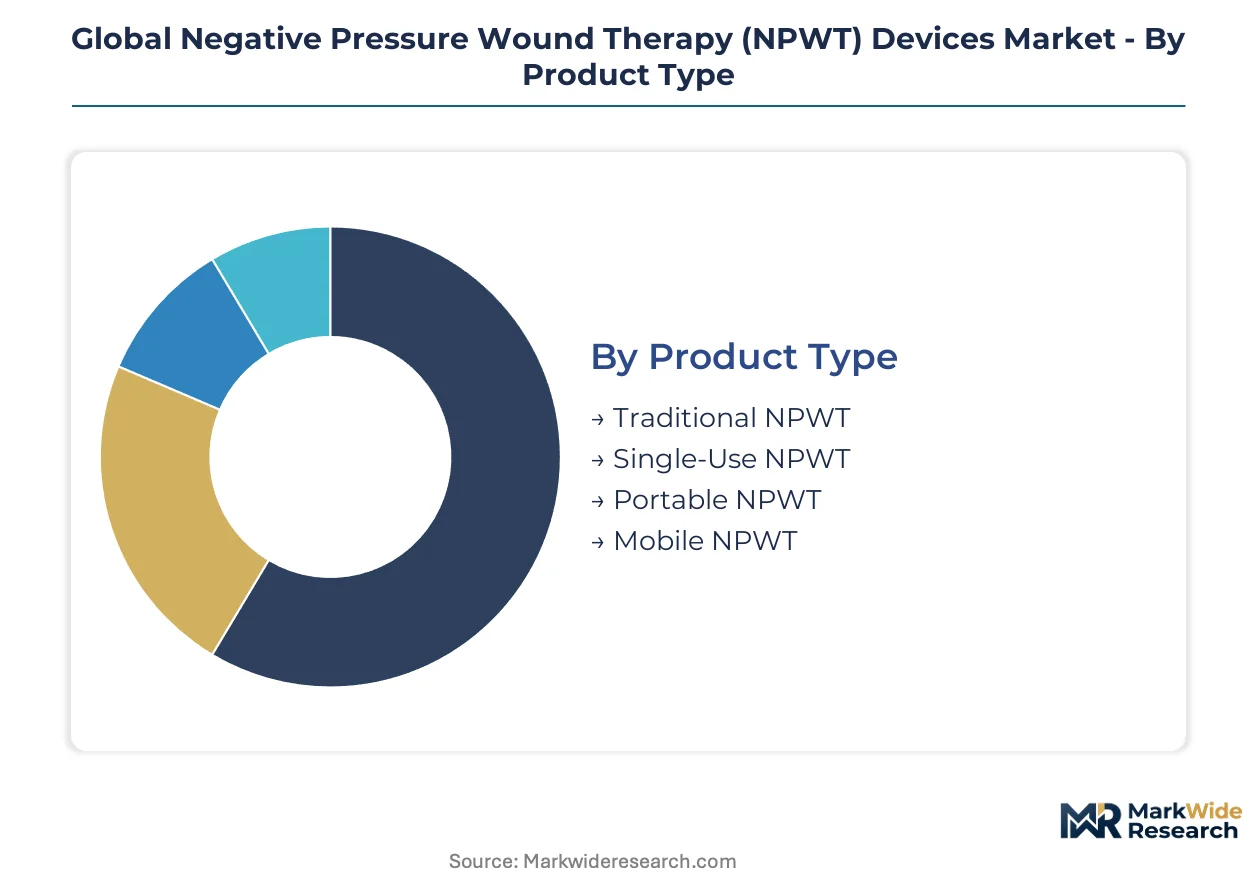
NPWT device segmentation reveals divergent margin structures across stationary hospital systems and mobile homecare platforms. Product architecture choices determine reimbursement eligibility, supply chain complexity, and competitive defensibility against moist wound therapy substitutes.
Product Type:
Volume concentrates in institutional canister-based systems while premium capture shifts toward battery-powered portable units.
- Traditional NPWT:Stationary vacuum systems with reusable canisters dominate intensive care and operating room workflows. Hospitals in Germany and Japan anchor demand through established central sterile processing infrastructure and bundled procedure reimbursement.
- Single-Use NPWT:Disposable closed-circuit systems eliminate cross-contamination risk in ambulatory settings. Surgical centers across the United States adopt these platforms to bypass durable medical equipment logistics and reduce infection control overhead.
- Portable NPWT:Battery-powered pumps with reduced canister capacity enable patient mobility during extended therapy. Medicare reimbursement expansion for home-based wound management accelerates clinical adoption outside institutional boundaries.
- Mobile NPWT:Wearable ultra-lightweight systems integrate with patient garments for continuous therapy during daily activities. Japan's aging diabetic population drives demand for discreet devices that preserve quality of life during chronic wound treatment.
Today's leader: Traditional NPWT. Tomorrow's challenger: Portable NPWT.
Technology:
Electromechanical sophistication separates premium-priced platforms from commodity vacuum sources.
- Vacuum Assists:Basic suction mechanisms without algorithmic modulation serve cost-sensitive procurement channels. Group purchasing organizations in the United States negotiate these systems as entry-tier options within multi-source contracts.
- Electromechanical Devices:Microprocessor-controlled pressure regulation with intermittent and continuous modes commands price premiums in hospital settings. Smart pump platforms from established manufacturers integrate proprietary dressing interfaces that resist commoditization.
- Smart Monitoring:Wireless telemetry with pressure sensor feedback enables remote patient monitoring reimbursement codes. FDA clearance pathways for connected devices extend development timelines but differentiate offerings in competitive homecare tenders.
- Disposable Systems:Pre-sterilized single-unit vacuum mechanisms eliminate maintenance protocols and simplify logistics. NHS England community care mandates accelerate substitution of reusable hardware with canister-free alternatives in district nursing services.
Electromechanical Devices command current margins. Smart Monitoring climbs the fastest toward connected health reimbursement.
End User:
Procurement authority fragments across institutional committees and individual patient prescriptions.
- Hospitals:Integrated delivery networks negotiate enterprise contracts covering pump hardware, disposable supplies, and service agreements. Value analysis committees in the United States unbundle dressing components from proprietary pump ecosystems to enable multi-source strategies.
- Homecare:Durable medical equipment suppliers and visiting nurse services coordinate portable NPWT delivery. Germany's G-BA reimbursement decisions determine whether home-based therapy qualifies as standard continuity-of-care or discretionary discharge accessory.
- Clinics:Outpatient wound care centers balance infection control protocols against capital equipment constraints. Single-use disposable systems penetrate this channel through simplified inventory management and reduced sterilization infrastructure.
- Surgical Centers:Ambulatory procedure volumes normalize post-pandemic with heightened emphasis on same-day discharge. Portable NPWT supports accelerated patient throughput while managing surgical site complications outside hospital admission.
Hospitals retain procurement volume dominance. Homecare captures the steepest expansion trajectory as reimbursement frameworks mature.
Application:
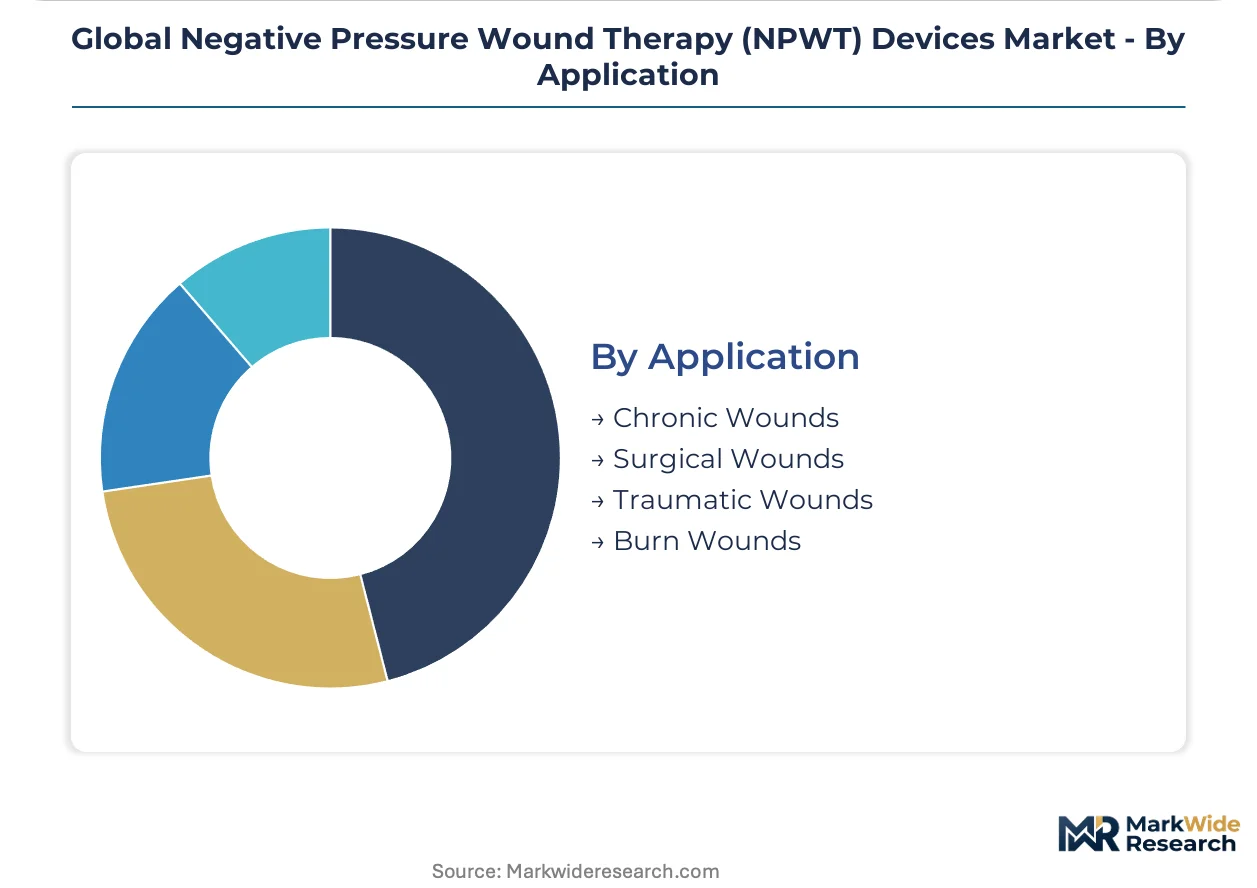
Chronic wound prevalence anchors utilization while acute surgical applications recover procedural momentum.
- Chronic Wounds:Diabetic foot ulcers, pressure injuries, and venous leg ulcers sustain recurring demand for extended therapy courses. Aging demographics in Japan and Germany concentrate patient volumes requiring granulation tissue promotion through sub-atmospheric pressure protocols.
- Surgical Wounds:Post-operative dehiscence prevention and closed incision management drive adoption in orthopedic and cardiovascular procedures. Elective surgery normalization restores procedural volumes that contracted during pandemic disruption.
- Traumatic Wounds:Acute injury management in emergency departments and trauma centers applies NPWT for temporary wound closure. Military and civilian mass casualty preparedness programs stock portable systems for field deployment scenarios.
- Burn Wounds:Partial-thickness burn management leverages negative pressure for exudate control and autograft preparation. Specialized burn centers in the United States integrate NPWT into multimodal protocols alongside biologic dressings and enzymatic debridement.
Chronic Wounds anchor revenue stability. Surgical Wounds represent the recovery-dependent upside case.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized wound care nursing talent concentrates in Germany, Japan, and the United States, anchoring clinical adoption and training infrastructure for sub-atmospheric pressure protocols across diverse reimbursement environments.
United States
Medicare's expanding reimbursement codes for portable NPWT transform homecare delivery models. The FDA maintains stringent 510(k) clearance pathways for powered suction devices with connected monitoring capabilities. Minneapolis-St. Paul anchors device manufacturing clusters where electromechanical pump production integrates with advanced dressing material development.
Germany
Aging demographics sustain chronic wound prevalence requiring extended granulation tissue therapy courses. The EU MDR imposes heightened clinical evaluation requirements that extend certification timelines for new electromechanical entrants. Tuttlingen in Baden-Württemberg concentrates surgical instrument manufacturing expertise that extends into negative pressure wound system component supply.
Japan
Diabetic patient volumes among elderly populations drive demand for discreet wearable therapy systems. The PMDA enforces separate quality system inspections that filter manufacturers lacking localized regulatory infrastructure. Osaka-Kobe manufacturing corridors host precision electromechanical component suppliers serving domestic pump assembly operations.
United Kingdom
NHS England community care mandates accelerate shift from acute trust wound management to district nursing services. MHRA post-Brexit regulatory pathways diverge from EU MDR timelines while maintaining equivalent safety standards. Yorkshire and Humber regional health economies pilot integrated wound care pathways combining portable NPWT with telemedicine monitoring.
India
Private insurance expansion creates whitespace for portable platforms outside institutional settings as homecare infrastructure matures. CDSCO regulatory pathway maturation streamlines import licensing for electromechanical medical devices. Hyderabad's medical technology corridor attracts contract manufacturing for disposable single-use NPWT systems targeting price-sensitive procurement channels.
Global Negative Pressure Wound Therapy (NPWT) Devices Market Competitive Landscape
The competitive structure tilts toward diversified medical technology conglomerates with vertically integrated wound care portfolios. Hospital procurement committees increasingly unbundle device acquisition from consumable supply contracts, fragmenting historical ecosystem lock-in. Three archetypes dominate: full-spectrum wound care specialists, diversified industrial conglomerates with healthcare divisions, and focused electromechanical pump manufacturers. Capacity expansion in disposable single-use systems and strategic partnerships for smart monitoring integration represent the dominant competitive moves reshaping positioning.
Within the diversified conglomerate tier, 3M and Cardinal Health exemplify scale-driven resource allocation across adhesive materials and distribution infrastructure. Smith & Nephew occupies a position as the archetypal wound care specialist, while Mölnlycke Health Care represents European market penetration expertise navigating notified body bottlenecks. These three entities anchor the competitive topography through distinct capability configurations rather than overlapping strategic postures.
| Leading Market Players |
|---|
| Smith & Nephew |
| 3M |
| ConvaTec |
| Mölnlycke Health Care |
| Cardinal Health |
| Medela |
| DeRoyal Industries |
| Paul Hartmann |
| Talley Group |
| Others |
Supply & Pricing Matrix
Medicare's expanding portable NPWT reimbursement codes in the United States force manufacturers to reconfigure service architectures around patient mobility, compressing traditional hospital procurement margins and shifting pricing power toward logistics-efficient disposable platforms.
Pricing Analysis
Bundled device-and-consumable contracts historically dominated hospital procurement, though group purchasing organizations now unbundle these agreements to enable multi-source dressing strategies. Three-tier pricing structure across premium algorithm-enabled pumps, standard electromechanical systems, and economy vacuum-assist units reflects FDA clearance tier and wireless telemetry capability. Cost compression in economy tiers intensifies as silicone and acrylic adhesive feedstock volatility squeezes disposable single-use manufacturers. Ambulatory surgical centers exhibit highest price sensitivity due to capital constraints, while integrated delivery networks prioritize total cost-of-ownership over unit pricing.
Supply Chain Analysis
ISO 10993 biocompatibility certification and FDA 510(k) clearance gating concentrates electromechanical pump assembly in the United States, Germany, and Japan where quality system infrastructure is established. Supply chains draw from precision-machined components in Baden-Württemberg, advanced polymers in Osaka-Kobe corridors, and contract sterilization services in Minneapolis-St. Paul. Single-source vulnerability persists in proprietary dressing foam formulations. Distribution runs through durable medical equipment channels for homecare and direct-to-hospital logistics for institutional procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU MDR compliance costs in Europe run substantially higher than CDSCO pathway investments in India, creating divergent capital efficiency profiles for manufacturers with multi-regional footprints.
For Market Incumbents: Anticipate accelerated commoditization of adhesive foam and film layers as hospital procurement committees fragment historical ecosystem lock-in. Defensive positioning requires deepening backward integration into advanced dressing materials and securing notified body relationships ahead of MDR bottleneck intensification. Capacity expansion in India's Hyderabad corridor captures emerging private insurance reimbursement while reducing exposure to European certification delays. For New Entrants and Emerging Players: Capture whitespace in India's underpenetrated homecare segment where CDSCO regulatory maturation coincides with private insurance expansion outside institutional settings. Portable NPWT platforms targeting diabetic foot ulcer management in district nursing services offer the most penetrable entry point. Go-to-market execution should prioritize unit-dose distribution partnerships over durable medical equipment channel development. For Investors and Strategic Acquirers: Asymmetric upside sits with electromechanical pump manufacturers possessing proprietary pressure modulation algorithms and established FDA 510(k) predicate libraries. Long-term viability across the projection horizon favors entities with vertically integrated wound care portfolios capable of withstanding dressing commoditization. The signal to watch is NHS England reimbursement code expansion for remote patient monitoring integration.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evaluation requirements extend timelines for new electromechanical entrants lacking notified body relationships. |
| Hospital System Partnership | GPO contract unbundling enables multi-source dressing strategies while preserving premium pump positioning. |
| Software Companion Development | Wireless telemetry integration unlocks remote patient monitoring reimbursement codes in competitive homecare tenders. |
| Reimbursement Strategy | Medicare portable NPWT code expansion transforms hospital discharge accessories into standard continuity-of-care treatments. |
| FDA Submission | 510(k) clearance for connected monitoring capabilities differentiates offerings in algorithm-enabled pump platforms. |
Research Methodology
Multiple input streams — primary interviews with wound care clinicians, hospital purchasing committee members, and biomedical engineers; secondary validation through FDA 510(k) filings, CMS Medicare reimbursement databases, and GPO contract repositories; plus customs and trade data for silicone and acrylic adhesive feedstocks — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across product type, technology sophistication, end-user procurement authority, wound application category, and geographic regulatory cluster enabled volume and value modeling throughout the forecast period. CAGRs were derived from procedure volume normalization trajectories, homecare reimbursement expansion schedules, and diabetic patient demographic projections across Japan and Germany.
EU MDR implementation delays, Medicare reimbursement code reversals, and silicone feedstock price volatility are the dominant revision risks to modeled outputs. A model refresh is warranted upon material change in notified body capacity allocation or portable NPWT reimbursement determination by Germany's G-BA.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Wound Healing Market
Wound Care
Wound Debridement Products Market
Wound Care
South Korea Wound Care Market
Wound Care
Global Diabetic Foot Ulcers Market
Wound Care
Global Burn Care Market
Wound Care
Wound Evacuators Market
Wound Care
Moist Wound Dressings Market
Wound Care
Wound Closure Strips Market
Wound Care
Asia Pacific Advanced Wound Care Market
Wound Care
Maggot Debridement Market
Wound Care
Advanced Wound Therapy Devices Market
Wound Care
Non-Invasive Surgical Wound Closure Market
Wound Care
Venous Skin Ulcer Treatment Market
Wound Care
North America Advanced Wound Care Market
Wound Care
Advanced Wound Management Market
Wound Care
Europe Negative Pressure Wound Therapy Market