
 Surgical Dressing Market | 2026-2036
Surgical Dressing Market Size, Share, and Industry Trends Forecast 2026-2036
Surgical Dressing Market Intelligence
The shift toward bioactive and antimicrobial dressings is rotating the market toward higher-value segments focused on active wound healing. This transition favors companies with strong R&D capabilities in material science. Smith & Nephew leverages its extensive portfolio in advanced wound management to capture this demand. Mölnlycke Health Care differentiates through its proprietary technologies in foam and silicone-based dressings for post-operative care, while 3M competes with its broad range of film and adhesive products.
A surgical dressing is a sterile material applied directly to a wound to absorb exudate, prevent infection, and create an optimal healing environment. These products are engineered with specific properties like controlled moisture vapor transmission rates and fluid handling capacity. Foam and hydrocolloid dressings command significant value due to their efficacy in managing moderately to highly exuding wounds. While hospitals remain the largest end-user segment, home healthcare is expanding rapidly, driven by an aging population and chronic disease prevalence.
Market access is governed by stringent regulatory frameworks that mandate sterility and biocompatibility. The U.S. FDA's 510(k) clearance process, Europe’s Medical Device Regulation (MDR), and China’s NMPA approvals require extensive clinical data for advanced dressings. Navigating evolving reimbursement policies for specialized wound care products will be critical for sustaining profitability and market penetration.
Market Dynamics
The transition toward active wound healing, driven by material science breakthroughs in bioactive and antimicrobial agents, is the central structural force. This shift prioritizes therapeutic outcomes over simple wound coverage, favoring R&D-intensive product segments.
Growth Catalysts
- Reimbursement Expansion:Favorable reimbursement in markets like Germany and the US for home healthcare encourages use of advanced dressings for chronic wounds.
- Infrastructure Investment:China's investment in hospital infrastructure expands national access to specialized wound care products.
- Material Science Innovation:Development of novel polymers and hydrogels with enhanced absorbency enables more effective dressing technologies.
Market Restraints
- Regulatory Hurdles:Extensive clinical data required by Europe’s MDR and the US FDA's 510(k) process creates long, costly development cycles.
- Input Cost Volatility:Prices for raw materials like medical-grade silicone and silver are subject to supply fluctuations, impacting margins.
- Substitution Threat:Lower-cost traditional gauze remains a strong competitor for simple wounds in price-sensitive hospital environments.
Strategic Opportunities
- Emerging Market Penetration:Expanding distribution for advanced wound care into underpenetrated markets like Brazil and India presents significant growth potential.
- Sensor Integration:Incorporating biosensors into dressings to monitor wound status in real-time opens a market for smart wound management systems.
- Personalized Dressings:Using 3D printing to create patient-specific dressings tailored to wound geometry offers a path to customized therapy.
Industry Challenges
- Reimbursement Complexity:Navigating disparate reimbursement codes across national and private payer systems complicates market access strategies.
- Sterile Supply Chain Management:Maintaining the integrity of sterile, temperature-sensitive bioactive dressings from manufacturing to the point of care is a key logistical challenge.
- Clinician Training Gaps:A deficit in specialized training on the proper application of advanced dressing technologies can limit effective adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surgical Dressing Market |
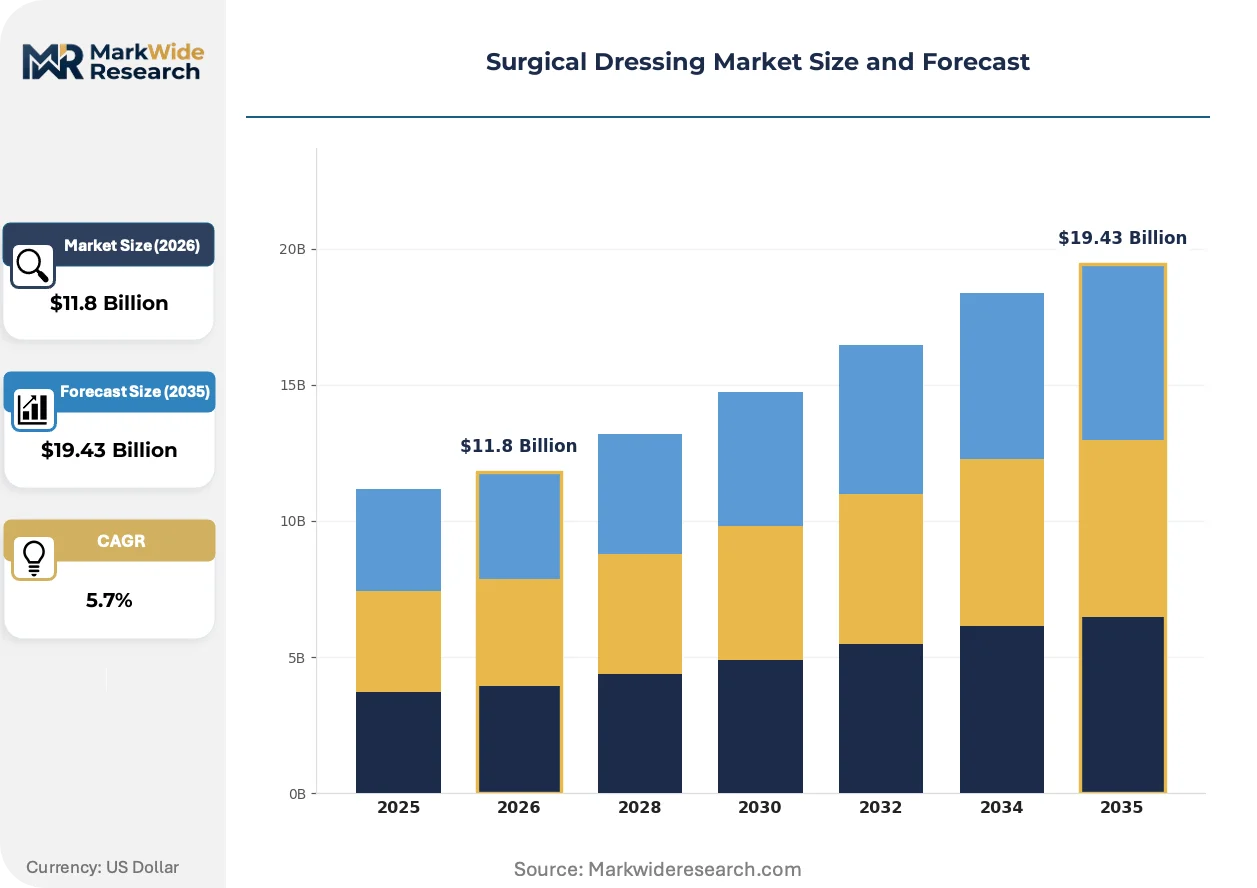
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $19.43 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adhesive, Foam, Hydrocolloid, Alginate, Transparent Film, Gauze Application: Burn Care, Wound Closure, Ulcer Treatment, Post-Operative Care, Trauma Wounds, Pressure Sores End User: Hospitals, Ambulatory Surgical Centers, Clinics, Specialized Care Centers, Rehabilitation Facilities, Home Healthcare Material Type: Non-Woven Fabric, Cotton, Silicone, Hydrogel, Polyurethane, Film |
| Companies Covered | 3M, Smith & Nephew, ConvaTec Group, Coloplast, Cardinal Health, Mölnlycke Health Care, Medline Industries, Solventum, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surgical Dressing Market Strategic Shifts & Innovations
A fundamental shift from passive wound coverage to active therapeutic intervention defines current market evolution. This change elevates dressings from simple barriers to integral components of healing, demanding greater material sophistication and clinical validation.
Smart dressings integrate micro-sensors to monitor wound conditions like pH, temperature, and bacterial load. Specialized wound care clinics and hospitals are adopting this technology for managing high-risk chronic wounds. This data-driven approach is displacing reactive, schedule-based dressing changes with proactive, condition-based interventions.
Europe's Medical Device Regulation (MDR) imposes stricter post-market surveillance and clinical evidence requirements on manufacturers. This elevates the compliance burden and costs for all device classes, including advanced wound dressings. Products with bioactive or antimicrobial properties are most affected, needing more robust clinical data to maintain CE marking.
Value-based healthcare models incentivize providers to reduce total care costs, including hospital readmissions from infections. This changes purchasing criteria, favoring advanced dressings that accelerate healing over cheaper, less effective traditional options. This shift is most prominent within integrated delivery networks in the United States and public health systems across Western Europe.
Surgical Dressing Market Segmentation
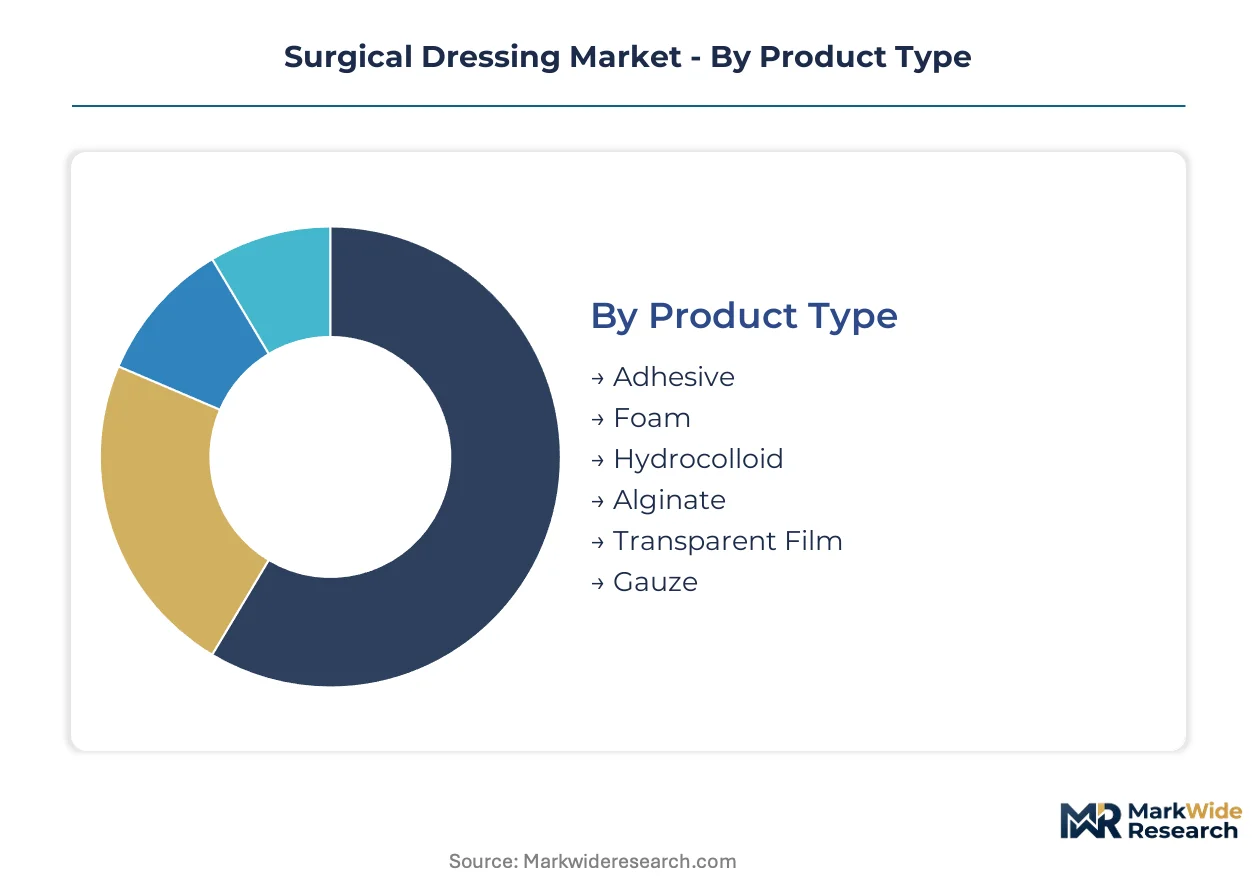
Understanding the segmentation of the surgical dressing market reveals how different product attributes, clinical applications, and end-user requirements shape demand. This detailed breakdown highlights areas of concentrated value and specific growth trajectories across the industry landscape.
Product Type:
The diverse product types within surgical dressings dictate their optimal distribution channels, influencing procurement patterns across various healthcare settings.
- Foam:These multi-layered dressings manage moderate to heavy exudate, often featuring a hydrophilic foam layer and a semi-permeable outer film. Demand concentrates in specialized wound care clinics and hospitals for chronic wound management, driven by their efficacy in maintaining a moist healing environment.
- Hydrocolloid:These self-adhesive, waterproof dressings contain gel-forming agents that interact with wound exudate to create a moist environment. Their use is increasing in home healthcare settings for pressure sores and leg ulcers, supported by ease of application and extended wear time.
- Adhesive:These dressings feature an adhesive border for secure fixation, commonly used for surgical incisions and minor wounds.
- Alginate:Derived from seaweed, these highly absorbent dressings are suitable for heavily exuding wounds, particularly in hospital acute care.
- Transparent Film:Permeable to moisture vapor but impermeable to bacteria, these thin dressings protect superficial wounds and IV sites.
- Gauze:Traditional woven or non-woven cotton dressings provide basic wound coverage and absorption, maintaining a strong presence in general hospital use.
By volume, Gauze dressings lead due to their widespread basic application. By growth pace, Foam and Hydrocolloid dressings are ahead, reflecting their advanced therapeutic properties.
Application:
Each application area for surgical dressings presents unique clinical requirements, influencing product design and material selection for optimal therapeutic outcomes.
- Ulcer Treatment:This segment focuses on managing chronic wounds like diabetic foot ulcers and venous leg ulcers, often requiring advanced dressings with extended wear times and infection control features. Demand is significant in home healthcare and specialized clinics, driven by an aging population and chronic disease prevalence.
- Post-Operative Care:Dressings in this category protect surgical incisions from infection and manage exudate, supporting faster healing and reducing complications. Hospitals remain the primary users, with a growing emphasis on comfortable, low-trauma removal options.
- Burn Care:Specialized dressings protect burn wounds, promote healing, and manage pain, often incorporating antimicrobial agents.
- Wound Closure:These products support the approximation of wound edges, including sterile strips and liquid adhesives for minor cuts.
- Trauma Wounds:Dressings for trauma injuries prioritize rapid hemostasis and infection prevention, frequently used in emergency settings.
- Pressure Sores:Managing pressure ulcers involves dressings that offload pressure and maintain a moist healing environment, critical in long-term care facilities.
The value proposition for dressings in Ulcer Treatment and Post-Operative Care is high, driven by the need for advanced healing solutions. Burn Care applications demand highly specialized and often costly materials.
End User:
The varied end-user segments exhibit distinct procurement patterns and clinical protocols, shaping the demand for specific types of surgical dressings.
- Hospitals:These institutions represent the largest end-user segment, utilizing a broad spectrum of dressings for acute care, surgical procedures, and chronic wound management. Procurement often involves bulk purchasing and adherence to strict formularies, influenced by cost-effectiveness and clinical efficacy.
- Home Healthcare:This rapidly expanding segment serves patients managing chronic wounds and post-operative recovery outside traditional clinical settings. Demand centers on user-friendly, long-wear dressings that minimize the need for frequent changes, driven by an aging population and favorable reimbursement policies.
- Ambulatory Surgical Centers:These facilities primarily use dressings for minor surgical procedures and post-operative care, prioritizing efficiency and cost-effectiveness.
- Clinics:General physician clinics and smaller medical practices apply dressings for minor injuries and routine wound care.
- Specialized Care Centers:These centers, including dermatology and podiatry clinics, require specific dressings for targeted wound conditions.
- Rehabilitation Facilities:Dressings are essential in rehabilitation for managing pressure ulcers and other chronic wounds during long-term patient stays.
Hospitals hold the largest market share for surgical dressings, representing the foundational demand. Home Healthcare is a significant growth area, driving innovation in user-friendly and extended-wear products.
Material Type:
Material science advancements underpin the performance characteristics of surgical dressings, directly impacting absorbency, breathability, and biocompatibility.
- Silicone:Dressings made with silicone offer gentle adhesion, minimizing trauma during removal and providing a moist healing environment. Mölnlycke Health Care leverages proprietary silicone technologies for post-operative care, reducing skin damage.
- Hydrogel:These dressings contain high water content, providing moisture to dry wounds and facilitating autolytic debridement. Their use is expanding in managing partial and full-thickness wounds, particularly those with slough or necrotic tissue.
- Non-Woven Fabric:These materials form the base for many modern dressings, offering softness, absorbency, and conformability.
- Cotton:Traditional cotton is used in gauze and padding, providing basic absorption for a wide range of wounds.
- Polyurethane:Often used in foam and film dressings, polyurethane provides moisture vapor transmission and bacterial barriers.
- Film:Thin, transparent film dressings protect superficial wounds and allow visual monitoring without removal.
Polyurethane and Silicone materials are attracting significant R&D investment due to their advanced properties. Cotton and Non-Woven Fabric remain foundational materials for cost-effective dressing solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The supply side for surgical dressings is concentrating in regions with advanced healthcare infrastructure and robust R&D capabilities. This strategic alignment optimizes distribution channels. It ensures compliance with diverse regulatory requirements across key markets.
United States
Demand for advanced dressings in the United States stems from an aging population and increasing chronic wound prevalence. The U.S. FDA's 510(k) clearance process mandates rigorous product validation for market entry. Major medical device clusters in places like Minnesota and California drive innovation in material science and smart dressing technologies.
Germany
Germany's demand for surgical dressings is driven by favorable reimbursement policies for home healthcare and post-operative care. Europe’s Medical Device Regulation (MDR) sets strict standards for product safety and clinical evidence. The Rhine-Main region, with its strong medical technology presence, fosters development of specialized wound care solutions.
China
China's expanding healthcare infrastructure investment significantly boosts demand for specialized wound care products. The NMPA approval process requires extensive local clinical data for advanced dressings. Industrial parks in cities such as Suzhou and Shanghai are becoming hubs for domestic and international medical device manufacturing.
India
Expanding healthcare access and a large patient pool characterize India's growing demand for surgical dressings. The CDSCO regulates medical devices, focusing on quality and affordability for local markets. Manufacturing clusters in states like Gujarat and Maharashtra are increasing production of both traditional and advanced wound care items.
Brazil
Brazil presents significant potential for surgical dressing adoption, particularly with increasing surgical volumes and chronic disease management. ANVISA, the national health surveillance agency, oversees medical device registration and post-market surveillance. The São Paulo metropolitan area serves as a key distribution and innovation center for medical supplies across Latin America.
Surgical Dressing Market Key Industry Players
Concentration sits with established multinational corporations that possess extensive R&D capabilities and broad product portfolios in advanced wound care. The market structure features a tiered landscape, with global leaders offering high-value solutions alongside regional specialists. Strategic archetypes include innovation-driven firms, diversified healthcare conglomerates, and cost-focused manufacturers. Companies are pursuing portfolio diversification into active healing technologies and geographic expansion into emerging markets to capture new opportunities.
On the innovation-driven vector, 3M Company exemplifies a diversified technology conglomerate leveraging material science across multiple healthcare segments. Smith & Nephew plc, a UK-based medical technology company, represents a global leader with a strong focus on advanced wound management products. Sweden-based Mölnlycke Health Care AB occupies a position as a specialist in gentle, high-performance dressings, particularly with its proprietary silicone technologies. These entities anchor the market's premium and advanced solution offerings.
| Leading Market Players |
|---|
| 3M |
| Smith & Nephew |
| ConvaTec Group |
| Coloplast |
| Cardinal Health |
| Mölnlycke Health Care |
| Medline Industries |
| Solventum |
| Johnson & Johnson |
| Others |
Cost & Logistics Intelligence
Traditional gauze substitution by advanced materials simultaneously reshapes supply geography and pricing economics for surgical dressings. This transition shifts procurement patterns from basic, commodity-driven inputs toward R&D-intensive, specialized components, impacting both production locations and market value.
Pricing Analysis
Europe’s Medical Device Regulation (MDR) dictates the pricing tier structure for advanced surgical dressings. The dominant pricing model is value-based, tiered by clinical efficacy and material sophistication. Price differentiation drivers include certified biocompatibility and brand premium, especially for advanced foam and hydrocolloid products. Pricing pressure stems from input cost volatility for medical-grade silicone and silver. Hospitals exhibit higher price sensitivity for basic dressings, while specialized wound care clinics prioritize therapeutic outcomes.
Supply Chain Analysis
China produces basic dressings and some advanced material components, influencing global supply. Geographic supply concentration includes China, Germany, and the United States for various components. Raw material dependencies center on medical-grade silicone, specialized polymers, and silver compounds. A structural risk involves maintaining the integrity of sterile, temperature-sensitive bioactive dressings throughout the distribution network. Distribution runs through direct sales channels to large hospital systems and specialized medical distributors for home healthcare.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a fragmentation opportunity, driven by the demand-side shift toward personalized wound care solutions. Patient-specific dressings and smart monitoring systems create distinct niches.
For Market Incumbents: Secure R&D pipelines for next-generation bioactive and antimicrobial materials. Invest in clinical validation to meet stringent regulatory requirements in Europe and the US. Counter the substitution threat from lower-cost traditional options by demonstrating superior long-term patient outcomes. Leverage existing hospital relationships to introduce advanced wound management protocols.
For New Entrants and Emerging Players: Clinician training gaps in the proper application of advanced dressing technologies offer a significant entry point. Target underpenetrated emerging markets like India and Brazil with cost-effective, yet clinically sound, advanced dressings. A viable go-to-market angle involves bundling educational programs with product offerings to drive adoption. Focus on user-friendly designs for home healthcare settings.
For Investors and Strategic Acquirers: The market sits at a growth phase that favors R&D-intensive specialists with proprietary material science. Acquisition targets should include companies demonstrating strong intellectual property in smart dressing technologies or novel bioactive agents. A critical signal to watch is the expansion of reimbursement policies for advanced wound care in home healthcare settings. Long-term viability is strong, driven by chronic disease prevalence.
| Strategic Initiative | Industry Significance |
|---|---|
| R&D Investment in Bioactive Materials | Enhances therapeutic outcomes and captures higher-value segments in advanced wound care. |
| Geographic Expansion into Emerging Markets | Accesses large patient pools and new demand centers in India and Brazil. |
| Partnership with Home Healthcare Providers | Expands reach for user-friendly dressings to an aging population in the US and Germany. |
| Sensor Integration for Smart Dressings | Creates data-driven wound management solutions for chronic conditions. |
| Clinical Data Generation for MDR/FDA | Ensures compliance and market access for advanced wound care products. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory filings, medical journal articles, and industry reports. Primary data collection involved structured interviews with wound care specialists, hospital procurement managers, home healthcare providers, and regulatory affairs leads. This approach ensures bottom-up and top-down triangulation for comprehensive market insights.
The segmentation dimensions modeled include product type, application, end-user, material type, and the regional regulatory landscape. The analytical framework projects market growth across the analysis window, with CAGRs derived from historical trends and future projections. Forecast inputs include chronic disease prevalence rates and aging population demographics across key geographies.
Forecasts assume regulatory continuity in the US FDA, Europe MDR, and China NMPA regimes; material policy shifts would require re-modeling. The analysis reflects current market dynamics and known technological trajectories. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Antimicrobial Regenerative Wound Matrix Market
Wound Care
Pressure Ulcer Treatment Market
Wound Care
Asia Pacific Wound Care Biologics Market
Wound Care
Antimicrobial Wound Dressings Market
Wound Care
Wound Care Centers Market
Wound Care
Single-Use Negative Pressure Wound Therapy Devices Market
Wound Care
Wound Biologics Market
Wound Care
Australia Wound Care Management Devices Market
Wound Care
Global Wound Irrigation System Market
Wound Care
Collagen Dressings Market
Wound Care
Biopatches Market
Wound Care
Anti-Biofilm Wound Dressing Market
Wound Care
Hemostats for Wound Closure Market
Wound Care
Chronic Wound Care Market
Wound Care
Wound Care Market
Wound Care
Autologous Wound Patches Market