
 Wound Care Market | 2026-2036
Wound Care Market Size, Share, and Industry Trends Forecast 2026-2036
Wound Care Market Intelligence
The EU Medical Device Regulation is realigning product registration requirements across European markets, forcing manufacturers to rebuild clinical evidence portfolios for legacy dressings. Smith & Nephew leverages its biosynthetics pipeline to sustain premium positioning in advanced wound matrices. Mölnlycke Health Care AB anchors European hospital supply chains through direct distribution networks. 3M competes on material science depth with silicone-adhesive platforms that dominate post-operative segments.
Wound care encompasses dressings, devices, and biologics engineered to maintain moist healing environments, manage exudate, prevent infection, and accelerate tissue regeneration through controlled moisture vapor transmission rates typically between 2,000 and 8,000 g/m²/24hr. Bioactive dressings incorporating collagen, alginates, or antimicrobial silver occupy the fastest-expanding margin pool as clinicians shift from passive to interactive wound management. Surgical wounds and diabetic ulcers represent the dominant application clusters, with pressure ulcers gaining traction in long-term care reimbursement frameworks. Hospitals remain the primary delivery channel, though homecare is extending into negative-pressure wound therapy as portable systems reduce readmission exposure.
FDA 510(k) pathways and EU MDR conformity assessments shape market access timelines, while ISO 13485 quality management standards govern manufacturing scale-up for sterile wound products. The EPA regulates antimicrobial claims on silver-impregnated dressings, creating compliance bottlenecks for new entrants. Stakeholders must monitor reimbursement coding shifts for bioengineered skin substitutes and vacuum-assisted closure systems as payers recalibrate outpatient wound care economics.
Market Dynamics
EU MDR clinical evidence requirements are forcing manufacturers to rebuild legacy dressing portfolios, compressing timelines for product launches while elevating barriers for commoditized offerings.
Growth Catalysts
- Silver-ion antimicrobial coatings:EPA clearance pathways for silver-impregnated dressings are expanding reimbursable outpatient protocols in long-term care settings.
- Japan's aging demographic:METI reimbursement expansion for negative-pressure wound therapy in homecare is accelerating portable system adoption.
- Moisture vapor transmission engineering:Advanced hydrocolloid and silicone-adhesive platforms are displacing traditional gauze in post-operative segments.
Market Restraints
- Petrochemical feedstock volatility:Polyurethane and silicone raw material costs fluctuate with energy markets, squeezing margin on advanced dressing substrates.
- EU MDR notified body capacity:Conformity assessment bottlenecks in Germany and the Netherlands are extending time-to-market for Class IIb wound devices.
- Substitute pressure from biosynthetics:Collagen matrices and bioengineered skin substitutes are capturing high-value chronic wound cases previously served by antimicrobial dressings.
Strategic Opportunities
- German outpatient wound centers:Reimbursement coding expansion for bioactive dressings creates white space beyond hospital procurement.
- Telemedicine-integrated dressing sensors:pH and temperature monitoring films converging with remote patient monitoring platforms enable subscription revenue models.
- US IRA preventive care incentives:Medicare Advantage plans are deepening coverage for home-based negative-pressure systems to reduce readmission penalties.
Industry Challenges
- ISO 13485 audit backlogs:Sterile manufacturing certification delays are constraining capacity expansion for advanced wound matrix producers.
- Biocompatibility testing complexity:Cytotoxicity and sensitization studies for bioactive materials extend development cycles by 12-18 months.
- Legacy ERP integration:Track-and-trace requirements for EU MDR Unique Device Identification are forcing mid-tier manufacturers to overhaul supply chain systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wound Care Market |
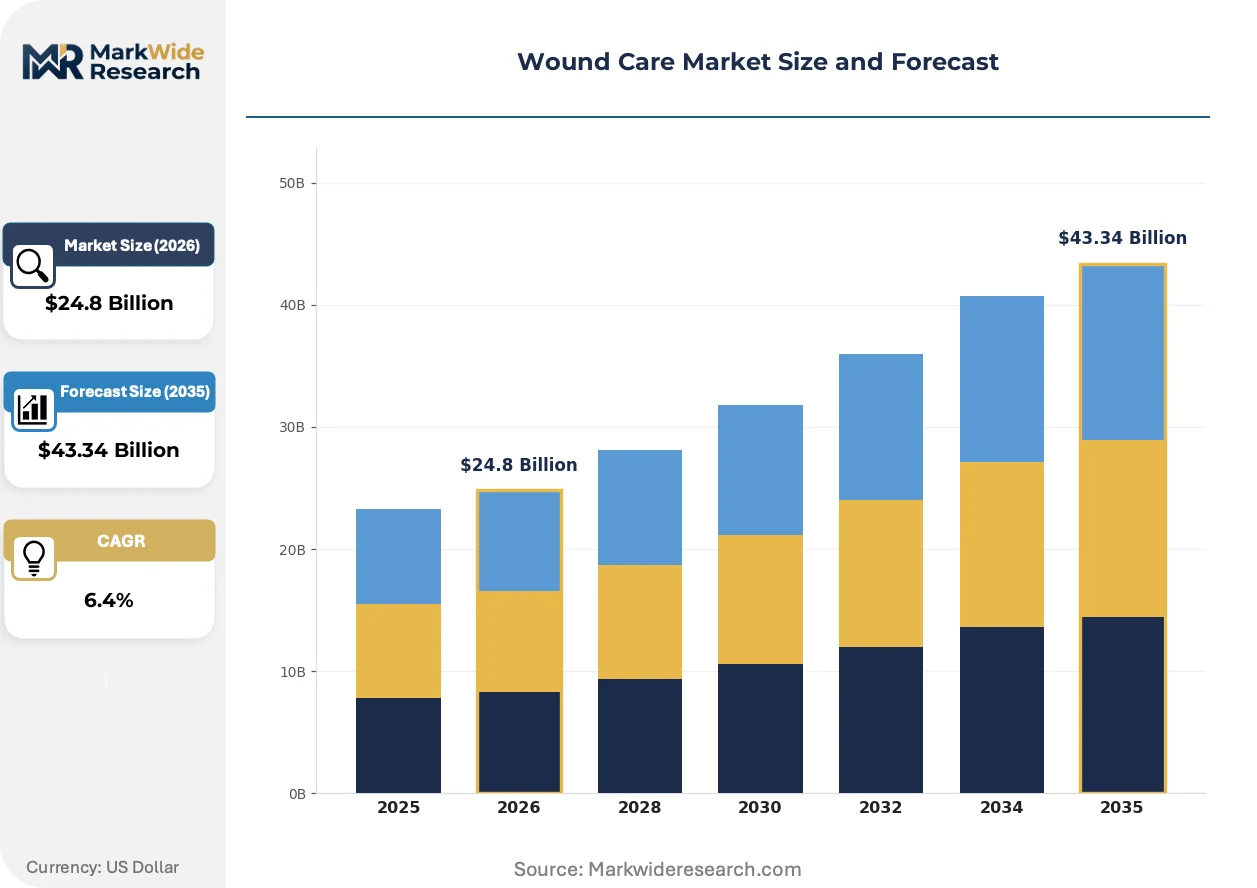
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $43.34 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dressings, Gauzes, Antibiotic Creams, Bioactive Dressings Application: Burns, Surgical Wounds, Diabetic Ulcers, Pressure Ulcers Delivery Mode: Topical, Biologics, Transdermal, Vacuum-Assisted End User: Hospitals, Homecare, Clinics, Long-term Care Facilities |
| Companies Covered | Solventum, Johnson & Johnson Services, Inc., Smith & Nephew, Convatec Group PLC, Cardinal Health, Mölnlycke Health Care AB, 3M, B. Braun SE, Coloplast Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wound Care Market Strategic Shifts & Innovations
Material science convergence with digital health is redefining wound care from passive coverage to interactive healing management, with regulatory frameworks racing to catch up to product complexity.
Electrospun nanofiber dressings with programmable degradation rates are automating moisture management in diabetic ulcer protocols. Hospital wound care teams in the United States are piloting these substrates for patients with irregular exudate patterns. The technology is automating clinician decision-making around dressing change frequency, compressing labor costs in high-volume outpatient clinics.
EU MDR post-market surveillance requirements are mandating systematic clinical follow-up for legacy dressings previously grandfathered under the Medical Device Directive. Manufacturers must now generate real-world evidence for hydrocolloids and alginates marketed for decades. German hospital purchasing consortia are using this compliance burden to consolidate supplier lists, favoring portfolios with robust clinical data.
Homecare agencies are unbundling negative-pressure wound therapy from acute care discharge bundles, creating standalone rental and service contracts. This shift displaces traditional durable medical equipment distributors with specialized wound care logistics providers. The transformation is most visible in Japan, where METI-approved homecare networks are building dedicated NPWT technician workforces.
Wound Care Market Segmentation
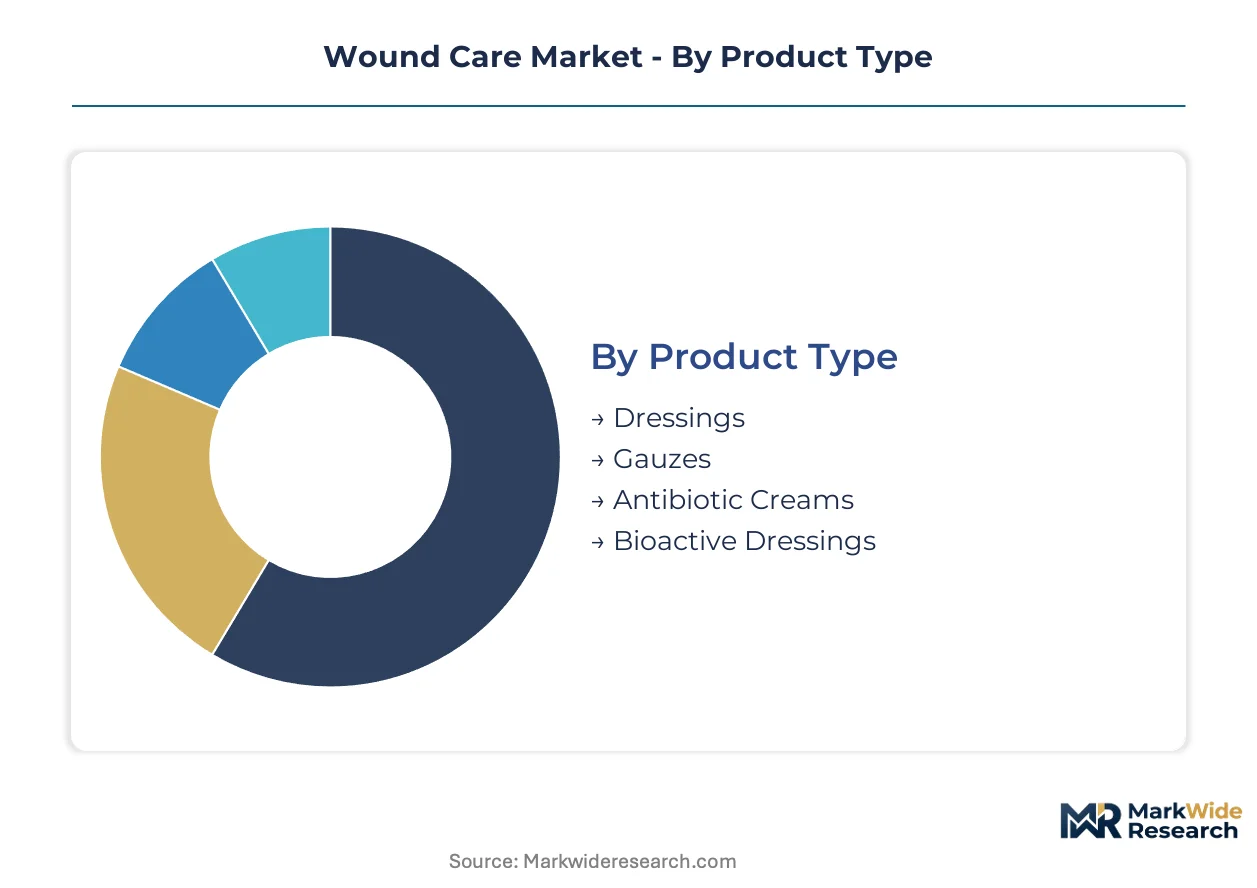
Wound care segmentation reveals how clinical requirements and reimbursement frameworks fragment demand across technology tiers. Each dimension captures distinct upgrade cycles as facilities migrate from passive coverage to interactive healing management.
Product Type:
Replacement cycles accelerate where antimicrobial efficacy and moisture management specifications outpace legacy material performance.
- Dressings:Hydrocolloid and silicone-adhesive platforms dominate post-operative protocols with moisture vapor transmission rates between 2,000 and 8,000 g/m²/24hr. Hospital procurement in the United States favors these substrates for their labor compression in high-volume outpatient clinics.
- Bioactive Dressings:Collagen, alginate, and silver-impregnated matrices command premium positioning as clinicians shift from passive to interactive wound management. German outpatient wound centers are deepening reimbursement coding for these materials, creating white space beyond traditional hospital procurement.
- Gauzes:Cotton and synthetic woven materials retain cost-sensitive applications where exudate management requirements remain minimal.
- Antibiotic Creams:Topical antimicrobial formulations serve superficial infection prevention in community care settings with limited access to advanced dressings.
Volume placements concentrate in Dressings; the faster expansion belongs to Bioactive Dressings.
Application:
Cost tier stratification separates acute procedural demand from chronic condition management with extended treatment horizons.
- Surgical Wounds:Post-operative incision care drives standardized dressing protocols with predictable change frequencies. Japan's METI reimbursement structures support portable negative-pressure systems for surgical site management in transitioning patients.
- Diabetic Ulcers:Lower extremity wounds in diabetic populations require sustained moisture balance and infection control over months. Electrospun nanofiber dressings with programmable degradation rates are automating clinician decision-making for these irregular exudate patterns.
- Pressure Ulcers:Long-term care facilities in aging economies are expanding staff training for staging and prevention protocols.
- Burns:Thermal and chemical injuries demand specialized fluid management and biocompatibility certification beyond standard wound care portfolios.
Procurement volume clusters in Surgical Wounds; margin expansion is steepest in Diabetic Ulcers.
Delivery Mode:
Customer type differentiation separates institutional buyers with capital equipment budgets from consumables-focused procurement.
- Vacuum-Assisted:Negative-pressure wound therapy systems compress healing timelines through controlled exudate removal and perfusion enhancement. Homecare agencies in Japan are unbundling NPWT from acute discharge bundles, building dedicated technician workforces under METI-approved networks.
- Biologics:Engineered skin substitutes and growth factor matrices capture high-value chronic cases with cellular regeneration requirements. FDA 510(k) pathways and EU MDR conformity assessments shape access timelines for these advanced modalities.
- Topical:Direct application formats dominate first-line treatment and patient self-management in resource-constrained settings.
- Transdermal:Drug-eluting patches and active delivery systems bridge pharmaceutical and device regulatory frameworks.
Equipment investment concentrates in Vacuum-Assisted; the steepest volume climb belongs to Biologics.
End User:
Supply concentration varies by care setting complexity, with certification requirements and inventory scale determining vendor relationships.
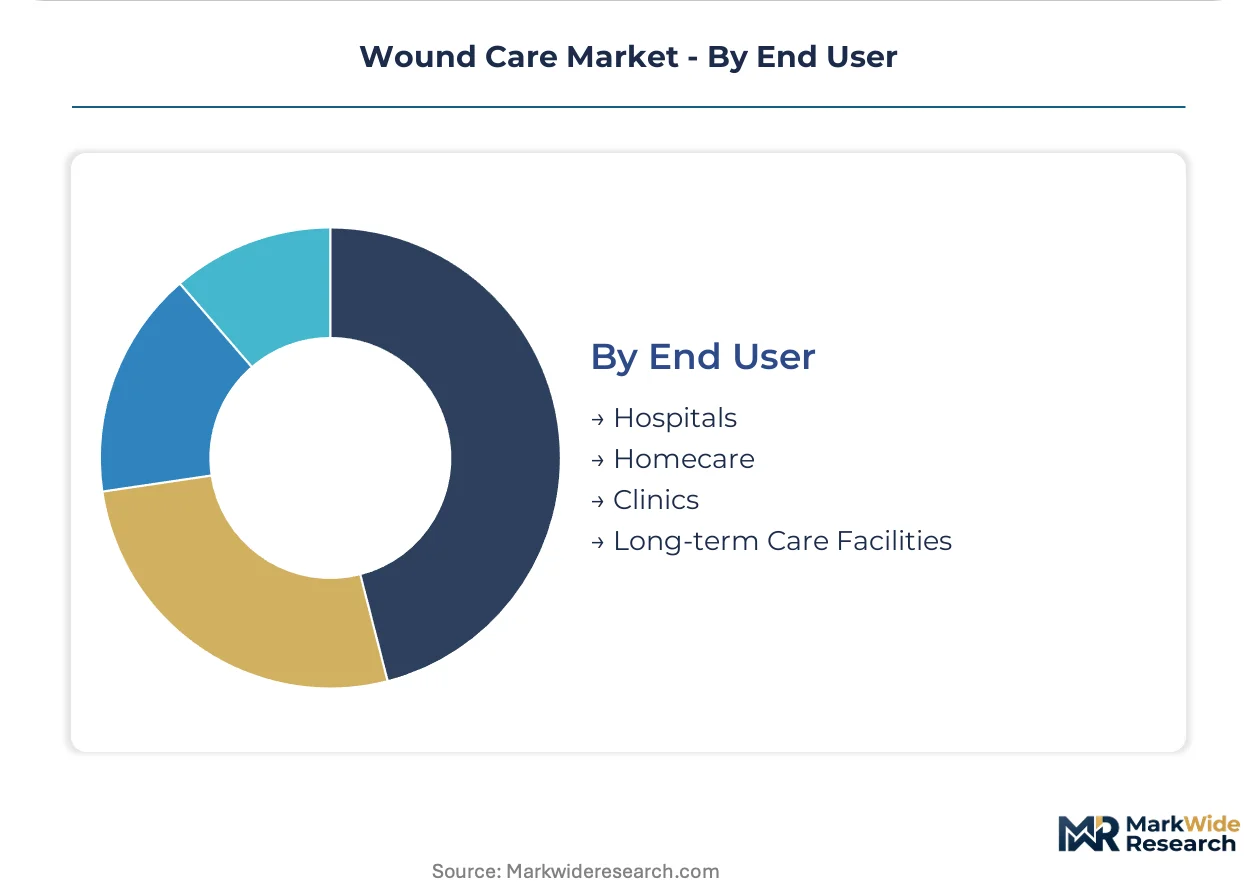
- Hospitals:Integrated delivery networks leverage purchasing consortia to consolidate supplier lists around portfolios with robust clinical data. EU MDR post-market surveillance mandates are accelerating this consolidation in German hospital systems.
- Long-term Care Facilities:Aging resident populations are accelerating consumption of advanced dressings as reimbursement frameworks deepen for outpatient wound management. Silver-ion antimicrobial coatings are expanding reimbursable protocols in these settings.
- Homecare:Remote patient monitoring convergence is enabling subscription revenue models for sensor-integrated dressing systems.
- Clinics:Ambulatory surgical centers and wound specialty practices balance procedure volume against inventory carrying costs.
Procurement scale concentrates in Hospitals; the fastest share gain belongs to Long-term Care Facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of advanced wound dressings concentrates in Germany, the United States, and Japan, while consumption growth accelerates in aging economies deepening reimbursement for outpatient protocols. Production clusters leverage polymer science expertise and sterile manufacturing infrastructure. Demand expansion outpaces supply capacity in long-term care settings across multiple jurisdictions.
United States
Medicare Advantage plans are deepening coverage for home-based negative-pressure systems under IRA preventive care incentives. FDA 510(k) pathways shape access timelines for bioengineered skin substitutes and antimicrobial dressings. The Boston-Cambridge corridor anchors biosynthetics research, with hospital purchasing consortia consolidating supplier lists around portfolios with robust clinical data.
Germany
Outpatient wound centers are expanding reimbursement coding for bioactive dressings beyond traditional hospital procurement. EU MDR notified body capacity constraints in Germany and the Netherlands extend time-to-market for Class IIb wound devices. The Rhine-Ruhr industrial basin hosts sterile manufacturing facilities serving European hospital supply chains.
Japan
METI reimbursement expansion for negative-pressure wound therapy in homecare accelerates portable system adoption. PMDA regulatory frameworks govern market access for advanced wound matrices and sensor-integrated dressings. The Kanto region around Tokyo concentrates distribution networks for METI-approved homecare technician workforces.
United Kingdom
NHS procurement frameworks are recalibrating outpatient wound care economics through value-based purchasing pilots. MHRA post-Brexit regulatory alignment creates transitional compliance requirements for legacy dressing portfolios. The Oxford-Cambridge arc hosts biocompatibility testing laboratories extending development cycles for bioactive materials.
India
CDSCO regulatory pathways are streamlining for advanced dressings as domestic manufacturing scales under PLI scheme incentives. Central government health missions are expanding access to antimicrobial coatings in district hospital networks. The Mumbai-Pune pharmaceutical corridor anchors contract manufacturing for hydrocolloid and alginate substrates.
Wound Care Market Key Industry Players
The competitive structure tilts toward diversified medical technology conglomerates with material science depth and sterile manufacturing scale. Market access depends on regulatory dossier strength across FDA, EU MDR, and PMDA jurisdictions. Three archetypes dominate: integrated wound care specialists with full portfolio coverage, diversified healthcare conglomerates leveraging cross-divisional R&D, and regional champions with deep hospital supply chain relationships. Competitive moves concentrate on biosynthetics pipeline development and direct distribution network expansion into outpatient settings.
Among diversified healthcare conglomerates, Johnson & Johnson Services, Inc. and 3M occupy positions anchored by material science capabilities spanning adhesive platforms and sterile manufacturing. Smith & Nephew and Mölnlycke Health Care AB represent the wound care specialist archetype with focused portfolio depth. Solventum exemplifies the spin-off structure, carving dedicated wound and dental care operations from broader healthcare conglomerate foundations. These entities sit within a tiered competitive map where regulatory dossier breadth and hospital procurement relationships determine access to premium pricing segments.
| Leading Market Players |
|---|
| Solventum |
| Johnson & Johnson Services, Inc. |
| Smith & Nephew |
| Convatec Group PLC |
| Cardinal Health |
| Mölnlycke Health Care AB |
| 3M |
| B. Braun SE |
| Coloplast Group |
| Others |
Cost & Logistics Intelligence
Skilled polymer chemists in the Rhine-Ruhr industrial basin command wage premiums that compress margin spreads between economy-grade gauzes and advanced silicone-adhesive platforms. Labor-cost differentials between German sterile manufacturing facilities and contract producers in India widen pricing-tier spreads for hydrocolloid dressings sold into European hospital consortia.
Pricing Analysis
Margin tightening in standard hydrocolloid tiers reflects petrochemical feedstock volatility and polyurethane raw material cost swings. Three-tier pricing structure across premium bioactive matrices, standard silicone-adhesive platforms, and economy woven gauzes separates clinical evidence depth from commodity positioning. Pricing pressure intensifies in mid-tier alginates as biosynthetic collagen substitutes capture high-value chronic wound cases. Long-term care facilities exhibit highest price sensitivity due to fixed per-patient reimbursement caps, while German outpatient wound centers demonstrate lowest sensitivity where bioactive coding expansion deepens coverage.
Supply Chain Analysis
Regional distribution centers in the Netherlands and Germany operate hub-and-spoke patterns serving EU hospital purchasing consortia with consolidated sterile dressing inventories. Manufacturing concentrates in Germany, the United States, and Japan, drawing from polyurethane foam, medical-grade silicone, and silver-ion antimicrobial precursor supply chains. Single-source vulnerability in EPA-cleared silver-impregnated substrate suppliers creates bottleneck exposure for antimicrobial dressing portfolios. Distribution runs through direct hospital contracts and specialized wound care logistics providers displacing traditional durable medical equipment channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wound care market functions as a cost-of-compliance arena where EU MDR clinical evidence requirements erect barrier-to-entry moats favoring manufacturers with robust post-market surveillance infrastructure.
For Market Incumbents: Extend clinical evidence portfolios for legacy hydrocolloids and alginates to satisfy EU MDR post-market surveillance mandates, converting compliance burden into supplier consolidation leverage against mid-tier competitors. Deepen backward integration into electrospun nanofiber substrate production to capture margin from programmable degradation rate technologies displacing traditional antimicrobial dressings. For New Entrants and Emerging Players: Homecare agencies unbundling negative-pressure wound therapy from acute discharge bundles represent the most penetrable buyer archetype, particularly in Japan's METI-approved technician networks. Target portable NPWT system rental contracts and subscription sensor-integrated dressing revenue models to bypass entrenched hospital procurement gatekeepers. For Investors and Strategic Acquirers: Re-rating potential sits with biosynthetics specialists possessing FDA 510(k) cleared collagen matrices given accelerating substitution of antimicrobial dressings in diabetic ulcer protocols. Watch EPA clearance timelines for novel silver-ion coatings as inflection indicators for outpatient long-term care reimbursement expansion.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Clinical Evidence Buildout | Post-market surveillance compliance secures hospital consortium supplier list retention against commoditized competitors. |
| Homecare NPWT Unbundling | METI reimbursement expansion in Japan enables dedicated technician workforce models displacing traditional distributors. |
| Sensor-Integrated Dressing Development | pH and temperature monitoring films converge with remote patient monitoring platforms enabling subscription revenue capture. |
| Biosynthetics Pipeline Investment | Collagen matrices and bioengineered skin substitutes capture high-value chronic wound cases from antimicrobial dressings. |
| Direct Distribution Network Expansion | Outpatient wound center relationships in Germany bypass hospital procurement consolidation pressures. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with hospital purchasing committee members, GPO contracts managers, biomedical engineers, and wound care clinicians validated demand assumptions. FDA 510(k) databases, EU MDR notified body submissions, CMS Medicare reimbursement coding updates, and Japanese METI reimbursement bulletins supplied secondary validation. Bottom-up modeling of dressing unit volumes triangulated against top-down market value estimates derived from sterile manufacturing capacity assessments.
Granularity-level modeling operated at product-type, application, delivery mode, and end-user dimensions across the analysis window. CAGRs were derived from segmented volume projections calibrated to aging demographic trajectories and reimbursement coding expansion timelines. Forecast inputs incorporated EU MDR transition compliance costs, silver-ion antimicrobial EPA clearance pathways, and portable negative-pressure wound therapy adoption curves in homecare settings.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU MDR notified body capacity constraints, petrochemical feedstock volatility, and biosynthetic substitute penetration rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Chronic Wound Care Market
Wound Care
Negative Pressure Wound Therapy Market
Wound Care
Global Wound Dressings Market
Wound Care
US Burn Care Centers Market
Wound Care
Acute Wound Care Market
Wound Care
Bioactive Wound Care Market
Wound Care
Vascular Dressings Market
Wound Care
Surgery Medical Bandage Market
Wound Care
Global Traditional Wound Management Market
Wound Care
Animal Wound Care Market
Wound Care
Collagen Dressings Market
Wound Care
Surgical Dressing Market
Wound Care
Wound Irrigation Devices Market
Wound Care
Wound Biologics Market
Wound Care
Saudi Arabia Wound Care Management Devices Market
Wound Care
Global Compression Bandages Market