
 US Wound Care Centers Market | 2026-2036
US Wound Care Centers Market Size, Share, and Industry Trends Forecast 2026-2036
US Wound Care Centers Market Intelligence
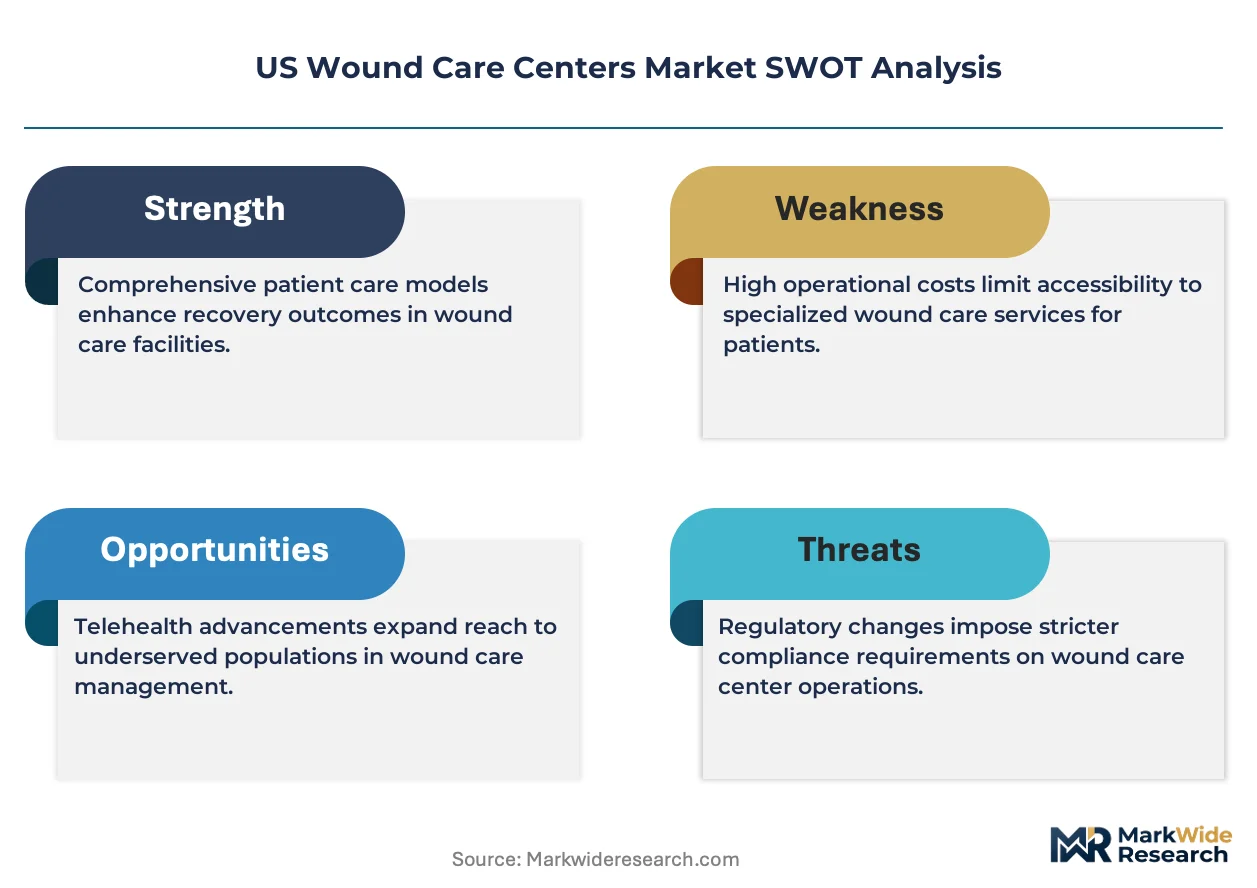
The CMS Hospital Outpatient Prospective Payment System is realigning the cost-of-entry calculus for independent wound care operators, compressing margins on hyperbaric oxygen therapy while rewarding value-based wound healing outcomes. Healogics, Inc. anchors the national center network model through its managed-service agreements with hospital systems across forty-six states. RestorixHealth competes via joint-venture structures that transfer operational risk to health system partners. Baptist Health South Florida leverages its vertically integrated South Florida footprint to control referral flow from diabetic patient populations.
US wound care centers deliver specialized outpatient and inpatient services for chronic, surgical, and diabetic wounds, employing debridement, advanced dressings, biologics, and negative pressure wound therapy systems to reduce amputation rates and hospital readmissions. Biologics and negative pressure wound therapy command the strongest margin pools as clinicians shift from commodity dressings toward cellular and tissue-based products that accelerate closure in recalcitrant diabetic ulcers. Among end user segments, ambulatory surgical centers represent the fastest-growing site of service as payors push lower-acuity procedures away from inpatient settings.
FDA clearance requirements for biologic wound products and CMS national coverage determinations for hyperbaric oxygen therapy shape both product development timelines and center reimbursement eligibility. State-level certificate-of-need regulations in Florida, Texas, and New York constrain greenfield center expansion, protecting incumbents but limiting access in underserved counties. Stakeholders must monitor upcoming CMS physician fee schedule proposals and state Medicaid wound care carve-outs that could redirect patient volume toward home healthcare channels.
Market Dynamics
Medicare reimbursement compression through the CMS Hospital Outpatient Prospective Payment System is forcing independent wound care operators toward hospital-affiliated joint ventures or outright consolidation, fundamentally restructuring how centers achieve capital access and patient volume.
Growth Catalysts
- Diabetic ulcer prevalence:Rising incidence of diabetes mellitus across Florida, Texas, and Arizona generates sustained demand for specialized debridement and advanced dressing protocols in outpatient settings.
- CMS value-based wound healing metrics:Reimbursement incentives tied to amputation reduction and readmission avoidance accelerate adoption of cellular and tissue-based products over commodity alternatives.
- Negative pressure wound therapy miniaturization:Portable single-use systems enable treatment migration from inpatient wards to ambulatory surgical centers and home-based care environments.
Market Restraints
- Certificate-of-need regulations:Florida, Texas, and New York state laws constrain new center licensing, protecting incumbent operators but creating access deserts in rural counties and secondary metropolitan areas.
- Biologic product input concentration:Reliance on limited FDA-registered tissue banks for cellular and tissue-based products creates supply vulnerability and pricing volatility for advanced dressings.
- Hyperbaric oxygen therapy margin compression:CMS national coverage determination revisions have reduced reimbursement rates for HBO treatments, pressuring centers dependent on this modality for profitability.
Strategic Opportunities
- Southeast Medicaid carve-outs:State-level wound care benefit expansions in Georgia and South Carolina create reimbursement pathways for previously uninsured patient populations.
- Telewound integration:Remote monitoring platforms paired with AI-powered tissue assessment tools enable asynchronous specialist consultation, extending center reach into underserved Appalachian and Delta regions.
- ASC site-of-service migration:Commercial payor pressure to shift lower-acuity debridement and grafting procedures from hospital outpatient departments creates volume capture potential for ambulatory surgical centers with wound care capabilities.
Industry Challenges
- Wound care nursing specialization gaps:Limited accredited training programs for advanced wound care certification create recruitment bottlenecks as center networks expand into new metropolitan markets.
- EHR interoperability fragmentation:Disparate electronic health record systems between referring primary care networks and specialized wound centers impede seamless referral tracking and outcome documentation required for value-based contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Wound Care Centers Market |
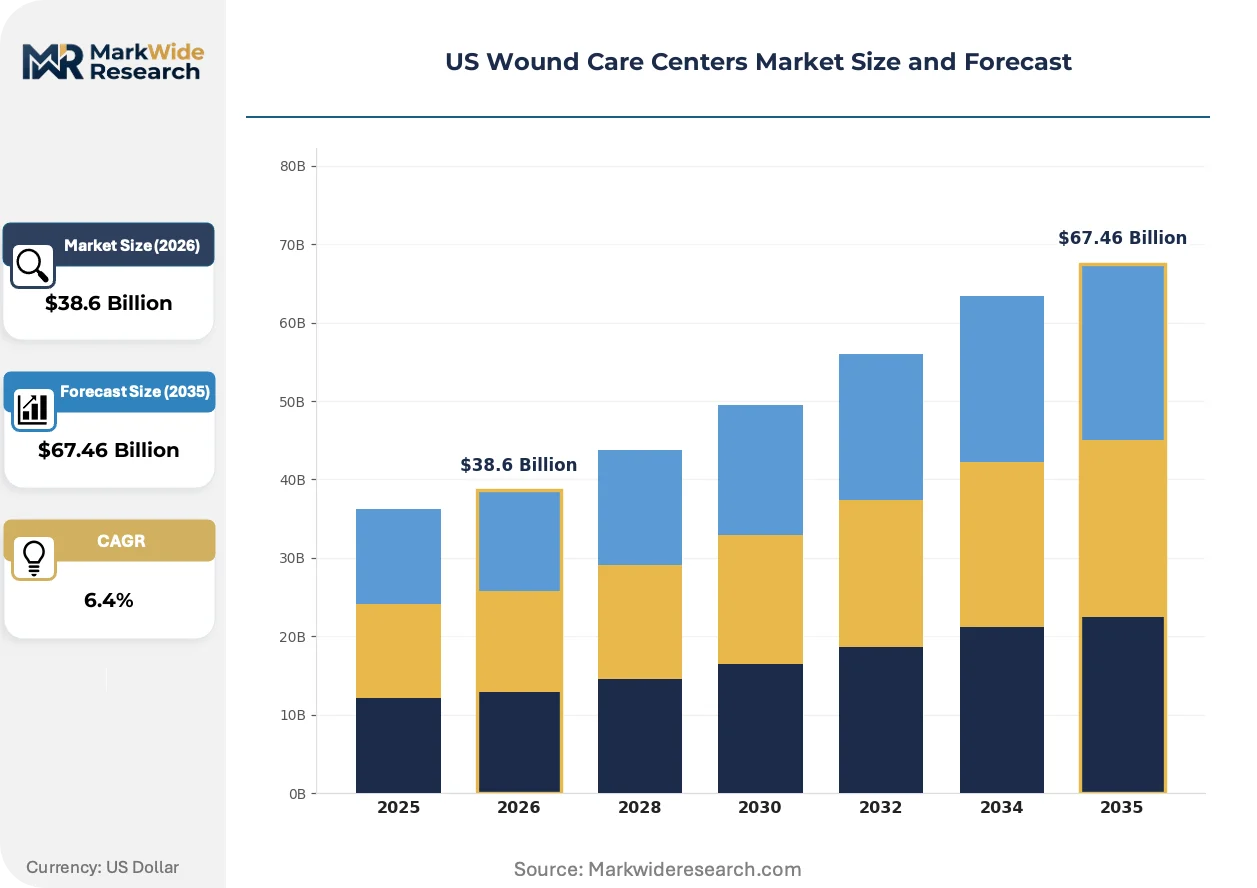
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $67.46 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dressings, Topicals, Biologics, Negative Pressure Wound Therapy Application: Chronic Wounds, Surgical Wounds, Burn Wounds, Diabetic Ulcers End User: Hospitals, Home Healthcare, Long-term Care Facilities, Ambulatory Surgical Centers Service Type: Outpatient Care, Inpatient Care, Telemedicine, Rehabilitation Services |
| Companies Covered | Healogics, Inc., Baptist Health South Florida, EmergeOrtho, TOWER Wound Care Center, RestorixHealth, John Hopkins Medicine, Wound Care Center NYC, North Shore Health and Hyperbarics, The Wound Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Wound Care Centers Market Strategic Shifts & Innovations
Clinical protocol standardization around biologic modalities and remote monitoring capabilities is compressing variation in treatment pathways while opening new site-of-service possibilities previously confined to hospital-based settings.
Cellular and tissue-based products derived from placental and amniotic membranes are consolidating clinical preference in recalcitrant diabetic ulcer management. Hospital-based wound centers and affiliated outpatient facilities are replacing alginate and hydrocolloid dressings with these biologics for wounds stalled in inflammatory phase. The shift is consolidating purchasing power among integrated delivery networks capable of negotiating exclusive supply agreements with tissue processors.
CMS national coverage determinations for hyperbaric oxygen therapy have tightened eligibility criteria, restricting reimbursement to specific Wagner grade diabetic foot ulcers and arterial insufficiency wounds. This regulatory narrowing is compressing HBO service line viability at independent centers while redirecting capital toward negative pressure and biologic modalities. Operators in certificate-of-need states face additional compliance layers as state Medicaid programs adopt parallel coverage restrictions.
Commercial payors are unbundling wound care episode payments from traditional fee-for-service schedules, instead offering bundled rates covering 30-90 day healing cycles. This contracting evolution is displacing commodity dressing suppliers who cannot demonstrate closure acceleration, favoring biologic manufacturers with validated outcomes data. The transformation is most visible in Medicare Advantage penetration markets across Arizona, Nevada, and Texas where payor competition drives rapid contract innovation.
US Wound Care Centers Market Segmentation
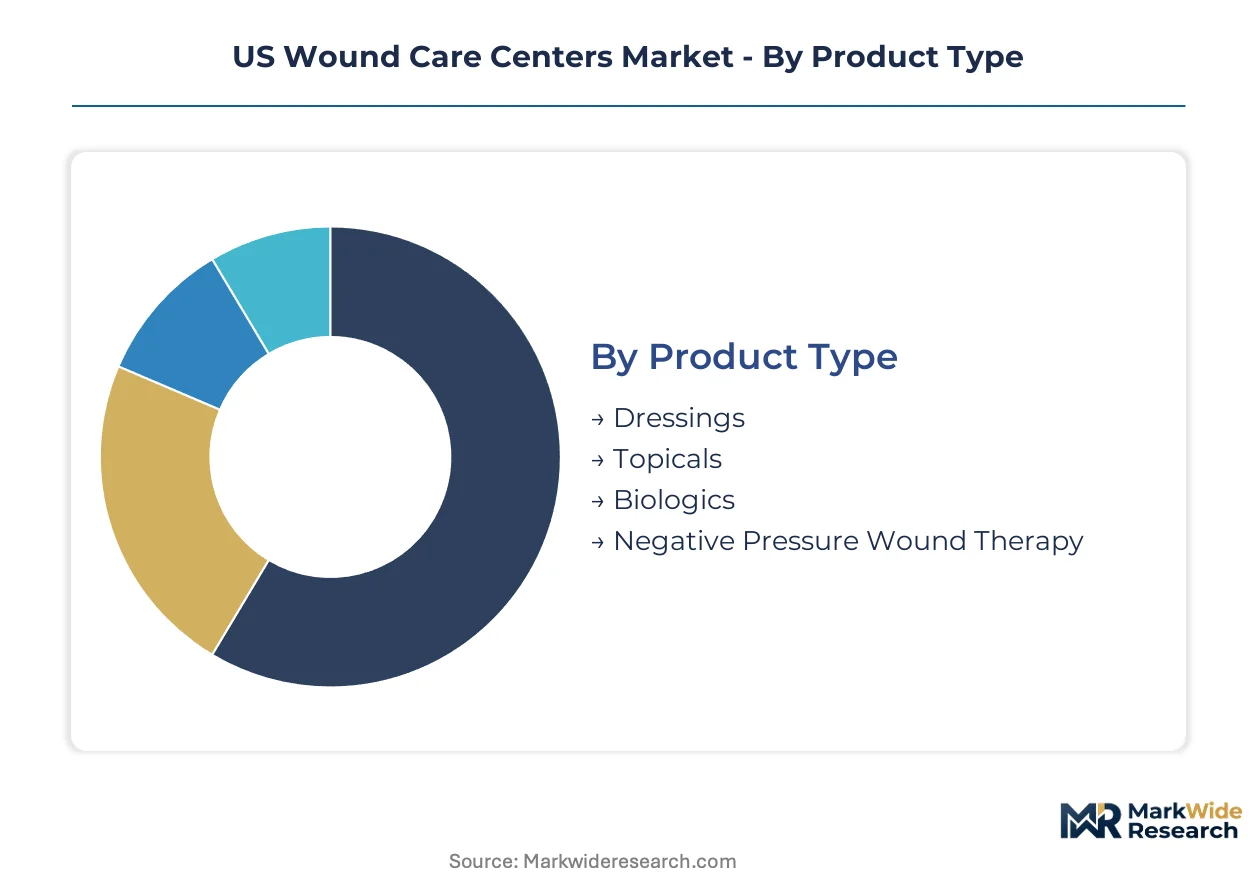
Segmentation in the US wound care centers market reveals how reimbursement pathways, site-of-service economics, and clinical acuity requirements reshape procurement patterns across product categories and delivery settings. Understanding these divisions exposes where margin pools concentrate and where volume is migrating under CMS payment reform.
Product Type:
Clinicians select wound care products based on wound chronicity, closure velocity requirements, and reimbursement eligibility under Medicare national coverage determinations.
- Biologics:Cellular and tissue-based products derived from placental and amniotic membranes command premium positioning for recalcitrant diabetic ulcers stalled in inflammatory phase. Demand concentrates in hospital-based centers across Florida and Texas where integrated delivery networks negotiate exclusive supply agreements with FDA-registered tissue processors.
- Negative Pressure Wound Therapy:Portable single-use systems enable treatment migration from inpatient wards to ambulatory settings. Arizona and Nevada health systems are deploying these devices to capture bundled payment episodes for surgical wound management.
- Dressings:Alginate and hydrocolloid variants serve as first-line options for moist wound healing in cost-constrained settings.
- Topicals:Antimicrobial and enzymatic preparations support debridement protocols in long-term care environments.
Volume sits with dressings; growth tilts toward biologics.
Application:
Wound etiology determines treatment intensity, specialist involvement, and site-of-service eligibility under commercial and government payor contracts.
- Diabetic Ulcers:Wagner grade classifications drive CMS hyperbaric oxygen therapy reimbursement eligibility and biologic adoption rates. Southeast health systems prioritize these cases for amputation reduction metrics tied to value-based contracts.
- Chronic Wounds:Venous and arterial insufficiency ulcers require extended treatment cycles across multiple care settings. Southwest centers manage high volumes of these cases among aging Medicare populations.
- Surgical Wounds:Postoperative incision management supports ASC migration strategies for lower-acuity procedures.
- Burn Wounds:Specialized center certification requirements limit treatment to designated regional burn centers and affiliated outpatient facilities.
Diabetic ulcers anchor revenue concentration; chronic wounds are climbing the fastest as population aging accelerates incidence.
End User:
Capital requirements, regulatory licensing, and referral network control determine which delivery settings capture specific wound care volumes.
- Ambulatory Surgical Centers:Commercial payor pressure to shift debridement and grafting procedures from hospital outpatient departments creates volume capture opportunities. Texas and Arizona ASC networks are adding wound care capabilities to secure bundled payment contracts.
- Hospitals:Hospital-based wound centers maintain dominance for complex cases requiring HBO therapy and surgical intervention. Certificate-of-need regulations in Florida and New York protect incumbent hospital operators from greenfield competition.
- Home Healthcare:Portable negative pressure systems and telewound platforms extend specialist reach into rural counties and secondary metropolitan areas.
- Long-term Care Facilities:Skilled nursing environments manage pressure injury prevention and basic wound maintenance for post-acute populations.
Hospitals retain the largest volume footprint; ASCs are gaining share fastest under site-of-service migration incentives.
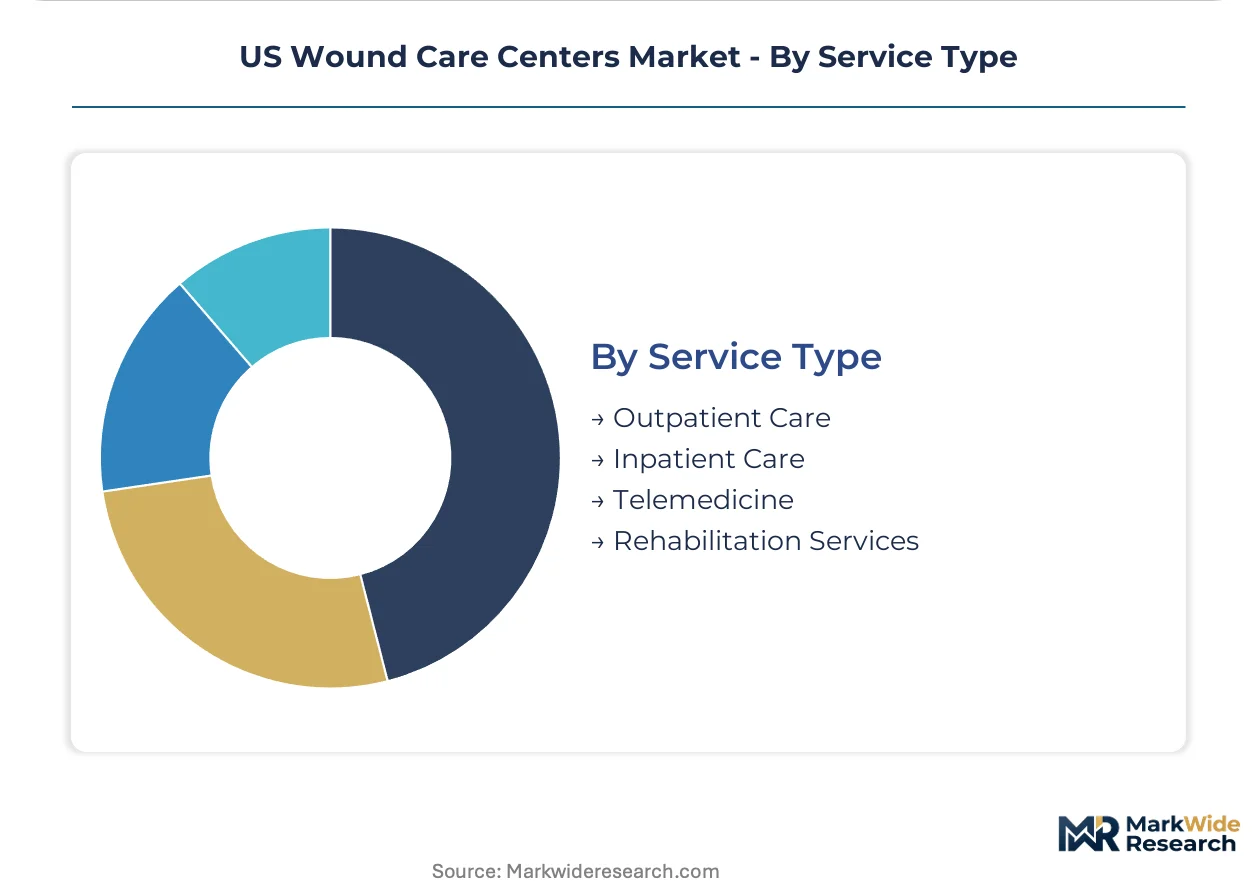
Service Type:
Reimbursement structure and clinical workforce availability determine how care delivery fragments across synchronous and asynchronous modalities.
- Outpatient Care:Freestanding and hospital-affiliated centers deliver debridement, dressing changes, and biologic applications on scheduled visit cycles. Southeast Medicaid carve-outs in Georgia and South Carolina are expanding reimbursement pathways for previously uninsured populations.
- Telemedicine:Remote monitoring platforms paired with AI-powered tissue assessment enable asynchronous specialist consultation. Appalachian and Delta regions are deploying these tools to address access deserts created by certificate-of-need restrictions.
- Inpatient Care:Acute surgical services and complex wound management remain concentrated in designated wound centers within hospital systems.
- Rehabilitation Services:Post-acute wound care supports functional recovery protocols in skilled nursing and inpatient rehabilitation facilities.
Outpatient services dominate current volume; telemedicine shows the steepest expansion trajectory as workforce constraints and rural access gaps intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity Zones in distressed census tracts accelerate wound care center placement across Florida and Texas, concentrating capital deployment where diabetic prevalence intersects with aging demographics.
Southeast
Florida and Georgia drive regional volume through Medicare Advantage penetration and Medicaid carve-outs for uninsured diabetic populations. CMS Hospital Outpatient Prospective Payment System reforms compress HBO margins while rewarding amputation-reduction outcomes. Miami-Dade and Broward counties anchor integrated delivery networks controlling referral flow from dense Medicare populations.
Southwest
Texas and Arizona health systems capture bundled payment contracts through ASC migration strategies for lower-acuity debridement. State certificate-of-need regulations in Texas protect incumbent hospital operators from greenfield competition. Dallas-Fort Worth and Houston medical centers deploy portable negative pressure systems to extend specialist reach into rural access deserts.
Northeast
New York certificate-of-need laws constrain new center licensing, creating protected markets for existing hospital-affiliated operators. CMS physician fee schedule proposals threaten to redirect volume toward home healthcare channels. New York City and Long Island wound care networks leverage dense referral bases for complex case concentration.
Midwest
Illinois and Ohio aging industrial populations generate chronic wound incidence from venous insufficiency and peripheral artery disease. State Medicaid wound care benefit variations create reimbursement fragmentation across county lines. Chicago and Cleveland health systems consolidate purchasing power for biologic supply agreements with tissue processors.
Mountain West
Nevada and Colorado commercial payor competition drives rapid bundled payment contract innovation for 30-90 day healing cycles. Telewound platforms paired with AI tissue assessment tools address workforce gaps in rural counties. Las Vegas and Denver medical centers pilot asynchronous specialist consultation for Appalachian and Delta region extension.
US Wound Care Centers Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across fragmented site-of-service configurations. Hospital-affiliated joint ventures transfer operational risk to health system partners while independent operators face Medicare reimbursement compression forcing consolidation. Three archetypes dominate: national center network models, regional integrated delivery networks, and ambulatory surgical center specialists. Competitive moves center on managed-service agreement expansion and exclusive biologic supply negotiations.
Within the national network tier, Healogics, Inc. and RestorixHealth exemplify scale-driven positioning through hospital system partnerships spanning multiple states. Baptist Health South Florida occupies a vertically integrated regional anchor role controlling referral flow from dense diabetic populations. These three entities represent contrasting capital structures: pure-play wound specialists, joint-venture risk transfer models, and health system captive operations.
| Leading Market Players |
|---|
| Healogics, Inc. |
| Baptist Health South Florida |
| EmergeOrtho |
| TOWER Wound Care Center |
| RestorixHealth |
| John Hopkins Medicine |
| Wound Care Center NYC |
| North Shore Health and Hyperbarics |
| The Wound Company |
| Others |
Cost & Logistics Intelligence
Amniotic membrane tissue pricing indices cascade through wound care supply chains into three-tier pricing structures across premium biologics, standard advanced dressings, and economy commodity alternatives. CMS reimbursement compression at the hospital outpatient level feeds back into procurement decisions, pressuring integrated delivery networks to consolidate purchasing power through exclusive supply agreements with FDA-registered tissue processors.
Pricing Analysis
Lead-time-driven pricing angles dominate biologic procurement, with premium positioning for same-day amniotic membrane availability against discounted rates for scheduled spot inventory releases. Three-tier pricing structure across premium cellular products, standard negative pressure systems, and economy hydrocolloid dressings reflects FDA clearance status and clinical outcome validation. Cost compression in hyperbaric oxygen therapy service lines is intensifying because CMS national coverage determinations have narrowed eligibility criteria. Ambulatory surgical centers exhibit the highest price sensitivity as they compete for bundled payment contracts, while hospital-based centers maintain pricing power through certificate-of-need protected markets.
Supply Chain Analysis
Domestic-content mandates in Florida and Texas certificate-of-need proceedings are reshaping sourcing toward US-based tissue banks and regional distribution hubs. Supply concentration centers on domestic FDA-registered tissue processors for placental and amniotic membrane derivatives, with secondary sourcing from South Korean and Israeli advanced dressing manufacturers. Raw material dependencies include cryopreserved human allograft tissue, medical-grade polyurethane foam, and antimicrobial silver compounds. Single-source vulnerability persists for cellular product inputs from limited accredited tissue banks. Distribution runs through integrated delivery network central procurement offices and group purchasing organizations serving hospital-affiliated wound centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US wound care centers market is becoming a vertical-integration race as operators pursue backward integration into tissue processing and exclusive supply agreements to defend margin pools against reimbursement compression.
For Market Incumbents: Cement hospital system partnerships through managed-service agreements that lock in referral flow and block competitor access to certificate-of-need protected markets. Deepen captive supply arrangements with FDA-registered tissue banks to secure biologic product availability amid input concentration risks. Fortify against ASC site-of-service migration by embedding wound care capabilities into hospital outpatient departments eligible for higher reimbursement rates.
For New Entrants and Emerging Players: Capture telewound platforms and remote monitoring capabilities that extend specialist reach into rural access deserts created by certificate-of-need restrictions. Target Medicaid carve-out expansions in Georgia and South Carolina where reimbursement pathways for previously uninsured diabetic populations are opening. Deploy AI-powered tissue assessment tools as the primary go-to-market angle, positioning asynchronous consultation as a workforce multiplier for health systems facing nursing specialization gaps.
For Investors and Strategic Acquirers: Distressed-cycle entries favor ambulatory surgical center networks with wound care capabilities in Texas and Arizona where bundled payment contract innovation is accelerating. Long-term viability over the coming decade hinges on exposure to value-based reimbursement structures rather than fee-for-service dependency. Monitor CMS physician fee schedule proposals as the critical inflection signal for volume migration toward home healthcare channels.
| Strategic Initiative | Industry Significance |
|---|---|
| Biologic Supply Agreement | Exclusive contracts with FDA-registered tissue processors lock in margin pools and block competitor access to cellular products. |
| Telewound Platform Deployment | Remote monitoring paired with AI tissue assessment extends specialist reach into certificate-of-need constrained rural counties. |
| ASC Capability Addition | Texas and Arizona surgery centers adding wound care services capture bundled payment contracts shifting from hospital outpatient departments. |
| Hospital Joint Venture Structure | Risk transfer models align operator incentives with health system partners under CMS value-based wound healing metrics. |
| Reimbursement Strategy Investment | Early positioning for Medicare Advantage penetration and Medicaid carve-out expansions secures patient volume in Southeast markets. |
Research Approach
Independent corroboration across wound center operations executives, hospital purchasing committee members, biomedical engineers, and GPO contracts managers underwrites the qualitative findings. Primary fieldwork with these stakeholders combined with secondary validation against CMS Medicare reimbursement databases, FDA 510(k) clearance filings, and hospital procurement records establishes analytical rigor. Bottom-up center-level volume estimates and top-down market sizing triangulate toward convergent figures.
Comparable-period anchoring to historical reimbursement rate trajectories and diabetic ulcer incidence patterns grounds the projection framework across the analysis window. Segmentation modeling incorporates product type, wound etiology, end-user site of service, and state-level regulatory cluster dimensions. CAGRs derive from regression analysis against Medicare enrollment projections and payor mix evolution. Forecast inputs include CMS Hospital Outpatient Prospective Payment System reform timelines and certificate-of-need licensing approval rates by state.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to CMS national coverage determination revisions and biologic product supply disruptions. Assumptions underlying volume projections reflect current reimbursement eligibility criteria and state Medicaid program structures. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Europe Negative Pressure Wound Therapy Market
Wound Care
Advanced Wound Management Market
Wound Care
North America Negative Pressure Wound Therapy Market
Wound Care
Wound Irrigation Solutions Market
Wound Care
Biopatches Market
Wound Care
Wound Closure Market
Wound Care
Global Wound Dressings Market
Wound Care
Wound Management Market
Wound Care
Venous Leg Ulcer (VLU) Treatment Market
Wound Care
Wound Closure Strips Market
Wound Care
Post-Operative Wound Treatment Market
Wound Care
Alginate Dressing Market
Wound Care
Vascular Dressings Market
Wound Care
Wound Healing Supplement Market
Wound Care
Wound Drainage Devices Market
Wound Care
Interactive Wound Dressing Market