
 Burn Care Centers Market | 2026-2036
Burn Care Centers Market Size, Share, and Industry Trends Forecast 2026-2036
Burn Care Centers Market Intelligence
Modular service bundling is decoupling emergency stabilization from long-term reconstructive care, allowing payers to contract discrete phases separately. Burn and Reconstructive Centers of America leverages its multi-state network to control referral channel volume across the Southeast. Weill Cornell Medicine William Randolph Hearst Burn Center anchors its competitive position through R&D intensity in tissue-engineered graft protocols. Joseph M. Still Burn Center specializes in military and industrial burn cases, sustaining volume through Department of Veterans Affairs partnerships.
Burn care centers deliver acute surgical intervention, wound management, and functional rehabilitation for thermal, chemical, electrical, and radiation injuries requiring specialized debridement, fluid resuscitation, and grafting procedures exceeding general hospital capability. Biological dressings and skin grafting technologies dominate current procedure mix, though tissue engineering represents the fastest-expanding margin pool as autologous cell therapies advance toward standardized reimbursement. Inpatient care still occupies the largest revenue share across service types, but outpatient protocols are displacing length-of-stay patterns where partial-thickness protocols allow early discharge with remote monitoring.
FDA breakthrough device designation and CMS inpatient prospective payment system updates jointly shape product adoption timelines and facility reimbursement rates for novel graft technologies. State-level certificate-of-need regulations in Texas, Florida, and Georgia control new center entry, entrenching incumbents with established trauma network affiliations. Stakeholders must monitor whether Medicare's evolving site-neutral payment stance will compress margins for hospital-based burn units versus freestanding specialized clinics.
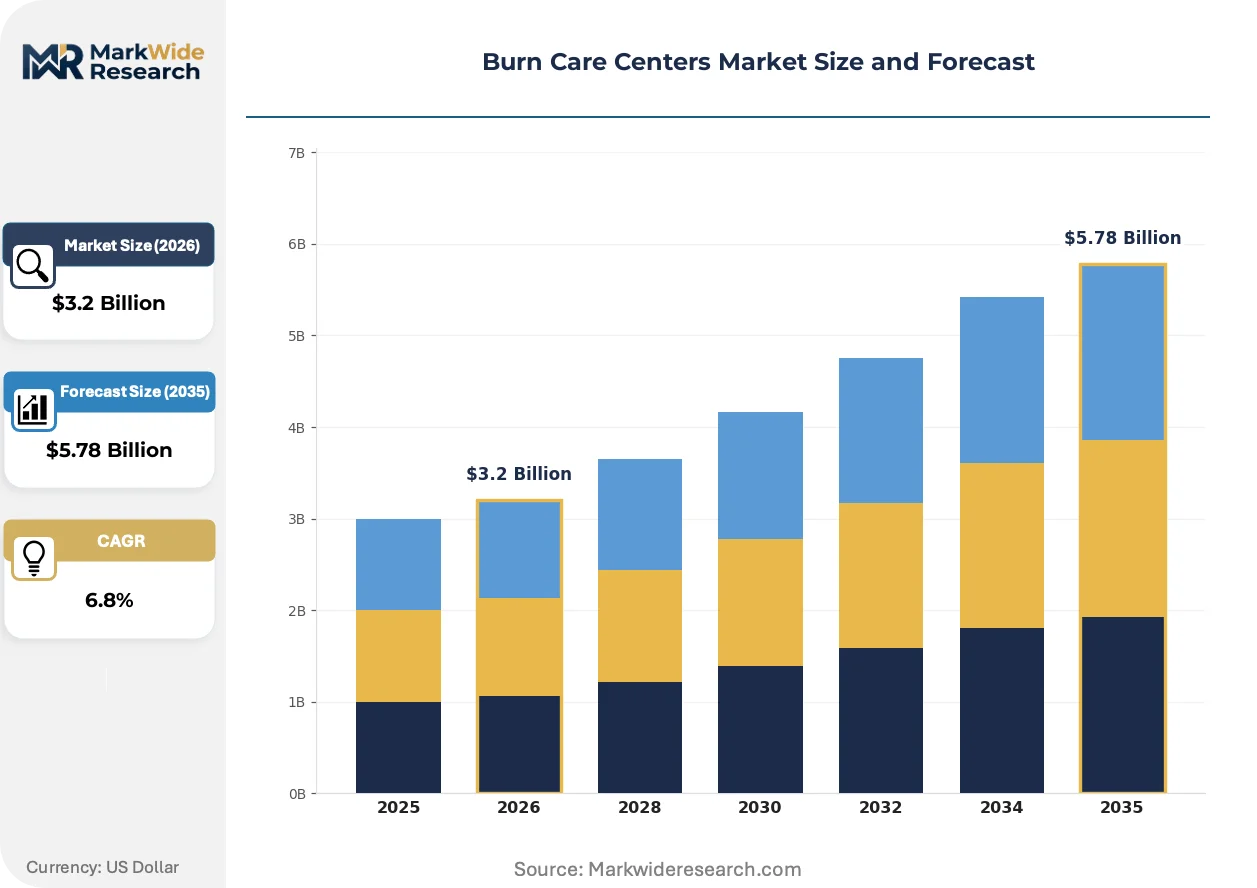
Market Dynamics
Certificate-of-need regulations in Texas, Florida, and Georgia are locking in established trauma network affiliations while FDA breakthrough designations accelerate novel graft technology adoption. This regulatory dualism entrenches incumbent centers with regional referral monopolies while creating asymmetric access for advanced biologics.
Growth Catalysts
- CMS Inpatient Prospective Payment System updates:Reimbursement rate adjustments for novel graft technologies are incentivizing hospital investment in advanced wound care infrastructure. Burn centers with established trauma affiliations capture disproportionate case volume.
- Military and veteran healthcare procurement expansion:Department of Veterans Affairs partnerships are sustaining specialized burn treatment volume through dedicated referral channels for industrial and combat-related injuries.
- Autologous cell therapy standardization:Tissue-engineered graft protocols are advancing toward formalized reimbursement codes, expanding margin pools beyond biological dressings for centers with R&D capabilities.
Market Restraints
- Certificate-of-need barriers:Texas, Florida, and Georgia regulations block new center entry, limiting competitive pressure on incumbent pricing and service innovation.
- Specialized surgeon supply concentration:Fellowship-trained burn surgeons cluster at established academic medical centers, constraining workforce expansion for new market entrants.
- Biological dressing input cost volatility:Cadaveric allograft and xenograft supply chains face donor availability fluctuations and cold-chain logistics premiums.
Strategic Opportunities
- Outpatient protocol expansion:Partial-thickness burn remote monitoring programs are displacing traditional length-of-stay patterns, opening freestanding clinic models outside hospital cost structures.
- Southeastern United States network density:Underserved rural catchments within high-burn-incidence states present acquisition targets for multi-state referral system expansion.
- Site-neutral payment arbitrage:Medicare's evolving stance on hospital-based versus freestanding reimbursement creates margin compression opportunities for specialized clinic formats.
Industry Challenges
- Tissue engineering certification timelines:FDA breakthrough designation pathways require extensive clinical evidence packages, delaying commercialization for autologous cell therapy platforms.
- Integrated electronic health record fragmentation:Burn center-specific documentation requirements for graft tracking and wound photography resist standardization across hospital system IT architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Burn Care Centers Market |
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $5.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Inpatient Care, Outpatient Care, Rehabilitation Services, Emergency Services Technology: Laser Treatment, Biological Dressings, Skin Grafting, Tissue Engineering Care Setting: Hospitals, Specialized Clinics, Urgent Care, Home Health Client Type: Pediatric Patients, Adult Patients, Burn Survivors, Caregivers |
| Companies Covered | Parkland Memorial Hospital Regional Burn Center, St. Barnabas Burn Center, LAC+USC Medical Burn Center, Burn and Reconstructive Centers of America, UMC Lions Burn Center, Weill Cornell Medicine William Randolph Hearst Burn Center, MedStar Washington Hospital Center, Joseph M. Still Burn Center, Temple University Hospital Adult Burn Center, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Burn Care Centers Market Strategic Shifts & Innovations
Technology convergence between regenerative medicine and remote patient monitoring is collapsing traditional care episode boundaries. Regulatory pathways and procurement models are adapting unevenly across federal and state jurisdictions.
Biological dressings paired with negative pressure wound therapy systems are consolidating acute surgical intervention protocols. Military treatment facilities and Level I trauma centers are adopting these integrated platforms fastest. The technology is consolidating vendor relationships around single-source procurement contracts that bundle graft materials with monitoring hardware.
FDA breakthrough device designation pathways are compressing clinical access timelines for advanced wound care technologies. The designation grants prioritized review and enhanced Medicare coverage determination support. Tissue-engineered graft manufacturers with autologous cell platforms are capturing disproportionate regulatory resources under this framework.
Modular service unbundling is separating emergency stabilization from long-term reconstructive contracting. Payers now negotiate discrete phase contracts rather than episode-based bundles. This pattern concentrates across southeastern states where burn center density enables competitive phase sourcing.
Burn Care Centers Market Segmentation
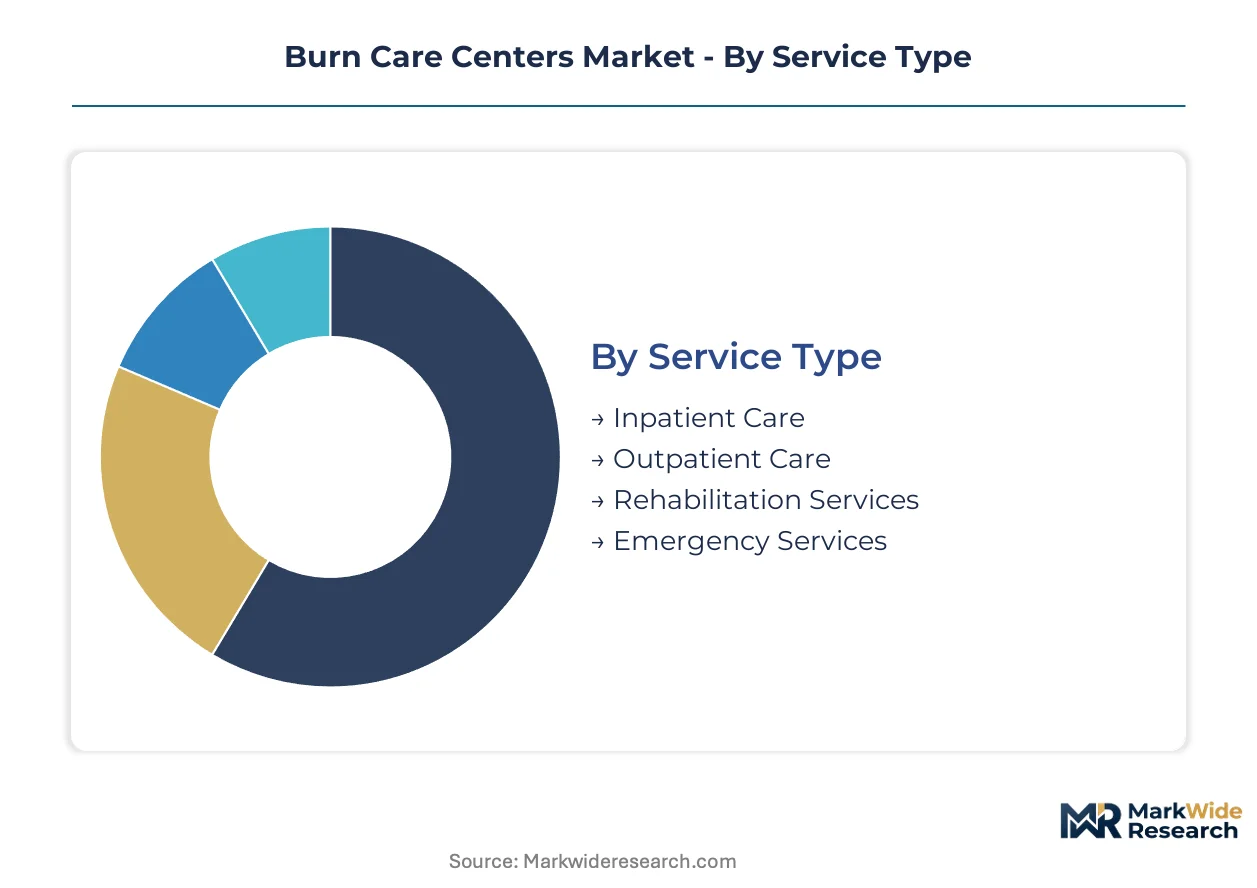
Burn care delivery fragments across acute intervention intensity, technological sophistication, and care setting economics. Each segmentation axis reveals distinct margin structures, regulatory exposure, and competitive entry barriers that determine facility investment priorities.
Service Type:
Intervention acuity defines staffing ratios, length-of-stay economics, and payer mix concentration.
- Inpatient Care:Continuous surgical intervention, fluid resuscitation, and intensive grafting procedures requiring Level I trauma center infrastructure. Military treatment facilities and industrial corridor hospitals in Texas, Florida, and Georgia capture disproportionate severe case volume through established trauma network affiliations.
- Outpatient Care:Partial-thickness wound management with remote monitoring protocols displacing traditional admission patterns. Southeastern United States freestanding clinics are expanding fastest where certificate-of-need regulations protect incumbent hospital systems from direct competition.
- Rehabilitation Services:Functional restoration and scar management protocols extending post-acute revenue capture.
- Emergency Services:Stabilization and triage functions increasingly unbundled from longitudinal reconstructive contracting.
Inpatient Care leads on scale; Outpatient Care leads on momentum.
Technology:
Material science advancement and regulatory pathway speed separate margin pools across wound closure modalities.
- Biological Dressings:Cadaveric allografts and xenografts dominating current procedure volume with established reimbursement codes. Supply chain volatility from donor availability fluctuations constrains cost predictability for centers dependent on third-party tissue bank procurement.
- Tissue Engineering:Autologous cell therapy platforms advancing through FDA breakthrough device designation toward standardized CMS coverage. Weill Cornell Medicine and academic medical centers with R&D intensity capture regulatory resources and early adoption premiums.
- Skin Grafting:Autograft and allograft surgical protocols remaining the clinical standard for full-thickness injuries.
- Laser Treatment:Scar revision and vascular lesion management for late-stage reconstructive phases.
Biological Dressings anchors current revenue; Tissue Engineering climbs the fastest.
Care Setting:
Capital intensity and site-neutral payment exposure determine competitive positioning against hospital cost structures.
- Hospitals:Integrated trauma networks with certificate-of-need protected catchments in Texas, Florida, and Georgia. Burn and Reconstructive Centers of America leverages multi-state hospital affiliations to control referral channel volume across the Southeast.
- Specialized Clinics:Freestanding facilities arbitraging Medicare's evolving site-neutral payment stance to compress overhead versus hospital-based units. Outpatient protocol expansion enables partial-thickness case capture outside inpatient cost structures.
- Urgent Care:Initial triage and stabilization for minor thermal injuries with transfer agreements to verified burn centers.
- Home Health:Remote monitoring and dressing change protocols for selected outpatient transitions.
Hospitals dominate acute complexity; Specialized Clinics gain share fastest on payment arbitrage.
Client Type:
Demographic-specific physiology and psychosocial support requirements shape service design and reimbursement negotiation.
- Adult Patients:Industrial and military injury concentration sustaining volume through Department of Veterans Affairs partnerships. Joseph M. Still Burn Center specializes in combat-related and occupational thermal, chemical, and electrical cases.
- Pediatric Patients:Scald prevention protocols and developmental-stage reconstructive planning requiring specialized fellowship training. Fellowship-trained pediatric burn surgeons cluster at established academic medical centers, constraining workforce expansion.
- Burn Survivors:Long-term functional and aesthetic reconstruction spanning years post-injury with discrete phase contracting opportunities.
- Caregivers:Training and support services increasingly unbundled as separate reimbursable episodes.
Adult Patients leads on volume concentration; Pediatric Patients leads on specialized margin capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Burn care infrastructure traces its modern lineage to military medicine advances during mid-20th century conflicts, with specialized centers later commercializing trauma protocols into civilian networks. Geographic distribution now concentrates where industrial corridors, military installations, and regulatory frameworks intersect.
United States
Southeastern states sustain the highest burn center density per capita, with Texas, Florida, and Georgia operating under certificate-of-need regulations that protect incumbent trauma network affiliations. FDA breakthrough device designations accelerate novel graft technology access at academic medical centers. Dallas anchors the Parkland Memorial Hospital Regional Burn Center, which controls referral volume across the Southwest industrial corridor.
Germany
Industrial chemical manufacturing clusters along the Rhine generate occupational thermal and chemical injury demand for specialized intervention. The country's national pharmaceutical regulator enforces MDR compliance for advanced wound care biologics entering clinical use. Berlin and Hamburg concentrate Level I trauma centers with integrated burn units serving northern European catchments.
China
Rapid industrialization across manufacturing zones elevates electrical and chemical burn incidence requiring surgical capacity beyond general hospital capability. NMPA prioritizes review pathways for tissue-engineered graft technologies meeting domestic production targets. Shanghai and Beijing academic medical centers anchor regional networks with procurement ties to military healthcare systems.
United Kingdom
London and Birmingham trauma networks coordinate specialized burn referrals across England's regional health service structure. NHS England reimbursement frameworks differentiate acute surgical intervention from reconstructive phase contracting. Manchester and Glasgow centers capture industrial corridor volume from northern manufacturing and petrochemical installations.
Australia
Remote mining operations and rural thermal injury patterns necessitate aeromedical retrieval networks feeding metropolitan burn centers. TGA regulates biological dressing importation with cold-chain certification requirements. Sydney and Melbourne anchor the eastern seaboard infrastructure, with Perth serving Western Australian mining corridor demand.
Burn Care Centers Market Key Industry Players
Premium-margin players sit above commodity-margin players across R&D intensity and trauma network exclusivity. The market structure consolidates around academic medical centers with fellowship training programs and multi-state referral systems. Three archetypes dominate: trauma-network-anchored academic centers, multi-state specialized networks, and military-partnered industrial specialists. Competitive moves concentrate on geographic network expansion through certificate-of-need protected catchments and tissue engineering platform development.
Among trauma-network-anchored academic centers, Weill Cornell Medicine William Randolph Hearst Burn Center and Joseph M. Still Burn Center exemplify divergent specialization vectors—one emphasizing R&D intensity in tissue-engineered protocols, the other sustaining volume through Department of Veterans Affairs partnerships. Burn and Reconstructive Centers of America occupies a position as the multi-state network archetype, leveraging hospital affiliations to control referral channel volume across protected southeastern markets.
| Leading Market Players |
|---|
| Parkland Memorial Hospital Regional Burn Center |
| St. Barnabas Burn Center |
| LAC+USC Medical Burn Center |
| Burn and Reconstructive Centers of America |
| UMC Lions Burn Center |
| Weill Cornell Medicine William Randolph Hearst Burn Center |
| MedStar Washington Hospital Center |
| Joseph M. Still Burn Center |
| Temple University Hospital Adult Burn Center |
| Others |
Cost & Logistics Intelligence
Tissue-engineered graft manufacturing transitions from cadaveric sourcing to autologous cell cultivation simultaneously compresses per-unit production costs and concentrates supply among academic medical centers with captive bioreactor capacity. This shift redraws procurement economics for burn centers dependent on third-party tissue bank relationships.
Pricing Analysis
Episode-based contracting for acute stabilization separates from discrete reconstructive phase pricing across southeastern states with burn center density. Price differentiation rests on FDA breakthrough designation status and trauma network exclusivity rather than commodity graft material costs. Cost compression in biological dressing tiers intensifies as cadaveric allograft supply chains face donor availability constraints. Hospital-based burn units exhibit lowest price sensitivity due to certificate-of-need protected catchments; freestanding specialized clinics face highest pressure from Medicare site-neutral payment evolution.
Supply Chain Analysis
Remanufacturing flows for negative pressure wound therapy hardware create secondary equipment channels that subsidize graft material procurement for cost-constrained centers. Biological dressing supply concentrates in the United States, Germany, and Australia where tissue banking infrastructure meets cold-chain certification standards. Raw material dependencies center on cadaveric skin donors, porcine xenograft sources, and synthetic scaffold polymers. Single-source vulnerability runs through consolidated tissue bank networks feeding multiple regional burn centers. Distribution runs through Group Purchasing Organizations and military medical logistics channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Burn care centers operate as stable compounders anchored by trauma network exclusivity and military procurement continuity. Regulatory barriers and specialized workforce scarcity protect incumbent returns across multi-year horizons.
For Market Incumbents: Extend trauma network affiliations into adjacent certificate-of-need states before regulatory windows narrow. Deepen backward integration into autologous cell therapy bioreactor capacity to capture margin pools shifting from biological dressings. Defend against freestanding clinic entrants by accelerating outpatient protocol development for partial-thickness cases. For New Entrants and Emerging Players: Telemedicine-enabled remote monitoring platforms offer the lowest-friction entry vector for outpatient burn care capture. Target underserved rural catchments within Texas, Florida, and Georgia where certificate-of-need regulations block hospital-based competition but permit freestanding clinic formats. Pursue Department of Veterans Affairs subcontractor status to secure dedicated referral volume outside competitive trauma networks. For Investors and Strategic Acquirers: Valuations sit cheapest among regional burn centers lacking R&D infrastructure but holding protected catchment demographics. Long-term viability frames around tissue engineering platform adoption timelines and Medicare site-neutral payment finalization. Monitor FDA breakthrough device designation grants to academic medical centers as inflection signals for margin pool redistribution.| Strategic Initiative | Industry Significance |
|---|---|
| Certificate-of-Need Expansion | Geographic network extension into adjacent regulated states captures protected referral volume. |
| Autologous Cell Therapy Development | FDA breakthrough designation pursuit secures prioritized review and enhanced CMS coverage support. |
| Military Partnership Deepening | Department of Veterans Affairs contracting sustains volume through dedicated combat and industrial injury channels. |
| Outpatient Protocol Standardization | Remote monitoring program expansion arbitrages Medicare site-neutral payment against hospital cost structures. |
| Bioreactor Infrastructure Investment | In-house tissue engineering capacity reduces third-party tissue bank dependency and input cost volatility. |
Research Approach
Coverage spans the United States, Germany, China, the United Kingdom, and Australia, with primary inputs from each regional cluster. The approach combines structured interviews with burn center medical directors, hospital procurement officers, tissue bank supply managers, and military healthcare logistics coordinators with secondary validation from FDA 510(k) filings, CMS reimbursement databases, and state certificate-of-need regulatory records. Bottom-up facility capacity modeling and top-down trauma network volume estimates triangulate market sizing.
Rate-of-change decomposition separates volume drivers from price evolution across the projection horizon. Segmentation dimensions include service type acuity, technology sophistication tier, care setting economics, and client demographic category. CAGRs derive from facility expansion pipelines, graft technology adoption curves, and payer mix evolution assumptions. Military procurement forecasts and tissue engineering regulatory pathway timelines anchor scenario boundaries.
The model assumes a particular technology adoption path; alternative pathways for autologous cell therapy commercialization would alter the outlook if FDA breakthrough designations accelerate or delay. Forecasts reflect assumptions around certificate-of-need regulatory stability and Medicare site-neutral payment implementation scope. Practitioners should monitor state legislative sessions for CON reform proposals and CMS inpatient prospective payment system rulemaking for graft technology reimbursement adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Wound Drainage Devices Market
Wound Care
Chronic Wound Care Market
Wound Care
Middle East and Africa Advanced Wound Care Market
Wound Care
Wound Care Market
Wound Care
Wound Skin Care Market
Wound Care
Global Active Wound Care Market
Wound Care
Global Digital Wound Measurement Devices Market
Wound Care
Saudi Arabia Wound Care Management Devices Market
Wound Care
Mexico Wound Care Management Devices Market
Wound Care
Venous Ulcer Treatment Market
Wound Care
Surgery Medical Bandage Market
Wound Care
Moist Wound Dressings Market
Wound Care
Wound Biologics Market
Wound Care
Global Negative Pressure Wound Therapy (NPWT) Devices Market
Wound Care
Advanced Wound Therapy Devices Market
Wound Care
United States Negative Pressure Wound Therapy Market