
 Vaginal Applicators Market | 2026-2036
Vaginal Applicators Market Size, Share, and Industry Trends Forecast 2026-2036
Vaginal Applicators Market Analytics
Pre-filled, unit-dose bundling with hormone therapies is realigning how patients and pharmacies evaluate vaginal applicator procurement. HTI Plastics leverages its injection-molding scale to supply pharmaceutical-grade disposable applicators under contract manufacturing arrangements. Beyon Devices anchors its position through specialized design services for biotech clients requiring custom gel-capsule delivery geometries. BD competes across hospital and retail channels with integrated packaging that combines applicators with prescribed therapeutic loads.
Vaginal applicators are single-use or limited-use devices engineered from medical-grade plastics, silicone, or bio-composites, typically featuring barrel lengths of 7–10 centimeters and calibrated dose-markings for precise intravaginal deposition of creams, gels, or tablets. Their primary commercial purpose is to enable accurate, hygienic self-administration of topical or localized pharmaceutical and wellness formulations. Disposable plastic applicators dominate procurement volumes across hormonal therapy applications, where sterility assurance and convenience override unit-cost considerations. Reusable silicone variants command premium positioning within fertility treatment segments, where patients cycle through multiple medication phases and prioritize device durability and ease of cleaning.
The FDA regulates vaginal applicators as Class I or Class II medical devices depending on drug-device combination status, while the EPA governs plastic resin sourcing and post-consumer disposal pathways for disposable units. ISO 10993 biocompatibility testing and USP Class VI certification shape material selection and supplier qualification timelines for manufacturers serving North American markets. Stakeholders must monitor evolving state-level pharmaceutical packaging waste regulations and reimbursement policy shifts for at-home administration to anticipate channel margin pressures and compliance-driven redesign cycles.
Market Dynamics
Telehealth-integrated prescription services are compressing the channel distance between pharmaceutical manufacturers and at-home users, forcing applicator suppliers to redesign packaging for direct-to-consumer fulfillment rather than clinical bulk distribution.
Growth Catalysts
- Telehealth prescription expansion:Direct-to-consumer pharmacy channels in the United States are accelerating at-home adoption of disposable applicator systems by eliminating clinical intermediaries.
- FDA 510(k) pathway modernization:The FDA's updated clearance protocols for single-use vaginal drug delivery devices are compressing product development timelines and accelerating market entry.
- Home-based fertility protocols:Fertility treatment segments are expanding beyond clinical settings, creating sustained pull for both disposable and reusable applicator formats.
Market Restraints
- Medical-grade resin cost volatility:Petroleum-derived polypropylene and polyethylene input costs fluctuate with energy markets, squeezing margins on high-volume disposable production.
- Post-consumer disposal pathway constraints:EPA regulations governing plastic waste streams limit landfill alternatives and impose compliance costs on manufacturers without recycling infrastructure partnerships.
- Reusable silicone cleaning burden:Fertility patients cycling through multiple medication phases face hygiene complexity that suppresses premium reusable adoption despite durability advantages.
Strategic Opportunities
- Biocomposite material convergence:Bio-based polymers paired with compostable certification are creating white space for sustainability-positioned premium applicators in wellness segments.
- State-level pharmaceutical packaging incentives:Extended producer responsibility frameworks in California and New York are creating regulatory tailwinds for redesign investments that exceed baseline compliance.
- Underpenetrated Latin American pharmacy channels:Brazil and Mexico present expansion opportunities where telehealth infrastructure is maturing but specialized applicator distribution remains fragmented.
Industry Challenges
- ISO 10993 biocompatibility testing timelines:Material qualification protocols for new resin formulations extend supplier onboarding by 12-18 months, delaying product line refreshes.
- Injection-molding talent scarcity:Precision medical device manufacturing requires specialized tooling expertise that concentrates in aging workforce clusters across the US Midwest and Germany.
- Drug-device combination documentation:FDA Class II submissions for pre-filled applicators demand integrated stability data that fragments project management across pharmaceutical and device development teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vaginal Applicators Market |
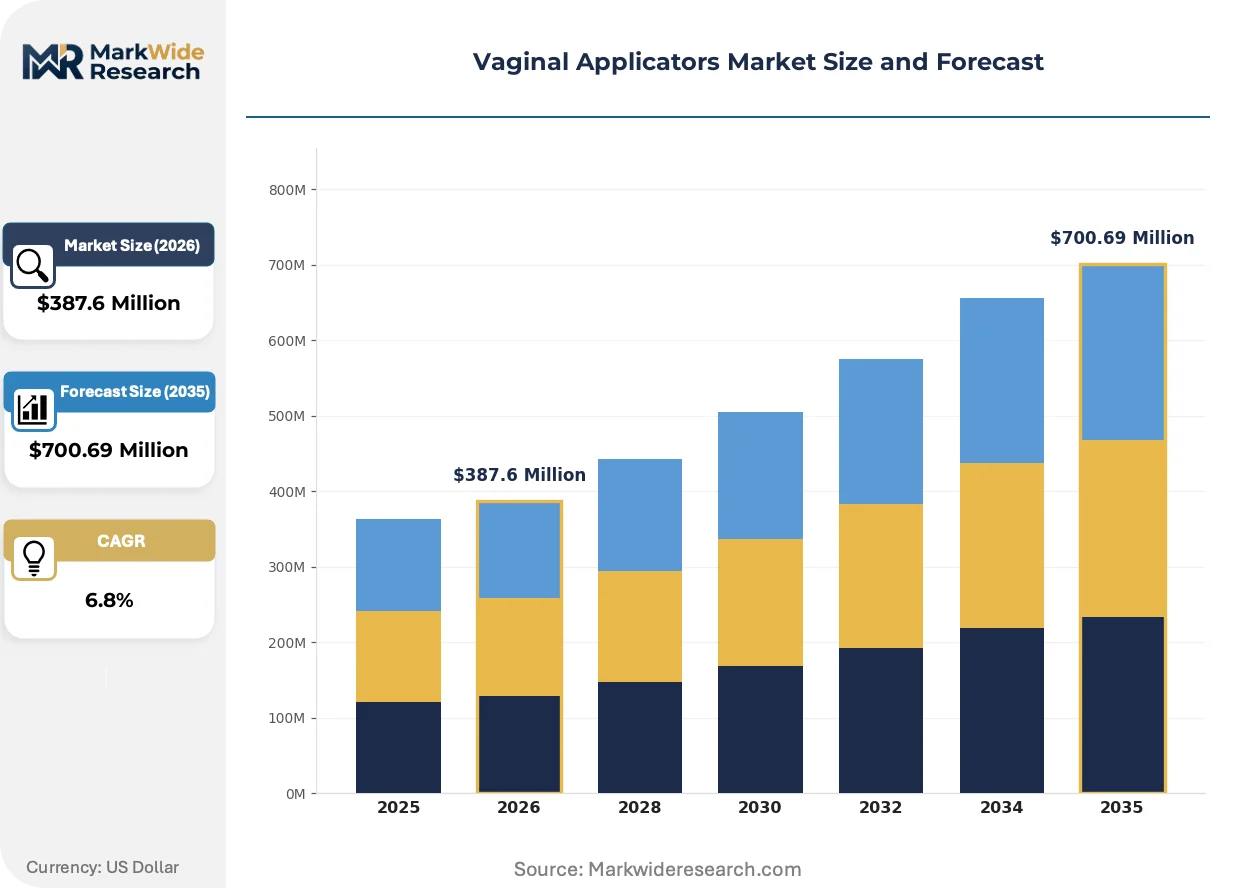
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Reusable, Tampon-Based, Gel-Capsule Application: Hormonal Therapy, Lubrication, Contraception, Fertility Treatment End User: Healthcare Professionals, Home Users, Pharmacies, Clinics Material: Plastic, Silicone, Bio-Composite, Rubber |
| Companies Covered | HTI Plastics, Tekpak, Beyon Devices, BD (Becton Dickinson and Company), Cardinal Health, Union Plastic S.A, Ningbo Suncity, CooperSurgical Inc, SRC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vaginal Applicators Market Evolving Landscape
Connected health infrastructure and material science advances are converging to redefine how vaginal applicators are designed, regulated, and procured across therapeutic categories.
Smart dosing feedback mechanisms are integrating micro-pressure sensors and Bluetooth connectivity into reusable applicator platforms. Fertility clinics in Denmark and the Netherlands are piloting these devices to improve patient adherence to complex hormone protocols. This convergence is integrating real-world adherence data into pharmaceutical contract negotiations, compressing the traditional separation between device efficacy and drug outcomes.
The FDA's updated 510(k) clearance pathways for single-use vaginal drug delivery devices are reshaping submission requirements to emphasize human factors validation. Manufacturers must now demonstrate intuitive self-administration across diverse patient populations before market authorization. Pre-filled applicator systems combining hormone therapies are experiencing the most significant documentation burden increases, with sponsors investing in dedicated usability engineering teams.
Pharmacy benefit managers are consolidating formulary control over at-home fertility and hormone replacement therapies, concentrating purchasing power among three national distributors. Independent specialty pharmacies are responding by unbundling clinical counseling from product fulfillment, creating service-based differentiation. This concentration is most visible in the United States, where CVS Caremark and Express Scripts now dictate packaging specifications for disposable applicators across multiple therapeutic categories.
Vaginal Applicators Market Segmentation
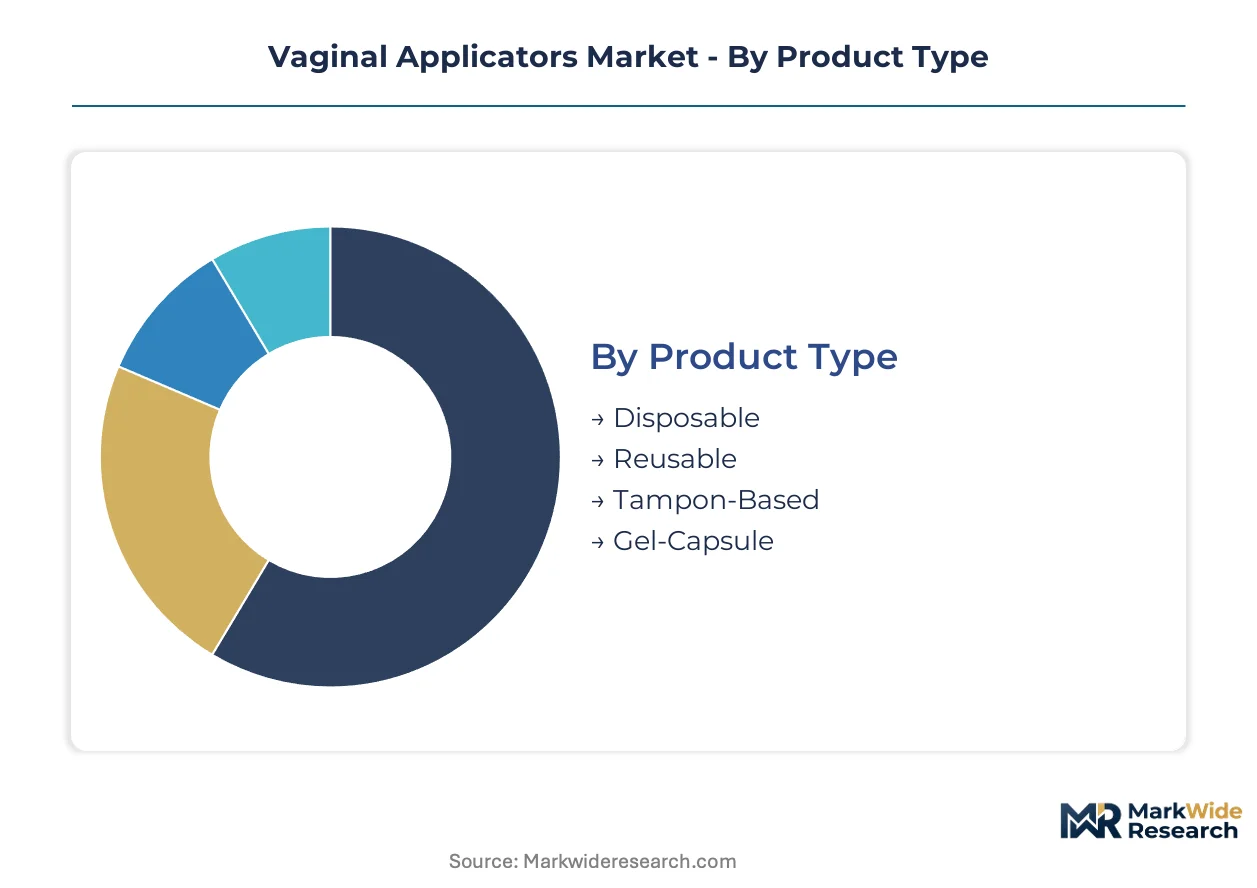
Segmentation in vaginal applicators reveals how procurement power fragments across therapeutic use cases and sterilization requirements. Manufacturers must align production capacity with the divergent volume, margin, and regulatory profiles of each segment cluster.
Product Type:
Supply concentration in injection-molding capacity favors high-volume disposable formats, while specialized tooling investments protect niche reusable and gel-capsule geometries.
- Disposable:Medical-grade polypropylene construction with pre-sterilized unit-dose packaging dominates hormonal therapy procurement. Demand concentrates in United States pharmacy benefit manager networks where CVS Caremark and Express Scripts dictate packaging specifications for at-home fulfillment.
- Reusable:Platinum-cured silicone platforms withstand repeated autoclaving and support multi-cycle fertility protocols. Denmark and Netherlands fertility clinics pilot connected versions with adherence sensors, though cleaning burden suppresses patient adoption despite durability advantages.
- Tampon-Based:Cotton-synthetic hybrid applicators serve wellness and menstrual product crossovers with minimal regulatory overhead.
- Gel-Capsule:Custom barrel geometries for biotech clients require specialized mold tooling and extended qualification timelines.
Today's leader: Disposable. Tomorrow's challenger: Reusable.
Application:
Cost tier stratification separates high-compliance pharmaceutical applications from discretionary wellness categories with minimal reimbursement attachment.
- Hormonal Therapy:Estrogen and progesterone delivery demands precise dose-marking and FDA Class II documentation. United States direct-to-consumer telehealth channels are accelerating volume fastest as pharmacy benefit managers consolidate formulary control.
- Fertility Treatment:Complex multi-phase protocols require calibrated deposition accuracy and patient adherence support. Home-based protocol expansion in Copenhagen and Amsterdam clinics is pulling both disposable and reusable formats beyond traditional clinical settings.
- Lubrication:Wellness-positioned SKUs compete on retail shelf presence with minimal therapeutic claims.
- Contraception:Spermicide gel delivery maintains steady institutional procurement through family planning clinics.
Pharmaceutical-grade applications command margin premiums; wellness categories compete on unit economics.
End User:
Volume concentration in home-based administration is forcing packaging redesign away from clinical bulk formats toward direct-to-consumer fulfillment specifications.
- Home Users:Self-administration demand requires intuitive human factors validation under FDA updated 510(k) pathways. United States telehealth-integrated prescription services are compressing channel distance and accelerating disposable system adoption.
- Healthcare Professionals:Clinical settings prioritize sterility assurance and single-use compliance over per-unit cost.
- Pharmacies:Independent specialty pharmacies are unbundling clinical counseling from product fulfillment to differentiate against consolidated distributors.
- Clinics:Fertility clinics in Denmark and Netherlands pilot connected reusable platforms for adherence monitoring.
Procurement power is concentrating in home-user channels; clinical volumes are flattening.
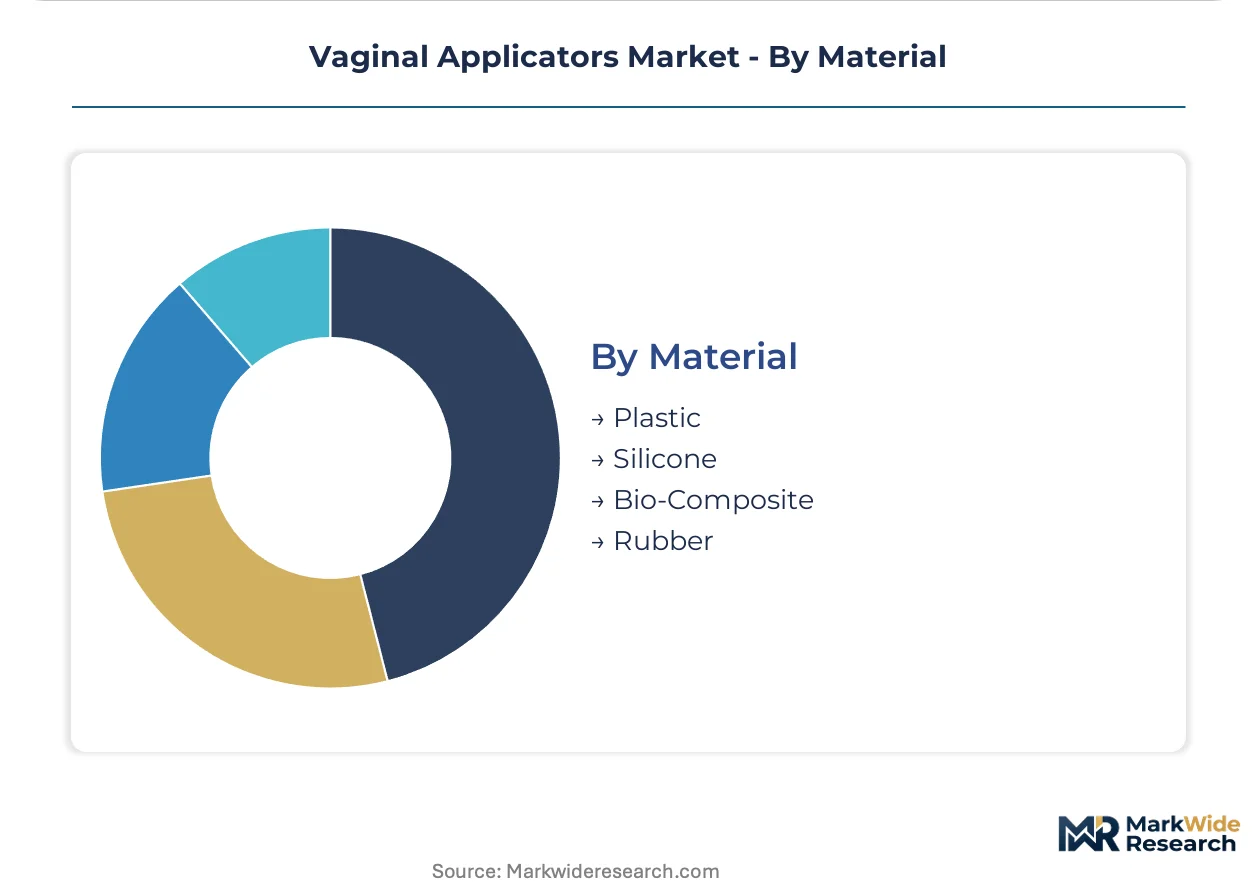
Material:
Margin structure diverges sharply between petroleum-derived commodity resins and certified bio-composite alternatives positioned for sustainability premiums.
- Plastic:Polypropylene and polyethylene dominate disposable production with ISO 10993 biocompatibility certification. Medical-grade resin cost volatility tied to energy markets squeezes margins on high-volume lines.
- Silicone:Platinum-cured formulations support reusable fertility platforms requiring autoclave durability and USP Class VI validation.
- Bio-Composite:Compostable-certified polymers are creating white space for sustainability-positioned wellness SKUs under California and New York extended producer responsibility frameworks.
- Rubber:Latex and synthetic elastomer variants serve cost-sensitive regional markets with minimal regulatory stringency.
Petroleum-derived plastics anchor current volume; bio-composites are climbing the fastest as regulatory tailwinds strengthen.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The vaginal applicators industry traces its commercial origins to mid-20th century pharmaceutical packaging innovations in the United States, where disposable medical-grade plastics first enabled standardized hormone therapy delivery at scale.
United States
Direct-to-consumer telehealth channels and pharmacy benefit manager consolidation drive procurement volume. FDA 510(k) pathway modernization accelerates product development timelines for single-use drug delivery devices. Minneapolis-St. Paul hosts concentrated injection-molding capacity serving contract manufacturing arrangements.
Germany
Precision medical device tooling expertise supports reusable silicone platform development for fertility applications. REACH regulations govern bio-composite material certification pathways. Baden-Württemberg industrial clusters specialize in platinum-cured silicone processing for autoclave-durable platforms.
Denmark
Copenhagen fertility clinics pilot connected reusable applicators with adherence monitoring sensors. EMA medical device regulations align with FDA Class II documentation requirements for combination products. Øresund Region biotech clusters integrate real-world adherence data into pharmaceutical contract negotiations.
Netherlands
Amsterdam fertility centers expand home-based protocols beyond traditional clinical settings. Extended producer responsibility frameworks create regulatory tailwinds for compostable packaging redesign. Eindhoven-region smart health technology clusters develop Bluetooth-enabled dosing feedback mechanisms.
Brazil
Maturing telehealth infrastructure and fragmented specialized distribution create expansion opportunities. ANVISA pharmaceutical packaging regulations govern import qualification timelines. São Paulo pharmacy channels consolidate procurement power as independent distributors respond to formulary concentration.
Vaginal Applicators Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material certification and sterilization assurance tiers. The vendor base stratifies between high-volume disposable producers and specialized reusable platform developers. Three archetypes dominate: contract manufacturing specialists supplying pharmaceutical-grade injection-molded units, biotech-facing design houses delivering custom gel-capsule geometries, and integrated health technology firms bundling applicators with therapeutic loads. Capacity expansion and strategic partnerships represent the dominant competitive moves as suppliers reposition for telehealth-integrated fulfillment channels.
Within the contract manufacturing tier, HTI Plastics and Beyon Devices occupy distinct positioning. HTI Plastics exemplifies scale-driven supply to pharmaceutical clients through injection-molding capacity concentration. Beyon Devices represents specialized design services for biotech firms requiring custom delivery geometries. BD anchors the integrated health technology segment, competing across hospital and retail channels with combined device-therapeutic packaging. These three players collectively illustrate how procurement power concentrates among suppliers capable of navigating FDA 510(k) documentation requirements while serving direct-to-consumer fulfillment specifications.
| Leading Market Players |
|---|
| HTI Plastics |
| Tekpak |
| Beyon Devices |
| BD (Becton Dickinson and Company) |
| Cardinal Health |
| Union Plastic S.A |
| Ningbo Suncity |
| CooperSurgical Inc |
| SRC |
| Others |
Value Network & Pricing Analysis
Medical-grade polypropylene resin costs cascade through three distinct pricing tiers before reaching pharmacy benefit managers, with petroleum price volatility at the upstream tier compressing margins for high-volume disposable manufacturers while premium reusable silicone platforms absorb input fluctuations through durability positioning.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the vaginal applicators market by sterilization assurance and certification grade. FDA Class II documentation and ISO 10993 biocompatibility certification separate premium hormone therapy applicators from standard wellness SKUs, while economy tiers serve cost-sensitive regional markets with minimal regulatory stringency. Cost compression in the standard tier intensifies because pharmacy benefit manager consolidation concentrates procurement power among three national distributors. Home-based fertility patients demonstrate lowest price sensitivity due to adherence requirements, whereas wellness segment consumers exhibit highest elasticity to unit-cost changes.
Supply Chain Analysis
Injection-molding talent scarcity in Minneapolis-St. Paul and Baden-Württemberg constrains precision medical device manufacturing capacity expansion. Supply concentrates in the United States, Germany, and China, with the US Midwest hosting concentrated pharmaceutical-grade production and German clusters specializing in platinum-cured silicone processing. Raw material sourcing draws from petroleum-derived polypropylene, platinum-cured silicone formulations, and emerging bio-composite polymers. Single-source vulnerability characterizes specialized mold tooling for custom gel-capsule geometries. Distribution runs through pharmacy benefit manager networks for hormonal therapy applications and direct-to-consumer telehealth channels for at-home fertility protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vaginal applicators market functions as a regulatory compounder where FDA 510(k) pathway modernization for single-use drug delivery devices continuously elevates compliance barriers and consolidates procurement power among documentation-capable suppliers.
For Market Incumbents: Cement dominance by deepening backward integration into medical-grade resin sourcing to buffer petroleum price volatility, while expanding injection-molding capacity in Minneapolis-St. Paul to capture pharmacy benefit manager volume concentration. Biocomposite material convergence from sustainability-positioned entrants threatens premium positioning; counter through preemptive compostable certification investments under California and New York extended producer responsibility frameworks. For New Entrants and Emerging Players: Direct-to-consumer telehealth fulfillment routes offer the most penetrable entry vector for specialized applicator systems, bypassing consolidated distributor gatekeeping. Target Latin American pharmacy channels in Brazil and Mexico where telehealth infrastructure matures but specialized distribution remains fragmented. Pursue white-space positioning in connected reusable platforms with adherence sensors for fertility clinic pilot programs in Copenhagen and Amsterdam. For Investors and Strategic Acquirers: Consolidation pressure builds where ISO 10993 biocompatibility testing timelines extend supplier onboarding and fragment project management across drug-device combination submissions. Long-term viability favors contract manufacturers with captive injection-molding capacity and documented FDA 510(k) clearance track records. Watch for inflection signals in state-level pharmaceutical packaging waste regulation tightening, which would accelerate redesign investment requirements and disadvantage non-compliant suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Compresses product development timelines for single-use drug delivery devices under modernized clearance pathways. |
| Backward Integration into Resin Sourcing | Buffers margin compression from petroleum-derived polypropylene cost volatility in high-volume disposable production. |
| Direct-to-Consumer Packaging Redesign | Aligns fulfillment specifications with telehealth-integrated prescription services and pharmacy benefit manager networks. |
| Biocomposite Certification Investment | Captures sustainability premiums under California and New York extended producer responsibility frameworks. |
| Smart Dosing Platform Development | Integrates Bluetooth-enabled adherence sensors for fertility clinic pilot programs in Denmark and Netherlands. |
Research Methodology
Multiple input streams — primary interviews with regulatory affairs leads at medical device manufacturers, formulary directors at pharmacy benefit managers, and biomedical engineers at fertility clinics; secondary validation through FDA 510(k) filings, EMA medical device registration databases, and hospital procurement records; plus customs data on medical-grade resin imports — were reconciled through bottom-up and top-down triangulation to construct market estimates.
Cross-referencing historical volume trajectories against panel-derived growth assumptions anchored projections across the analysis window. Segmentation dimensions modeled include product type (disposable, reusable, gel-capsule), application (hormonal therapy, fertility treatment), end user (home-based, clinical), and material certification tier. CAGRs were derived from slope consensus across input streams, with fertility protocol expansion rates and telehealth prescription penetration serving as key demand-side inputs.
The model assumes a particular technology adoption path; alternative pathways for connected reusable applicators with adherence sensors would alter the outlook if pilot programs in Copenhagen and Amsterdam fail to scale. Forecasts reflect assumptions about FDA documentation burden stability and pharmacy benefit manager consolidation continuity. Material deviation in state-level packaging waste regulation enforcement or medical-grade resin cost volatility warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Accelerometers Medical Sensors Market
Medical Devices
India Biopsy Devices Market
Medical Devices
North America Ultrasound Devices Market
Medical Devices
Pelvic Floor Electrical Stimulation Devices Market
Medical Devices
Transplant Monitoring Kits Market
Medical Devices
Global Cryotherapy Market
Medical Devices
Temporary Pacing Leads Market
Medical Devices
South Africa General Surgical Devices Market
Medical Devices
Ultrasound Transducers Market
Medical Devices
Transcatheter Mitral Valve Market
Medical Devices
Global Portable Oxygen Concentrators Market
Medical Devices
Flow Diverters Market
Medical Devices
Ocular Adhesive Market
Medical Devices
Gastric Bands Market
Medical Devices
Global Gynecological Dilators Market
Medical Devices
Retinal Surgery Devices Market