
 Wound Closure and Advanced Wound Care Market | 2026-2036
Wound Closure and Advanced Wound Care Market Size, Share, and Industry Trends Forecast 2026-2036
Wound Closure and Advanced Wound Care Market Intelligence
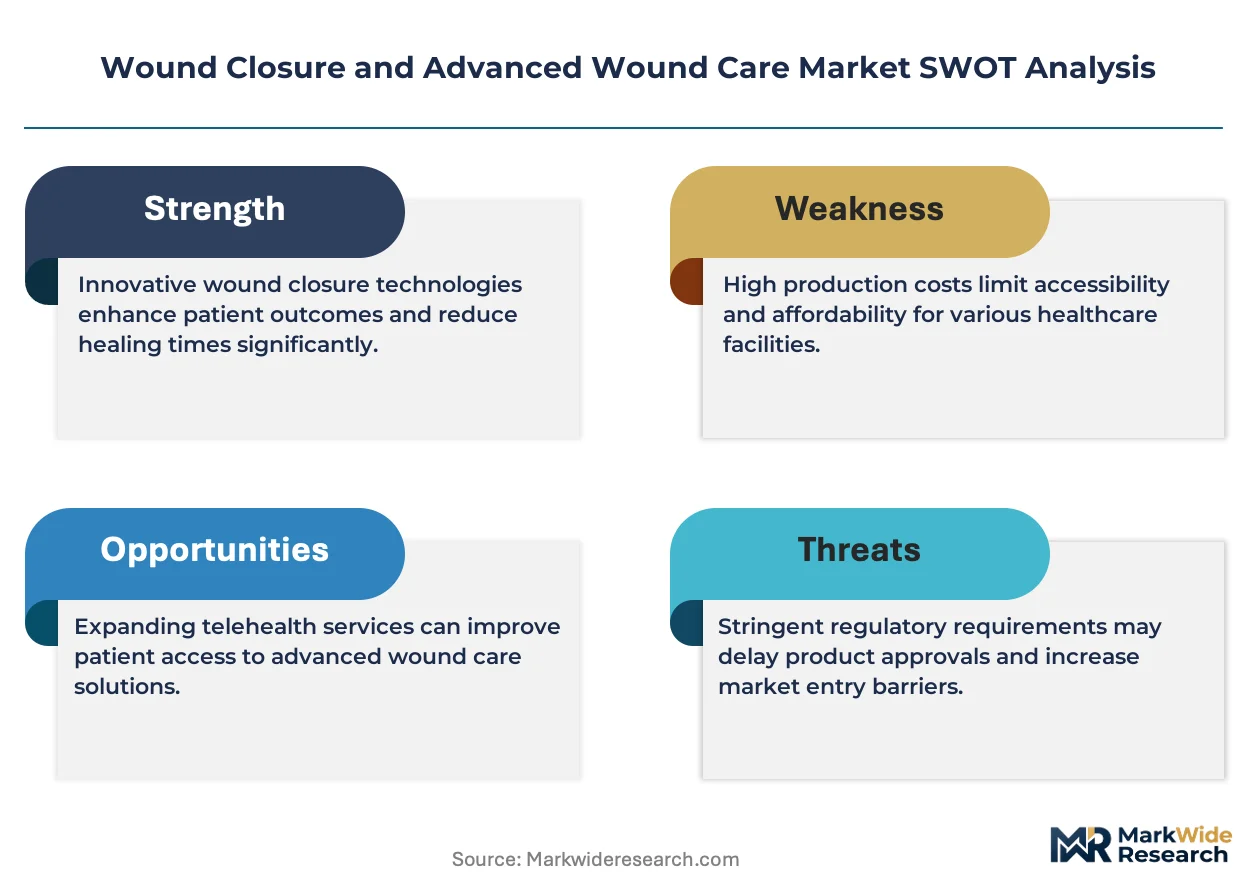
Hospital procurement is rewriting how wound care products reach end users as group purchasing organizations consolidate vendor lists and demand value-based contracting. Smith+Nephew leverages its integrated manufacturing footprint to sustain direct hospital relationships across multiple continents. Mölnlycke Health Care AB anchors its position through specialized silicone foam dressings that command premium placement in European surgical wards. ConvaTec Group PLC differentiates via its ostomy and wound portfolio breadth, competing for shelf space in integrated delivery networks.
Wound closure and advanced wound care encompasses mechanical devices, topical sealants, absorbent dressings, and active healing modalities designed to achieve hemostasis, prevent infection, and accelerate tissue regeneration through controlled moisture balance and cellular signaling. Sutures and staples retain dominant volume in surgical settings where tensile strength and cost efficiency remain paramount, while negative pressure wound therapy systems capture concentrated margin pools in chronic and traumatic wound management. Bioengineered materials represent the fastest-expanding technology dimension as collagen matrices and skin substitutes displace traditional dressings in diabetic foot ulcer and burn care protocols.
The FDA enforces 510(k) and PMA pathways for novel wound devices, while the EU MDR reclassifies absorbable sutures and active dressings under stricter clinical evidence requirements that reshape product development timelines. Health technology assessment bodies in Germany and Japan increasingly condition reimbursement on demonstrated healing outcomes, forcing manufacturers to generate real-world evidence. Stakeholders must monitor how regulatory divergence between FDA and EU MDR trajectories affects portfolio prioritization and clinical trial investment decisions.
Market Dynamics
Hospital procurement consolidation is compressing vendor margins and forcing manufacturers to prove clinical-economic value through real-world healing data rather than unit pricing alone.
Growth Catalysts
- EU MDR Reclassification:Stricter clinical evidence requirements for absorbable sutures and active dressings are accelerating R&D investment in bioengineered alternatives that demonstrate superior healing trajectories.
- Diabetes Prevalence:Rising diabetic foot ulcer burdens in the United States, Germany, and Japan are concentrating demand for advanced moisture-balancing dressings and negative pressure systems in tertiary wound centers.
- Silicone Foam Technology:Specialized silicone-adhesive dressings are commanding premium placement in European surgical wards by reducing tissue trauma during dressing changes.
Market Restraints
- Raw Material Concentration:Medical-grade collagen and hyaluronic acid supply concentrates among a handful of European and North American bioprocessing suppliers, exposing manufacturers to input volatility.
- FDA 510(k) Pathway Friction:Novel bioengineered skin substitutes face extended review timelines when predicate devices lack comparable cellular signaling mechanisms, delaying commercialization.
- Traditional Dressing Substitution:Low-cost hydrocolloid and alginate dressings retain volume in price-sensitive emerging markets, limiting premium product penetration.
Strategic Opportunities
- Home Care Channel Expansion:Post-acute protocols in the United States are shifting advanced dressing administration to home settings, creating demand for simplified negative pressure systems.
- Japan's PMDA Streamlining:Regulatory harmonization initiatives for regenerative medicine products are reducing approval timelines for collagen matrices in burn and ulcer applications.
- Digital Wound Monitoring Convergence:Integration of smartphone-based wound measurement apps with dressing systems is enabling remote healing tracking and reimbursement justification.
Industry Challenges
- Biofabrication Talent Scarcity:Tissue engineering and 3D bioprinting expertise concentrates in academic medical centers, constraining commercial-scale manufacturing workforce development.
- EU MDR Technical Documentation:Legacy product portfolios require extensive clinical evidence regeneration to maintain CE marking, straining regulatory affairs capacity.
- Health System EMR Integration:Wound care documentation tools lack standardized interoperability with hospital electronic medical record systems, complicating outcome data capture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wound Closure and Advanced Wound Care Market |
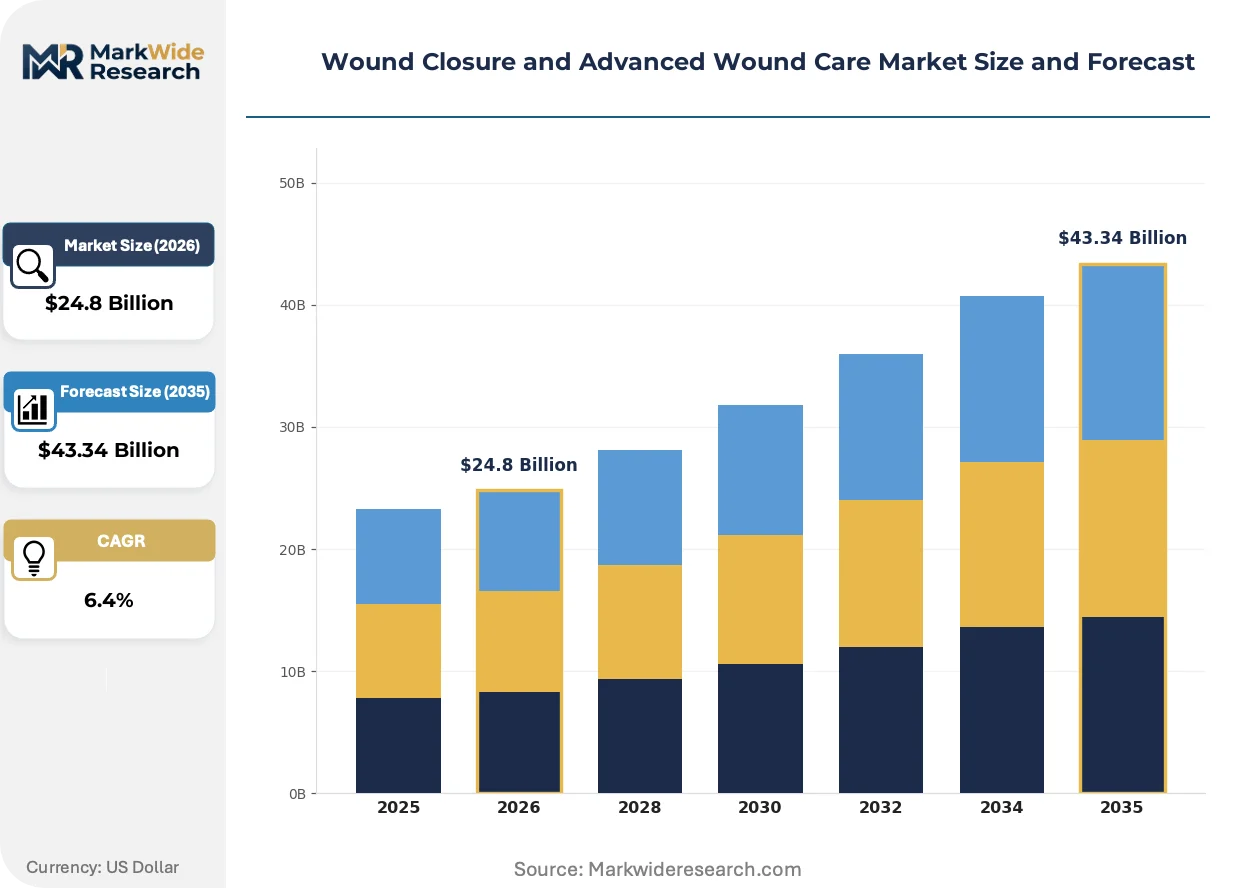
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $43.34 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sutures, Staples, Adhesives, Dressings Application: Surgical Wounds, Traumatic Wounds, Chronic Wounds, Burn Care End User: Hospitals, Clinics, Home Care, Urgent Care Centers Technology: Traditional Techniques, Bioengineered Materials, Advanced Dressings, Negative Pressure Wound Therapy |
| Companies Covered | Smith+Nephew, Mölnlycke Health Care AB, ConvaTec Group PLC, Solventum, 3M, Medline Industries, B. Braun, Johnson & Johnson, Coloplast Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wound Closure and Advanced Wound Care Market Strategic Shifts & Innovations
Digital wound assessment tools and bioactive material platforms are converging to create closed-loop healing systems that adjust therapy based on real-time tissue response data.
Smart dressing technology incorporating pH-responsive indicators and wireless moisture sensors is virtualizing traditional wound assessment workflows. Acute care facilities in Germany are piloting these systems to reduce nursing documentation burden. The technology is virtualizing scheduled dressing changes into event-driven interventions that trigger only when microenvironment thresholds breach.
The EU MDR's enhanced clinical evidence requirements for absorbable wound closure devices are extending product development timelines by 18-36 months for novel submissions. Manufacturers are responding by prioritizing predicate device strategies and real-world evidence collection through post-market surveillance. Surgical suture suppliers face the steepest compliance burden as reclassification elevates technical documentation standards.
Hospital group purchasing organizations are consolidating vendor lists around value-based contracting frameworks that tie reimbursement to demonstrated healing outcomes. Integrated delivery networks in the United States are replacing transactional purchasing with multi-year partnerships requiring manufacturers to assume outcome risk. This concentration is most visible in metropolitan health systems where procurement departments now mandate healing-rate guarantees for chronic wound contracts.
Wound Closure and Advanced Wound Care Market Segmentation
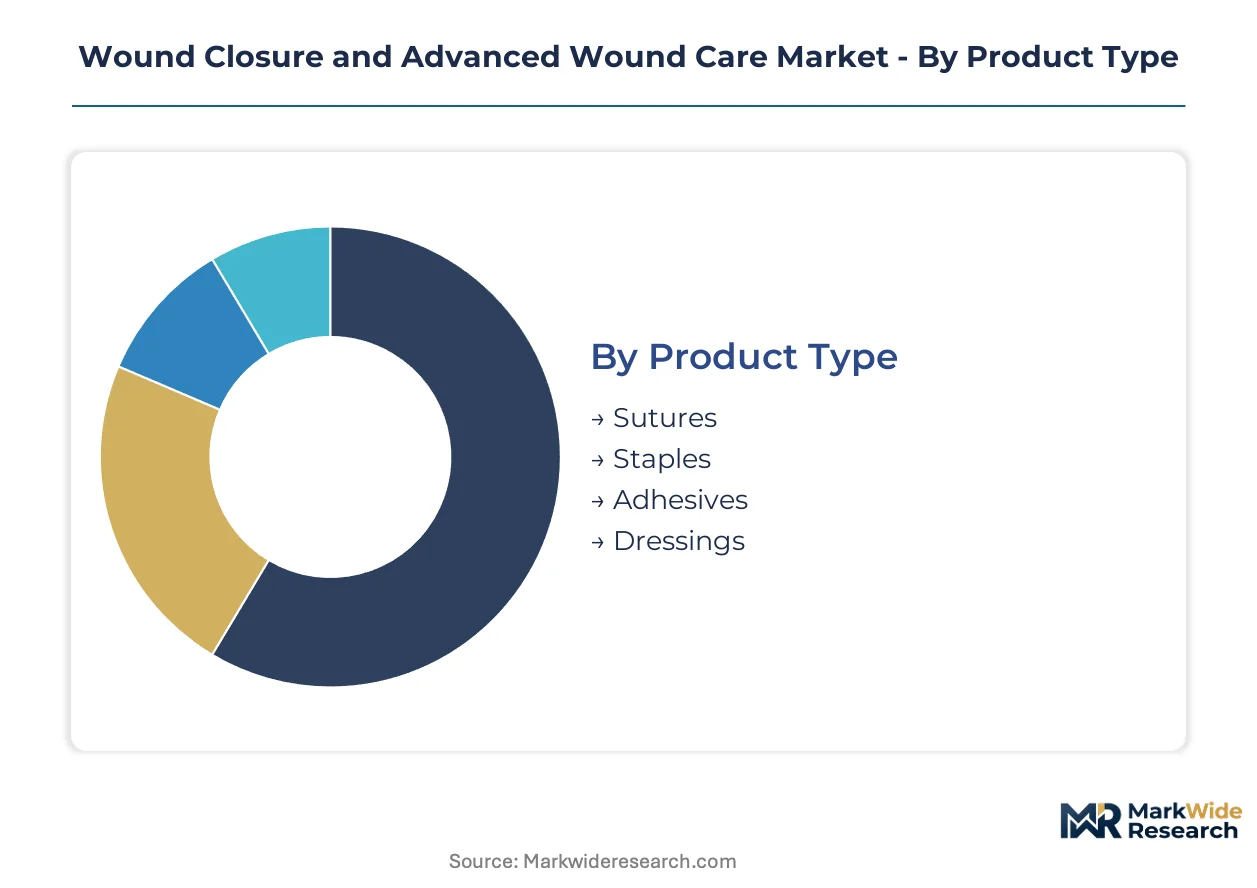
Wound closure and advanced wound care segmentation reveals divergent replenishment cycles across product categories. Sutures and staples turn rapidly in high-volume surgical settings while bioengineered skin substitutes require extended clinical validation before repeat procurement.
Product Type:
Cycle times range from weekly replenishment for consumable dressings to multi-year intervals for capital-intensive negative pressure systems, reshaping inventory management across supply tiers.
- Sutures:Absorbable and non-absorbable filament configurations dominate surgical volume. Demand concentrates in United States tertiary centers where robotic-assisted procedures require specialized barbed configurations.
- Staples:Stainless steel and titanium skin closure devices deliver rapid intraoperative efficiency. German ambulatory surgical centers favor disposable staplers with integrated cartridge systems for cost containment.
- Adhesives:Cyanoacrylate-based topical sealants reduce needlestick exposure in pediatric and cosmetic applications.
- Dressings:Alginate, hydrocolloid, and foam variants manage exudate across wound healing phases.
Sutures dominate installed base. Bioengineered alternatives are where expansion concentrates.
Application:
Cost tiers separate commodity trauma management from premium chronic wound protocols where reimbursement justifies advanced material investment.
- Surgical Wounds:Elective and emergency procedure closures demand predictable tensile strength profiles. Japanese university hospitals drive adoption of antimicrobial-coated sutures in orthopedic and cardiac specialties.
- Chronic Wounds:Diabetic foot ulcers and venous leg ulcers require moisture-balanced environments over extended durations. United States wound care centers prioritize negative pressure systems for pressure injury protocols.
- Traumatic Wounds:Emergency department closures balance speed against cosmetic outcomes in laceration repair.
- Burn Care:Partial and full-thickness thermal injuries necessitate biological coverage during autograft maturation.
Surgical wounds anchor volume throughput. Chronic wounds represent the steepest expansion trajectory.
End User:
Customer type determines purchasing authority, with integrated delivery networks consolidating hospital procurement while home care channels fragment toward direct-to-patient distribution.
- Hospitals:Inpatient surgical suites and intensive care units drive bulk suture and staple consumption. Group purchasing organizations in the United States extract volume discounts through multi-year commitment structures.
- Home Care:Post-acute dressing changes and negative pressure system management shift to residential settings. Medicare reimbursement expansion in the United States accelerates simplified device designs for non-clinical operators.
- Clinics:Outpatient wound centers handle debridement and dressing changes without admission overhead.
- Urgent Care Centers:Retail-adjacent facilities manage laceration closure with limited sterile processing capacity.
Hospitals retain procurement leverage. Home care is gaining share fastest.
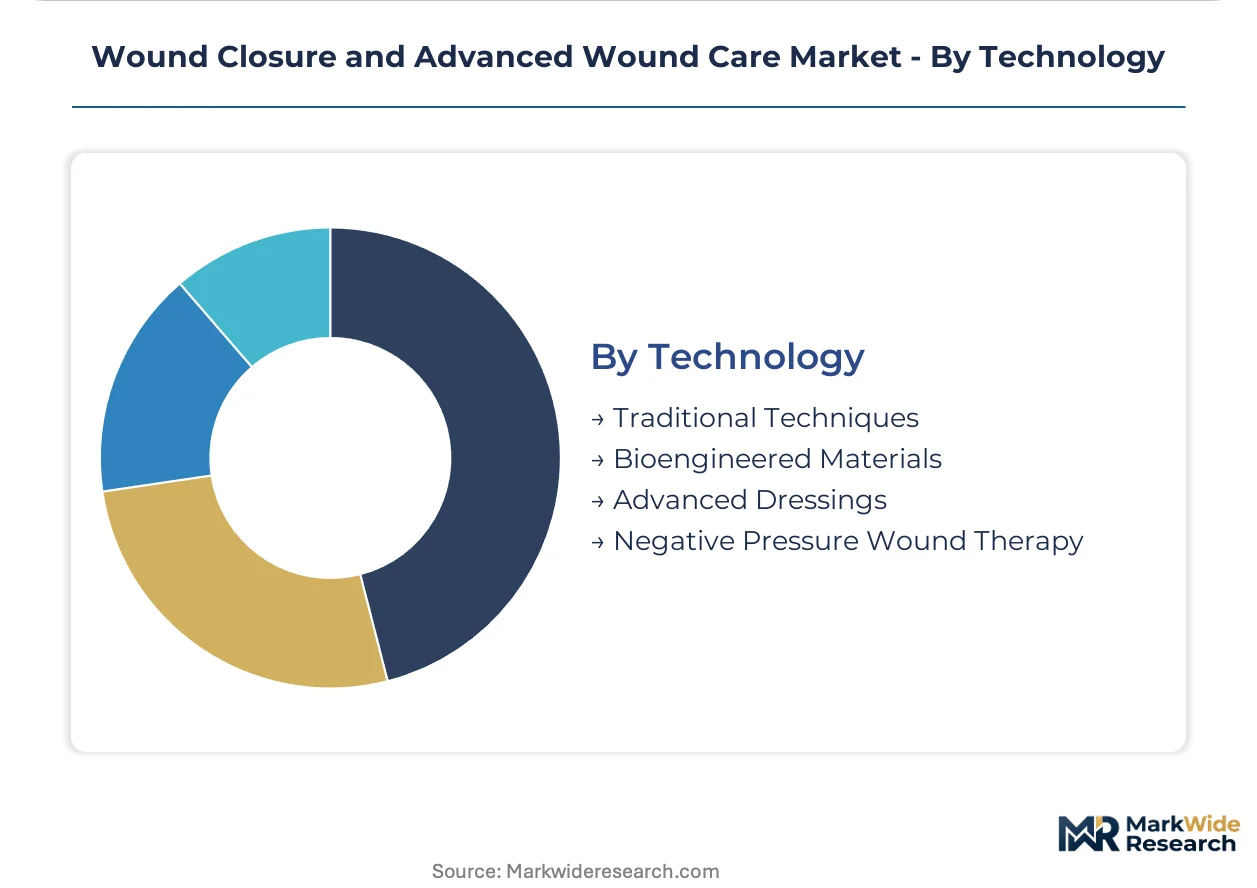
Technology:
Supply concentration varies sharply, with traditional techniques commoditized across multiple manufacturers while biofabrication capabilities cluster in specialized facilities.
- Traditional Techniques:Mechanical closure with sutures, staples, and standard gauze maintains cost advantage in price-sensitive markets. Indian and Brazilian public health systems rely on these modalities for trauma volume.
- Negative Pressure Wound Therapy:Vacuum-assisted closure systems generate concentrated margin pools in chronic wound management. German reimbursement frameworks favor portable devices enabling outpatient therapy continuation.
- Advanced Dressings:Silver-impregnated and silicone-adhesive platforms reduce dressing change trauma.
- Bioengineered Materials:Acellular dermal matrices and living skin substitutes command premium positioning. Japan's PMDA streamlining for regenerative medicine accelerates collagen matrix approvals in burn applications.
Traditional techniques saturate volume base. Bioengineered materials are where technology investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany's surgical wards exceeds that in India's public hospitals by a substantial margin, reflecting divergent reimbursement frameworks and procurement sophistication. Japan commands premium positioning for regenerative medicine products through streamlined regulatory pathways. The United States concentrates volume throughput across integrated delivery networks that extract outcome-based commitments from suppliers.
United States
Diabetic foot ulcer prevalence and Medicare reimbursement expansion for home-based negative pressure systems concentrate demand in tertiary wound centers and residential settings. The FDA enforces 510(k) and PMA pathways that extend review timelines for bioengineered skin substitutes lacking comparable predicates. Minneapolis-St. Paul anchors a cluster of medical device manufacturers serving integrated delivery networks with value-based contracting requirements.
Germany
Health technology assessment bodies condition reimbursement on demonstrated healing outcomes, forcing manufacturers to generate real-world evidence for advanced dressings. The EU MDR reclassifies absorbable sutures and active dressings under stricter clinical evidence requirements that reshape product development timelines. The Rhine-Ruhr metropolitan region hosts specialized silicone foam dressing production facilities supplying European surgical wards with premium placement products.
Japan
Aging demographics and burn care protocol sophistication elevate demand for collagen matrices and living skin substitutes in university hospital settings. PMDA streamlining initiatives for regenerative medicine products reduce approval timelines for bioengineered materials in ulcer and thermal injury applications. The Kanto region around Tokyo concentrates medical device distribution infrastructure serving orthopedic and cardiac specialties with antimicrobial-coated suture configurations.
India
Price-sensitive public health systems rely on traditional mechanical closure techniques for trauma volume, limiting premium product penetration. CDSCO regulates medical device imports and domestic manufacturing under escalating biocompatibility documentation requirements. Maharashtra's Mumbai-Pune corridor hosts contract manufacturing facilities serving multinational wound care suppliers with cost-competitive suture and staple production.
United Kingdom
NHS procurement consolidation through regional purchasing collaboratives compresses vendor margins and demands clinical-economic value demonstration. MHRA post-Brexit regulatory divergence from EU MDR creates parallel compliance obligations for wound closure device suppliers. The East Midlands cluster around Leicester concentrates wound dressing distribution logistics serving acute trusts and community nursing services.
Wound Closure and Advanced Wound Care Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in the supply chain, supplying medical-grade collagen and hyaluronic acid to finished goods manufacturers. The vendor base organizes into three tiers: multinational conglomerates with diversified healthcare portfolios, mid-cap specialists focused on wound care verticals, and regional contract manufacturers serving price-sensitive markets. Two strategic archetypes dominate: integrated manufacturers sustaining direct hospital relationships across continents, and focused players anchoring positions through specialized adhesive or foam technologies. Competitive moves concentrate on M&A for biofabrication capabilities and strategic partnerships for digital wound monitoring integration.
Within the integrated manufacturer tier, Smith+Nephew and Mölnlycke Health Care AB exemplify platform breadth spanning sutures, advanced dressings, and negative pressure systems. ConvaTec Group PLC occupies a position representing portfolio diversification across ostomy and wound care segments. These three entities anchor the competitive structure through distinct geographic and technological positioning rather than overlapping strategic postures.
| Leading Market Players |
|---|
| Smith+Nephew |
| Mölnlycke Health Care AB |
| ConvaTec Group PLC |
| Solventum |
| 3M |
| Medline Industries |
| B. Braun |
| Johnson & Johnson |
| Coloplast Group |
| Others |
Cost & Logistics Intelligence
Single-source dependency on European medical-grade collagen suppliers exposes manufacturers to input volatility that simultaneously widens premium-economy pricing spreads and forces geographic diversification in bioprocessing capacity. This concentration dynamic compresses margins for mid-tier producers while rewarding integrated manufacturers with captive supply relationships.
Pricing Analysis
The customization-premium spread separates configured-to-order bioengineered skin substitutes from standard hydrocolloid and alginate dressings. Pricing stratifies across premium, standard, and economy tiers driven by certification grade (FDA PMA vs. 510(k) vs. unregulated) and volume scale through GPO contracts. Cost compression in the economy tier intensifies as Indian and Brazilian public health systems consolidate procurement around basic mechanical closure. Hospital group purchasing organizations demonstrate the least price sensitivity for antimicrobial-coated sutures in robotic-assisted surgery, while home care channels fragment toward direct-to-patient distribution with heightened cost consciousness.
Supply Chain Analysis
Upstream feedstock concentration in medical-grade collagen and hyaluronic acid centers on bioprocessing facilities in the United States, Germany, and Switzerland. Raw material dependencies span porcine and bovine tissue sourcing, recombinant protein production, and specialized foam substrate manufacturing. Single-source vulnerability in pharmaceutical-grade sodium alginate from specific coastal harvesting regions creates chokepoint exposure. Distribution runs through tiered medical device distributors serving hospital systems, integrated delivery networks, and expanding home care channels with divergent service requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wound closure and advanced wound care market represents an early-cycle expansion story as bioengineered materials displace traditional dressings in diabetic foot ulcer protocols and post-acute settings accelerate adoption.
For Market Incumbents: Build switching-cost moats through EMR-integrated wound documentation platforms that capture outcome data required for value-based contracting. Consolidate position by acquiring biofabrication capabilities in the Kanto region to secure PMDA-streamlined collagen matrix approvals. Counter margin pressure from silicone foam commoditization by embedding moisture sensors into dressing systems, creating differentiated data services that transcend unit pricing. For New Entrants and Emerging Players: Establish a beachhead in Medicare-reimbursed home negative pressure systems where simplified device designs for non-clinical operators remain underpenetrated. Target white-space in smartphone-based wound measurement apps that integrate with existing dressing portfolios, avoiding capital-intensive manufacturing. Pursue regulatory arbitrage through Japan's PMDA regenerative medicine pathway for faster collagen matrix commercialization than FDA timelines permit. For Investors and Strategic Acquirers: Specialized biofabrication startups with academic medical center partnerships represent the most compelling acquisition target archetype given tissue engineering talent scarcity. Long-term viability hinges on demonstrated real-world evidence generation capabilities that satisfy German health technology assessment requirements. Watch for inflection when CMS expands reimbursement codes for digital wound monitoring, signaling home care channel maturation.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Legacy product portfolios require clinical evidence regeneration to maintain CE marking access across European surgical wards. |
| Hospital System Partnership | Integrated delivery networks in the United States mandate healing-rate guarantees for chronic wound contract eligibility. |
| Software Companion Development | Smartphone-based wound measurement apps enable remote healing tracking that satisfies Medicare reimbursement documentation requirements. |
| Reimbursement Strategy | German health technology assessment bodies condition advanced dressing coverage on demonstrated healing outcomes through real-world evidence. |
| CE Marking Pathway | EU MDR reclassification of absorbable sutures elevates clinical evidence standards that reshape product development timelines. |
Research Approach
The analysis maps sutures, advanced dressings, negative pressure systems, and bioengineered materials, each validated through wound care clinicians, hospital purchasing committees, biomedical engineers, and GPO contracts managers. Primary intelligence combines structured interviews with secondary validation against FDA 510(k) and PMA filings, EU MDR technical documentation databases, hospital procurement contracts, and CMS Medicare reimbursement codes. Bottom-up and top-down triangulation reconciles manufacturer shipment data with end-user consumption patterns across acute and post-acute settings.
The forecast framework holds regulatory pathway timelines and reimbursement expansion trajectories fixed while varying diabetes prevalence projections and home care protocol adoption rates across the analysis window. Segmentation dimensions include product type, application severity tier, end-user channel, and technology platform maturity. CAGRs derive from installed base turnover analysis and replacement cycle compression in chronic wound management. Industry-specific inputs incorporate PMDA streamlining impact on regenerative medicine approvals and EU MDR compliance cost absorption.
Macroeconomic conditions sit as an overlay; deviation in healthcare expenditure growth rates or trade policy affecting medical-grade collagen tariffs would shift the trajectory. Forecasts reflect assumptions regarding regulatory harmonization progress and GPO consolidation velocity. Cross-checking against hospital capital expenditure surveys and wound center capacity expansion announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Wound Closure Market
Wound Care
Wound Healing Supplement Market
Wound Care
Pressure Bandages Market
Wound Care
Bioadhesive Wound Care Market
Wound Care
Anti-Biofilm Wound Dressing Market
Wound Care
Saudi Arabia Wound Care Management Devices Market
Wound Care
Advanced Wound Care and Dressings Market
Wound Care
Bioactive Wound Management Market
Wound Care
Bioactive Wound Care Market
Wound Care
Global Silver Wound Dressing Market
Wound Care
Europe Compression Bandages Market
Wound Care
United States Negative Pressure Wound Therapy Market
Wound Care
Wound Care Market
Wound Care
Brazil Wound Care Management Devices Market
Wound Care
US Wound Care Centers Market
Wound Care
Venous Ulcer Treatment Market