
 Foam Dressing Market | 2026-2036
Foam Dressing Market Size, Share, and Industry Trends Forecast 2026-2036
Foam Dressing Market Intelligence
The gap between premium silicone-bordered foams and commodity polyurethane pads is recalibrating procurement behavior across health systems. Smith & Nephew plc leverages its hydrofiber-foam hybrid portfolio to anchor high-acuity hospital contracts in North America. Mölnlycke Health Care AB competes through vertically controlled manufacturing of soft silicone adhesives that reduce trauma on fragile skin. Medline Industries dominates private-label distribution, extending its reach through direct-to-facility logistics networks that bypass traditional distributor markups.
Foam dressing comprises a multilayer absorbent pad—typically polyurethane foam with a vapor-permeable film backing and optional silicone adhesive border—engineered to manage exudate while maintaining a moist wound environment conducive to granulation tissue formation. The material dimension shows polyurethane retaining volume leadership due to established conversion economics, though silicone contact layers command margin premiums in burn and pediatric applications. Antimicrobial foam variants containing silver or polyhexamethylene biguanide represent the fastest-expanding product type as clinicians seek to reduce bioburden without secondary dressings. Home care end users are gaining share as telehealth protocols and portable negative-pressure systems enable earlier discharge from acute settings.
FDA 510(k) pathways and the EU Medical Device Regulation shape product registration timelines and clinical evidence requirements for foam dressings entering commercial distribution. The EPA regulates antimicrobial claims on silver-impregnated devices, while ISO 10993 biocompatibility standards govern cytotoxicity and sensitization testing protocols. Stakeholders must monitor how CMS reimbursement adjustments for hospital-acquired pressure injuries and evolving NICE guidelines in the United Kingdom redirect purchasing toward prevention-oriented foam solutions rather than commodity interchangeables.
Market Dynamics
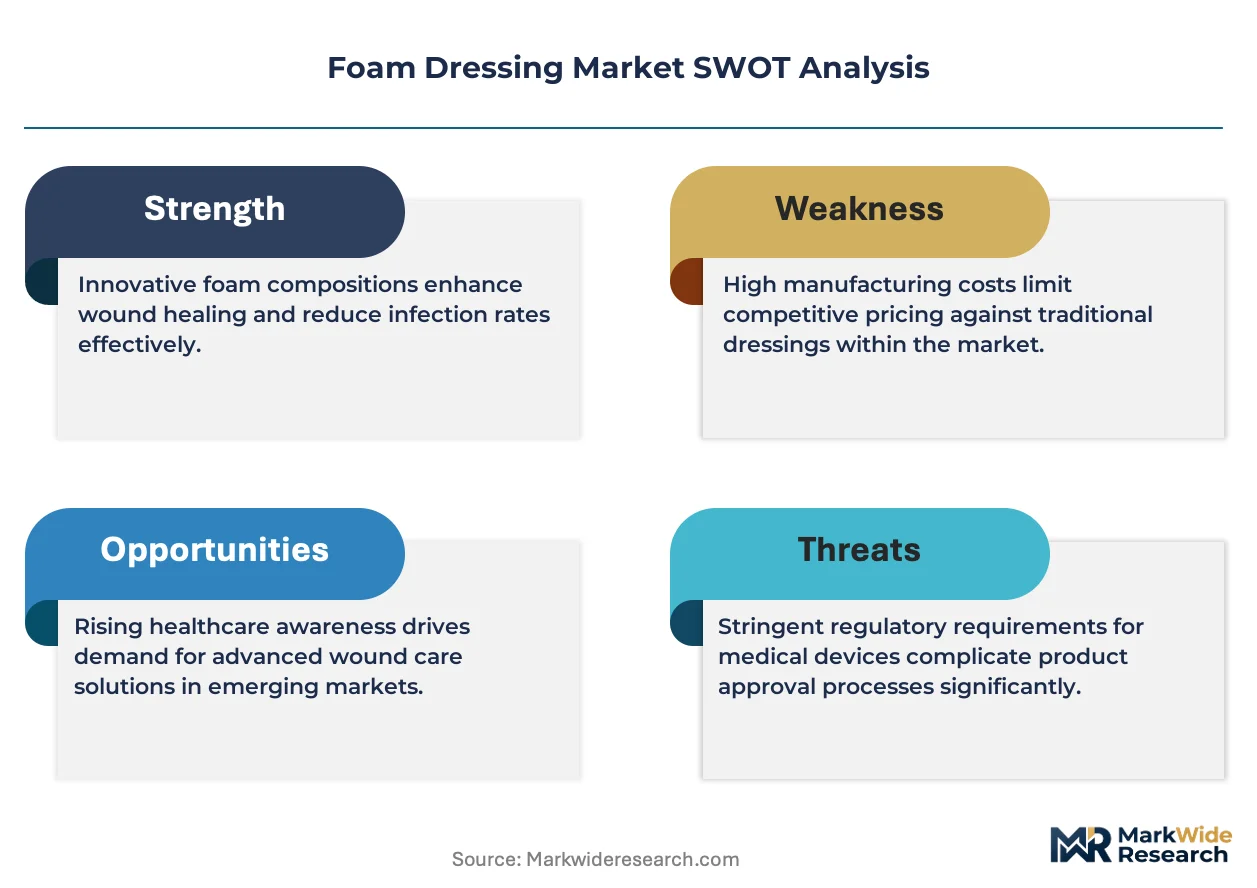
Hospital procurement departments are consolidating wound care contracts around antimicrobial foam formulations, compressing vendor margins while elevating technical specifications for silicone-bordered and silver-impregnated variants.
Growth Catalysts
- Antimicrobial foam variants:Silver and polyhexamethylene biguanide formulations address clinician demand for bioburden reduction without secondary dressings. Burn centers and pediatric wards drive uptake.
- EU Medical Device Regulation:MDR's enhanced clinical evidence requirements favor established manufacturers with robust ISO 10993 biocompatibility dossiers, accelerating hospital trust in certified suppliers.
- Home care transition:Telehealth protocols and portable negative-pressure systems enable earlier discharge from acute settings, extending foam dressing consumption into outpatient channels.
Market Restraints
- Polyurethane feedstock volatility:Crude oil derivative costs for foam substrates create margin pressure on commodity pad producers without silicone contact layer premiums.
- EPA antimicrobial claims scrutiny:Silver-impregnated device registrations face extended environmental impact review timelines, delaying product launches and freezing inventory commitments.
- Hydrocolloid substitution:Lower-cost hydrocolloid dressings capture price-sensitive chronic wound segments where exudate levels permit simpler moisture management.
Strategic Opportunities
- Germany's aged care facilities:Pressure injury prevention protocols in nursing homes create demand for high-absorbency foam with silicone adhesive borders that reduce skin trauma during removal.
- Japan's diabetic foot ulcer protocols:METI reimbursement adjustments for hospital-acquired complications redirect purchasing toward prevention-oriented foam solutions.
- Negative-pressure integration:Convergence of foam dressings with portable vacuum-assisted closure systems opens ambulatory surgical center channels previously reserved for inpatient negative-pressure devices.
Industry Challenges
- Biocompatibility testing bottlenecks:ISO 10993 cytotoxicity and sensitization validation queues at contracted laboratories extend product development cycles beyond procurement planning horizons.
- Legacy distributor relationships:Direct-to-facility logistics networks require renegotiation of exclusive territorial agreements that have structured wound care supply chains for decades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foam Dressing Market |
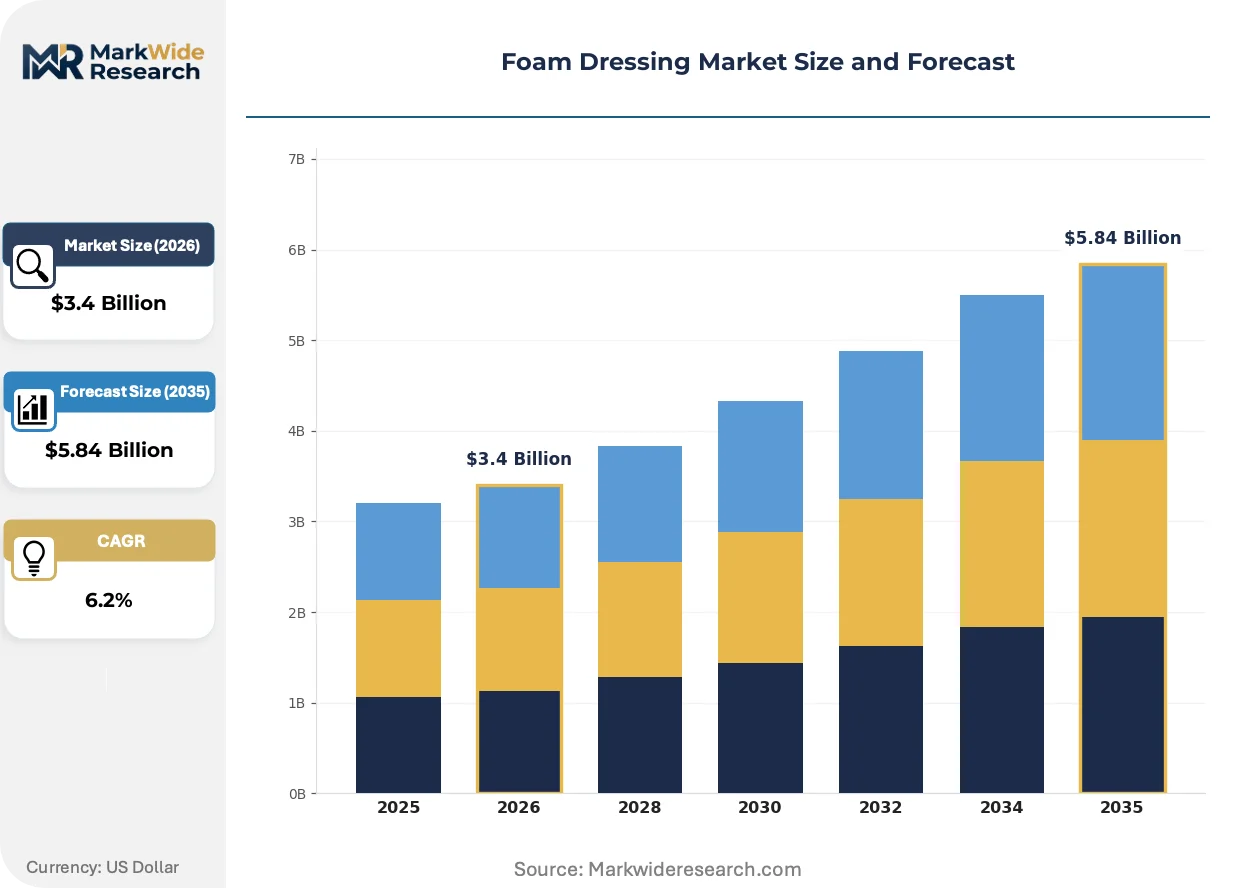
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $5.84 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrofiber, Non-Adherent, Self-Adhesive, Antimicrobial End User: Hospitals, Home Care, Long-Term Care, Clinics Application: Wound Care, Surgical Procedures, Burns Treatment, Pressure Ulcers Material: Polyurethane, Silicone, Hydrocolloid, Others |
| Companies Covered | 3M Company, Smith & Nephew plc, Coloplast Corp, Medline Industries, Cardinal Health, ConvaTec Group plc, Mölnlycke Health Care AB, B. Braun SE, Essity, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foam Dressing Market Strategic Shifts & Innovations
Material science advances and regulatory recalibration are compressing development timelines while fragmenting procurement authority across hospital supply chains and outpatient channels.
Silicone contact layer technology is expanding into pediatric and geriatric applications where fragile skin integrity demands atraumatic removal. Neonatal intensive care units and long-term care facilities in the United States and Japan are adopting soft silicone adhesive borders at accelerated rates. This migration is expanding into premium pricing tiers that commodity polyurethane pads cannot access, bifurcating the market by clinical acuity.
FDA 510(k) clearance pathways for silicone-bordered foam dressings have streamlined premarket notification requirements for predicate device comparisons. The industrial consequence is reduced clinical trial burden for incremental product modifications. Burn centers and surgical wards are responding by accelerating evaluation cycles for next-generation antimicrobial variants.
Hospital purchasing committees are unbundling wound care contracts from broad distributor agreements, creating direct manufacturer relationships for high-volume foam categories. Group purchasing organizations are losing leverage over silicone-bordered segments as clinicians specify product performance over contract compliance. This disintermediation is most visible in United States academic medical centers where value analysis committees override legacy supply contracts.
Foam Dressing Market Segmentation
Foam dressing procurement fragments across clinical acuity tiers, material specifications, and reimbursement environments. Understanding where customization commands premium pricing versus where standardization drives volume procurement reveals margin architecture across the value chain.
Product Type:
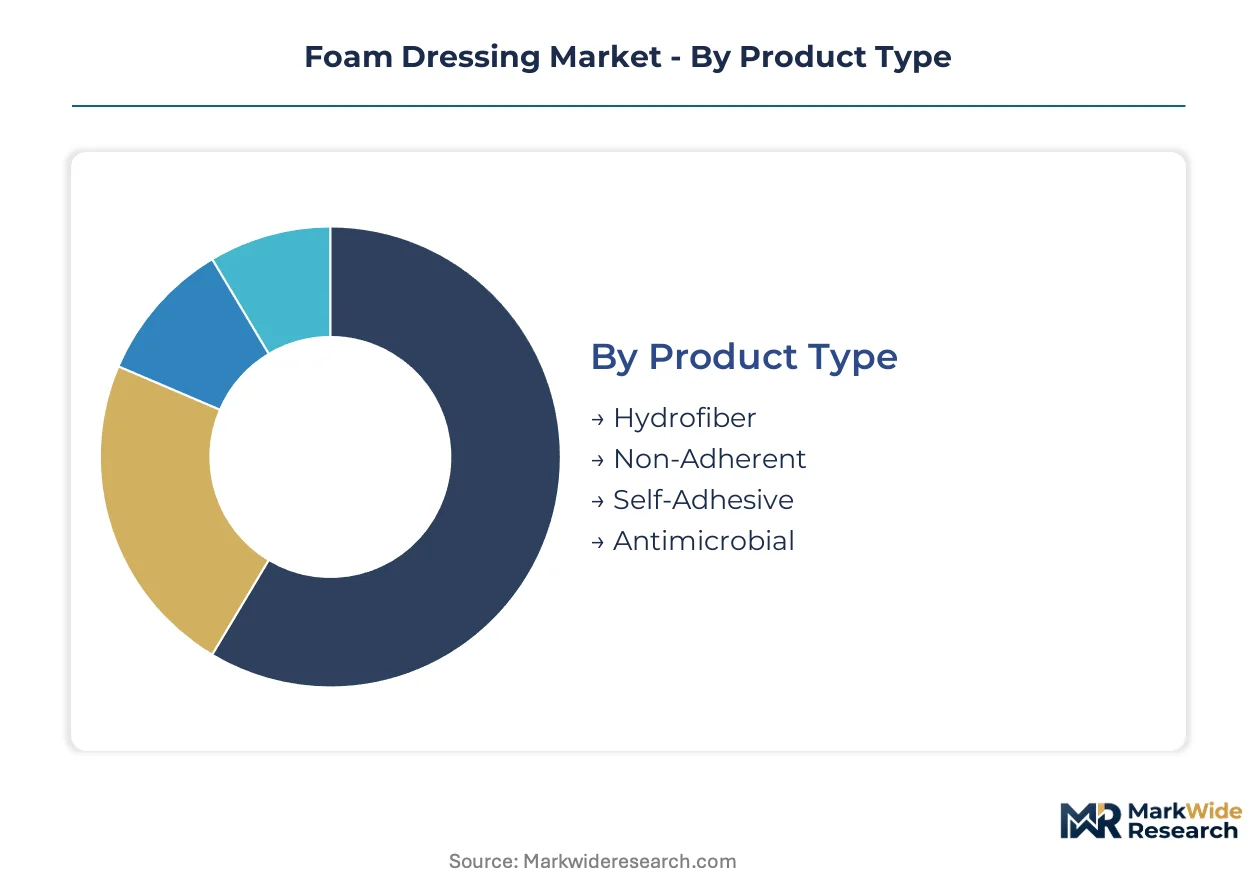
Customization intensity spans from commodity polyurethane pads to engineered hydrofiber-foam hybrids with integrated antimicrobial release kinetics.
- Antimicrobial:Silver-ion or polyhexamethylene biguanide matrices provide sustained bioburden reduction without secondary dressing changes. Burn centers in the United States and pediatric wards in Germany specify these formulations for high-exudate wounds where infection prevention outweighs material cost premiums.
- Hydrofiber:Carboxymethylcellulose-foam composites convert to cohesive gels upon contact with wound fluid, maintaining moist healing environments while locking exudate away from periwound skin. Acute care hospitals in Japan favor hydrofiber-foam hybrids for diabetic foot ulcers requiring extended wear time between changes.
- Self-Adhesive:Silicone-bordered constructions enable atraumatic removal for fragile geriatric skin in long-term care facilities.
- Non-Adherent:Open-cell polyurethane pads without adhesive layers suit secondary dressing applications where primary contact layer selection remains clinician-directed.
Leading the category by volume: Non-Adherent. Growing fastest: Antimicrobial.
End User:
Procurement authority concentrates differently across institutional buyers, with reimbursement codes dictating product specification intensity.
- Hospitals:Value analysis committees in United States academic medical centers unbundle wound care contracts from broad distributor agreements, creating direct manufacturer relationships for silicone-bordered and antimicrobial categories where clinical evidence requirements exceed commodity pad specifications.
- Home Care:Telehealth protocols and portable negative-pressure systems enable earlier discharge from acute settings, extending foam dressing consumption into channels where patient self-application demands simplified adhesive systems and longer wear intervals.
- Long-Term Care:Pressure injury prevention protocols in nursing homes create demand for high-absorbency foam with silicone borders that reduce skin trauma during removal.
- Clinics:Outpatient wound centers balance material cost against procedure throughput, often selecting mid-tier polyurethane constructions for debridement follow-up visits.
Volume leadership rests with Hospitals. Home Care channels are expanding most quickly as reimbursement shifts toward ambulatory models.
Application:
Clinical indication determines absorption capacity requirements, wear time specifications, and antimicrobial necessity.
- Pressure Ulcers:Stage III and IV presentations in aged care facilities require high-absorbency foam with vapor-permeable backings that manage exudate without macerating surrounding tissue, particularly where CMS reimbursement adjustments penalize hospital-acquired conditions.
- Burns Treatment:Partial-thickness thermal injuries in specialized centers demand non-adherent contact layers that permit pain-free dressing changes without disrupting delicate epithelialization, with silver-impregnated variants addressing colonization risk in contaminated wounds.
- Wound Care:Chronic venous leg ulcers and diabetic foot wounds in community settings drive consumption of standard polyurethane foam with moderate absorbency profiles.
- Surgical Procedures:Postoperative incisions with low-to-moderate drainage utilize thin-profile foam as secondary dressings over primary closure strips.
Wound Care generates the highest shipment volumes. Burns Treatment commands the steepest expansion trajectory as specialized center capacity expands.
Material:
Substrate selection governs conversion economics, biocompatibility testing burden, and pricing tier access.
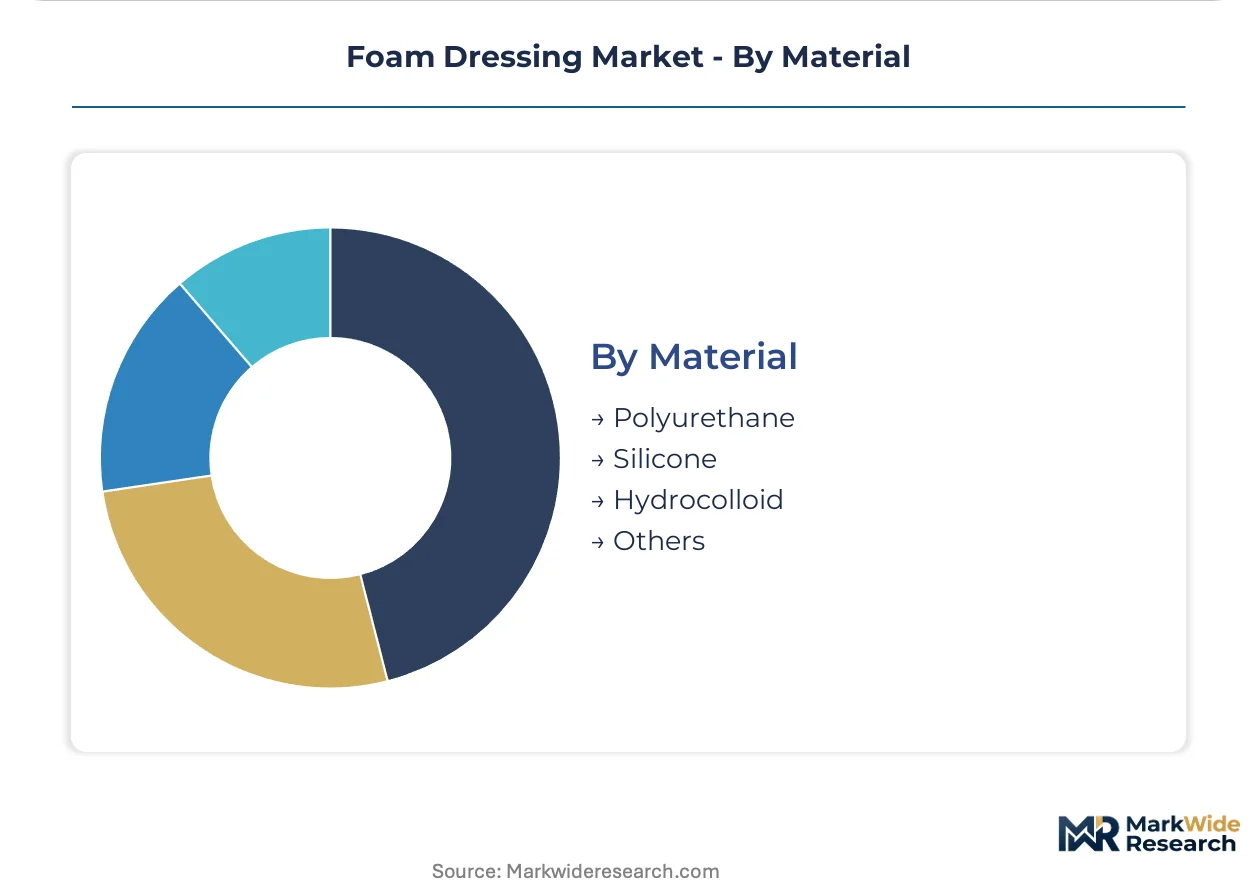
- Polyurethane:Open-cell ether or ester formulations dominate production volumes due to established foam conversion infrastructure, with vapor-permeable film backings added through thermal lamination processes that scale efficiently across high-volume contract manufacturers.
- Silicone:Soft-gel adhesive contact layers command margin premiums in pediatric and geriatric applications where fragile skin integrity demands atraumatic removal, with FDA 510(k) pathways streamlining predicate device comparisons for incremental product modifications.
- Hydrocolloid:Gel-forming particles integrated with foam substrates create hybrid constructions for moderate-exudate environments where moisture donation benefits autolytic debridement.
- Others:Alginates and carboxymethylcellulose variants occupy niche positions where specific ionic interactions with wound fluid provide therapeutic advantages.
Polyurethane retains volume leadership. Silicone contact layers are gaining share fastest as fragile-skin applications multiply across aging populations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Memphis anchors North American wound care manufacturing through Medline Industries' distribution infrastructure, while advanced wound care R&D concentrates in European medical technology clusters and Japanese precision manufacturing corridors.
United States
Diabetic foot ulcer prevalence and hospital-acquired pressure injury penalties sustain clinical volume across academic medical centers. FDA 510(k) pathways streamline silicone-bordered dressing approvals, compressing development timelines for predicate device comparisons. Texas and Illinois host major distribution hubs serving integrated delivery networks that unbundle wound care contracts from legacy distributor agreements.
Germany
Aged care facilities and nursing home pressure injury prevention protocols drive demand for high-absorbency silicone-bordered constructions. EU Medical Device Regulation clinical evidence requirements favor established manufacturers with robust ISO 10993 biocompatibility dossiers. Baden-Württemberg medical technology clusters concentrate soft silicone adhesive engineering expertise serving geriatric wound care applications.
Japan
Super-aging demographics and diabetic foot ulcer protocols sustain premium foam dressing consumption in acute and long-term care settings. METI reimbursement adjustments for hospital-acquired complications redirect purchasing toward prevention-oriented solutions. Osaka-based manufacturing corridors specialize in precision silicone contact layer production for fragile-skin applications.
United Kingdom
NICE guideline evolution redirects NHS procurement toward antimicrobial foam variants for high-exudate wound management. Community nursing services and outpatient wound centers expand home care dressing consumption through telehealth-enabled discharge protocols. Greater Manchester and West Midlands host distribution infrastructure serving integrated care systems.
China
Expanding hospital infrastructure and chronic wound prevalence create volume demand for standard polyurethane foam constructions. NMPA medical device registration pathways govern commercial distribution timelines and clinical evidence requirements. Yangtze River Delta manufacturing zones concentrate foam substrate conversion capacity serving domestic and export markets.
Foam Dressing Market Key Industry Players
Premium-margin players sit above commodity-margin players across silicone adhesive and antimicrobial formulation tiers, with hospital procurement consolidation compressing mid-tier vendor positions. The vendor base spans multinational medical technology conglomerates, regional wound care specialists, and private-label distributors. Three archetypes dominate: vertically integrated adhesive technology owners, direct-to-facility logistics operators, and hydrofiber-foam hybrid innovators. Capacity expansion and strategic portfolio diversification constitute the dominant competitive moves as procurement authority fragments across health systems.
Within the premium-tier vector, Smith & Nephew plc and Mölnlycke Health Care AB occupy positions anchored by proprietary soft silicone adhesive technologies and vertically controlled manufacturing. Medline Industries exemplifies the direct-distribution archetype, leveraging Memphis-based logistics infrastructure to bypass traditional distributor markups. These three entities represent distinct strategic postures: technology-led premium positioning, manufacturing integration, and supply chain disintermediation.
| Leading Market Players |
|---|
| 3M Company |
| Smith & Nephew plc |
| Coloplast Corp |
| Medline Industries |
| Cardinal Health |
| ConvaTec Group plc |
| Mölnlycke Health Care AB |
| B. Braun SE |
| Essity |
| Others |
Cost & Logistics Intelligence
Polyurethane feedstock costs cascade through foam dressing manufacturing, with ether and ester formulations from crude oil derivatives setting baseline economics for commodity pads while silicone contact layer premiums insulate high-acuity tiers from raw material volatility. This input-cost architecture bifurcates procurement behavior: hospital value analysis committees absorb silicone-bordered premiums for fragile-skin applications, while long-term care facilities negotiate volume contracts on standard polyurethane constructions where absorption capacity alone determines clinical suitability.
Pricing Analysis
Value-based pricing anchored to pressure injury prevention outcomes commands premium positioning in United States academic medical centers where CMS reimbursement penalties for hospital-acquired conditions create cost-of-non-compliance calculations. Three-tier pricing structure across premium silicone-bordered, mid-tier antimicrobial, and economy non-adherent levels stratifies by clinical acuity and wear-time performance. Price differentiation rests on ISO 10993 biocompatibility certification tier and silicone adhesive engineering complexity. Cost compression in commodity polyurethane tiers intensifies as private-label distributors bypass traditional markups, while antimicrobial variants with silver-ion matrices maintain pricing power through EPA registration barriers.
Supply Chain Analysis
Dual-sourcing requirements from United States integrated delivery networks and German hospital procurement departments mandate multi-supplier qualification for silicone adhesive contact layers, forcing manufacturers to qualify secondary foam conversion partners. Geographic supply concentration centers on China for polyurethane substrate production, Germany for soft silicone adhesive engineering, and the United States for Memphis-based distribution infrastructure. Raw material dependencies draw from crude oil derivatives for foam substrates, medical-grade silicone polymers for adhesive layers, and silver nanoparticles for antimicrobial matrices. Single-source vulnerability in silicone polymer supply creates exposure to specialty chemical production constraints. Distribution runs through direct-to-facility logistics networks that disintermediate legacy distributor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Medical Device Regulation's enhanced clinical evidence requirements function as a cost-of-compliance moat, elevating ISO 10993 biocompatibility dossiers from documentation burden to competitive barrier that freezes out undercapitalized entrants.
For Market Incumbents: Anchor market position through backward integration into soft silicone adhesive manufacturing and captive supply of antimicrobial silver-ion matrices. Hospital procurement consolidation threatens margin compression for non-differentiated polyurethane pads; defend through exclusive contracts with academic medical center value analysis committees that prioritize clinical evidence over unit cost. Capacity addition in Baden-Württemberg medical technology clusters secures proximity to German aged care demand. For New Entrants and Emerging Players: Antimicrobial foam formulations with polyhexamethylene biguanide matrices offer technology-first wedge into pediatric and burn center segments where infection prevention protocols override incumbent brand loyalty. Home care channels present the most penetrable geography as telehealth protocols extend dressing consumption beyond hospital discharge. Go-to-market through portable negative-pressure system OEM partnerships embeds foam dressings into device ecosystems. For Investors and Strategic Acquirers: FDA 510(k) clearance streamlining for silicone-bordered predicate devices is the leading indicator that development timeline compression will favor agile mid-cap specialists over conglomerate R&D bureaucracies. Long-term viability over the projection horizon rests on regulatory dossier depth rather than manufacturing scale alone. Acquisition target archetype: vertically controlled silicone adhesive technology owners with existing ISO 10993 validation. Watch for EPA antimicrobial claims review acceleration as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 10993 Biocompatibility Dossier Expansion | EU MDR compliance accelerates hospital trust in certified suppliers against undercapitalized competitors. |
| Silicone Adhesive Backward Integration | Captive supply of soft-gel contact layers secures margin premiums in pediatric and geriatric applications. |
| Direct-to-Facility Logistics Buildout | Memphis-based distribution infrastructure bypasses distributor markups in United States academic medical centers. |
| Antimicrobial Silver-Ion Formulation R&D | EPA registration barriers create sustainable differentiation in burn center and high-exudate wound segments. |
| Home Care Channel Partnership Development | Telehealth protocol integration extends foam dressing consumption into outpatient reimbursement environments. |
Research Approach
Hospital procurement databases, GPO contract filings, and FDA 510(k) clearance records formed the secondary backbone, supplemented by CMS Medicare reimbursement data and EU MDR notified body guidance documents. Primary interviews with hospital purchasing committee chairs, wound care clinicians, biomedical engineers, and GPO contracts managers validated demand assumptions and pricing tier boundaries. Bottom-up and top-down triangulation reconciled unit shipment estimates with value analysis committee budget allocations across United States, German, and Japanese acute care settings.
Bottom-up modeling anchored forecast outputs to procedure volume projections for diabetic foot ulcers, pressure injuries, and burn admissions across the analysis window. Segmentation dimensions spanned product type tier, end-user procurement authority, clinical application acuity, and material substrate specification. CAGRs derived from hospital admission trend extrapolation, reimbursement code evolution, and antimicrobial formulation adoption curves. Industry-specific inputs included METI reimbursement adjustment timelines and NICE guideline revision cycles.
Several conditions sit outside the modeled scope, including raw material price shock scenarios, abrupt EPA antimicrobial claims suspension, and pandemic-era hospital capacity disruptions. Forecasts reflect assumptions about regulatory pathway stability and silicone polymer supply continuity. Deviation in EU MDR enforcement intensity or FDA 510(k) predicate device comparability standards would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
LAMEA Surgical Dressing Market
Wound Care
Wound Closure Devices Market
Wound Care
Brazil Wound Care Management Devices Market
Wound Care
Surgical Dressing Market
Wound Care
Wound Care Market
Wound Care
Anti-Biofilm Wound Dressing Market
Wound Care
Global Antimicrobial Dressings Market
Wound Care
Advanced Wound Care Management Market
Wound Care
Wound Drainage Devices Market
Wound Care
Gauze Bandage Rolls Market
Wound Care
Wound Healing Supplement Market
Wound Care
Wound Care Sealants Market
Wound Care
Moist Wound Dressings Market
Wound Care
Italy Wound Care Market
Wound Care
Enzymatic Wound Debridement Market
Wound Care
Europe Advanced Wound Care Market