
 Wound Closure Devices Market | 2026-2036
Wound Closure Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Wound Closure Devices Market Outlook
A shortage of specialized surgical nurses is reorganizing how wound closure training and device selection occur across hospital systems. Ethicon leverages its broad sutures portfolio to sustain dominance in operating room supply chains. Medtronic anchors its position through advanced energy-based closure platforms that reduce operative time. Baxter differentiates via hemostasis-integrated closure systems that control bleeding during complex procedures.
Wound closure devices encompass mechanical, adhesive, and energy-based instruments designed to approximate tissue edges and promote healing, typically utilizing polymers, metals, or biological matrices with specified tensile strength and absorption profiles. Their primary commercial purpose is to replace or supplement traditional needle-and-thread techniques across minimally invasive and open surgical settings. Sutures retain the largest revenue share due to universal applicability across surgical disciplines, while adhesive devices represent the fastest-expanding segment as laparoscopic and cosmetic procedures demand scar-minimizing alternatives. Absorbable materials command premium positioning in internal closures where suture removal risks tissue trauma, whereas non-absorbable variants dominate orthopedic and cardiovascular applications requiring long-term mechanical support.
FDA 510(k) clearance pathways and EMA Medical Device Regulation compliance determine market access timelines and clinical evidence requirements for new closure technologies. ISO 10993 biocompatibility testing and ASTM tensile standards shape material selection and manufacturing protocols across the supplier base. Stakeholders must monitor how evolving reimbursement codes for outpatient surgical procedures redistribute volume between hospitals and ambulatory surgical centers, as site-of-care shifts directly alter product form factor and pricing requirements.
Market Dynamics
Site-of-care migration from inpatient hospitals to ambulatory surgical centers is compressing device form factors and forcing manufacturers to redesign sterilization protocols and packaging for non-traditional settings.
Growth Catalysts
- EMA Medical Device Regulation:Harmonized clinical evidence standards are accelerating cross-border approvals for advanced absorbable polymers in European markets.
- Laparoscopic surgery expansion:Minimally invasive procedural volumes in United States ambulatory centers are driving demand for specialized articulating staplers and clip appliers.
- Polyglycolic acid-lactide copolymers:Next-generation synthetic matrices with tunable degradation profiles are penetrating internal soft-tissue closures previously dominated by permanent sutures.
Market Restraints
- Polymer feedstock volatility:Caprolactone and glycolide monomer prices fluctuate with crude oil derivatives, squeezing margins for absorbable device manufacturers.
- Single-source sterilization capacity:Gamma irradiation services concentrate in Germany and United States facilities, creating geographic supply vulnerability.
- FDA 510(k) predicate limitations:Novel energy-based closure platforms face extended review timelines when no substantially equivalent devices exist in the database.
Strategic Opportunities
- Japan's super-aging cohort:Chronic wound management in rural prefectures remains underserved by advanced negative-pressure closure systems.
- Bioresorbable magnesium alloys:Convergence of metallurgy and polymer science enables temporary orthopedic fixation devices that eliminate secondary removal surgeries.
- India's PLI scheme for medical devices:Domestic manufacturing incentives are opening import-substitution pathways for suture and mesh producers.
Industry Challenges
- Specialized surgical nursing shortage:Training gaps in advanced stapler troubleshooting and energy-device safety protocols delay operating room throughput.
- ISO 10993-18 chemical characterization:Extractables and leachables testing timelines extend product development cycles by twelve to eighteen months.
- Legacy electronic health record integration:Device utilization tracking systems fail to capture real-world performance data required for post-market surveillance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wound Closure Devices Market |
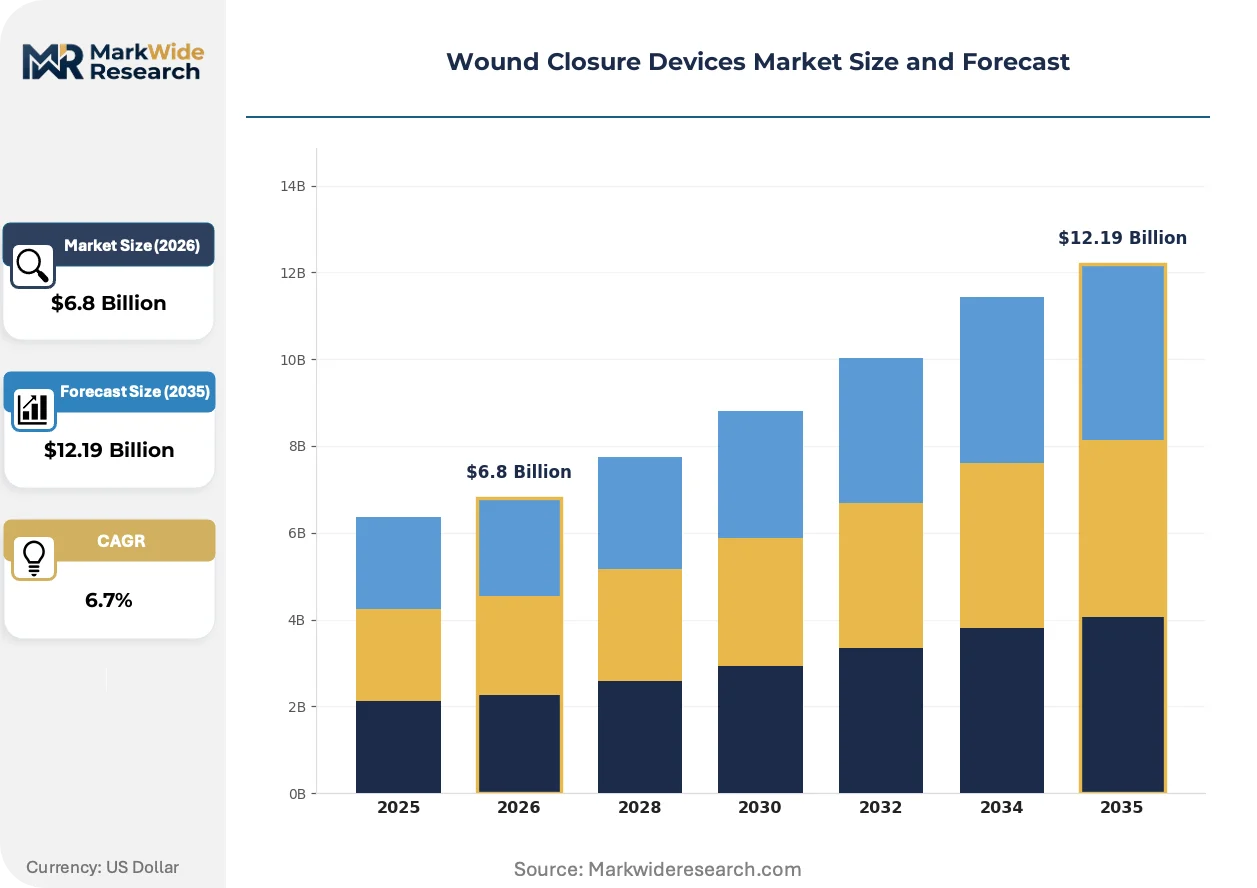
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.19 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sutures, Adhesive Devices, Staples, Clips End User: Hospitals, Clinics, Ambulatory Surgical Centers, Home Healthcare Material: Absorbable, Non-absorbable, Synthetic, Natural Application: Surgical Wounds, Traumatic Wounds, Chronic Wounds, Cosmetic Procedures |
| Companies Covered | Ethicon (Johnson & Johnson Services, Inc.), Medtronic, 3M, Baxter, Smith+Nephew, Stryker, B. Braun Melsungen AG, Corza Medical, Advanced Medical Solutions Group plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wound Closure Devices Market Strategic Shifts
Active polymer chemistry and energy-delivery engineering are converging to eliminate mechanical foreign bodies from healing tissue. These advances are compressing the distinction between closure and regeneration.
Barbed knotless suture technology is supplanting traditional interrupted suturing in laparoscopic myomectomy and bariatric procedures. Gynecologic and general surgeons in United States academic medical centers have adopted barbed configurations for over sixty percent of applicable cases. The technology is compressing operative time and reducing reliance on skilled laparoscopic knot-tying proficiency that remains scarce in community hospital settings.
FDA's evolving guidance on absorbable device degradation profiles now requires longitudinal mechanical property data through complete resorption. Manufacturers must submit tensile strength retention curves at thirty, sixty, and ninety-day intervals. Absorbable mesh and internal fixation device categories face the steepest compliance burden, with several submissions delayed for supplemental biocompatibility testing.
Hospital purchasing committees now unbundle device selection from surgeon preference card autonomy, centralizing contract negotiations for high-volume closure categories. Integrated delivery networks in Germany and United States are consolidating supplier rosters to three preferred vendors per product class. This concentration is most visible in cardiovascular surgery, where standardized stapler platforms reduce inventory complexity across multi-hospital systems.
Wound Closure Devices Market Segmentation
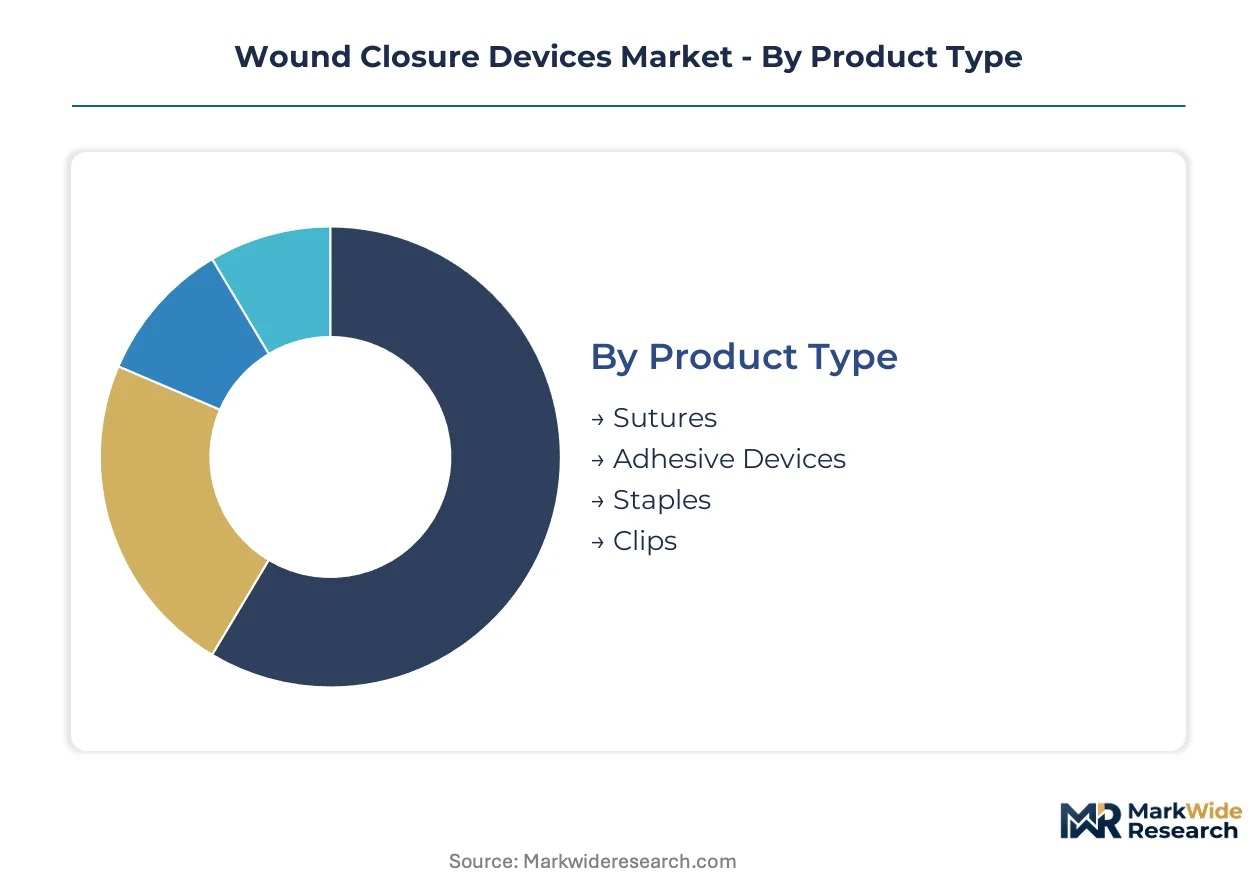
Wound closure device segmentation reveals divergent supply chain configurations across product categories. Material sourcing patterns and sterilization infrastructure requirements create distinct geographic production footprints for each segment cluster.
Product Type:
Sutures dominate domestic manufacturing footprints in the United States and Germany, while adhesive devices concentrate in specialized polymer chemistry clusters across Japan and Switzerland.
- Sutures:Monofilament and braided configurations utilizing polyglycolic acid, polylactic acid, or silk fibers with specified tensile strength retention profiles. United States academic medical centers and German hospital networks anchor demand for advanced antibacterial-coated variants that reduce surgical site infection rates.
- Adhesive Devices:Cyanoacrylate-based tissue adhesives and sealant films engineered for rapid polymerization upon tissue contact. Japan's cosmetic surgery clinics and United States dermatology practices drive uptake of scar-minimizing formulations that eliminate suture removal visits.
- Staples:Metallic or absorbable polymer configurations for rapid tissue approximation in gastrointestinal and thoracic procedures.
- Clips:Titanium or polymer ligating devices deployed in laparoscopic vessel sealing and tissue retraction.
Sutures command the established base. The steepest expansion runs through adhesive devices.
End User:
Procurement authority concentrates differently across settings—hospital purchasing committees negotiate bulk contracts while ambulatory centers prioritize device portability and simplified sterilization.
- Hospitals:Comprehensive surgical departments across United States, Germany, and Japan maintain diversified closure inventories spanning all product categories. Complex cardiothoracic and orthopedic procedures require immediate access to multiple closure modalities.
- Ambulatory Surgical Centers:United States outpatient facilities now perform over half of all laparoscopic cholecystectomies and hernia repairs. Device form factors must accommodate limited sterilization infrastructure and same-day discharge protocols.
- Clinics:Dermatology and minor trauma settings in urban Japan and Germany utilize adhesive devices and skin closure strips for superficial wound management.
- Home Healthcare:Post-operative wound monitoring and negative-pressure therapy delivery in rural United States markets where hospital access is constrained.
Hospitals retain the volume anchor. Ambulatory Surgical Centers are climbing the fastest as site-of-care migration accelerates.
Material:
Cost tier stratification separates premium absorbable synthetics from commodity natural fibers, with raw material sourcing determining geographic production concentration.
- Absorbable:Synthetic polymers including polyglycolic acid, polylactic acid, and polydioxanone engineered for controlled hydrolytic degradation. Internal soft-tissue closures in United States and German hospitals favor these materials to eliminate secondary removal procedures.
- Non-absorbable:Polypropylene, polyester, and stainless steel configurations providing permanent mechanical support. Cardiovascular and orthopedic applications across Japan and Germany require long-term tensile stability.
- Synthetic:Manufactured polymer matrices with standardized degradation profiles and batch consistency.
- Natural:Silk, cotton, and collagen-derived materials with historical usage patterns in emerging markets.
Absorbable materials capture premium positioning. Synthetic materials are gaining share fastest as manufacturing scale improves.
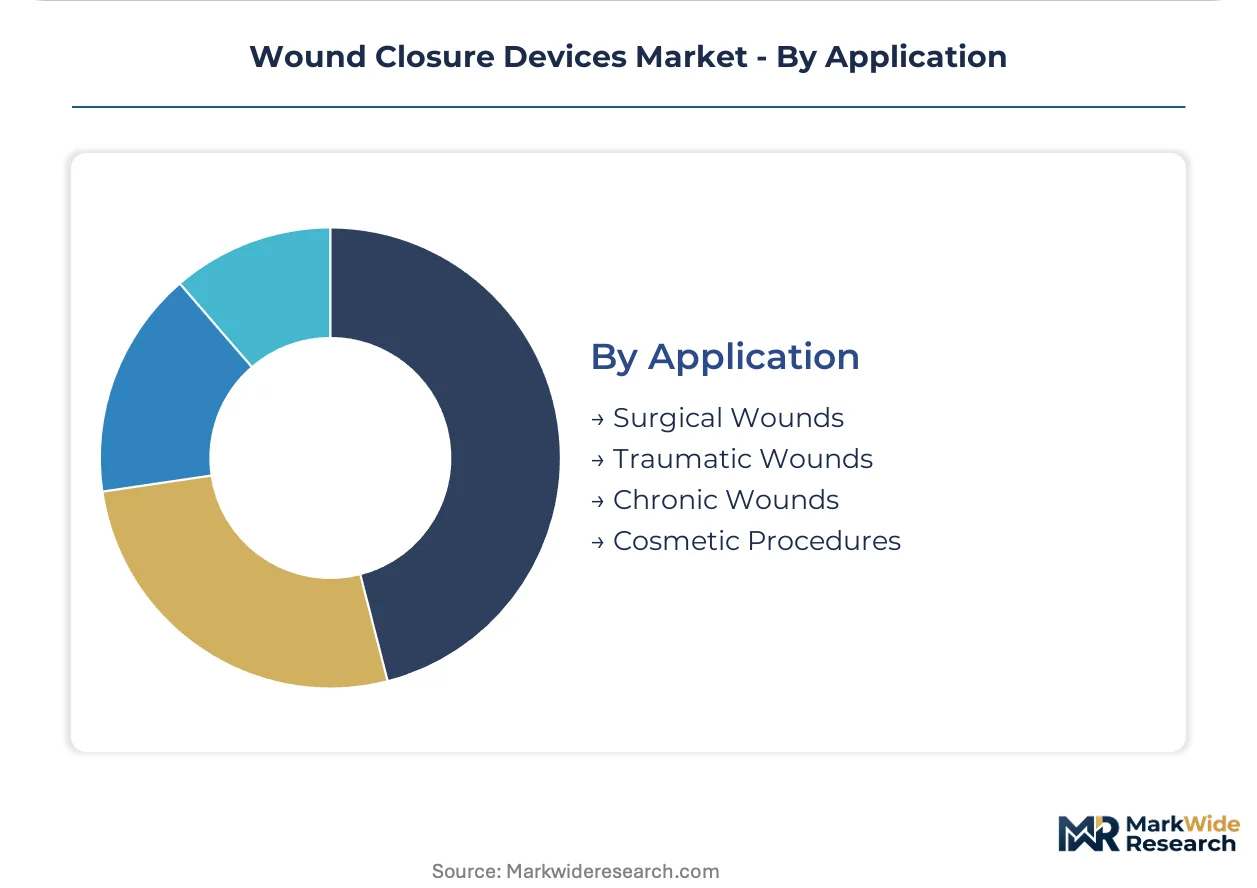
Application:
Clinical outcome requirements vary sharply—surgical wounds demand predictable tensile performance while chronic wounds prioritize biocompatibility and moisture management.
- Surgical Wounds:Operating room closures across general, orthopedic, and cardiovascular disciplines requiring standardized strength retention and infection resistance. United States and German hospital systems specify FDA-cleared and CE-marked devices with documented biomechanical performance.
- Chronic Wounds:Diabetic foot ulcers and pressure injuries in Japan's aging rural prefectures and United States long-term care facilities. Negative-pressure wound therapy and advanced dressings integrate with closure systems to manage exudate and granulation tissue.
- Traumatic Wounds:Emergency department repairs of lacerations and penetrating injuries requiring rapid hemostasis.
- Cosmetic Procedures:Minimally invasive aesthetic surgeries in Japan and United States metropolitan markets where scar visibility drives adhesive and subcuticular suture selection.
Surgical wounds anchor revenue concentration. Chronic wounds show the steepest expansion trajectory as population aging intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance pathways in the United States establish the regulatory benchmark that shapes clinical evidence requirements across wound closure device categories. Site-of-care migration toward ambulatory settings is redistributing procurement authority and sterilization infrastructure requirements across major economies.
United States
Ambulatory surgical centers now perform over half of all laparoscopic cholecystectomies and hernia repairs, compressing device form factors for limited sterilization infrastructure. FDA biocompatibility standards for absorbable polymers are tightening longitudinal mechanical property documentation requirements. The Minneapolis-St. Paul corridor anchors domestic manufacturing of advanced polymer sutures.
Germany
Hospital purchasing committees in integrated delivery networks are consolidating supplier rosters to three preferred vendors per closure category. EMA Medical Device Regulation harmonization is accelerating cross-border approvals for next-generation absorbable matrices. The Baden-Württemberg cluster concentrates gamma irradiation sterilization capacity serving European device manufacturers.
Japan
Super-aging rural prefectures drive chronic wound management demand for negative-pressure closure systems and advanced dressings. PMDA regulatory timelines for novel energy-based platforms extend review cycles when predicate devices lack established degradation profiles. The Kansai region around Osaka hosts specialized polymer chemistry facilities for cosmetic surgery adhesive formulations.
India
Domestic manufacturing incentives under the PLI scheme for medical devices are opening import-substitution pathways for suture and mesh producers. CDSCO regulatory pathways are streamlining for Class B and C closure devices with established international approvals. The Maharashtra-Gujarat pharmaceutical corridor is attracting contract manufacturing for absorbable synthetic matrices.
Switzerland
Specialized adhesive device manufacturing concentrates in precision polymer chemistry clusters serving cosmetic and dermatology markets. Swissmedic regulatory frameworks align with EMA standards while maintaining distinct post-market surveillance requirements. The Basel-Zurich corridor integrates pharmaceutical polymer expertise with medical device engineering capabilities.
Wound Closure Devices Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in wound closure device supply. Tier-one players leverage full-portfolio sutures and energy-based platforms to anchor hospital supply chain relationships. Mid-scale specialists concentrate on single-modality excellence in barbed knotless configurations or hemostasis-integrated systems. Dominant competitive moves include backward integration into polymer feedstock production and strategic partnerships with ambulatory surgical center networks.
Within the integrated multinational tier, Ethicon and Medtronic occupy positions defined by comprehensive operating room supply chain presence. Baxter exemplifies the hemostasis-integrated specialization archetype. B. Braun Melsungen AG represents European-scale manufacturing depth in suture and mesh categories. These anchors demonstrate how geographic origin and corporate structure shape competitive positioning without determining specific strategic outcomes.
| Leading Market Players |
|---|
| Ethicon (Johnson & Johnson Services, Inc.) |
| Medtronic |
| 3M |
| Baxter |
| Smith+Nephew |
| Stryker |
| B. Braun Melsungen AG |
| Corza Medical |
| Advanced Medical Solutions Group plc |
| Others |
Value Chain & Pricing Dynamics
Ninety-day polymer feedstock inventory buffers separate tier-one manufacturers from commodity suppliers, concentrating pricing power with German and United States producers who control gamma sterilization capacity and absorb raw material volatility through backward integration into caprolactone production.
Pricing Analysis
United States hospital systems command fifteen to twenty percent discounts against Japanese cosmetic surgery clinics for identical absorbable suture SKUs. Contract-based long-term offtake agreements dominate, with price differentiation resting on FDA 510(k) clearance tier and volume scale. Pricing pressure stems from polymer feedstock volatility squeezing mid-tier manufacturers without captive glycolide supply. Ambulatory surgical centers exhibit highest price sensitivity due to constrained capital budgets, while academic medical centers prioritize clinical performance over unit cost.
Supply Chain Analysis
Strategic stockpiling of gamma-irradiated finished goods characterizes tier-one inventory strategy, contrasting with just-in-time raw material procurement among contract manufacturers. Supply concentrates in Germany, the United States, and Japan, with polymer synthesis feeding from Belgian and Texan petrochemical corridors. Caprolactone, glycolide monomers, and medical-grade titanium constitute critical input dependencies. Single-source sterilization vulnerability in Baden-Württemberg and Minneapolis-St. Paul creates geographic concentration risk. Distribution runs through integrated delivery network procurement committees and group purchasing organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized surgical nursing scarcity constrains operating room throughput and forces device selection toward automation-friendly formats, privileging manufacturers who embed training protocols and remote troubleshooting support within product ecosystems.
For Market Incumbents: Consolidate supplier roster positions within German and United States integrated delivery networks before purchasing committee standardization locks out secondary vendors. Deepen backward integration into polylactic acid feedstock production to defend margins against glycolide price volatility. Anchor hospital supply chain relationships through exclusive stapler platform contracts that raise switching costs for competing energy-based closure systems. For New Entrants and Emerging Players: Lead with barbed knotless suture configurations targeting United States community hospitals where laparoscopic knot-tying proficiency gaps delay procedure throughput. Japan's rural chronic wound management segment offers penetrable white space for negative-pressure closure systems currently underserved by incumbent distribution networks. Pursue CDSCO regulatory pathway alignment with established FDA 510(k) predicates to accelerate Indian market entry under PLI scheme incentives. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because hospital purchasing committee concentration and sterilization infrastructure scarcity favor scaled incumbents with integrated manufacturing footprints. Target acquisition archetypes include mid-scale specialists with single-modality excellence in hemostasis-integrated systems or barbed suture configurations. Monitor FDA degradation-profile guidance evolution as inflection signal for absorbable device category compliance burdens.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates United States market access for novel absorbable polymer matrices with predicate alignment. |
| CE Marking Pathway | Unlocks German hospital network procurement under EMA Medical Device Regulation harmonization. |
| Hospital System Partnership | Secures preferred vendor status within United States integrated delivery network sterilization protocols. |
| Software Companion Development | Enables remote stapler troubleshooting that addresses specialized surgical nursing scarcity in community settings. |
| Reimbursement Strategy | Aligns device form factors with CMS outpatient procedure codes driving ambulatory surgical center volume migration. |
Study Parameters
Initial hypotheses were tested against primary input from hospital purchasing committee directors, biomedical engineers, GPO contracts managers, and ambulatory surgical center administrators and refined through secondary validation against FDA 510(k) filings, EMA Medical Device Regulation submissions, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up unit demand estimates across product type, material, end user, and application segments were triangulated with top-down macroeconomic indicators.
Variance decomposition across the projection horizon isolates volume drivers from pricing dynamics and mix-shift effects. Segmentation dimensions modeled include product category, absorbable versus non-absorbable material tier, hospital versus ambulatory site-of-care, and surgical versus chronic wound application. CAGRs were derived from segment-level growth trajectories weighted by revenue contribution. Industry-specific forecast inputs incorporate polymer feedstock price indices and regulatory approval timeline distributions.
The analysis sits within stated boundaries; outcomes outside sustained ambulatory surgical center volume migration or polymer feedstock price stability would require recalibration. Forecasts reflect documented assumptions regarding FDA review timeline distributions and EMA harmonization implementation pace. Revision becomes warranted when gamma sterilization capacity utilization crosses threshold levels that trigger geographic supply vulnerability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Global Burn Care Market
Wound Care
Wound Closure and Advanced Wound Care Market
Wound Care
Advanced Wound Management Market
Wound Care
South Korea Wound Care Market
Wound Care
Patch Based Wound Healing Products Market
Wound Care
Alginate Dressing Market
Wound Care
Mexico Wound Care Management Devices Market
Wound Care
Global Traditional Wound Management Market
Wound Care
Brazil Wound Care Management Devices Market
Wound Care
LAMEA Surgical Dressing Market
Wound Care
Global Digital Wound Measurement Devices Market
Wound Care
North America Advanced Wound Care Market
Wound Care
Wound Care Market
Wound Care
Wound Debridement (Wound Cleaning) Market
Wound Care
Saudi Arabia Wound Care Management Devices Market
Wound Care
Maggot Debridement Market