
 Hemostats for Wound Closure Market | 2026-2036
Hemostats for Wound Closure Market Size, Share, and Industry Trends Forecast 2026-2036
Hemostats for Wound Closure Market Foresight
A capital-intensity divergence between integrated multinationals and focused specialists is redrawing competitive boundaries in hemostatic wound closure. Johnson & Johnson leverages its broad surgical portfolio to bundle hemostats with suture and stapler systems, securing preferential placement in hospital formulary committees. Baxter International anchors its position through captive plasma-derived supply chains that insulate fibrin sealant production from raw material volatility. Gelita Medical specializes in porcine-derived gelatin matrices, occupying a defensible niche in bioresorbable hemostatic applications.
Hemostats for wound closure comprise absorbable and non-absorbable agents designed to accelerate clot formation at surgical or traumatic wound sites, typically formulated from oxidized cellulose, gelatin, collagen, or thrombin-based compounds that achieve hemostasis within two to ten minutes of application. Their primary commercial purpose centers on reducing operative blood loss, shortening time-to-hemostasis, and minimizing transfusion requirements across invasive procedures. Topical hemostats lead product category revenue due to universal deployment in general surgery, while sealants command premium pricing in cardiovascular and neurological applications where precise tissue adherence proves critical. Ambulatory surgical centers represent the fastest-growing end-user channel as procedure migration accelerates from inpatient settings, though hospitals retain dominant volume share through bundled payment structures that favor integrated supply contracts.
The FDA's 510(k) clearance framework and the EU Medical Device Regulation's updated clinical evidence requirements for absorbable implants collectively elevate barriers for new hemostat entrants lacking established biocompatibility dossiers. The EPA monitors manufacturing effluent from collagen-processing facilities, adding compliance costs concentrated among suppliers dependent on animal-derived raw materials. Stakeholders must monitor evolving reimbursement thresholds for outpatient hemostat application as payors recalibrate coverage policies around same-day surgical economics.
Market Dynamics
The FDA's evolving 510(k) premarket notification pathways for absorbable hemostats are compressing product development timelines while elevating biocompatibility dossier requirements, forcing manufacturers to front-load clinical evidence generation.
Growth Catalysts
- EU MDR clinical evidence mandates:Stricter requirements for absorbable implants are accelerating consolidation among established players with robust biocompatibility portfolios, raising competitive barriers for entrants.
- Ambulatory surgical center migration:Procedure volume shifts from inpatient to same-day settings are expanding addressable demand for rapid-acting topical hemostats optimized for shorter operative windows.
- Fibrin sealant precision:Advanced thrombin-based formulations achieving hemostasis within two minutes are displacing conventional mechanical methods in cardiovascular and neurological suites.
Market Restraints
- Plasma supply volatility:Baxter International's captive supply chains insulate production, but smaller competitors face raw material concentration risk from fractionation facility geography.
- Animal-derived processing costs:EPA effluent monitoring of collagen-processing facilities adds compliance burdens concentrated among gelatin and collagen matrix suppliers.
- Reimbursement threshold compression:CMS and commercial payors are recalibrating coverage policies around outpatient hemostat application, pressuring premium pricing for sealant categories.
Strategic Opportunities
- Bioresorbable matrix innovation:Porcine-derived gelatin formulations from specialized suppliers occupy defensible niches as hospitals prioritize synthetic alternatives to bovine collagen.
- Integrated formulary bundling:Health networks are consolidating procurement of hemostats with suture and stapler systems, favoring multiline surgical portfolio vendors.
- Same-day surgical economics:Payer policy evolution toward bundled outpatient payments creates white space for rapid-hemostasis products that reduce time-to-discharge metrics.
Industry Challenges
- ISO 10993 biocompatibility timeline:Extended cytotoxicity and sensitization testing protocols for novel absorbable materials delay commercialization by 18-24 months.
- Legacy ERP integration:Hospital supply chain systems require costly middleware development to track lot-level hemostat utilization against patient outcomes for value-based contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hemostats for Wound Closure Market |
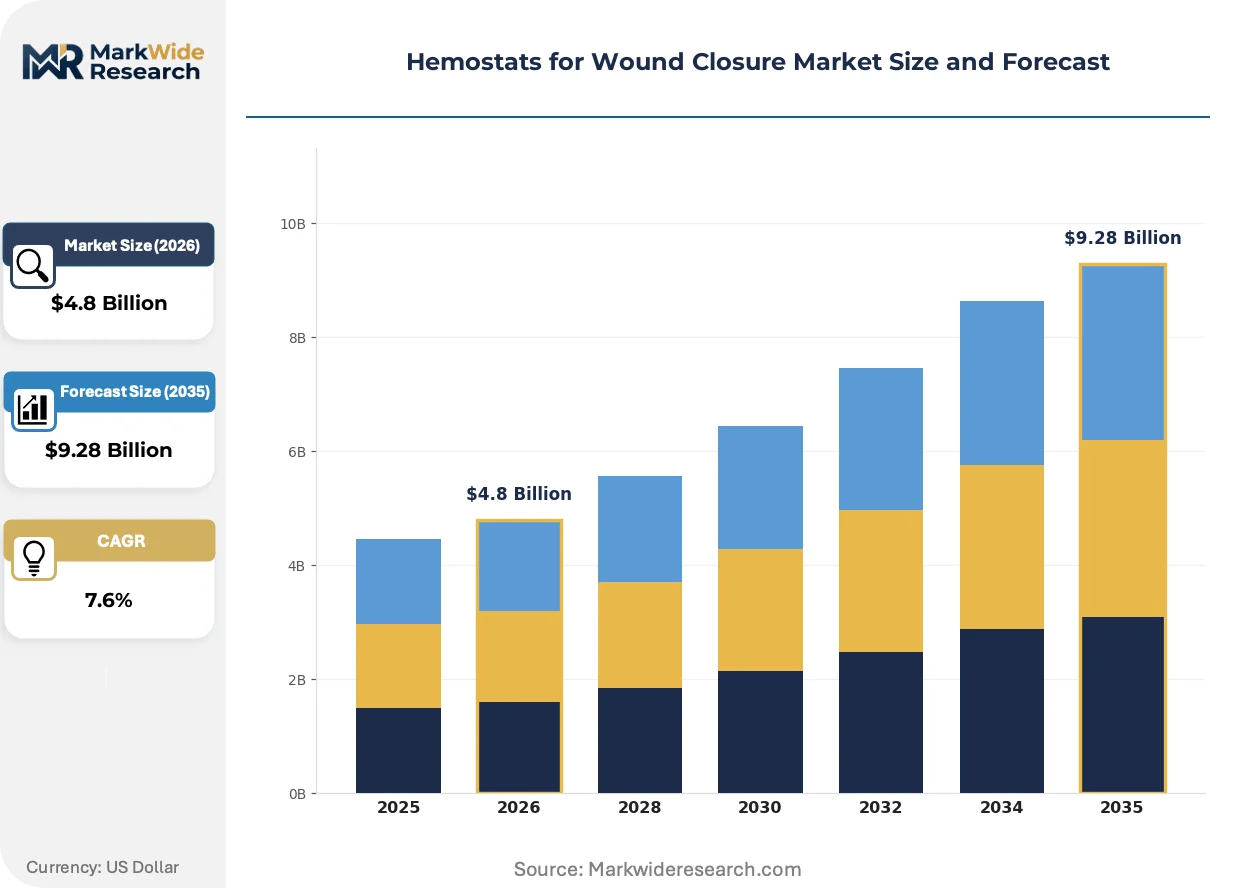
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Hemostats, Sealants, Gels, Pads Application: Emergency Care, Surgical Procedures, Dental Procedures, Gynecological Surgery End User: Hospitals, Clinics, Ambulatory Surgical Centers, Outpatient Facilities Delivery Mode: Disposable, Reusable, Pre-packaged, Customizable |
| Companies Covered | Johnson & Johnson, Medtronic, Baxter International, B. Braun, Corza Health, Integra LifeSciences Corporation, Smith & Nephew, Pfizer, Gelita Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hemostats for Wound Closure Market Shifts & Advancements
Three intersecting developments are reshaping competitive positioning: device miniaturization enabling precision application, regulatory evidence requirements elevating development costs, and procurement centralization favoring integrated suppliers.
Flowable gelatin-thrombin composites are miniaturizing delivery systems for laparoscopic and robotic surgical platforms, enabling sub-millimeter applicator tips that access confined anatomical spaces. Academic medical centers with high robotic surgery penetration are piloting these systems at twice the rate of community hospitals. The technology is miniaturizing the addressable procedure set, expanding hemostat deployment into previously inaccessible microsurgical fields.
REACH chemical substance restrictions and EU MDR updated clinical evidence requirements for absorbable implants are forcing manufacturers to revalidate legacy product lines with enhanced biocompatibility data. The regulatory burden falls disproportionately on mid-tier suppliers lacking established post-market surveillance infrastructure. Cardiovascular sealant categories face the steepest compliance cost escalation as notified bodies demand extended thrombogenicity studies.
Integrated health networks are consolidating vendor relationships around single-source surgical contracts that bundle hemostats with mechanical closure devices. The purchasing pattern displaces standalone hemostat suppliers from formulary access in favor of multiline portfolio vendors. This concentration is most visible in United States metropolitan markets where three-to-five hospital systems control regional surgical volume.
Hemostats for Wound Closure Market Segmentation
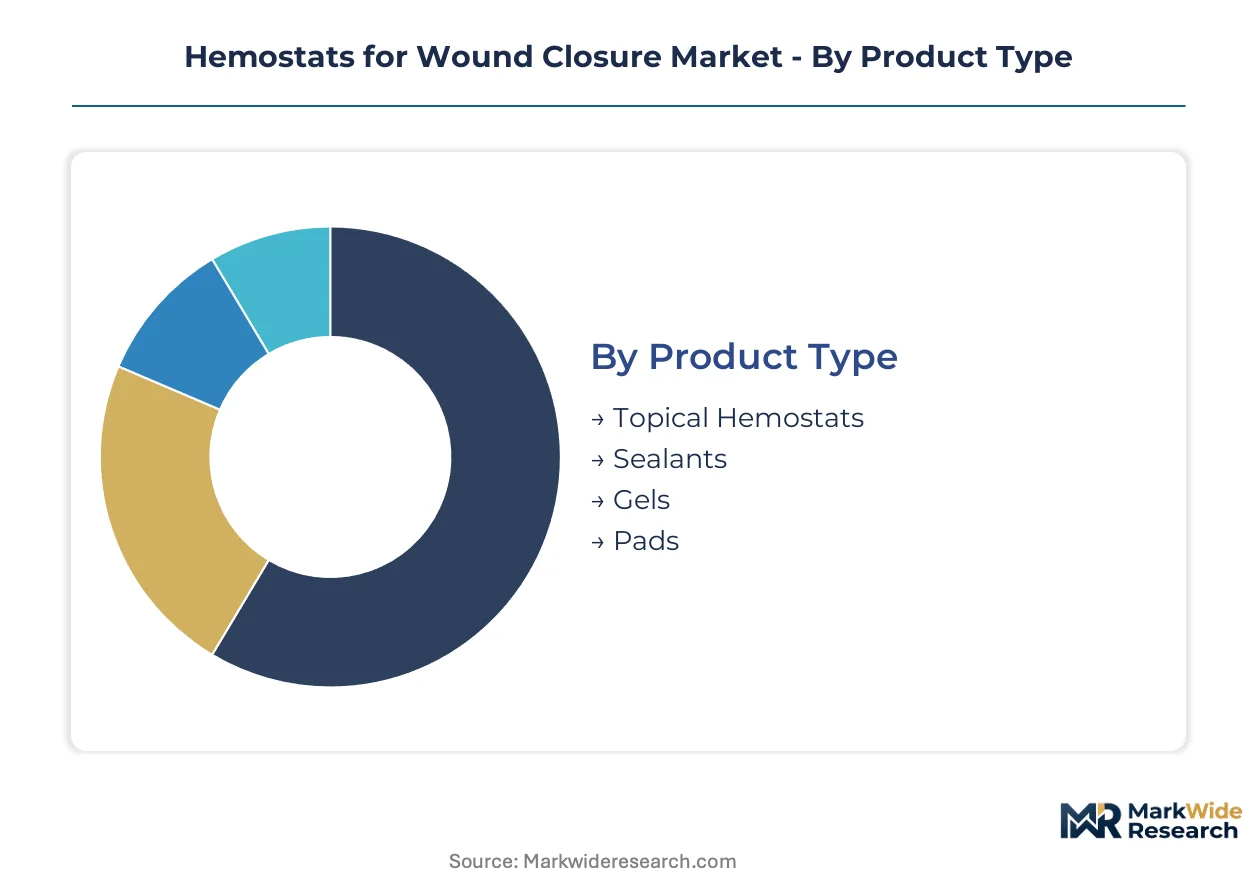
Segmentation in hemostatic wound closure reveals how product specifications, procedural settings, and supply configurations create distinct commercial battlegrounds. Each dimension carries implications for regulatory pathway, pricing power, and channel access.
Product Type:
Domestic production concentrates on topical hemostats and gelatin matrices, while sealant categories rely more heavily on imported plasma-derived or recombinant thrombin inputs.
- Topical Hemostats:Oxidized cellulose and gelatin sponge formulations achieve hemostasis through mechanical compression and platelet activation. Demand concentrates in United States hospital systems where bundled surgical contracts favor rapid-acting mechanical agents for general surgery suites. CMS reimbursement codes for inpatient procedures sustain volume leadership despite pricing pressure from outpatient migration.
- Sealants:Fibrin and synthetic polymer adhesives provide tissue adherence alongside hemostasis. European cardiovascular centers in Germany and Switzerland drive premium demand where precise sealing in neurological and thoracic procedures justifies higher acquisition costs. EU MDR clinical evidence requirements favor established suppliers with post-market surveillance infrastructure.
- Gels:Flowable gelatin-thrombin composites enable laparoscopic application through sub-millimeter delivery systems.
- Pads:Pre-formed collagen and cellulose sheets serve emergency field deployment and military medical kits.
Topical hemostats hold the largest share; momentum sits with sealants as robotic surgery penetration climbs.
Application:
Surgical procedures generate the highest absolute volume, though emergency care and same-day settings are expanding the addressable case mix fastest.
- Surgical Procedures:Open and minimally invasive interventions across general, orthopedic, and cardiovascular specialties consume hemostats at scale. United States integrated delivery networks centralize procurement through value-based surgical bundles that tie hemostat selection to total episode cost. Fibrin sealant displacement of mechanical methods accelerates in academic medical centers with high robotic surgery penetration.
- Emergency Care:Trauma and battlefield medicine demand rapid-deployment formats with minimal preparation. Military procurement through the Defense Logistics Agency sustains domestic manufacturing capacity for oxidized cellulose and kaolin-based products.
- Dental Procedures:Localized bleeding control in extraction and implantology favors small-format gelatin sponges.
- Gynecological Surgery:Laparoscopic hysterectomy and myomectomy applications favor flowable gels over woven matrices.
Surgical procedures anchor volume; emergency care is climbing the fastest as pre-hospital trauma protocols standardize hemostatic dressing use.
End User:
Hospital purchasing concentration creates tiered access patterns, with ambulatory channels fragmenting vendor relationships.
- Hospitals:Inpatient surgical departments and hybrid operating rooms command formulary control through integrated supply contracts. Three-to-five hospital systems in United States metropolitan markets consolidate regional surgical volume, displacing standalone hemostat suppliers in favor of multiline portfolio vendors. Bundled payment structures for cardiac and orthopedic episodes reinforce centralized procurement.
- Ambulatory Surgical Centers:Same-day procedure migration expands addressable demand for rapid-acting formats optimized for shorter operative windows. United States freestanding ASCs operate outside hospital purchasing agreements, creating white space for specialized suppliers with direct distribution capabilities.
- Clinics:Dermatology and minor procedure settings favor over-the-counter and physician-dispensed formats.
- Outpatient Facilities:Hospital-affiliated same-day surgery units bridge inpatient and ambulatory economics.
Hospitals retain dominant share; ambulatory surgical centers are gaining share fastest as procedure migration accelerates.
Delivery Mode:
Pre-packaged configurations dominate institutional procurement, while customizable formats serve niche surgical requirements.
- Pre-packaged:Sterile, single-use units with fixed thrombin or gelatin concentrations streamline operating room workflow. United States hospital supply chains mandate lot-level traceability for liability and recall management, favoring manufacturers with ERP integration capabilities. Standardized formats reduce nursing training burden and waste.
- Disposable:Single-use applicators and matrices eliminate reprocessing costs and cross-contamination risk. European outpatient clinics favor disposable economics where reprocessing infrastructure is limited.
- Reusable:Autoclavable delivery systems serve cost-constrained settings with high procedure volume.
- Customizable:Surgeon-compounded thrombin concentrations and matrix sizes address specialized anatomical requirements.
Pre-packaged formats hold the largest share; customizable options are expanding most quickly in robotic and microsurgical applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes hemostats through bundled surgical contracts that tie product selection to total episode economics, while European markets fragment across national reimbursement systems that elevate clinical evidence requirements above procurement scale.
United States
Integrated delivery networks in metropolitan markets concentrate surgical volume through three-to-five hospital systems, centralizing formulary control around multiline portfolio vendors. The FDA's 510(k) premarket notification framework compresses development timelines while elevating biocompatibility dossier standards. Academic medical centers in Boston and the Research Triangle pilot robotic surgery platforms that accelerate fibrin sealant displacement of mechanical methods.
Germany
Cardiovascular centers in Munich and Heidelberg drive premium demand for precision sealants where neurological and thoracic procedures justify higher acquisition costs. The EU Medical Device Regulation mandates enhanced clinical evidence for absorbable implants, favoring established suppliers with post-market surveillance infrastructure. The Baden-Württemberg medical technology cluster anchors sealant formulation capabilities serving Central European surgical networks.
Switzerland
Swissmedic's stringent device approval standards concentrate demand among manufacturers with established European notified body relationships. The Basel-Zurich corridor hosts precision chemical formulation capabilities that supply thrombin-based compounds to adjacent EU markets. Cantonal hospital procurement systems favor products with demonstrated health technology assessment outcomes over price-competitive alternatives.
Japan
PMDA's pharmaceutical affairs law classifies advanced hemostats as regenerative medical products, extending review timelines for novel absorbable materials. The Kansai region's surgical device manufacturing base supplies flowable gelatin-thrombin composites optimized for laparoscopic platforms. Tokyo metropolitan hospitals anchor volume through centralized procurement of premium wound closure solutions.
India
CDSCO's medical device rules are harmonizing with international standards, accelerating market access for CE-marked and FDA-cleared products. The Maharashtra-Gujarat pharmaceutical corridor hosts contract manufacturing for gelatin matrix production serving domestic and export markets. Corporate hospital chains in Delhi-NCR and Bengaluru consolidate procurement through group purchasing organizations that negotiate directly with multinational suppliers.
Hemostats for Wound Closure Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with market structure determined by portfolio breadth and captive supply chain control. Consolidated procurement through United States health networks favors multiline surgical vendors with ERP integration capabilities. Three archetypes dominate: diversified medical device conglomerates with formulary bundling power, plasma fractionation specialists with raw material security, and focused bioresorbable matrix developers occupying defensible niches. Competitive moves concentrate on strategic partnerships for distribution access and backward integration into animal-derived raw material processing.
Among diversified surgical portfolio vendors, Johnson & Johnson and Medtronic exemplify the integrated leader archetype through formulary bundling capabilities. Baxter International occupies a distinct position through captive plasma supply chains that insulate fibrin sealant production. Within the specialist tier, Gelita Medical represents focused expertise in porcine-derived gelatin matrices.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Medtronic |
| Baxter International |
| B. Braun |
| Corza Health |
| Integra LifeSciences Corporation |
| Smith & Nephew |
| Pfizer |
| Gelita Medical |
| Others |
Supply & Pricing Matrix
Porcine-derived gelatin substitution for bovine collagen is redrawing raw material sourcing geography while compressing premium-tier pricing power as hospitals demand synthetic alternatives to mammalian tissue matrices. This input shift simultaneously elevates compliance costs for EPA-monitored processing facilities and fragments supplier concentration across Central European gelatin specialists.
Pricing Analysis
After-sales service contracts and formulary integration fees drive lifetime value more than per-unit sealant margins. Pricing stratifies across premium fibrin formulations, standard oxidized cellulose, and economy gelatin sponges, with differentiation resting on FDA 510(k) clearance tier and robotic surgery compatibility. Pricing pressure stems from CMS outpatient reimbursement recalibration compressing sealant premiums. Ambulatory surgical centers exhibit highest price sensitivity; academic medical centers with bundled contracts show least.
Supply Chain Analysis
Strategic stockpiling of plasma-derived thrombin concentrates dominates inventory strategy given fractionation facility concentration risk. Supply concentrates in the United States for oxidized cellulose, Germany for precision sealant formulation, and Switzerland for thrombin chemical processing. Raw material flows draw from porcine tissue abattoirs, human plasma fractionation pools, and recombinant bacterial fermentation. Single-source vulnerability runs through Baxter International's captive plasma network. Distribution runs through integrated health network GPO contracts and direct ASC channel partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face a substitution defense against flowable synthetic polymer sealants displacing mechanical hemostats in robotic surgery suites, requiring portfolio repositioning to maintain formulary access.
For Market Incumbents: Compound formulary bundling power by integrating hemostats with mechanical closure systems to deepen hospital supply contract penetration. Anchor backward integration into porcine gelatin processing to insulate against EPA effluent compliance cost escalation. Prioritize ISO 10993 biocompatibility dossier completion ahead of EU MDR absorbable implant deadlines. For New Entrants and Emerging Players: Anchor in ambulatory surgical center direct distribution channels where hospital GPO exclusion creates white space. Target rapid-acting topical formats optimized for same-day discharge metrics. Penetrate United States freestanding ASCs through specialized salesforce deployment bypassing integrated network procurement. For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier bioresorbable matrix developers with established porcine supply relationships and pending FDA 510(k) submissions. Long-term viability hinges on regulatory clearance velocity outpacing consolidation pressure from multiline surgical vendors. Watch for EU notified body capacity constraints as inflection signal for European market access bottlenecks.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Formulary integration with integrated delivery networks secures multiyear supply contract lock-in. |
| CE Marking Pathway | EU MDR clinical evidence dossiers enable premium sealant positioning in German cardiovascular centers. |
| Backward Integration | Captive porcine gelatin processing insulates production from EPA effluent monitoring cost spikes. |
| Software Companion Development | Robotic surgery platform integration drives fibrin sealant displacement of mechanical hemostasis methods. |
| Reimbursement Strategy | CMS outpatient coverage alignment positions rapid-acting formats for ASC procedure migration capture. |
Research Methodology
Desk research of FDA 510(k) clearance databases, EU MDR notified body guidance documents, and hospital GPO contract filings preceded structured interviews with surgical supply chain managers, biomedical engineers, and formulary committee directors. Primary fieldwork with clinicians and procurement officers was cross-validated against CMS reimbursement code analysis and plasma fractionation industry trade data. Bottom-up demand modeling was triangulated with top-down market sizing across product categories.
Variance decomposition across product type, application setting, end-user channel, and delivery mode segmentation informed volume and value projections throughout the forecast period. CAGRs were derived from procedure volume elasticity modeling and pricing trajectory analysis. Forecast inputs incorporated robotic surgery penetration curves, EU notified body capacity constraints, and ambulatory surgical center migration rates.
Underlying assumptions cover stable FDA 510(k) pathway timelines and continued plasma fractionation supply security, with deviation risk concentrated in EU MDR clinical evidence requirement escalation and CMS outpatient reimbursement compression. Revision becomes warranted when EU notified body review queue durations exceed historical baselines or when integrated health network consolidation accelerates beyond modeled concentration thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Wound Management Market
Wound Care
Burn Care Centers Market
Wound Care
Wound Retractor Market
Wound Care
Surgery Medical Bandage Market
Wound Care
Global Diabetic Foot Ulcers Market
Wound Care
Interactive Wound Dressing Market
Wound Care
Europe Negative Pressure Wound Therapy Market
Wound Care
South Korea Wound Care Management Market
Wound Care
South Korea Wound Care Market
Wound Care
Alginate Dressing Market
Wound Care
Wound Measurement Devices Market
Wound Care
Wound Irrigation Devices Market
Wound Care
Wound Closure and Advanced Wound Care Market
Wound Care
Wound Closure Devices Market
Wound Care
Liquid Bandages Market
Wound Care
Wound Closure Strips Market