
 Venous Ulcer Treatment Market | 2026-2036
Venous Ulcer Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Venous Ulcer Treatment Market Analytics
A shortage of certified wound care specialists is redrawing competitive dynamics across the venous ulcer treatment landscape. Smith & Nephew leverages its specialized training academies to sustain clinician loyalty across hospital systems. Mölnlycke Health Care anchors its position through direct-to-provider education programs that compete with traditional distributor channels. Coloplast Corp. differentiates by controlling specialized nursing certification partnerships in Europe.
Venous ulcer treatment encompasses medical interventions for chronic lower-extremity wounds arising from sustained venous hypertension, typically involving compression therapy systems with 20-40 mmHg graduated pressure specifications alongside advanced moisture-balancing dressings. The primary purpose centers on restoring functional venous return while preventing wound recurrence and limb complications. Compression devices command the largest installed base among product categories, though skin grafts represent the fastest-expanding margin pool as bioengineered tissue technologies mature. Home healthcare applications are gaining structural share as reimbursement shifts favor outpatient wound management over institutional stays.
FDA 510(k) clearance pathways govern advanced wound dressing introductions in the United States, while the EU Medical Device Regulation imposes strengthened clinical evidence requirements for compression device classifications. Germany's statutory health insurance framework shapes demand through its explicit coverage of multilayer compression systems, creating divergent access patterns across European markets. Stakeholders must monitor evolving payer evidence requirements for bioactive dressings as health technology assessment bodies tighten reimbursement thresholds.
Market Dynamics
Reimbursement compression across Medicare Advantage networks is forcing wound care providers toward outpatient delivery models that reduce institutional bed days while maintaining clinical outcomes.
Growth Catalysts
- Germany's Statutory Health Insurance:Explicit coverage of multilayer compression systems creates predictable demand visibility for device manufacturers serving Central European markets.
- Bioengineered Skin Substitutes:Maturing tissue engineering platforms expand addressable cases into previously non-healing chronic wounds with compromised vascular supply.
- Home Healthcare Infrastructure:Durable medical equipment networks in the United States now support remote compression therapy monitoring through connected device integration.
Market Restraints
- Petroleum-Derived Dressing Costs:Hydrocarbon-based moisture barriers face input price volatility tied to refinery capacity constraints and polymer feedstock fluctuations.
- Clinical Specialist Concentration:Certified wound care nurses cluster disproportionately in urban academic medical centers, leaving rural and exurban markets underserved.
- FDA 510(k) Evidence Burden:Incremental innovation pathways for advanced dressings now require comparative clinical data that extends development timelines without expanding indications.
Strategic Opportunities
- India's Tier-2 Hospital Networks:Underpenetrated secondary cities present first-mover positioning for standardized compression protocol implementation.
- Cellular Therapy Convergence:Combination products merging autologous cell harvest with synthetic scaffolds open regenerative medicine adjacencies beyond passive dressings.
- Direct-to-Patient Subscription Models:Compression garment replenishment programs bypass traditional durable medical equipment distributors in cash-pay segments.
Industry Challenges
- Specialized Nursing Certification Bottlenecks:Wound Ostomy and Continence Nursing certification programs operate below throughput capacity needed for workforce expansion.
- Legacy Electronic Health Record Integration:Wound measurement and tracking applications face interoperability friction with dominant hospital information systems.
- Biological Product Cold Chain Complexity:Living tissue constructs require temperature-controlled logistics that strain existing distributor infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Venous Ulcer Treatment Market |
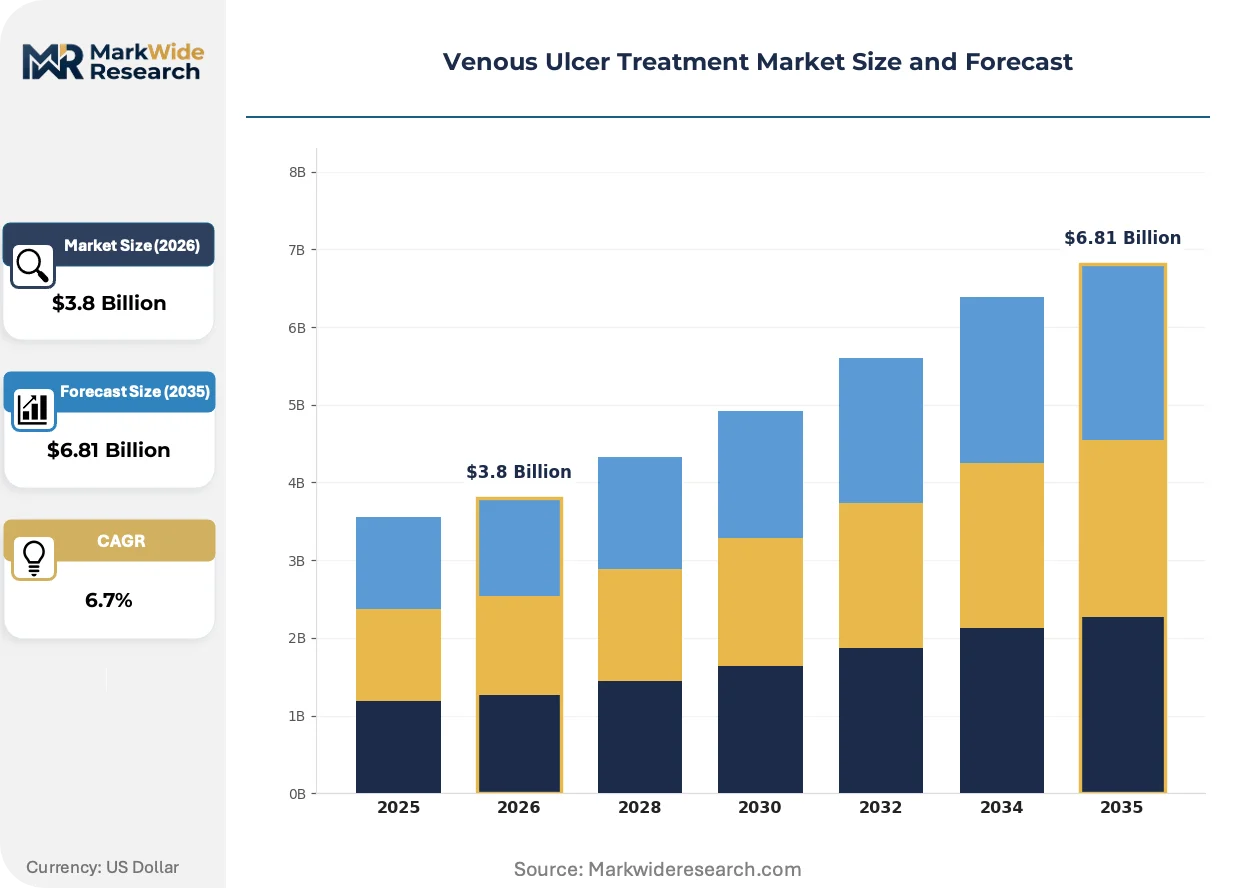
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dressings, Compression Devices, Topical Agents, Skin Grafts Application: Hospital Settings, Home Healthcare, Clinics, Long-term Care Facilities End User: Healthcare Providers, Patients, Caregivers, Payers Delivery Mode: Topical, Intravenous, Surgical, Others |
| Companies Covered | ConvaTec Group, Integra Lifesciences, Smith & Nephew, Medtronic Plc., Bayer AG, 3M, Mölnlycke Health Care, Sanofi S.A, Coloplast Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Venous Ulcer Treatment Market Evolving Landscape
Compression therapy systems are converging with sensor-enabled monitoring platforms that transform passive mechanical intervention into data-generating care episodes.
Wearable pneumatic compression devices are miniaturizing through micro-pump and flexible circuit advances. Home health agencies in the United States are deploying these systems for post-acute venous insufficiency patients. The technology is miniaturizing previously hospital-confined interventions into ambulatory settings that reduce readmission exposure.
EU Medical Device Regulation strengthened clinical evidence requirements for compression device classifications in 2021. Manufacturers must now submit post-market surveillance data that exceeds previous Medical Device Directive thresholds. Class IIa compression systems face particular scrutiny, driving consolidation among smaller notified body relationships.
Hospital purchasing committees now unbundle wound care consumables from bundled payment contracts. Group purchasing organizations are losing exclusivity leverage as individual facilities negotiate direct manufacturer agreements for bioactive dressings. This pattern concentrates in Medicare-funded long-term care networks seeking margin protection under value-based reimbursement.
Venous Ulcer Treatment Market Segmentation
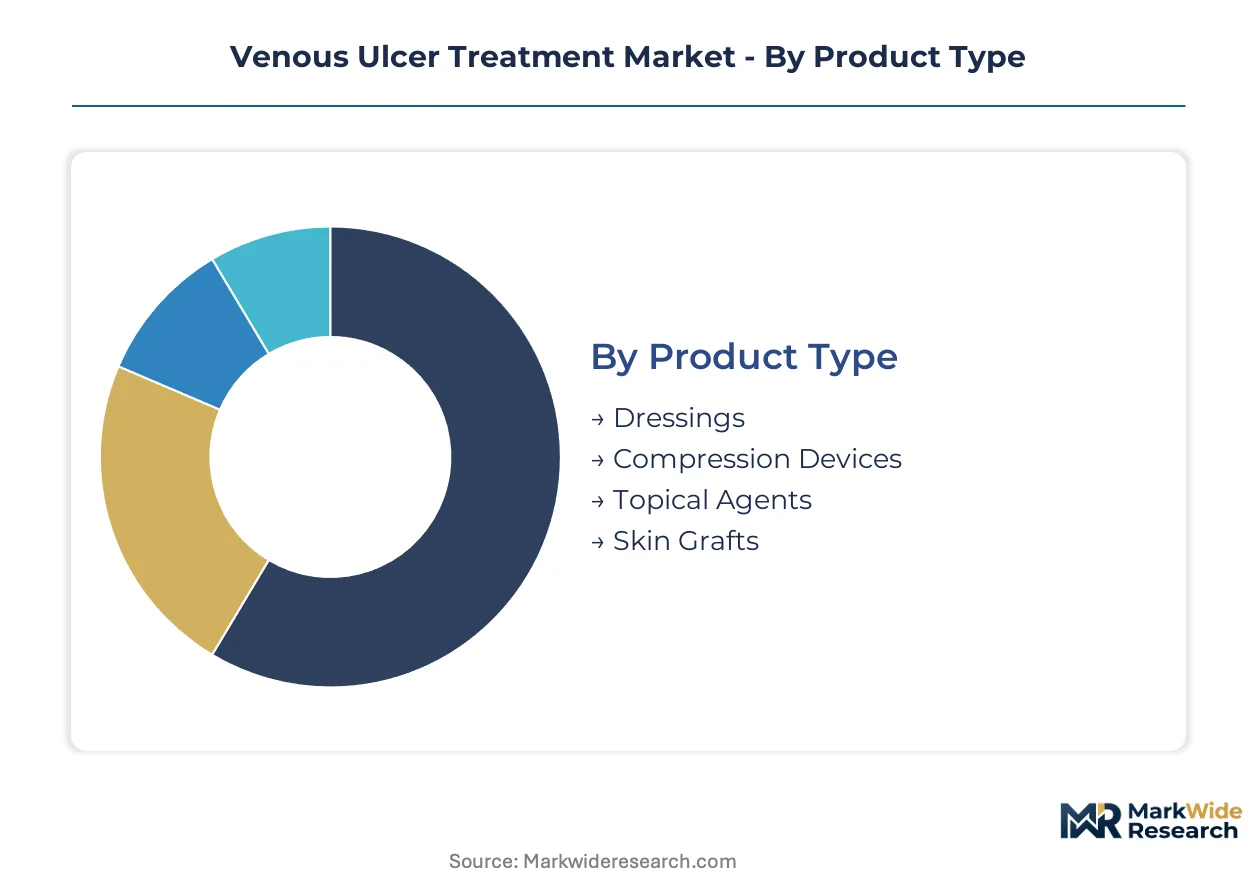
Venous ulcer treatment markets fragment across product technologies, care settings, and reimbursement pathways that shape commercial strategy. Understanding these segment boundaries clarifies where manufacturers compete on clinical evidence versus operational efficiency.
Product Type:
FDA 510(k) pathways govern advanced dressings in the United States, while EU MDR imposes strengthened clinical evidence requirements for compression device classifications that reshape competitive barriers.
- Dressings:Moisture-balancing formulations with hydrocolloid, alginate, or foam substrates manage exudate while protecting periwound skin. Demand concentrates in Medicare-funded long-term care networks where reimbursement favors cost-effective consumables over advanced interventions.
- Compression Devices:Graduated pressure systems delivering 20-40 mmHg through multilayer bandaging or pneumatic garments restore functional venous return. Germany's statutory health insurance framework creates predictable demand visibility through explicit coverage of multilayer systems.
- Topical Agents:Antimicrobial and growth factor preparations address bioburden and stalled healing in complex wounds.
- Skin Grafts:Bioengineered tissue technologies expand into previously non-healing chronic wounds with compromised vascular supply.
Established volume favors compression devices; emerging adoption favors skin grafts.
Application:
Reimbursement compression across Medicare Advantage networks is forcing wound care providers toward outpatient delivery models that reduce institutional bed days.
- Hospital Settings:Academic medical centers anchor advanced wound care protocols with specialized nursing certification requirements. Urban hospital systems concentrate certified wound care specialists, leaving rural markets structurally underserved.
- Home Healthcare:Durable medical equipment networks now support remote compression therapy monitoring through connected device integration. United States post-acute agencies deploy wearable pneumatic systems that miniaturize previously hospital-confined interventions.
- Clinics:Outpatient wound centers balance clinical throughput with value-based reimbursement constraints.
- Long-term Care Facilities:Skilled nursing facilities negotiate direct manufacturer agreements as group purchasing organizations lose exclusivity leverage under bundled payment pressures.
Hospital settings retain procedural complexity; home healthcare gains structural share through reimbursement shifts.
End User:
Procurement authority concentrates differently across stakeholder types, with payers increasingly dictating product selection through coverage determinations.
- Healthcare Providers:Physicians and wound care nurses drive protocol decisions where specialized certification creates purchasing influence.
- Patients:Cash-pay segments for compression garment replenishment enable direct-to-patient subscription models that bypass traditional durable medical equipment distributors.
- Caregivers:Family members managing home-based wound care require simplified application systems.
- Payers:Medicare Advantage plans and Germany's statutory health insurance framework shape demand through explicit coverage policies and health technology assessment thresholds.
Provider authority dominates clinical selection; payer authority dominates access determination.
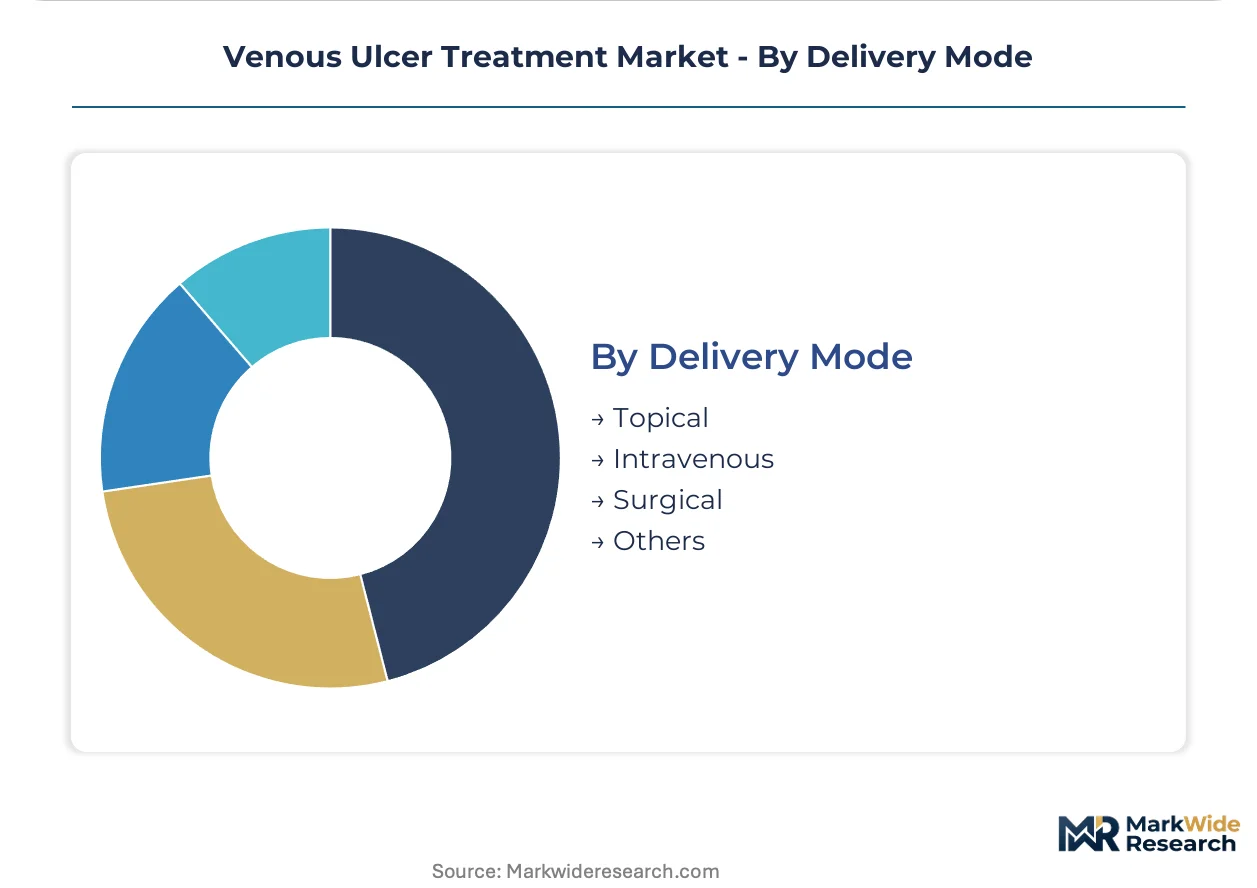
Delivery Mode:
Biological product cold chain complexity constrains distribution strategies for living tissue constructs that require temperature-controlled logistics.
- Topical:Surface-applied dressings, ointments, and compression systems constitute the majority of venous ulcer interventions with straightforward administration.
- Intravenous:Systemic therapies address underlying venous insufficiency or infection complications in complex cases.
- Surgical:Debridement and skin grafting procedures concentrate in hospital settings with specialized surgical capabilities.
- Others:Emerging cellular therapy combinations merge autologous cell harvest with synthetic scaffolds.
Topical delivery commands installed base; surgical delivery captures highest acuity cases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA governs advanced wound dressing introductions through 510(k) clearance pathways that anchor United States demand. Medicare-funded long-term care networks concentrate procurement authority across this geography. Germany's statutory health insurance framework creates divergent access patterns through explicit multilayer compression coverage.
United States
Medicare Advantage reimbursement compression forces outpatient wound management adoption over institutional bed days. FDA 510(k) pathways now require comparative clinical data that extends development timelines without expanding indications. Hospital purchasing committees in Medicare-funded long-term care networks unbundle consumables from bundled payment contracts.
Germany
Statutory health insurance explicit coverage of multilayer compression systems generates predictable demand visibility for device manufacturers. EU Medical Device Regulation strengthened clinical evidence requirements for compression device classifications in 2021. Berlin-Brandenburg medical device clusters face particular scrutiny for Class IIa compression system post-market surveillance submissions.
United Kingdom
NHS wound care pathway standardization drives protocol adoption across community nursing services. MHRA operates under retained EU MDR alignment with strengthened clinical evidence requirements for compression classifications. London and Southeast England academic medical centers concentrate certified wound care specialists leaving rural markets structurally underserved.
India
Tier-2 hospital networks present first-mover positioning for standardized compression protocol implementation. CDSCO medical device regulations govern advanced dressing introductions with evolving clinical evidence requirements. Maharashtra and Gujarat secondary cities concentrate underpenetrated demand as urban academic centers retain specialist nursing certification capacity.
Japan
PMDA governs bioengineered tissue product approvals with stringent quality management system requirements. METI healthcare technology assessment frameworks shape reimbursement for advanced wound care interventions. Kanto and Tokyo metropolitan clusters concentrate hospital-based wound care protocol development.
Venous Ulcer Treatment Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier that competes on clinical training ecosystems and certification partnerships. The upper tier controls direct-to-provider education programs that bypass traditional distributor channels. Mid-scale specialists anchor positions through regional nursing certification partnerships. Dominant competitive moves include strategic consolidation of training academy networks and geographic expansion into underpenetrated secondary hospital systems.
Within the integrated device-and-dressing tier, Smith & Nephew and Mölnlycke Health Care exemplify archetypes competing on clinician loyalty through specialized education infrastructure. Coloplast Corp. occupies a distinct position controlling nursing certification partnerships in European markets. These three entities represent contrasting strategic postures: training academy ownership, direct-to-provider channel investment, and certification partnership control.
| Leading Market Players |
|---|
| ConvaTec Group |
| Integra Lifesciences |
| Smith & Nephew |
| Medtronic Plc. |
| Bayer AG |
| 3M |
| Mölnlycke Health Care |
| Sanofi S.A |
| Coloplast Corp. |
| Others |
Value Network & Pricing Analysis
FDA 510(k) clearance pathways gate both manufacturer qualification and price differentiation across compression device and advanced dressing tiers, creating a dual-filter where clinical evidence investment simultaneously determines supply access and premium positioning. Germany's statutory health insurance framework adds a parallel gating mechanism through explicit multilayer compression coverage that segments pricing power by reimbursement tier.
Pricing Analysis
Long-term offtake contracts dominate hospital purchasing committee negotiations, particularly within Medicare-funded long-term care networks unbundling consumables from bundled payment arrangements. Three-tier pricing structure across premium, standard, and economy levels separates bioengineered skin substitutes from hydrocolloid dressings from basic gauze products, with certification grade and volume scale as primary differentiation drivers. Cost compression in standard-tier dressings is intensifying because petroleum-derived polymer feedstock volatility feeds through to hydrocarbon-based moisture barriers. Skilled nursing facilities exhibit highest price sensitivity due to bundled payment margin pressures, while academic medical centers show lowest sensitivity where clinical outcomes data commands premium positioning.
Supply Chain Analysis
Strategic stockpile preferences concentrate among distributors managing biological product cold chains, where temperature-controlled logistics for living tissue constructs necessitate buffer inventory against spoilage risk. Manufacturing concentration clusters in the United States for FDA-governed advanced dressings, Germany for multilayer compression systems, and Japan for bioengineered tissue platforms. Raw material dependencies draw from petroleum refineries for polymer substrates, cotton textile processors for compression bandages, and cell culture facilities for tissue engineering scaffolds. Single-source vulnerability runs through specialized nursing certification bottlenecks that constrain trained clinician availability for product application. Distribution runs through durable medical equipment networks for home healthcare segments and direct manufacturer agreements for hospital purchasing committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through hospital purchasing committee consolidation and Medicare Advantage network integration, fragmenting supplier leverage across fragmented long-term care procurement. Group purchasing organizations are losing exclusivity leverage as individual facilities negotiate direct agreements.
For Market Incumbents: Secure specialized nursing certification partnerships to lock in clinician loyalty against Mölnlycke Health Care's direct-to-provider education programs and Coloplast Corp.'s European certification control. Deepen backward integration into bioengineered tissue manufacturing to capture margin expansion in skin grafts, the fastest-expanding product category. Channel control through training academy ownership represents the critical defensive lever against emerging entrant price undercutting in standard dressing tiers. For New Entrants and Emerging Players: Differentiate on connected device integration for remote compression therapy monitoring, targeting United States home healthcare agencies deploying wearable pneumatic systems. India's Tier-2 hospital networks present the most penetrable geography for standardized compression protocol first-mover positioning. Direct-to-patient subscription models for compression garment replenishment offer a viable go-to-market angle bypassing traditional durable medical equipment distributor relationships in cash-pay segments. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across bioengineered tissue manufacturing as EU MDR post-market surveillance requirements extend development timelines and clinical evidence investment thresholds. Acquisition targets should prioritize mid-scale specialists with established notified body relationships and regional nursing certification partnerships rather than pure-play dressing manufacturers facing petroleum input cost volatility. The signal to watch is FDA 510(k) comparative clinical data requirements tightening further, which would accelerate consolidation among smaller advanced dressing developers unable to fund expanded evidence generation.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Smith & Nephew's training academies sustain clinician loyalty across integrated delivery networks. |
| CE Marking Pathway | EU MDR strengthened requirements reshape competitive barriers for Class IIa compression systems. |
| Reimbursement Strategy | Germany's statutory health insurance explicit coverage creates predictable demand visibility. |
| Software Companion Development | Connected compression devices transform passive intervention into data-generating care episodes. |
| Backward Integration | In-house bioengineered tissue production captures margin expansion in fastest-growing product tier. |
Research Methodology
The analysis maps compression devices, advanced dressings, bioengineered skin grafts, and topical agents, each validated through wound care nurses, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) filings, EU MDR notified body submissions, CMS Medicare reimbursement databases, and hospital procurement contract records. Bottom-up demand modeling across patient population segments triangulated with top-down market sizing from manufacturer revenue disclosures.
Consistency checks validated volume and value outputs against external benchmarks including health technology assessment body coverage determinations and statutory insurance framework expenditure reports. Segmentation dimensions modeled include product technology, care setting, reimbursement pathway, and delivery mode across the projection horizon. CAGRs derived from patient incidence trend analysis, procedure volume trajectories, and product mix shift assumptions. Industry-specific forecast inputs incorporated compression therapy protocol adoption curves and bioengineered tissue clinical evidence maturation timelines.
The analysis sits within stated boundaries; outcomes outside sustained Medicare reimbursement stability and EU MDR enforcement continuity would require recalibration. Forecasts reflect assumptions regarding certified wound care specialist workforce expansion rates and petroleum feedstock price normalization. Revision becomes warranted when FDA 510(k) evidence burden crosses thresholds that materially extend development timelines or when Germany's statutory health insurance framework modifies explicit compression coverage terms.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Wound Care Market
Wound Care
France Wound Care Market
Wound Care
Global Burn Care Market
Wound Care
Japan Wound Care Management Devices Market
Wound Care
Infectious Wound Care Management Market
Wound Care
Wound Biologics Market
Wound Care
Biopatches Market
Wound Care
Global Compression Bandages Market
Wound Care
Wound Healing Market
Wound Care
Asia Pacific Advanced Wound Care Market
Wound Care
US Wound Care Management Devices Market
Wound Care
Wound Debridement Products Market
Wound Care
Asia Pacific Negative Pressure Wound Therapy Market
Wound Care
Wound Healing Supplement Market
Wound Care
Foam Dressing Market
Wound Care
Wound Closure Market