
 Wound Care Sealants Market | 2026-2036
Wound Care Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
Wound Care Sealants Market Analytics
A capital-intensity divergence between integrated biologics manufacturers and specialty adhesive developers is rotating competitive advantage toward firms with captive plasma fractionation. Baxter International leverages its vertically sourced fibrinogen supply to sustain margin stability across hospital contracts. Medtronic anchors its position through broad surgical portfolio bundling, while Advanced Medical Solutions Group plc competes via focused R&D intensity in synthetic polymer platforms.
Wound care sealants comprise sterile, tissue-adhesive formulations—typically fibrin-based, synthetic polymer, or hybrid collagen matrices—that achieve hemostasis and wound closure without mechanical sutures, generally requiring activation times under two minutes and tensile strength sufficient to withstand physiological pressures at the application site. The product mix tilts toward biologic sealants in cardiothoracic and orthopedic surgery where autologous compatibility commands premium positioning, while synthetic polyethylene glycol variants gain procedural share in dermatology and ambulatory settings where storage stability and off-the-shelf availability reduce logistics burden. Application segmentation reveals general surgery as the mature volume base, with orthopedic surgery representing the fastest-expanding margin pool as sports medicine and joint reconstruction volumes rise across integrated delivery networks.
FDA 510(k) pathways and EMA Medical Device Regulation (MDR) compliance frameworks enforce biocompatibility, sterility assurance, and clinical efficacy thresholds that filter market access and elevate quality-system investments for new entrants. ISO 10993 biological evaluation standards further delineate acceptable cytotoxicity and sensitization profiles, effectively segmenting approved products from developmental candidates. Stakeholders must monitor evolving reimbursement coding for sealant-assisted closure procedures and assess synthetic platform patent cliffs to time portfolio transitions.
Market Dynamics
FDA and EMA tightening of hemostasis performance standards is compressing approval timelines for new entrants while elevating quality-system investments, concentrating procurement power among vertically integrated biologics manufacturers with captive plasma fractionation capabilities.
Growth Catalysts
- Aging Demographics:Japan, Germany, and the United States face expanding chronic wound incidence as populations over 65 require surgical intervention, driving hospital demand for advanced sealant technologies with rapid activation profiles.
- ISO 10993 Standards:Biological evaluation protocols for cytotoxicity and sensitization now filter substandard candidates, creating quality-tier differentiation that rewards firms with validated sterilization assurance and clinical efficacy documentation.
- Synthetic Polymer Platforms:Polyethylene glycol formulations gain procedural share in dermatology and ambulatory settings where extended storage stability and off-the-shelf availability reduce cold-chain logistics burden versus biologic alternatives.
Market Restraints
- Plasma Fractionation Concentration:Fibrinogen supply depends on a limited network of fractionators, exposing margin stability to raw material volatility and geographic concentration in North American and European processing facilities.
- EMA MDR Compliance Burden:Medical Device Regulation frameworks enforce biocompatibility and sterility thresholds that extend certification timelines and elevate documentation costs for developmental-stage sealant candidates.
- Mechanical Suture Substitution:Conventional closure methods retain cost advantage in price-sensitive healthcare systems, limiting sealant penetration in emerging markets and routine procedural categories.
Strategic Opportunities
- Orthopedic Surgery Expansion:Sports medicine and joint reconstruction volumes across integrated delivery networks represent underpenetrated margin pools where biologic sealant compatibility commands premium positioning.
- Hybrid Collagen Matrices:Convergence of fibrin-based and synthetic polymer technologies enables tailored activation profiles for specific tissue types, opening customization revenue streams beyond standard formulations.
- Reimbursement Coding Evolution:Sealant-assisted closure procedures in the United States and Germany are gaining dedicated billing codes that reduce procurement friction and accelerate hospital formulary adoption.
Industry Challenges
- Biologics Manufacturing Talent Scarcity:Plasma-derived product expertise remains concentrated among legacy fractionators, constraining scale-up capabilities for synthetic platform specialists seeking backward integration.
- Patent Cliff Navigation:Synthetic polymer patent expirations require portfolio transition timing to preserve margin structures as generic competitors enter polyethylene glycol formulation markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wound Care Sealants Market |
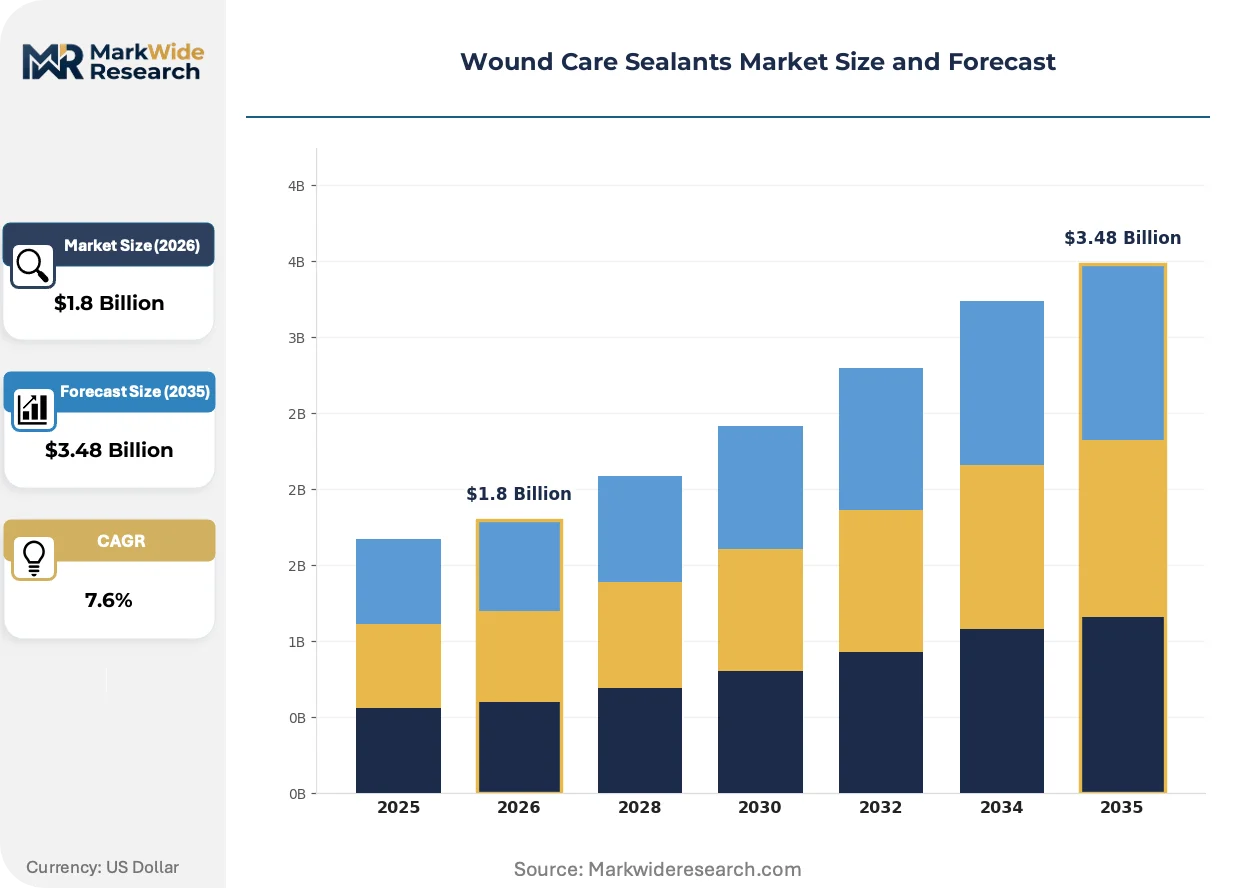
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biologic Sealants, Synthetic Sealants, Fibrin Sealants, Surgical Adhesives Application: Dermatology, General Surgery, Orthopedic Surgery, Cardiothoracic Surgery End User: Hospitals, Clinics, Ambulatory Surgical Centers, Home Care Material: C fibrin, Polyethylene Glycol, Collagen, Albumin |
| Companies Covered | Johnson & Johnson (Ethicon), Baxter International, BD, Integra LifeSciences Corporation, Medtronic, Advanced Medical Solutions Group plc, Terumo Corporation, Cohera Medical, LifeBond, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wound Care Sealants Market Evolving Landscape
Technology convergence between biologic and synthetic platforms is fragmenting traditional product categories, while regulatory harmonization efforts and procurement centralization reshape competitive positioning across hospital networks.
Hybrid collagen-fibrin matrices are decomposing the historical binary between biologic and synthetic sealants. Cardiothoracic surgical teams in tertiary hospitals are adopting these platforms for their tunable degradation rates and tissue-specific adhesion profiles. The technology is decomposing standardization assumptions that previously separated premium biologic positioning from economy synthetic alternatives.
EMA Medical Device Regulation implementation is compressing market access for non-compliant manufacturers. Clinical efficacy documentation requirements now mandate extended follow-up data that smaller developers struggle to generate, filtering the competitive landscape toward established quality-system operators. Orthopedic and general surgery segments in Germany and France are responding by consolidating supplier relationships around pre-validated platform technologies.
Hospital procurement centralization is consolidating purchasing authority within integrated delivery networks. Group purchasing organizations in the United States are unbundling after-sales service from product pricing, pressuring manufacturers to compete on transparent cost-per-procedure metrics. This behavioral shift is most visible in ambulatory surgery centers where volume scale and standardization priorities override individual surgeon preference.
Wound Care Sealants Market Segmentation
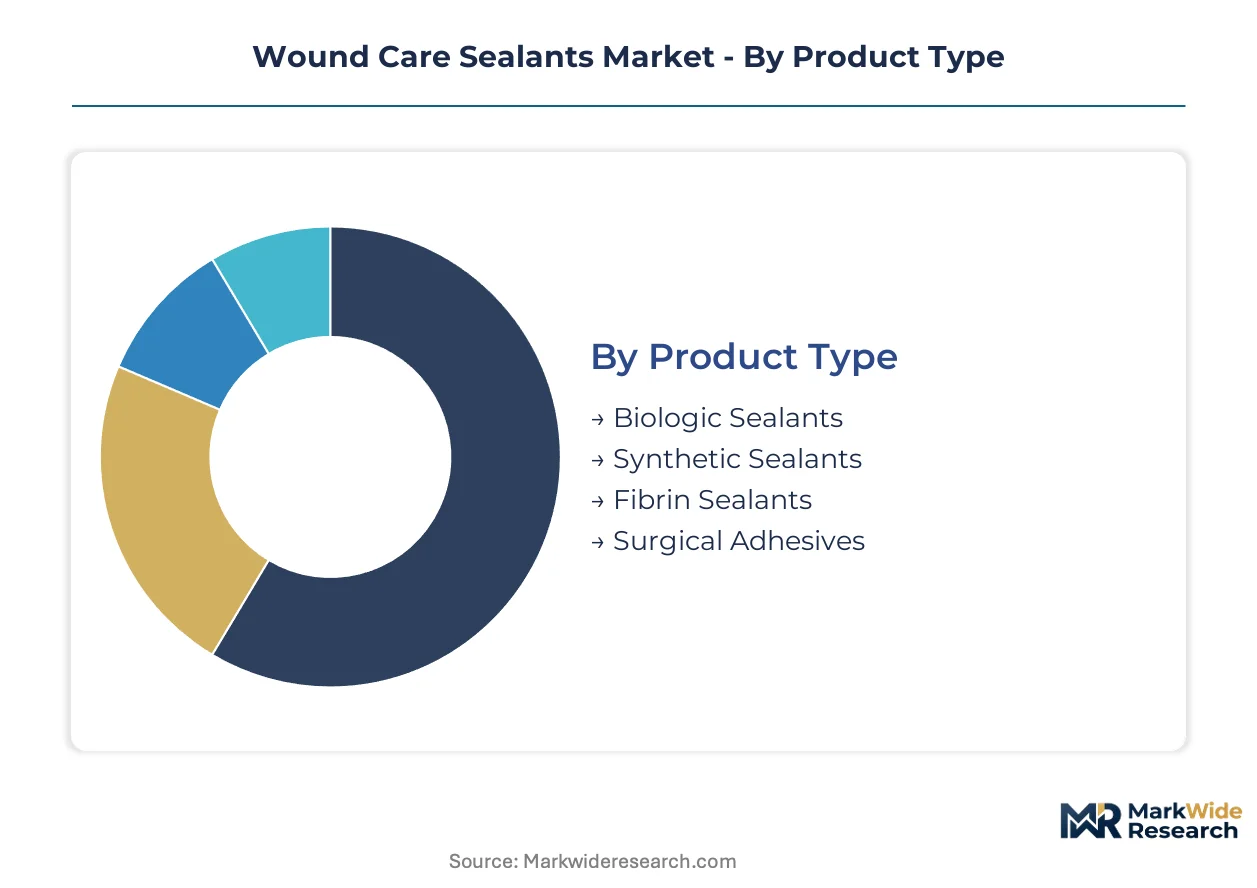
Wound care sealant procurement fragments across four distinct taxonomies—product chemistry, surgical application, care setting, and base material—each governing reimbursement codes, storage protocols, and margin capture differently. Hospital formulary committees weight these dimensions against activation speed, tensile performance, and cold-chain requirements when tiering vendor contracts.
Product Type:
Margin pools concentrate in biologic platforms where plasma fractionation barriers protect pricing power, while synthetic alternatives compete on logistics efficiency.
- Biologic Sealants:Plasma-derived formulations containing fibrinogen and thrombin command premium positioning in cardiothoracic and vascular procedures. United States hospital procurement of these sealants is accelerating as FDA tightens hemostasis performance standards and surgeons prioritize autologous compatibility in high-risk patients.
- Synthetic Sealants:Polymer-based platforms eliminate cold-chain dependencies and extend shelf stability. Germany's ambulatory surgery centers are rotating procurement toward these alternatives where storage simplicity and off-the-shelf availability reduce operational burden.
- Fibrin Sealants:Dual-component systems requiring mixing before application.
- Surgical Adhesives:Cyanoacrylate and similar bonding agents for superficial wound closure.
Biologic sealants hold installed capacity. Synthetic sealants are rotating up the share rankings.
Application:
Volume concentration sits in general surgery, though orthopedic procedures generate superior per-procedure economics.
- Orthopedic Surgery:Sports medicine and joint reconstruction applications demand sealants with load-bearing adhesion and controlled degradation. Integrated delivery networks in Japan are expanding formulary access for these products as aging populations drive arthroscopy volumes and reimbursement shifts toward value-based procedural bundles.
- General Surgery:Broad abdominal and soft-tissue procedures constitute the mature volume base. Hospital procurement in the United States treats these applications as cost-center commodities, pressuring manufacturers toward transparent cost-per-procedure metrics.
- Dermatology:Outpatient cosmetic and reconstructive procedures favor rapid-setting formulations.
- Cardiothoracic Surgery:Sternal closure and vascular anastomosis require premium biologic compatibility.
General surgery maintains procedure volume leadership. Orthopedic surgery is climbing the fastest toward margin parity.
End User:
Procurement authority is consolidating within integrated delivery networks, altering vendor access patterns across care settings.
- Hospitals:Tertiary and community facilities with centralized purchasing negotiate multi-year contracts bundling sealants across surgical service lines. EMA MDR compliance requirements in Germany and France are filtering supplier relationships toward established quality-system operators with validated sterilization documentation.
- Ambulatory Surgical Centers:Freestanding facilities prioritize storage-stable synthetic platforms and simplified inventory management. Group purchasing organizations in the United States are unbundling after-sales service from product pricing at these sites.
- Clinics:Office-based procedural settings with limited surgical volume.
- Home Care:Post-acute and chronic wound management applications.
Hospitals anchor procurement volume. Ambulatory surgical centers are gaining share fastest in synthetic platform adoption.
Material:
Supply concentration in plasma-derived inputs shapes cost structures differently than petrochemical or collagen supply chains.
- Fibrin:Plasma-sourced fibrinogen combined with thrombin creates the clinical gold standard for hemostasis speed. North American and European fractionation facility concentration exposes margin stability to raw material geography and donor plasma availability constraints.
- Polyethylene Glycol:Synthetic polymer platforms enable tunable degradation rates without biological sourcing. Patent cliffs approaching for foundational PEG formulations require portfolio transition timing to preserve margin structures.
- Collagen:Bovine, porcine, or recombinant structural proteins.
- Albumin:Plasma-derived or recombinant carrier proteins.
Fibrin maintains clinical preference in high-acuity settings. Polyethylene glycol is expanding most quickly into ambulatory and dermatology applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The wound care sealants market runs a structural trade surplus in plasma-derived biologics, with the United States and Germany exporting fractionated fibrinogen while Japan and emerging manufacturing hubs import synthetic polymer intermediates for local formulation.
United States
FDA tightening of 510(k) hemostasis standards is accelerating hospital procurement of validated biologic sealants. The agency's sterility assurance requirements filter substandard candidates from formulary access. Boston and Minneapolis medical device clusters concentrate contract manufacturing for plasma-derived platforms serving integrated delivery networks.
Germany
EMA MDR compliance frameworks extend certification timelines for developmental sealant candidates, concentrating procurement around established quality-system operators. The country's aging population drives chronic wound incidence requiring surgical intervention. Frankfurt and Munich house the European headquarters of major fractionators managing fibrinogen supply across hospital networks.
Japan
PMDA oversight of biological evaluation standards shapes market access for imported sealant technologies. METI programs support domestic synthetic polymer development to reduce cold-chain dependencies. Osaka and Tokyo medical centers anchor demand as sports medicine and joint reconstruction volumes expand among aging demographics.
United Kingdom
MHRA post-Brexit regulatory autonomy is converging toward FDA and EMA standards for biocompatibility documentation. NHS procurement centralization pressures manufacturers toward transparent cost-per-procedure metrics. Cambridge and Oxford research clusters advance hybrid collagen-fibrin matrix development for orthopedic applications.
Switzerland
Swissmedic's stringent sterility thresholds elevate quality-system investments for market entry. The country's precision manufacturing base supports specialty adhesive formulation for export markets. Basel and Zurich concentrate pharmaceutical packaging and sterilization infrastructure serving European hospital networks.
Wound Care Sealants Market Competitive Landscape
Concentration sits with vertically integrated biologics manufacturers possessing captive plasma fractionation capabilities. Three to four legacy fractionators control fibrinogen supply chains, while synthetic polymer specialists compete on logistics efficiency and patent-protected formulation. Strategic moves center on backward integration into raw material sourcing and portfolio diversification across biologic-synthetic hybrid platforms.
Among diversified healthcare conglomerates, Johnson & Johnson and Baxter International exemplify the integrated biologics archetype with upstream control over plasma-derived inputs. Medtronic represents the surgical portfolio bundling approach, leveraging broad device relationships to secure sealant formulary placement. Advanced Medical Solutions Group plc occupies a position within the focused R&D intensity tier, competing through synthetic polymer platform specialization rather than vertical supply chain ownership.
| Leading Market Players |
|---|
| Johnson & Johnson (Ethicon) |
| Baxter International |
| BD |
| Integra LifeSciences Corporation |
| Medtronic |
| Advanced Medical Solutions Group plc |
| Terumo Corporation |
| Cohera Medical |
| LifeBond |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day cold-chain inventory cycles for plasma-derived fibrinogen concentrate procurement power in the hands of North American and European fractionators, while synthetic polyethylene glycol alternatives bypass temperature-controlled logistics entirely. This lead-time divergence separates biologic sealant premiums from synthetic platform cost efficiency across hospital formulary tiers.
Pricing Analysis
Configured-to-order pricing for patient-specific fibrin sealants commands substantial premiums over standard synthetic formulations. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 10993 certification grade and activation speed performance. Cost compression in economy synthetic tiers is intensifying because group purchasing organizations unbundle after-sales service from product pricing. Ambulatory surgery centers exhibit highest price sensitivity, while cardiothoracic surgical units in tertiary hospitals demonstrate lowest sensitivity due to autologous compatibility requirements.
Supply Chain Analysis
Port congestion on trans-Atlantic pharmaceutical lanes elevates inbound logistics costs for European-sourced thrombin components entering United States manufacturing facilities. Plasma fractionation capacity concentrates in the United States, Germany, and Switzerland, drawing from donor plasma, recombinant thrombin, and synthetic polymer intermediates. Single-source vulnerability in fibrinogen supply exposes margin stability to geographic concentration of fractionation infrastructure. Distribution runs through hospital group purchasing organizations and integrated delivery network central warehouses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wound care sealants sit in early-cycle expansion as hybrid collagen-fibrin matrices decompose traditional biologic-synthetic boundaries and drive replacement demand across orthopedic service lines.
For Market Incumbents: Shield margin structures in biologic platforms by securing captive plasma fractionation agreements before raw material volatility intensifies. Deepen backward integration into thrombin sourcing and accelerate sterilization assurance investments to satisfy FDA 510(k) pathway tightening. Synthetic platform specialists threaten premium positioning through logistics efficiency and patent-protected formulation. For New Entrants and Emerging Players: FDA 510(k) fast-track designation for synthetic polymer platforms with tunable degradation profiles opens immediate market access. Target ambulatory surgery centers in Germany and United States dermatology clinics where storage-stable formulations reduce cold-chain burden. Pursue hospital formulary placement through transparent cost-per-procedure metrics and unbundled service pricing. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified healthcare conglomerates with underoptimized sealant portfolios lacking vertical fibrinogen control. Long-term viability centers on hybrid platform capabilities spanning biologic compatibility and synthetic logistics efficiency. Watch for reimbursement coding evolution in United States and Germany as inflection signal for accelerated hospital adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Fractionation Backward Integration | Captive fibrinogen supply secures margin stability against raw material volatility across hospital contracts. |
| Hybrid Collagen-Fibrin Matrix Development | Tunable degradation rates open orthopedic surgery revenue streams beyond standard formulation categories. |
| FDA 510(k) Pathway Advancement | Accelerated sterility assurance validation filters substandard competitors from formulary access. |
| Hospital System Partnership | Integrated delivery network bundling secures multi-year contracts across surgical service lines. |
| Reimbursement Strategy Implementation | Dedicated billing codes for sealant-assisted closure reduce procurement friction in United States markets. |
Research Methodology
A standing panel of hospital procurement managers, biomedical engineers, GPO contracts specialists, and regulatory affairs directors provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA 510(k) filings, EMA MDR compliance databases, hospital procurement records, and CMS reimbursement coding updates. Bottom-up procedure volume modeling and top-down plasma fractionation capacity analysis enabled triangulation of market sizing estimates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product chemistry class, surgical application category, care setting tier, and base material type. CAGRs derived from procedure volume elasticity to demographic aging patterns and reimbursement policy shifts. Forecast inputs incorporated ISO 10993 biological evaluation standard evolution and synthetic polymer patent cliff timing.
Decision-makers should treat outputs as directional under base assumptions of stable regulatory frameworks and continued hospital procurement centralization; material deviation would warrant model refresh. Specific risk factors include EMA MDR implementation delays, plasma donor availability shocks, and mechanical suture substitution resistance in price-sensitive healthcare systems. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Wound Closure Market
Wound Care
Next Generation Wound Closure Device Market
Wound Care
Brazil Wound Care Management Devices Market
Wound Care
Surgical Wound Care Market
Wound Care
Acute Wound Care Market
Wound Care
Advanced Wound Care and Dressings Market
Wound Care
Global Burn Care Market
Wound Care
Global Negative Pressure Wound Therapy (NPWT) Devices Market
Wound Care
Antimicrobial Regenerative Wound Matrix Market
Wound Care
Collagen Dressings Market
Wound Care
Wound Closure and Advanced Wound Care Market
Wound Care
Global Surgical Drains/Wound Drainage Market
Wound Care
US Burn Care Centers Market
Wound Care
Interactive Wound Dressing Market
Wound Care
Wound Care Biologics Market
Wound Care
Enzymatic Wound Debridement Market