
 LAMEA Surgical Dressing Market | 2026-2036
LAMEA Surgical Dressing Market Size, Share, and Industry Trends Forecast 2026-2036
LAMEA Surgical Dressing Market Insights
ISO 13485 certification is redrawing competitive boundaries across the LAMEA Surgical Dressing Market. Smith & Nephew PLC leverages its quality management depth to sustain hospital contracts in Saudi Arabia and the UAE. Molnlycke Health Care AB anchors its regional position through specialized foam and silicone portfolios. Cardinal Health, Inc. competes on distribution scale, controlling supply routes into sub-Saharan African markets.
Surgical dressings comprise sterile barrier materials engineered from polyurethane films, hydrocolloid matrices, or alginate fibers designed to manage exudate, prevent infection, and promote wound closure following operative procedures. Foam dressings dominate current volume due to their absorption capacity across high-exudate surgical sites, while silicone-based variants command premium positioning in burn treatment and grafting applications where atraumatic removal reduces tissue disruption. Hospitals remain the structural anchor by end user, though home healthcare channels are expanding fastest as post-acute protocols shift toward outpatient recovery models.
Brazil's ANVISA, South Africa's national health regulator, and Saudi Arabia's SFDA enforce divergent sterilization and biocompatibility standards that fragment product registration pathways across LAMEA. These frameworks compel manufacturers to maintain multiple quality dossiers, raising compliance costs but also creating defensive moats for firms with established regulatory infrastructure. Stakeholders must monitor convergence between national medical device frameworks and the EU MDR reference standards to anticipate future harmonization shifts.
Market Dynamics
ISO 13485 certification requirements are restructuring supplier eligibility across LAMEA surgical dressing procurement, forcing manufacturers to rebuild quality management infrastructure or exit hospital tender pools entirely. This regulatory filter favors incumbent players with established documentation systems while raising capital barriers for new entrants.
Growth Catalysts
- Advanced wound care protocols:Tertiary hospitals in Brazil and South Africa are mandating antimicrobial and moisture-retentive dressings for post-operative recovery, expanding addressable volume in high-acuity settings.
- SFDA regulatory modernization:Saudi Arabia's streamlined medical device registration pathways are compressing product approval timelines from 18 months to under 12 months for ISO-certified manufacturers.
- Silicone adhesive chemistry:Atraumatic removal properties in burn and graft applications are commanding premium positioning as clinicians prioritize patient comfort metrics in quality assessments.
Market Restraints
- Petrochemical feedstock volatility:Polyurethane and silicone raw material costs fluctuate with crude oil indices, compressing margin predictability for film and foam dressing producers.
- Single-source sterilization infrastructure:Gamma irradiation capacity concentrates in South Africa and the UAE, creating supply bottlenecks for manufacturers serving East African markets.
- ANVISA biocompatibility testing requirements:Brazil's extended cytotoxicity and sensitization study mandates add 8-14 months to product registration compared with regional peers.
Strategic Opportunities
- Home healthcare channel expansion:Post-acute recovery protocols in the UAE and Saudi Arabia are shifting surgical wound management to outpatient settings, opening direct-to-patient distribution models.
- Egyptian manufacturing zones:Underutilized production capacity near Cairo offers tariff-advantaged export positioning into sub-Saharan African markets with limited local dressing manufacturing.
- EU MDR alignment incentives:South African regulators are signaling future harmonization with European Medical Device Regulation standards, rewarding early dossier preparation with accelerated future approvals.
Industry Challenges
- Multinational quality auditor scarcity:ISO 13485 lead assessor availability is constrained across the Middle East, extending certification renewal cycles and audit backlogs.
- Legacy ERP integration:Hospital procurement systems in Nigeria and Kenya require manual bridging to electronic inventory platforms, complicating vendor-managed replenishment programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LAMEA Surgical Dressing Market |
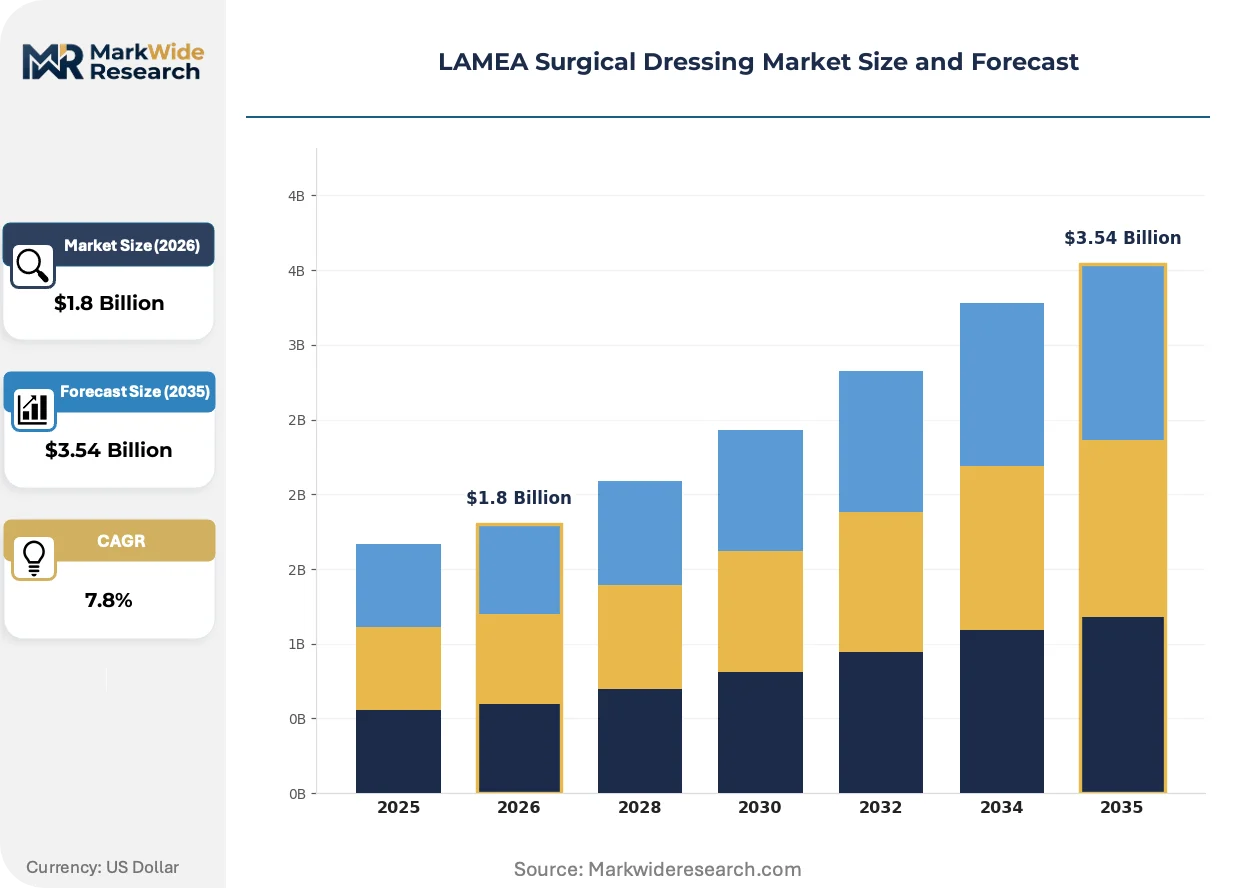
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.54 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Film Dressings, Foam Dressings, Hydrocolloid Dressings, Alginate Dressings End User: Hospitals, Clinics, Home Healthcare, Long-term Care Facilities Application: Wound Care, Surgical Procedures, Grafting, Burn Treatment Material: Polyester, Cotton, Polyurethane, Silicone |
| Companies Covered | 3M Company, Smith & Nephew PLC, Molnlycke Health Care AB, Convatec, Inc., Johnson & Johnson, Coloplast Group, Cardinal Health, Inc., B. Braun SE, Essity Aktiebolag, Others |
| Regions Covered | LAMEA: Brazil, Mexico, Argentina, Saudi Arabia, UAE, South Africa, Nigeria, Egypt, Rest of LAMEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LAMEA Surgical Dressing Market Trends and Innovations
Antimicrobial integration and smart exudate monitoring are redefining performance benchmarks in LAMEA surgical dressing procurement, with buyers prioritizing infection prevention metrics over unit cost in tender evaluations.
Silver-ion and PHMB-impregnated foam dressings are supplanting standard absorbent variants in high-risk surgical sites across tertiary hospitals in Saudi Arabia and the UAE. Burn centers and orthopedic wards are adopting these antimicrobial formats fastest, with procurement committees now mandating bacterial log-reduction documentation in technical specifications. This shift is compressing demand for commodity foam while expanding premium contract values for certified antimicrobial suppliers.
ANVISA's 2023 updated medical device guidance documents are forcing manufacturers to submit pyrogenicity and hemocompatibility data for all wound-contacting layers, not merely primary dressings. This regulatory expansion is diverting R&D resources toward comprehensive biocompatibility testing suites. Brazilian contract manufacturers are responding by partnering with São Paulo-based testing laboratories to build in-house toxicology capabilities rather than outsourcing to European facilities.
Hospital group purchasing organizations in South Africa are consolidating supplier rosters from twelve to four preferred vendors per dressing category, compressing switching flexibility for procurement officers. This concentration is displacing fragmented distributor networks with direct manufacturer agreements backed by consignment inventory guarantees. The Western Cape and Gauteng provinces are exhibiting this pattern most acutely, with Netcare and Life Healthcare chains leading the consolidation push.
LAMEA Surgical Dressing Market Segmentation
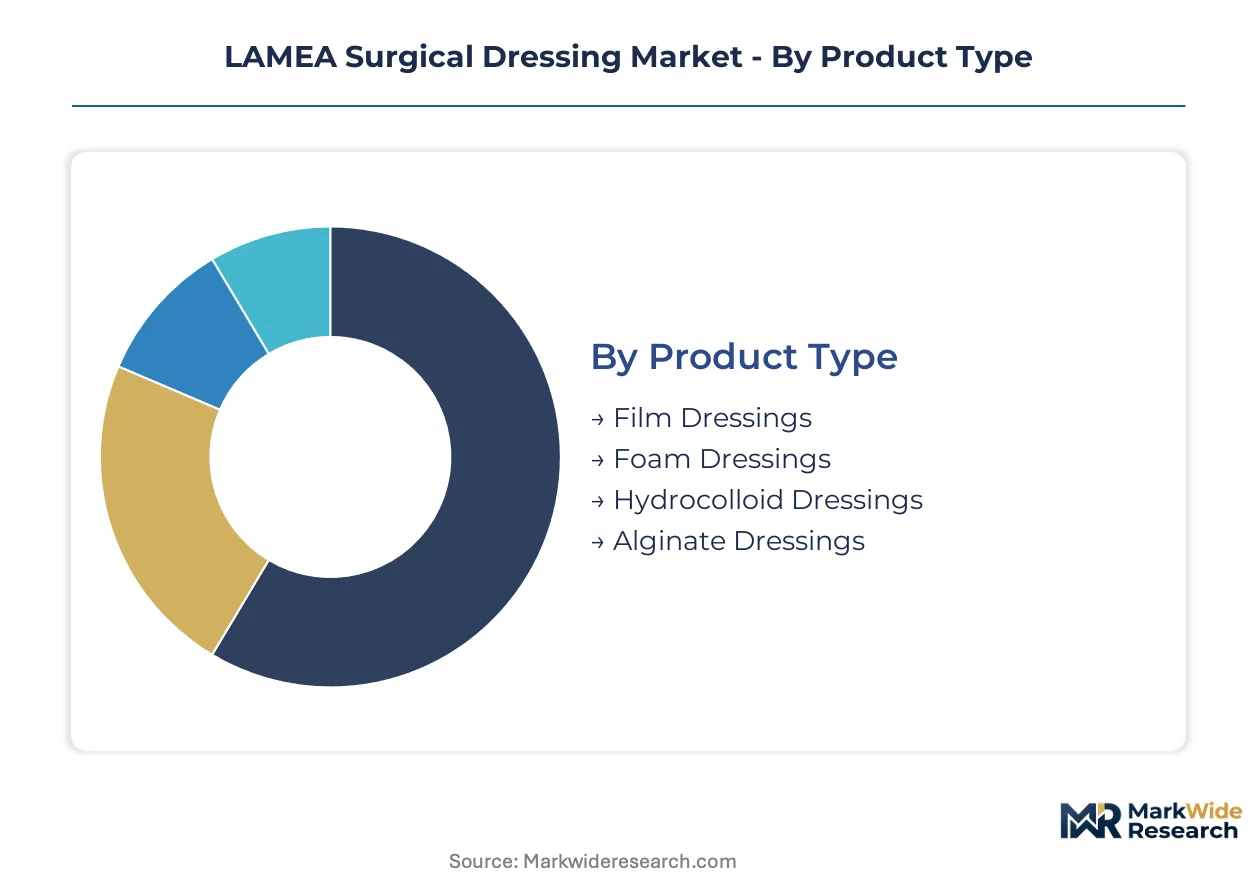
Surgical dressing procurement across Latin America, the Middle East, and Africa fragments along product performance tiers, care setting infrastructure, and material chemistry specifications. Understanding these segment boundaries reveals where antimicrobial premiums command pricing power versus where commodity absorption drives volume.
Product Type:
Foam and film variants face acute substitution pressure from advanced antimicrobial formats as Saudi and South African tertiary hospitals rewrite technical specifications.
- Foam Dressings:Open-cell polyurethane structures manage high-exudate surgical sites through vertical wicking channels. Brazilian tertiary centers anchor volume demand as post-operative protocols mandate extended wear times without maceration.
- Film Dressings:Semi-permeable polyurethane membranes provide bacterial barriers while permitting moisture vapor transmission. Burn units in the UAE prefer transparent formats for graft monitoring, though silicone alternatives are displacing standard films in premium contracts.
- Hydrocolloid Dressings:Carboxymethylcellulose-based gels form cohesive wound contact layers; Kenyan district hospitals source these for pressure ulcer management where advanced foam stocks prove cost-prohibitive.
- Alginate Dressings:Calcium-sodium fiber mats derived from brown seaweed absorb via ion exchange; Egyptian importers distribute these for diabetic foot clinics serving Cairo and Alexandria.
Foam dressings anchor the volume base while silicone-integrated variants gain share at the steepest rate as atraumatic removal protocols spread through Gulf Cooperation Council burn centers.
End User:
Procurement authority concentrates differently across settings, with hospital group purchasing organizations wielding pricing leverage that fragmented clinic networks cannot replicate.
- Hospitals:Tertiary and secondary acute care facilities with centralized sterilization infrastructure. South Africa's Netcare and Life Healthcare chains negotiate direct manufacturer agreements backed by consignment inventory guarantees.
- Clinics:Outpatient surgical and wound care facilities with limited storage capacity. Nigerian private clinic networks rely on distributor credit terms rather than volume discounts.
- Home Healthcare:Post-acute recovery services managing surgical wound closure outside institutional settings. Saudi home nursing agencies are expanding fastest as SFDA streamlines reimbursement for outpatient dressing protocols.
- Long-term Care Facilities:Chronic wound management in nursing homes and rehabilitation centers. Brazil's expanding geriatric care infrastructure drives alginate demand for pressure injury prevention.
Hospitals dominate current procurement value while home healthcare channels expand most quickly as Gulf health systems shift recovery outside institutional walls.
Application:
Clinical outcome requirements vary sharply between elective surgical sites and trauma-heavy burn wards, fragmenting product qualification pathways.
- Wound Care:General post-operative and chronic wound management across all care settings. South African public hospital procurement prioritizes absorption capacity over antimicrobial features in budget-constrained tenders.
- Surgical Procedures:Incision site protection following operative intervention. Brazilian ANVISA mandates biocompatibility documentation for all wound-contacting layers, extending registration timelines for foreign suppliers.
- Grafting:Skin graft donor and recipient site management requiring atraumatic removal. UAE burn centers specify silicone adhesive chemistry to prevent graft disruption during dressing changes.
- Burn Treatment:Partial and full-thickness thermal injury management with infection prevention priorities. Saudi tertiary burn units are mandating silver-ion impregnation in technical specifications.
Wound care anchors the volume base while burn treatment applications gain share at the steepest rate as infection metrics displace unit cost in tender evaluations.
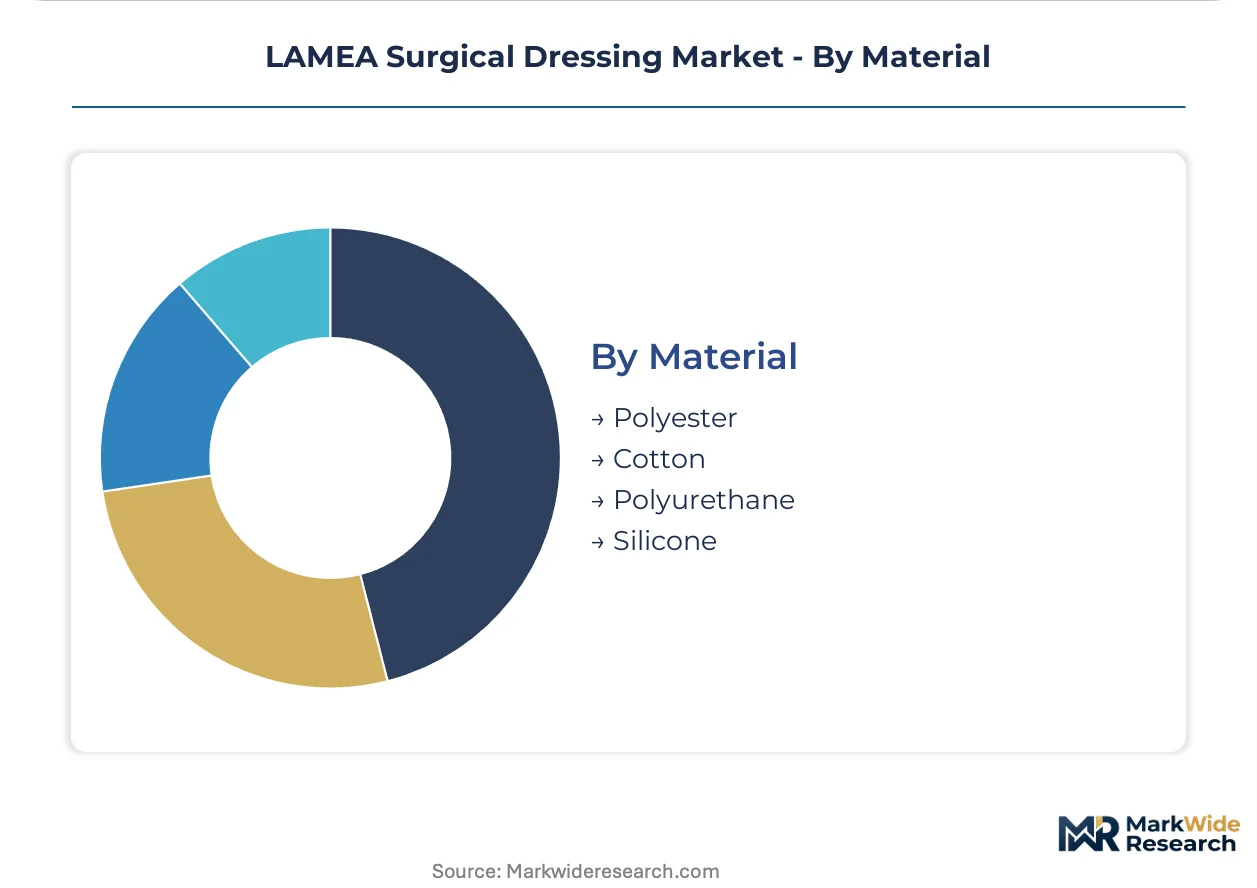
Material:
Petrochemical feedstock volatility creates divergent margin stability across synthetic and natural fiber supply chains.
- Polyurethane:Thermoplastic polymer forming film barriers and foam matrices. Film and foam producers face margin compression when crude indices spike, though Saudi petrochemical integration offers regional cost advantages.
- Silicone:Medical-grade elastomers enabling gentle adhesion and atraumatic removal. Premium positioning in graft and burn applications commands pricing power despite higher raw material costs.
- Polyester:Synthetic fiber woven or non-woven into backing layers and absorbent pads. Egyptian textile manufacturers supply regional converters with tariff-advantaged feedstock.
- Cotton:Natural cellulose fiber for traditional gauze and absorbent substrates. Nigerian and Kenyan procurement still specifies cotton for basic wound coverage where advanced synthetics remain cost-prohibitive.
Polyurethane anchors the volume base while silicone gains share at the steepest rate as clinician comfort metrics reshape quality assessments in Gulf tertiary centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Suez Canal Authority's medical logistics corridor underwrites Egypt's emergence as a distribution hub for surgical dressings entering sub-Saharan African markets. Port Said and Alexandria container terminals handle sterilized dressing shipments from European and Asian manufacturers, with bonded warehousing reducing transit times to East African hospital systems.
Brazil
Tertiary hospital construction in São Paulo and Rio de Janeiro drives antimicrobial dressing procurement as Netcare-equivalent chains expand post-operative protocols. ANVISA's 2023 biocompatibility guidance extends registration timelines, diverting foreign suppliers toward São Paulo-based contract manufacturers with in-house toxicology capabilities. The Campinas medical device cluster hosts Brazilian converters partnering with European raw material suppliers.
Saudi Arabia
SFDA's streamlined registration pathways compress approval cycles for ISO-certified manufacturers, accelerating product entry into Riyadh and Jeddah hospital systems. Burn center expansion in the Eastern Province mandates silver-ion dressing specifications, displacing standard foam in premium tenders. King Faisal Specialist Hospital contracts anchor demand for silicone-adhesive formats in graft management.
South Africa
Netcare and Life Healthcare group purchasing organizations consolidate supplier rosters from twelve to four vendors per dressing category, concentrating procurement leverage in Gauteng and Western Cape provinces. Public hospital budgets prioritize absorption capacity over antimicrobial features, creating dual-tier demand segmentation. The Durban pharmaceutical manufacturing zone offers underutilized sterilization capacity for regional exporters.
United Arab Emirates
Dubai Healthcare City's specialty burn units specify transparent film dressings for graft monitoring, while Abu Dhabi hospital networks shift post-acute protocols toward home healthcare channels. MOHAP's medical device registration alignment with international standards rewards early dossier preparation with accelerated approvals. Jebel Ali free zone warehousing supports Gulf Cooperation Council distribution.
LAMEA Surgical Dressing Market Competitive Landscape
Listed leaders compete with private specialists across quality certification depth, with publicly traded manufacturers leveraging balance sheet capacity to sustain multi-year hospital contracts while privately held firms exploit niche antimicrobial formulations. The supplier base exhibits tiered concentration: multinational incumbents with established ISO 13485 documentation systems, regional converters with tariff-advantaged manufacturing positions, and specialty importers serving fragmented clinic networks. Strategic moves center on regulatory dossier expansion and direct procurement agreements that displace distributor intermediaries.
Within the multinational incumbent tier, Smith & Nephew PLC and Molnlycke Health Care AB exemplify quality management depth that sustains Gulf hospital contracts, while Cardinal Health, Inc. anchors distribution scale into sub-Saharan African markets. These three occupy positions defined by certification infrastructure rather than product differentiation alone.
| Leading Market Players |
|---|
| 3M Company |
| Smith & Nephew PLC |
| Molnlycke Health Care AB |
| Convatec, Inc. |
| Johnson & Johnson |
| Coloplast Group |
| Cardinal Health, Inc. |
| B. Braun SE |
| Essity Aktiebolag |
| Others |
Pricing and Supply Chain Analysis
Silver-ion impregnation displacing standard foam formats is redrawing procurement economics across LAMEA surgical dressing markets, simultaneously concentrating supply in ISO-certified manufacturing zones and compressing margin structures for commodity converters unable to absorb biocompatibility testing costs.
Pricing Analysis
Certification level creates the primary spread between premium silicone-adhesive formats and economy cotton-gauze alternatives. Pricing stratifies across antimicrobial-integrated, standard synthetic, and basic natural fiber tiers, with SFDA and ANVISA documentation depth determining hospital contract eligibility. Cost compression in commodity foam segments is intensifying because Brazilian and South African public tenders prioritize absorption capacity over advanced features. Clinic networks in Nigeria and Kenya exhibit the highest price sensitivity, while Saudi burn centers accept substantial premiums for atraumatic removal properties.
Supply Chain Analysis
South Africa and the UAE anchor gamma sterilization infrastructure for regional dressing distribution. Raw material flows draw from Saudi petrochemical integration for polyurethane feedstock, Egyptian textile mills for polyester backings, and Asian alginate fiber suppliers for advanced absorbent matrices. Single-source sterilization vulnerability concentrates risk in Durban and Dubai facilities serving East African markets. Distribution runs through Jebel Ali and Port Said free zones into sub-Saharan hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 13485 lead assessor scarcity across the Middle East creates a structural bottleneck that determines which manufacturers can sustain hospital tender eligibility, privileging incumbents with established quality infrastructure over capital-constrained challengers.
For Market Incumbents: Shield market position by deepening captive sterilization capacity in the UAE and South Africa to offset single-source infrastructure risk. Accelerate antimicrobial formulation pipelines to capture procurement committees now mandating bacterial log-reduction documentation in Saudi and Emirati tertiary centers. For New Entrants and Emerging Players: SFDA's compressed approval timelines for pre-certified manufacturers offer the fastest route to Gulf hospital contracts. Target Egyptian manufacturing zones for tariff-advantaged export positioning into East African markets with limited local production. Lead with direct-to-patient distribution models as Saudi home healthcare channels expand fastest. For Investors and Strategic Acquirers: The market sits at a regulatory-concentration phase that favors vertically integrated specialists with in-house toxicology capabilities. Long-term viability rests on manufacturers capable of managing multiple biocompatibility dossiers across divergent national frameworks. Monitor ANVISA-SFDA convergence signals as the primary inflection indicator for future harmonization premiums.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Establishes eligibility for Saudi and South African hospital tender pools. |
| Antimicrobial Formulation Pipeline | Captures procurement mandates specifying silver-ion bacterial log-reduction. |
| Egyptian Manufacturing Footprint | Enables tariff-advantaged distribution into sub-Saharan African markets. |
| Direct Hospital System Partnerships | Displaces fragmented distributor networks in Netcare and Life Healthcare chains. |
| Home Healthcare Channel Development | Aligns with SFDA reimbursement streamlining for outpatient recovery protocols. |
Research Methodology
Initial hypotheses were tested against primary input from hospital procurement managers, biomedical engineers, GPO contracts specialists, and regulatory affairs directors, then refined through secondary validation against ANVISA guidance documents, SFDA registration databases, hospital procurement records, and customs trade flows. Bottom-up demand modeling triangulated with top-down macroeconomic indicators across the analysis window.
Variance decomposition separates volume drivers from pricing dynamics across product type, end-user setting, application site, and material chemistry dimensions. CAGRs were derived from segment-level growth trajectories anchored to sterilization capacity expansion and regulatory approval velocity. Forecast inputs incorporate petrochemical feedstock indices and tertiary hospital construction pipelines.
Underlying assumptions cover regulatory stability in Saudi Arabia and South Africa, with deviation risk concentrated in ANVISA biocompatibility testing timeline extensions and gamma irradiation capacity bottlenecks. Recalibration cycles align with material shifts in national medical device harmonization initiatives.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Mexico Wound Care Management Devices Market
Wound Care
Venous Leg Ulcer (VLU) Treatment Market
Wound Care
Advanced Wound Care Management Market
Wound Care
Wound Healing Supplement Market
Wound Care
Wound Care Centers Market
Wound Care
Single-Use Negative Pressure Wound Therapy Devices Market
Wound Care
Middle East and Africa Advanced Wound Care Market
Wound Care
Venous Skin Ulcer Treatment Market
Wound Care
Patch Based Wound Healing Products Market
Wound Care
Wound Skin Care Market
Wound Care
Vascular Ulcer Treatment Market
Wound Care
Wound Contact Layer Dressing Market
Wound Care
Europe Compression Bandages Market
Wound Care
Wound Debridement Products Market
Wound Care
Europe Wound Care Market
Wound Care
Wound Irrigation Solutions Market