
 Global Hemostats Market | 2026-2036
Global Hemostats Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hemostats Market Foresight
Premium-grade absorbable hemostat specifications is unwinding the competitive hierarchy across surgical supply chains. Johnson & Johnson leverages its broad hospital formulary access to sustain high-margin positions in mechanical and active formats. Baxter International anchors North American distribution through direct sales channels and specialized surgical support teams. Pfizer competes on recombinant thrombin technology leadership, while B. Braun Melsungen dominates European procurement with integrated operating-room supply bundles.
Hemostats comprise bioabsorbable agents, oxidized cellulose, gelatin sponges, collagen matrices, and synthetic polymer sealants engineered to accelerate clot formation and control bleeding during operative procedures. Mechanical hemostats occupy the largest volume share due to established reimbursement and surgeon familiarity, though flowable hemostats and sealants represent the fastest-expanding margin pools as laparoscopic and robotic platforms proliferate. Therapy area segmentation reveals cardiovascular surgery and orthopedic surgery as the most concentrated demand centers, with neurosurgery commanding premium pricing for precision-active formulations.
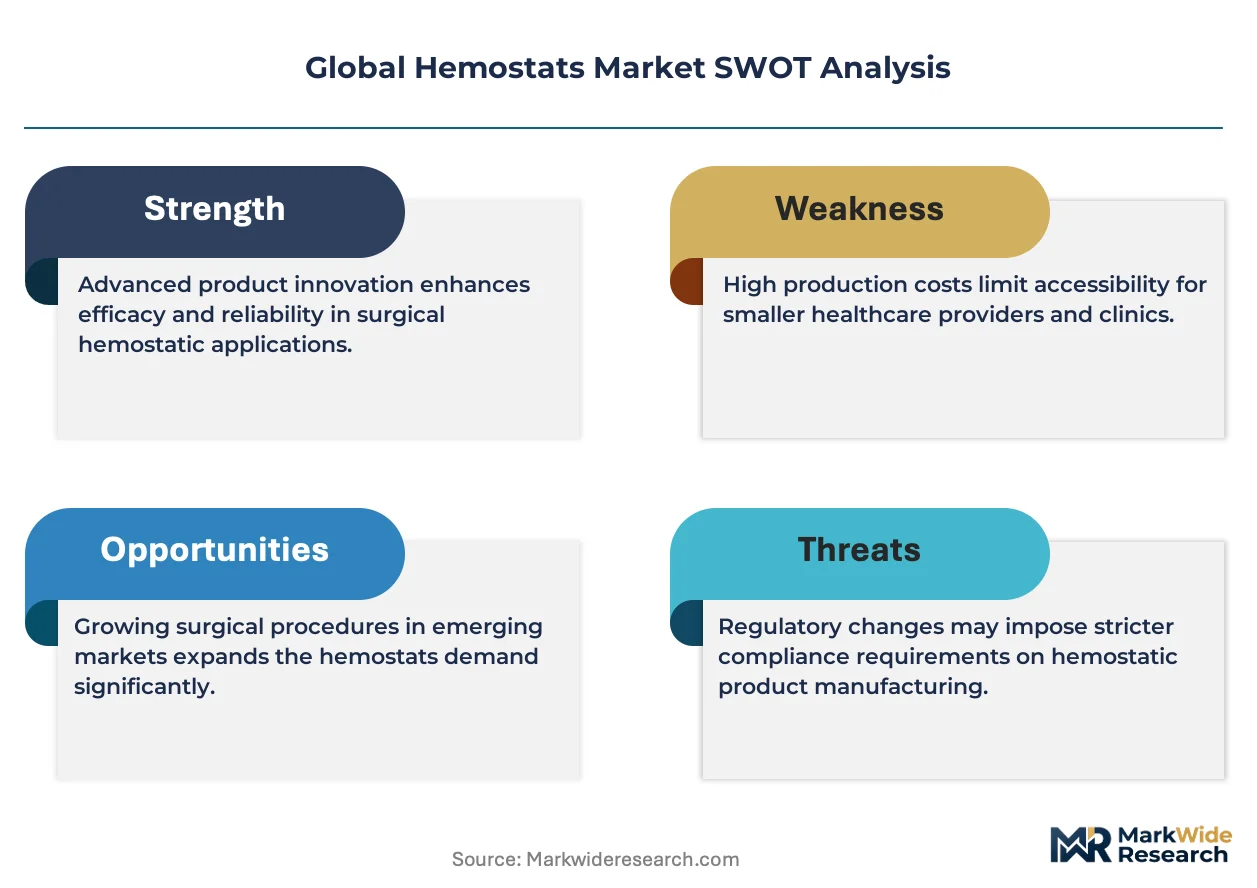
FDA 510(k) clearance pathways and EMA Medical Device Regulation (MDR) conformity requirements shape product development timelines and market access barriers for absorbable hemostat innovations. ISO 10993 biocompatibility testing and REACH chemical safety standards further constrain material selection and supplier qualification across the European Union and United States. Stakeholders must monitor evolving reimbursement thresholds for advanced sealants versus conventional mechanical options as health technology assessment bodies recalibrate cost-effectiveness benchmarks.
Market Dynamics
Active hemostat platforms are compressing mechanical formats across cardiovascular and orthopedic surgical suites as biocompatibility standards harden and procurement consolidates around premium absorbable specifications.
Growth Catalysts
- FDA 510(k) pathway streamlining:Accelerated clearance timelines for absorbable hemostat iterations reduce development-to-revenue cycles for manufacturers targeting US hospital systems.
- Cardiovascular surgical volume expansion:Rising procedure counts in coronary artery bypass grafting and valve replacement drive concentrated demand for precision-active formulations.
- Oxidized regenerated cellulose:This bioabsorbable matrix material delivers rapid hemostasis with minimal tissue reaction, displacing older gelatin sponge protocols in trauma centers.
Market Restraints
- Collagen raw material concentration:Bovine and porcine sourcing dependencies create supply vulnerability linked to agricultural disease outbreaks in Brazil and Argentina.
- EMA MDR conformity costs:Expanded clinical evidence requirements for Class III absorbable devices extend time-to-market by 18-24 months for European entrants.
- Recombinant thrombin substitution pressure:Human plasma-derived thrombin faces displacement from biosynthetic alternatives, eroding margin pools for conventional active hemostat portfolios.
Strategic Opportunities
- India's surgical infrastructure buildout:Government hospital modernization programs and medical device parks in Andhra Pradesh and Gujarat create entry points for mid-tier mechanical hemostat suppliers.
- Flowable-sealant laparoscopic convergence:Integration of synthetic polymer sealants with robotic surgical platforms opens premium positioning in minimally invasive procedures.
- Japan PMDA regenerative medicine framework:Accelerated review pathways for cell-integrated hemostat products incentivize R&D investment in next-generation bioactive matrices.
Industry Challenges
- ISO 10993-18 chemical characterization:Expanded toxicological screening requirements for absorbable polymers strain analytical chemistry capabilities and extend validation timelines.
- Operating room integration complexity:New hemostat formats require retraining surgical support staff and redesigning sterile field protocols, slowing adoption velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hemostats Market |
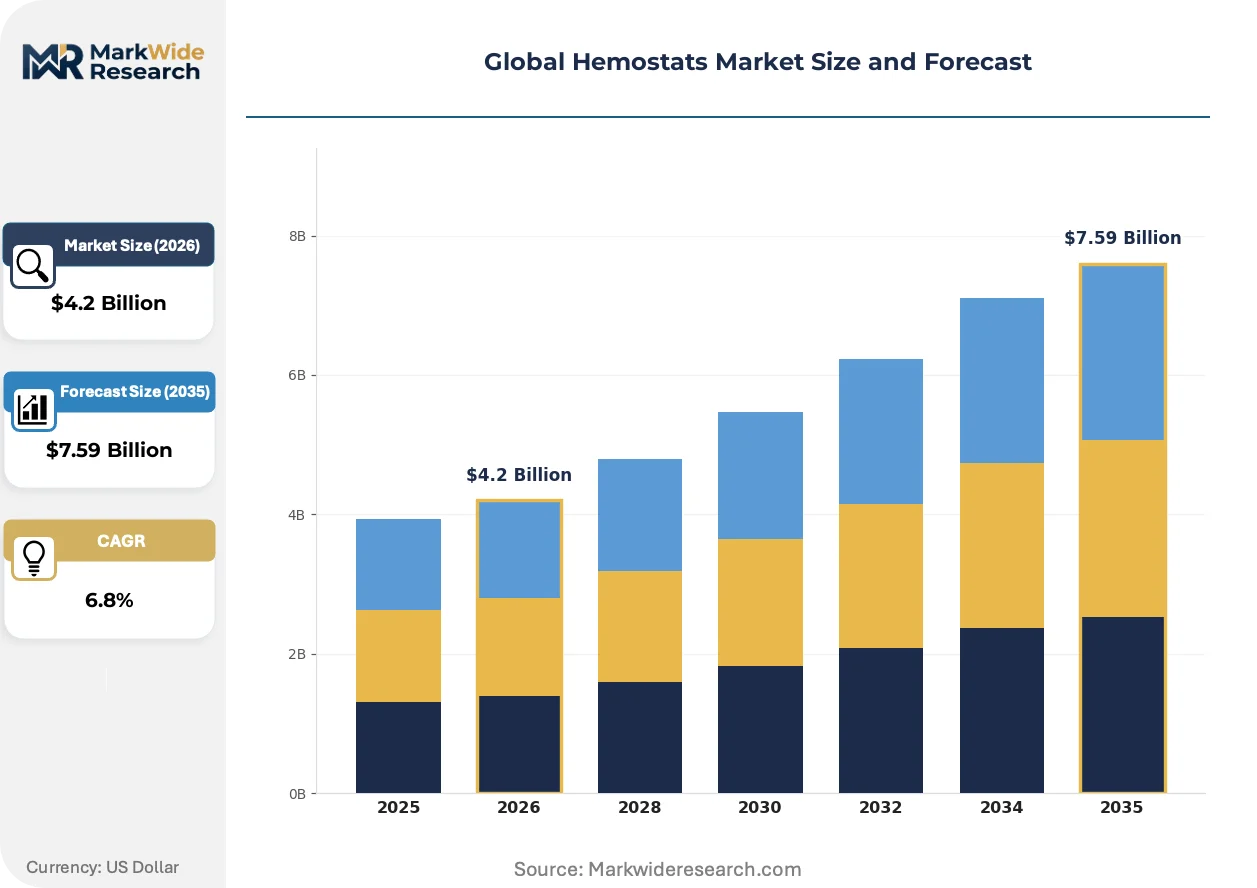
| Market Size in 2026 | $4.2 Billion |
| Market Size in 2035 | $7.59 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Hemostats, Active Hemostats, Flowable Hemostats, Sealants, Adhesives Therapy Area: Cardiovascular Surgery, Orthopedic Surgery, Neurosurgery, General Surgery, Urology End User: Ambulatory Surgical Centers, Specialty Clinics, Research Laboratories, Diagnostic Centers Distribution Channel: Direct Sales, Hospitals Procurement, Online Pharmacies, Medical Device Distributors, Government Tender |
| Companies Covered | Becton Dickinson (BD), Pfizer, Johnson & Johnson, CSL Behring, Integra LifeSciences, Baxter International, B. Braun Melsungen, CryoLife, Medtronic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hemostats Market Shifts & Advancements
Biomaterial engineering and regulatory convergence are redefining competitive advantage around hemostat efficacy validation and supply chain traceability rather than traditional formulation heritage.
Flowable hemostats incorporating polyethylene glycol-based synthetic matrices is supplanting oxidized cellulose sheets in laparoscopic procedures. Academic medical centers in Germany and the United States are transitioning procurement specifications toward these formats. The shift is compressing volume share for legacy mechanical platforms while expanding addressable margin in robotic surgery suites.
REACH chemical safety standards and EMA MDR biocompatibility requirements are tightening material disclosure obligations across European supply chains. Manufacturers must now document full substance composition down to 0.1% concentration thresholds. Absorbable hemostat producers with integrated polymer synthesis capabilities are capturing preferential formulary access as hospitals face liability exposure from incomplete chemical characterization.
Hospital purchasing consortiums are consolidating supplier relationships around dual-source active hemostat contracts with embedded technical service provisions. Group purchasing organizations in the United States are displacing independent procurement decisions by individual surgeons. This concentration is most visible in cardiovascular service lines where standardization protocols now mandate specific hemostat formats across entire health systems.
Global Hemostats Market Segmentation
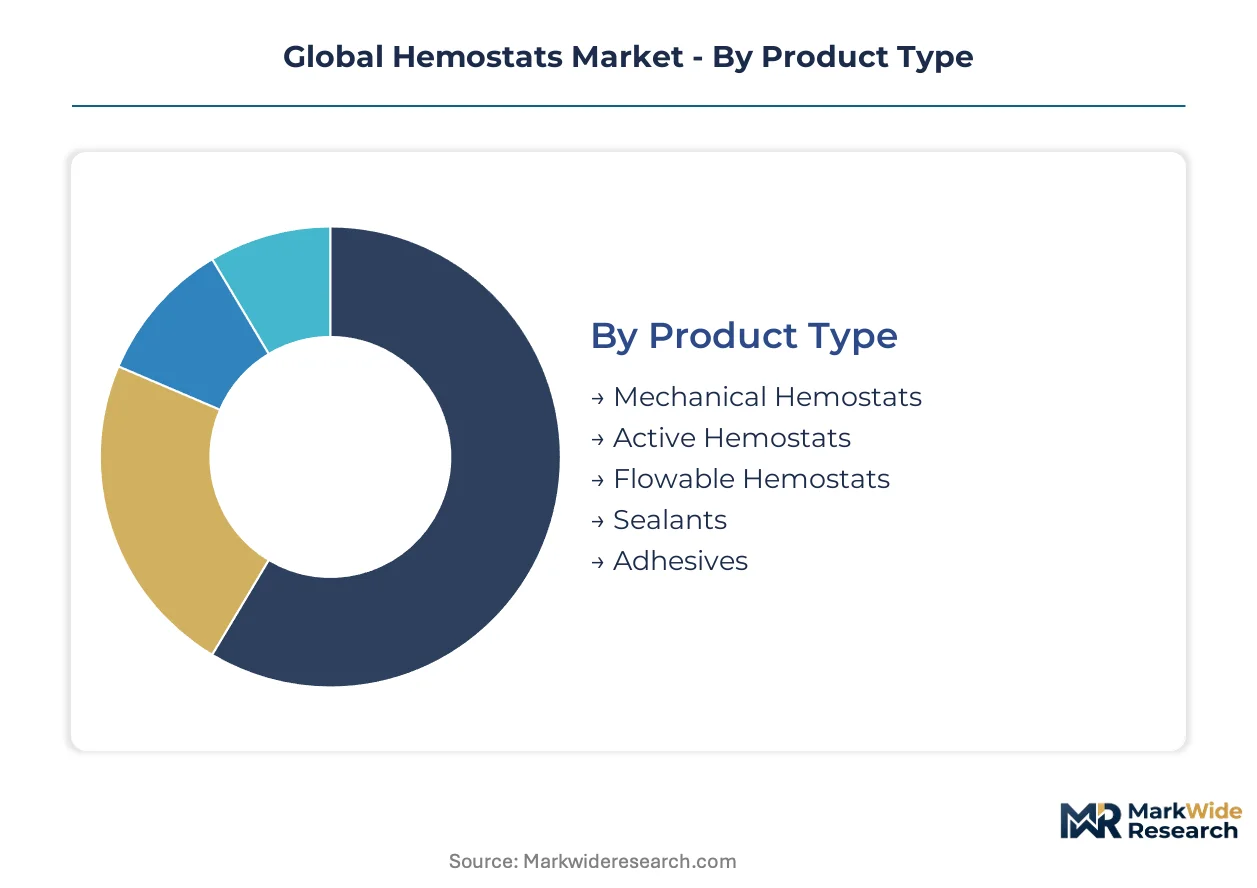
Hemostat procurement patterns diverge sharply across product formats and clinical settings. Substitution dynamics between mechanical platforms and active formulations reshape competitive positioning within each segment cluster.
Product Type:
Active hemostats face the most intense substitution pressure as flowable formats and synthetic sealants displace older mechanical protocols in laparoscopic suites.
- Mechanical Hemostats:Oxidized cellulose sheets and gelatin sponges deliver passive hemostasis through physical compression. United States trauma centers sustain volume demand despite margin compression from newer formats.
- Active Hemostats:Thrombin-integrated matrices accelerate clotting through biochemical cascade activation. Cardiovascular surgical suites in Germany and Japan concentrate procurement around recombinant thrombin specifications as biocompatibility standards harden.
- Flowable Hemostats:Synthetic polymer matrices enable minimally invasive application through laparoscopic delivery systems.
- Sealants:Polyethylene glycol and albumin-glutaraldehyde formulations create mechanical barriers across tissue planes.
- Adhesives:Cyanoacrylate and protein-based tissue bonding agents serve niche microsurgical applications.
Mechanical hemostats anchor the volume base while flowable hemostats gain share at the steepest rate.
Therapy Area:
Procedure complexity and reimbursement tiers stratify demand across surgical disciplines, with premium pricing concentrated in precision-critical specialties.
- Cardiovascular Surgery:Coronary artery bypass grafting and valve replacement procedures require rapid, reliable hemostasis in anticoagulated patients. United States hospital systems standardize active hemostat protocols across cardiac service lines to reduce transfusion rates.
- Orthopedic Surgery:Joint arthroplasty and spinal fusion generate high-volume consumption of mechanical and flowable formats. German ambulatory surgical centers drive mid-tier specification demand through bundled payment contracts.
- Neurosurgery:Delicate tissue handling requirements command premium pricing for precision-active formulations with minimal swelling reaction.
- General Surgery:Broad procedural diversity sustains mechanical hemostat volume across trauma and emergency applications.
- Urology:Prostatectomy and nephrectomy procedures favor flowable sealants for suture-line reinforcement.
Cardiovascular surgery commands the highest per-procedure spend while orthopedic surgery generates the largest aggregate volume.
End User:
Site-of-care economics determine format selection, with consolidation pressures favoring standardized procurement across integrated delivery networks.
- Ambulatory Surgical Centers:Cost-containment imperatives drive preference for mechanical hemostats in low-complexity procedures. United States Medicare reimbursement cuts accelerate same-day discharge protocols that limit premium format adoption.
- Specialty Clinics:Dermatologic and ophthalmologic procedures utilize niche adhesive formulations with specialized applicator designs.
- Research Laboratories:Preclinical testing facilities consume hemostat materials for device validation and biocompatibility studies.
- Diagnostic Centers:Biopsy and interventional radiology suites require rapid hemostasis for percutaneous procedures.
Ambulatory surgical centers concentrate mechanical hemostat volume while specialty clinics sustain the most fragmented format requirements.
Distribution Channel:
Channel structure reflects procurement consolidation trends, with direct manufacturer relationships displacing traditional distributor intermediaries in high-volume accounts.
- Direct Sales:Manufacturer field representatives provide technical support and sterile field training for active hemostat platforms. Baxter International and Johnson & Johnson deploy specialized surgical support teams to United States academic medical centers.
- Hospitals Procurement:Group purchasing organizations consolidate supplier contracts across health systems. German hospital federations negotiate framework agreements covering multiple hemostat categories.
- Online Pharmacies:E-commerce platforms serve small clinics and rural facilities with limited distributor access.
- Medical Device Distributors:Regional wholesalers maintain inventory buffers for mechanical hemostat stock-keeping units.
- Government Tender:Public hospital systems in India and Brazil procure hemostats through centralized competitive bidding processes.
Direct sales captures the premium active hemostat segment while government tender channels concentrate mechanical format procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply concentration for hemostat manufacturing clusters in the United States, Germany, and Japan, with regulatory harmonization across FDA, EMA, and PMDA jurisdictions shaping cross-border product development timelines.
United States
Cardiovascular surgical volume and academic medical center procurement consolidation drive demand concentration. FDA 510(k) pathway streamlining accelerates clearance for absorbable hemostat iterations, compressing development-to-revenue cycles. Boston and Cleveland surgical clusters standardize active hemostat protocols across integrated delivery networks.
Germany
Ambulatory surgical center expansion and bundled payment contracts sustain mid-tier mechanical hemostat consumption. EMA MDR conformity requirements extend time-to-market for Class III absorbable devices by 18-24 months. The Tübingen-Stuttgart medical technology corridor anchors European R&D for precision-active formulations.
Japan
Aging demographics and coronary artery bypass volume expansion concentrate demand for premium hemostat specifications. PMDA regenerative medicine frameworks accelerate review pathways for cell-integrated bioactive matrices. The Kobe-Osaka medical device cluster specializes in next-generation polymer sealant development.
India
Government hospital modernization and medical device parks in Andhra Pradesh and Gujarat create entry points for mid-tier mechanical suppliers. CDSCO medical device regulations align with ISO 13485 quality management standards. The Hyderabad-Bengaluru corridor attracts contract manufacturing for oxidized cellulose production.
Switzerland
Precision manufacturing heritage and pharmaceutical integration support premium hemostat component supply. Swissmedic medical device regulations enforce stringent biocompatibility documentation requirements. The Basel-Zurich corridor specializes in recombinant protein and thrombin formulation capabilities.
Global Hemostats Market Competitive Landscape
Concentration sits with diversified medical technology conglomerates that leverage hospital formulary access and direct sales infrastructure. Johnson & Johnson and Baxter International anchor North American distribution through specialized surgical support teams. Three archetypes dominate: integrated conglomerates with broad portfolio breadth, regional specialists with operating-room supply bundles, and recombinant biotechnology leaders. Competitive moves center on M&A for biocompatibility capabilities and strategic partnerships with robotic surgical platform manufacturers.
Among diversified medical technology conglomerates, Johnson & Johnson and Baxter International exemplify the integrated archetype with established hospital system relationships. Pfizer occupies a position representing recombinant biotechnology leadership, while B. Braun Melsungen anchors the European specialist tier with integrated supply bundle capabilities. CSL Behring and CryoLife exemplify plasma-derived and biological matrix specialists respectively, each sitting within distinct procurement channels defined by therapeutic application focus.
| Leading Market Players |
|---|
| Becton Dickinson (BD) |
| Pfizer |
| Johnson & Johnson |
| CSL Behring |
| Integra LifeSciences |
| Baxter International |
| B. Braun Melsungen |
| CryoLife |
| Medtronic |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between United States hospital systems and active hemostat manufacturers lock in supply access and price visibility across multi-year procurement cycles. These contracts bundle technical service provisions with volume commitments, insulating premium-tier suppliers from spot-market volatility while compressing margins for mechanical format producers competing on tender-based pricing.
Pricing Analysis
FDA 510(k) clearance tiers dictate the pricing tier structure across the United States market, with Class III absorbable devices commanding premium positioning against 510(k)-exempt mechanical alternatives. Three-tier pricing structure across premium recombinant thrombin matrices, standard oxidized cellulose platforms, and economy gelatin sponge formats reflects certification burden and clinical validation depth. Cost compression in the mechanical tier intensifies because of concentrated bovine collagen sourcing and Indian contract manufacturing inroads. Ambulatory surgical centers exhibit the highest price sensitivity due to Medicare reimbursement constraints, while academic medical centers prioritize clinical outcomes over unit cost.
Supply Chain Analysis
United States, Germany, and Switzerland anchor hemostat manufacturing through distinct capability specializations. The United States concentrates recombinant thrombin fermentation and polymer sealant R&D. Germany sustains oxidized regenerated cellulose production and precision-active formulation engineering. Switzerland feeds from recombinant protein purification and thrombin finishing capabilities. Raw material dependencies span Brazilian bovine collagen, porcine gelatin from Argentina, and pharmaceutical-grade cellulose from Nordic pulp processors. Single-source vulnerability concentrates in plasma-derived thrombin supply following recombinant substitution acceleration. Distribution runs through direct manufacturer field teams for active platforms and regional medical device distributors for mechanical stock-keeping units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face a substitution defense imperative as flowable synthetic sealants displace mechanical protocols in laparoscopic suites and recombinant thrombin erodes plasma-derived active hemostat margins.
For Market Incumbents: Compound formulary stickiness through embedded sterile field training programs and dual-source contract structures that raise switching costs for United States health systems. Deepen backward integration into recombinant protein production to defend margin pools against biosynthetic thrombin displacement. Prioritize ISO 10993-18 chemical characterization capabilities to capture preferential access under REACH and EMA MDR disclosure requirements. For New Entrants and Emerging Players: Differentiate on laparoscopic delivery system integration with robotic surgical platforms, targeting the fastest-expanding premium segment where incumbent technical service infrastructure remains underdeveloped. Penetrate India's government hospital modernization programs through CDSCO-compliant mechanical hemostat manufacturing in Andhra Pradesh medical device parks. Pursue white-label supply contracts with European distributors seeking second-source oxidized cellulose alternatives to reduce Brazilian collagen exposure. For Investors and Strategic Acquirers: Capital is best deployed toward recombinant biotechnology specialists with PMDA regenerative medicine pathway positioning and integrated polymer synthesis capabilities that satisfy tightening chemical characterization mandates. Long-term viability hinges on regulatory navigation expertise rather than formulation heritage alone. Monitor Japan's cell-integrated hemostat approval velocity as an inflection indicator for next-generation bioactive matrix commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerated timelines compress development-to-revenue cycles for absorbable iterations targeting United States academic medical centers. |
| CE Marking Pathway | EMA MDR conformity investments extend European market access barriers and favor incumbents with clinical evidence generation capabilities. |
| Hospital System Partnership | Integrated delivery network standardization protocols in cardiovascular service lines consolidate procurement around specific active hemostat formats. |
| Software Companion Development | Digital surgical workflow integration with robotic platforms differentiates flowable sealant positioning in minimally invasive procedures. |
| Reimbursement Strategy | Health technology assessment body engagement shapes cost-effectiveness benchmarks for advanced sealants versus mechanical alternatives. |
Research Methodology
Cross-validation between hospital procurement database analysis and GPO contract documentation anchors the qualitative findings on pricing dynamics and format substitution patterns. Primary interviews with cardiovascular surgeons, hospital purchasing committee chairs, biomedical engineers specializing in sterile field protocols, and GPO contracts managers inform demand-side segmentation. Secondary validation draws from FDA 510(k) filings, EMA MDR conformity assessment databases, hospital formulary listings, and CMS Medicare reimbursement schedules. Bottom-up procedure volume modeling and top-down manufacturer revenue triangulation converge on segment-level estimates.
Sensitivity analysis across regulatory approval timeline scenarios, raw material cost volatility assumptions, and reimbursement threshold adjustments tests forecast robustness. The analytical framework disaggregates volume and value across product type, therapy area, end user site-of-care economics, and distribution channel concentration throughout the projection horizon. CAGRs derive from logistic adoption curve fitting for robotic surgical platform penetration and elasticity-adjusted price trajectory modeling. Forecast inputs incorporate cardiovascular procedure volume projections and REACH chemical disclosure compliance cost estimates.
The analysis sits within stated boundaries; outcomes outside sustained FDA 510(k) pathway efficiency, stable bovine collagen supply from Brazil and Argentina, and continued EMA MDR implementation without regulatory rollback would require recalibration. Forecasts reflect documented assumptions regarding recombinant thrombin substitution velocity and laparoscopic platform proliferation. Recalibration cycles align with material shifts in PMDA regenerative medicine framework decisions, major agricultural disease outbreaks affecting collagen sourcing, and health technology assessment body reimbursement determinations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Knife Sterilizer Market
Medical Supplies
Nursing Breast Pads Market
Medical Supplies
Plasma Separation Tubes Market
Medical Supplies
Dehydrated Culture Media Market
Medical Supplies
Soaker Pads Market
Medical Supplies
Luer Lock Syringe Market
Medical Supplies
Global Synthetic Absorbable Sutures Market
Medical Supplies
Dissolvable Stitches Market
Medical Supplies
Europe Ostomy Drainage Bags Market
Medical Supplies
India Hospital Supplies Market
Medical Supplies
North America Healthcare Packaging Market
Medical Supplies
Cell Freezing Media Market
Medical Supplies
Medical Tapes and Bandages Market
Medical Supplies
Global Sharps Containers Market
Medical Supplies
Diagnostic Vials Market
Medical Supplies
France Hospital Supplies Market