
 Wound Healing Nutrition Market | 2026-2036
Wound Healing Nutrition Market Size, Share, and Industry Trends Forecast 2026-2036
Wound Healing Nutrition Market Insights
Aftermarket clinical support services are reshaping how manufacturers capture recurring revenue beyond initial formula sales. Abbott Nutrition leverages registered dietitian networks to sustain institutional loyalty across long-term care facilities. Nestlé Health Science anchors its position through specialized burn-recovery portfolios that dominate European hospital purchasing. Pfizer competes via hospital-exclusive distribution agreements that control formulary access in North American health systems.
Wound healing nutrition comprises enteral and oral nutritional interventions engineered with protein densities exceeding standard dietary supplements, typically delivering 1.2 to 2.0 grams of protein per kilogram of body weight to support collagen synthesis and immune response during tissue repair. These formulations integrate conditionally essential amino acids such as arginine and glutamine alongside zinc and vitamin C to accelerate closure rates in compromised patients. Amino acid formulations attract premium positioning due to targeted substrate delivery for pressure sore management, while diabetic ulcer applications represent the fastest-growing clinical segment as glycemic control protocols integrate nutrition into standard wound care pathways. Home care patients emerge as a structurally expanding end-user channel as hospital-at-home reimbursement frameworks mature.
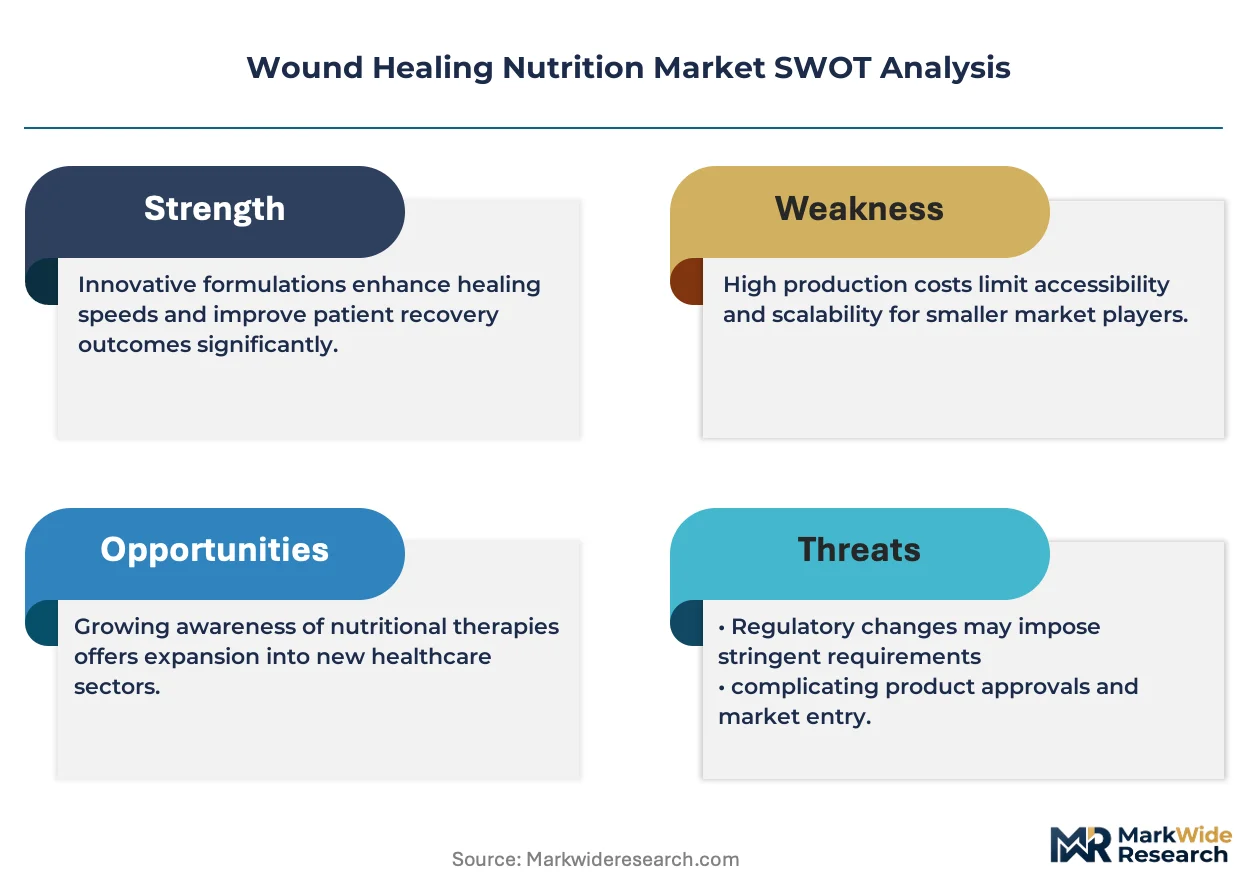
The FDA's medical food regulations and the EMA's clinical nutrition guidelines create divergent compliance burdens that fragment product registration strategies across Atlantic markets. ISO 22000 and HACCP protocols govern manufacturing quality for lipid complex stability and microbial safety in parenteral-adjacent formulations. Stakeholders must monitor evolving reimbursement coding for medical foods versus standard supplements, as payer classification determines margin accessibility in institutional procurement.
Market Dynamics
Hospital-at-home reimbursement frameworks are restructuring demand architecture for wound healing nutrition, pulling enteral formula procurement from centralized pharmacy systems into distributed home care networks that require cold-chain logistics and patient self-administration training.
Growth Catalysts
- 21 CFR 101.9(j) medical food labeling:The FDA's distinctive nutritional claim requirements create defensible market positions for manufacturers who complete clinical substantiation, locking out commodity supplement competitors from institutional formularies.
- Japan's super-aged society:Pressure ulcer prevalence among institutionalized elderly exceeds 5% in acute care settings, generating concentrated demand for arginine-enriched formulations that accelerate collagen deposition.
- Enteral delivery system miniaturization:Portable pump technologies enable continuous feeding protocols outside hospital walls, expanding addressable patient populations to ambulatory surgical recovery.
Market Restraints
- Whey protein concentrate volatility:Dairy input costs fluctuate with New Zealand and EU milk powder auction cycles, compressing gross margins for standard enteral formulations during commodity spikes.
- EMA clinical nutrition guideline fragmentation:Divergent member state interpretation of medical food versus food supplement classification creates registration duplication costs that deter mid-cap market entry.
- Oral nutritional supplement substitution:Retail-positioned high-protein beverages priced below medical food thresholds capture price-sensitive home care patients who bypass prescription channels.
Strategic Opportunities
- German outpatient wound centers:Bundled reimbursement pilots for diabetic foot care create integrated nutrition-pharmacy procurement opportunities that bypass hospital purchasing committees.
- Telehealth-dietitian hybrid models:Remote monitoring platforms pair enteral compliance tracking with automated reordering, capturing recurring revenue through subscription logistics rather than one-time sales.
- UK National Health Service "Net Zero" mandates:Carbon footprint disclosure requirements for medical nutrition procurement favor regional manufacturing hubs and recyclable packaging innovations.
Industry Challenges
- Enteral nutrition pharmacist certification:Specialized compounding and parenteral-adjacent formulation expertise remains concentrated in academic medical centers, constraining home care program scale-up.
- ISO 22000 HACCP implementation:Lipid emulsion stability testing and microbial safety validation require capital-intensive cleanroom infrastructure that extends facility commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wound Healing Nutrition Market |
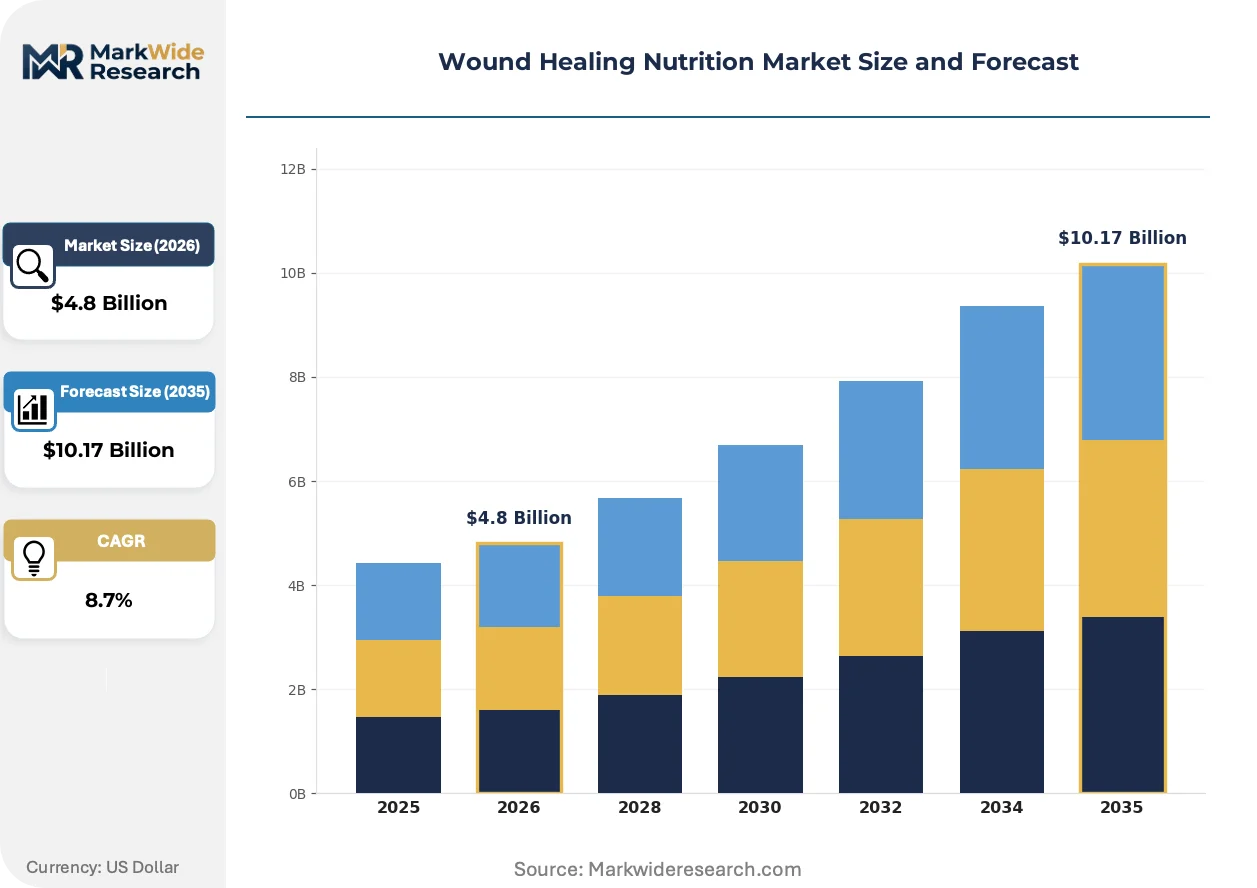
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Supplements, Amino Acid Formulations, Vitamins, Mineral Enrichments, Lipid Complexes Application: Chronic Wounds, Surgical Wounds, Burn Injuries, Diabetic Ulcers, Pressure Sores End User: Home Care Patients, Rehabilitation Centers, Specialized Clinics, Long-term Care Facilities, Wellness Centers Distribution Channel: Pharmacies, Online Retailers, Hospitals, Nutritionists, Direct Sales |
| Companies Covered | Abbott Nutrition, Nestlé Health Science, Vitabiotics, Pfizer, GlaxoSmithKline, Lupin, Intas Pharmaceuticals, Mankind Pharma, DermaRite Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wound Healing Nutrition Market Trends and Innovations
Digital health infrastructure is virtualizing patient monitoring and supply chain coordination across wound healing nutrition delivery, compressing the traditional separation between clinical decision support and logistics fulfillment.
Precision fermentation-derived recombinant proteins are virtualizing amino acid sourcing for specialized wound formulations, enabling exact arginine-to-glutamine ratios without agricultural supply constraints. Biotech ingredient suppliers in Denmark and the Netherlands are scaling manufacturing capacity threefold to serve medical food contracts. This technology is virtualizing the geographic concentration of protein ingredient supply chains that historically depended on dairy belt regions.
The EU Medical Device Regulation (MDR) reclassification of enteral feeding pumps as Class IIa devices imposes clinical evidence requirements that filter out low-cost Asian manufacturers from European hospital tenders. German notified bodies are extending conformity assessment timelines to 18-24 months for pump-nutrition integrated systems. Burn centers and ICU departments are consolidating procurement around MDR-certified suppliers to eliminate dual-track maintenance protocols.
Hospital supply chain directors are consolidating vendor lists around integrated nutrition-service contracts that bundle formula, delivery equipment, and dietitian teleconsultation into per-patient-day fees. This displaces the traditional model of separate pharmaceutical, durable medical equipment, and professional service procurement. The United Kingdom's NHS Supply Chain and several US integrated delivery networks have piloted these arrangements for complex wound populations.
Wound Healing Nutrition Market Segmentation
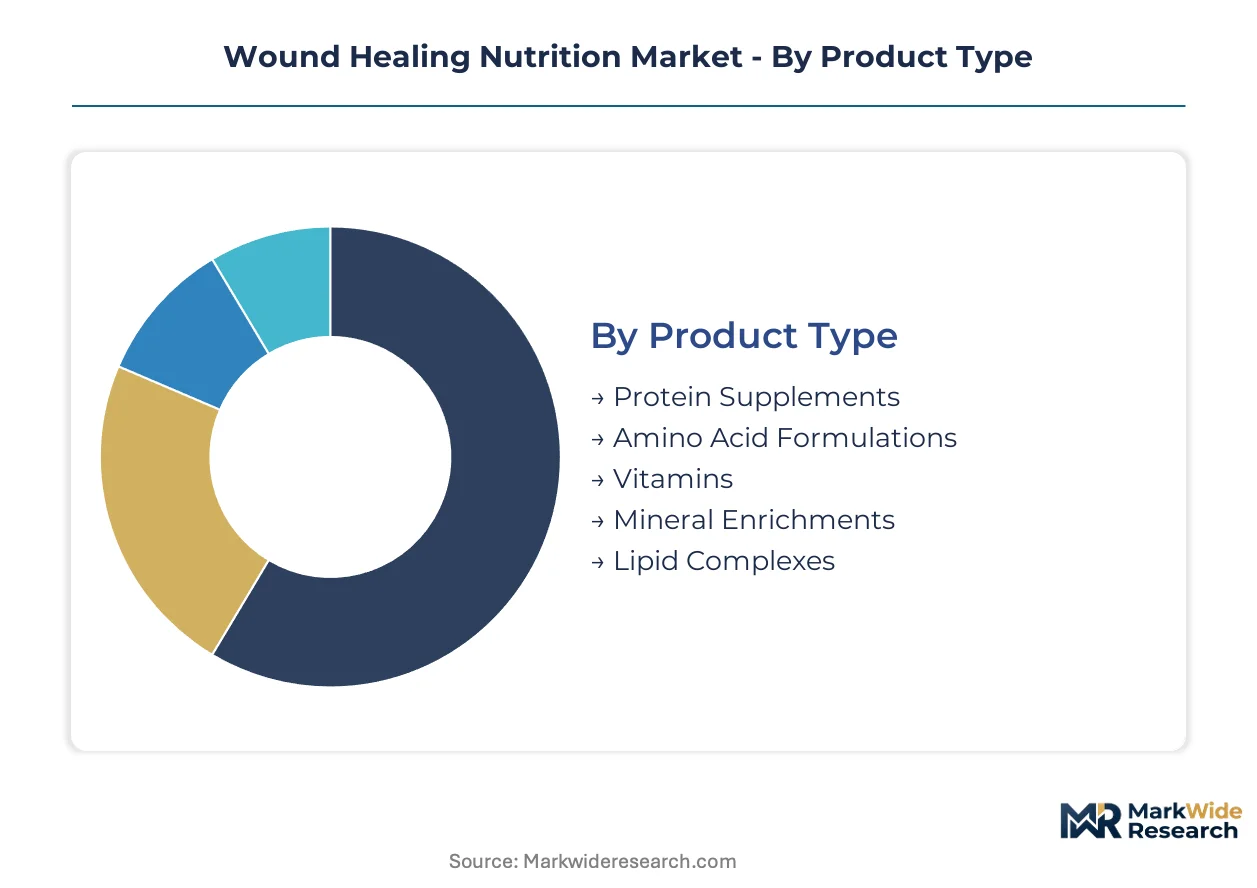
Wound healing nutrition procurement cycles vary dramatically by segment, with acute care applications turning inventory weekly while home care channels stretch replenishment to monthly intervals. Manufacturers calibrate production runs and cold-chain logistics around these velocity differentials to minimize expiry losses and maximize margin capture.
Product Type:
Protein-dense formulations rotate through hospital formularies fastest due to post-surgical protocol standardization, while mineral enrichments sit in inventory longer as clinicians reserve them for deficiency-confirmed cases.
- Protein Supplements:Standard enteral formulas delivering 1.2 to 2.0 grams per kilogram body weight, typically whey or casein hydrolysate bases. German hospital purchasing committees prioritize these for orthopedic recovery wards where collagen synthesis demands peak. Supply contracts lock in six-month pricing to buffer New Zealand dairy auction volatility.
- Amino Acid Formulations:Targeted arginine and glutamine blends engineered for pressure ulcer and burn recovery. Japan's super-aged institutional facilities command premium positioning here, with METI reimbursement codes favoring conditionally essential amino acid claims over standard protein.
- Vitamins:Ascorbic acid and vitamin E complexes supporting epithelialization. UK NHS "Net Zero" procurement favors regional manufacturing to minimize carbon disclosure penalties.
- Mineral Enrichments:Zinc sulfate and selenium protocols for deficiency-corrected healing. Long-term care facilities stock these for intermittent supplementation rather than continuous feeding.
- Lipid Complexes:Omega-3 fatty acid emulsions for anti-inflammatory modulation. ISO 22000 HACCP compliance extends facility commissioning timelines for these parenteral-adjacent formulations.
Protein Supplements anchors the volume base while Amino Acid Formulations gains share at the steepest rate.
Application:
Cost tiering separates emergency burn interventions from elective surgical protocols, with reimbursement intensity determining formula sophistication and procurement channel.
- Chronic Wounds:Venous leg ulcer and arterial insufficiency cases requiring months-long nutritional support. Home care networks in the United Kingdom distribute oral supplements here to avoid hospital bed days.
- Surgical Wounds:Post-operative enteral feeding protocols standardized across orthopedic and gastrointestinal recovery. German outpatient wound centers pilot bundled reimbursement integrating nutrition into surgical episode payments.
- Burn Injuries:Hypermetabolic states demanding 2.0+ grams protein per kilogram with arginine enrichment. European burn centers consolidate procurement around MDR-certified pump-nutrition integrated systems.
- Diabetic Ulcers:Glycemic control protocols integrating medical food nutrition into standard wound care pathways. This application expands most quickly as payers recognize reduced amputation costs from accelerated closure.
- Pressure Sores:Institutionalized elderly populations drive concentrated demand in Japan, where prevalence exceeds 5% in acute care settings.
Surgical Wounds generates the highest absolute revenue while Diabetic Ulcers climbs the fastest on payer cost-avoidance incentives.
End User:
Customer sophistication determines compliance monitoring intensity, with institutional settings tolerating complex enteral delivery and home patients defaulting to oral formats.
- Home Care Patients:Hospital-at-home reimbursement frameworks mature fastest in the United States and United Kingdom, pulling enteral procurement into distributed networks requiring patient self-administration training.
- Rehabilitation Centers:Post-acute facilities standardizing protein supplementation for mobility recovery. These centers represent stable recurring demand with formulary loyalty once Abbott- or Nestlé-contracted dietitians embed protocols.
- Specialized Clinics:Wound care centers in Germany bypass hospital purchasing committees through outpatient bundled pilots.
- Long-term Care Facilities:Pressure sore prevention protocols drive arginine-enriched formula adoption in Japan's institutionalized elderly population.
- Wellness Centers:Elective cosmetic surgery recovery and preventative nutrition positioning. These facilities operate outside medical food reimbursement, capturing retail-margin patients directly.
Long-term Care Facilities anchors the volume base while Home Care Patients gains share at the steepest rate.
Distribution Channel:
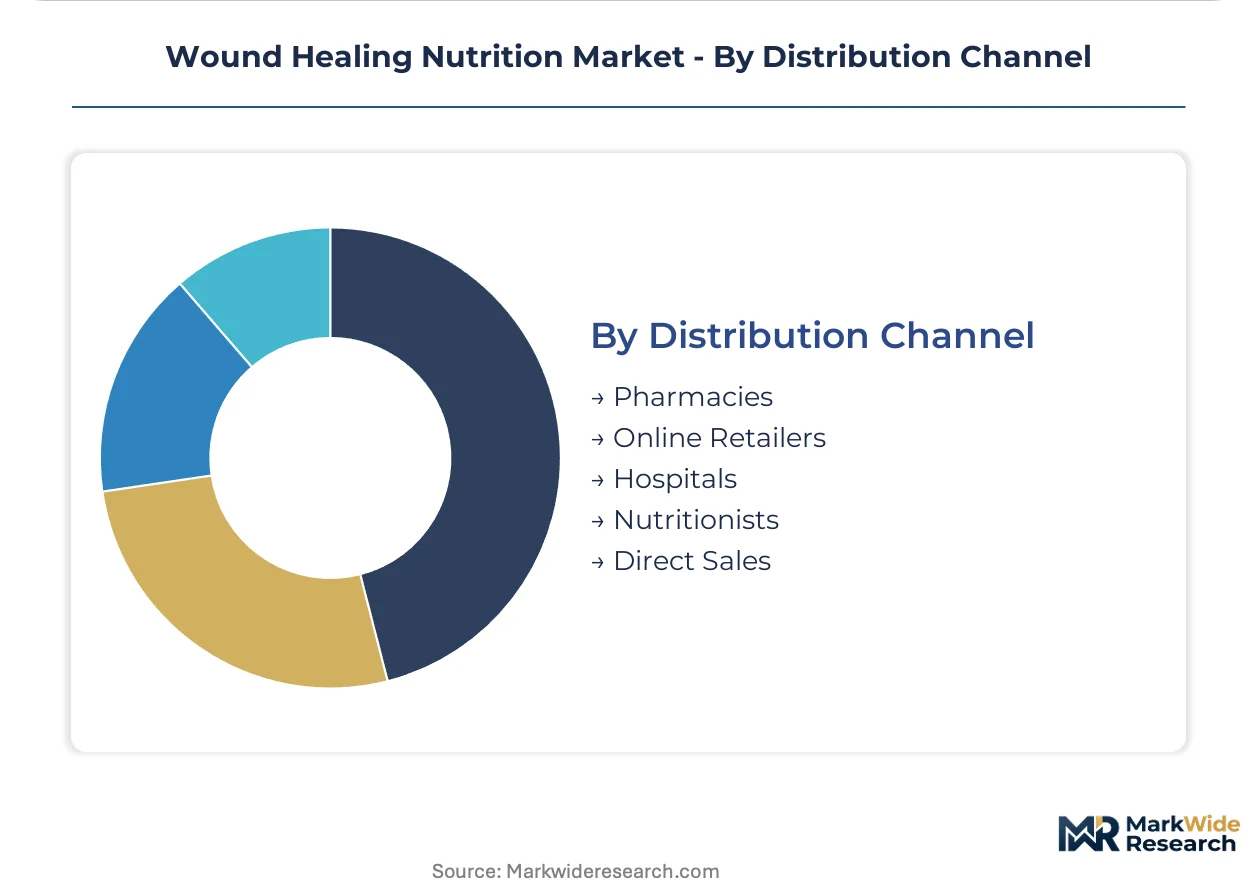
Margin structure separates institutional procurement with dietitian oversight from retail channels where price-sensitive patients substitute standard supplements.
- Pharmacies:Community and hospital outpatient dispensaries handling prescription enteral nutrition. EMA medical food versus supplement classification determines margin accessibility here.
- Online Retailers:Direct-to-patient platforms capturing home care patients bypassing prescription channels. High-protein beverages priced below medical food thresholds dominate this channel.
- Hospitals:Centralized pharmacy systems consolidating formulary access through exclusive distribution agreements. US health systems increasingly bundle formula, equipment, and teleconsultation into per-patient-day fees.
- Nutritionists:Registered dietitian networks sustaining institutional loyalty through compliance tracking and automated reordering subscriptions.
- Direct Sales:Manufacturer field forces targeting burn centers and ICU departments with MDR-certified integrated systems.
Hospitals anchors the volume base while Online Retailers gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Home care patients in the United States show the lowest price elasticity, accepting premium medical food pricing under hospital-at-home reimbursement, while online retail channels in India capture the most price-sensitive buyers substituting standard protein supplements for prescription formulas.
United States
FDA medical food regulations under 21 CFR 101.9(j) compel clinical substantiation for distinctive nutritional claims, creating defensible market positions for manufacturers who complete trials. Hospital-at-home reimbursement frameworks mature fastest here, pulling enteral procurement into distributed networks requiring cold-chain logistics. Texas and Florida health systems pilot bundled per-patient-day fees integrating formula, equipment, and teleconsultation.
Germany
Outpatient wound centers in Bavaria and North Rhine-Westphalia pilot bundled reimbursement for diabetic foot care, creating integrated nutrition-pharmacy procurement opportunities. EMA clinical nutrition guidelines fragment across member state interpretations, driving registration duplication costs. The country's hospital purchasing committees prioritize protein-dense formulations for orthopedic recovery wards, locking in six-month supply contracts.
Japan
METI reimbursement codes favor conditionally essential amino acid claims over standard protein, generating concentrated demand for arginine-enriched formulations. Pressure ulcer prevalence among institutionalized elderly exceeds 5% in acute care settings, driving long-term care facility procurement. The Kanto region around Tokyo anchors manufacturing capacity for precision fermentation-derived recombinant proteins.
United Kingdom
NHS Supply Chain pilots integrated nutrition-service contracts bundling formula, delivery equipment, and dietitian teleconsultation into per-patient-day fees. NHS "Net Zero" mandates for carbon footprint disclosure favor regional manufacturing hubs and recyclable packaging innovations. London and Southeast England health systems consolidate procurement around these arrangements for complex wound populations.
India
CDSCO regulates medical food classification alongside FSSAI standards for nutritional supplements, creating compliance navigation challenges for multinational entrants. Online retail channels capture price-sensitive home care patients bypassing prescription channels with high-protein beverages priced below medical food thresholds. Maharashtra and Gujarat host expanding manufacturing capacity serving domestic and export markets.
Wound Healing Nutrition Market Competitive Landscape
Pharmaceutical conglomerates and specialized nutrition divisions split the market between institutional formularies and home care channels. The vendor base concentrates around three strategic archetypes: diversified healthcare conglomerates with registered dietitian networks, dedicated medical nutrition specialists with burn-recovery portfolios, and generic pharmaceutical manufacturers competing on hospital-exclusive distribution agreements. Capacity expansion and backward integration into amino acid sourcing dominate competitive moves as manufacturers seek supply security.
Within the diversified healthcare tier, Abbott Nutrition and Nestlé Health Science exemplify distinct strategic positioning. Abbott anchors institutional loyalty through registered dietitian networks embedded across long-term care facilities. Nestlé occupies a specialized position through medical nutrition portfolios targeting European hospital purchasing. Pfizer represents the pharmaceutical-distribution archetype, competing via hospital-exclusive agreements that control formulary access in North American health systems.
| Leading Market Players |
|---|
| Abbott Nutrition |
| Nestlé Health Science |
| Vitabiotics |
| Pfizer |
| GlaxoSmithKline |
| Lupin |
| Intas Pharmaceuticals |
| Mankind Pharma |
| DermaRite Industries |
| Others |
Pricing and Supply Chain Analysis
Precision fermentation capacity utilization above 80% in Denmark and the Netherlands is compressing amino acid spot prices while forcing traditional dairy-protein suppliers into longer-term contract structures to defend shelf positions. This utilization dynamic simultaneously rewards biotech ingredient suppliers with pricing power on specialized arginine-glutamine blends and squeezes margin on commodity whey hydrolysates as hospital formularies consolidate procurement.
Pricing Analysis
After-sales clinical support contracts anchored by registered dietitian networks drive lifetime value beyond initial formula sales. Three-tier pricing structure across premium amino acid formulations, standard protein supplements, and economy oral nutrition products separates reimbursement-eligible medical foods from retail-positioned substitutes. Cost compression in standard enteral tiers is intensifying because New Zealand dairy auction volatility transmits directly into whey concentrate input costs. Home care patients in the United States show the lowest price sensitivity under hospital-at-home reimbursement, while online retail channels in India capture the most price-elastic buyers substituting high-protein beverages for prescription formulas.
Supply Chain Analysis
Export-control scrutiny on precision fermentation bioreactor technology limits capacity transfer to unlicensed jurisdictions, constraining geographic diversification of recombinant protein supply. Manufacturing gravity centers on Denmark, the Netherlands, and New Zealand for specialized amino acids and dairy-derived proteins. Formulation draws from whey protein concentrates, conditionally essential amino acids, and lipid emulsion precursors as core inputs. Single-source vulnerability concentrates in precision fermentation capacity for arginine-enriched medical foods. Distribution runs through hospital centralized pharmacy systems, home care networks with cold-chain requirements, and direct-to-patient online platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital-at-home reimbursement frameworks are disrupting traditional institutional procurement channels, creating a high-growth inflection as enteral nutrition demand shifts from centralized pharmacy systems into distributed logistics networks requiring patient self-administration capabilities.
For Market Incumbents: Pre-empt formulary consolidation by embedding registered dietitian networks into long-term care facility protocols before competitors replicate Abbott Nutrition's compliance-tracking subscription models. Secure backward integration into precision fermentation capacity to reduce exposure to New Zealand dairy auction cycles. Invest in MDR-certified pump-nutrition integrated systems to filter out low-cost Asian manufacturers from European hospital tenders. For New Entrants and Emerging Players: German outpatient wound centers piloting bundled reimbursement for diabetic foot care represent the most penetrable entry point, bypassing hospital purchasing committees through integrated nutrition-pharmacy procurement channels. Telehealth-dietitian hybrid models pairing remote enteral compliance tracking with automated reordering offer a direct go-to-market angle that captures recurring revenue without requiring entrenched institutional relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across precision fermentation-derived recombinant protein manufacturing as cleanroom infrastructure and ISO 22000 HACCP validation extend facility commissioning timelines. Target acquisition profiles should emphasize biotech ingredient suppliers with established medical food contracts and regional manufacturing hubs positioned for NHS "Net Zero" carbon disclosure compliance. The signal to watch is METI reimbursement code expansion for conditionally essential amino acid claims in Japan's super-aged institutional facilities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Fermentation | Captive supply of recombinant proteins insulates margin from New Zealand dairy auction volatility. |
| MDR Certification for Pump-Nutrition Systems | EU Medical Device Regulation compliance filters low-cost Asian manufacturers from European hospital tenders. |
| Telehealth-Dietitian Hybrid Platform Launch | Remote compliance tracking converts one-time formula sales into subscription recurring revenue streams. |
| Regional Manufacturing Hub Establishment | NHS "Net Zero" procurement favors UK-based production minimizing carbon footprint disclosure penalties. |
| Hospital-Exclusive Distribution Agreement | Formulary access control in North American health systems locks out competing commodity supplement suppliers. |
Research Methodology
Operator-level perspectives from hospital nutrition team directors, enteral compounding pharmacists, wound care center administrators, GPO contracts managers, and home care logistics coordinators anchored the qualitative base. Primary interview insights combined with secondary validation from FDA 21 CFR 101.9(j) filings, EMA clinical nutrition guideline documents, METI reimbursement code databases, NHS Supply Chain procurement records, and hospital formulary databases. Bottom-up patient-population modeling and top-down healthcare expenditure triangulation ensured cross-verification of market sizing assumptions.
Scenario-bracketing around reimbursement framework maturation, precision fermentation scale-up timelines, and regulatory classification divergence shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, application severity, end-user sophistication, and distribution channel margin structure. CAGRs derived from fitted growth curves applied to patient population projections and per-patient-day spending trajectories. Forecast inputs incorporated hospital-at-home policy adoption rates and ISO 22000 HACCP facility commissioning timelines.
Practitioners should monitor EMA member state classification rulings on medical food versus supplement status, New Zealand GlobalDairyTrade auction price movements, and NHS "Net Zero" procurement pilot expansions for early signals requiring forecast revision. Cross-checking against CMS hospital-at-home reimbursement enrollment data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
US Wound Irrigation System Market
Wound Care
Wound Management Market
Wound Care
Wound Retractor Market
Wound Care
South Korea Wound Care Market
Wound Care
Wound Drainage Devices Market
Wound Care
Enzymatic Wound Debridement Market
Wound Care
Interactive Wound Dressing Market
Wound Care
Moist Wound Dressings Market
Wound Care
Wound Irrigation Solutions Market
Wound Care
Maggot Debridement Market
Wound Care
Liquid Bandages Market
Wound Care
Hydrocolloid Dressing Market
Wound Care
Bioadhesive Wound Care Market
Wound Care
Mexico Wound Care Management Devices Market
Wound Care
Antimicrobial Wound Dressings Market
Wound Care
Advanced Wound Care and Dressings Market