
 Post-Operative Wound Treatment Market | 2026-2036
Post-Operative Wound Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Post-Operative Wound Treatment Market Analytics
Hospital group purchasing organization channels is narrowing as integrated delivery networks consolidate supplier contracts across multi-state systems. Smith & Nephew leverages its silicone foam technology leadership to anchor premium contracts with large health systems. Mölnlycke Health Care competes through direct-to-facility logistics networks that bypass traditional distribution tiers. Coloplast specializes in hydrocolloid platforms for outpatient surgical segments where reimbursement favors early discharge protocols.
Post-operative wound treatment encompasses sterile barrier systems, absorbent layers, and active pharmaceutical ingredients applied to incision sites following surgical intervention, typically incorporating polyurethane films, carboxymethyl cellulose fibers, or silver sulfadiazine at concentrations between 0.5% and 1.2% to maintain moist healing environments and prevent bacterial colonization. The technology dimension shows antimicrobial platforms commanding premium positioning as hospital-acquired infection protocols tighten, while hydrocolloid formulations sustain volume leadership in ambulatory settings where wear time and patient compliance drive selection. Application segmentation reveals surgical wounds generating the dominant revenue pool, though chronic wound crossover indications are expanding as payers bundle post-discharge care costs.
The FDA's 510(k) premarket notification framework and the EU Medical Device Regulation (MDR) class IIa requirements shape product development timelines and clinical evidence standards for antimicrobial claims. The EPA regulates silver ion release thresholds in environmental discharge contexts, adding compliance layers to manufacturing scale-up decisions. Stakeholders must monitor evolving CMS bundled payment models for surgical episodes, as these reimbursement structures increasingly determine whether advanced dressings receive formulary placement versus commodity alternatives.
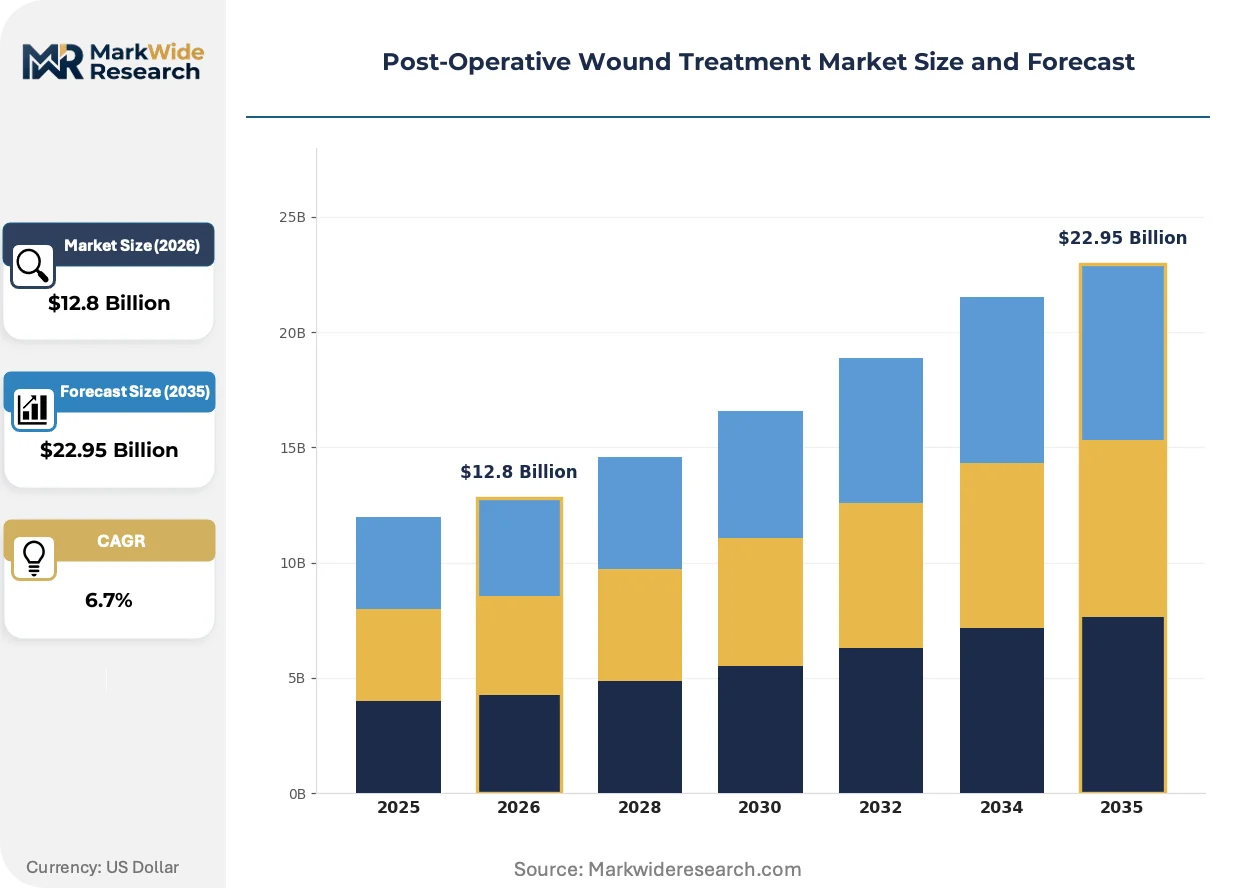
Market Dynamics
Integrated delivery network consolidation is compressing supplier tiers, forcing wound care manufacturers to secure multi-state formulary placements through single contract negotiations rather than incremental hospital wins.
Growth Catalysts
- CMS bundled payment expansion:Surgical episode reimbursement models incentivize advanced dressings that reduce readmission penalties across US ambulatory networks.
- Silver ion release technology:Antimicrobial platforms meeting EPA discharge thresholds command premium positioning as hospital-acquired infection protocols tighten.
- Germany:Ambulatory surgical center network expansion drives hydrocolloid volume for early discharge protocols reimbursed through statutory health insurance.
Market Restraints
- Carboxymethyl cellulose fiber supply:Input concentration among Nordic pulp processors creates price volatility for absorbent layer manufacturers.
- EU MDR class IIa clinical evidence requirements:Antimicrobial claim substantiation extends development timelines by 18-24 months for novel silver formulations.
- Commodity gauze substitution:Cost-containment pressures in emerging markets divert procurement toward basic sterile barriers despite inferior moisture management.
Strategic Opportunities
- Japan home care transition:METI-funded post-acute programs create demand for extended-wear silicone foam dressings in community nursing settings.
- Polyurethane film + biosensor convergence:Real-time moisture detection integrated into barrier layers enables remote monitoring reimbursement under telehealth codes.
- Direct-to-facility logistics:Bypassing distributor tiers captures margin compression from group purchasing organization consolidation.
Industry Challenges
- Biocompatibility testing capacity:ISO 10993-5 cytotoxicity validation bottlenecks delay 510(k) submissions for antimicrobial platforms.
- Legacy EHR integration:Wound documentation modules in hospital information systems require manual bridge development for automated dressing replenishment triggers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Post-Operative Wound Treatment Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dressings, Adhesives, Gels, Sprays Technology: Antimicrobial, Hydrocolloid, Hydrogel, Alginate Application: Surgical Wounds, Traumatic Wounds, Burn Wounds, Chronic Wounds End User: Hospitals, Clinics, Home Care, Long-term Care Facilities |
| Companies Covered | 3M, Smith & Nephew, Mölnlycke Health Care, ConvaTec Group, Coloplast, Baxter International, Integra LifeSciences, URGO Medical, Medline Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Post-Operative Wound Treatment Market Evolving Landscape
Antimicrobial efficacy claims are becoming the primary axis of competitive differentiation as payers link reimbursement to infection rate metrics rather than unit cost alone.
Negative pressure wound therapy integrated dressings are rendering obsolete conventional absorbent pads in high-risk surgical closures. Cardiovascular and orthopedic service lines at tertiary centers in the United States are adopting these systems within 48 hours of incision. The technology is rendering obsolete standard-of-care protocols that relied on visual inspection for exudate management.
REACH authorization requirements for silver nanoparticles are forcing reformulation of antimicrobial platforms toward ionic silver complexes with documented environmental fate profiles. Manufacturers serving EU markets must resubmit technical dossiers for existing product lines by 2026 deadlines. German and French hospital procurement coalitions are prioritizing suppliers with completed substance registrations to avoid supply interruptions.
Consolidated contracting through multi-state health systems is compressing vendor lists to three approved suppliers per dressing category. Integrated delivery networks in the United States are replacing individual hospital purchasing autonomy with centralized formulary committees. This concentration is most visible in Texas and Florida systems where ambulatory surgical center rollups have accelerated post-COVID.
Post-Operative Wound Treatment Market Segmentation
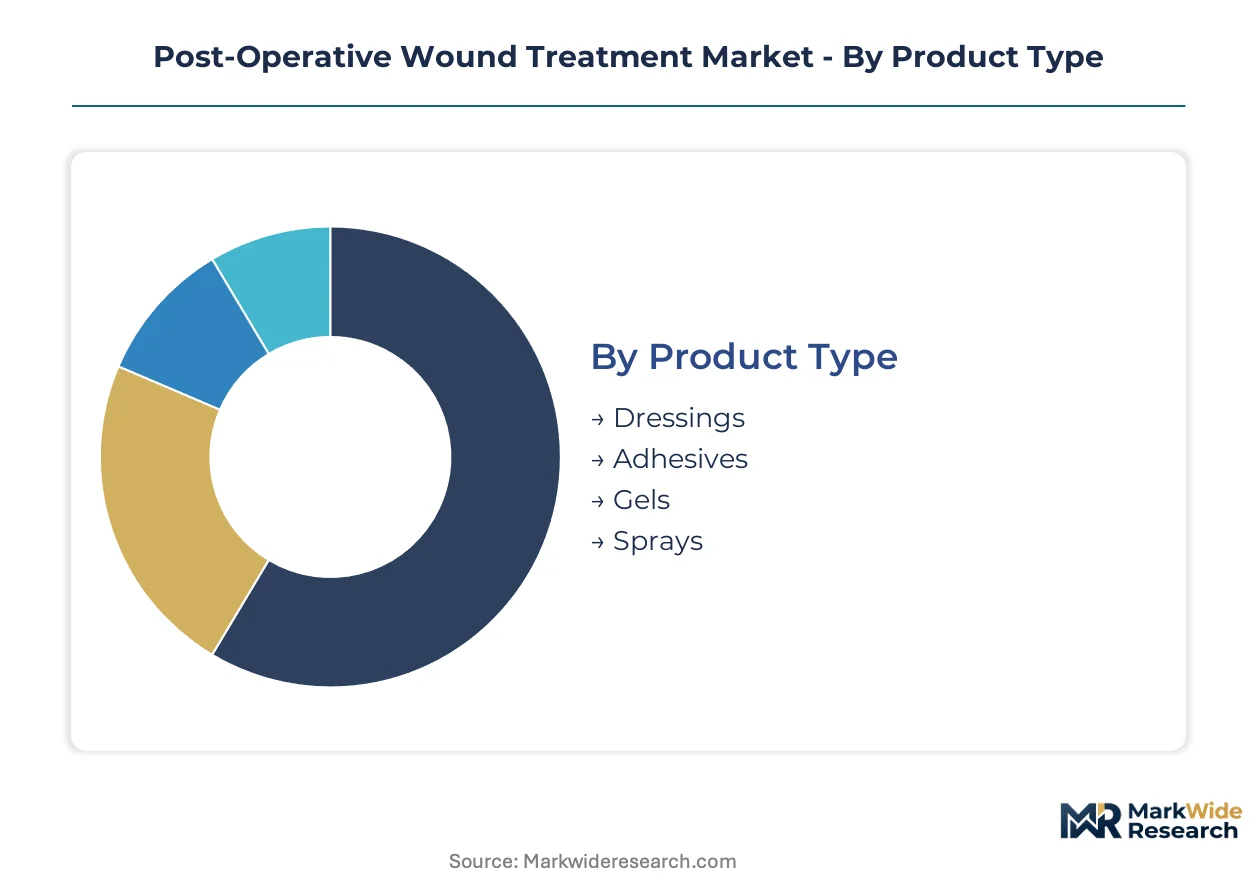
Post-operative wound treatment segmentation reveals distinct procurement patterns across acute versus ambulatory settings. Technology and application dimensions drive reimbursement eligibility and formulary placement decisions more than unit economics alone.
Product Type:
Mature absorbent platforms dominate hospital procurement volumes, while emerging delivery formats capture outpatient growth corridors.
- Dressings:Polyurethane films, silicone foams, and hydrocolloid layers constitute the core sterile barrier systems used in incision management. United States integrated delivery networks concentrate purchase orders through group purchasing organization channels that favor extended-wear silicone variants with 7-day adhesion profiles.
- Adhesives:Medical-grade acrylic and silicone-based skin bonding agents secure barrier systems to periwound tissue. German ambulatory surgical centers source these through statutory health insurance reimbursement frameworks that prioritize gentle removal protocols for early discharge pathways.
- Gels:Amorphous hydrogel formulations provide moisture donation to dry wound beds.
- Sprays:Aerosolized polymer barriers offer film-forming protection for irregular anatomical contours.
Dressings handle the majority of throughput; sprays are the fastest mover on share.
Technology:
Cost tier separation runs deepest in this dimension, with antimicrobial platforms commanding premium positioning against commodity hydrocolloid alternatives.
- Antimicrobial:Silver ion release systems and iodine-impregnated matrices deliver bacterial load reduction at incision sites. Japan's METI-funded post-acute programs specify these for community nursing settings where infection surveillance is limited.
- Hydrocolloid:Carboxymethyl cellulose fiber matrices form cohesive gels upon exudate contact to maintain moist healing environments. United States ambulatory surgical networks favor these for low-exudate closures where reimbursement favors rapid patient turnover.
- Hydrogel:Cross-linked polymer networks donate moisture to autolytic debridement.
- Alginate:Calcium-sodium seaweed-derived fibers convert to gel upon fluid contact.
Hydrocolloid maintains volume leadership; antimicrobial is expanding most quickly on value contribution.
Application:
Customer type concentration varies sharply across wound etiology, with surgical closures generating predictable demand versus chronic wound crossover requiring outcome-based contracting.
- Surgical Wounds:Clean and contaminated incision sites following operative intervention represent the primary reimbursement category under CMS bundled payment models. Cardiovascular and orthopedic service lines at tertiary United States centers specify negative pressure wound therapy integrated systems within 48 hours of closure.
- Traumatic Wounds:Lacerations and penetrating injuries requiring operative debridement drive demand for high-absorbency alginate platforms. Emergency department procurement in Germany routes these through hospital pharmacy formularies with antimicrobial preference protocols.
- Burn Wounds:Thermal and chemical injuries requiring eschar management.
- Chronic Wounds:Venous leg ulcers and pressure injuries with surgical intervention history.
Surgical wounds absorb the dominant procurement spend; chronic wounds are gaining share fastest through bundled post-discharge contracts.
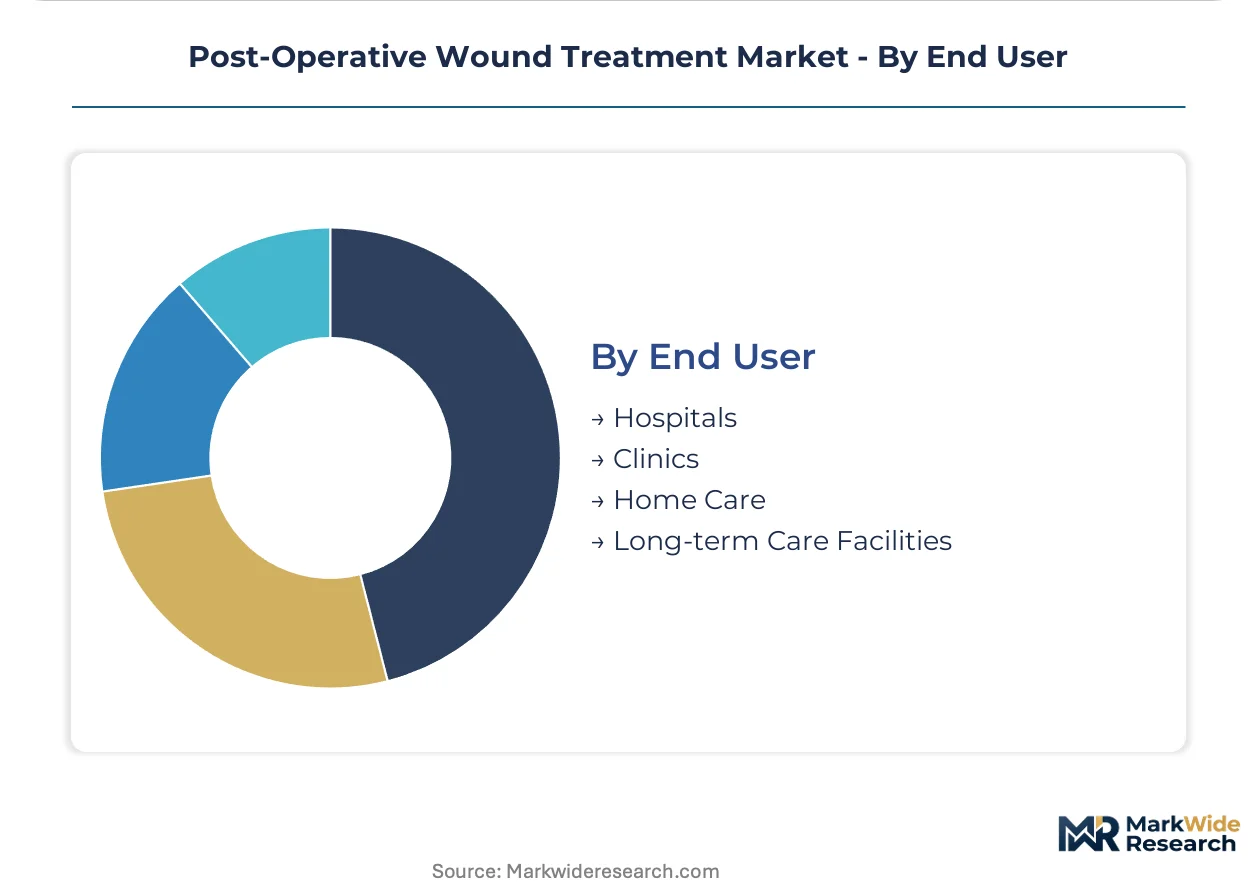
End User:
Volume concentration tilts toward institutional purchasers, though margin expansion follows the shift toward patient-administered care.
- Hospitals:Tertiary and community acute care facilities operate centralized wound care committees that narrow vendor lists to three approved suppliers per dressing category. Texas and Florida health system rollups have accelerated post-COVID, compressing supplier tiers through multi-state formulary consolidation.
- Home Care:Community nursing and self-administered post-acute settings create demand for extended-wear silicone foam with simplified application protocols. Japan's expanding post-acute home care programs reimburse these under telehealth-integrated monitoring codes.
- Clinics:Outpatient wound centers and physician office-based surgery suites.
- Long-term Care Facilities:Skilled nursing and assisted living residences managing post-surgical residents.
Hospitals retain the dominant procurement volume; home care is climbing the fastest on reimbursement reform momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA clearance pathways anchor the United States as the dominant geography, while EU MDR timelines and Japan's METI programs reshape procurement patterns across developed markets. Country-specific regulations and reimbursement structures determine formulary placement and technology adoption rates.
United States
CMS bundled payment expansion for surgical episodes drives integrated delivery networks toward advanced antimicrobial dressings that reduce readmission penalties. The FDA's updated 510(k) pathways for silver ion products compress development timelines for manufacturers targeting hospital formulary committees. Texas and Florida health system rollups concentrate procurement through multi-state contracts that favor extended-wear silicone foam variants.
Germany
Statutory health insurance reimbursement for ambulatory surgical centers prioritizes hydrocolloid platforms enabling early discharge protocols. EU MDR class IIa clinical evidence requirements extend antimicrobial claim substantiation timelines, favoring established suppliers with existing technical dossiers. The Rhine-Ruhr and Bavarian hospital procurement coalitions narrow vendor lists to three approved suppliers per dressing category.
Japan
METI-funded post-acute home care programs create demand for extended-wear dressings in community nursing settings where infection surveillance is limited. PMDA regulatory harmonization with FDA 510(k) frameworks accelerates market entry for antimicrobial platforms with US clearance. The Kanto region around Tokyo anchors specialist wound care demand from aging demographic concentrations.
United Kingdom
NHS England's integrated care systems consolidate wound care procurement across former clinical commissioning group boundaries. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR standards while streamlining UK-specific antimicrobial claims. The Greater Manchester and London health system clusters pilot outcome-based contracting for post-surgical dressing protocols.
China
NMPA medical device registration reforms accelerate market access for imported advanced dressing technologies in tier-one hospitals. Provincial centralized procurement platforms in Guangdong and Jiangsu drive price compression on commodity absorbent products while creating premium segments for antimicrobial platforms. The Yangtze River Delta concentration of tertiary centers generates disproportionate demand for negative pressure wound therapy integrated systems.
Post-Operative Wound Treatment Market Competitive Landscape
Diversified medical technology conglomerates and specialized wound care manufacturers split the market into distinct capability tiers. Supplier consolidation through integrated delivery network contracting has compressed the vendor base from fragmented hospital-by-hospital competition toward multi-state formulary placements. Three strategic archetypes dominate: silicone foam technology leaders securing premium health system contracts, direct-to-facility logistics operators bypassing distribution tiers, and hydrocolloid specialists capturing ambulatory volume through reimbursement-optimized protocols. M&A activity concentrates on antimicrobial platform acquisitions, while capacity expansion focuses on automated carboxymethyl cellulose fiber processing.
Within the diversified medical technology tier, 3M and Baxter International occupy positions spanning adhesive platforms through advanced wound closure systems. Smith & Nephew exemplifies the silicone foam technology leadership archetype through its health system contract anchoring strategy. Mölnlycke Health Care represents the direct-to-facility logistics model with its bypass distribution approach. Coloplast sits within the outpatient-focused specialization segment where hydrocolloid platforms align with early discharge reimbursement incentives.
| Leading Market Players |
|---|
| 3M |
| Smith & Nephew |
| Mölnlycke Health Care |
| ConvaTec Group |
| Coloplast |
| Baxter International |
| Integra LifeSciences |
| URGO Medical |
| Medline Industries |
| Others |
Value Network & Pricing Analysis
Carboxymethyl cellulose fiber concentration among Nordic pulp processors creates simultaneous input volatility and pricing tier compression, forcing absorbent layer manufacturers to absorb margin erosion or reformulate toward synthetic alternatives while hospital group purchasing organizations exploit supplier fragility to extract contract concessions.
Pricing Analysis
The customization-premium spread separates configured-to-order antimicrobial platforms from standard hydrocolloid volumes, with three-tier pricing structure across premium, standard, and economy levels anchored by FDA 510(k) certification tier and silver ion release performance. Price differentiation hinges on clinical evidence depth and geographic delivery cost to integrated delivery networks. Cost compression in economy tiers intensifies because commodity gauze substitution pressures divert emerging market procurement toward basic sterile barriers. Ambulatory surgical centers exhibit highest price sensitivity; tertiary cardiovascular service lines show lowest sensitivity due to bundled payment readmission penalty exposure.
Supply Chain Analysis
Export-control regime angles from EU REACH authorization requirements for silver nanoparticles limit antimicrobial platform flows into European markets, forcing reformulation toward ionic silver complexes with documented environmental fate profiles. Geographic supply concentration centers on Sweden and Finland for carboxymethyl cellulose fiber, Germany for polyurethane film substrates, and Japan for silicone adhesive polymers. Raw material dependencies include Nordic softwood pulp, medical-grade silicone elastomers, and silver nitrate precursors. Single-source vulnerability in cellulose fiber processing creates bottleneck risk. Distribution runs through consolidated group purchasing organization channels that bypass traditional distributor tiers toward direct-to-facility logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Post-operative wound treatment market fragmentation creates entry niches as home care transition in Japan and telehealth-integrated reimbursement codes split demand away from hospital-centric procurement patterns.
For Market Incumbents: Build regulatory moat through accelerated EU MDR technical dossier completion ahead of 2026 deadlines to capture German and French hospital procurement coalition preference. Secure backward integration into carboxymethyl cellulose fiber processing to neutralize Nordic pulp processor concentration risk. Anchor multi-state formulary placements through extended-wear silicone foam technology leadership before integrated delivery network consolidation completes in Texas and Florida systems. For New Entrants and Emerging Players: Build out community nursing presence in Japan's METI-funded post-acute programs where infection surveillance limitations create antimicrobial platform demand without established incumbent lock-in. Target home care segment penetration through simplified application protocol development for extended-wear dressings. Pursue reimbursement strategy centered on telehealth-integrated monitoring codes that bypass hospital formulary committee gatekeeping. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors antimicrobial platform specialists with completed regulatory dossiers over commodity hydrocolloid volume players. Long-term viability over the projection horizon rests on infection rate metric linkage to reimbursement rather than unit cost competition. Acquisition target archetype includes ionic silver formulation developers with REACH-compliant environmental fate documentation. Watch CMS bundled payment model expansion into additional surgical episode categories as inflection indicator for advanced dressing formulary prioritization.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerated clearance pathways for silver ion products compress development timelines for hospital formulary targeting. |
| CE Marking Pathway | EU MDR class IIa clinical evidence requirements extend timelines but create barrier against non-compliant competitors. |
| Hospital System Partnership | Multi-state integrated delivery network contracts concentrate procurement through three-supplier vendor lists. |
| Software Companion Development | Real-time moisture detection integration enables remote monitoring reimbursement under telehealth codes. |
| Reimbursement Strategy | CMS bundled payment alignment positions advanced dressings to reduce readmission penalties versus commodity alternatives. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR technical dossiers, hospital procurement databases, and CMS Medicare reimbursement data through structured interviews with wound care clinicians, hospital purchasing committee members, biomedical engineers, and group purchasing organization contracts managers. Bottom-up triangulation across product-level demand modeling and top-down validation against statutory health insurance reimbursement frameworks ensures cross-verification of volume and value estimates.
Forecast inputs include surgical procedure volume trajectories, ambulatory surgical center network expansion rates, and antimicrobial claim substantiation timeline assumptions across the analysis window. Segmentation dimensions span product type, technology platform, wound etiology, and end-user setting with specific modeling of silicone foam versus hydrocolloid adoption curves. CAGRs derive from procedure volume elasticity to reimbursement reform and technology substitution dynamics in negative pressure wound therapy integration.
Stress conditions across EU MDR deadline compliance rates, Nordic pulp processor pricing volatility, and CMS bundled payment expansion scope were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory pathway timelines and reimbursement code adoption. Material shifts in EPA silver ion discharge threshold enforcement or REACH authorization scope expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Bioactive Wound Management Market
Wound Care
Mexico Wound Care Management Devices Market
Wound Care
Advanced Wound Care and Dressings Market
Wound Care
Wound Care Centers Market
Wound Care
Infectious Wound Care Management Market
Wound Care
Global Compression Bandages Market
Wound Care
Wound Debridement Products Market
Wound Care
Wound Management Market
Wound Care
Animal Wound Care Market
Wound Care
North America Wound Care Management Market
Wound Care
Wound Closure Devices Market
Wound Care
Advanced Wound Dressings Market
Wound Care
Global Negative Pressure Wound Therapy (NPWT) Devices Market
Wound Care
Wound Healing Nutrition Market
Wound Care
Next Generation Wound Closure Device Market
Wound Care
Advanced Wound Therapy Devices Market