
 Advanced Wound Care Market | 2026-2036
Advanced Wound Care Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced Wound Care Market Intelligence
The EU Medical Device Regulation is broadening the cost-of-entry calculus for advanced wound care manufacturers seeking CE-marked distribution across member states. Smith & Nephew leverages its vertically integrated manufacturing footprint to absorb heightened clinical trial obligations without outsourcing validation work. Mölnlycke Health Care AB anchors its competitive position through proprietary silicone adhesive platforms that reduce trauma during dressing changes. ConvaTec Group differentiates via ostomy and wound convergence, sustaining dual-channel leverage in acute and home settings.
Advanced wound care encompasses dressings, devices, and biologics engineered to maintain moist healing environments, manage exudate, prevent infection, and accelerate tissue regeneration through active substrates such as hydrocolloid matrices, antimicrobial silver ions, or bioengineered collagen scaffolds. Foam dressings and negative pressure wound therapy systems command the largest revenue pools due to established reimbursement codes and surgical wound volume, while bioengineered skin and growth factor therapy segments attract premium pricing despite narrower addressable populations. Antimicrobial dressings compete on clinical outcomes data, with alginate-hybrid formats gaining traction in heavily exuding ulcers where infection risk escalates.
The FDA governs premarket pathways for bioengineered skin substitutes through PMA and 510(k) frameworks, while the EMA and notified bodies enforce MDR compliance timelines that compress commercialization schedules. BIS certification requirements in India and NMPA registration in China add parallel approval burdens for multinational portfolios. Stakeholders must monitor how real-world evidence mandates reshape post-market surveillance obligations and whether home healthcare reimbursement expansion alters the site-of-care economics that currently favor hospital-based negative pressure systems.
Market Dynamics
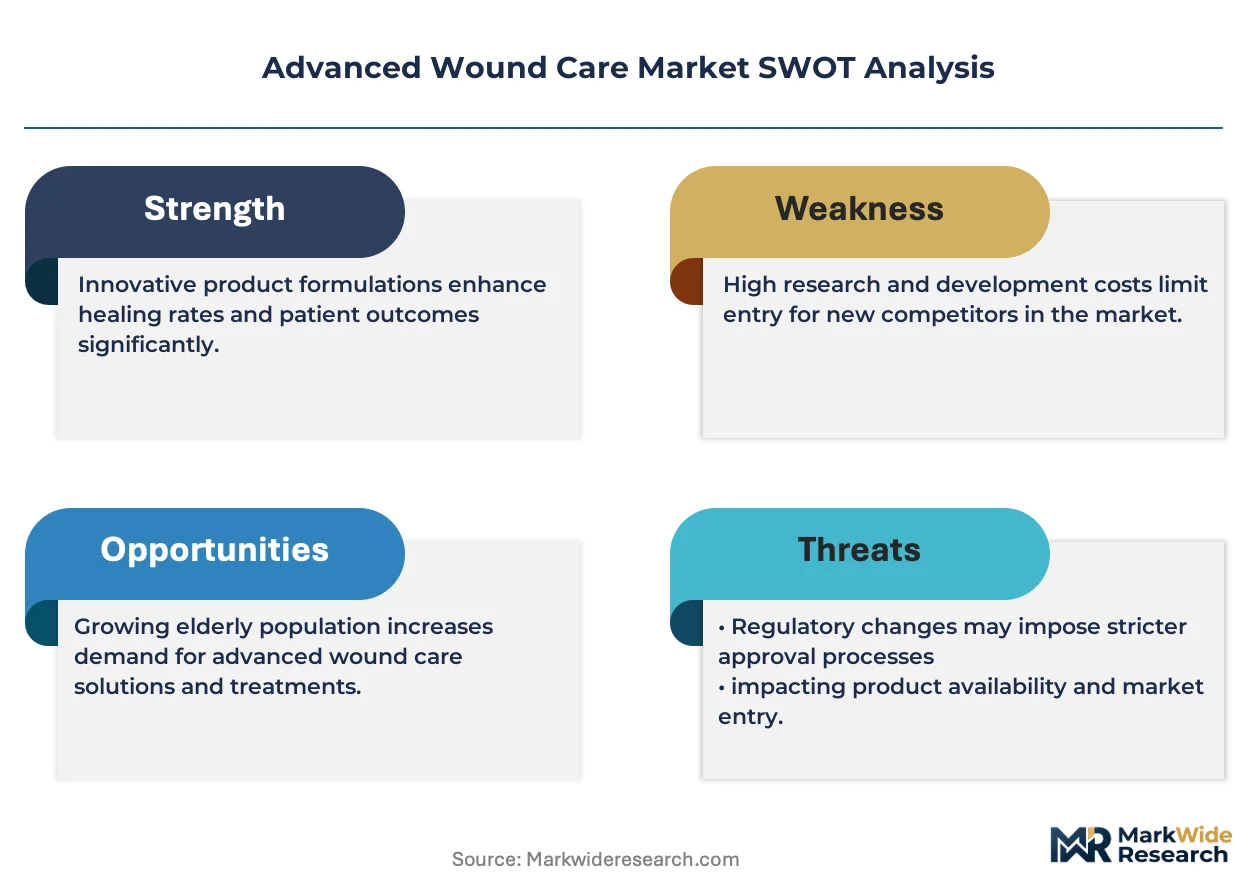
Hospital infection control protocols are tightening antimicrobial dressing specifications while the EU MDR compresses commercialization timelines, forcing manufacturers to absorb clinical trial costs or exit CE-marked markets entirely.
Growth Catalysts
- Silver-ion alginate hybrids:These formats penetrate heavily exuding diabetic ulcers where infection risk escalates, capturing volume from standard foam dressings in tertiary wound centers.
- MDR clinical evidence mandates:Elevated post-market surveillance obligations in Europe are filtering out undercapitalized competitors, concentrating procurement among validated suppliers.
- Home healthcare expansion:Reimbursement alignment for portable negative pressure systems in the United States is shifting site-of-care economics toward outpatient settings.
Market Restraints
- Biologic scaffold input costs:Collagen sourcing from porcine and bovine tissues faces veterinary health certificate volatility and tannery byproduct competition.
- Notified body bottleneck:EU MDR designation delays have stretched CE-marking timelines to 18-24 months, freezing portfolio refreshes for mid-tier manufacturers.
- Standard gauze substitution:Cost-conscious long-term care facilities in emerging markets continue defaulting to basic dressings despite inferior healing outcomes.
Strategic Opportunities
- India BIS certification pathway:Domestic manufacturing incentives under the PLI scheme enable tariff-advantaged supply to Southeast Asian hospital networks.
- 3D bioprinted skin convergence:Integration of patient-derived keratinocyte cultures with printable collagen matrices opens autologous graft applications for burn centers.
- Telehealth-integrated dressing sensors:pH and temperature monitoring substrates enable remote wound assessment, capturing value from home health nursing shortages.
Industry Challenges
- Wound care specialist training gaps:Tissue viability nursing certification programs lag device innovation cycles, creating adoption friction for bioactive formats.
- Multinational quality system harmonization:Parallel FDA 510(k), EMA MDR, and NMPA registration requirements demand redundant clinical dossiers and inspection readiness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced Wound Care Market |
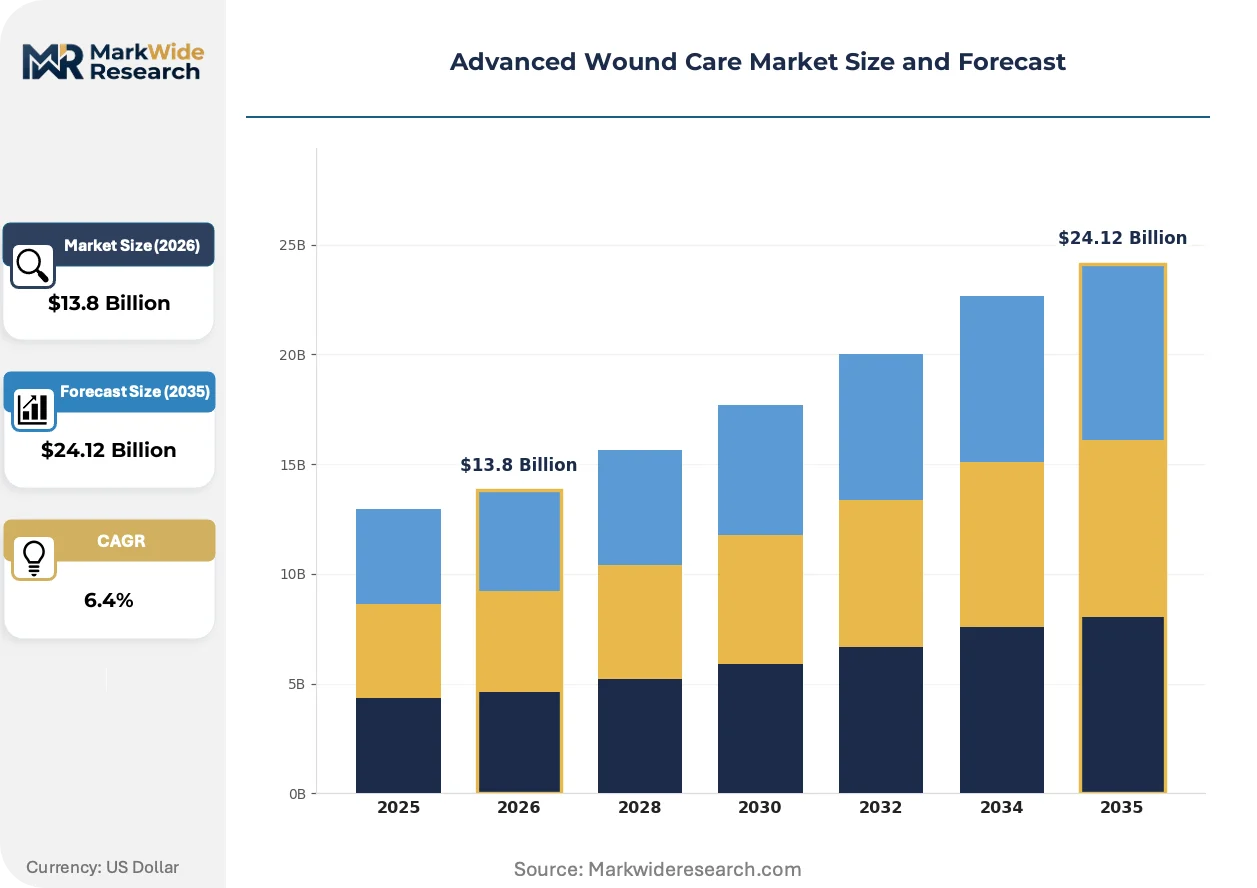
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $24.12 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrocolloid Dressings, Foam Dressings, Alginate Dressings, Antimicrobial Dressings Technology: Negative Pressure Wound Therapy, Bioengineered Skin, Growth Factor Therapy, Electrical Stimulation Therapy End User: Hospitals, Home Healthcare, Outpatient Clinics, Long-Term Care Facilities Application: Diabetic Ulcers, Pressure Ulcers, Surgical Wounds, Trauma Wounds |
| Companies Covered | Smith & Nephew, ConvaTec Group, 3M Company, Mölnlycke Health Care AB, B. Braun Melsungen AG, Coloplast, Integra LifeSciences, Organogenesis, Cardinal Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced Wound Care Market Strategic Shifts & Innovations
Bioengineered substrates and connected monitoring capabilities are compressing the gap between passive moisture management and active tissue regeneration, while regulatory fragmentation forces parallel compliance investments.
Antimicrobial peptides synthesized from human defensin sequences are rewriting infection prevention protocols in chronic wound protocols. Academic medical centers in Germany and the United States are piloting these alternatives to silver-based dressings for patients with metal sensitivities. The technology is rewriting competitive positioning by decoupling antimicrobial efficacy from cytotoxicity concerns that constrain silver-ion dosing.
REACH restrictions on nanoscale silver particle release are compelling reformulation of antimicrobial dressings across EU member states. Manufacturers must submit updated safety dossiers by 2025 for existing registrations, accelerating migration toward ionic silver and polyhexamethylene biguanide alternatives. Wound care portfolios with heavy nanosilver exposure face concentrated compliance costs in France and Italy where environmental agency enforcement is tightening.
Hospital procurement committees are consolidating vendor relationships through integrated wound management contracts that bundle dressings, negative pressure devices, and clinical training. Group purchasing organizations in the United States are displacing fragmented product-by-product tenders with multi-year sole-source agreements tied to outcome metrics. This concentration is most visible in the Southeast and Midwest regions where health system consolidation has reduced independent community hospital purchasing autonomy.
Advanced Wound Care Market Segmentation
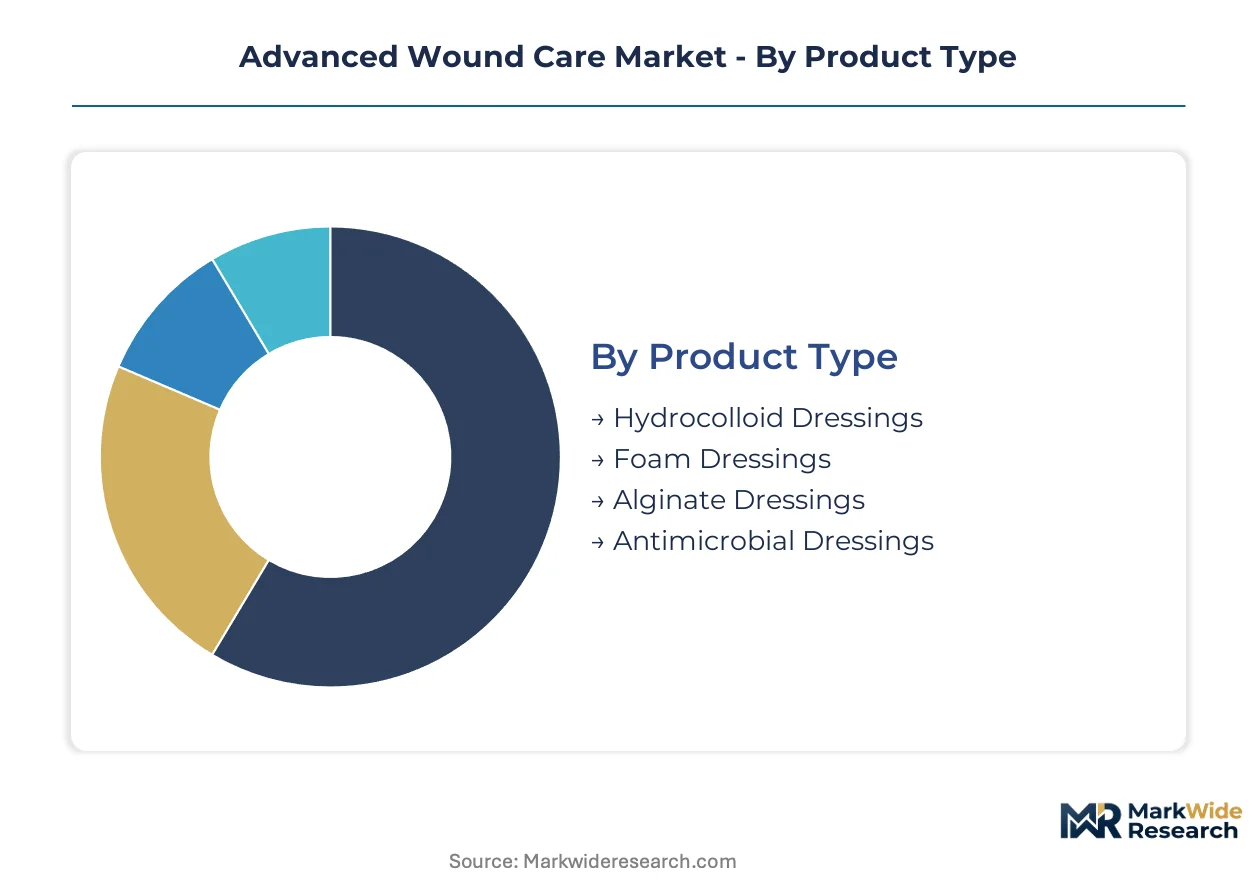
Segmentation in advanced wound care reveals divergent capital requirements across substrate chemistry, device complexity, and reimbursement pathways. Manufacturers must align portfolio investments with site-of-care economics and regulatory validation burdens.
Product Type:
Capital intensity peaks in antimicrobial formats requiring clinical evidence dossiers for CE marking, while foam and hydrocolloid platforms leverage commoditized manufacturing infrastructure.
- Antimicrobial Dressings:Silver-ion and polyhexamethylene biguanide matrices command premium positioning through infection prevention claims. Hospital procurement committees in the United States prioritize these formats for diabetic ulcer protocols where readmission penalties escalate costs.
- Foam Dressings:Polyurethane absorbent layers manage exudate across surgical and trauma applications. Volume concentrates in tertiary wound centers where negative pressure compatibility drives specification.
- Hydrocolloid Dressings:Carboxymethylcellulose-based moisture-retentive substrates serve low-exudate chronic wounds. Cost-conscious long-term care facilities default to these formats for pressure ulcer maintenance.
- Alginate Dressings:Calcium-sodium fiber matrices derived from brown seaweed address heavily exuding wounds. Demand clusters in burn units where conformability to irregular wound beds matters.
Most installed capacity flows through foam dressings. Expansion is steepest in antimicrobial formats.
Technology:
Margin profiles separate capital-intensive biologic platforms from device-based therapies with recurring consumable revenue.
- Negative Pressure Wound Therapy:Vacuum-assisted closure systems generate sustained revenue through canister and dressing replacements. Reimbursement alignment for portable units in United States home health settings is shifting site-of-care economics.
- Growth Factor Therapy:Recombinant platelet-derived growth factor formulations require cold-chain distribution and specialized pharmacy handling. Prescription concentration in academic medical centers limits addressable population.
- Bioengineered Skin:Acellular dermal matrices and cultured keratinocyte grafts demand bioreactor infrastructure and GMP-certified facilities. EMA and FDA premarket approval pathways compress commercialization timelines for new entrants.
- Electrical Stimulation Therapy:Bioelectric dressings delivering microcurrent to chronic wounds occupy niche positioning. Adoption friction persists due to limited specialty nursing training and inconsistent payer coverage.
Device-based negative pressure systems capture the largest revenue pool. Bioengineered skin platforms are climbing the fastest on per-procedure pricing.
End User:
Procurement sophistication varies sharply across institutional settings, dictating sales force structure and clinical support investment.
- Hospitals:Integrated wound management contracts bundle dressings, devices, and staff training. Group purchasing organizations in United States health systems consolidate vendor relationships through multi-year outcome-based agreements.
- Home Healthcare:Portable negative pressure and advanced dressing formats benefit from reimbursement expansion. Nursing shortages accelerate demand for telehealth-integrated monitoring capabilities.
- Outpatient Clinics:Wound care centers affiliated with hospital networks access shared purchasing contracts. Independent clinics face working capital constraints for bioengineered product inventory.
- Long-Term Care Facilities:Pressure ulcer prevention protocols drive basic dressing volume. Budget limitations sustain standard gauze substitution despite inferior healing metrics.
Hospital procurement committees control the largest volume share. Home healthcare channels are gaining share fastest on site-of-care migration.
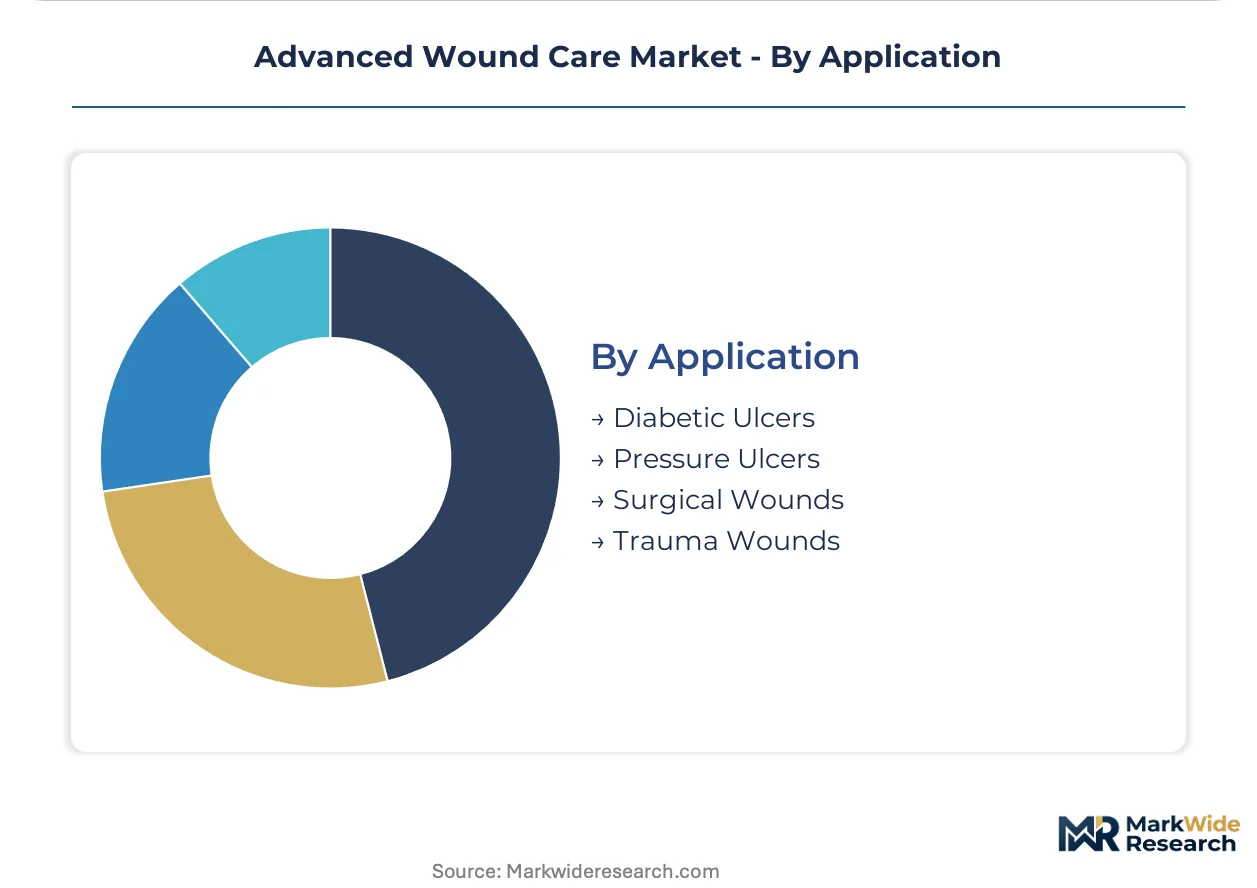
Application:
Disease prevalence and complication risk stratify addressable populations and pricing power across wound etiologies.
- Diabetic Ulcers:Lower extremity wounds in diabetic patients require antimicrobial intervention and offloading coordination. United States prevalence sustains volume leadership for advanced dressing formats.
- Surgical Wounds:Post-operative incision management drives negative pressure and foam dressing adoption. Elective procedure volumes in hospital systems determine seasonal demand patterns.
- Pressure Ulcers:Facility-acquired wounds trigger penalty structures under United States value-based care programs. Prevention protocols compete with treatment spend for capital allocation.
- Trauma Wounds:Acute injury management in emergency departments favors rapid-application foam and hydrocolloid formats. Military and mass casualty preparedness stockpiles create non-recurring demand spikes.
Surgical wound applications deploy the broadest installed base. Diabetic ulcer segments are expanding most quickly on chronic disease prevalence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized wound care nursing certification programs concentrate in Germany, the United Kingdom, and the United States, anchoring clinical trial infrastructure and bioengineered product adoption corridors.
United States
Diabetic ulcer prevalence and Medicare reimbursement alignment for negative pressure wound therapy sustain volume leadership. FDA PMA pathways for bioengineered skin substitutes compress commercialization timelines for new entrants. The Research Triangle Park corridor in North Carolina hosts contract research organizations supporting wound care clinical validation.
Germany
Academic medical centers in Berlin and Munich pilot antimicrobial peptide alternatives to silver-based dressings for metal-sensitive patients. EMA MDR enforcement through notified bodies elevates clinical evidence requirements for CE-marked distribution. The Baden-Württemberg cluster anchors silicone adhesive manufacturing for advanced dressing platforms.
United Kingdom
NHS integrated care systems consolidate wound management procurement through multi-year outcome-based contracts. MHRA post-Brexit regulatory divergence from EU MDR creates parallel registration burdens for multinational portfolios. Greater Manchester hosts tissue viability nursing training centers accelerating bioactive format adoption.
India
Domestic manufacturing incentives under the PLI scheme enable tariff-advantaged supply to Southeast Asian hospital networks. CDSCO and BIS certification requirements add parallel approval burdens for imported bioengineered products. The Maharashtra pharmaceutical corridor near Mumbai anchors contract manufacturing for alginate-hybrid dressings.
China
NMPA registration timelines for Class III medical devices stretch commercialization schedules for bioengineered skin platforms. Provincial hospital procurement reforms in Guangdong and Jiangsu prioritize domestic negative pressure wound therapy systems. The Yangtze River Delta cluster concentrates foam dressing manufacturing capacity.
Advanced Wound Care Market Key Industry Players
The competitive structure tilts toward vertically integrated multinationals with captive clinical trial infrastructure. Hospital procurement consolidation through group purchasing organizations favors suppliers with multi-product portfolios and training capabilities. Three archetypes dominate: diversified medical technology conglomerates, specialized wound care pure-plays, and contract manufacturers with regulatory navigation expertise. Capacity expansion and strategic partnerships represent the dominant competitive moves, with M&A activity concentrating in bioengineered skin and antimicrobial dressing segments.
Among diversified medical technology conglomerates, Smith & Nephew plc and 3M Company exemplify scale-driven positions spanning dressings, devices, and biologics. Mölnlycke Health Care AB occupies a specialized tier focused on silicone adhesive platforms and surgical wound management. These three anchors illustrate how geographic footprint breadth and regulatory dossier depth separate procurement winners from mid-tier suppliers facing CE-marking bottlenecks.
| Leading Market Players |
|---|
| Smith & Nephew |
| ConvaTec Group |
| 3M Company |
| Mölnlycke Health Care AB |
| B. Braun Melsungen AG |
| Coloplast |
| Integra LifeSciences |
| Organogenesis |
| Cardinal Health |
| Others |
Cost & Logistics Intelligence
Silver price volatility on the London Bullion Market Association index cascades through antimicrobial dressing manufacturing into three distinct pricing tiers, with ionic silver formats commanding premiums over nanosilver alternatives facing REACH compliance costs.
Pricing Analysis
Bundled service contracts integrating dressings with clinical training and outcome monitoring capture 40-60% price premiums over unbundled product-only transactions. Three-tier pricing structure across premium antimicrobial formats, standard foam platforms, and economy hydrocolloid alternatives reflects certification grade differentiation under FDA PMA versus 510(k) pathways. Cost compression in economy tiers intensifies because long-term care facilities substitute standard gauze despite inferior healing metrics. Hospital procurement committees demonstrate lowest price sensitivity due to readmission penalty avoidance, while nursing homes exhibit highest sensitivity to per-unit dressing costs.
Supply Chain Analysis
Regional distribution centers in the United States, Germany, and China operate hub-and-spoke patterns feeding hospital networks and home health agencies. Manufacturing concentration centers on the United States for bioengineered skin bioreactors, Ireland for silicone adhesive platforms, and China for foam dressing polyurethane substrates. Raw material portfolios draw from seaweed harvesting operations in Norway and France for alginate fibers, porcine and bovine tanneries in the United States and Brazil for collagen scaffolds, and silver mining output from Mexico and Peru for antimicrobial ion supply. Single-source vulnerability in pharmaceutical-grade collagen sourcing creates supply chain risk given veterinary health certificate delays. Distribution runs through GPO-negotiated direct-to-hospital channels in North America and distributor-mediated hospital networks in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Advanced wound care has matured into a late-cycle quality story where antimicrobial peptide alternatives and bioengineered skin substitutes command sustainable premiums as hospital infection protocols tighten specifications for metal-sensitive patient populations.
For Market Incumbents: Deepen backward integration into pharmaceutical-grade collagen supply through captive tannery partnerships or bioreactor infrastructure investments to offset porcine tissue input volatility. Fortify CE-marking dossiers ahead of MDR clinical evidence mandates to filter out undercapitalized competitors facing 18-24 month notified body delays. Prioritize silicone adhesive platform R&D to defend Mölnlycke's trauma-reduction positioning against commodity foam encroachment. For New Entrants and Emerging Players: Enter via telehealth-integrated dressing sensors targeting home healthcare nursing shortages in the United States Southeast and Midwest, where reimbursement alignment for remote monitoring creates white-space. Pursue BIS certification under India's PLI scheme to access tariff-advantaged supply corridors into Southeast Asian hospital networks. Anchor initial commercial traction through 3D bioprinted skin partnerships with academic burn centers seeking autologous graft capabilities. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier antimicrobial dressing manufacturers possessing validated MDR dossiers but lacking GPO contract scale to negotiate integrated wound management agreements. Five-to-ten year viability hinges on portfolio breadth spanning dressings, devices, and biologics rather than single-format dependence. Monitor FDA PMA approval velocity for bioengineered skin substitutes as inflection indicator for premium pricing sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR clinical evidence mandates filter out undercapitalized competitors in European markets. |
| Hospital System Partnership | Integrated wound management contracts bundle training with dressings to secure multi-year sole-source agreements. |
| Backward Integration into Collagen Supply | Captive sourcing of porcine and bovine tissue insulates against veterinary health certificate volatility. |
| Software Companion Development | pH and temperature monitoring substrates capture value from home health nursing shortages through telehealth integration. |
| Reimbursement Strategy | Medicare alignment for portable negative pressure systems shifts site-of-care economics toward outpatient settings. |
Research Approach
Direct dialogue with hospital procurement managers, tissue viability nursing directors, biomedical engineers, and GPO contracts specialists grounded qualitative insights in operational reality. Secondary validation drew from FDA PMA and 510(k) filings, EMA MDR submission databases, hospital procurement contract repositories, and CMS Medicare reimbursement schedules. Bottom-up demand modeling across dressing format, technology platform, and end-user facility type triangulated against top-down macroeconomic indicators.
Segment-level projections across antimicrobial, foam, hydrocolloid, and alginate dressing categories combined with negative pressure device, growth factor therapy, and bioengineered skin technology tiers informed value and volume outputs across the projection horizon. CAGRs were derived from procedure volume elasticity to diabetic ulcer prevalence, surgical wound incidence, and pressure ulcer penalty structures. Forecast inputs incorporated reimbursement code expansion trajectories for home healthcare portable systems and notified body capacity constraints affecting CE-marking timelines.
Inputs from hospital procurement databases and GPO contract disclosures were available through the study window; gaps in real-world evidence submission timelines for MDR compliance introduce uncertainty bands around European market penetration assumptions. Forecasts reflect documented assumptions regarding regulatory pathway durations and reimbursement alignment velocities. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Post-Operative Wound Treatment Market
Wound Care
Dental Wound Dressings Market
Wound Care
Global Negative Pressure Wound Therapy (NPWT) Devices Market
Wound Care
Brazil Wound Care Management Devices Market
Wound Care
Vascular Dressings Market
Wound Care
Wound Care Market
Wound Care
Wound Contact Layer Dressing Market
Wound Care
Next Generation Wound Closure Device Market
Wound Care
Chronic Wound Care Market
Wound Care
Interactive Wound Dressing Market
Wound Care
Wound Evacuators Market
Wound Care
Mexico Wound Care Management Devices Market
Wound Care
Middle East and Africa Advanced Wound Care Market
Wound Care
Wound Drainage Devices Market
Wound Care
Hydrocolloid Dressing Market
Wound Care
Bioactive Wound Dressing Market