
 Europe Advanced Wound Care Market | 2026-2036
Europe Advanced Wound Care Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Advanced Wound Care Market Insights
Hospital procurement of antimicrobial dressings is restructuring the buyer landscape across Europe, shifting volume toward centralized tender frameworks. Smith & Nephew PLC leverages its negative pressure wound therapy portfolio to dominate acute care contracts in the United Kingdom. Mölnlycke Health Care AB anchors its position through advanced foam manufacturing scale and direct hospital channel control. Coloplast AS specializes in hydrocolloid innovation for outpatient and home care transitions.
Advanced wound care comprises bioactive dressings, negative pressure systems, and electrical stimulation devices engineered to accelerate healing in chronic or complex wounds through moisture balance, infection control, and tissue regeneration. These products typically integrate superabsorbent polymers, silver ion matrices, or polyurethane foam layers to maintain optimal wound bed conditions. Antimicrobial dressings lead product type revenue due to reimbursement alignment with surgical site infection protocols, while smart dressings represent the fastest-growing technology segment as sensor-enabled moisture and pH monitoring gain clinical validation. Home care end users command expanding share as post-acute discharge protocols shorten hospital stays.
The EU Medical Device Regulation (MDR) and EMA guidance on bioactive wound products shape clinical evidence requirements and market access timelines across member states. CE marking under MDR demands expanded biocompatibility testing for alginate and biosynthetic dressings, favoring established players with dedicated regulatory affairs infrastructure. REACH compliance for chemical additives in antimicrobial coatings adds downstream compliance costs. Stakeholders must monitor reimbursement harmonization progress under cross-border healthcare directives to anticipate pricing and access divergence between northern and southern European markets.
Market Dynamics
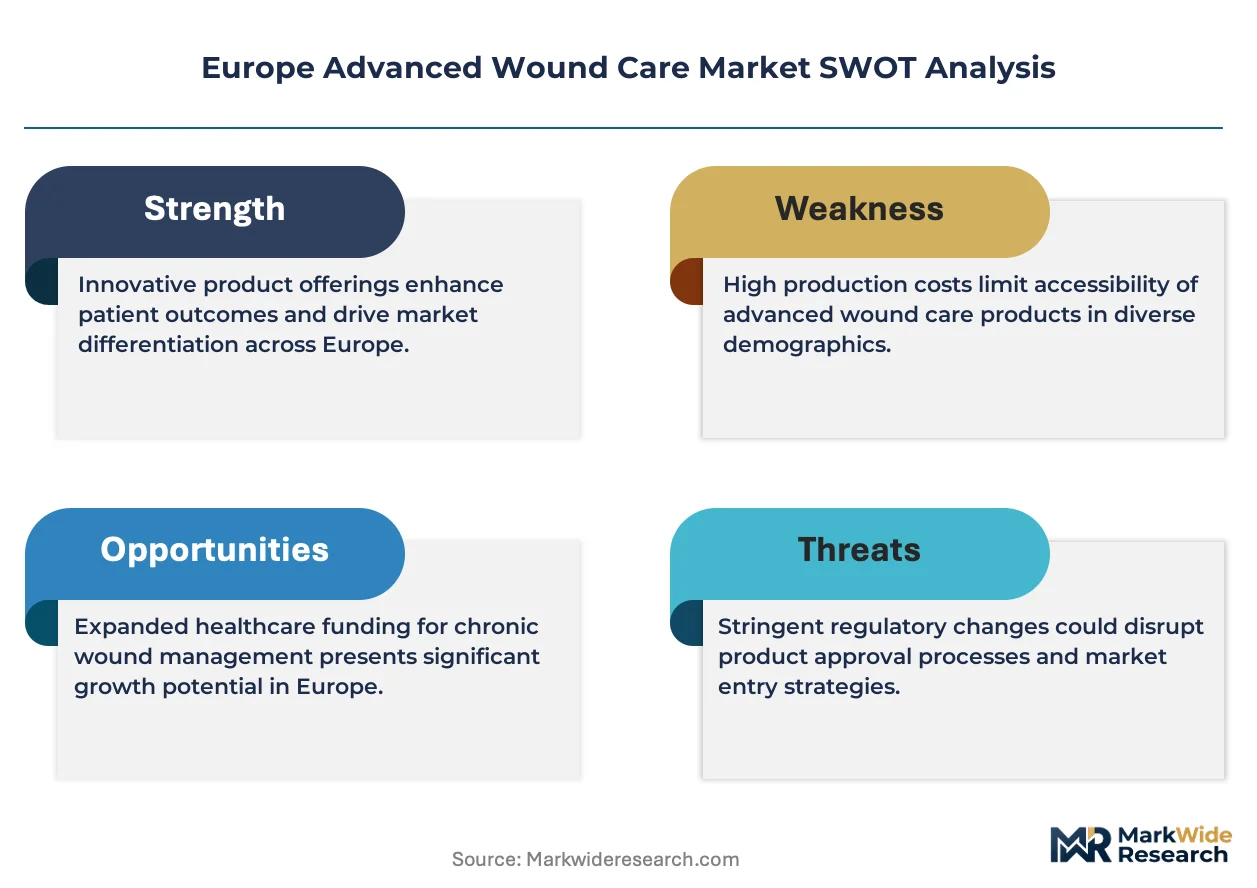
The EU Medical Device Regulation (MDR) is compressing market access timelines for alginate and biosynthetic dressings, forcing manufacturers to rebuild clinical evidence portfolios while hospital procurement centralization redistributes volume toward tender-winning portfolios.
Growth Catalysts
- Silver ion matrices:Surgical site infection protocols in German and French hospitals mandate antimicrobial prophylaxis, aligning reimbursement with advanced dressing uptake.
- REACH compliance:Chemical safety frameworks for coating additives are standardizing manufacturing quality, filtering out subscale suppliers and concentrating procurement on certified producers.
- Diabetic ulcer prevalence:Germany's aging demographics are expanding specialized wound center networks, creating dedicated demand channels for bioactive products.
Market Restraints
- Biocompatibility testing costs:CE marking under MDR demands expanded toxicological studies for alginate dressings, elevating fixed costs for product line maintenance.
- Superabsorbent polymer supply:Petrochemical feedstock volatility affects polyurethane foam input pricing, compressing margin predictability for dressing manufacturers.
- Electrical stimulation device substitution:Negative pressure wound therapy systems capture complex case volume, limiting addressable market expansion for passive dressing categories.
Strategic Opportunities
- Home care transitions:Post-acute discharge protocols in the United Kingdom are shortening hospital stays, expanding outpatient dressing consumption channels.
- Sensor-enabled monitoring:pH and moisture detection technologies are converging with wireless telemetry, enabling remote wound assessment platforms for rural patient populations.
- EMA bioactive guidance:Streamlined pathways for regenerative dressings accelerate market access for collagen and growth factor products in chronic wound applications.
Industry Challenges
- Regulatory affairs talent scarcity:MDR technical documentation requirements exceed legacy notified body capacity, creating bottlenecks in quality management system staffing.
- Clinical trial infrastructure:Biosynthetic dressing validation demands prospective wound healing studies, requiring multi-site investigator networks that strain sponsor budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Advanced Wound Care Market |
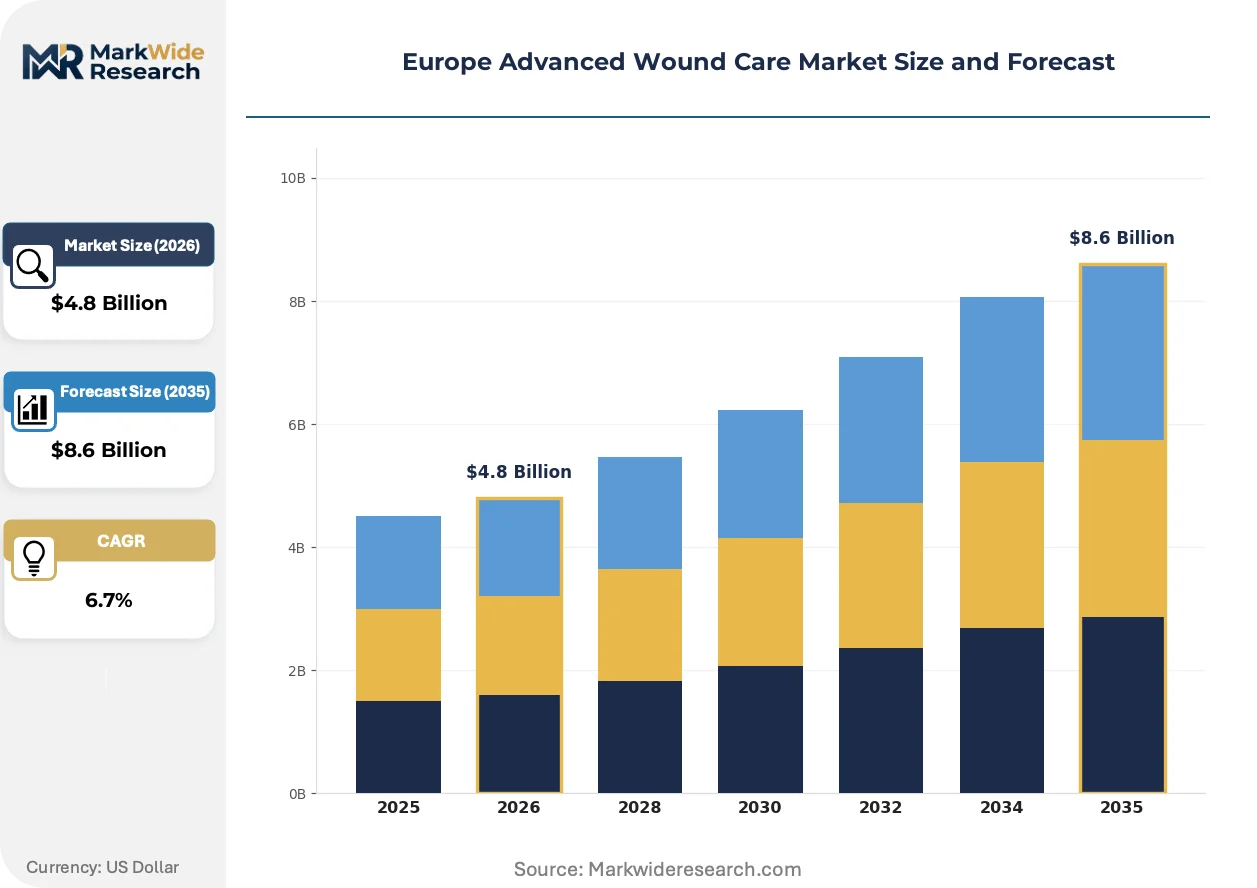
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrocolloids, Foams, Alginates, Antimicrobial Dressings End User: Hospitals, Home Care, Long-term Care Facilities, Outpatient Clinics Technology: Negative Pressure Wound Therapy, Electrical Stimulation Therapy, Biosynthetic Dressings, Smart Dressings Application: Diabetic Ulcers, Pressure Sores, Surgical Wounds, Traumatic Wounds |
| Companies Covered | Coloplast AS, Paul Hartmann AG, ConvaTec Group PLC, 3M, Integra LifeSciences, Smith & Nephew PLC, B. Braun Melsungen AG, Medtronic PLC, Mölnlycke Health Care AB, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Advanced Wound Care Market Trends and Innovations
Moisture-responsive materials and connected diagnostics are restructuring how wound bed conditions are monitored and managed, shifting clinical decision-making from scheduled assessment to real-time intervention.
Smart dressings incorporating printed electrochemical sensors are absorbing continuous pH and temperature data from exudate, transmitting alerts to clinical dashboards when healing trajectories deviate. Acute care wards in Dutch university hospitals are piloting these systems for post-surgical monitoring, reducing unplanned dressing changes by enabling targeted intervention. The technology is absorbing nursing labor previously allocated to visual inspection rounds, compressing staffing intensity per occupied bed.
The EU MDR's expanded clinical evidence requirements for bioactive wound products are extending CE marking timelines by demanding prospective safety and performance data. Manufacturers must now conduct biocompatibility studies beyond cytotoxicity to include sensitization and irritation endpoints for alginate and collagen dressings. German wound care specialists report delayed product launches as firms rebuild technical documentation portfolios to satisfy notified body scrutiny.
Centralized hospital procurement frameworks are consolidating antimicrobial dressing volume under multi-year tender contracts, displacing fragmented purchasing across individual wards. National health service buyers in Spain and Italy are adopting framework agreements that bundle negative pressure systems with advanced dressings, locking in supplier relationships for three-to-five-year terms. This concentration is most visible in the United Kingdom, where NHS Supply Chain standardization has reduced active dressing suppliers by half across acute trusts.
Europe Advanced Wound Care Market Segmentation
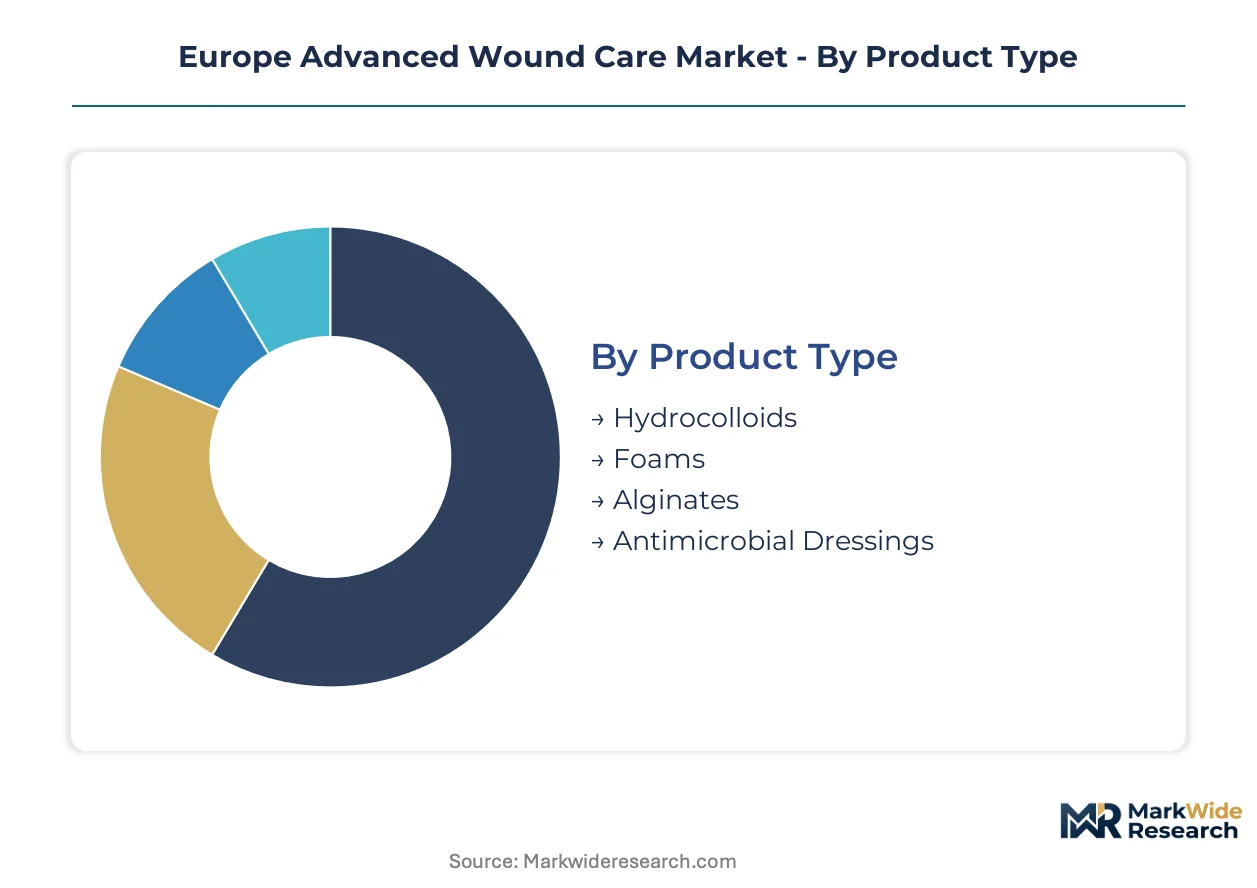
Segmentation in advanced wound care reveals how capital intensity, regulatory burden, and reimbursement pathways concentrate margin across distinct product and channel configurations. Manufacturers must align R&D allocation with the segments where clinical evidence requirements and procurement centralization create sustainable competitive moats.
Product Type:
Capital requirements vary sharply across dressing categories, with antimicrobial and alginate platforms demanding the heaviest biocompatibility testing infrastructure under EU MDR.
- Antimicrobial Dressings:Silver ion matrices and polyhexamethylene biguanide coatings deliver sustained bacterial load reduction for infected or high-risk wounds. German and French hospital procurement frameworks now mandate these products for surgical site infection prophylaxis, aligning tender specifications with reimbursement codes.
- Alginates:Calcium-sodium alginate fibers derived from brown seaweed form gel matrices upon contact with exudate, maintaining moist wound beds for moderate-to-heavy drainage cases. CE marking timelines have extended substantially as notified bodies demand expanded sensitization and irritation endpoint data beyond legacy cytotoxicity screens.
- Hydrocolloids:Carboxymethylcellulose and gelatin-based adhesive layers manage light exudate in partial-thickness wounds; outpatient transition protocols in the United Kingdom are expanding home care consumption.
- Foams:Polyurethane superabsorbent structures wick moisture vertically while preventing maceration; petrochemical feedstock volatility compresses margin predictability for manufacturers without backward integration into polymer supply.
Antimicrobial dressings absorb the bulk of installed capacity; smart dressings embedded with sensor technology are expanding most quickly.
End User:
Channel economics diverge sharply between acute care tender frameworks and the fragmented purchasing patterns of home and long-term care settings.
- Hospitals:Centralized procurement across NHS Supply Chain and comparable national frameworks concentrates volume under multi-year contracts, favoring suppliers with dedicated regulatory affairs infrastructure and pan-European logistics networks.
- Home Care:Post-acute discharge protocols in the United Kingdom and Netherlands are shortening hospital stays, expanding consumption of simplified dressing formats that patients or informal caregivers can apply without clinical supervision.
- Long-term Care Facilities:Pressure sore prevention programs in German and Belgian nursing homes drive recurring demand for repositioning protocols combined with protective dressing layers.
- Outpatient Clinics:Specialized wound centers in urban German clusters handle complex diabetic ulcer cases requiring bioactive products beyond standard formulary coverage.
Hospitals dominate absolute volume; home care channels are gaining share fastest as reimbursement shifts toward outpatient management.
Technology:
Technology segmentation maps directly onto evidence generation burden, with electrical stimulation and negative pressure systems requiring prospective clinical trials that passive dressings escape.
- Negative Pressure Wound Therapy:Vacuum-assisted closure systems apply sub-atmospheric pressure to accelerate granulation tissue formation in complex or dehisced surgical wounds. Smith & Nephew PLC dominates United Kingdom acute care contracts through bundled device-consumable offerings.
- Smart Dressings:Printed electrochemical sensors integrated into dressing substrates transmit continuous pH, temperature, and moisture data to clinical dashboards. Dutch university hospitals are piloting these systems for post-surgical monitoring, reducing unplanned dressing changes through targeted intervention.
- Biosynthetic Dressings:Collagen and growth factor matrices require EMA-aligned clinical evidence portfolios for regenerative claims, extending development timelines for mid-tier manufacturers.
- Electrical Stimulation Therapy:Bioelectric devices deliver microcurrent to chronic wounds with compromised vascularization; reimbursement fragmentation across member states limits addressable market expansion.
Negative pressure wound therapy commands the largest installed base; smart dressings are climbing the fastest as wireless telemetry gains clinical validation.
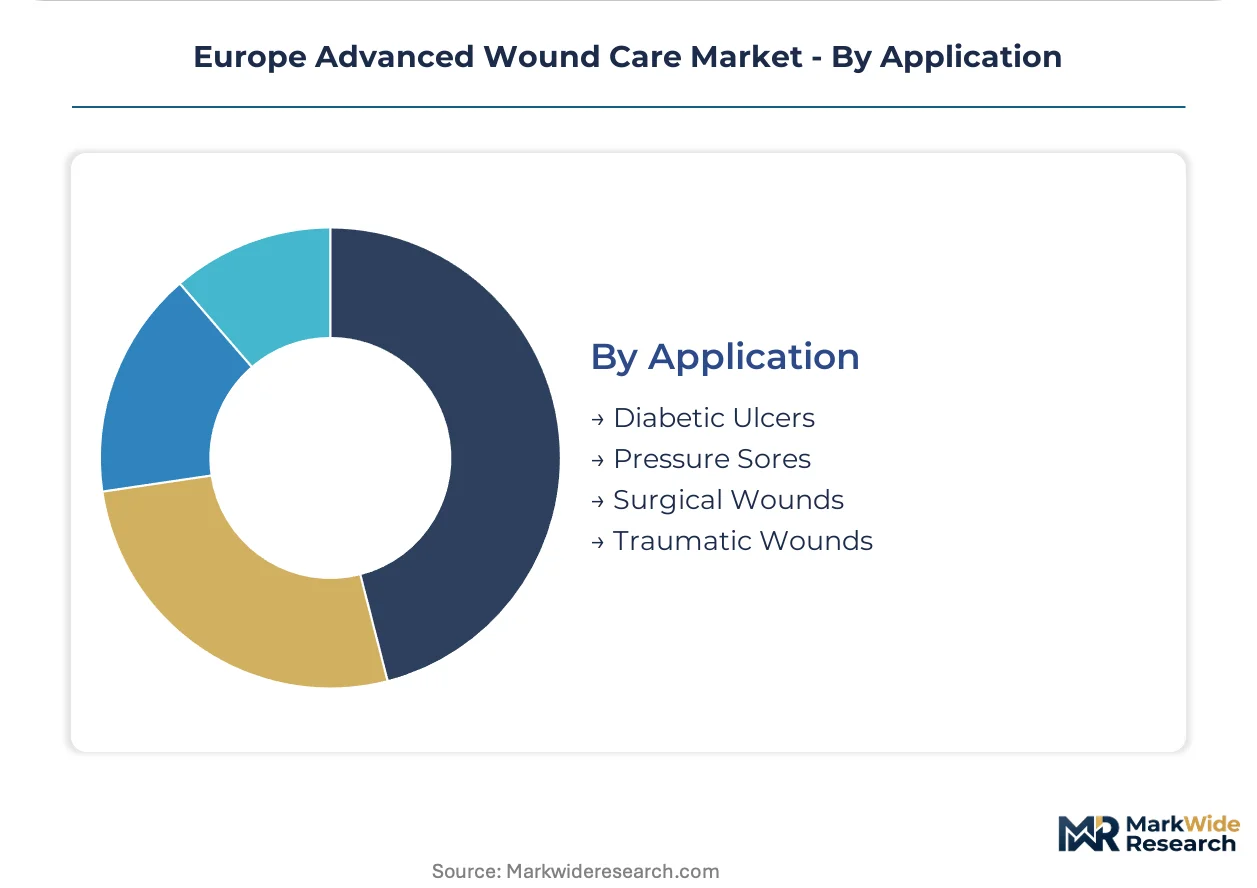
Application:
Wound etiology determines both product selection and reimbursement pathway, with diabetic ulcers and surgical wounds presenting the most structured payment environments.
- Diabetic Ulcers:Neuropathic foot lesions in aging German populations drive specialized wound center expansion and dedicated demand channels for bioactive collagen and antimicrobial alginate combinations.
- Surgical Wounds:Post-operative incision management aligns with standardized infection prevention protocols, concentrating procurement of antimicrobial dressings under procedure-linked reimbursement codes.
- Pressure Sores:Facility-acquired decubitus ulcers trigger penalty frameworks in some member states, shifting prevention investment toward protective foam and hydrocolloid layering systems.
- Traumatic Wounds:Acute injury cases in emergency settings favor rapid-application foam and alginate formats with minimal training requirements for frontline clinical staff.
Surgical wounds capture the greatest procurement volume; diabetic ulcer applications are expanding most quickly as specialized care networks mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity for advanced wound dressings clusters in northern Europe while consumption tilts toward aging populations in Germany and the United Kingdom. Regulatory divergence between EU member states fragments market access timelines despite harmonized CE marking frameworks.
Germany
Specialized wound center networks in Bavaria and North Rhine-Westphalia absorb bioactive collagen and antimicrobial alginate combinations for diabetic foot lesions. BfArM reimbursement codes align procurement with infection prevention protocols, compressing tender cycles for hospital buyers. The Ruhr industrial corridor hosts polymer processing facilities supplying superabsorbent foam substrates to dressing manufacturers.
United Kingdom
NHS Supply Chain centralization has halved active dressing suppliers across acute trusts since 2022, concentrating volume under multi-year framework agreements. NICE technology appraisals for negative pressure wound therapy systems determine hospital capital allocation priorities. London and Manchester university hospitals pilot sensor-enabled smart dressings for post-surgical remote monitoring.
France
ANSM clinical evidence requirements for biosynthetic dressings extend CE marking timelines, favoring established players with dedicated regulatory affairs infrastructure. Surgical site infection protocols in Paris and Lyon hospital clusters mandate silver ion matrix prophylaxis for high-risk procedures. The Île-de-France region anchors medical device distribution networks serving francophone African markets.
Netherlands
Dutch university hospitals in Amsterdam and Rotterdam lead clinical validation trials for printed electrochemical sensor dressings, transmitting pH and temperature data to centralized nursing dashboards. Zorginstituut Nederland reimbursement guidance favors outpatient wound management, expanding home care channel consumption. Eindhoven's microelectronics cluster supplies sensor components to dressing integrators.
Italy
Regional health system fragmentation across Lombardy, Veneto, and Campania produces divergent tender specifications for antimicrobial coatings. AIFA pricing negotiations for advanced dressings lag northern European benchmarks, compressing margin realization for imported products. Milan's pharmaceutical packaging sector adapts sterile barrier systems for bioactive wound product formats.
Europe Advanced Wound Care Market Competitive Landscape
Top-tier vendors anchor hospital procurement frameworks, while mid-scale specialists concentrate on regulatory differentiation for alginate and biosynthetic segments. The vendor base stratifies across three tiers: multinational device-dressing bundlers, regional foam and hydrocolloid fabricators, and niche collagen matrix developers. Dominant competitive moves include M&A to capture negative pressure system-consumable integration and capacity expansion in polymer substrate manufacturing.
Among Nordic-based wound care specialists, Mölnlycke Health Care AB and Coloplast AS exemplify contrasting scale strategies within the European market. Smith & Nephew PLC anchors the United Kingdom acute care channel through bundled device offerings. Paul Hartmann AG represents the German Mittelstand fabrication model, occupying a position between multinational scale and specialized regional supply.
| Leading Market Players |
|---|
| Coloplast AS |
| Paul Hartmann AG |
| ConvaTec Group PLC |
| 3M |
| Integra LifeSciences |
| Smith & Nephew PLC |
| B. Braun Melsungen AG |
| Medtronic PLC |
| Mölnlycke Health Care AB |
| Others |
Pricing and Supply Chain Analysis
Centralized NHS Supply Chain tender frameworks in the United Kingdom and comparable national procurement bodies across Germany and France are compressing supplier margins and forcing manufacturers to absorb biocompatibility testing costs under EU MDR while competing on multi-year contract terms.
Pricing Analysis
Short lead-time premiums for antimicrobial alginate dressings command pricing separation from standard hydrocolloid formats, with German hospital procurement officers paying elevated rates for validated silver ion matrices that satisfy surgical site infection protocols. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with CE-marked MDR-compliant products capturing margin above legacy-cytotoxicity-screen alternatives. Pricing pressure stems from petrochemical feedstock volatility affecting polyurethane foam substrates, squeezing manufacturers lacking captive polymer supply. Home care channels exhibit highest price sensitivity due to out-of-pocket patient contributions, while acute care tenders prioritize clinical performance over unit cost.
Supply Chain Analysis
Domestic-content preferences under EU public procurement directives are redirecting sourcing toward polymer processing facilities in the Ruhr corridor and sterile barrier fabricators in northern Italy. Manufacturing concentration clusters in Germany, Sweden, and Denmark for advanced foam substrates and hydrocolloid adhesives, with calcium-sodium alginate fibers drawing from brown seaweed harvesters in Norway and Scotland. Raw material dependencies rest on petrochemical derivatives for superabsorbent polymers, silver nitrate for antimicrobial coatings, and collagen isolates for biosynthetic matrices. Single-source vulnerability concentrates in notified body capacity for MDR technical documentation review. Distribution runs through national health service logistics networks and specialized medical device wholesalers serving hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where control over polymer substrate manufacturing and regulatory affairs infrastructure determines tender-winning capacity. Players are pursuing backward integration into superabsorbent foam production to escape petrochemical margin volatility.
For Market Incumbents: To counter mid-tier alginate specialists gaining share through MDR compliance agility, Smith & Nephew PLC and Mölnlycke Health Care AB should lock in multi-year raw material offtake agreements with Ruhr corridor polymer processors and expand dedicated regulatory affairs staffing in Germany. Channel control through direct hospital system partnerships remains essential for defending framework contract positions against emerging bundlers. For New Entrants and Emerging Players: EU MDR streamlined pathways for regenerative dressings in Germany and the Netherlands open a window for collagen matrix developers to penetrate diabetic ulcer wound centers underserved by multinational formulary limitations. Target home care transitions in the United Kingdom where simplified dressing formats face less incumbent concentration. A go-to-market angle emphasizing remote monitoring integration with Dutch university hospital pilot programs accelerates clinical validation. For Investors and Strategic Acquirers: The window for entry favors mid-scale alginate and biosynthetic specialists with completed MDR technical documentation portfolios and established notified body relationships. Acquisition targets should demonstrate regulatory affairs infrastructure depth and polymer substrate sourcing security. Watch EMA guidance finalization on growth factor claims as the inflection signal for regenerative dressing valuation resets. Within a five-to-ten year horizon, vertically integrated players with captive manufacturing and pan-European logistics networks hold structural advantage.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Completion | MDR technical documentation accelerates market access for alginate and collagen portfolios in German tenders. |
| Hospital System Partnership | NHS Supply Chain framework agreements lock in three-to-five year volume commitments for bundled device-dressing offerings. |
| Backward Integration into Polymer Supply | Ruhr corridor superabsorbent foam facilities reduce petrochemical feedstock exposure for margin stability. |
| Software Companion Development | |
| Reimbursement Strategy | BfArM code alignment with infection prevention protocols secures antimicrobial dressing procurement mandates. |
Research Methodology
Hospital procurement databases, GPO contracts, and EMA regulatory filing records formed the secondary backbone, cross-referenced with primary interviews involving hospital purchasing committee members, biomedical engineers, wound care clinicians, and regulatory affairs directors at notified bodies. Bottom-up triangulation validated manufacturer shipment data against national health service consumption records, while top-down approaches cross-checked aggregate market sizing against polymer substrate production volumes from northern European chemical clusters.
Historical trendline analysis across installed base expansion and tender award patterns informed projection modeling over the analysis window, with segmentation dimensions spanning product type, end user channel, wound etiology application, and technology platform. CAGRs were derived from weighted average growth assumptions across antimicrobial dressing volume, smart dressing adoption curves, and negative pressure system replacement cycles, incorporating diabetic ulcer prevalence trajectories and surgical procedure recovery rates as demand-side inputs.
Caveats apply where EU MDR implementation delays, notified body capacity constraints, or REACH chemical restriction expansions could materially shift the outlook for biosynthetic dressing launches and antimicrobial coating formulations. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
North America Negative Pressure Wound Therapy Market
Wound Care
South Korea Wound Care Management Market
Wound Care
Advanced Wound Dressings Market
Wound Care
Wound Biologics Market
Wound Care
Wound Irrigation Devices Market
Wound Care
US Wound Irrigation System Market
Wound Care
Collagen Dressings Market
Wound Care
Antimicrobial Regenerative Wound Matrix Market
Wound Care
US Burn Care Centers Market
Wound Care
Autologous Wound Patches Market
Wound Care
Acute Wound Care Market
Wound Care
Wound Healing Market
Wound Care
Asia Pacific Negative Pressure Wound Therapy Market
Wound Care
Smart Bandages and Smart Wound Dressings Market
Wound Care
Vascular Dressings Market
Wound Care
Patch Based Wound Healing Products Market