
 Bioactive Wound Dressing Market | 2026-2036
Bioactive Wound Dressing Market Size, Share, and Industry Trends Forecast 2026-2036
Bioactive Wound Dressing Market Outlook
Multi-source procurement for collagen matrices and antimicrobial substrates is rebalancing toward vertically integrated suppliers with captive biopolymer production. Smith+Nephew leverages its Sheffield manufacturing base to sustain European hospital contracts. Convatec Group PLC anchors its position through specialized ostomy and advanced wound care channels. Mölnlycke Health Care competes via controlled distribution into surgical suites across Nordic health systems.
Bioactive wound dressings comprise engineered materials impregnated with biologically active agents such as silver ions, honey derivatives, or growth factors that modulate the wound microenvironment and accelerate re-epithelialization. These products typically achieve moisture vapor transmission rates between 2,000 and 8,000 g/m²/24h while maintaining tensile strength sufficient for application on exuding wound beds. Alginate segments draw margin from chronic wound protocols where gelling fiber action manages moderate-to-heavy exudate. Antimicrobial variants lead surgical wound applications due to sustained silver ion release profiles that align with infection prevention bundles. Nanofiber technology segments show fastest trajectory as electrospun scaffolds enable precise loading of bioactive molecules with controlled release kinetics.
FDA 510(k) clearance pathways shape product development timelines for US market entry, while EMA Medical Device Regulation class IIa/IIb designations govern conformity assessment across European Economic Area states. Health Canada and TGA recognition of FDA or CE certifications creates streamlined parallel approval corridors for manufacturers with established regulatory dossiers. Stakeholders must monitor evolving biocompatibility testing standards under ISO 10993 revisions and assess how state-level Medicaid reimbursement adjustments for home-based wound care redirect demand between hospital and long-term care channels.
Market Dynamics
Electrospun nanofiber manufacturing is fragmenting production economics by enabling small-batch precision loading of bioactive molecules, compressing minimum viable scale for specialty dressing entrants and eroding incumbent volume advantages in antimicrobial segments.
Growth Catalysts
- EU Medical Device Regulation (MDR) class IIb pathways:Streamlined conformity assessment for antimicrobial dressings accelerates hospital procurement cycles across German chronic wound clinics and Nordic surgical networks.
- Silver ion release kinetics:Advanced sustained-release profiles align with infection prevention bundles in US hospital systems managing diabetic foot ulcer protocols.
- Alginate gelling fiber action:Superior exudate management in moderate-to-heavy wound beds drives protocol adoption in long-term care channels.
Market Restraints
- Collagen raw material concentration:Bovine and porcine sourcing dependencies create supply vulnerability linked to agricultural commodity cycles and zoonotic disease screening protocols.
- FDA 510(k) timeline compression:Substantial equivalence determinations for novel bioactive substrates extend development-to-revenue cycles beyond typical medtech horizons.
- Antiseptic substitute pressure:Topical antimicrobial sprays and negative pressure wound therapy systems capture margin in surgical prophylaxis applications.
Strategic Opportunities
- Home-based wound care Medicaid channels:Reimbursement adjustments in US state programs redirect volume from acute settings toward long-term care and patient self-management.
- Honey derivative formulations:Medical-grade Manuka and Leptospermum scoparium extracts address antibiotic-resistant biofilm indications with distinct regulatory positioning.
- ISO 10993 biocompatibility convergence:Harmonized cytotoxicity and sensitization testing standards reduce redundant certification costs for multi-territory launches.
Industry Challenges
- Electrospinning scale-up engineering:Translating laboratory-grade nanofiber uniformity to continuous production lines requires specialized polymer processing expertise scarce outside academic-industrial partnerships.
- Legacy hospital formulary integration:Advanced dressings must demonstrate cost-effectiveness against established protocols within rigid procurement committee timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bioactive Wound Dressing Market |
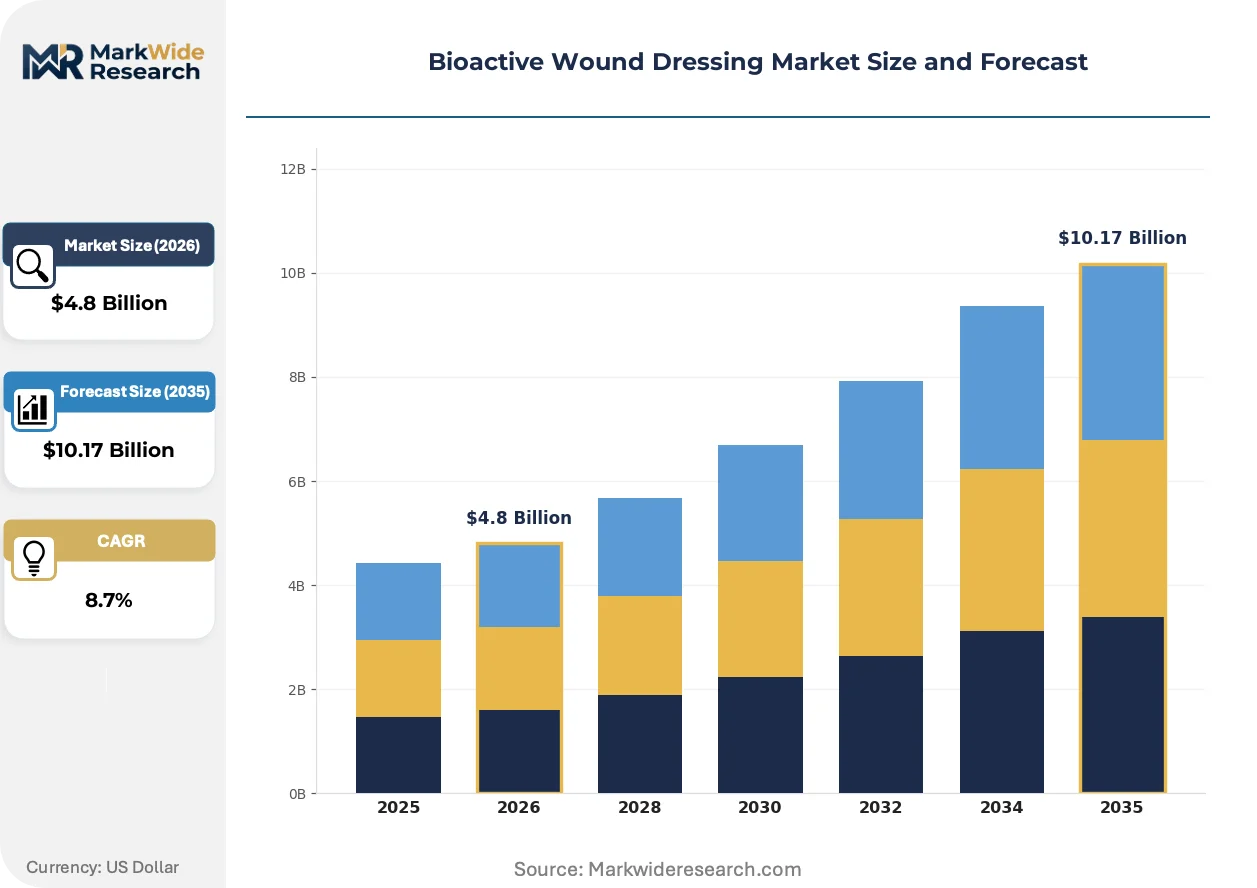
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrogel, Foam, Alginate, Antimicrobial End User: Hospitals, Home Care, Long-term Care Facilities, Clinics Application: Surgical Wounds, Chronic Wounds, Burns, Traumatic Injuries Technology: Nanofiber, Biopolymer, 3D Bioprinting, Hydrocolloid |
| Companies Covered | 3M, Smith+Nephew, Convatec Group PLC, B. Braun SE, Integra LifeSciences, Organogenesis Inc., Covalon Technologies Ltd, Hollister Incorporated, Mölnlycke Health Care, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bioactive Wound Dressing Market Strategic Shifts
Manufacturing flexibility and regulatory harmonization are converging to reshape competitive entry points, with precision fabrication technologies and reimbursement realignment creating openings for specialized players outside traditional wound care conglomerates.
Electrospun scaffold technology is modularizing the architecture of bioactive delivery systems. Chronic wound clinics in the United States are adopting these platforms at accelerating pace for growth factor incorporation. The technology is modularizing supplier tiers by decoupling fiber production from downstream bioactive impregnation, enabling contract manufacturers to capture value previously held by integrated dressing producers.
EMA Medical Device Regulation class IIa/IIb designation refinements are compressing conformity assessment variability across European Economic Area states. Manufacturers with established quality management system certifications face reduced notified body audit burden for antimicrobial dressing line extensions. German hospital procurement coalitions are leveraging these efficiencies to consolidate supplier panels around vertically integrated European producers.
Hospital-at-home reimbursement expansion is fragmenting traditional channel concentration in the United States. Medicare Advantage plans and state Medicaid programs are unbundling wound care services from facility fees, redirecting advanced dressing volume toward durable medical equipment distributors and specialty pharmacy networks. Diabetic foot ulcer management protocols in Texas and Florida health systems show earliest behavioral shift toward remote monitoring-integrated dressing replenishment.
Bioactive Wound Dressing Market Segmentation
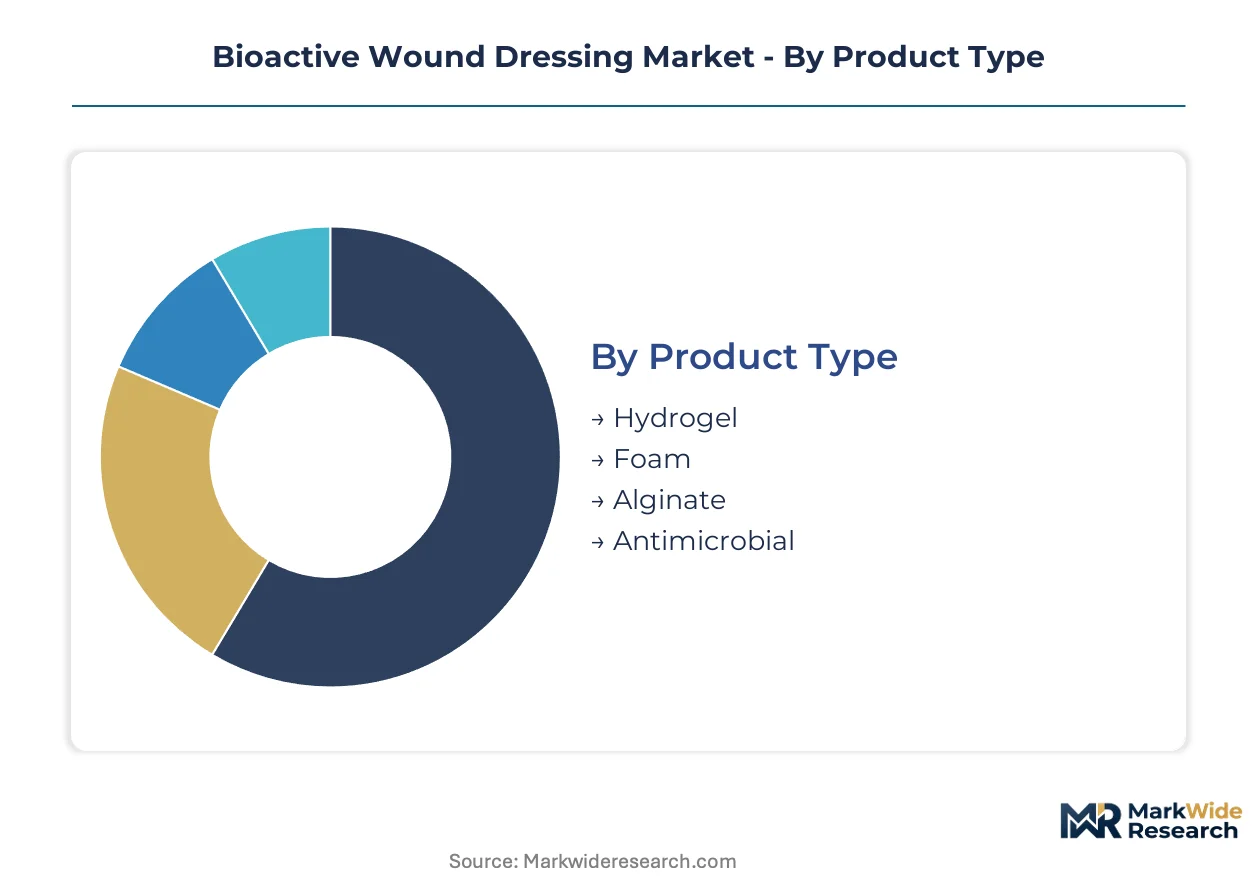
Bioactive wound dressing segmentation reflects divergent clinical requirements across acute intervention versus chronic management protocols. Material selection, delivery technology, and care setting economics create distinct competitive arenas with specialized margin structures.
Product Type:
Customization intensity spans from commodity substrates to engineered bioactive matrices with precise release kinetics.
- Antimicrobial:Silver ion-impregnated dressings achieve sustained release profiles between 48 and 96 hours, aligning with infection prevention bundles in US hospital surgical departments. Demand concentrates in diabetic foot ulcer protocols where biofilm suppression drives formulary inclusion.
- Alginate:Gelling fiber matrices derived from brown seaweed extract manage moderate-to-heavy exudate through ion exchange with wound fluid. German chronic wound clinics prioritize these substrates for venous leg ulcer protocols under EU MDR class IIb procurement frameworks.
- Hydrogel:Cross-linked polymer networks maintain moist wound environments for autolytic debridement.
- Foam:Hydrophilic polyurethane structures absorb exudate while protecting periwound tissue.
Leading the category by volume: Antimicrobial. Growing fastest: Alginate.
End User:
Channel economics shift dramatically between reimbursed facility fees and patient self-pay or durable medical equipment billing.
- Hospitals:Operating room and wound care center procurement dominates antimicrobial and advanced matrix adoption, with formulary committees evaluating cost-per-healed-wound metrics against negative pressure alternatives.
- Home Care:Medicaid reimbursement unbundling in Texas and Florida health systems redirects alginate and hydrogel volume toward specialty pharmacy networks with remote monitoring integration.
- Long-term Care Facilities:Pressure injury protocols drive recurring substrate consumption.
- Clinics:Outpatient wound centers manage debridement and dressing change cadence.
Channel concentration: Hospitals capture the majority of advanced dressing value. Expanding most quickly: Home Care.
Application:
Wound etiology determines bioactive agent selection, dressing change frequency, and total episode cost accountability.
- Chronic Wounds:Diabetic foot ulcers and venous leg ulcers require sustained moisture balance and bioactive modulation over extended healing timelines, driving subscription-style replenishment models in US Medicare Advantage networks.
- Surgical Wounds:Prophylactic antimicrobial dressing application in orthopedic and cardiovascular procedures aligns with CDC surgical site infection reduction targets.
- Burns:Partial-thickness thermal injuries demand conformable substrates with cooling properties.
- Traumatic Injuries:Emergency department application prioritizes rapid hemostasis and contamination control.
Volume leader: Chronic Wounds. Steepest expansion trajectory: Surgical Wounds.
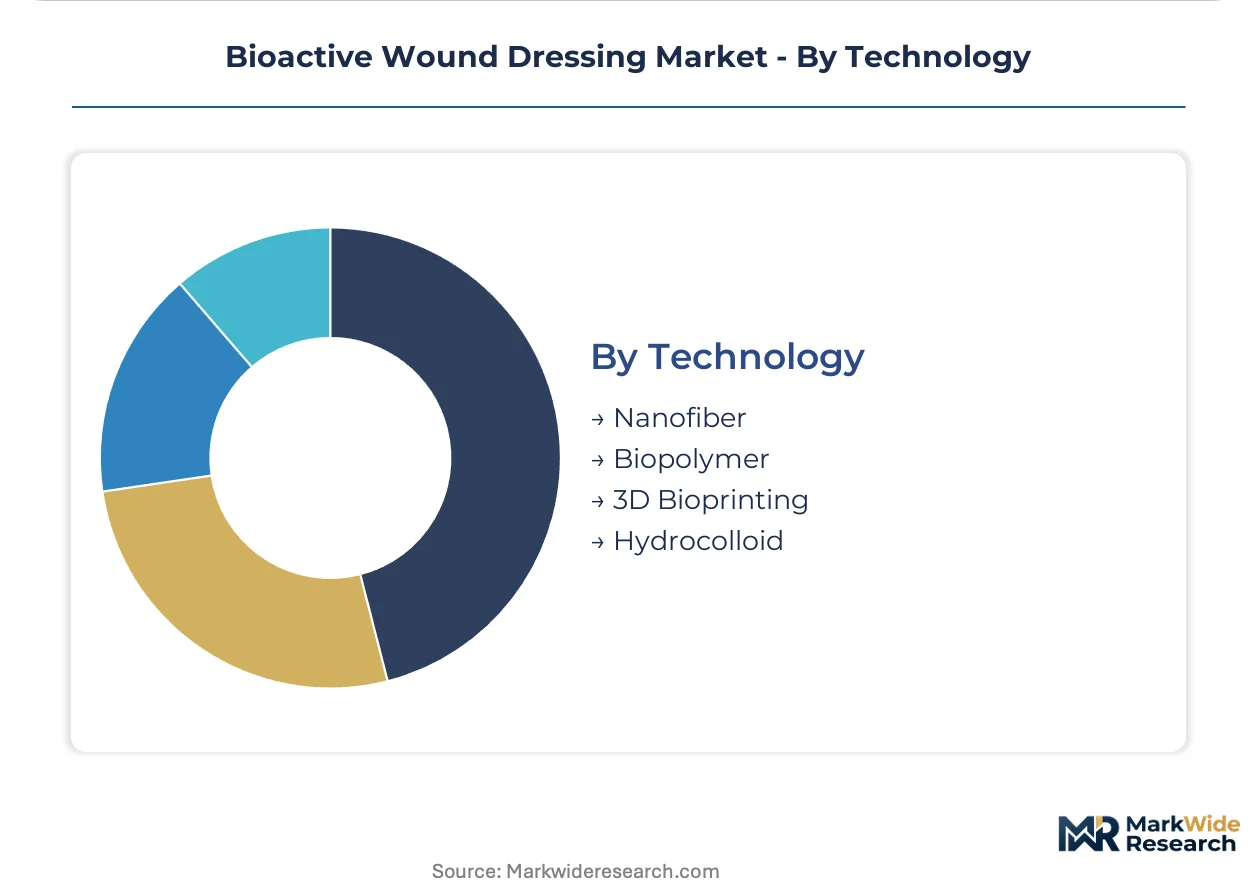
Technology:
Manufacturing sophistication separates laboratory-scale precision from continuous production economics.
- Nanofiber:Electrospun scaffolds enable precise loading of growth factors and antimicrobial peptides with tunable release kinetics, attracting venture investment for chronic wound regeneration platforms.
- Biopolymer:Collagen, chitosan, and hyaluronic acid matrices leverage established extraction and purification supply chains with ISO 10993 biocompatibility certification pathways.
- 3D Bioprinting:Patient-specific scaffold geometry with living cell incorporation remains preclinical for most indications.
- Hydrocolloid:Carboxymethyl cellulose and gelatin matrices provide self-adherent moisture management.
Production scale leader: Biopolymer. Gaining share fastest: Nanofiber.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bovine collagen sourcing from Midwestern US processing facilities and brown seaweed harvesting along Norwegian coastlines anchor raw material flows into dressing manufacturing networks.
United States
Hospital systems in Texas and Florida prioritize diabetic foot ulcer protocols with antimicrobial dressing formulary inclusion. FDA 510(k) clearance pathways compress development timelines for electrospun nanofiber entrants targeting Medicare Advantage networks. The Greater Boston cluster hosts contract research organizations specializing in ISO 10993 biocompatibility testing for multi-territory regulatory dossiers.
Germany
Chronic wound clinics in North Rhine-Westphalia expand alginate procurement under EU MDR class IIb streamlined conformity assessments. The country's national medical device regulator enforces post-market surveillance requirements for silver ion release profile documentation. The Sheffield-Ruhr industrial corridor sustains vertically integrated collagen matrix production serving hospital procurement coalitions.
Japan
Aging demographics accelerate demand for home-based wound care with hydrogel dressing reimbursement under universal health coverage. The national pharmaceutical and medical device agency maintains stringent biocompatibility testing standards aligned with ISO 10993 revisions. The Kansai region concentrates specialty polymer processing expertise for electrospinning scale-up engineering partnerships.
United Kingdom
NHS integrated care boards consolidate advanced wound care purchasing around antimicrobial dressing cost-per-healed-wound metrics. The Medicines and Healthcare products Regulatory Agency recognizes FDA and CE certifications for parallel approval pathways. The Sheffield manufacturing base anchors European hospital contracts for collagen substrate supply.
India
Domestic hospital chains adopt medical-grade honey derivative formulations for antibiotic-resistant biofilm indications. The Central Drugs Standard Control Organization streamlines import licensing for established regulatory dossiers from FDA-cleared manufacturers. The Maharashtra-Gujarat pharmaceutical corridor develops contract manufacturing capacity for biopolymer extraction and purification.
Bioactive Wound Dressing Market Competitive Environment
Portfolio diversification dominates the current landscape as incumbents extend antimicrobial and alginate lines into nanofiber platforms. The vendor base organizes around three tiers: diversified medical technology conglomerates with captive biopolymer production, specialized wound care pure-plays with controlled distribution networks, and emerging contract manufacturers leveraging electrospinning modularity. Strategic archetypes include vertically integrated substrate producers, channel-integrated hospital suppliers, and technology-licensing specialists. M&A activity and capacity expansion in captive collagen sourcing represent the dominant competitive moves reshaping supply security.
Among diversified medical technology conglomerates, 3M and Smith+Nephew exemplify scale-driven positioning with established regulatory dossiers and manufacturing footprints. Convatec Group PLC occupies a specialist position within the ostomy and advanced wound care channel archetype. These three entities represent contrasting strategic postures: technology breadth, geographic manufacturing integration, and specialized clinical channel focus respectively.
| Leading Market Players |
|---|
| 3M |
| Smith+Nephew |
| Convatec Group PLC |
| B. Braun SE |
| Integra LifeSciences |
| Organogenesis Inc. |
| Covalon Technologies Ltd |
| Hollister Incorporated |
| Mölnlycke Health Care |
| Others |
Value Chain & Pricing Dynamics
German chronic wound clinic procurement coalitions concentrate purchasing power for antimicrobial dressings, driving contract-based pricing with performance guarantees tied to biofilm suppression outcomes. This buyer concentration rewards suppliers with EU MDR class IIb certification and captive collagen sourcing.
Pricing Analysis
Service bundling separates premium antimicrobial dressings with clinical training and remote monitoring integration from unbundled commodity substrates. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 10993 certification grade and silver ion release profile consistency. Cost compression in alginate segments intensifies as Indian contract manufacturers scale biopolymer extraction capacity. Home care channels exhibit highest price sensitivity due to Medicaid reimbursement caps, while US hospital systems prioritize cost-per-healed-wound metrics over unit price.
Supply Chain Analysis
Regional distribution centers in Sheffield, Ruhr, and Greater Boston coordinate hub-and-spoke patterns for collagen matrix and antimicrobial substrate flows. Manufacturing concentrates in the United States, Germany, and Japan for electrospun nanofiber platforms and biopolymer purification. Raw material dependencies draw from Midwestern US bovine processing, Norwegian brown seaweed harvesting, and Indian pharmaceutical-grade honey derivatives. Single-source vulnerability in porcine collagen sourcing during zoonotic disease screening protocols threatens continuity. Distribution runs through hospital procurement coalitions, GPO contracts, and durable medical equipment networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into biopolymer extraction and electrospinning capacity anchors competitive position as nanofiber technology fragments production economics.
For Market Incumbents: Deepen captive supply of collagen matrices through Sheffield-Ruhr corridor expansion to offset agricultural commodity cycle volatility. Secure EU MDR class IIb line extension pathways before notified body audit queues lengthen. Electrospinning contract manufacturers threaten margin capture in growth factor delivery segments. For New Entrants and Emerging Players: Specialty pharmacy networks with remote monitoring integration offer lowest barrier entry for alginate and hydrogel volume capture in Texas and Florida Medicaid unbundling channels. Target chronic wound clinic protocols in German North Rhine-Westphalia where streamlined conformity assessments accelerate procurement cycles. Pursue honey derivative formulations for antibiotic-resistant biofilm indications with distinct regulatory positioning. For Investors and Strategic Acquirers: The window for entry favors electrospinning technology specialists with ISO 10993 certification infrastructure and hospital system validation partnerships. Long-term viability hinges on manufacturing modularity enabling precision bioactive loading at small-batch scale. Monitor FDA 510(k) clearance velocity for novel nanofiber substrates as inflection indicator for platform consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Biopolymer Production | Captive collagen sourcing insulates margin from agricultural commodity cycles and zoonotic screening disruptions. |
| EU MDR Class IIb Certification Pathway | Streamlined conformity assessment accelerates hospital procurement cycles across German chronic wound networks. |
| Electrospinning Scale-Up Partnership | Academic-industrial collaboration transfers laboratory-grade nanofiber uniformity to continuous production lines. |
| Hospital System Partnership | Cost-per-healed-wound demonstration secures formulary inclusion against negative pressure wound therapy alternatives. |
| Reimbursement Strategy | Medicare Advantage and Medicaid unbundling alignment redirects volume toward home care and specialty pharmacy channels. |
Study Parameters
Multi-period observation of FDA 510(k) clearance timelines, EU MDR notified body audit queues, and hospital procurement contract awards anchored the trend analysis, supplemented by interviews with wound care clinicians, hospital purchasing committee directors, biomedical engineers, GPO contracts managers, and alginate extraction facility operators. Secondary validation drew from FDA 510(k) databases, EMA Medical Device Regulation submissions, hospital procurement databases, CMS Medicare reimbursement schedules, and ISO 10993 biocompatibility testing records. Bottom-up segment sizing and top-down market triangulation cross-verified volume and value estimates.
Input-output matrices mapped electrospinning capacity expansion, collagen raw material flows, and antimicrobial ion release profile adoption across product type, end user, application, and technology segmentation dimensions. CAGRs were derived from regression analysis of historical procurement volume against regulatory pathway efficiency and reimbursement policy shifts. Forecast inputs incorporated diabetic foot ulcer protocol adoption rates and nanofiber manufacturing yield improvements.
The model holds under stable EU MDR implementation timelines and continued Medicaid unbundling trajectory; deviation in FDA 510(k) backlog accumulation or zoonotic disease screening protocol intensification would shift manufacturer prioritization toward synthetic biopolymer alternatives. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Global Digital Wound Measurement Devices Market
Wound Care
Advanced Wound Care and Dressings Market
Wound Care
Wound Care Biologics Market
Wound Care
Wound Healing Supplement Market
Wound Care
France Wound Care Market
Wound Care
US Wound Care Management Devices Market
Wound Care
Dental Wound Dressings Market
Wound Care
Gauze Bandage Rolls Market
Wound Care
Infectious Wound Care Management Market
Wound Care
Philippines Wound Care Market
Wound Care
Brazil Wound Care Management Devices Market
Wound Care
Pressure Ulcer Treatment Market
Wound Care
Collagen Dressings Market
Wound Care
Surgical Dressing Market
Wound Care
Wound Care Sealants Market
Wound Care
Negative Pressure Wound Therapy Market