
 Wood Flooring Market | 2026-2036
Wood Flooring Market Size, Share, and Industry Trends Forecast 2026-2036
Wood Flooring Market Intelligence
Asset-light manufacturing, which relies on outsourced production, is reconfiguring the competitive landscape. This strategy allows Mohawk Industries, Inc. to focus on brand development and its vast distribution network. Tarkett S.A. leverages its broad product portfolio to secure large-scale commercial projects. In parallel, Shaw Industries Group, Inc. sustains its market presence through deep integration with major home improvement retailers.
Wood flooring comprises products manufactured from timber designed for use as a permanent covering for a floor. These products are often graded based on the Janka hardness test, which measures the resistance of a wood species to denting and wear. Engineered wood is a rapidly expanding product segment, valued for its stability in varied humidity conditions. Within end-user applications, the residential properties segment remains the largest volume consumer, driven by renovation and new construction activities.
The EU's Construction Products Regulation (CPR) and CE marking mandate specific performance and safety standards for flooring sold within Europe. In the United States, the EPA enforces formaldehyde emission standards for composite wood products, influencing material composition. Consequently, manufacturers' ability to document supply chain transparency and compliance with evolving chemical safety rules will determine future market access and brand trust.
Market Dynamics
The market's central dynamic is the conflict between rising demand for authentic wood aesthetics in residential construction and the increasing stringency of global regulations governing timber sourcing and chemical safety, such as the EU's REACH framework.
Growth Catalysts
- Renovation Policies:Government-backed initiatives, including the EU's Renovation Wave, incentivize retrofitting buildings with sustainable materials, directly benefiting wood flooring manufacturers who can provide certified products.
- Residential Remodeling:Demand in high-end residential renovation projects, particularly for custom and wide-plank formats, continues to drive volume in developed markets like the United States and Germany.
- Emerging Construction Markets:Rapid urbanization and new construction activity in Southeast Asian countries, including Vietnam and Indonesia, are creating significant new demand for both solid and engineered wood flooring.
Market Restraints
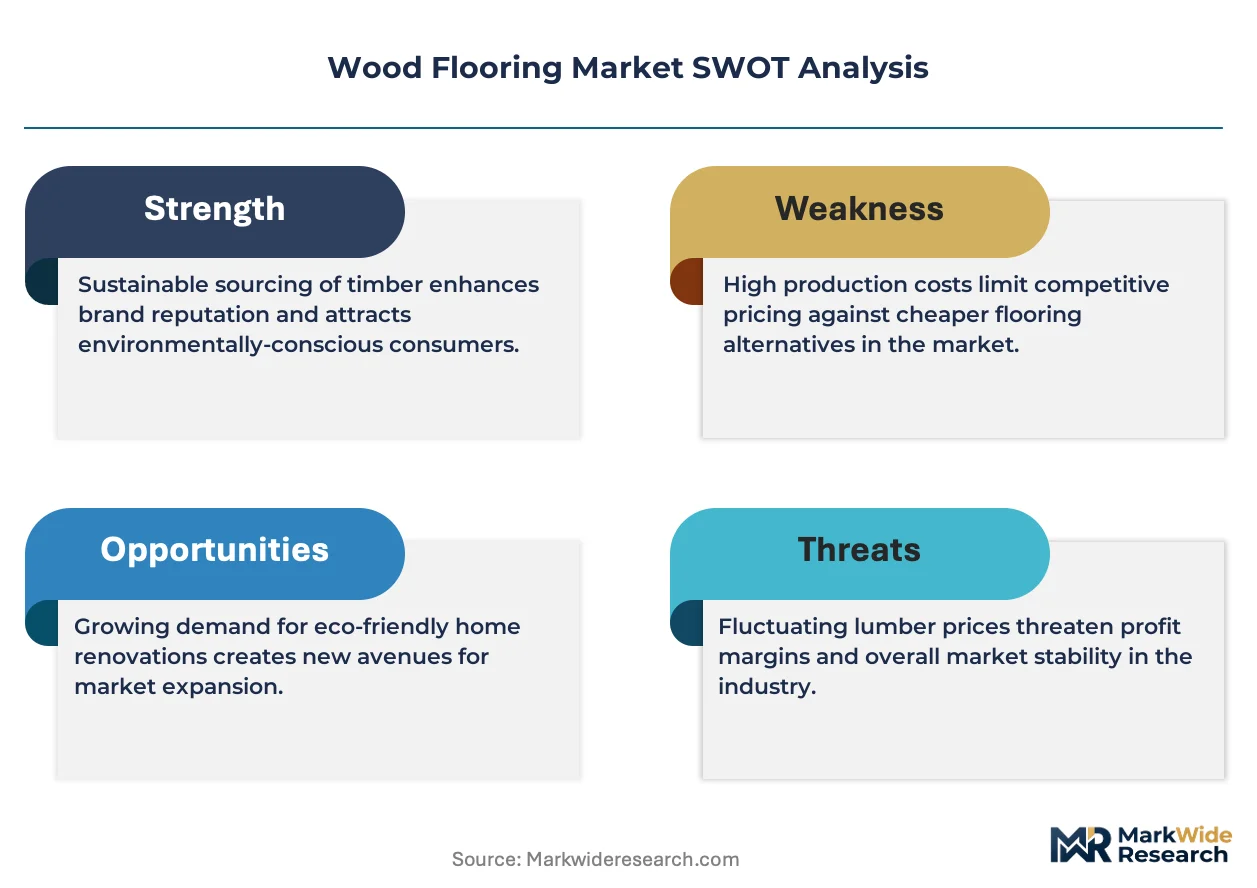
- Input Cost Volatility:Fluctuations in the price of raw timber, especially for sought-after species like European oak, create margin pressure and sourcing instability for manufacturers globally.
- Substitution from Synthetics:Advanced luxury vinyl tile (LVT) and laminate flooring products increasingly offer realistic wood aesthetics with superior scratch resistance and lower price points, posing a significant substitution threat.
- Sourcing Legislation:Compliance with anti-illegal logging laws, such as the US Lacey Act, adds complexity and cost to supply chain management, requiring rigorous documentation to prove timber legality.
Strategic Opportunities
- Advanced Finishes:Developing and marketing flooring with ultra-low or zero-VOC finishes and formaldehyde-free adhesives can command a premium in health-conscious segments like healthcare and education facilities.
- Commercial Sector Expansion:There is an opportunity to increase penetration in commercial applications like corporate offices and hospitality in Middle Eastern markets, where design trends are shifting toward natural materials.
- Circular Economy Products:Introducing engineered wood flooring lines that utilize reclaimed wood or certified recycled content for their core layers appeals to sustainability mandates and corporate ESG goals.
Industry Challenges
- Certification Management:The operational burden of securing and maintaining multiple sustainability and safety certifications, such as FSC, PEFC, and GREENGUARD, across different product lines and regions is substantial.
- Installer Skill Gaps:A shortage of trained flooring installers proficient in complex installations, such as intricate parquet or herringbone patterns, limits the market for high-value, custom flooring projects.
- Supply Chain Transparency:Establishing and documenting full traceability from the forest to the final product is a major operational hurdle required to comply with emerging anti-deforestation regulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wood Flooring Market |
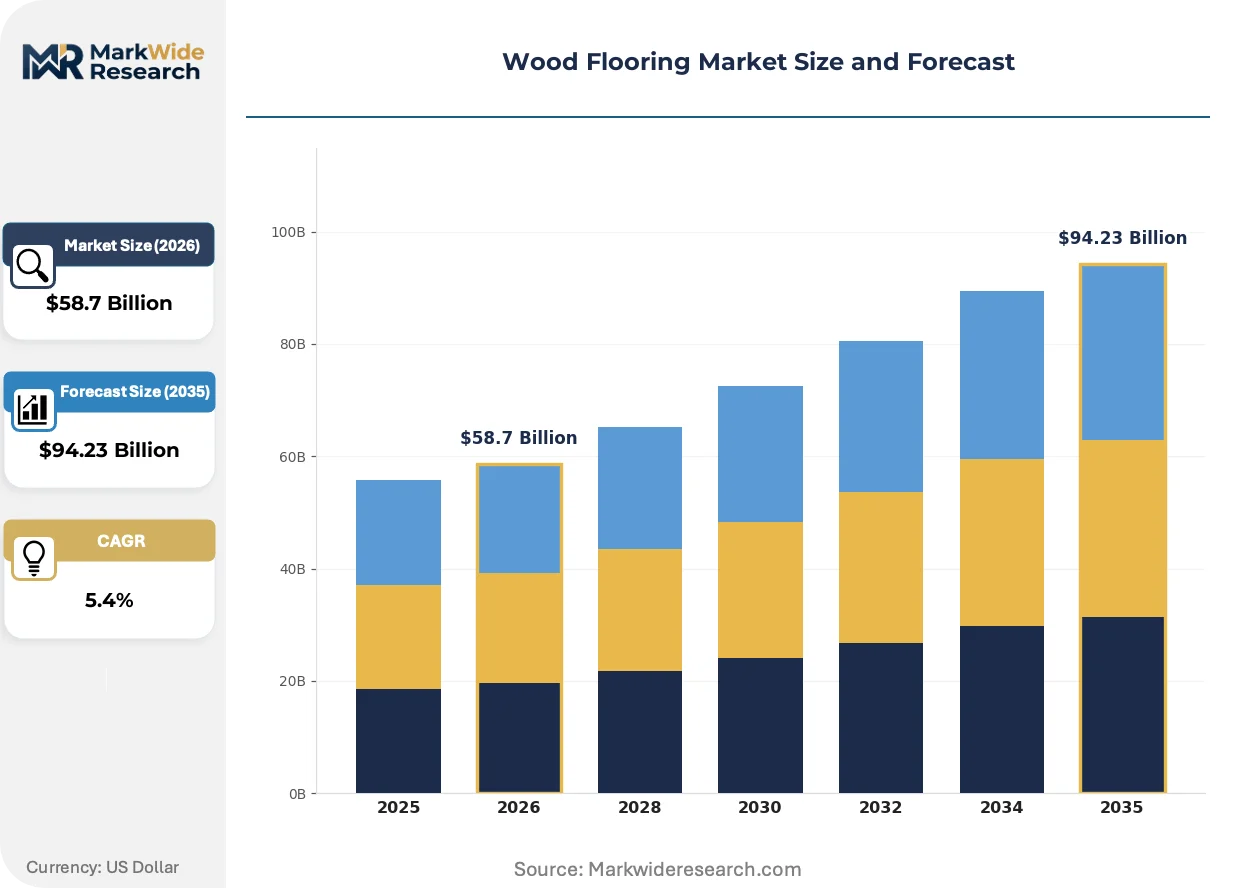
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $94.23 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid Hardwood, Engineered Wood, Bamboo Flooring, Parquet Flooring Installation Method: Glue Down, Nail Down, Floating, Staple Down End User: Residential Properties, Commercial Complexes, Institutional Buildings, Office Spaces Distribution Channel: Specialized Retailers, Direct Sales, Online Platforms, Home Improvement Stores |
| Companies Covered | Mannington Mills, Inc., Beaulieu International Group N.V., Mohawk Industries, Inc., EGGER Holzwerkstoffe GmbH, Kronospan Holding GmbH, Shaw Industries Group, Inc., Armstrong Flooring, Inc., AHF LLC, Tarkett S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wood Flooring Market Strategic Shifts & Innovations
Material science and digital manufacturing are converging to redefine product capabilities and aesthetics. This intersection allows manufacturers to meet stringent environmental standards, such as those governing formaldehyde emissions, while expanding design possibilities beyond the limits of natural timber alone.
Digital printing and surface texturing technologies enable the creation of hyper-realistic grain patterns on engineered wood. Commercial and residential developers are adopting these products for their design consistency and ability to replicate the look of rare woods on a sustainable substrate. The market for premium aesthetics is migrating from a dependence on sourcing exotic timber toward leveraging digitally enhanced designs on abundant, certified wood species.
The European Union's Construction Products Regulation (CPR) is a key policy shift impacting market access. It compels manufacturers to provide a standardized Declaration of Performance (DoP) covering essential characteristics like fire safety and substance emissions. This forces investment in extensive product testing and documentation, particularly for multi-layered engineered products where each component's performance must be verified and declared.
A significant behavioral shift among architects and designers involves the prioritization of products with transparent environmental and health documentation. This trend moves procurement decisions beyond aesthetics and price, giving preference to flooring with certifications like FloorScore or the Cradle to Cradle standard. This demand-side pull is most visible in North American and European commercial projects, especially within the education and healthcare sectors.
Wood Flooring Market Segmentation
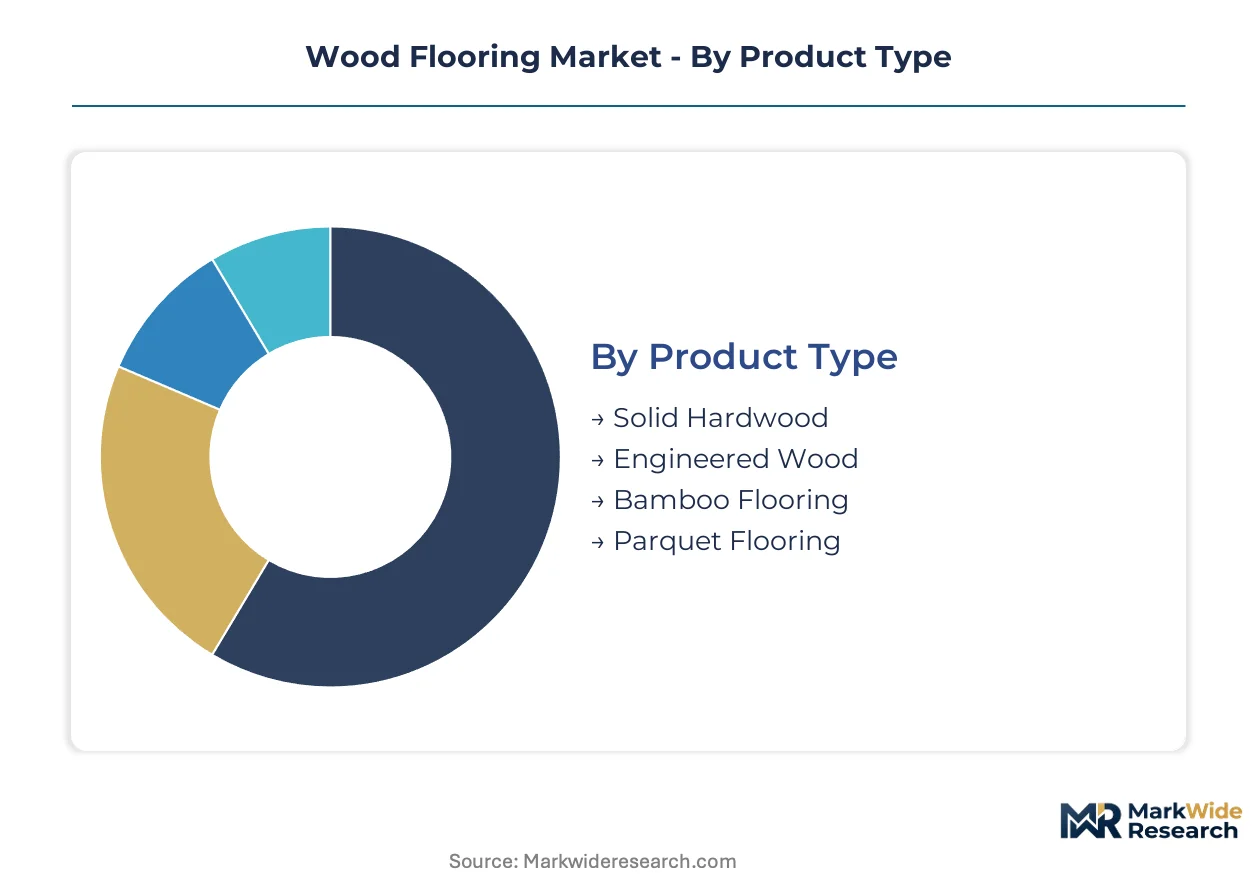
The wood flooring market exhibits diverse segmentation based on product characteristics, installation methods, end-user applications, and distribution channels. Understanding these distinct segments allows manufacturers to tailor product development, marketing strategies, and supply chain logistics to specific demand patterns.
Product Type:
The after-sales service intensity for wood flooring products varies significantly based on their inherent material composition and manufacturing complexity.
- Solid Hardwood:These products consist of a single piece of timber, typically 3/4 inch thick, offering exceptional durability and refinishing potential over decades. Demand concentrates in high-end residential renovation projects in developed markets, where consumers prioritize longevity and authentic aesthetics.
- Engineered Wood:Comprising multiple layers of wood veneers or composite materials topped with a solid wood lamella, engineered wood offers enhanced stability against humidity fluctuations. This segment expands most quickly in new construction within Southeast Asian countries, driven by performance requirements and material efficiency.
- Bamboo Flooring:Crafted from bamboo grass, this product offers a sustainable and hard-wearing alternative with a distinct aesthetic.
- Parquet Flooring:This type involves geometric patterns formed by individual wood pieces, highly valued for decorative and bespoke installations.
Solid Hardwood holds the largest share; momentum sits with Engineered Wood.
Installation Method:
The choice of installation method for wood flooring directly impacts project timelines and the suitability for diverse subfloor conditions.
- Glue Down:This method involves adhering the wood planks directly to the subfloor using a specialized adhesive, providing a very stable and solid feel underfoot. It sees significant use in commercial complexes where long-term stability and sound dampening are critical performance criteria.
- Floating:Planks in a floating installation are connected to each other but not directly fastened to the subfloor, allowing for natural expansion and contraction. This method is gaining share fastest in residential remodeling due to its ease of installation and reduced labor costs.
- Nail Down:Primarily used for solid hardwood, this traditional method secures planks to a wooden subfloor using nails.
- Staple Down:Similar to nail down, this method uses staples to fasten wood flooring, often preferred for engineered wood over wooden subfloors.
Demand for specific installation methods correlates with project scale and desired acoustic properties.
End User:
Different end-user segments exhibit distinct purchasing behaviors and aesthetic preferences for wood flooring products.
- Residential Properties:This segment includes single-family homes, apartments, and condominiums, driven by both new construction and extensive renovation activities. Consumers in this segment prioritize aesthetic appeal, comfort, and indoor air quality, influencing material and finish selections.
- Commercial Complexes:Encompassing retail spaces, hotels, and restaurants, this segment requires highly durable and low-maintenance flooring solutions capable of withstanding heavy foot traffic. The shift towards natural materials in hospitality design in Middle Eastern markets represents a growing opportunity for this segment.
- Institutional Buildings:This segment comprises schools, hospitals, and government facilities, where safety, hygiene, and long-term performance are paramount.
- Office Spaces:Corporate environments seek flooring that combines professional aesthetics with acoustic properties and resistance to wear from office chairs.
Renovation cycles in residential settings consistently drive the largest volume consumption.
Distribution Channel:
The concentration of wood flooring supply channels dictates market reach and pricing strategies across different consumer groups.
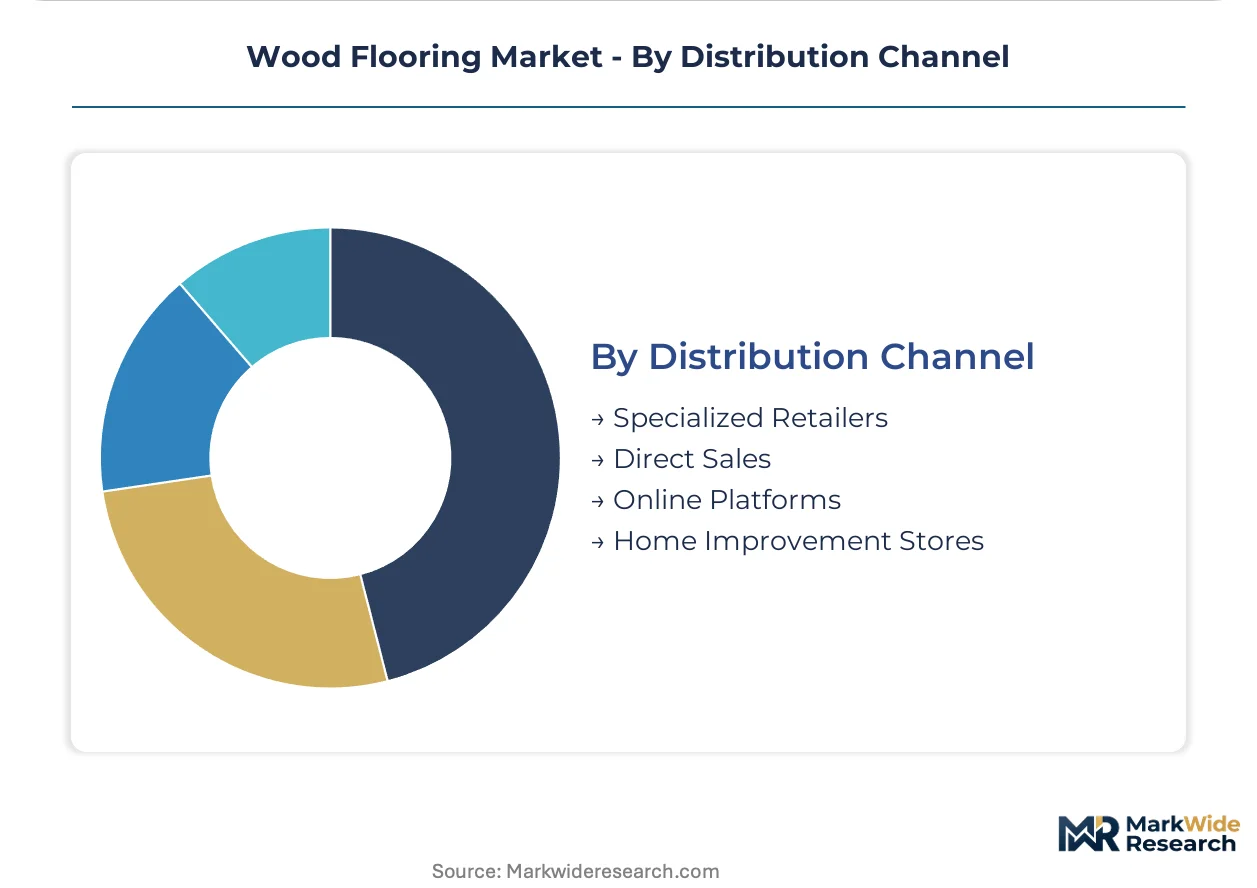
- Specialized Retailers:These outlets offer a curated selection of wood flooring products, often including custom and high-end options, alongside expert installation services and product knowledge. They cater to discerning customers seeking personalized solutions and design consultation.
- Home Improvement Stores:Large format retailers provide a broad range of wood flooring options, from budget-friendly laminates to mid-range engineered wood, emphasizing accessibility and DIY appeal. These stores serve a mass market, offering competitive pricing and convenient purchasing.
- Direct Sales:Manufacturers selling directly to contractors or large developers bypass intermediaries, often facilitating bulk orders and project-specific customization.
- Online Platforms:E-commerce sites offer convenience and a wide product catalog, appealing to consumers prioritizing price comparison and home delivery.
Traditional retail channels maintain significant market share, while digital platforms expand consumer access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government-backed initiatives, such as the EU's Renovation Wave, significantly influence wood flooring demand. These policies promote retrofitting buildings with sustainable materials, directly benefiting certified product manufacturers. This creates distinct regional market dynamics across key global economies.
United States
High-end residential renovation projects drive substantial demand for wood flooring in the United States. The EPA enforces strict formaldehyde emission standards for composite wood products. Metropolitan areas like New York and Los Angeles exhibit robust demand for custom and wide-plank formats.
Germany
Residential remodeling, spurred by the EU's Renovation Wave, boosts wood flooring consumption in Germany. The Construction Products Regulation (CPR) mandates specific performance standards for flooring. Major urban centers like Berlin and Munich see sustained demand for certified and sustainable wood flooring products.
Vietnam
Rapid urbanization and new construction activities are creating substantial demand for wood flooring in Vietnam. The government's focus on sustainable development encourages eco-friendly building materials. Major cities like Ho Chi Minh City and Hanoi drive volume for both solid and engineered wood flooring.
Indonesia
Emerging construction markets and a growing middle class fuel wood flooring demand across Indonesia. The country's forestry regulations promote sustainable timber harvesting and combat illegal logging. Jakarta's extensive urban development represents a significant concentration of new wood flooring installations.
China
Large-scale residential development and commercial projects contribute significantly to wood flooring consumption in China. National GB standards and environmental protection laws influence material composition and sourcing. Major urban clusters like the Yangtze River Delta, especially Shanghai, demand engineered wood in multi-family housing.
Wood Flooring Market Key Industry Players
On the supply side, the industry is diverse and tiered, encompassing a range of players from large, vertically integrated manufacturers to specialized product innovators. This structure includes established players with extensive production capabilities and asset-light brand developers focusing on distribution. Key competitive moves include strategic partnerships with retailers and continuous portfolio diversification to meet evolving aesthetic and performance demands.
Within the established manufacturer tier, Mohawk Industries, Inc. represents a player prioritizing brand development and a vast distribution network. Tarkett S.A. exemplifies a global entity leveraging its broad product portfolio to secure large-scale commercial projects, particularly in the commercial sector. Shaw Industries Group, Inc., a US-based entity, anchors its market presence through deep integration with major home improvement retailers. These companies collectively demonstrate diverse strategies for market penetration and sustained competitive advantage within the wood flooring sector.
| Leading Market Players |
|---|
| Mannington Mills, Inc. |
| Beaulieu International Group N.V. |
| Mohawk Industries, Inc. |
| EGGER Holzwerkstoffe GmbH |
| Kronospan Holding GmbH |
| Shaw Industries Group, Inc. |
| Armstrong Flooring, Inc. |
| AHF LLC |
| Tarkett S.A. |
| Others |
Cost & Logistics Intelligence
The Trans-Pacific shipping lanes' cost dynamics significantly influence wood flooring supply concentration and subsequent retail price differentiation across global markets.
Pricing Analysis
Certification levels, including FSC and FloorScore, create the primary price spread in the wood flooring market. The dominant pricing structure features premium-mid-economy differentiation, influenced by material quality, finish type, and after-sales service bundles. Margin pressure stems from raw timber input cost volatility, particularly for sought-after species like European oak. High-end residential buyers, valuing custom aesthetics, exhibit lower price sensitivity, while mass-market home improvement store consumers remain highly price-sensitive.
Supply Chain Analysis
The EU's Construction Products Regulation and US Lacey Act, as regulatory export controls, limit timber flows from non-compliant sources. Supply concentrates in timber-rich regions like Europe and emerging markets in Southeast Asia, including Vietnam and Indonesia, drawing heavily on raw timber, wood veneers, and specialized adhesives. Regulatory restrictions, such as anti-deforestation laws, pose a significant structural risk, requiring rigorous documentation. Traditional retail channels like specialized stores and large home improvement chains dominate downstream distribution across developed markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wood flooring market faces a buyer-power shift, driven by the increasing consolidation of major home improvement retailers.
For Market Incumbents: Build distribution network density to reinforce market presence against emerging online platforms. Incumbents like Shaw Industries Group must deepen integration with major home improvement retailers, ensuring shelf space and promotional visibility. Investing in advanced ultra-low VOC finishes and formaldehyde-free adhesives can counter substitution from advanced LVT products. Prioritizing certification investment, such as FloorScore, enhances brand trust and market access in regulated segments.
For New Entrants and Emerging Players: Build out specialized product lines targeting niche aesthetics and performance requirements. New entrants should focus on custom wide-plank formats or circular economy products utilizing reclaimed content. The high-end residential renovation segment in developed markets like Germany offers the most penetrable entry point. A direct-to-designer sales model, emphasizing bespoke solutions and sustainability documentation, provides a strong go-to-market angle.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified building materials conglomerates seeking to streamline portfolios. The wood flooring market demonstrates long-term viability, anchored by consistent residential renovation cycles. Investors should seek asset-light manufacturers with strong brand equity or proprietary digital manufacturing technologies. The signal to watch is the accelerating adoption rates of digitally printed engineered wood, indicating a shift in premium aesthetic procurement.
| Strategic Initiative | Industry Significance |
|---|---|
| Deepen Retailer Partnerships | Secures prime shelf space and promotional support within major home improvement retailers like Home Depot. |
| Invest in Digital Manufacturing | Enables hyper-realistic grain patterns on engineered wood, meeting evolving design consistency demands. |
| Expand Certified Product Portfolio | Addresses growing demand for sustainable materials, particularly in EU Renovation Wave projects. |
| Target Commercial Hospitality | Penetrates Middle Eastern markets where design trends favor natural materials in new developments. |
| Develop Installer Training Programs | Mitigates installer skill gaps, supporting high-value custom flooring projects like intricate parquet. |
Research Approach
The analysis maps wood flooring product types and end-user applications, each validated through primary interviews with industry stakeholders. This involved conversations with manufacturers, specialized retailers, architects, and flooring contractors. Secondary validation drew from EU CPR documents, EPA emission standards, and customs trade data. Bottom-up and top-down triangulation methods ensured comprehensive data accuracy.
Assumptions regarding global economic growth and construction activity were held fixed, while regulatory stringency was varied across the projection horizon. The analytical framework modeled segmentations by product type, installation method, end-user application, and distribution channel. Compound annual growth rates derived from historical trends integrated timber price volatility and LVT substitution rates. This approach ensured a robust market outlook.
Stress conditions across raw material availability and geopolitical trade policies were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these defined assumptions. Material shifts in anti-deforestation regulations or global construction slowdowns would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
United States Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Luxury Vinyl Tiles Market
Flooring, Carpets, and Rugs
Laminate Flooring Market
Flooring, Carpets, and Rugs
GCC Floor Covering Market
Flooring, Carpets, and Rugs
Decorative Rugs Market
Flooring, Carpets, and Rugs
Europe Floor Covering Market
Flooring, Carpets, and Rugs
Fiberglass Flooring Market
Flooring, Carpets, and Rugs
Global Soft Covering Flooring Market
Flooring, Carpets, and Rugs
Europe Carpet Tile Market
Flooring, Carpets, and Rugs
Asia Pacific Flooring Market
Flooring, Carpets, and Rugs
China Luxury Vinyl Tile (LVT) Market
Flooring, Carpets, and Rugs
Brazil Floor Covering Market
Flooring, Carpets, and Rugs
Europe Flooring Market
Flooring, Carpets, and Rugs
Carpets and Rugs Market
Flooring, Carpets, and Rugs
Global Luxury Vinyl Tile Floor Covering Market
Flooring, Carpets, and Rugs
US Vinyl Floor Covering Market