
 United States Non-Resilient Floor Covering Market | 2026-2036
United States Non-Resilient Floor Covering Market Size, Share, and Industry Trends Forecast 2026-2036
United States Non-Resilient Floor Covering Market Analytics
Market Dynamics
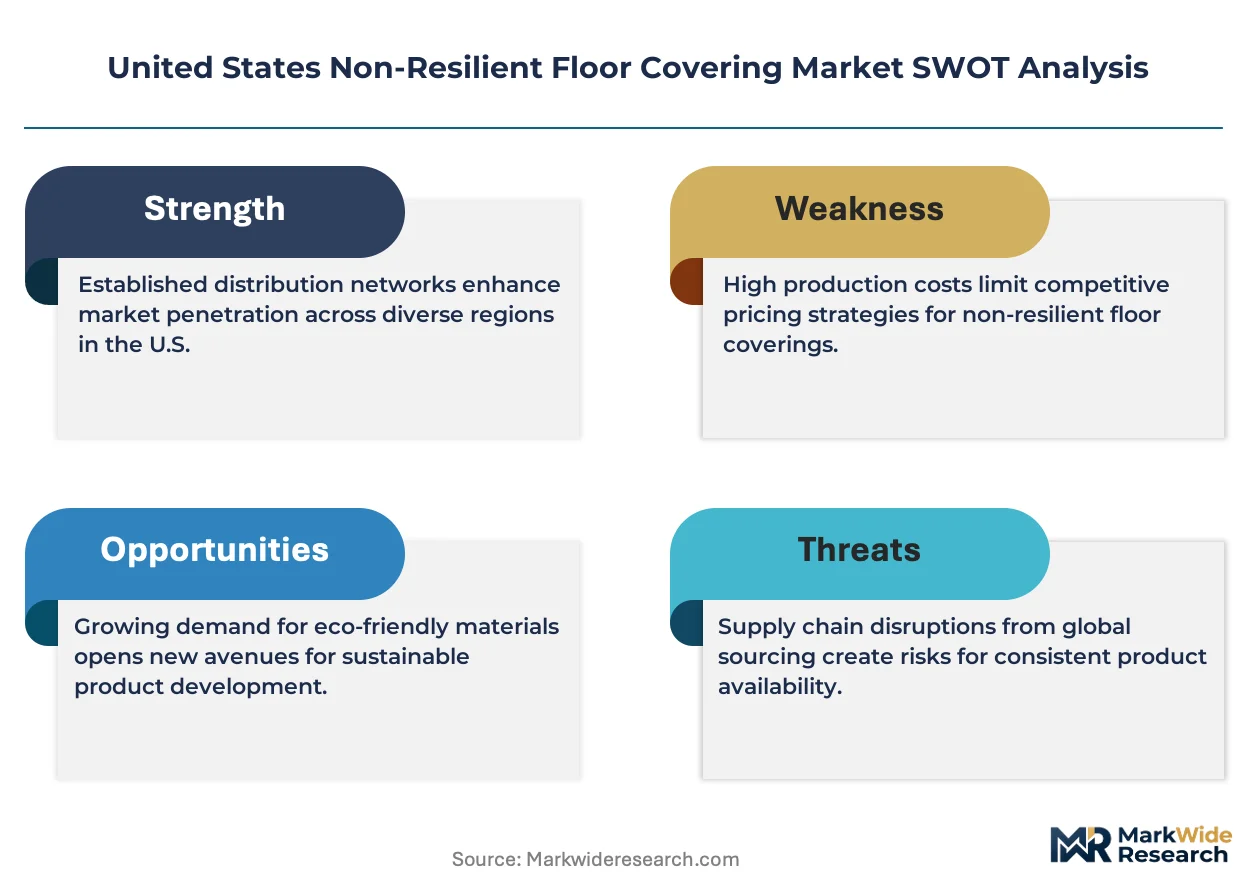
The capital-intensity divergence between integrated tile manufacturers and specialized laminate producers is redrawing competitive boundaries in the United States non-resilient floor covering industry. Mohawk Industries leverages captive ceramic production and broad distribution infrastructure to sustain margin resilience across price cycles. Shaw Industries Group anchors its position through advanced digital printing technology on laminate and vinyl composition tile lines. Mannington Mills differentiates via regional manufacturing density and quick-turn commercial specification capabilities.
Product Landscape
Non-resilient floor coverings encompass rigid surfacing materials including ceramic tile, natural stone, laminate, and vinyl composition tile, typically installed with mortar, adhesive, or mechanical fastening systems requiring subfloor preparation and expansion joint management. These products serve primary commercial and institutional functions where dimensional stability, load-bearing capacity, and moisture resistance exceed resilient flooring performance thresholds. Ceramic tiles occupy the largest value pool due to entrenched specification in healthcare and education verticals, while laminate flooring segments capture faster volume growth through floating installation methods that reduce skilled labor dependency. Natural stone maintains premium positioning in hospitality and corporate lobby applications where aesthetic differentiation commands specification loyalty.
Regulatory Environment
EPA formaldehyde emission standards under the Toxic Substances Control Act and OSHA workplace silica exposure limits govern manufacturing processes and jobsite cutting practices for non-resilient flooring materials. The FTC Green Guides and California Air Resources Board certification requirements shape product labeling and environmental marketing claims accessible to specifiers. Stakeholders must monitor evolving state-level extended producer responsibility proposals and embodied carbon disclosure mandates that threaten to restructure material selection criteria in public procurement.
Market Dynamics
EPA formaldehyde emission standards under the Toxic Substances Control Act are forcing material reformulation across ceramic, laminate, and vinyl composition tile supply chains. Manufacturers must reconfigure adhesive systems and substrate compositions to maintain specification access in healthcare and education verticals where indoor air quality compliance gates procurement decisions.
Growth Catalysts
- Sun Belt Construction Surge:New residential and commercial builds in Florida, Texas, and Arizona outpace national averages, concentrating demand for ceramic tile and laminate flooring in these high-migration corridors.
- Healthcare Infection Control Mandates:Joint Commission standards and CMS reimbursement policies reward non-porous, seam-minimized flooring in acute care settings, elevating ceramic and stone specification rates.
- OSHA Silica Rule Compliance:Workplace exposure limits on crystalline silica during cutting operations accelerate adoption of pre-sized tile modules and water-cooled saws that reduce on-site dust generation.
Market Restraints
- Petrochemical Input Volatility:Vinyl composition tile and laminate backing layers depend on PVC resin and melamine-formaldehyde chemistry, exposing margins to ethylene and natural gas feedstock swings.
- Skilled Installer Scarcity:Mortar-set ceramic and natural stone require certified tile setters; union apprenticeship programs in California and New York cannot match retirement-driven attrition.
- Resilient Flooring Substitution:Luxury vinyl plank and sheet vinyl with enhanced wear layers capture mid-market commercial projects where budget constraints override durability premiums.
Strategic Opportunities
- Carbon Disclosure Procurement Mandates:California and New York State pilot programs for embodied carbon reporting in public buildings create first-mover advantage for manufacturers with Environmental Product Declarations and third-party verified life-cycle assessments.
- Floating Installation Technology:Click-lock laminate and rigid core vinyl systems reduce labor dependency and permit faster tenant improvement cycles in speculative office and retail buildouts.
- Rural Healthcare Modernization:USDA Rural Development grants and Hill-Burton Act successor programs fund clinic renovations across the Mountain West and Great Plains, opening specification channels outside traditional coastal corridors.
Industry Challenges
- Cross-Training Deficits in Digital Specification Tools:Architects and interior designers lack fluency in Building Information Modeling plugins for flooring performance simulation, slowing technology adoption in design-build workflows.
- Extended Producer Responsibility Compliance Burden:Proposed state-level take-back programs for construction and demolition waste threaten to impose reverse logistics costs on manufacturers without established reclamation infrastructure.
Report Scope
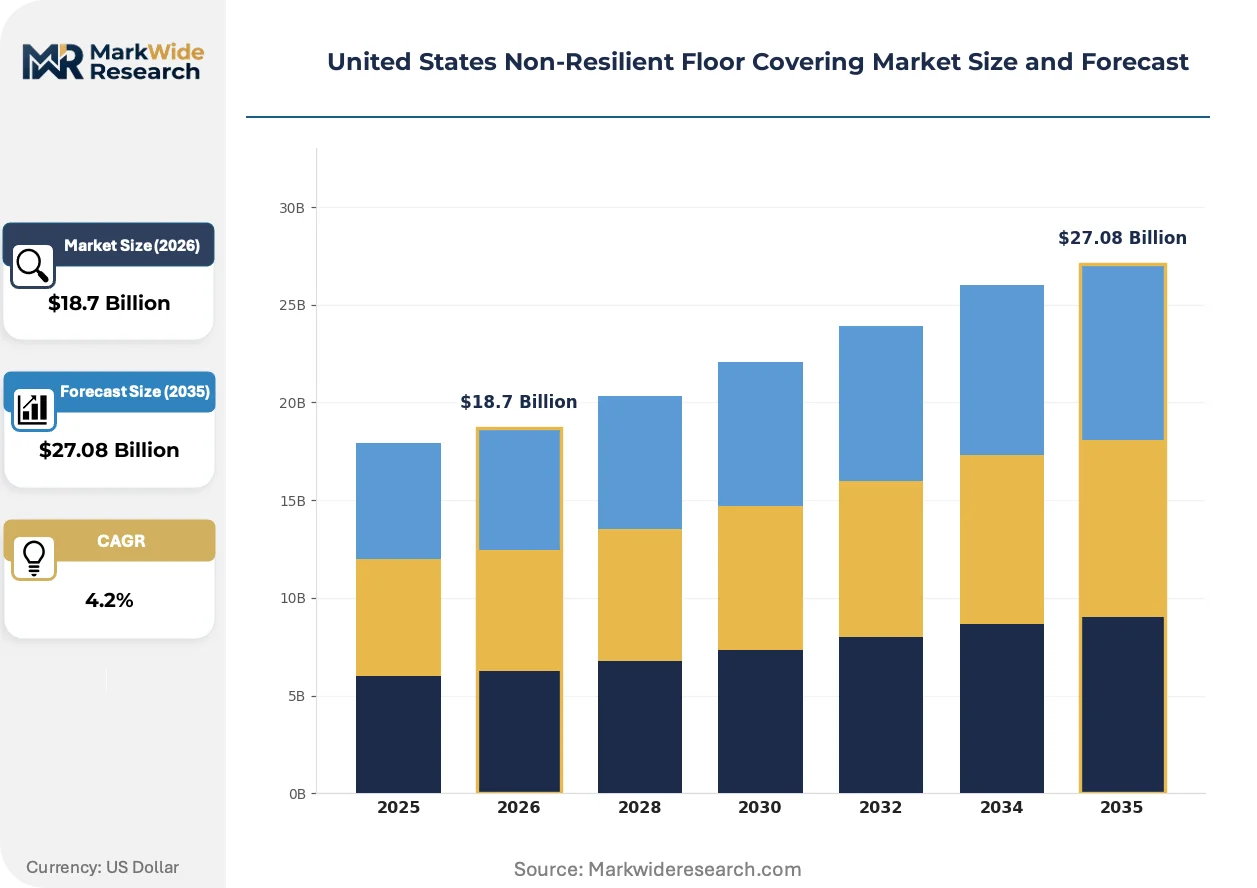
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Non-Resilient Floor Covering Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $27.08 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ceramic Tiles, Laminate Flooring, Vinyl Composition Tiles, Natural Stone Installation Method: Glue-Down, Floating, Nail-Down, Grout End User: Residential, Commercial, Industrial, Institutional Thickness: Thin, Medium, Thick, Extra Thick |
| Companies Covered | Mohawk Industries Inc, Shaw Industries Group Inc, Armstrong Flooring Inc, Marazzi Group, Florida Tile Inc, Mannington Mills Inc, Daltile, Crossville Inc, Interface Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Non-Resilient Floor Covering Market Evolving Landscape
Digital printing technology is collapsing the aesthetic premium historically commanded by natural stone and exotic wood species. Surface replication fidelity now enables laminate and vinyl composition tile to penetrate specification tiers previously reserved for quarry materials, rewiring buyer value calculations across commercial verticals.
High-definition inkjet decoration is supplanting traditional rotogravure and screen printing in ceramic and laminate production. Healthcare facility managers specify these digitally printed surfaces for patient corridors and waiting areas where visual warmth supports healing environment protocols. The technology compresses SKU proliferation costs while accelerating style refresh cycles that previously required capital-intensive mold changes.
California Air Resources Board certification requirements for low-emitting materials now extend beyond formaldehyde to encompass volatile organic compound thresholds in installation adhesives and surface sealants. Flooring contractors in the state must document chain-of-custody compliance for LEED and WELL Building Standard projects. Manufacturers with in-house toxicology testing capabilities capture specification preference in public K-12 and community college procurement.
Facility managers in the hospitality sector now unbundle flooring specification from general contractor packages, engaging directly with manufacturers for performance warranties and maintenance training. This disintermediation compresses distributor margins while rewarding suppliers with technical service depth. Casino and resort operators in Nevada and Atlantic City drive this pattern, seeking direct accountability for slip resistance and stain warranty claims in high-traffic gaming and food service zones.
United States Non-Resilient Floor Covering Market Segmentation
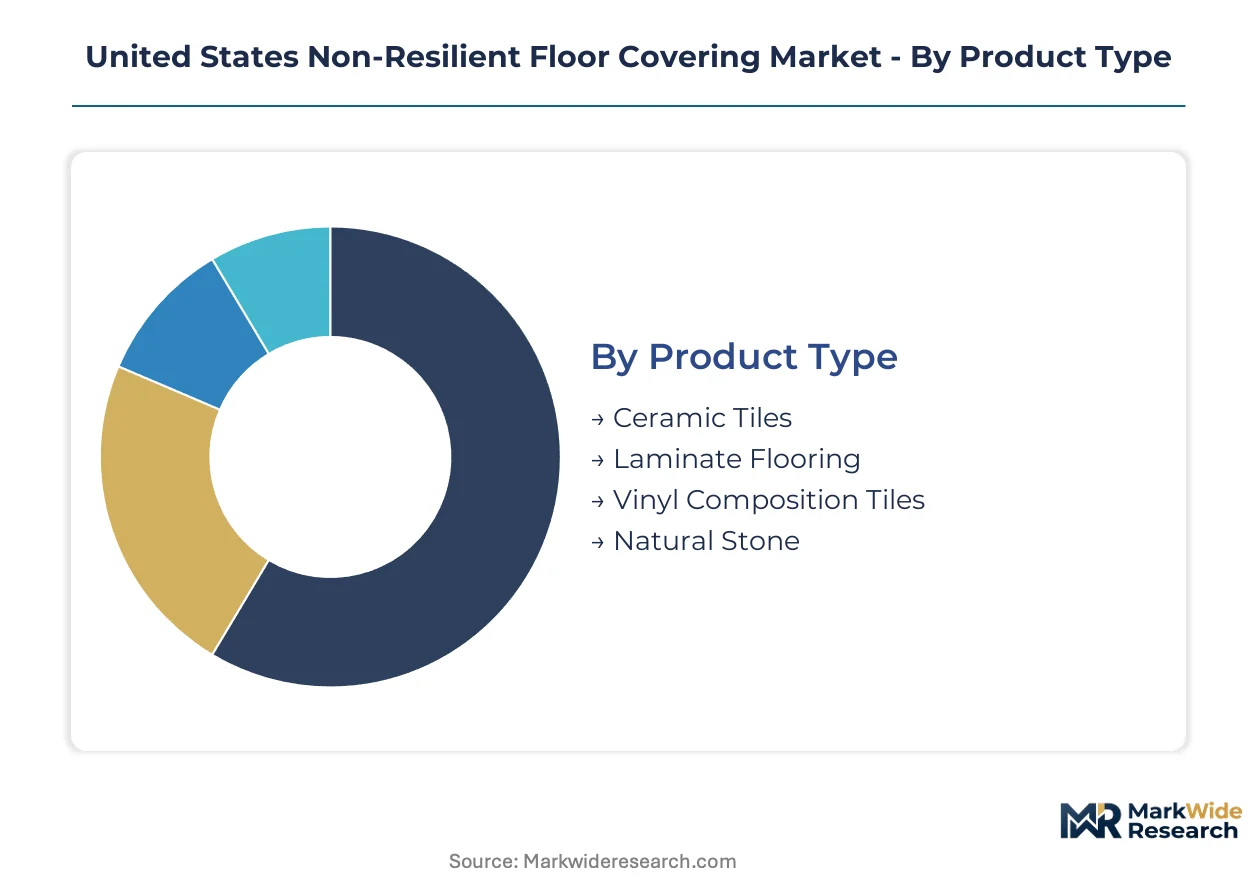
Non-resilient floor covering procurement decisions cascade through multiple technical dimensions. Specification teams weigh product chemistry against installation constraints, end-use traffic loads, and subfloor preparation requirements. Each segmentation axis carries distinct margin implications and supply chain configurations.
Product Type:
Ceramic tiles dominate domestic production capacity concentrated in Tennessee and Texas manufacturing corridors. Laminate flooring relies more heavily on Asian substrate imports, creating divergent tariff exposure profiles.
- Ceramic Tiles:Fired clay and porcelain compositions deliver impervious surfaces specified for Joint Commission-compliant healthcare environments. Demand concentrates in Sun Belt acute care construction where infection control mandates elevate specification rates. EPA formaldehyde standards favor ceramic's inorganic chemistry over resin-based alternatives.
- Laminate Flooring:High-density fiberboard cores with melamine-impregnated decorative layers enable floating installation methods. Texas and Florida residential builders specify these for cost-sensitive multifamily projects where speed-to-occupancy drives procurement. Digital printing advances collapse the aesthetic gap with exotic hardwood species.
- Vinyl Composition Tiles:PVC resin and limestone filler formulations serve high-traffic institutional corridors in K-12 and community college verticals.
- Natural Stone:Granite, marble, and travertine maintain premium positioning in hospitality lobbies and corporate headquarters where specification budgets accommodate material and skilled labor premiums.
Ceramic tiles hold the largest share; momentum sits with laminate flooring.
Installation Method:
Cost tier stratification separates labor-intensive traditional methods from capital-light floating systems. Glue-down and grout applications demand certified trades; floating methods reduce skilled installer dependency.
- Glue-Down:Pressure-sensitive and wet-set adhesives secure vinyl composition tile and laminate in commercial environments where dimensional stability under rolling loads is mandatory. California contractors face CARB-compliant adhesive sourcing constraints that elevate material costs.
- Floating:Click-lock and loose-lay systems eliminate subfloor adhesive preparation, compressing tenant improvement timelines in speculative office buildouts. Arizona and Nevada retail developers specify these for rapid lease-up cycles.
- Nail-Down:Traditional hardwood-style fastening persists in residential renovation where existing plywood subfloors permit mechanical attachment.
- Grout:Mortar-bed and thin-set applications for ceramic and stone demand certified tile setter labor pools concentrated in union states.
Glue-down methods retain commercial dominance; floating installation is gaining share fastest.
End User:
Volume concentration varies sharply by customer type, with institutional procurement governed by public bid processes and residential sales flowing through distribution networks.
- Residential:Single-family and multifamily builders in Florida, Texas, and Arizona drive ceramic and laminate volume through production home specifications. Builder preference programs lock in manufacturer relationships across metro Phoenix and Dallas-Fort Worth.
- Commercial:Office, retail, and hospitality developers prioritize wear-layer performance warranties and maintenance training programs. Nevada casino operators now bypass distributors for direct manufacturer engagement.
- Industrial:Manufacturing and warehouse facilities specify heavy-duty vinyl composition tile with static-dissipative properties for cleanroom and electronics assembly environments.
- Institutional:Public K-12, healthcare, and government buildings operate under LEED and WELL Building Standard compliance gates that favor EPD-documented products.
Residential channels move the highest unit volumes; institutional verticals command premium pricing.
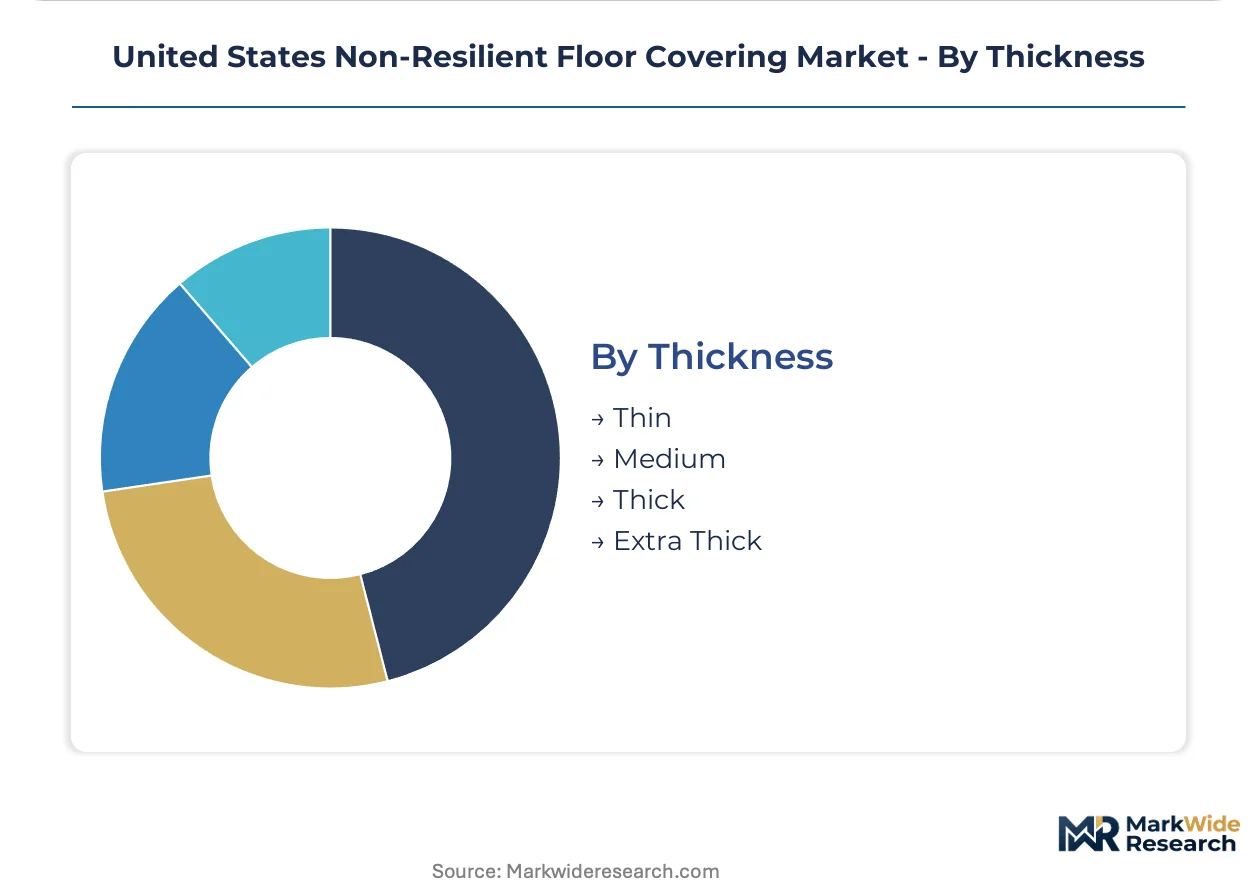
Thickness:
Performance tier alignment maps thickness grades to traffic load expectations and subfloor condition tolerance.
- Thin:Sub-6mm products serve budget-constrained renovation where existing floor height constraints limit build-up. Residential landlords in Sun Belt secondary markets specify these for quick-turn apartment refreshes.
- Medium:6-10mm laminates and ceramic formats balance impact resistance with material cost efficiency across mid-market commercial specifications.
- Thick:10-14mm rigid core and porcelain formats deliver acoustic dampening and thermal mass for hospitality and senior living environments.
- Extra Thick:14mm+ stone and engineered formats accommodate underfloor heating integration in luxury residential and wellness facility construction.
Medium thickness commands the broadest specification base; extra thick formats show steepest expansion trajectory in healthcare and hospitality.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across the United States diverge sharply between Sun Belt migration corridors and legacy industrial markets, with the former driving ceramic and laminate volume while the latter sustains specialized stone and institutional specification channels.
Texas
Dallas-Fort Worth and Houston metro areas concentrate multifamily construction activity where laminate flooring specifications dominate cost-sensitive builder programs. The Texas Commission on Environmental Quality enforces volatile organic compound limits on installation adhesives that elevate compliant material costs. Manufacturing clusters in the Dallas-Fexas corridor host ceramic tile production facilities serving regional distribution networks.
Florida
Miami, Tampa, and Orlando residential markets absorb substantial ceramic tile imports through Port Everglades and Port Tampa Bay entry points. The Florida Building Code mandates moisture-resistant subfloor preparations that favor porcelain formats in ground-level construction. Tile setter labor pools in South Florida face capacity constraints from hurricane reconstruction cycles competing for skilled trades.
California
Los Angeles and San Francisco Bay Area commercial specifications operate under the strictest indoor air quality regime nationwide. The California Air Resources Board certifies low-emitting materials for public K-12 and community college procurement gates. Sacramento Valley distribution centers stage laminate and vinyl composition tile inventories for West Coast contractor fulfillment.
Arizona
Phoenix and Tucson retail developers prioritize rapid tenant improvement cycles that accelerate floating installation method adoption. The Arizona Department of Environmental Quality administers construction waste diversion requirements affecting demolition flooring removal protocols. Speculative office buildouts in Scottsdale and Tempe drive rigid core product specifications.
New York Metro
Manhattan and Brooklyn commercial renovations sustain premium natural stone specification for corporate lobby and hospitality applications. The New York State Department of Environmental Conservation enforces extended producer responsibility proposals that threaten reverse logistics cost structures. Union-certified tile setter apprenticeships in the five boroughs cannot match retirement-driven attrition rates.
United States Non-Resilient Floor Covering Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive raw material control separating margin-resilient players from specification-dependent competitors. The market structure concentrates around manufacturers with in-house ceramic production, regional distribution density, and digital printing capabilities. Three archetypes dominate: integrated multinationals with backward supply chain control, regional specialists with quick-turn commercial specification services, and import-dependent distributors with floating installation technology portfolios. Competitive moves center on M&A consolidation of ceramic production assets and strategic partnerships for carbon disclosure documentation.
Within the integrated multinational tier, Mohawk Industries Inc and Shaw Industries Group Inc exemplify scale-driven archetypes with broad distribution infrastructure spanning residential and commercial channels. Mannington Mills Inc occupies a position within the regional specialist segment, anchoring quick-turn specification capabilities for institutional verticals. Florida Tile Inc represents the import-dependent distributor model, sitting within Sun Belt market concentration where port access and logistics efficiency determine competitive positioning. These three company structures illustrate the vertical-tier divergence reshaping procurement relationships across the industry.
| Leading Market Players |
|---|
| Mohawk Industries Inc |
| Shaw Industries Group Inc |
| Armstrong Flooring Inc |
| Marazzi Group |
| Florida Tile Inc |
| Mannington Mills Inc |
| Daltile |
| Crossville Inc |
| Interface Inc |
| Others |
Value Network & Pricing Analysis
Sixty-day ceramic tile inventory cycles in Tennessee and Texas manufacturing corridors compress pricing power for integrated producers while amplifying volatility for import-dependent laminate distributors. This lead-time spread between captive production and Asian substrate sourcing directly shapes margin resilience across contract structures.
Pricing Analysis
Long-term offtake agreements dominate institutional procurement for ceramic and vinyl composition tile, locking in volume commitments from healthcare and education verticals. Price differentiation rests on CARB certification tier and installation method complexity, with glue-down systems commanding premiums over floating alternatives. Cost compression in laminate segments intensifies due to melamine-formaldehyde input volatility. Residential builders in Sun Belt states exhibit highest price sensitivity; hospitality developers in Nevada and Atlantic City show lowest, prioritizing direct manufacturer accountability over unit cost.
Supply Chain Analysis
Strategic stockpile preferences concentrate among integrated ceramic manufacturers buffering against Tennessee Valley clay supply interruptions, while laminate distributors run lean just-in-time inventories exposed to port congestion. Production gravity centers on Tennessee, Texas, and China for ceramic, with high-density fiberboard substrates drawing from Malaysian and Indonesian pulp feedstocks. Single-source vulnerability in Asian melamine resin supply threatens laminate margin stability. Distribution runs through regional stocking distributors serving contractor fulfillment networks, with direct manufacturer engagement gaining share in commercial hospitality.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as healthcare infection control mandates penetrate rural clinic construction and carbon disclosure procurement gates restructure public sector specification criteria.
For Market Incumbents: Consolidate ceramic production assets in Tennessee and Texas corridors to defend against resin-based flooring substitution in mid-market commercial. Secure captive limestone filler supply for vinyl composition tile to buffer PVC resin price swings. Deepen backward integration into digital printing equipment to compress SKU proliferation costs. For New Entrants and Emerging Players: Lead with floating installation technology targeting speculative office buildouts in Arizona and Nevada where rapid lease-up cycles reward speed-to-occupancy. Penetrate USDA Rural Development-funded clinic renovations across Mountain West states underserved by coastal specification channels. Deploy direct-to-contractor digital specification tools bypassing traditional distributor markups. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because ceramic production capacity scarcity and regional distribution density advantages compound over replacement cycles. Target mid-cap manufacturers with in-house toxicology testing capabilities and established Environmental Product Declarations. Watch California and New York embodied carbon disclosure mandate adoption rates as inflection signal for procurement gate restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Raw Material Supply | Captive limestone and clay sourcing buffers Mohawk and Shaw against petrochemical input volatility. |
| Carbon Disclosure Documentation Investment | Third-party verified life-cycle assessments unlock California and New York public procurement gates. |
| Floating Installation Technology Expansion | Click-lock laminate systems reduce skilled labor dependency in Sun Belt multifamily construction. |
| Direct Manufacturer Engagement Programs | Nevada casino operators now bypass distributors for technical service depth and warranty accountability. |
| Regional Manufacturing Density Optimization | Quick-turn commercial specification capabilities anchor Mannington's institutional vertical positioning. |
Research Methodology
Desk research of EPA formaldehyde emission filings, OSHA silica exposure compliance records, and state-level extended producer responsibility proposals preceded structured interviews with ceramic plant managers, commercial flooring contractors, healthcare facility procurement directors, and distributor inventory planners. Secondary validation drew from Tennessee and Texas manufacturing cluster trade data, CARB certification databases, and healthcare construction permit records. Bottom-up volume estimates triangulated against top-down construction spending allocations across Sun Belt states.
Variance decomposition across product type, installation method, end-user vertical, and regional regulatory cluster shaped analytical framework outputs over the projection horizon. CAGRs derived from segmented growth rate reconciliation against macro construction indicators. Modeled inputs included Joint Commission infection control specification rates, union tile setter apprenticeship graduation trajectories, and floating installation technology penetration curves in speculative commercial buildouts.
Underlying assumptions cover sustained healthcare construction spending and stable ethylene feedstock pricing, with deviation risk concentrated in state-level carbon disclosure mandate acceleration and Asian substrate tariff regime shifts. Forecasts reflect these conditions without scenario weighting. Revision becomes warranted when laminate import tariff rates or silica exposure enforcement intensity crosses thresholds altering contractor method preferences.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
India Carpets and Rugs Market
Flooring, Carpets, and Rugs
India Wood Flooring Market
Flooring, Carpets, and Rugs
North America Wood Flooring Market
Flooring, Carpets, and Rugs
Europe Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Global Non-Resilient Flooring Market
Flooring, Carpets, and Rugs
Flooring Wood Panels Market
Flooring, Carpets, and Rugs
Japan Floor Covering Market
Flooring, Carpets, and Rugs
India Vinyl Flooring Market
Flooring, Carpets, and Rugs
Global Soft Covering Flooring Market
Flooring, Carpets, and Rugs
Global Vinyl Flooring Market
Flooring, Carpets, and Rugs
Canada Terrazzo Flooring Market
Flooring, Carpets, and Rugs
Rigid Core Flooring Market
Flooring, Carpets, and Rugs
Wood Flooring Market
Flooring, Carpets, and Rugs
Luxury Vinyl Plank (LVP) Market
Flooring, Carpets, and Rugs
Europe Carpet and Rugs Market
Flooring, Carpets, and Rugs
Brazil Floor Covering Market