
 Global Vinyl Floor Covering Market | 2026-2036
Global Vinyl Floor Covering Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vinyl Floor Covering Market Foresight
Modular click-lock configurations is broadening buyer choice across residential and light-commercial segments. Mohawk Industries leverages captive resin compounding to control raw material variability across its vinyl plank lines. Tarkett SA anchors European hospital and school specifications through low-VOC certification programs. Shaw Industries Group competes on domestic manufacturing scale, operating multiple U.S.-based calendering and extrusion facilities.
Vinyl floor covering comprises polyvinyl chloride resin blended with plasticizers, stabilizers, and print layers, typically calendered into sheets or extruded into tiles and planks with wear-layer thickness ranging from 6 mil to 28 mil for commercial durability. Its primary purpose spans cost-effective surfacing for high-traffic commercial interiors and moisture-resistant residential basements and kitchens. Luxury vinyl tiles now lead value contribution due to superior margin pools in design-forward hospitality and retail fit-outs, while glue-down sheet vinyl remains entrenched in healthcare institutional buildings where seamless hygiene protocols dominate specification. Click lock installation is displacing traditional adhesive methods in residential renovation channels as DIY-friendly assembly reduces labor cost and project duration.
The U.S. EPA regulates phthalate content in vinyl flooring through TSCA Section 6 restrictions, while the EU REACH framework limits specific plasticizer chemistries in indoor applications. California's CDPH Section 01350 sets emission testing protocols that manufacturers must navigate for state-level procurement eligibility. China's GB standards govern formaldehyde and VOC thresholds in building materials sold domestically. Stakeholders must monitor evolving chemical restriction schedules across multiple jurisdictions to anticipate reformulation timelines and avoid stranded inventory positions.
Market Dynamics
REACH compliance deadlines across Europe are compressing reformulation timelines for phthalate-based plasticizers, forcing manufacturers to rebuild supply chains around bio-based alternatives before 2025 restriction phases take full effect.
Growth Catalysts
- Residential renovation acceleration:Germany's housing stock renewal programs are accelerating specification of click-lock vinyl planks in owner-occupied units, with DIY installation reducing project labor costs by half.
- REACH Annex XVII restrictions:The EU's phased prohibition on specific plasticizer chemistries is creating first-mover advantage for manufacturers with compliant formulations already certified for hospital and school environments.
- Digital printing layer advances:High-definition rotogravure and UV-cured ink systems are enabling photorealistic wood and stone replication at wear-layer thicknesses below 12 mil, opening economy-tier hospitality segments.
Market Restraints
- Petrochemical input volatility:PVC resin and plasticizer feedstocks track ethylene and propylene spot markets, exposing margin stability to crude oil price swings and refinery capacity constraints in the US Gulf Coast.
- Concentrated stabilizer supply:Organotin and calcium-zinc heat stabilizer production concentrates in Chinese specialty chemical clusters, creating single-source vulnerability for European calendering operations.
- Seamless sheet substitution:Glue-down sheet vinyl retains specification lock-in for healthcare operating theaters and cleanrooms where joint-free hygiene protocols override LVT aesthetic advantages.
Strategic Opportunities
- Tier-two Chinese urbanization:Commercial real estate development in Chengdu, Wuhan, and Xi'an is outpacing saturation in Shanghai and Beijing, creating specification windows for mid-market LVT distributors.
- California CDPH 01350 procurement:State-level emission testing protocols for public school construction are elevating low-VOC vinyl flooring to sole-source eligibility in K-12 bond-funded projects.
- Wear-layer nanocoating convergence:Ceramic bead and UV-cured polyurethane surface treatments are extending commercial warranty periods from 10 to 20 years, repositioning vinyl against engineered hardwood in boutique retail.
Industry Challenges
- Multi-jurisdiction compliance staffing:Manufacturers must maintain parallel regulatory intelligence functions for EPA TSCA Section 6, REACH SVHC candidate list updates, and China's GB 18580 formaldehyde standards.
- Legacy adhesive inventory stranding:Warehouse positions in solvent-based pressure-sensitive adhesives face accelerated obsolescence as click-lock floating floor systems capture residential renovation volume.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vinyl Floor Covering Market |
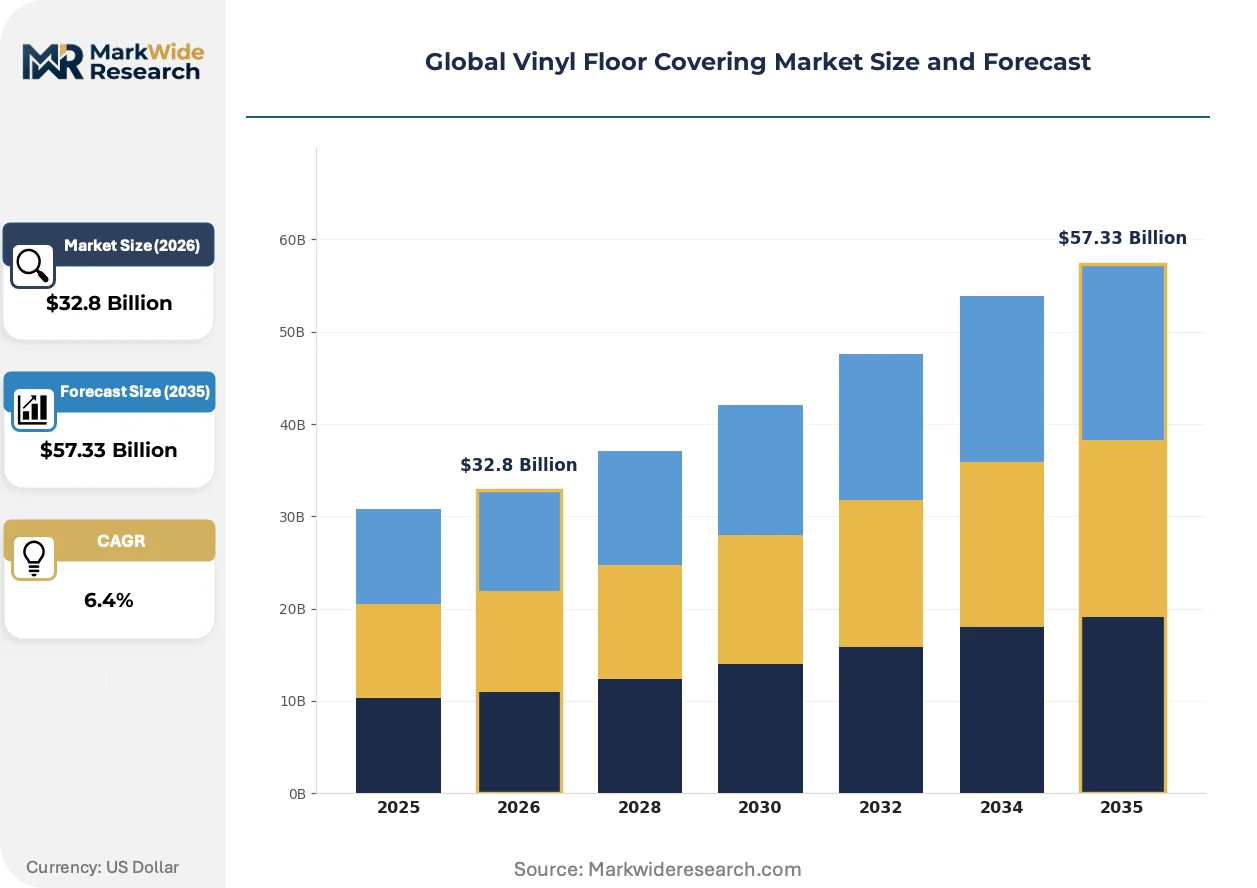
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $57.33 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sheet Vinyl, Luxury Vinyl Tiles, Vinyl Planks, Vinyl Tiles Installation Method: Glue-Down, Loose Lay, Click Lock, Self-Adhesive End User: Commercial Spaces, Educational Facilities, Hospitality, Institutional Buildings Distribution Channel: Specialty Retailers, Online Retailers, Wholesalers, Direct Sales |
| Companies Covered | Mohawk Industries, Tarkett SA, Shaw Industries Group, Gerflor Group, Mannington Mills, Armstrong Flooring, Forbo Flooring Systems, Polyflor Ltd, LG Hausys, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vinyl Floor Covering Market Shifts & Advancements
Surface engineering and installation mechanics are converging to compress project timelines and expand addressable flooring segments beyond traditional vinyl strongholds.
Digital twin visualization tools are unifying specification workflows between architects, contractors, and facility managers. Hospitality designers in Dubai and Singapore are adopting real-time render engines to validate LVT patterns against lighting conditions before order commitment. This technology is unifying decision cycles that previously required physical sample loops, compressing procurement timelines from weeks to days.
EPA TSCA Section 6 restrictions on phthalate content are tightening enforcement thresholds for imported vinyl flooring. Domestic manufacturers with pre-certified formulations are capturing specification share in federally funded housing projects. The regulation most affects sheet vinyl producers serving nursing home chains, which are accelerating supplier audits to avoid procurement disqualification.
Facility managers are consolidating flooring maintenance contracts under single-source service agreements that bundle installation, periodic recoating, and end-of-life removal. Healthcare systems in Texas and Florida are piloting these arrangements for acute care campuses, replacing transactional material purchasing with lifecycle cost accountability. This shift is most visible in hospital networks where capital budget constraints favor operational expenditure smoothing.
Global Vinyl Floor Covering Market Segmentation
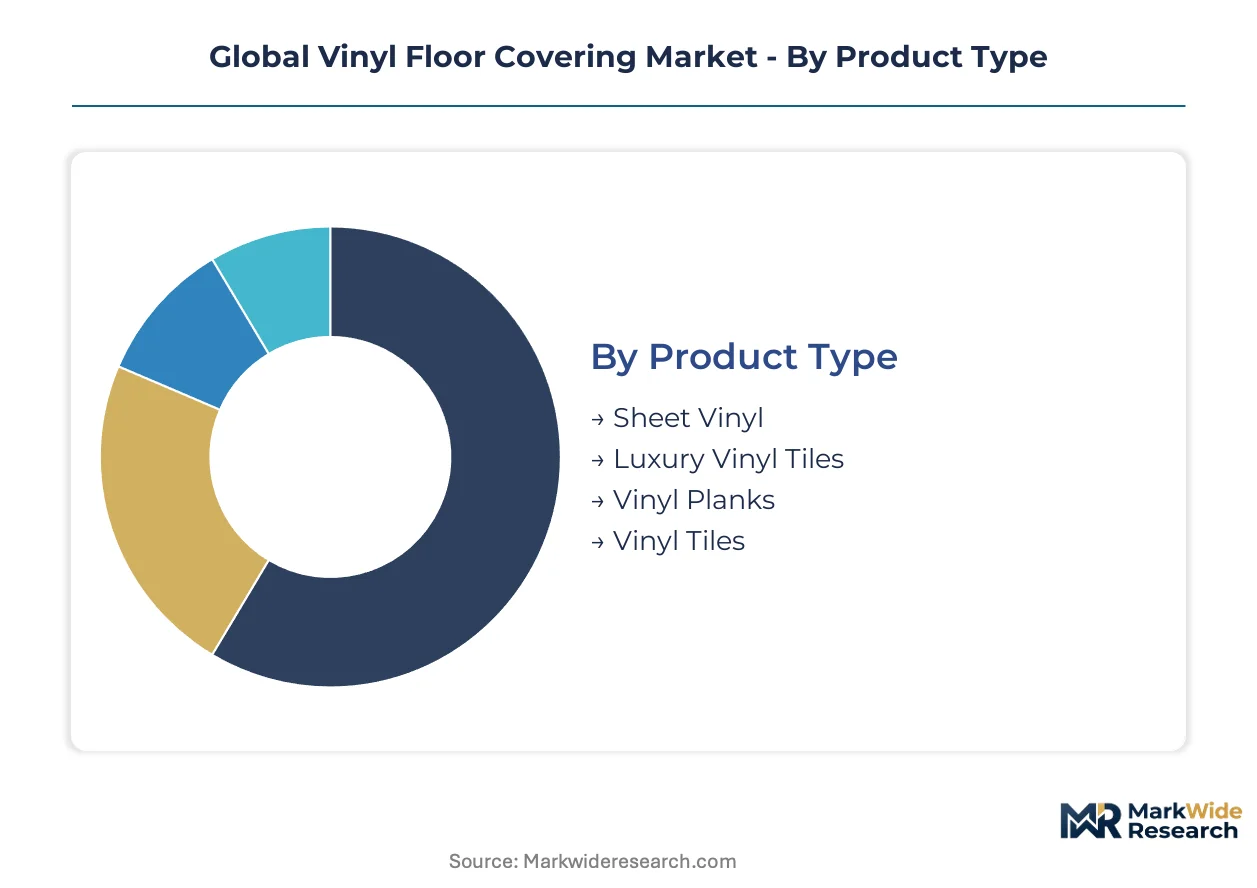
Product architecture and installation mechanics segment the vinyl floor covering market into distinct specification tiers. Upgrade cycles vary dramatically across residential renovation versus commercial refurbishment channels. Understanding these segment boundaries clarifies where margin pools concentrate and which technologies are displacing legacy formats.
Product Type:
Replacement cycles accelerate where visual authenticity commands premium positioning and wear-layer durability extends service intervals.
- Luxury Vinyl Tiles:Multi-layer construction fuses rigid core substrates with high-definition print films and polyurethane wear layers. Hospitality designers in Dubai and Singapore specify these for boutique hotel lobbies where stone replication must withstand rolling luggage traffic.
- Vinyl Planks:Extruded or calendered strips with click-lock edge profiles dominate residential renovation channels. German housing stock renewal programs are accelerating specification of 5G locking systems in owner-occupied apartments where DIY installation halves labor costs.
- Sheet Vinyl:Continuous rolls calendered to 6-12 foot widths deliver seamless hygiene surfaces. Healthcare operating theaters in Texas and Florida retain glue-down sheet specifications where joint-free protocols override aesthetic considerations.
- Vinyl Tiles:Standard 12x12 inch composition tiles serve economy-tier commercial refresh cycles. Facility managers in China's tier-two cities deploy these for office carpet replacement where budget constraints limit specification flexibility.
Volume placements concentrate in vinyl planks; the faster expansion belongs to luxury vinyl tiles.
Installation Method:
Cost tier stratification separates professional-contractor dependence from homeowner-accessible assembly systems.
- Click Lock:Mechanical edge profiles enable floating floor installation without adhesives or specialized tools. Residential renovation contractors in Germany and the United States are shifting specification toward these systems to compress project timelines and reduce skilled-labor dependency.
- Glue-Down:Full-spread or pressure-sensitive adhesive application delivers permanent dimensional stability. Institutional buildings in Florida and Texas specify glue-down sheet vinyl for acute care corridors where rolling medical equipment demands absolute surface integrity.
- Loose Lay:Friction-backed or weighted-edge planks rely on perimeter retention and gravity. Commercial real estate landlords in Singapore deploy these for tenant improvement allowances where frequent reconfiguration cycles demand reversible installation.
- Self-Adhesive:Pre-applied pressure-sensitive backing strips accelerate residential bathroom and kitchen refreshes. DIY retailers in Chengdu and Wuhan stock these for first-time homeowners executing moisture-resistant surface upgrades without contractor coordination.
Professional contractors favor glue-down permanence; click lock systems are climbing the fastest among renovation channels.
End User:
Application-specific performance requirements segment demand across durability, hygiene, and aesthetic priority hierarchies.
- Hospitality:Design-forward specifications prioritize photorealistic wood and stone replication with 20-mil commercial wear layers. Boutique hotel chains in Dubai specify luxury vinyl planks for guest room corridors where acoustic underlayment addresses sound transmission codes.
- Commercial Spaces:High-traffic retail and office fit-outs balance replacement cost against warranty duration. Shopping mall operators in Shanghai and Beijing are shortening refurbishment cycles to 5-7 years, accelerating specification of mid-tier luxury vinyl tile.
- Institutional Buildings:Healthcare and government facilities demand seamless sheet vinyl with heat-welded seams. Hospital networks in Texas pilot lifecycle service agreements that bundle installation, maintenance, and end-of-life removal under operational expenditure budgets.
- Educational Facilities:K-12 and university construction navigates California CDPH 01350 emission protocols. Public school bond-funded projects in the state elevate low-VOC vinyl flooring to sole-source eligibility, displacing conventional alternatives.
Institutional buildings anchor volume through healthcare specification lock-in; hospitality applications are expanding most quickly as design-forward LVT penetrates boutique segments.
Distribution Channel:
Customer type and project scale determine channel selection between specification influence and transaction efficiency.
- Specialty Retailers:Showroom-based consultation supports complex residential renovation decisions. Independent flooring dealers in Germany curate click-lock vinyl plank assortments where tactile sample evaluation drives premium tier selection.
- Wholesalers:Volume aggregation serves commercial contractor and multi-location facility manager procurement. Distributors in China's tier-one cities stock mid-market luxury vinyl tile for commercial real estate developers executing standardized fit-out packages.
- Direct Sales:Manufacturer-to-contractor relationships govern large-scale hospitality and institutional projects. Tarkett SA and Mohawk Industries deploy specification teams to architect and facility manager decision cycles for hospital and school environments.
- Online Retailers:Digital catalog browsing with sample-to-home programs penetrates DIY residential segments. E-commerce platforms in the United States capture economy-tier vinyl plank volume where installation simplicity reduces pre-purchase consultation needs.
Specialty retailers dominate premium residential specification; online channels are gaining share fastest in economy-tier renovation projects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of PVC resin feedstock while the United States and Germany drive specification innovation for high-performance wear-layer formulations. This production-consumption divide shapes regional competitive advantages across the value chain.
United States
Residential renovation contractors in Texas and Florida specify click-lock vinyl planks for moisture-resistant basement and kitchen installations. The EPA regulates phthalate content through TSCA Section 6 restrictions, pushing domestic manufacturers toward pre-certified formulations for federally funded housing projects. Calendering and extrusion facilities cluster in the Southeast, where Shaw Industries Group operates multiple manufacturing sites to serve regional distribution networks.
Germany
Owner-occupied housing stock renewal programs accelerate specification of 5G locking systems in apartments where DIY installation halves labor costs. REACH Annex XVII restrictions on plasticizer chemistries compress reformulation timelines, creating first-mover advantage for manufacturers with compliant hospital and school certifications. Specialty flooring dealers in North Rhine-Westphalia curate premium click-lock assortments where tactile sample evaluation drives selection.
China
Commercial real estate refurbishment cycles in Shanghai and Beijing shorten to five-to-seven years, accelerating mid-market luxury vinyl tile specification. GB standards govern formaldehyde and VOC thresholds in domestically sold building materials. Organotin and calcium-zinc heat stabilizer production concentrates in specialty chemical clusters, creating supply vulnerability for European calendering operations dependent on Chinese imports.
United Arab Emirates
Hospitality designers in Dubai specify luxury vinyl planks with acoustic underlayment for boutique hotel corridors addressing sound transmission codes. MOHAP oversees building material safety standards for commercial construction. Real-time render engines for digital twin visualization see adoption among specification teams validating LVT patterns against lighting conditions before order commitment.
Singapore
Commercial landlords deploy loose-lay friction-backed planks for tenant improvement allowances where frequent reconfiguration demands reversible installation. The Building and Construction Authority enforces green building standards that elevate low-emission flooring in public procurement. Facility managers pilot single-source service agreements bundling installation, maintenance, and end-of-life removal under operational expenditure budgets.
Global Vinyl Floor Covering Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct specification tiers. The vendor base organizes around three strategic archetypes: integrated resin-to-flooring manufacturers controlling raw material variability, specification-driven European players anchoring institutional channels through certification programs, and scale-oriented North American producers leveraging domestic manufacturing footprints. Dominant competitive moves include captive resin compounding investments and low-VOC certification acquisition for public sector eligibility.
Among North American diversified manufacturers, Mohawk Industries exemplifies vertical integration through captive resin compounding operations. Tarkett SA represents the European specification-focused archetype with positioning anchored in institutional channel penetration. Shaw Industries Group occupies the scale-driven tier with multi-facility domestic manufacturing coverage. These three entities collectively illustrate the strategic segmentation between raw material control, certification-driven specification, and manufacturing scale across the competitive landscape.
| Leading Market Players |
|---|
| Mohawk Industries |
| Tarkett SA |
| Shaw Industries Group |
| Gerflor Group |
| Mannington Mills |
| Armstrong Flooring |
| Forbo Flooring Systems |
| Polyflor Ltd |
| LG Hausys |
| Others |
Supply & Pricing Matrix
Calendering and extrusion operator density in China's Jiangsu and Zhejiang provinces feeds labor-cost differentials that widen pricing-tier spreads between premium European formulations and economy Asian exports. REACH compliance investments in German and French compounding facilities compress margins at the mid-tier, forcing specification-grade producers to recover certification costs through hospital and school channel premiums while budget residential lines absorb volatile PVC resin spot pricing.
Pricing Analysis
Cost-down pressure on standard-grade vinyl planks accelerates because ethylene and propylene feedstock volatility exposes compounders to margin compression without contract hedging. Three-tier pricing structure across premium, standard, and economy levels separates 28-mil commercial wear-layer specifications from 6-mil residential economy lines, with certification grade under CDPH 01350 and REACH Annex XVII serving as the primary price differentiation drivers. Pricing pressure stems from concentrated stabilizer supply in Chinese specialty chemical clusters. DIY residential renovators exhibit highest price sensitivity, while healthcare facility managers prioritize lifecycle cost over unit pricing.
Supply Chain Analysis
Freight cost inflation on Asia-Europe container routes compounds landed cost volatility for European calendering operations dependent on Chinese organotin and calcium-zinc stabilizer imports. PVC resin production concentrates in China, the United States, and Germany, while wear-layer polyurethane and digital print film supply clusters in South Korea and Japan. Raw material dependencies span petrochemical feedstocks, specialty plasticizers, and ceramic bead surface treatments. Single-source vulnerability in Chinese heat stabilizer production threatens European manufacturing continuity. Distribution runs through specialty flooring dealers for premium residential specification and wholesale distributors for commercial volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive resin compounding and in-house print film production determine margin capture against commodity resin spot exposure.
For Market Incumbents: Lock in specification lock-in for hospital and school channels through accelerated REACH-compliant plasticizer certification ahead of restriction phase deadlines. Deepen backward integration into wear-layer polyurethane formulation to offset South Korean and Japanese supplier pricing power. Defend against emerging Chinese mid-tier LVT exporters by anchoring European institutional relationships through low-VOC certification programs.
For New Entrants and Emerging Players: The premium-to-economy price gap in China's tier-two cities offers white-space entry for mid-market luxury vinyl tile distribution with localized digital print pattern libraries. Target Chengdu and Wuhan commercial real estate developers with accelerated refurbishment cycles. Pursue direct contractor relationships bypassing established wholesale layers through project-specific specification teams.
For Investors and Strategic Acquirers: Re-rating potential sits with captive resin compounders given REACH-driven reformulation timelines that strand non-compliant inventory. Long-term viability favors manufacturers with demonstrated hospital and school certification traction over pure-play extrusion operators. Monitor EPA TSCA Section 6 enforcement thresholds as signal for domestic manufacturing preference inflection in federally funded housing procurement.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Resin Compounding Investment | Mohawk Industries controls raw material variability across vinyl plank lines through in-house PVC formulation. |
| Low-VOC Certification Acquisition | Tarkett SA anchors European hospital specifications through CDPH 01350 and REACH-compliant product portfolios. |
| Digital Print Film Backward Integration | High-definition rotogravure capability reduces dependency on Korean and Japanese print layer suppliers. |
| Click-Lock Installation Platform Expansion | 5G locking system adoption in German housing renewal compresses project timelines and labor costs. |
| Tier-Two Chinese Distribution Buildout | Chengdu and Wuhan commercial real estate development outpaces saturation in Shanghai and Beijing. |
Research Methodology
Trade databases, customs records, and SEC 10-K filings formed the secondary backbone, cross-referenced with primary interviews spanning plant managers at calendering facilities, procurement leads at hospital networks, distribution channel partners in Germany and China, and technical R&D directors for wear-layer formulation. Bottom-up volume triangulation against top-down value estimates validated segment splits across product architecture, installation method, and end-use application.
Historical trendline analysis of replacement cycles and refurbishment frequencies anchored the projection framework across the analysis window. Segmentation dimensions modeled include product type, installation mechanics, end-use vertical, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to base-year market sizing, with inputs from petrochemical feedstock pricing indices and commercial real estate development permits in tier-one and tier-two Chinese cities.
Underlying measurement precision varies by segment; luxury vinyl tile and hospitality application data carry tighter precision than economy vinyl tile and standard commercial office refresh cycles. Forecasts reflect assumptions regarding REACH enforcement timelines, EPA TSCA Section 6 implementation, and Chinese GB standard evolution. Stakeholders should weight assumptions against their own operating context and regulatory intelligence functions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
United States Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Resilient Flooring Market
Flooring, Carpets, and Rugs
Rigid Core Flooring Market
Flooring, Carpets, and Rugs
Global Soft Covering Flooring Market
Flooring, Carpets, and Rugs
Terrazzo Flooring Market
Flooring, Carpets, and Rugs
Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Global Carpet Tile Market
Flooring, Carpets, and Rugs
Lightweight Acoustic Floor Systems Market
Flooring, Carpets, and Rugs
Quarter Sawn Flooring Market
Flooring, Carpets, and Rugs
Resilient Floor Covering Market
Flooring, Carpets, and Rugs
US Flooring Market
Flooring, Carpets, and Rugs
Bath Mats Market
Flooring, Carpets, and Rugs
Europe Carpet and Rugs Market
Flooring, Carpets, and Rugs
China Wood Flooring Market
Flooring, Carpets, and Rugs
Germany Floor Covering Market
Flooring, Carpets, and Rugs
United Kingdom Non-Resilient Floor Covering Market