
 North America Traditional Toilet Seat Market | 2026-2036
North America Traditional Toilet Seat Market Size, Share, and Industry Trends Forecast 2026-2036
North America Traditional Toilet Seat Market Analytics
EPA WaterSense certification is hardening as a baseline requirement for traditional toilet seat procurement across residential and commercial channels. Kohler Co. leverages its captive ceramics foundry network to control material costs and specification compliance. Bemis Manufacturing Company anchors the mid-market through dominant presence in home improvement retail channels. TOTO USA differentiates via Japanese-engineered hinge systems that reduce long-term wear.
A traditional toilet seat is a hinged fixture designed to cover the bowl of a water-flush toilet, typically molded from polypropylene, duroplast, or wood-composite substrates with stainless-steel or zinc-alloy hinge hardware, and engineered to withstand cyclic loading exceeding thousands of open-close operations while maintaining sanitary surface integrity. The elongated product type dominates unit volume in North America due to building code alignment with ADA-compliant bowl dimensions. Plastic material formulations sustain the largest share of production owing to moldability, color consistency, and chemical resistance, though plywood variants retain niche demand in heritage restoration and premium residential segments.
The EPA regulates water-efficiency labeling through WaterSense, while the Consumer Product Safety Commission oversees mechanical safety standards for hinge and slam-prevention mechanisms, and state-level plumbing codes in California and Texas impose additional material and installation specifications that manufacturers must navigate for market access. Stakeholders should monitor pending revisions to federal water-efficiency thresholds and state-level low-flow mandates that could accelerate material substitution or trigger replacement cycles ahead of typical product lifespans.
Market Dynamics
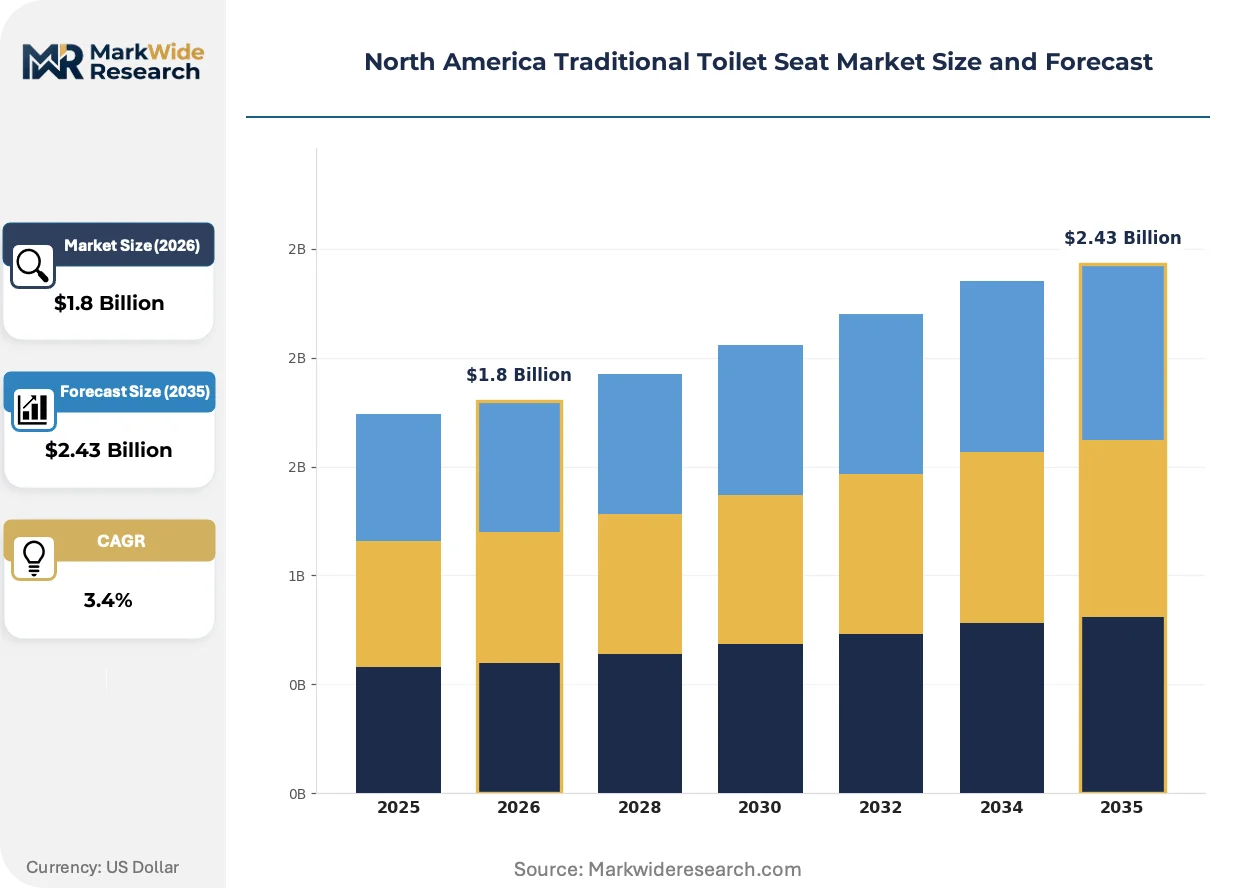
EPA WaterSense certification tightening is compressing product lifecycles across the North America Traditional Toilet Seat Market, forcing manufacturers to accelerate material substitution ahead of typical replacement schedules.
Growth Catalysts
- Residential renovation spending:Aging housing stock across the southeastern United States is lifting replacement demand as homeowners modernize bathrooms ahead of resale.
- WaterSense compliance:EPA labeling requirements are hardening as a baseline procurement threshold across both residential and commercial distribution channels.
- ADA-aligned bowl dimensions:Building code convergence around elongated seat specifications is standardizing product portfolios and reducing SKU complexity.
Market Restraints
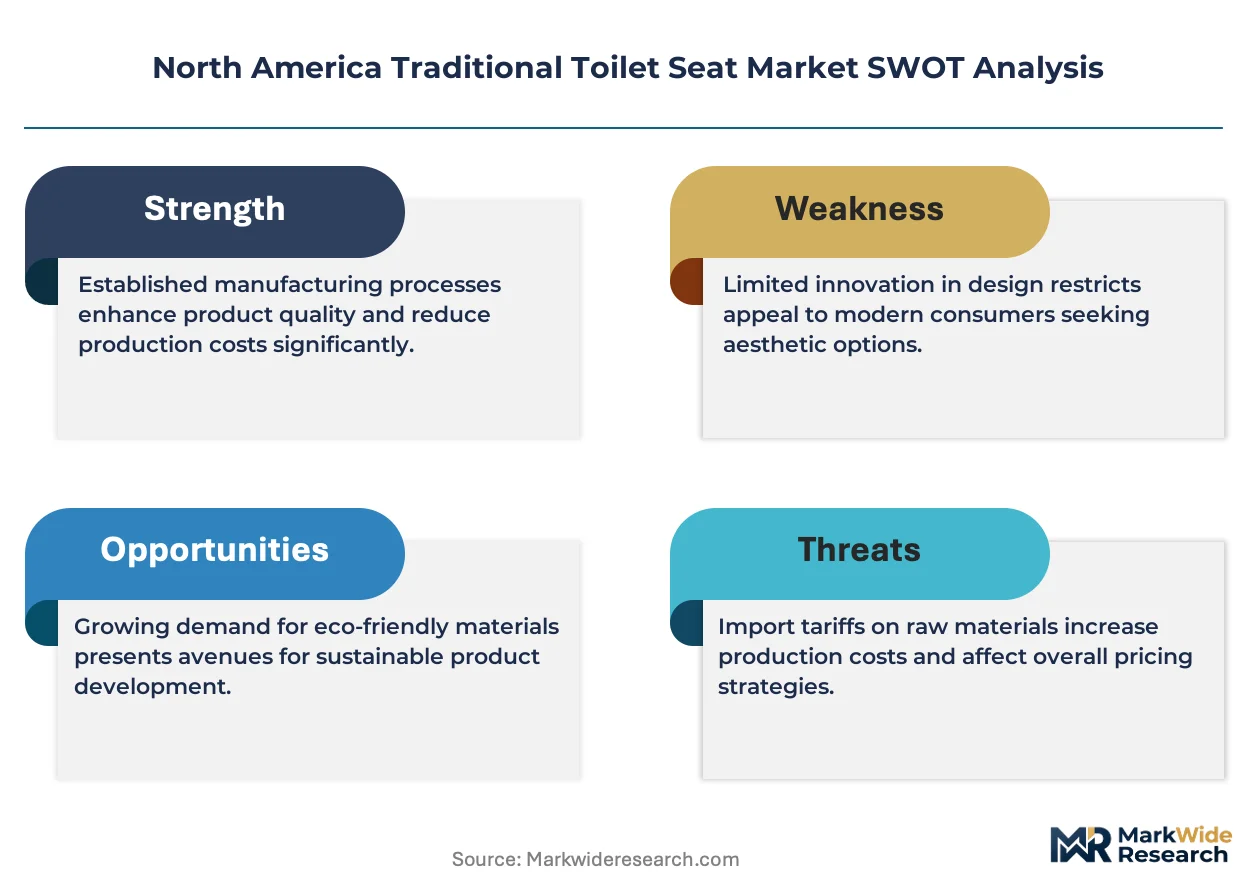
- Polypropylene resin volatility:Petrochemical feedstock fluctuations compress margin stability for plastic-formulation producers.
- Southeastern production concentration:Molded seat manufacturing clusters heavily in Georgia and Alabama, creating weather and logistics exposure.
- California Title 24 friction:State-level plumbing codes impose material and installation specifications that complicate national product line rationalization.
Strategic Opportunities
- Canadian market underpenetration:Ontario and British Columbia housing starts lag US per-capita seat replacement rates, offering volume expansion potential.
- Heritage restoration niche:Plywood-composite variants retain premium pricing power in historic district renovations across New England.
- Home improvement retail channel innovation:Big-box private-label partnerships enable direct-to-installer bypass of traditional distributor markups.
Industry Challenges
- WaterSense certification timeline compression:EPA review backlogs delay product launch windows by multiple quarters.
- Legacy inventory reconciliation:Pre-2023 stockpiles of non-compliant hinge hardware require write-downs or regional diversion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Traditional Toilet Seat Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.43 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Round, Elongated, Bidet, Smart Material: Plywood, Plastic, Ceramic, Metal Installation Type: Standard, Wall-Mounted, Floor-Mounted, Adjustable Distribution Channel: Online Retail, Home Improvement Stores, Wholesalers, Supermarkets |
| Companies Covered | LIXIL Corporation, Kohler Co., TOTO USA, American Standard, Delta Faucet Company, Bemis Manufacturing Company, Centoco, Ginsey Home Solutions, Ferguson (PROFLO), Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Traditional Toilet Seat Market Evolving Landscape
Material science advances and regulatory stringency are converging to reshape competitive positioning across the North America Traditional Toilet Seat Market, with durability and compliance emerging as dual purchase criteria.
Duroplast thermoset formulations are decentralizing production economics by enabling thinner-wall molding with equivalent structural performance. Mid-market manufacturers in Tennessee and North Carolina are adopting these compounds to reduce resin consumption per unit. The shift is compressing cost differentials between premium and standard product tiers while maintaining WaterSense-compliant surface integrity.
Texas and California state plumbing codes are tightening material specifications for bathroom fixtures, with Texas adopting amended installation standards and California advancing low-flow mandate thresholds. Commercial builders in Dallas-Fort Worth and Los Angeles metro areas are pre-emptively specifying compliant seats to avoid retrofit liability. The regulatory divergence is forcing national suppliers to maintain parallel product lines.
Buyer concentration among large home improvement retailers is consolidating specification authority away from individual contractors. Regional distributors in the Midwest are losing shelf space to direct vendor-retailer arrangements. The channel shift is most visible in Florida and Arizona, where new construction volume concentrates purchasing power among three national retail chains.
North America Traditional Toilet Seat Market Segmentation
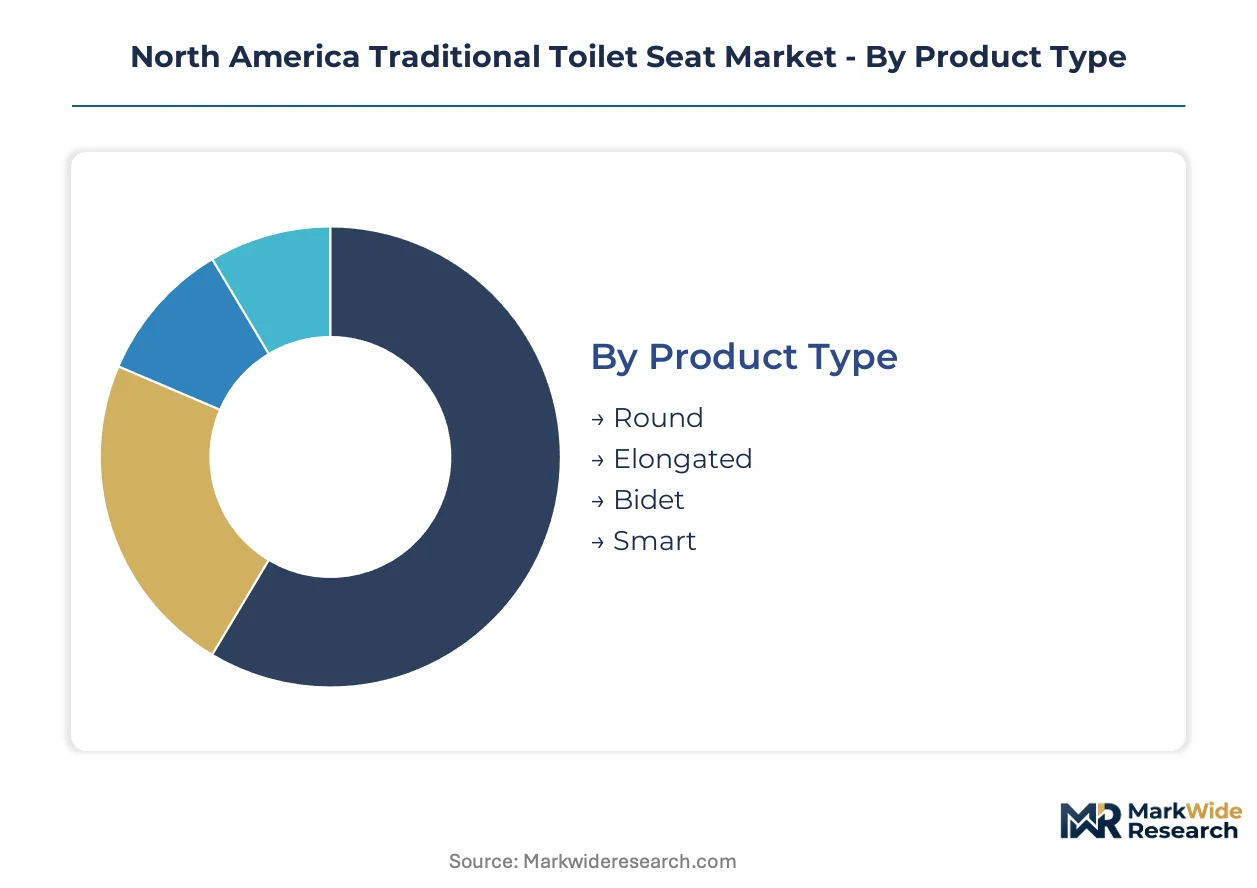
Segmentation in the North America Traditional Toilet Seat Market reveals how product specifications, material choices, and channel configurations align with distinct buyer workflows. Procurement patterns differ sharply between new construction, renovation, and replacement cycles.
Product Type:
Round toilet seats serve standalone replacement demand in older housing stock, while elongated variants embed into ADA-compliant new construction specifications.
- Round:Compact 16.5-inch bowl coverage suits pre-1980s residential bathrooms across the northeastern United States. Demand concentrates in Massachusetts and Pennsylvania heritage districts where homeowners prioritize period-appropriate restoration over code compliance.
- Elongated:18.5-inch front-to-rear dimension aligns with ADA accessibility standards and dominates southeastern new housing starts. Georgia and Florida builders specify these as default for compliance risk mitigation.
- Bidet:Integrated spray functionality commands premium positioning in California wellness-focused renovations.
- Smart:Sensor-activated heating and night-light features penetrate high-end Texas custom home segments.
Volume placements concentrate in Elongated; the faster expansion belongs to Smart.
Material:
Cost tier stratification separates commodity resin formulations from heritage-grade substrates, with durability and surface finish driving specification authority.
- Plywood:Multi-layer birch or oak veneer construction retains niche demand in New England historic district renovations where authenticity requirements override moisture-resistance concerns.
- Plastic:Polypropylene and duroplast thermoset formulations sustain the largest production share due to moldability and EPA WaterSense surface-integrity compliance. Tennessee and North Carolina manufacturers favor duroplast for thinner-wall molding economics.
- Ceramic:Vitreous china construction pairs with high-end integrated toilet systems in luxury California residential towers.
- Metal:Stainless-steel substrates serve institutional and correctional facility specifications across the southwestern United States.
Plastic captures the dominant placement volume; plywood maintains the steepest premium pricing power.
Installation Type:
Application context determines mounting configuration, with residential replacement favoring drop-in simplicity and commercial new construction demanding integrated structural solutions.
- Standard:Two-bolt hinge attachment dominates residential replacement cycles across the Midwest. Big-box retail channels stock these as default for homeowner self-installation.
- Wall-Mounted:Concealed carrier systems penetrate urban multifamily construction in Toronto and Vancouver where floor-space optimization drives specification.
- Floor-Mounted:Integrated bowl-and-seat units align with production homebuilder volume procurement in Arizona and Nevada.
- Adjustable:Sliding hinge mechanisms accommodate non-standard bowl dimensions in pre-1960s housing stock across Chicago and Detroit.
Standard configurations dominate replacement frequency; wall-mounted specifications are climbing fastest in Canadian urban cores.
Distribution Channel:
Customer type and purchase urgency shape channel selection, with contractor-driven volume consolidating around direct retail relationships.
- Online Retail:Direct-to-consumer platforms capture specification-shopping behavior in remote Canadian markets where physical retail density lags. Alberta and Saskatchewan homeowners favor this channel for replacement urgency.
- Home Improvement Stores:Lowe's and Home Depot anchor mid-market volume through contractor loyalty programs and same-day pickup. Florida and Arizona construction corridors concentrate purchasing power here.
- Wholesalers:Regional distributors serve commercial plumbing contractors in Texas and California with bulk pricing and specification support.
- Supermarkets:Mass-merchandise retail captures emergency replacement demand in rural southeastern markets.
Home improvement stores command the heaviest volume throughput; online retail is gaining share fastest in underpenetrated Canadian provinces.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seat manufacturing concentrates in the southeastern United States while Canadian demand runs ahead of local production capacity. Mexico's maquiladora corridor absorbs overflow fabrication for US-bound inventory.
United States
Housing starts across Georgia and Florida drive elongated seat specifications into new construction workflows. EPA WaterSense certification deadlines compress product launch timelines for manufacturers serving federal procurement channels. Molded seat production clusters in Alabama and Georgia where resin suppliers and logistics infrastructure overlap.
Canada
Ontario and British Columbia housing permits lag US per-capita replacement rates, creating volume expansion headroom for suppliers. Health Canada and PMRA oversee material safety standards for bathroom fixtures imported or manufactured domestically. Toronto and Vancouver urban multifamily construction favors wall-mounted configurations to optimize floor plates.
Mexico
Maquiladora operations in Nuevo León and Tamaulipas handle overflow molding capacity for US retailers seeking tariff-advantaged production. Mexican federal standards coordinate with US plumbing code requirements for cross-border product lines. Monterrey anchors the northern manufacturing belt with resin supply chain proximity to Texas petrochemical feedstocks.
North America Traditional Toilet Seat Market Competitive Landscape
The competitive structure tilts toward integrated fixture manufacturers with captive ceramics and metalworking capabilities. Mid-market specialists compete through home improvement retail channel dominance rather than manufacturing scale. Two archetypes define the field: vertically integrated bathroom fixture conglomerates and focused seat-and-hinge component specialists. Consolidation pressure manifests through distributor acquisition and direct retail partnership expansion.
Among integrated fixture manufacturers, Kohler Co. and LIXIL Corporation exemplify the conglomerate archetype with multi-product bathroom portfolios. Bemis Manufacturing Company occupies a distinct position as a seat-focused specialist with channel depth in retail distribution. These three anchors demonstrate how scale and specialization split competitive advantage across procurement workflows.
| Leading Market Players |
|---|
| LIXIL Corporation |
| Kohler Co. |
| TOTO USA |
| American Standard |
| Delta Faucet Company |
| Bemis Manufacturing Company |
| Centoco |
| Ginsey Home Solutions |
| Ferguson (PROFLO) |
| Others |
Value Network & Pricing Analysis
Home improvement retail buyer concentration in Florida and Arizona corridors anchors a contract-based long-term offtake pricing model where volume scale determines tier placement. Big-box procurement teams leverage consolidated purchasing power to compress supplier margins while demanding EPA WaterSense certification compliance as a non-negotiable baseline.
Pricing Analysis
Margin tightening in the plastic-formulation tier reflects polypropylene resin volatility tied to Texas petrochemical feedstock fluctuations. Three-tier pricing structure across premium, standard, and economy levels separates duroplast hinge systems from commodity polypropylene and heritage plywood variants. Certification grade and volume scale drive price differentiation, with WaterSense-labeled products commanding placement premiums. Commercial builders in Dallas-Fort Worth demonstrate lowest price sensitivity due to retrofit liability avoidance, while rural southeastern supermarket channels face acute cost-down pressure from emergency replacement shoppers.
Supply Chain Analysis
Direct-to-retailer channels handle consolidated home improvement store demand, bypassing traditional Midwest distributor markups. Manufacturing concentrates in Georgia, Alabama, and Tennessee where resin suppliers and logistics infrastructure overlap. Raw material dependencies draw from Texas petrochemical feedstocks, zinc-alloy hinge hardware from domestic metalworking clusters, and birch veneer for heritage restoration niches. Tariff exposure on Mexican maquiladora overflow capacity in Nuevo León and Tamaulipas presents structural risk amid cross-border regulatory divergence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Traditional Toilet Seat Market sits in a materials-transition phase as duroplast thermoset formulations displace legacy polypropylene across mid-market portfolios. Manufacturers adopting thinner-wall molding economics gain cost parity with premium tiers while maintaining WaterSense surface-integrity compliance.
For Market Incumbents: To counter polypropylene resin volatility, Bemis Manufacturing Company and Kohler Co. should deepen backward integration into captive ceramics foundry networks and secure long-term resin offtake agreements with Texas petrochemical suppliers. Channel control through direct retail partnerships in Florida and Arizona construction corridors provides defensive positioning against distributor disintermediation. For New Entrants and Emerging Players: Enter via underpenetrated Canadian provinces where Ontario and British Columbia housing starts lag US per-capita replacement rates. Bidet-integrated and smart-seat segments in California wellness renovations offer the most penetrable white-space, with go-to-market execution through direct-to-consumer platforms capturing specification-shopping behavior in Alberta and Saskatchewan remote markets. For Investors and Strategic Acquirers: The window for entry favors mid-market specialists with home improvement retail channel depth and WaterSense certification infrastructure already in place. Long-term viability hinges on material science capabilities enabling regulatory compliance ahead of EPA threshold revisions. Watch for EPA review backlog resolution as the inflection signal accelerating product launch windows.| Strategic Initiative | Industry Significance |
|---|---|
| WaterSense Certification Investment | EPA labeling requirements harden as baseline procurement threshold across residential and commercial channels. |
| Duroplast Material Transition | Tennessee and North Carolina manufacturers reduce resin consumption per unit while maintaining structural performance. |
| Direct Retail Partnership Expansion | Big-box private-label arrangements bypass traditional distributor markups in Florida and Arizona corridors. |
| Canadian Market Penetration | Ontario and British Columbia housing permits create volume expansion headroom for compliant suppliers. |
| Heritage Restoration Niche Cultivation | Plywood-composite variants retain premium pricing power in New England historic district renovations. |
Research Methodology
Multi-period observation of housing starts, renovation spending patterns, and EPA regulatory filing timelines anchored the trend analysis, supplemented by interviews with home improvement retail category managers, commercial plumbing contractors, residential renovation specialists, and bathroom fixture procurement officers at production homebuilders. Secondary validation drew from EPA WaterSense certification databases, state plumbing code revisions in California and Texas, customs trade data on Mexican maquiladora shipments, and SEC filings of integrated fixture manufacturers. Bottom-up unit volume estimates triangulated against top-down construction spending models.
Segment-weighting applied product type, material formulation, installation configuration, and distribution channel dimensions across the projection horizon. CAGRs derived from regression analysis linking replacement cycle frequency to housing stock age demographics and regulatory compliance deadlines. Industry-specific forecast inputs incorporated polypropylene resin price indices and WaterSense certification approval timelines.
Revisions become necessary when EPA water-efficiency threshold adjustments, state-level low-flow mandate accelerations, or petrochemical feedstock disruptions materialize outside modeled ranges. Forecasts reflect documented assumptions regarding housing start trajectories and regulatory implementation schedules. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bathroom Fixtures and Accessories
Australia Bathroom Products Market
Bathroom Fixtures and Accessories
Bathroom Furniture Market
Bathroom Fixtures and Accessories
Europe Bath and Shower Products Market
Bathroom Fixtures and Accessories
India Steam Rooms Market
Bathroom Fixtures and Accessories
United States Bath Fitting Market
Bathroom Fixtures and Accessories
Luxury Plumbing Fixtures Market
Bathroom Fixtures and Accessories
Bathroom Pods Market
Bathroom Fixtures and Accessories
Europe Steam Room Market
Bathroom Fixtures and Accessories
Washbasin Market
Bathroom Fixtures and Accessories
US Faucet Market
Bathroom Fixtures and Accessories
Bathroom Worktops Market
Bathroom Fixtures and Accessories
Global Shower Enclosure and Cubicles Market
Bathroom Fixtures and Accessories
Shower Curtain Market
Bathroom Fixtures and Accessories
North America Toilet Seat Market
Bathroom Fixtures and Accessories
Automatic Toilet Seat Market
Bathroom Fixtures and Accessories
India Shower Cubicle Market