
 Laminate Flooring Market | 2026-2036
Laminate Flooring Market Size, Share, and Industry Trends Forecast 2026-2036
Laminate Flooring Market Intelligence
Digital printing technology is rewriting how decorative layers replicate natural wood and stone aesthetics with photorealistic fidelity. Mohawk Industries leverages captive inkjet manufacturing to control design-to-delivery timelines across North American retail networks. Kronospan anchors European supply through integrated resin and board production in Austria and Germany. Egger differentiates via synchronized pore surface textures that command specification in premium residential projects.
Laminate flooring consists of a high-density fiberboard core bonded with a decorative melamine-impregnated paper layer and aluminum oxide wear coating, engineered for dimensional stability under residential and commercial foot traffic. The 12 mm thickness category dominates renovation replacement cycles where acoustic underlay integration and subfloor tolerance matter most. Waterproof laminate captures the fastest structural growth as rigid core polymer formulations displace traditional vinyl in moisture-prone commercial applications. Wholesale distributors occupy the margin-heavy channel position by bundling installation accessories and volume-tiered project pricing.
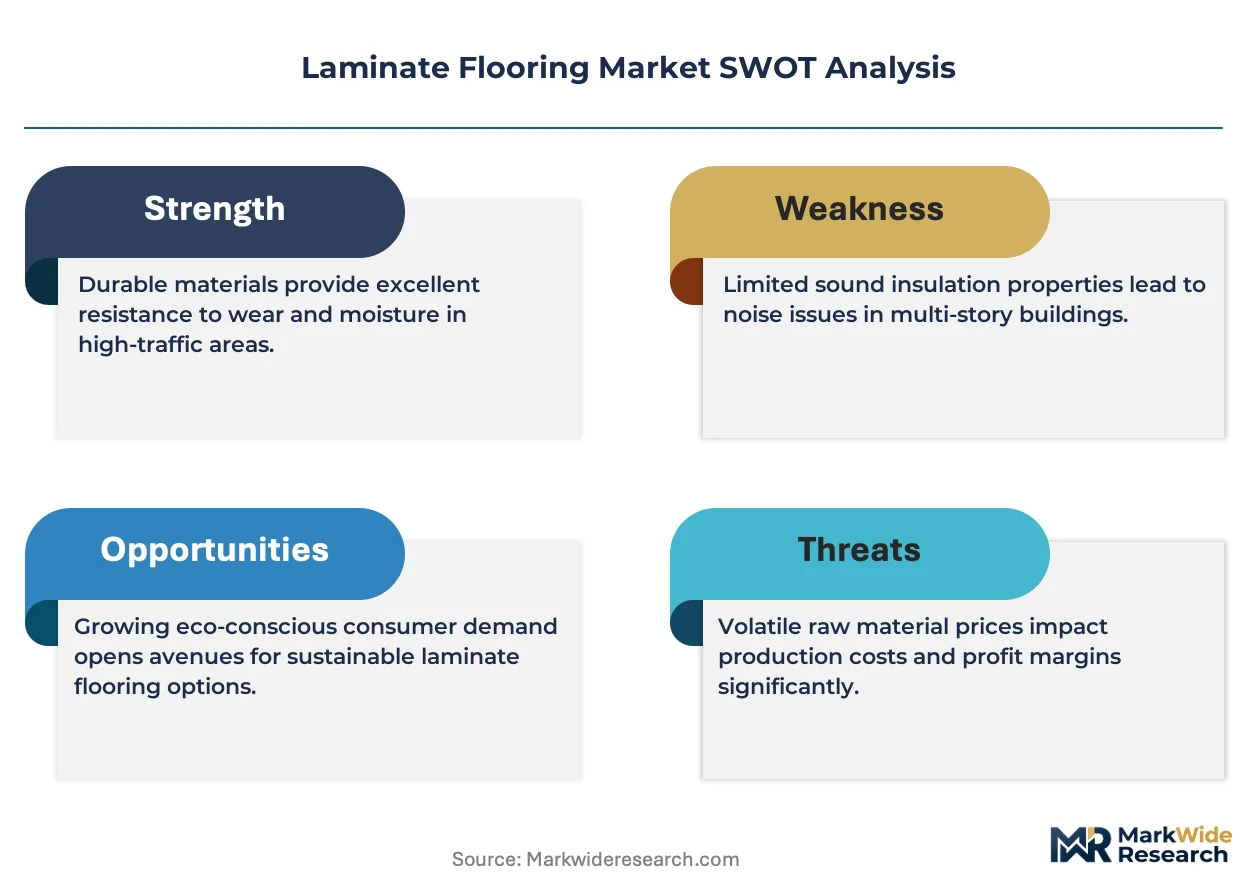
EPA TSCA Title VI formaldehyde emissions standards govern composite wood products sold in the United States, compelling core board suppliers to maintain third-party certification. The EU ECHA REACH framework restricts specific isocyanates in adhesive binders, while CE marking under the Construction Products Regulation mandates declared performance characteristics for flooring placed on the European market. Stakeholders must monitor how California Air Resources Board amendments and evolving German DIBt building material approvals interact to determine which product platforms can serve both markets without formulation divergence.
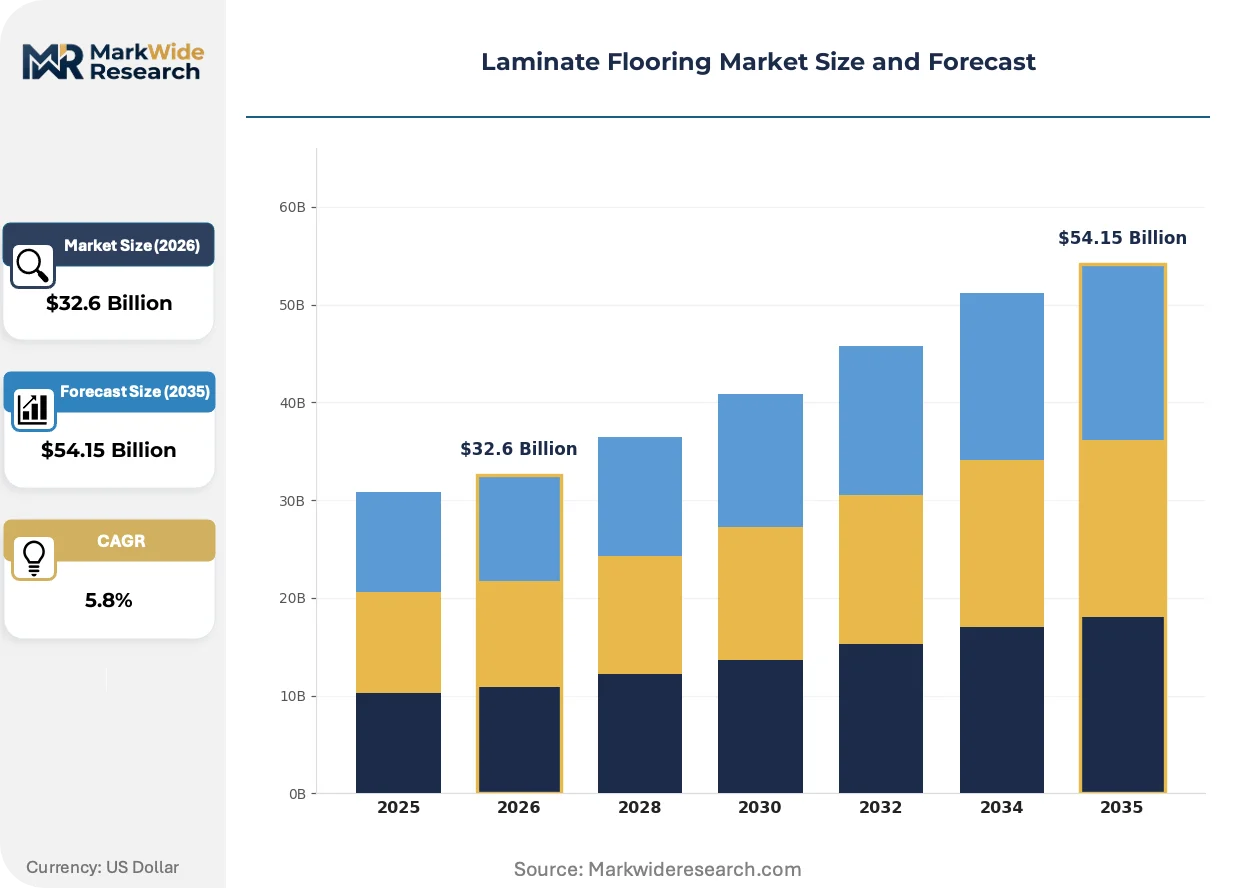
Market Dynamics
Waterproof rigid core polymer formulations are compressing replacement cycles in moisture-prone commercial segments while EPA TSCA Title VI compliance costs reshape supplier economics across North American distribution networks.
Growth Catalysts
- EU Green Deal renovation mandates:Germany's federal subsidy programs for energy-efficient housing retrofits are accelerating specification of certified low-emission laminate in residential replacement projects.
- Digital printing fidelity gains:Inkjet decorative layer technology enables photorealistic wood and stone replication that commands premium positioning in residential renovation channels.
- Suburban North America:Residential renovation activity concentrates demand for waterproof laminate variants in single-family housing stock across exurban development corridors.
Market Restraints
- Resin input cost volatility:Melamine-formaldehyde resin prices fluctuate with natural gas feedstock exposure, compressing margin stability for high-density fiberboard core producers.
- European supply concentration:Integrated resin and board production clusters in Austria and Germany create geographic vulnerability to regional energy price shocks.
- Luxury vinyl tile substitution:Rigid core SPC and WPC products capture specification in commercial moisture applications where traditional laminate faced technical barriers.
Strategic Opportunities
- Acoustic underlay bundling:12 mm thickness category products with integrated sound-dampening layers penetrate multi-family housing retrofits where footfall noise regulations tighten.
- CE marking performance declarations:Construction Products Regulation compliance enables cross-border specification in EU member state public procurement frameworks.
- Wholesale distributor channel expansion:Volume-tiered project pricing bundled with installation accessories captures margin-heavy positions in renovation contractor networks.
Industry Challenges
- Dual-market formulation divergence:California Air Resources Board amendments and German DIBt building material approvals require separate product platforms, fragmenting production scale economies.
- REACH isocyanate restrictions:ECHA adhesive binder compliance timelines extend product certification cycles for European market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laminate Flooring Market |
| Market Size in 2026 | $32.6 Billion |
| Market Size in 2035 | $54.15 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Laminate, Waterproof Laminate, High Gloss Laminate, Textured Laminate End User: Residential, Commercial, Industrial, Institutional Thickness: 7 mm, 8 mm, 10 mm, 12 mm Distribution Channel: Online Stores, Wholesale Distributors, Retail Outlets, Direct Sales |
| Companies Covered | Mohawk Industries, Shaw Industries Group, Tarkett, Mannington Mills, Armstrong Flooring, Beaulieu International Group, Kronospan, Egger, Forbo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laminate Flooring Market Strategic Shifts & Innovations
Surface texture synchronization and rigid core chemistry advances are redefining performance benchmarks while regulatory emissions frameworks accelerate material substitution across supply chains.
Inkjet decorative layer printing is digitizing how laminate manufacturers replicate natural material aesthetics with sub-millimeter registration accuracy. Residential renovation contractors specify these products for premium single-family projects where visual authenticity drives homeowner willingness to pay. The technology is digitizing design-to-delivery timelines by eliminating engraved cylinder lead times and enabling rapid pattern turnover.
EPA TSCA Title VI formaldehyde emissions standards compel third-party certification for composite wood products sold in the United States. Core board suppliers must maintain chain-of-custody documentation and laboratory testing protocols to access retail distribution networks. Residential replacement channels face the strictest documentation requirements, with big-box retailers demanding certified supplier lists before product placement.
Renovation contractors increasingly specify complete flooring systems rather than materials-only procurement. Wholesale distributors respond by bundling underlayment, trim, and installation consumables into single-source project quotes. This pattern concentrates most visibly in German housing retrofit sectors where energy-efficiency certification requirements demand integrated system performance documentation.
Laminate Flooring Market Segmentation
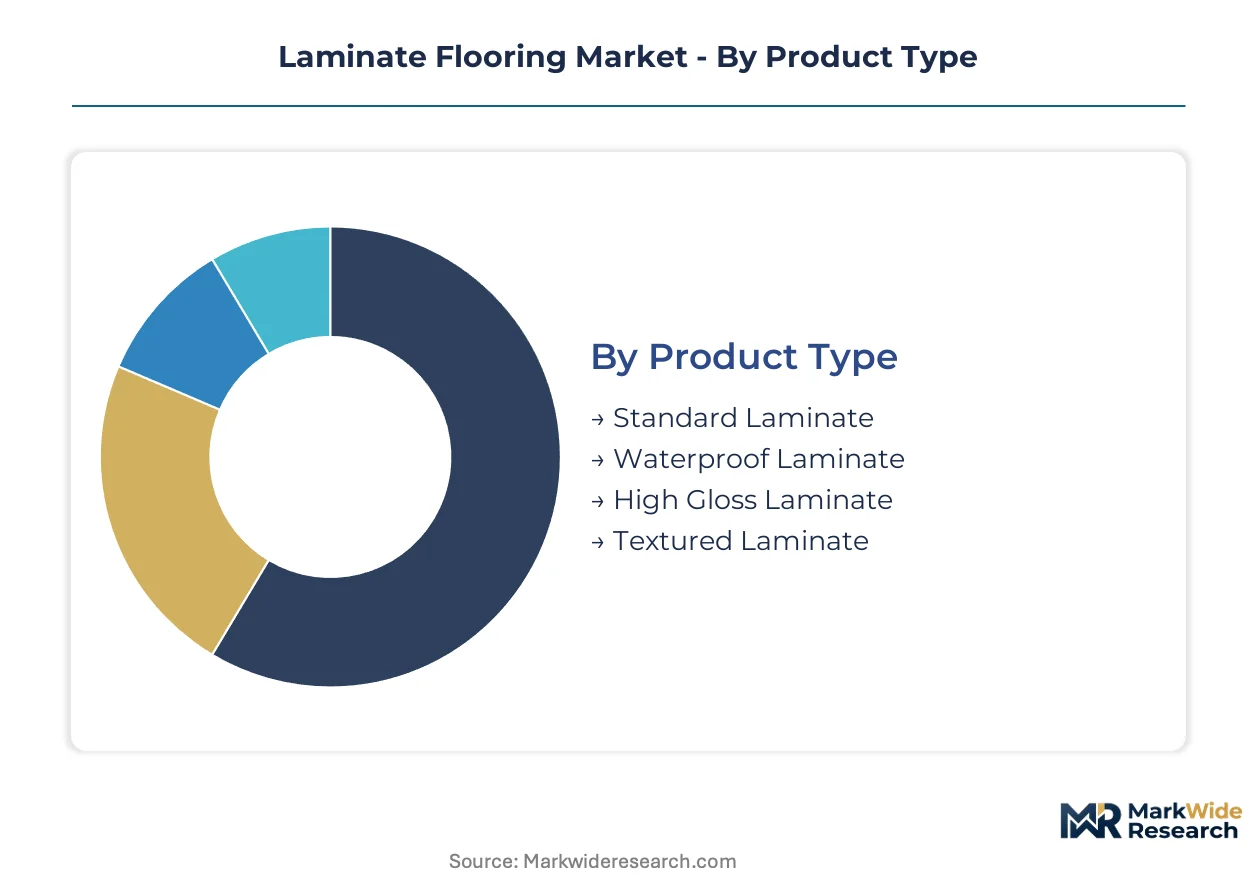
Laminate flooring segmentation reveals distinct performance tiers aligned with moisture exposure, traffic intensity, and installation substrate requirements. Specification patterns diverge sharply between renovation replacement cycles and new construction, with waterproof rigid core formulations capturing specification in moisture-prone commercial applications.
Product Type:
Product differentiation spans moisture resistance, surface aesthetics, and wear layer durability across residential and commercial use cases.
- Standard Laminate:Melamine-impregnated decorative paper bonded to high-density fiberboard core with aluminum oxide wear coating. Residential replacement cycles in suburban single-family housing across the United States concentrate demand where cost efficiency outweighs moisture exposure risk.
- Waterproof Laminate:Rigid core polymer formulations replace traditional fiberboard with waterproof substrates and tight-locking edge profiles. Commercial moisture applications in healthcare and hospitality sectors drive specification where traditional laminate faced technical barriers.
- High Gloss Laminate:Premium surface finish replicating polished stone aesthetics through enhanced melamine overlay chemistry. Retail showrooms and residential entryways specify these products for visual impact.
- Textured Laminate:Synchronized pore surface embossing replicating natural wood grain tactility. German housing retrofit sectors favor these variants where energy-efficiency certification programs reward material authenticity.
Established volume favors standard laminate; emerging adoption favors waterproof laminate.
End User:
End-user segmentation tracks traffic intensity, moisture exposure tolerance, and regulatory compliance requirements across building types.
- Residential:Single-family renovation replacement dominates volume, with waterproof variants penetrating multi-family retrofits where footfall noise regulations tighten. Suburban North American exurban corridors concentrate demand for 12 mm thickness categories with acoustic underlay integration.
- Commercial:Office, retail, and hospitality applications specify rigid core waterproof formulations for moisture-prone zones. EU Green Deal building renovation targets accelerate specification of certified low-emission products in Germany's federal subsidy programs.
- Industrial:Light manufacturing and warehousing applications prioritize wear layer durability over aesthetic fidelity. These installations specify thicker substrates for forklift and heavy equipment tolerance.
- Institutional:Schools, hospitals, and government buildings demand CE marking performance declarations under EU Construction Products Regulation for public procurement eligibility.
Residential channels anchor production scale; commercial segments command premium positioning.
Thickness:
Thickness selection determines subfloor tolerance, acoustic performance, and installation method compatibility across renovation and new construction.
- 7 mm:Economy-tier products for budget-conscious residential applications with prepared subfloors. These specifications dominate new construction where substrate leveling occurs during build-out.
- 8 mm:Mid-range residential standard balancing cost and dimensional stability. Volume production concentrates in integrated resin and board manufacturing clusters.
- 10 mm:Transitional specification for moderate traffic commercial zones requiring enhanced acoustic dampening without full 12 mm premium positioning.
- 12 mm:Premium residential and commercial specification with integrated underlay compatibility and maximum subfloor imperfection tolerance. Renovation replacement cycles favor this category where existing floor conditions vary unpredictably.
8 mm thickness sustains manufacturing volume; 12 mm specifications capture margin expansion.
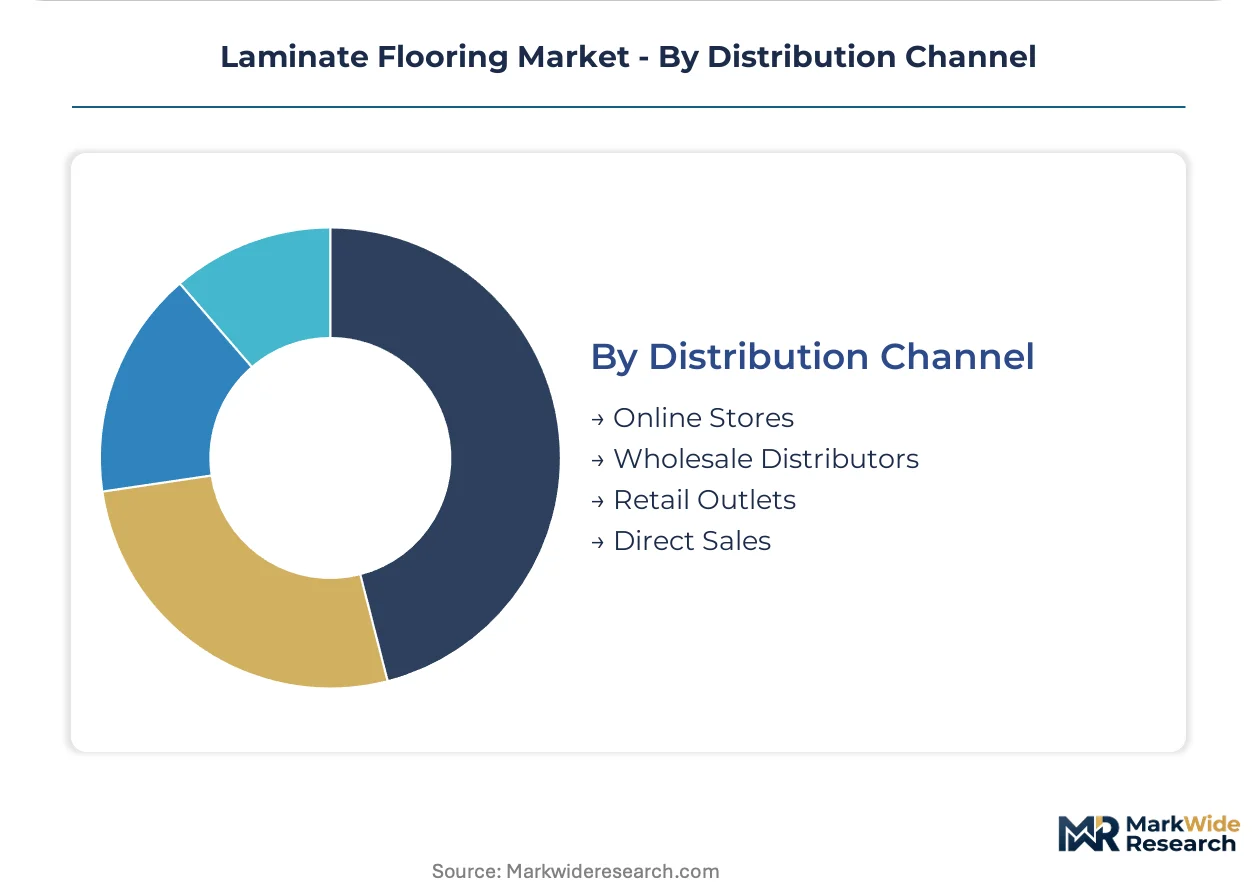
Distribution Channel:
Channel structure determines margin capture, project bundling capability, and specification influence across contractor and consumer decision journeys.
- Online Stores:Direct-to-consumer sales of standardized products with documented installation guidance. These channels expand reach into rural and underserved geographic markets.
- Wholesale Distributors:Margin-heavy channel position through volume-tiered project pricing and bundled installation accessories. German renovation contractor networks concentrate procurement through these intermediaries for energy-efficiency certification documentation.
- Retail Outlets:Big-box and specialty flooring retailers demanding EPA TSCA Title VI third-party certification before product placement. Residential replacement channels face strictest documentation requirements.
- Direct Sales:Manufacturer-to-contractor relationships for large-scale commercial and institutional projects. These arrangements enable custom specification and dedicated project management.
Wholesale distributors consolidate renovation market influence; online channels expand geographic penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German laminate flooring exports flow primarily into neighboring EU member states and North American renovation markets, with Austrian integrated producers serving as the secondary supply corridor for waterproof rigid core formulations.
United States
Suburban single-family renovation across exurban corridors drives waterproof laminate specification, with EPA TSCA Title VI compliance costs reshaping supplier economics. California Air Resources Board amendments interact with federal standards to create dual-certification requirements. The Southeast manufacturing belt, particularly around Georgia and the Carolinas, hosts resin and board production facilities serving domestic retail networks.
Germany
Federal subsidy programs for energy-efficient housing retrofits accelerate certified low-emission laminate specification in residential replacement cycles. EU Green Deal building renovation targets tighten material emissions standards through ECHA REACH isocyanate restrictions in adhesive binders. The North Rhine-Westphalia industrial cluster anchors integrated production, with Kronospan and Egger maintaining captive resin and board manufacturing near Cologne and Bielefeld.
China
Domestic construction activity concentrates demand for economy-tier 7-8 mm products in new residential developments, with export-oriented producers serving Southeast Asian and Middle East markets. GB standards for formaldehyde emissions in wood-based panels govern domestic certification requirements. The Yangtze River Delta manufacturing zone, centered on Jiangsu and Zhejiang provinces, hosts decorative paper impregnation and high-density fiberboard production at scale.
Austria
Integrated resin and board production clusters supply waterproof laminate substrates across European distribution networks, with tight-locking edge profile technology commanding specification in moisture-prone commercial applications. CE marking under the Construction Products Regulation enables cross-border public procurement eligibility. Upper Austrian industrial zones around Linz and Wels concentrate melamine-formaldehyde resin synthesis and laminate pressing capacity.
Canada
Health Canada and PMRA oversight of building material emissions aligns with US EPA frameworks, enabling seamless cross-border product platform deployment. Multi-family housing retrofits in Toronto and Vancouver metro areas specify 12 mm thickness categories with acoustic underlay integration for footfall noise compliance. Ontario-based wholesale distributors bundle installation accessories for renovation contractor networks serving the Great Lakes corridor.
Laminate Flooring Market Key Industry Players
On the supply side, the industry is consolidating around integrated resin-to-board manufacturers and specialized decorative layer producers, with tiered competitive positioning separating captive inkjet printing specialists from volume-driven standard laminate fabricators. Three strategic archetypes dominate: vertically integrated European producers controlling raw material inputs, North American retail-channel specialists with captive distribution networks, and Asian scale manufacturers serving cost-sensitive new construction segments. Capacity expansion in waterproof rigid core formulations and strategic partnerships for digital printing technology licensing represent the dominant competitive moves reshaping supplier economics.
Among North American retail-channel specialists, Mohawk Industries and Shaw Industries Group exemplify the integrated distribution archetype, with captive manufacturing enabling control over design-to-delivery timelines. European integrated producers Kronospan and Egger occupy positions emphasizing synchronized pore surface textures and resin-to-board vertical control. These four entities represent the structural poles around which competitive positioning organizes: retail-captive North American networks versus European manufacturing-scale specialists.
| Leading Market Players |
|---|
| Mohawk Industries |
| Shaw Industries Group |
| Tarkett |
| Mannington Mills |
| Armstrong Flooring |
| Beaulieu International Group |
| Kronospan |
| Egger |
| Forbo |
| Others |
Cost & Logistics Intelligence
Integrated melamine-formaldehyde resin synthesis clusters in Upper Austria and North Rhine-Westphalia concentrate upstream margin capture, with captive production of high-density fiberboard cores and decorative paper impregnation feeding downstream pricing power to wholesale distributors bundling installation accessories.
Pricing Analysis
Technology-generation pricing gaps separate standard fiberboard-core laminate from waterproof rigid-core polymer formulations and emerging synchronized-pore textured variants. Three-tier pricing structure across premium, standard, and economy levels stratifies by wear-layer durability and moisture-resistance certification, with 12 mm thickness categories commanding positioning above 7-8 mm economy tiers. Price differentiation rests on EPA TSCA Title VI compliance documentation and CE marking under the Construction Products Regulation. Cost compression in standard laminate is intensifying because melamine-formaldehyde resin prices fluctuate with natural gas feedstock exposure. Residential renovation contractors exhibit highest price sensitivity; institutional procurement with federal subsidy eligibility shows lowest.
Supply Chain Analysis
Export-control regime angles are minimal in flooring, though ECHA REACH isocyanate restrictions in adhesive binders limit formulation flows into European markets. Geographic supply concentration centers on Austria, Germany, and China's Yangtze River Delta manufacturing zone. Raw material dependencies draw from melamine-formaldehyde resin, aluminum oxide wear-layer minerals, and decorative paper substrates. Single-source vulnerability concentrates in European resin synthesis clusters exposed to regional energy price shocks. Distribution runs through wholesale distributors bundling underlayment and trim for renovation contractor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Laminate flooring markets increasingly reward complete flooring system providers over materials-only suppliers, with acoustic underlay bundling and energy-efficiency certification documentation expanding faster than base product hardware sales.
For Market Incumbents: Pre-empt rigid core waterproof laminate substitution by luxury vinyl tile through backward integration into polymer substrate chemistry and tight-locking edge profile manufacturing. Invest in captive inkjet decorative layer printing to compress design-to-delivery timelines against retail-channel specialists. Prioritize dual-market platform consolidation to resolve California Air Resources Board and German DIBt formulation divergence fragmenting production scale economies. For New Entrants and Emerging Players: Pursue white-space positioning in multi-family housing retrofit segments where footfall noise regulations tighten and acoustic underlay bundling penetrates fastest. Target waterproof rigid core specification in commercial moisture applications where traditional laminate faced technical barriers. Enter through wholesale distributor partnerships offering volume-tiered project pricing with energy-efficiency certification documentation for German federal subsidy programs. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated European manufacturers with captive resin-to-board production and synchronized pore surface texture capabilities. Long-term viability over a multi-year horizon favors suppliers controlling decorative layer digitization and rigid core chemistry advances. Watch waterproof laminate specification rates in healthcare and hospitality sectors as the inflection indicator for technology-generation transition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Substrate Chemistry | Captive rigid core production insulates margin from resin price volatility and accelerates waterproof formulation development. |
| Digital Printing Technology Licensing | Inkjet decorative layer partnerships compress design-to-delivery timelines and enable rapid pattern turnover for premium residential channels. |
| Acoustic Underlay System Bundling | Integrated sound-dampening layers penetrate multi-family retrofits where German footfall noise regulations tighten compliance requirements. |
| Dual-Market Certification Harmonization | Unified product platforms resolving EPA TSCA Title VI and ECHA REACH divergence restore production scale economies across North American and European distribution. |
| Wholesale Distributor Channel Expansion | Volume-tiered project pricing with installation accessories captures margin-heavy positions in renovation contractor networks. |
Research Approach
A spread of perspectives from plant managers at integrated resin and board manufacturers, procurement leads at wholesale distribution networks, renovation contractor specification heads, and regulatory compliance officers converged on the working assumptions. Primary fieldwork combined with secondary validation from customs and trade data, industry association reports, and construction products regulatory filings. Bottom-up shipment analysis by thickness category and product type triangulated against top-down spending estimates across residential replacement and commercial new construction.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation modeled by product type, end-user application, thickness specification, and distribution channel. CAGRs derived from shipment volume trajectories and value-per-unit trends by performance tier. Industry-specific forecast inputs included federal subsidy program allocations for energy-efficient housing retrofits and waterproof laminate specification rates in moisture-prone commercial segments.
Sensitivities concentrate around melamine-formaldehyde resin price volatility, ECHA REACH adhesive binder compliance timeline extensions, and California Air Resources Board amendment interactions with federal standards. Forecasts reflect documented assumptions about renovation replacement cycle timing and subsidy program continuity. Material shifts in EU Green Deal building renovation target enforcement or natural gas feedstock pricing would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
Turkey Carpet and Rugs Market
Flooring, Carpets, and Rugs
Wooden Floor Market
Flooring, Carpets, and Rugs
China Engineered Wood Flooring Market
Flooring, Carpets, and Rugs
Japan Floor Covering Market
Flooring, Carpets, and Rugs
India Vinyl Flooring Market
Flooring, Carpets, and Rugs
Bath Rugs and Mats Market
Flooring, Carpets, and Rugs
Carpets and Rugs Market
Flooring, Carpets, and Rugs
Carpet Market
Flooring, Carpets, and Rugs
Global Flooring Market
Flooring, Carpets, and Rugs
Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Luxury Vinyl Tiles Market
Flooring, Carpets, and Rugs
United States Floor Covering Market
Flooring, Carpets, and Rugs
Luxury Vinyl Plank (LVP) Market
Flooring, Carpets, and Rugs
Global Commercial Flooring Market
Flooring, Carpets, and Rugs
Europe Carpet Tile Market
Flooring, Carpets, and Rugs
Global Flooring and Carpet Market