
 Global Luxury Vinyl Tile Floor Covering Market | 2026-2036
Global Luxury Vinyl Tile Floor Covering Market Size, Share, and Industry Trends Forecast 2026-2036
Global Luxury Vinyl Tile Floor Covering Market Foresight
Southeast Asia is tilting toward integrated LVT manufacturing as Chinese producers establish resin compounding and print film operations in Vietnam and Thailand. Shaw Industries Group leverages captive PVC supply chains to stabilize input costs across North American distribution. Mohawk Industries anchors its position through rigid core technology leadership in the residential replacement segment. Tarkett competes on sustainability credentials backed by third-party verified recycled content programs.
Luxury vinyl tile floor covering consists of multi-layered synthetic flooring products combining a PVC or SPC core with a photographic print layer and protective wear layer, typically measuring 2–8 mm in total thickness and rated for commercial traffic loads exceeding AC3 abrasion classifications. The primary purpose is to deliver hardwood or stone aesthetics with superior moisture resistance and lower lifecycle cost in high-traffic commercial and residential environments. Plank formats dominate residential renovation due to ease of installation and visual continuity, while tile configurations capture commercial specification where modular replacement and design flexibility command margin premiums. Click-lock installation systems represent the fastest-growing structural category as floating floors reduce subfloor preparation costs and accelerate project timelines for contractor end users.
The US EPA regulates phthalate content in vinyl flooring through TSCA Section 6 restrictions, while the EU REACH framework restricts cadmium and lead stabilizers in PVC compounds used for interior applications. California's Department of Public Health maintains CDPH Standard Method v1.2 for VOC emissions testing, creating a de facto national benchmark for product certification in the US market. China's GB standards govern formaldehyde release and heavy metal limits under MEE enforcement protocols. Stakeholders must monitor evolving chemical restriction timelines across these jurisdictions to anticipate reformulation costs and certification gaps before procurement cycles lock specifications.
Market Dynamics
EU Green Deal building performance standards are forcing accelerated disclosure requirements for PVC compound chemistry across European specification channels, compressing reformulation timelines for manufacturers serving commercial renovation contracts.
Growth Catalysts
- Hospitality Renovation Cycles:North American hotel property improvement plans are expanding LVT specification rates as owners prioritize moisture-resistant flooring with reduced installation downtime versus traditional hardwood.
- REACH Chemical Restrictions:European REACH framework phase-outs of legacy stabilizers are pulling demand toward certified low-VOC rigid core products that preempt compliance gaps in procurement cycles.
- SPC Core Technology:Stone-polymer composite rigid cores are displacing flexible PVC in high-traffic commercial applications by delivering dimensional stability without adhesive installation.
Market Restraints
- Resin Supply Concentration:Captive PVC supply chains concentrate among integrated petrochemical groups, exposing independent manufacturers to ethylene and chlorine derivative price volatility without backward integration buffers.
- Phthalate Substitution Costs:US EPA TSCA Section 6 restrictions on ortho-phthalate plasticizers require reformulation investments that compress margins for mid-tier producers lacking scale economies in bio-based alternative sourcing.
- Ceramic Tile Substitution:Thin-profile porcelain tiles with inkjet surface replication retain specification share in premium commercial segments where thermal mass and fire resistance ratings exceed LVT performance ceilings.
Strategic Opportunities
- India Commercial Real Estate:Office and retail construction in Bengaluru, Mumbai, and Delhi NCR presents underpenetrated specification potential as domestic developers adopt floating floor systems to accelerate project handover timelines.
- EU Taxonomy Alignment:Green building certification schemes tied to EU Green Deal performance standards create procurement preference for LVT products with third-party verified recycled content and end-of-life take-back programs.
- Digital Print Convergence:Advancements in rotogravure and UV-cured digital printing are enabling batch-size-one customization for hospitality and healthcare design specifications without minimum order quantity penalties.
Industry Challenges
- Wear Layer Certification Timelines:CDPH Standard Method v1.2 VOC emissions testing and FloorScore certification create 12-16 week approval bottlenecks that misalign with compressed commercial project bidding windows.
- Installation Skill Fragmentation:Click-lock floating floor systems require specialized contractor training for subfloor moisture testing and expansion gap management, creating quality variance in warranty claim rates across distribution territories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Luxury Vinyl Tile Floor Covering Market |
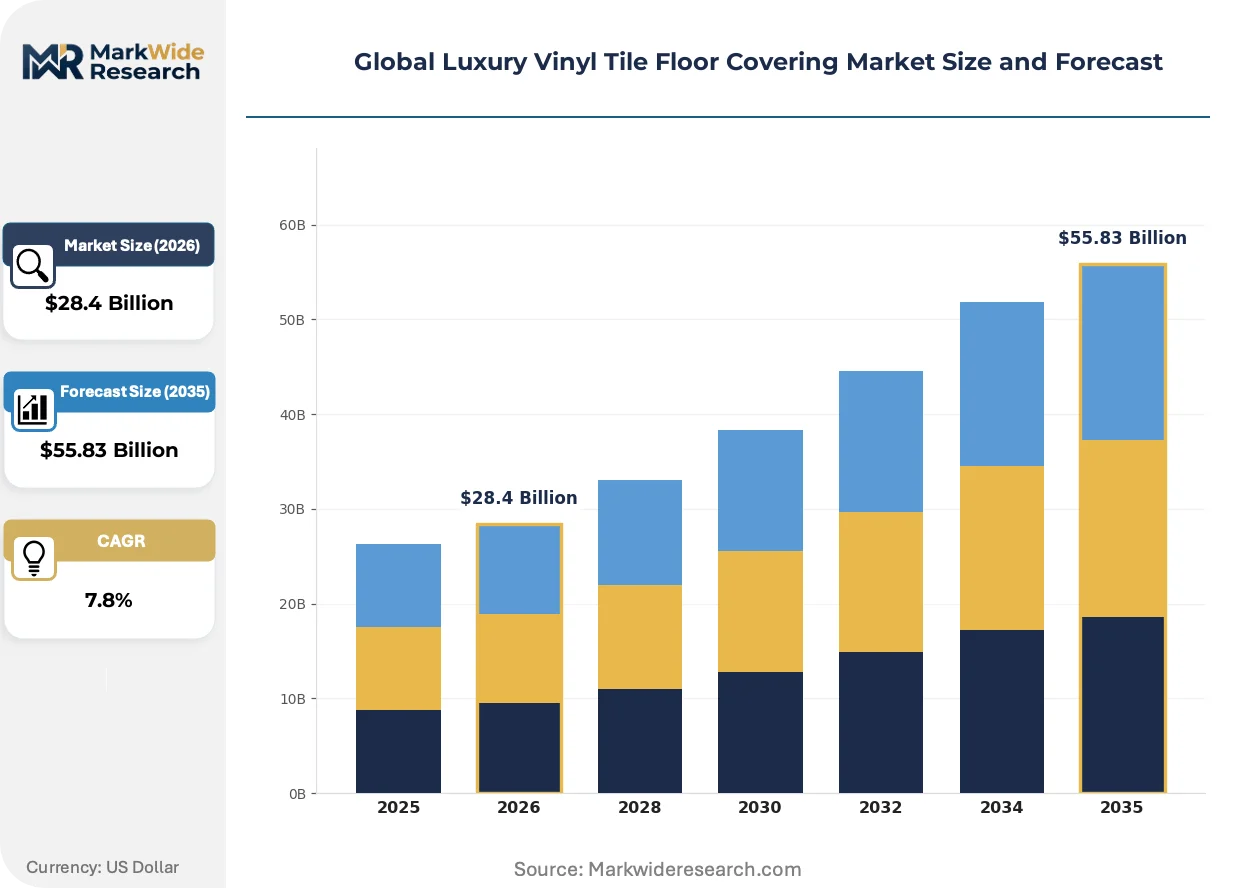
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $55.83 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plank, Tile, Sheet, Hybrid Application: Residential, Commercial, Industrial, Hospitality End User: Homeowners, Contractors, Designers, Retailers Installation: Glue-Down, Floating, Click-Lock, Loose Lay |
| Companies Covered | Shaw Industries Group, Gerflor, Mohawk Industries, LG Hausys, Forbo Holding, Tarkett, Mannington Mills, Interface, Armstrong Flooring, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Luxury Vinyl Tile Floor Covering Market Shifts & Advancements
Surface replication technologies and installation system simplification are compressing the performance gap between synthetic and natural materials while reshaping contractor labor economics and project timeline structures.
Digital embossing technology is migrating from mechanical press plates to in-register synchronized texture systems that align surface relief with printed grain patterns. High-end residential developers in California and Texas are specifying these products for single-family custom homes where tactile authenticity commands margin premiums. This capability is compressing specification share for engineered hardwood in moisture-prone basement and bathroom applications.
China's MEE enforcement protocols under GB standards for formaldehyde release and heavy metal limits are tightening testing frequency requirements for PVC compound imports. Domestic manufacturers with in-house resin compounding capabilities are capturing specification share from import-dependent distributors. Commercial projects in Shanghai and Beijing are increasingly requiring batch-level test reports as contract deliverables.
Specification decisions are consolidating around lifecycle cost documentation rather than first-cost comparison. Healthcare facility managers in Germany and the Netherlands are prioritizing products with guaranteed wear layer replacement programs and documented maintenance cost curves. This behavior is elevating procurement influence of facility management consultants over traditional general contractor material selection authority.
Global Luxury Vinyl Tile Floor Covering Market Segmentation
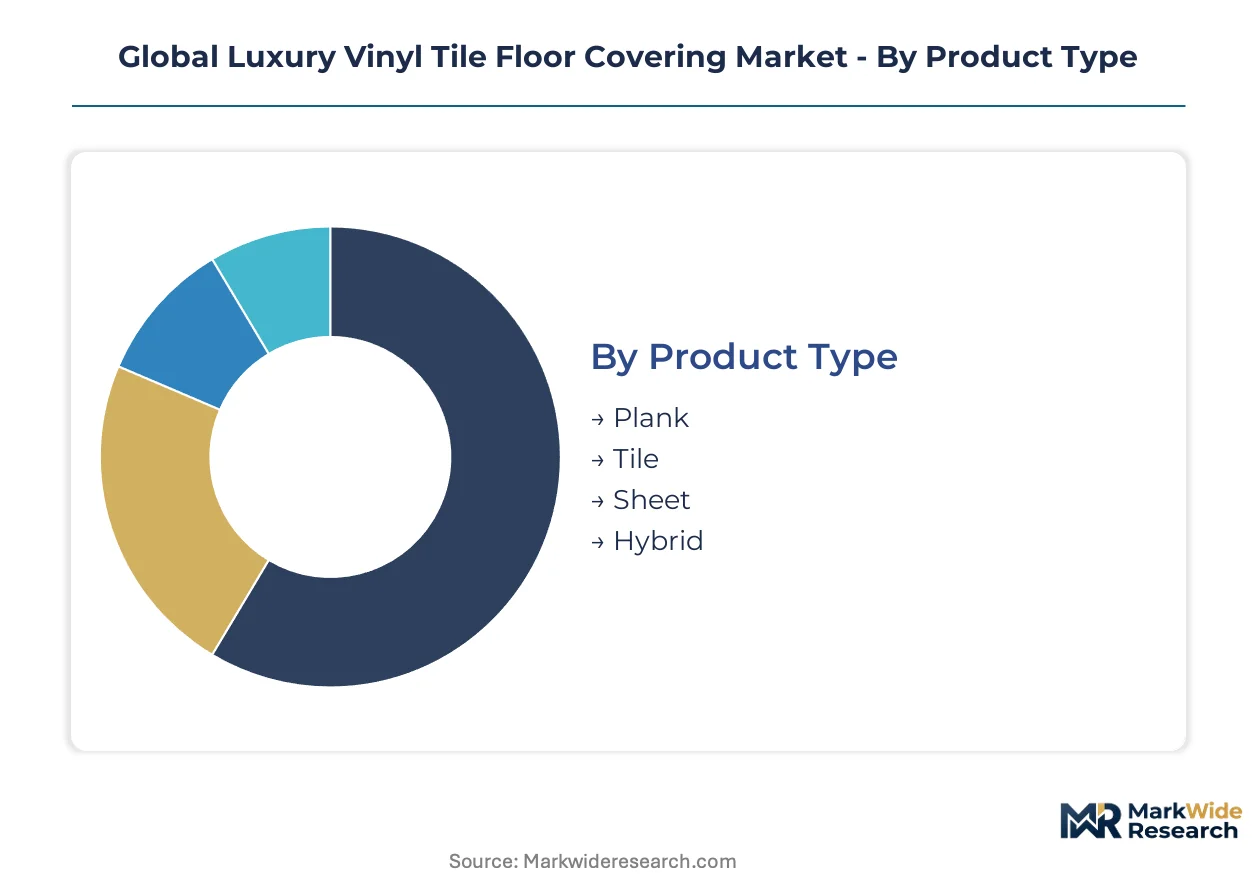
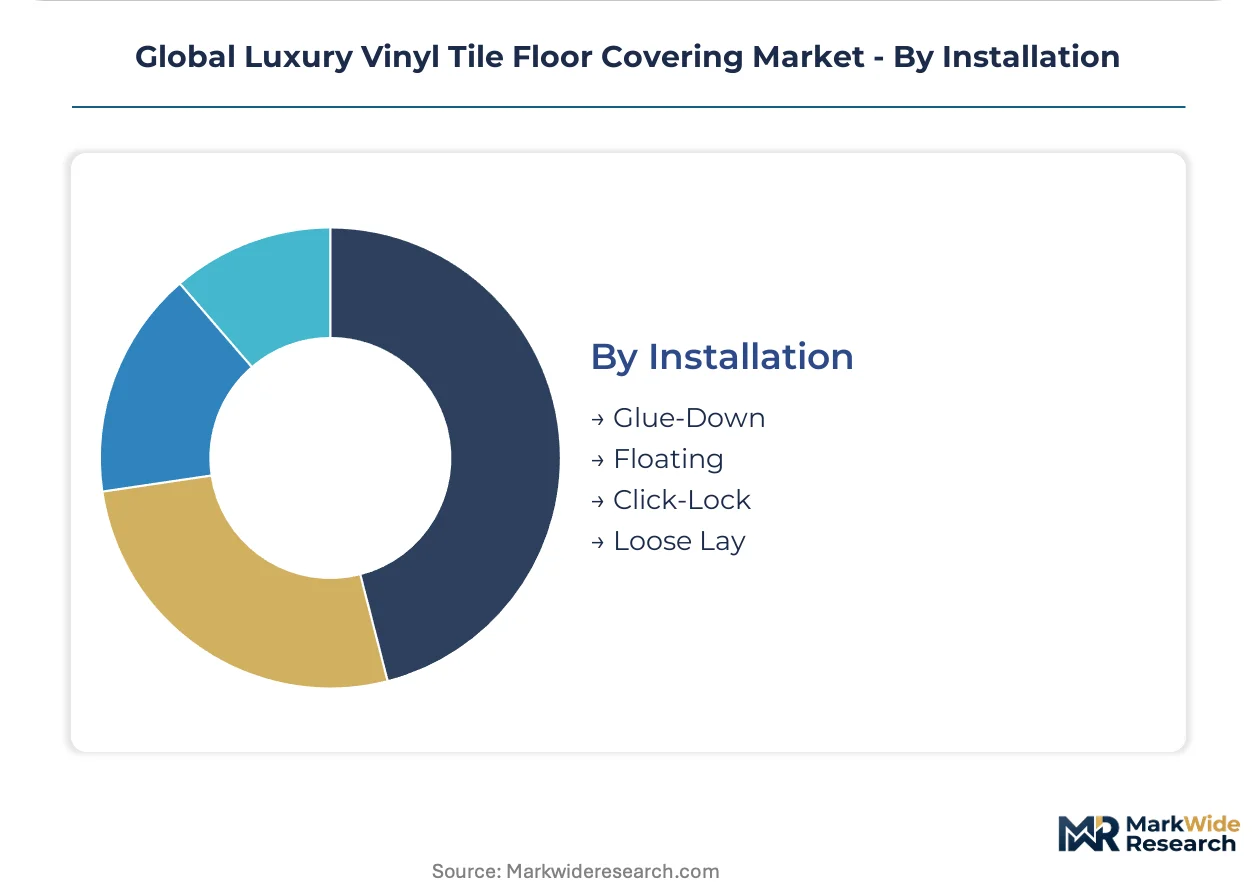
Segmentation in luxury vinyl tile floor covering reveals how product architecture, installation mechanics, and procurement authority reshape margin capture across project types. Specification behavior diverges sharply between residential renovation cycles and commercial procurement channels.
Product Type:
Cost tier differentiation separates entry-level specification from premium-margin capture across residential and commercial channels.
- Plank:Rectangular formats measuring 4–9 inches wide replicate hardwood visuals through synchronized embossing. Home renovation in Texas and Florida concentrates demand here as floating installation reduces skilled labor requirements.
- Tile:Square configurations from 12×12 to 24×24 inches deliver stone aesthetics with modular replacement capability. Hospitality specification in California and New York prioritizes these products for design flexibility and reduced downtime during partial renovation.
- Sheet:Continuous rolls up to 12 feet wide minimize seams in healthcare and food service environments. Seam welding requirements limit specification to specialized contractor networks.
- Hybrid:Composite constructions combining rigid core stability with flexible installation adapt to uneven subfloors. Emerging specification in multifamily housing renovation across Germany.
Plank commands the established base. The steepest expansion runs through hybrid formats.
Application:
Volume concentration and project timeline structures differentiate procurement behavior across end-use environments.
- Residential:Single-family and multifamily replacement cycles drive specification through big-box retail and specialty flooring dealers. Moisture resistance in basement applications displaces engineered hardwood across the US Southeast.
- Commercial:Office, retail, and institutional projects require AC4+ wear ratings and documented lifecycle cost analysis. Facility management consultants in the Netherlands and Germany increasingly control material selection authority.
- Industrial:Manufacturing and warehouse environments prioritize chemical resistance and static control properties. Limited specification due to epoxy and polished concrete competition.
- Hospitality:Hotel property improvement plans demand rapid installation turnaround and modular replacement for damaged rooms. North American renovation budgets are expanding specification rates.
Commercial applications anchor volume concentration. Hospitality is climbing the fastest.
End User:
Customer type determines information requirements, pricing sensitivity, and channel access across the purchase journey.
- Homeowners:DIY-capable consumers prioritize click-lock systems with visual continuity and moisture warranties. Research behavior concentrates on online reviews and showroom tactile evaluation.
- Contractors:Installation professionals control material specification through builder programs and volume pricing agreements. Subfloor preparation cost reduction drives floating floor preference.
- Designers:Interior architects specify through aesthetic performance and third-party certification documentation. EU Green Deal alignment increasingly filters product eligibility.
- Retailers:Flooring dealers and home improvement chains influence substitution decisions at point-of-sale through inventory positioning and private label programs.
Contractors command specification authority in residential renovation. Designers are gaining procurement influence fastest in commercial channels.
Installation:
Application method reshapes labor economics, subfloor tolerance requirements, and project timeline compression.
- Glue-Down:Full-spread adhesive application delivers maximum dimensional stability for high-traffic commercial environments. Extended cure times and subfloor moisture testing requirements compress specification share.
- Floating:Interlocking systems installed over underlayment without adhesive attachment. Residential replacement in Germany and France prioritizes these products for rapid project completion.
- Click-Lock:Precision-milled joint systems enable tool-free assembly with expansion gap management. Fastest-growing structural category as contractor training programs expand.
- Loose Lay:Weight-backed products rely on friction and perimeter retention without mechanical fastening. Limited to temporary installations and low-traffic commercial environments.
Click-lock systems anchor growth trajectory. Glue-down retains specification in premium commercial segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA TSCA Section 6 restrictions on ortho-phthalate plasticizers anchor the regulatory framework in the United States, the dominant geography for LVT specification in hospitality and residential renovation channels.
United States
Hotel property improvement plans in Texas and Florida are accelerating LVT specification rates as owners prioritize moisture-resistant flooring with reduced installation downtime. The EPA enforces TSCA Section 6 phthalate restrictions that require reformulation investments across domestic manufacturers. Dalton, Georgia anchors North American production concentration where captive PVC supply chains stabilize input cost volatility.
Germany
Healthcare facility managers in Berlin and Munich are prioritizing lifecycle cost documentation over first-cost comparison for flooring procurement decisions. The EU Green Deal building performance standards tighten material disclosure requirements for PVC compound chemistry through ECHA enforcement. The Rhine-Ruhr industrial corridor concentrates rigid core technology development serving commercial renovation contracts across the Benelux region.
China
Tier-one cities including Shanghai and Beijing are experiencing accelerated commercial real estate retrofit cycles driving specification demand. MEE enforcement protocols under GB standards govern formaldehyde release and heavy metal limits with increasing testing frequency requirements. The Yangtze River Delta manufacturing cluster is capturing share from import-dependent distributors through in-house resin compounding capabilities.
India
Office and retail construction in Bengaluru, Mumbai, and Delhi NCR presents underpenetrated specification potential for floating floor systems. BIS standards for interior building materials create compliance benchmarks that domestic and import suppliers must satisfy for commercial project eligibility. The Delhi-Mumbai Industrial Corridor is attracting regional distribution investments as developers adopt accelerated project handover timelines.
Vietnam
Chinese producers are establishing resin compounding and print film operations to serve Southeast Asian export markets and domestic construction growth. The country's national building materials regulator maintains evolving standards for VOC emissions and heavy metal content in interior applications. Ho Chi Minh City and Hanoi industrial zones are concentrating integrated LVT manufacturing investments from regional supply chain relocations.
Global Luxury Vinyl Tile Floor Covering Market Competitive Landscape
Capability concentration sits with integrated petrochemical-backed manufacturers; scale advantage sits with diversified flooring conglomerates with captive distribution networks. The market structures around three tiers: vertically integrated resin compounders, technology-specialized rigid core developers, and regional private-label fabricators. Two dominant competitive moves are reshaping positioning: backward integration into PVC resin production to buffer ethylene price volatility, and portfolio diversification into SPC core formulations to capture commercial specification share.
Among North American flooring conglomerates, Shaw Industries Group and Mohawk Industries exemplify the scale-driven tier with captive supply chain control. Tarkett occupies a position within the sustainability-credentials segment where third-party verified recycled content programs filter procurement eligibility. These three anchors illustrate how competitive positioning stratifies between cost stabilization through upstream integration and margin capture through certified environmental performance.
| Leading Market Players |
|---|
| Shaw Industries Group |
| Gerflor |
| Mohawk Industries |
| LG Hausys |
| Forbo Holding |
| Tarkett |
| Mannington Mills |
| Interface |
| Armstrong Flooring |
| Others |
Supply & Pricing Matrix
Overcapacity in China's Yangtze River Delta resin compounding sector is compressing margin recovery timelines for integrated manufacturers while forcing independent producers toward aggressive spot-market pricing to maintain throughput. This utilization dynamic simultaneously erodes pricing power in standard-grade LVT exports and accelerates tier migration toward certified low-VOC products where supply constraints persist.
Pricing Analysis
Price spreads between US Gulf Coast and European delivered LVT products have widened as ethylene derivative cost disparities interact with divergent regulatory compliance investments. Three-tier pricing structure across premium, standard, and economy levels separates FloorScore-certified rigid core specification from entry-level flexible imports. Cost compression in economy-tier flexible products is intensifying because Vietnamese contract manufacturers are absorbing PVC resin volatility to secure volume commitments. Hospitality facility managers demonstrate lowest price sensitivity due to lifecycle cost documentation requirements, while residential renovation contractors exhibit highest sensitivity to first-cost differentials.
Supply Chain Analysis
Contract manufacturing concentration sits with Chinese-owned operations in Vietnam's Ho Chi Minh City industrial zones and Thailand's Eastern Economic Corridor, where resin compounding and print film capabilities have relocated to circumvent tariff exposure. Geographic supply concentration centers on China, Vietnam, and the United States, with the latter anchoring captive PVC production through integrated petrochemical complexes. Raw material dependencies draw from ethylene feedstocks, calcium carbonate fillers for SPC cores, and titanium dioxide pigments for wear layer opacity. Single-source vulnerability runs through concentrated phthalate-free plasticizer supply for EPA TSCA Section 6 compliance. Distribution runs through specialty flooring dealer networks in residential channels and direct specification relationships with facility management consultants in commercial segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity is expanding as EU Green Deal disclosure requirements splinter procurement eligibility around certified chemistry tiers, creating defendable niches for specialists with verified supply chain documentation.
For Market Incumbents: Harden specification lock-in through captive SPC core production in the US Southeast to buffer ethylene price volatility while accelerating FloorScore certification timelines to outrun CDPH approval bottlenecks. Deepen channel control via exclusive builder program agreements with top-ten US residential contractors. Prioritize wear layer technology R&D to extend lifecycle performance guarantees that facility management consultants in Germany and the Netherlands are demanding. For New Entrants and Emerging Players: Build out white-space presence in India's Bengaluru and Delhi NCR commercial real estate corridors where floating floor system specification remains underpenetrated and BIS compliance creates manageable entry barriers. Target hospitality renovation contractors in Texas and Florida with rapid-installation product bundles that compress project timelines. Pursue go-to-market partnerships with regional distributors holding established relationships with domestic Indian developers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among rigid core technology developers with installed base maintenance programs and documented replacement wear layer supply agreements. Long-term viability over the coming decade rests on positioning for EU Taxonomy-aligned procurement preference and end-of-life take-back infrastructure. Acquisition focus should center on mid-tier manufacturers with in-house resin compounding capabilities and established third-party certification portfolios. Monitor CDPH Standard Method v1.2 approval timeline compression as inflection signal for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PVC Resin Production | Captive ethylene supply chains at Shaw Industries Group stabilize input cost volatility across North American distribution. |
| SPC Core Technology Scale-Up | Stone-polymer composite formulations at Mohawk Industries capture commercial specification share from flexible PVC alternatives. |
| Third-Party Recycled Content Certification | Tarkett's verified programs filter EU Green Deal procurement eligibility in healthcare and hospitality channels. |
| Digital Print Customization Capability | Rotogravure and UV-cured systems enable batch-size-one production for hospitality design specifications without minimum order penalties. |
| End-of-Life Take-Back Program Development | Documented circular economy infrastructure aligns with EU Taxonomy performance standards for green building certification schemes. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with flooring industry stakeholders and secondary validation through regulatory filings and trade databases. Primary interviews encompassed plant managers at integrated resin compounders, procurement leads at hospitality REITs, distribution channel partners in Germany and the United States, and technical R&D directors specializing in rigid core formulations. Secondary sources drew from US EPA TSCA Section 6 regulatory dockets, ECHA REACH restriction timelines, China MEE enforcement protocols under GB standards, customs and trade flow data, and SEC 10-K disclosures from publicly traded flooring conglomerates. Bottom-up volume estimates triangulated against top-down market sizing derived from construction spending correlations.
Forecast inputs considered product type segmentation across plank, tile, sheet, and hybrid formats; installation method differentiation between glue-down, floating, click-lock, and loose lay systems; and end-user procurement authority patterns spanning homeowners, contractors, designers, and retailers. CAGRs were derived through regression analysis against commercial construction indices and renovation cycle timing across the projection horizon. Industry-specific inputs incorporated hospitality property improvement plan budget trajectories and EU Green Deal building performance standard implementation timelines.
Sensitivities concentrate around EPA phthalate restriction enforcement intensity, ethylene derivative price volatility, and CDPH certification approval timeline compression. Forecasts reflect modeling assumptions regarding regulatory compliance cost pass-through rates and contractor training program expansion curves. Quarterly review of hospitality renovation budget announcements, MEE enforcement protocol updates, and resin compounding capacity utilization indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
North America Laminate Flooring Market
Flooring, Carpets, and Rugs
Area Rugs Market
Flooring, Carpets, and Rugs
Wood and Laminate Flooring Market
Flooring, Carpets, and Rugs
China Engineered Wood Flooring Market
Flooring, Carpets, and Rugs
Middle East Flooring and Carpet Market
Flooring, Carpets, and Rugs
China Floor Covering Market
Flooring, Carpets, and Rugs
Bath Mats Market
Flooring, Carpets, and Rugs
Germany Resilient Flooring Market
Flooring, Carpets, and Rugs
United Arab Emirates Floor Covering Market
Flooring, Carpets, and Rugs
Europe Laminate Flooring Market
Flooring, Carpets, and Rugs
Turkey Floor Covering Market
Flooring, Carpets, and Rugs
Europe Floor Covering Market
Flooring, Carpets, and Rugs
Luxury Vinyl Tiles Market
Flooring, Carpets, and Rugs
Saudi Arabia Vinyl Flooring Market
Flooring, Carpets, and Rugs
United States Floor Covering Market
Flooring, Carpets, and Rugs
Sheet Flooring Market