
 Wood and Laminate Flooring Market | 2026-2036
Wood and Laminate Flooring Market Size, Share, and Industry Trends Forecast 2026-2036
Wood and Laminate Flooring Market Intelligence
Expanded manufacturing capacity in Vietnam is narrowing the cost gap between laminate and certain engineered wood products. Mohawk Industries, Inc. leverages its immense scale to influence pricing and material sourcing across segments. Shaw Industries Group, Inc. sustains its market position through extensive distribution networks in North America. Meanwhile, Mannington Mills, Inc. differentiates with a focus on design-forward products for the residential sector.
Wood and laminate flooring comprises surfacing materials designed to simulate wood aesthetics for interior spaces. Laminate products are composite boards featuring a photographic applique layer under a protective clear wear layer, typically made of melamine resin. In terms of product type, engineered wood holds a significant share due to its stability, while high-pressure laminate gains traction in high-traffic commercial complexes. The click-lock installation method continues to dominate the do-it-yourself residential segment due to its ease of use.
Regulatory frameworks significantly influence material composition and market access. In the United States, the EPA's formaldehyde emission standards under TSCA Title VI govern composite wood products, while in Europe, CE marking is mandatory for demonstrating compliance with safety and environmental criteria. Stakeholder decisions will increasingly hinge on securing sustainable timber supply chains and achieving third-party environmental certifications.
Market Dynamics
The central force shaping the market is the conflict between consumer demand for authentic wood aesthetics and intensifying global regulations on material health and sustainability. This dynamic pushes innovation in composite materials and adhesives while forcing a re-evaluation of timber supply chains to meet standards like the EU's REACH.
Growth Catalysts
- Residential Renovation:A surge in home remodeling projects, particularly within North America and Europe, stimulates demand for easy-to-install flooring. The do-it-yourself segment benefits significantly from the widespread availability of click-lock installation systems for both laminate and engineered wood.
- Low-VOC Products:Regulations such as the EPA's TSCA Title VI in the United States are accelerating the development and adoption of low-volatile organic compound (VOC) adhesives and core boards. This creates new specifications for flooring in schools, healthcare facilities, and green buildings.
- Durable Laminates:Advances in material science have improved the performance of high-pressure laminate (HPL) products. Their enhanced scratch and impact resistance makes them a preferred choice for high-traffic commercial environments like retail stores, airports, and hospitality venues.
Market Restraints
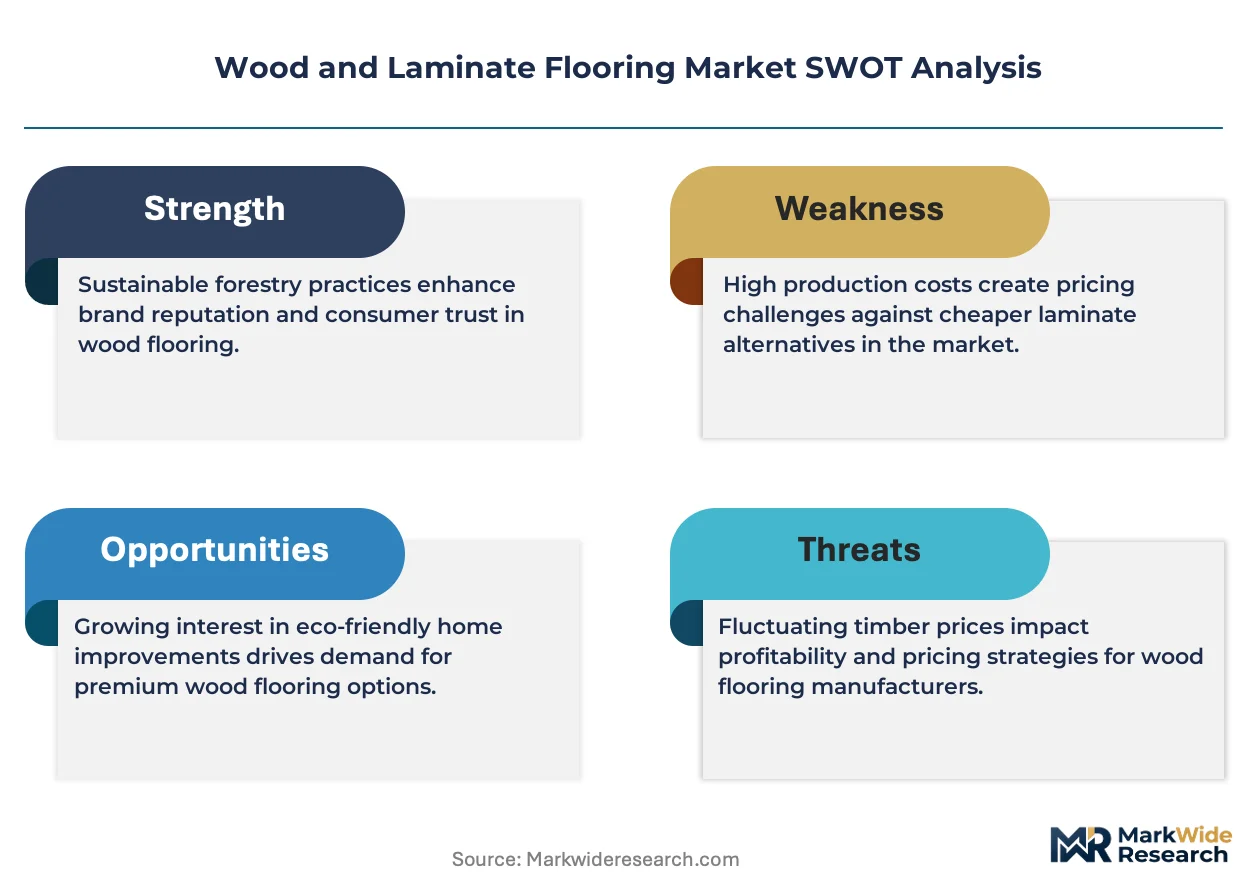
- Input Cost Volatility:The market faces persistent pressure from fluctuating prices of key raw materials. The costs of melamine resins for wear layers and specialty timber for engineered wood cores are subject to supply disruptions and geopolitical factors, impacting final product pricing.
- Substitution from LVT:Luxury vinyl tile (LVT) presents a significant substitution threat, especially in applications requiring superior water resistance. LVT's performance in wet areas like bathrooms and basements erodes the market share of laminate and some wood products in the residential sector.
- Complex Certification Pathways:Manufacturers face high costs and long lead times to secure multiple regional certifications. The need to comply with both CE marking in Europe and TSCA Title VI in the US for composite wood products creates a substantial barrier for smaller producers.
Strategic Opportunities
- High-Growth Construction Markets:Untapped demand exists within rapidly urbanizing economies, particularly India. The expansion of middle-class housing creates a significant opportunity for mid-range engineered wood and premium laminate products that offer a balance of cost and aesthetics.
- Digital Printing Integration:The convergence of advanced digital printing with laminate manufacturing enables hyper-realistic wood grains and custom patterns. This technology opens opportunities in the high-end architectural and interior design segments, where customization is a key value driver.
- Sustainable Sourcing:Developing and marketing product lines based on reclaimed wood or rapidly renewable timber species like bamboo offers a distinct competitive advantage. This strategy appeals to environmentally conscious consumers and specifiers in commercial green building projects.
Industry Challenges
- Timber Supply Chain Verification:Ensuring a consistent and legally verified supply of sustainable timber is a major operational challenge. Implementing robust chain-of-custody tracking to meet Forest Stewardship Council (FSC) or similar standards requires significant investment and logistical oversight.
- Installation Labor Scarcity:While click-lock systems aid DIY adoption, the professional installation of certain engineered wood and complex patterned floors requires skilled labor. A shortage of trained and certified installers can lead to project delays and impact brand reputation in the professional channel.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wood and Laminate Flooring Market |
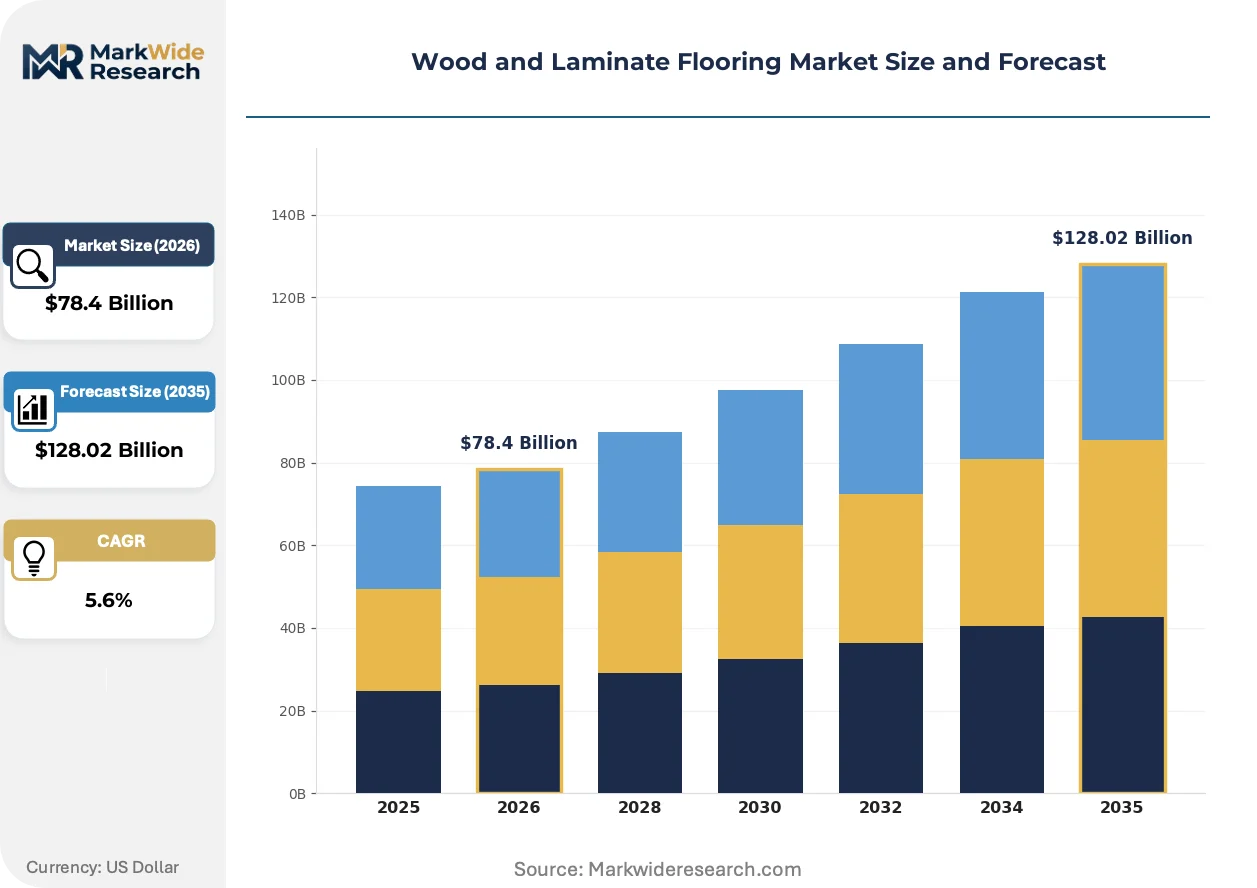
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $128.02 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid Wood, Engineered Wood, High-Pressure Laminate, Direct-Pressure Laminate, Bamboo Installation Method: Floating, Nail Down, Glue Down, Click Lock, Staple Down End Use Application: Residential Homes, Commercial Complexes, Educational Institutes, Healthcare Facilities, Recreational Centers Surface Finish: Matte, Glossy, Satin, Textured, Hand-Scraped |
| Companies Covered | Mannington Mills, Inc., Beaulieu International Group N.V., Mohawk Industries, Inc., EGGER Holzwerkstoffe GmbH, Kronospan Holding GmbH, Shaw Industries Group, Inc., Armstrong Flooring, Inc., Pergo, Tarkett S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wood and Laminate Flooring Market Strategic Shifts & Innovations
Material science advancements and digital technologies are fundamentally altering product capabilities and aesthetic possibilities. These innovations are a direct response to consumer and regulatory demands for flooring that is both visually appealing and environmentally responsible, pushing the boundaries of what composite materials can achieve.
Digital printing technology allows for the creation of high-fidelity photographic appliques for laminate flooring, perfectly replicating natural wood textures. High-end residential and bespoke commercial projects are adopting this for custom designs and unique visual effects. This innovation is collapsing the aesthetic gap between premium natural timber and top-tier laminate products, challenging traditional value perceptions in the market.
The European Union's Corporate Sustainability Reporting Directive (CSRD) is forcing greater transparency across supply chains. This regulation compels manufacturers to disclose detailed metrics on timber sourcing, embodied carbon, and end-of-life management. Engineered wood producers are most affected, now investing in lifecycle assessments and securing third-party certifications to prove compliance and maintain access to the European market.
A notable shift in buyer behavior is the prioritization of products with documented health and wellness credentials. This preference disrupts purchasing decisions based solely on aesthetics, giving an advantage to flooring with certifications like GREENGUARD for low chemical emissions. This is most prominent in the North American institutional sector, where schools and healthcare systems specify certified products to meet stringent indoor air quality mandates.
Wood and Laminate Flooring Market Segmentation
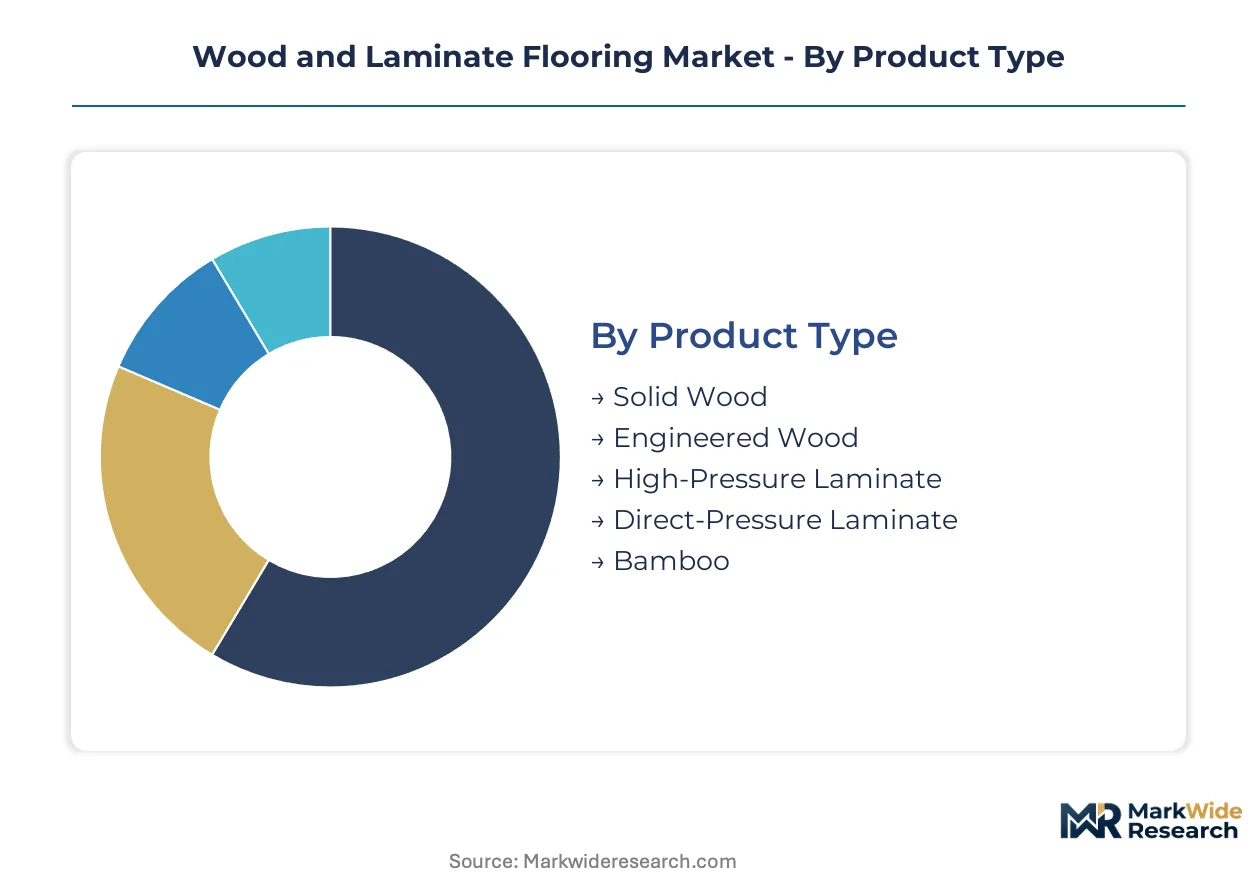
Market segmentation clarifies the diverse product offerings and consumer needs within the wood and laminate flooring industry. Understanding these distinct categories helps stakeholders identify targeted growth opportunities and tailor product development for specific end-use applications. This granular view reveals where innovation is most impactful and where established product types maintain dominance.
Product Type:
The product type dimension reflects a spectrum from established natural wood options to advanced composite materials. Each product serves distinct performance and aesthetic requirements across various price points.
- Engineered Wood:Composed of multiple wood layers bonded together, topped with a real wood veneer, offering enhanced stability against moisture and temperature fluctuations. Residential renovations in North America drive demand for its authentic appearance and reduced expansion properties.
- High-Pressure Laminate:Fabricated by fusing multiple layers under high pressure and temperature, featuring a durable melamine resin wear layer over a photographic design. Commercial complexes in rapidly urbanizing economies like India prefer its superior impact and scratch resistance.
- Solid Wood:Consists of single pieces of timber, providing a timeless aesthetic and the ability to be refinished multiple times over its lifespan.
- Direct-Pressure Laminate:Produced by pressing a decorative paper and protective overlay directly onto a core board, offering a cost-effective alternative to high-pressure variants.
- Bamboo:A rapidly renewable grass material processed into flooring planks, appealing to environmentally conscious consumers seeking sustainable options.
Engineered Wood handles the majority of throughput; High-Pressure Laminate is the fastest mover on share.
Installation Method:
Installation methods are primarily differentiated by their complexity, permanence, and suitability for various subfloor types. Ease of installation significantly influences adoption in the do-it-yourself segment.
- Click Lock:Features interlocking edges that snap together without adhesives or nails, making it highly suitable for DIY residential projects. Its widespread availability facilitates rapid project completion in North American households.
- Floating:Involves laying flooring planks over a subfloor without permanent attachment, allowing for natural expansion and contraction. This method is common for laminate products in European apartments due to its flexibility.
- Nail Down:Secures solid wood planks directly to a wooden subfloor using nails, providing a highly stable and traditional installation.
- Glue Down:Involves adhering flooring planks directly to the subfloor with a strong adhesive, suitable for both wood and laminate in high-traffic commercial settings.
- Staple Down:Utilizes staples to fasten engineered wood flooring to a wooden subfloor, offering a secure attachment method often preferred by professional installers.
Click Lock systems garner the highest volume of residential installations; Glue Down methods are expanding most quickly in commercial spaces.
End Use Application:
The market categorizes end-use applications based on the specific environmental demands and aesthetic preferences of different building types. Each sector requires distinct performance characteristics from flooring materials.
- Residential Homes:Encompasses single-family houses and multi-unit dwellings, primarily driven by renovation projects and new home construction. Consumer demand for authentic wood aesthetics and easy-to-install options shapes product choices in this segment.
- Commercial Complexes:Includes retail stores, offices, and hospitality venues, requiring flooring that withstands heavy foot traffic and offers superior durability. High-pressure laminate products with enhanced scratch resistance are frequently specified here.
- Educational Institutes:Specifies flooring solutions that are durable, easy to maintain, and contribute to healthy indoor air quality for classrooms and common areas.
- Healthcare Facilities:Demands sterile, low-VOC, and impact-resistant flooring suitable for hospitals, clinics, and long-term care environments.
- Recreational Centers:Requires robust and often water-resistant flooring for gyms, community centers, and sports facilities, balancing performance with safety.
Residential Homes consistently account for the largest share of flooring consumption; Commercial Complexes are climbing the fastest due to urban development.
Surface Finish:
Surface finishes dictate the aesthetic appeal, tactile quality, and durability of flooring, catering to diverse design preferences and functional needs. Each finish offers a unique visual and protective layer.
- Matte:Provides a low-sheen, natural wood appearance that effectively conceals minor scratches and imperfections. This finish is gaining favor in modern residential designs seeking understated elegance.
- Textured:Features an embossed surface that mimics the grain and feel of natural wood, enhancing realism and providing improved slip resistance. Architectural and interior design segments increasingly specify textured finishes for bespoke projects.
- Glossy:Delivers a high-shine, reflective surface that brightens spaces and offers a luxurious aesthetic, though it can highlight dust and scratches.
- Satin:Offers a medium sheen that balances the benefits of matte and glossy finishes, providing a subtle luster with moderate scratch concealment.
- Hand-Scraped:Characterized by an intentionally distressed, uneven surface that creates an aged, artisanal look, often found in rustic or traditional designs.
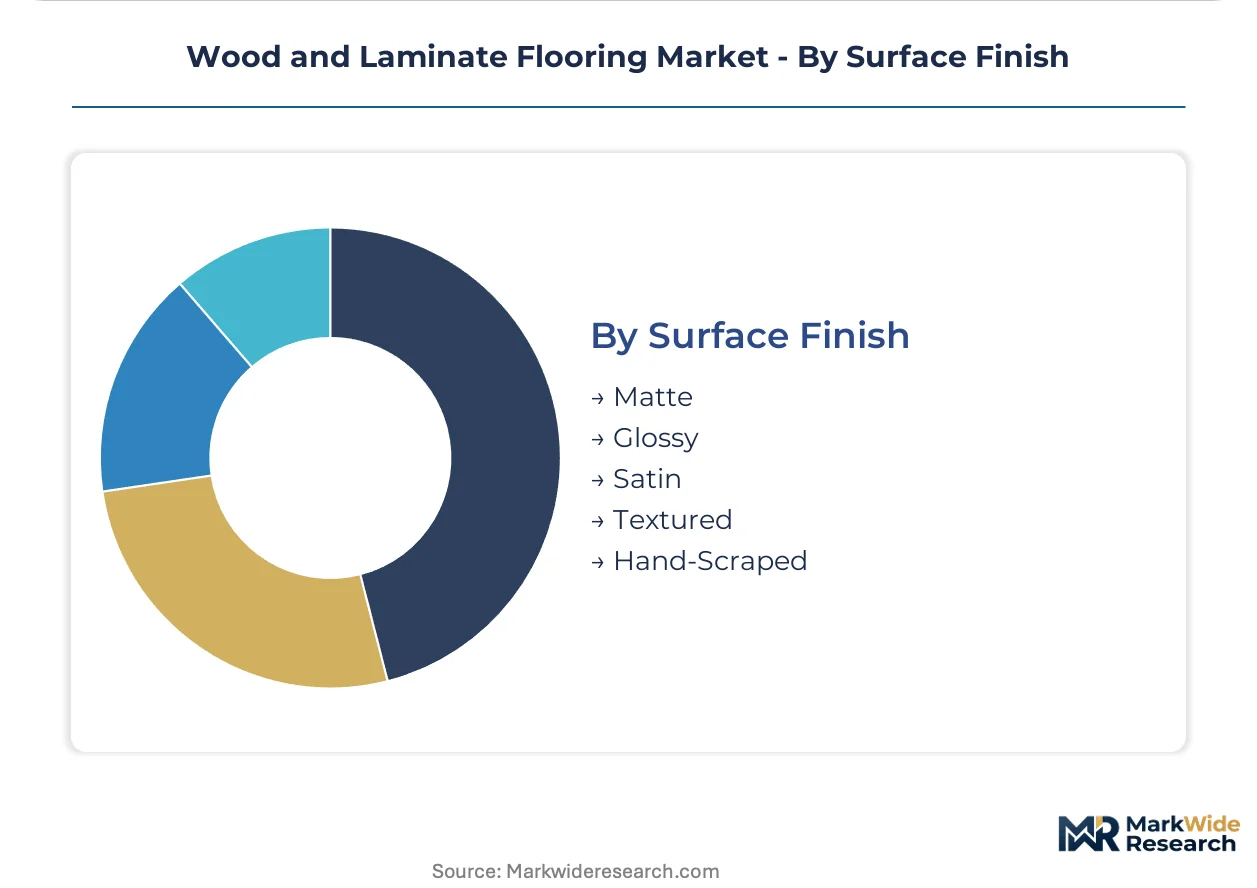
Matte finishes hold the largest share of current aesthetic preference; Textured finishes show the steepest expansion trajectory in new specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EPA's TSCA Title VI regulations in the United States significantly influence product development and market access for composite wood products globally. This regulatory environment, coupled with diverse regional construction trends, shapes demand for wood and laminate flooring across key geographies. Specific countries demonstrate unique market dynamics driven by local preferences, policy frameworks, and economic development stages.
United States
Residential renovation projects and new home construction heavily drive demand for engineered wood and laminate flooring in the United States. The EPA's formaldehyde emission standards under TSCA Title VI directly govern composite wood products sold domestically. Manufacturing and distribution hubs in states like Georgia and North Carolina continue to develop low-VOC product lines to meet evolving market specifications.
Germany
Demand for flooring in Germany centers on sustainable sourcing and high-performance, design-forward products. CE marking is mandatory for demonstrating compliance with European safety and environmental criteria for all flooring products. Manufacturers in North Rhine-Westphalia focus on innovation in low-VOC adhesives and environmentally certified timber supply chains.
India
High-growth construction markets and expanding middle-class housing segments stimulate demand for premium laminate and mid-range engineered wood products in India. The Bureau of Indian Standards (BIS) sets quality benchmarks for various construction materials. Major urban centers like Mumbai and Delhi experience rapid commercial and residential development, necessitating durable and cost-effective flooring solutions.
Vietnam
Expanded manufacturing capacity in Vietnam primarily serves export markets, narrowing the cost gap between laminate and certain engineered wood products. Local environmental regulations guide production processes and material sourcing for flooring manufacturers. Industrial zones near Ho Chi Minh City have become key centers for efficient, large-scale flooring production, attracting international investment.
Wood and Laminate Flooring Market Key Industry Players
Large-scale integrated manufacturers and specialized design-focused firms split the market for wood and laminate flooring. The competitive environment features both global conglomerates leveraging immense scale and agile niche players differentiating through product innovation. These players engage in diverse strategies, including geographic expansion to high-growth markets. Strategic partnerships for distribution and continuous capacity expansion remain common competitive moves.
On the scale-driven manufacturing vector, Mohawk Industries, Inc. and Shaw Industries Group, Inc. represent companies with extensive operational footprints. Mohawk Industries, Inc., as a global entity, influences pricing and material sourcing across multiple flooring segments. Shaw Industries Group, Inc. sustains its market position through robust distribution networks primarily in North America. Mannington Mills, Inc. exemplifies a design-forward approach, focusing on aesthetically driven products for the residential sector.
| Leading Market Players |
|---|
| Mannington Mills, Inc. |
| Beaulieu International Group N.V. |
| Mohawk Industries, Inc. |
| EGGER Holzwerkstoffe GmbH |
| Kronospan Holding GmbH |
| Shaw Industries Group, Inc. |
| Armstrong Flooring, Inc. |
| Pergo |
| Tarkett S.A. |
| Others |
Cost & Logistics Intelligence
Upstream concentration of specialty timber and melamine resin production creates persistent cost volatility for flooring manufacturers. This dynamic directly influences downstream product pricing and margin structures across the wood and laminate market.
Pricing Analysis
Price spreads across geographies reflect varying regulatory compliance costs and local market competition. The dominant pricing model is per-unit transactional, with larger commercial projects often operating on contract-based long-term agreements. Price differentiation stems from product type, brand reputation, and essential environmental certifications like CE marking. Pricing pressure intensifies from luxury vinyl tile substitution, particularly in water-prone residential areas. The DIY residential segment exhibits high price sensitivity, while commercial specifiers prioritize certified performance.
Supply Chain Analysis
Input cost volatility for melamine resins and specialty timber represents a primary supply chain risk. Manufacturing concentrates significantly in Vietnam, serving global export markets, while raw timber sourcing draws from diverse international regions. The supply chain relies heavily on consistent access to certified sustainable timber, driven by regulations like the EU's CSRD. Distribution runs through established networks, particularly in North America, with direct channels for large commercial projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wood and laminate flooring market is experiencing a cyclical recovery, primarily driven by a surge in residential renovation projects across North America and Europe. This upswing presents strategic opportunities for various market participants.
For Market Incumbents: Pre-empt further market share erosion from luxury vinyl tile by accelerating R&D into enhanced water-resistant laminate cores. Secure third-party environmental certifications like GREENGUARD and FSC to meet rising regulatory demands and green building specifications. Expand manufacturing capacity in strategic hubs like Vietnam to optimize cost structures and maintain competitive pricing. This mitigates margin pressure and reinforces brand reputation against emerging material threats.
For New Entrants and Emerging Players: Untapped demand in rapidly urbanizing economies, particularly India, offers a significant entry point for mid-range engineered wood. Focus on digital printing integration to offer hyper-realistic wood grains and custom patterns for the high-end architectural segment. Leverage sustainable sourcing of rapidly renewable timber like bamboo to appeal to environmentally conscious consumers. This strategy allows differentiation in a crowded market and captures specific consumer values.
For Investors and Strategic Acquirers: Capital is best deployed toward companies with robust R&D in low-VOC materials and verified sustainable timber supply chains. The long-term viability of this market depends on continuous innovation in composite materials and adaptation to evolving environmental regulations. Target acquisition profiles include manufacturers with strong intellectual property in digital printing or established distribution networks in high-growth construction markets. The signal to watch is the widespread adoption of GREENGUARD certified products in residential renovation projects.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Manufacturing in Vietnam | This move capitalizes on lower production costs to enhance competitiveness across export markets. |
| Invest in Low-VOC Product Development | This meets stringent regulatory standards like TSCA Title VI and appeals to health-conscious consumers. |
| Secure Sustainable Timber Certifications | This ensures compliance with EU's CSRD and attracts environmentally responsible specifiers. |
| Integrate Advanced Digital Printing | This enables customization and hyper-realistic aesthetics, appealing to high-end design segments. |
| Strengthen North American Distribution | This captures demand from the robust residential renovation and new construction sectors. |
Research Approach
Cross-validation between primary interviews and secondary data anchors the qualitative findings of this analysis. Interviews included R&D directors, procurement managers, and sales executives from leading flooring manufacturers, alongside residential contractors and commercial specifiers. Secondary validation drew from EPA formaldehyde emission standards, EU REACH regulations, BIS quality benchmarks, and relevant trade association reports. This approach ensured bottom-up and top-down triangulation of market insights.
The forecast framework calibrates market projections by integrating historical trends with anticipated shifts across the analysis window. Segmentation dimensions modeled include product type, installation method, end-use application, and surface finish. Compound Annual Growth Rates were derived from an assessment of historical performance and projected market dynamics. Key forecast inputs include global residential renovation spending and commercial construction starts.
The forecast holds incumbent behavior within observed patterns; aggressive moves by major manufacturers or rapid material science breakthroughs would shift outcomes. Projections reflect current regulatory landscapes, but unforeseen geopolitical events or rapid material substitution pose risks. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
China Engineered Wood Flooring Market
Flooring, Carpets, and Rugs
Bath Rugs and Mats Market
Flooring, Carpets, and Rugs
China Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Europe Carpet and Rugs Market
Flooring, Carpets, and Rugs
China Laminate Flooring Market
Flooring, Carpets, and Rugs
India Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Europe Carpet Tile Market
Flooring, Carpets, and Rugs
United States Floor Covering Market
Flooring, Carpets, and Rugs
Germany Resilient Flooring Market
Flooring, Carpets, and Rugs
India Floor Covering Market
Flooring, Carpets, and Rugs
Japan Floor Covering Market
Flooring, Carpets, and Rugs
Europe Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Resilient Flooring Market
Flooring, Carpets, and Rugs
US Vinyl Floorings Market
Flooring, Carpets, and Rugs
Stone Flooring Market
Flooring, Carpets, and Rugs
Brazil Floor Covering Market