
 Decorative Rugs Market | 2026-2036
Decorative Rugs Market Size, Share, and Industry Trends Forecast 2026-2036
Decorative Rugs Market Analysis
Premium hand-knotted specification tiers is rotating toward center stage as consumers trade up from machine-tufted alternatives. Mohawk Industries leverages integrated yarn-to-finished-goods operations across North American manufacturing footprints. Oriental Weavers anchors Egyptian production capacity for export into European and Middle Eastern distribution channels. Safavieh differentiates through design-forward collections that bridge traditional Persian motifs with contemporary interior palettes.
Decorative rugs are textile floor coverings constructed from wool, cotton, jute, or synthetic fibers through hand-knotting, hand-tufting, power-loom weaving, or braiding processes, typically measuring between 2x3 feet and 10x14 feet and serving both acoustic insulation and interior design functions in residential and commercial environments. Wool material segments sustain margin premiums due to durability perceptions and natural flame resistance, while synthetic material categories compete on price accessibility and stain-repellent performance. Hospitality end users represent the fastest-growing demand pool as hotel operators specify custom dimensions and branded colorways for property-wide installations.
EPA indoor air quality guidelines and California Proposition 65 chemical disclosure rules shape synthetic fiber and adhesive selection for US-market products, while REACH compliance in Europe restricts azo dyes and heavy metal treatments in imported collections. India's BIS certification requirements for textile labeling and fiber content disclosure create compliance thresholds for domestic manufacturers and importers alike. Stakeholders must monitor evolving chemical regulations across multiple jurisdictions while calibrating material sourcing strategies between natural fiber premiums and synthetic cost efficiency.
Market Dynamics
REACH chemical restrictions on azo dyes and heavy metal treatments are redirecting European procurement toward natural fiber alternatives, compressing synthetic rug margins while elevating wool and jute specifications across hospitality and residential channels.
Growth Catalysts
- Hospitality Renovation Cycles:Hotel chains in the United States and Middle East are specifying custom dimensions and branded colorways for property-wide installations, pulling premium hand-knotted volumes.
- REACH Compliance Pivot:European chemical disclosure rules are redirecting manufacturer investment toward natural dye processes and undyed wool collections that bypass synthetic formulation risks.
- Indian Artisan Cluster Expansion:Jaipur and Bhadohi weaving centers are scaling export capacity through integrated design-to-delivery pipelines that shorten lead times for North American and European buyers.
Market Restraints
- Wool Input Volatility:New Zealand and Australian wool auction prices fluctuate with drought cycles and Chinese import demand, compressing margin predictability for hand-knotted tier producers.
- Supply Concentration Risk:Egyptian power-loom capacity dominates middle-market synthetic exports, creating single-geography vulnerability for European and Middle Eastern distribution channels.
- Technical Performance Gaps:Natural fiber collections lack the stain-repellent chemistry and bleach-cleanable surfaces that synthetic PET and polypropylene alternatives deliver for commercial high-traffic environments.
Strategic Opportunities
- Underpenetrated Southeast Asian Markets:Indonesia and Vietnam hospitality construction is accelerating without established local rug supply chains, creating first-mover positioning for Indian and Turkish exporters.
- EU Green Deal Procurement Mandates:Public building renovation funding tied to circular economy criteria favors recyclable natural fiber specifications and take-back program integration.
- Digital-Physical Design Convergence:AI-assisted pattern generation combined with small-batch digital printing on wool substrates is compressing custom collection development from months to weeks.
Industry Challenges
- Master Weaver Talent Scarcity:Knot-density specialization in Bhadohi and Kashmir requires decade-long apprenticeship pipelines that younger workers are abandoning for urban manufacturing wages.
- Multi-Jurisdiction Certification Timelines:Simultaneous EPA indoor air quality, California Proposition 65, and BIS fiber-content compliance creates six-to-nine month product launch delays for cross-border collections.
- Legacy Inventory Integration:Wholesale distributors hold machine-tufted synthetic stock purchased under prior chemical formulations that now face restricted resale in European markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Decorative Rugs Market |
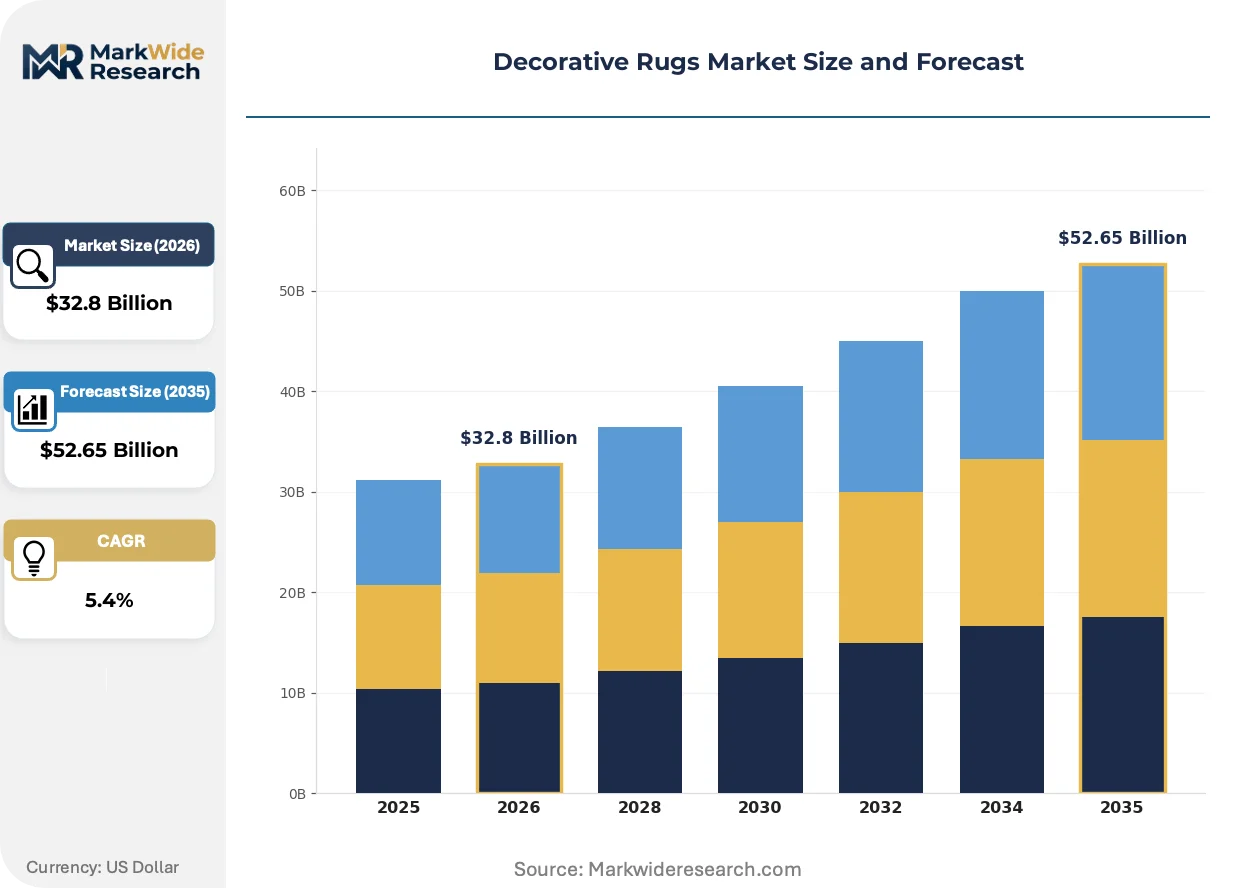
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $52.65 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Persian, Shag, Braided, Outdoor Material: Wool, Cotton, Jute, Synthetic Style: Modern, Vintage, Bohemian, Minimalist End User: Residential, Commercial, Hospitality, Others |
| Companies Covered | Mohawk Industries, Shaw Industries, Oriental Weavers, Safavieh, Nourison, Balta Group, Loloi Rugs, Milliken, Interface, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Decorative Rugs Market Emerging Trajectories
Digital design tools and regulatory chemistry constraints are converging to reshape how collections are developed, certified, and brought to market across natural and synthetic fiber categories.
Micro-dye precision technology is miniaturizing color application control to individual knot levels, enabling photographic-detail reproduction on hand-tufted wool substrates. Boutique hospitality designers in California and New York are specifying these collections for statement installations. The technology is compressing minimum order quantities from hundreds to single-piece custom runs without pattern repeat constraints.
REACH authorization lists now restrict over two thousand chemical substances in textile finishing, forcing reformulation of synthetic fiber mothproofing and stain-blocking treatments. German and French importers are demanding OEKO-TEX and GOTS certification documentation at purchase order stage. Natural fiber suppliers with pre-existing undyed inventory are capturing specification share from synthetic competitors facing twelve-to-eighteen month chemical re-registration timelines.
Direct-to-designer e-commerce platforms are disintermediating traditional wholesale showroom networks for commercial project specification. Interior design firms in Texas and Florida are sourcing full collection libraries through virtual sampling and augmented-reality room visualization tools. India-based manufacturers with dedicated North American logistics nodes are capturing project-level volume that previously flowed through regional distributor inventories.
Decorative Rugs Market Segmentation
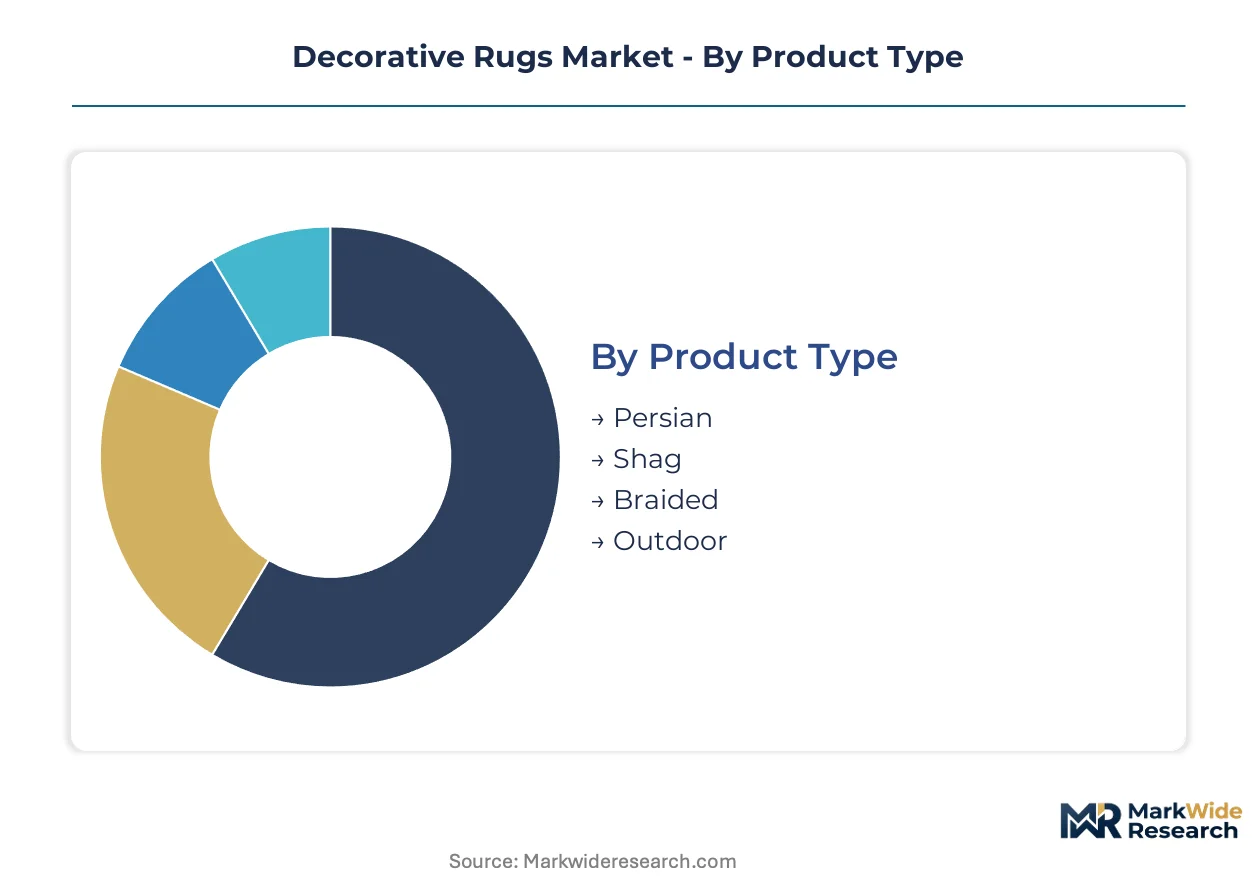
Segmentation in decorative rugs determines compliance pathways, margin structures, and specification authority across divergent procurement channels. Material chemistry and end-use durability requirements create non-overlapping supply chains that reshape competitive positioning.
Product Type:
REACH restrictions on synthetic dyes and California Proposition 65 disclosure rules split specification authority between hand-knotted heritage formats and machine-finished alternatives.
- Persian:Hand-knotted wool constructions with knot densities exceeding 100 knots per square inch command specification in luxury residential and boutique hospitality. EPA indoor air quality guidelines favor natural fiber Persian collections for US premium channels over synthetic alternatives requiring chemical disclosure.
- Shag:High-pile constructions in wool or synthetic blends deliver acoustic dampening for residential media rooms and commercial lounge environments. Demand concentrates in US coastal metros where design-forward consumers prioritize tactile texture over pattern complexity.
- Braided:Jute and cotton spiral constructions serve price-accessible residential entryways and casual living spaces.
- Outdoor:Solution-dyed synthetic fibers resist UV degradation and moisture absorption for patio and poolside installations.
Established volume favors Persian collections; emerging adoption favors Outdoor specifications.
Material:
Cost tier stratification separates natural fiber premiums from synthetic accessibility, with regulatory chemistry constraints redirecting procurement toward undyed wool and jute alternatives.
- Wool:New Zealand and Australian auction-sourced fibers provide inherent flame resistance and soil hiding for hospitality and premium residential. REACH authorization lists restrict over two thousand textile finishing substances, elevating undyed wool specifications that bypass synthetic mothproofing and stain-blocking reformulation timelines.
- Synthetic:PET and polypropylene extrusions deliver bleach-cleanable surfaces and stain-repellent performance for commercial high-traffic environments. Egyptian power-loom capacity anchors middle-market supply for European and Middle Eastern distribution channels.
- Cotton:Flat-weave constructions serve washable residential applications and price-sensitive commercial specifications.
- Jute:Bast fiber constructions provide biodegradable, low-cost alternatives for eco-conscious residential and hospitality staging.
Margin concentration sits with Wool; volume expansion tracks with Synthetic.
Style:
Customer type differentiation separates heritage-motif collectors from palette-driven contemporary specifiers, with digital design tools compressing collection development cycles.
- Modern:Geometric abstraction and solid-color fields align with minimalist interior architecture in US and European urban centers. AI-assisted pattern generation enables small-batch customization for designer-direct procurement channels.
- Vintage:Distressed finishes and reproduction patinas serve residential collectors seeking heritage aesthetic without antique acquisition costs.
- Bohemian:Eclectic pattern mixing and saturated colorways target younger residential demographics in Texas and Florida markets.
- Minimalist:Neutral palettes and reduced visual weight complement Scandinavian-influenced commercial and residential interiors.
Designer specification authority concentrates in Modern; retail velocity favors Vintage.
End User:
Application durability requirements and procurement scale separate fragmented residential demand from concentrated hospitality volume.
- Hospitality:Hotel chains in the United States and Middle East specify custom dimensions and branded colorways for property-wide installations. Custom collection development integrates with renovation cycles that pull premium hand-knotted volumes from Indian and Turkish supply chains.
- Residential:Fragmented individual and designer-directed procurement spans price tiers from machine-tufted synthetics to investment-grade hand-knotted pieces.
- Commercial:Office and retail specifications prioritize stain-repellent performance and rapid replacement cycles over longevity.
- Others:Institutional and educational procurement channels favor cost-minimized synthetic specifications with standardized dimensions.
Volume scale favors Residential; margin expansion tracks with Hospitality.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances tilt toward deficit in Western markets while Asian production clusters capture outbound volume. India and Turkey ship finished hand-knotted collections to North American and European distribution channels. Egyptian power-loom capacity anchors middle-market synthetic supply for Middle Eastern and European buyers.
United States
Hospitality renovation cycles in Texas and Florida pull premium hand-knotted volumes from Indian supply chains. EPA indoor air quality guidelines and California Proposition 65 chemical disclosure rules reshape synthetic fiber and adhesive selection for domestic-market products. Design-forward consumers in coastal metros concentrate demand for tactile shag constructions and AI-assisted custom patterning.
Germany
REACH authorization lists now restrict over two thousand chemical substances in textile finishing, forcing reformulation of synthetic fiber treatments. OEKO-TEX and GOTS certification documentation is demanded at purchase order stage by importers in Frankfurt and Munich distribution corridors. Undyed wool specifications from Jaipur and Bhadohi are capturing specification share from synthetic competitors facing extended chemical re-registration timelines.
India
Jaipur and Bhadohi weaving centers scale export capacity through integrated design-to-delivery pipelines that compress lead times for North American and European buyers. BIS certification requirements for textile labeling and fiber content disclosure create compliance thresholds for domestic manufacturers and importers. Master weaver talent scarcity in Kashmir threatens knot-density specialization pipelines as younger workers abandon decade-long apprenticeships for urban manufacturing wages.
Egypt
Power-loom capacity dominates middle-market synthetic exports for European and Middle Eastern distribution channels. REACH compliance pressures on azo dyes redirect some procurement toward natural fiber alternatives, compressing synthetic margins. Cairo and Alexandria industrial zones face single-geography vulnerability concerns as buyers diversify sourcing toward Turkish and Indian alternatives.
United Arab Emirates
Dubai and Abu Dhabi hospitality construction specifies custom dimensions and branded colorways for property-wide installations. Hotel operators in the Emirates pull premium collections from Turkish and Indian supply chains for renovation cycles. MOHAP chemical safety standards for imported textiles create documentation requirements that favor established exporters with pre-certified natural fiber inventories.
Decorative Rugs Market Vendor Landscape
Listed leaders compete with private specialists across capital access and design agility dimensions. Publicly traded flooring conglomerates with integrated yarn-to-finished-goods operations hold scale advantages in synthetic fiber extrusion and power-loom throughput. Private specialists anchor premium hand-knotted tiers through direct artisan relationships and small-batch customization capabilities. Strategic moves concentrate on backward integration into captive wool sourcing and digital design tool deployment.
Among North American flooring conglomerates, Mohawk Industries and Shaw Industries exemplify scale-driven archetypes with integrated manufacturing footprints. Oriental Weavers anchors Egyptian production capacity for export-oriented supply. Safavieh occupies a position bridging traditional Persian motifs with contemporary interior palettes through design-forward collections.
| Leading Market Players |
|---|
| Mohawk Industries |
| Shaw Industries |
| Oriental Weavers |
| Safavieh |
| Nourison |
| Balta Group |
| Loloi Rugs |
| Milliken |
| Interface |
| Others |
Supply Flow & Price Mechanics
Ninety-day inventory cycles for hand-knotted wool collections from Jaipur and Bhadohi anchor pricing power for Indian artisan clusters, compressing synthetic alternatives while elevating natural fiber premiums across hospitality procurement channels.
Pricing Analysis
Hospitality buyers anchor three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on knot-density certification and REACH-compliant natural dye documentation. Cost compression in synthetic tiers is intensifying because Egyptian power-loom capacity faces azo dye reformulation timelines. Residential consumers in Texas and Florida show highest price sensitivity, while Middle Eastern hotel operators accept premium positioning for custom dimensions.
Supply Chain Analysis
Strait of Hormuz transit underwrites Middle Eastern hospitality logistics, concentrating risk exposure for Turkish and Indian exporters serving Dubai and Abu Dhabi renovation cycles. Raw material dependencies draw from New Zealand wool auctions, Egyptian PET extrusion, and Indian cotton spinning. Single-geography vulnerability sits with Egyptian power-loom synthetic output. Distribution runs through North American wholesale showrooms and direct-to-designer e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospitality renovation cycles signal early-cycle expansion, with custom specification penetration accelerating as hotel chains prioritize branded interiors over commodity replacements.
For Market Incumbents: Compound design-to-delivery integration through AI-assisted pattern generation and captive logistics nodes in Texas and Florida. Backward integration into New Zealand wool sourcing defends margin position against auction volatility. OEKO-TEX certification investment creates compliance moats as REACH restrictions expand. For New Entrants and Emerging Players: Differentiate on micro-dye precision technology for single-piece custom runs targeting California and New York boutique hospitality designers. Underpenetrated Indonesian and Vietnamese hospitality construction offers first-mover positioning. Direct-to-designer e-commerce bypasses entrenched wholesale networks. For Investors and Strategic Acquirers: Long-term, this sits as a brand-arbitrage play because design-forward collections command specification authority over commodity synthetics. Target private specialists with direct artisan relationships in Bhadohi and Kashmir. Watch master weaver apprenticeship pipeline collapse as inflection signal for supply-constrained premium tier repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wool Sourcing | Captive New Zealand and Australian auction access stabilizes input costs for hand-knotted tiers. |
| AI-Assisted Pattern Generation Deployment | California and New York designers compress custom development timelines from months to weeks. |
| Direct-to-Designer E-Commerce Launch | Texas and Florida interior firms bypass traditional wholesale showroom networks for project volume. |
| REACH-Compliant Natural Dye Reformulation | German and French importers demand OEKO-TEX documentation at purchase order stage. |
| Southeast Asian Logistics Node Establishment | Indonesian and Vietnamese hospitality construction lacks established local supply chains. |
Methodological Framework
Desk research of customs trade records, hospitality procurement databases, and BIS certification filings preceded structured interviews with master weavers, hotel FF&E directors, and North American wholesale distributors. Primary fieldwork with Jaipur and Bhadohi artisan clusters validated secondary capacity estimates. Bottom-up shipment data triangulated against top-down hospitality construction pipelines.
Variance decomposition across material chemistry, end-use durability requirements, and geographic regulatory clusters shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include product construction method, fiber content tier, style archetype, and procurement channel type. CAGRs derived from shipment volume trajectories and specification mix shifts, with wool auction price cycles and REACH authorization list updates as key inputs.
The analysis sits within stated boundaries; outcomes outside sustained hospitality renovation spending or accelerated REACH chemical restrictions would require recalibration. Practitioners should keep alternative scenarios live as master weaver talent availability and synthetic dye reformulation timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
Stone Flooring Market
Flooring, Carpets, and Rugs
Textured Variegates Market
Flooring, Carpets, and Rugs
Saudi Arabia Vinyl Flooring Market
Flooring, Carpets, and Rugs
United Kingdom Floor Covering Market
Flooring, Carpets, and Rugs
Turkey Carpet and Rugs Market
Flooring, Carpets, and Rugs
Resilient Flooring Market
Flooring, Carpets, and Rugs
Asia-Pacific Floor Covering Market
Flooring, Carpets, and Rugs
GCC Floor Covering Market
Flooring, Carpets, and Rugs
Saudi Arabia Carpet and Rugs Market
Flooring, Carpets, and Rugs
Egypt Floor Covering Market
Flooring, Carpets, and Rugs
North America Laminate Flooring Market
Flooring, Carpets, and Rugs
India Carpets and Rugs Market
Flooring, Carpets, and Rugs
Europe Flooring Market
Flooring, Carpets, and Rugs
United Kingdom Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Wood and Laminate Flooring Market
Flooring, Carpets, and Rugs
Area Rugs Market