
 Carpets and Rugs Market | 2026-2036
Carpets and Rugs Market Size, Share, and Industry Trends Forecast 2026-2036
Carpets and Rugs Market Analysis
Polyester fiber is decoupling from petroleum price volatility as recycled PET feedstock scales across major production corridors. Mohawk Industries leverages captive recycling infrastructure to stabilize input costs across its residential portfolio. Shaw Industries Group anchors its position through extensive extrusion capacity in the American Southeast. Interface differentiates via closed-loop manufacturing systems that reclaim post-consumer nylon for commercial carpet tile programs.
Carpets and rugs are textile floor coverings manufactured through tufting, weaving, or needle-felting processes, typically constructed with pile yarns bonded to primary and secondary backing layers using latex or thermoplastic adhesives, designed to provide thermal insulation, acoustic dampening, and aesthetic surface finishing in interior environments. Nylon segments command premium positioning in commercial applications due to superior resilience and stain resistance under heavy foot traffic. Wool retains structural importance in hospitality and luxury residential channels where natural fiber credentials support sustainability narratives. Polyester captures volume leadership in mass-market residential applications through cost-efficient production and broad color availability.
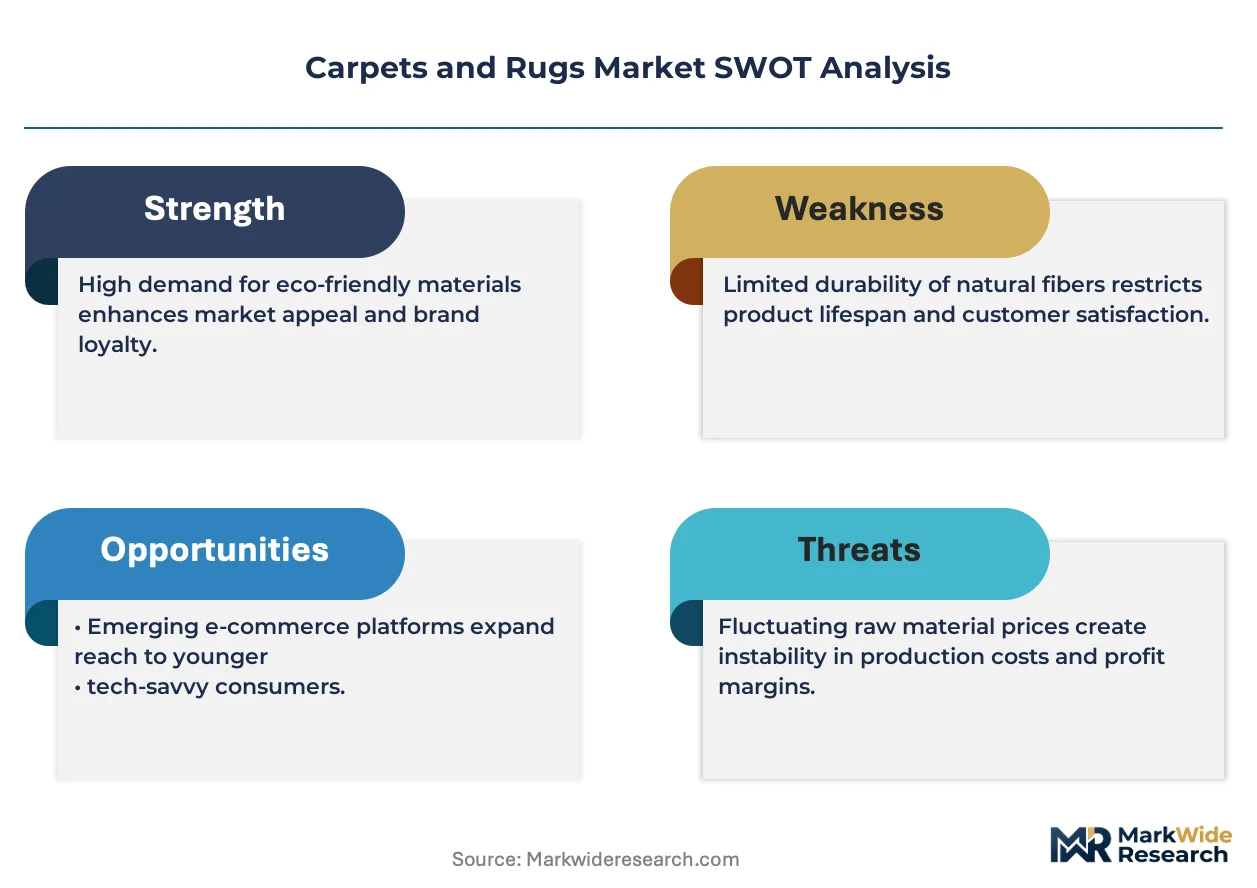
The EPA regulates volatile organic compound emissions from carpet adhesives and backing materials under indoor air quality frameworks, while REACH restricts hazardous substance use in European-manufactured products, and California's Department of Public Health maintains stringent emission standards through its Section 01350 protocol. These overlapping compliance requirements elevate testing and certification costs for cross-border suppliers while creating specification advantages for manufacturers with verified low-emission product lines. Stakeholders must monitor evolving chemical restriction schedules and building certification alignment to preserve specification access across major procurement channels.
Market Dynamics
REACH chemical restrictions and the EU Green Deal are forcing wholesale reformulation of carpet adhesives and backing materials, compressing margins for suppliers lacking bio-based alternatives while rewarding early movers with verified low-emission product lines.
Growth Catalysts
- Hospitality refurbishment cycles:Hotel and cruise line operators in the United States are accelerating specification-grade carpet replacements as post-pandemic travel demand normalizes.
- REACH compliance advantages:Manufacturers with pre-certified low-VOC product lines capture specification access across European commercial procurement channels.
- Recycled PET feedstock scaling:Polyester fiber production is decoupling from petroleum volatility as mechanical recycling infrastructure expands across major manufacturing corridors.
Market Restraints
- Petroleum-linked input costs:Nylon 6,6 resin prices remain tethered to benzene derivatives, exposing producers to energy market swings.
- Chinese manufacturing concentration:Tufting equipment and synthetic fiber supply chains cluster in Zhejiang and Jiangsu provinces, creating single-source vulnerabilities.
- Hard flooring substitution:Luxury vinyl tile and engineered wood products capture residential square footage in moisture-prone applications.
Strategic Opportunities
- Indian commercial construction:Office and retail development in Mumbai and Bangalore is outpacing domestic carpet manufacturing capacity.
- Take-back program mandates:Extended producer responsibility frameworks in Germany and France reward closed-loop reclamation infrastructure.
- Digital textile printing convergence:Piezoelectric inkjet systems combined with solution-dyed yarns enable micro-batch customization for hospitality specifiers.
Industry Challenges
- Certification timeline compression:California Section 01350 and LEED v4.1 alignment requires parallel testing protocols that extend product launch cycles.
- Skilled tufting technician scarcity:Experienced loom operators in the American Southeast are aging out faster than apprenticeship programs replenish the workforce.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carpets and Rugs Market |
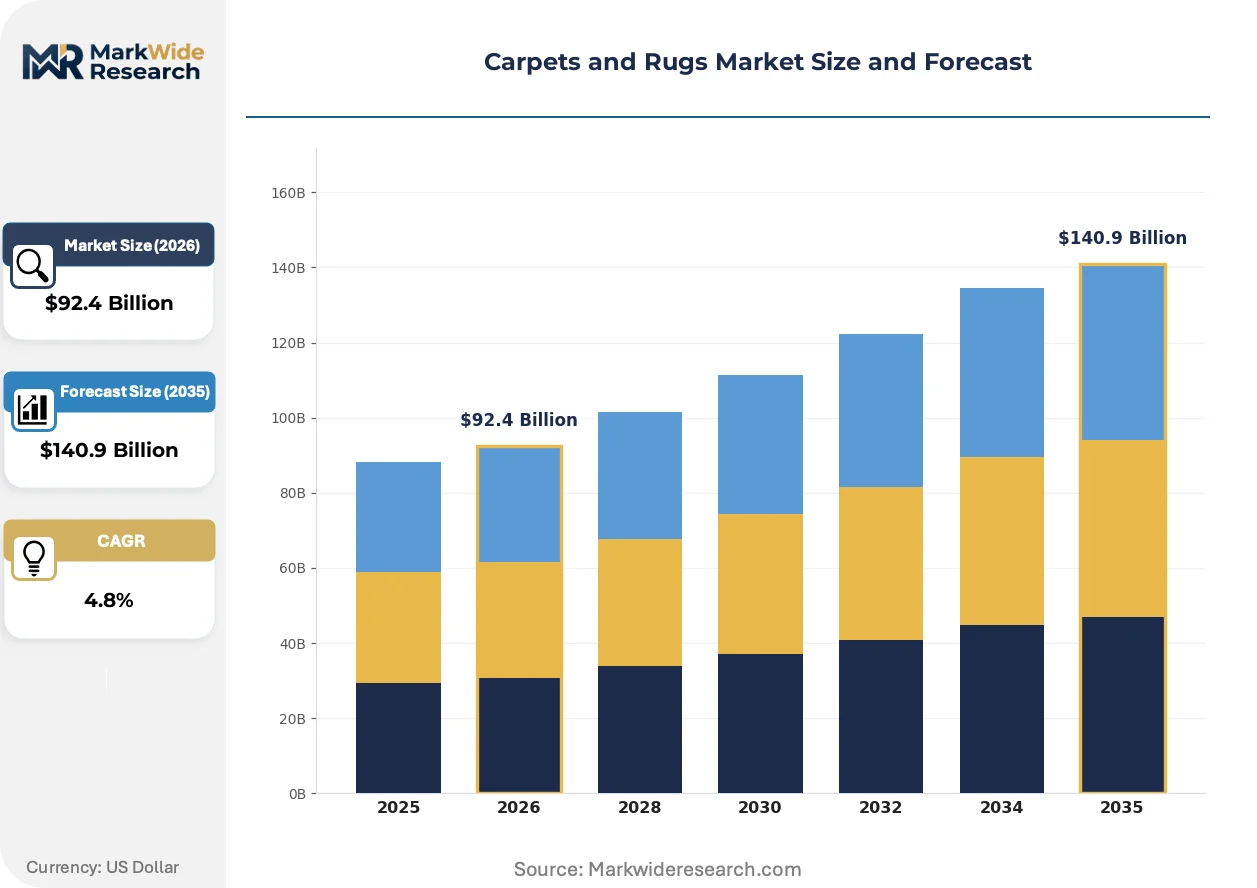
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $140.9 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Wool, Nylon, Polyester, Jute Application: Residential, Commercial, Hospitality, Automotive Style: Modern, Traditional, Shag, Oriental Size: Small, Medium, Large, Custom |
| Companies Covered | Mohawk Industries, Shaw Industries Group, Interface, Beaulieu International Group, Oriental Weavers, Tarkett Group, The Dixie Group, Balta Industries, Milliken & Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carpets and Rugs Market Emerging Trajectories
Digital manufacturing and closed-loop material systems are compressing production lead times while regulatory pressure on embodied carbon intensifies specification criteria across commercial channels.
Solution-dyed polyester extrusion with integrated colorant injection is automating batch consistency control while eliminating post-tufting dyeing stages. Hospitality specifiers in Dubai and Singapore are specifying these systems for rapid-turn renovation projects. The technology is automating quality assurance protocols that previously required manual shade-matching labor.
REACH Annex XVII restrictions on phthalate plasticizers and heavy metal pigments are redirecting adhesive formulations toward bio-based polyurethane alternatives. German and Dutch manufacturers face accelerated compliance deadlines compared to southern European counterparts. Commercial carpet tile programs in France and Belgium are prioritizing ECHA-registered supply chains to maintain public procurement eligibility.
Specifiers are consolidating vendor relationships around full-service reclamation partners who manage removal, transport, and recycling of post-consumer carpet. Facility managers in California and New York are bundling installation and end-of-life service into single-source contracts. This consolidation pattern is most visible in Class A office repositioning projects where LEED waste diversion credits influence contractor selection.
Carpets and Rugs Market Segmentation
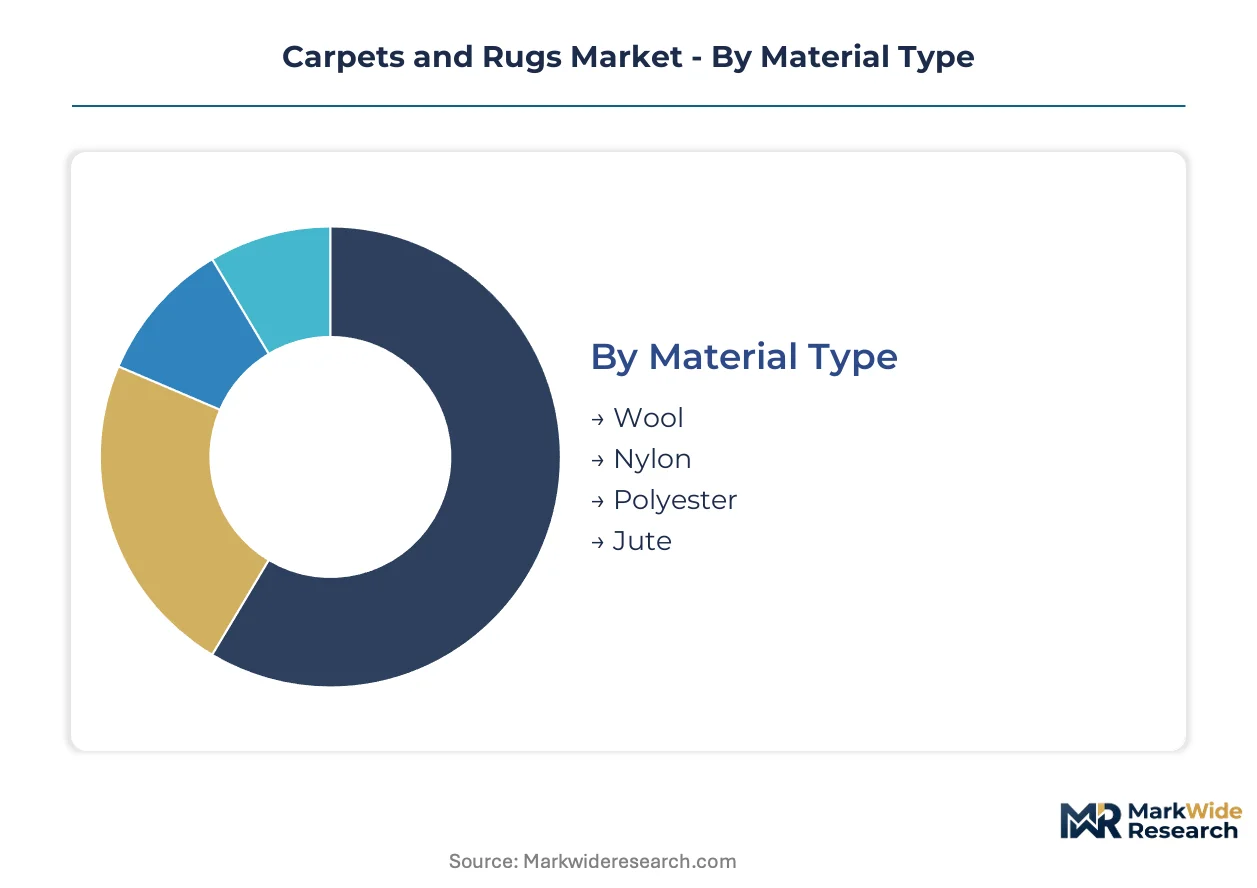
Carpet segmentation reveals divergent supply chain configurations across material inputs and end-use channels. Specification requirements in hospitality and commercial verticals create premium tiers distinct from mass-market residential production.
Material Type:
Wool and nylon anchor specification-grade applications where performance certification commands price premiums; polyester and jute serve cost-sensitive and sustainability-positioned segments respectively.
- Wool:Natural protein fiber with inherent flame resistance and moisture-regulating properties. Hospitality procurement in Germany and France prioritizes wool for luxury hotel lobbies where biogenic carbon credentials satisfy EPD requirements under EU Green Deal frameworks.
- Nylon:Polyamide 6 and 6,6 polymers deliver superior resilience and stain resistance under heavy foot traffic. Commercial office specifications in the United States concentrate on solution-dyed nylon for open-plan environments requiring extended replacement cycles.
- Polyester:Recycled PET feedstock enables cost-efficient bulk production with broad color gamut availability.
- Jute:Bast fiber from Corchorus plants serves backing substrates and natural-fiber surface coverings.
Polyester leads volumes today; wool is gaining share fastest in premium commercial specifications.
Application:
End-use channels separate stock-keeping residential programs from project-based commercial and hospitality specifications with custom dye-matching requirements.
- Residential:Mass-market tufted broadloom and area rugs distributed through home center and e-commerce channels. Builder specifications in the American Southeast favor polyester cut-pile for tract housing installations where first-cost optimization dominates procurement.
- Commercial:Carpet tile and broadloom systems engineered for LEED v4.1 compliance and extended wear warranties. Facility managers in California bundle installation with reclamation services to capture waste diversion credits.
- Hospitality:Custom patterning and rapid-turn production for hotel renovation cycles.
- Automotive:Molded carpet assemblies for passenger compartment and trunk applications.
Residential channels dominate unit volumes; hospitality specifications are climbing the fastest as refurbishment cycles accelerate.
Style:
Aesthetic positioning determines tufting density, pattern complexity, and distribution channel alignment across consumer and contract markets.
- Modern:Clean lines and geometric patterns align with contemporary interior design specifications. Commercial specifiers in Singapore and Dubai specify modern styles for technology sector office fit-outs where minimal visual noise supports workplace productivity metrics.
- Traditional:Classic motifs and border treatments persist in residential replacement demand. Midwestern United States markets maintain preference for traditional patterns in owner-occupied housing where longevity of design reduces redecorating frequency.
- Shag:High-pile cut fiber constructions targeting residential accent and comfort applications.
- Oriental:Hand-knotted and power-loomed reproductions of classical Persian and Asian designs.
Modern styling leads specification activity today; traditional patterns retain the steadiest replacement demand.
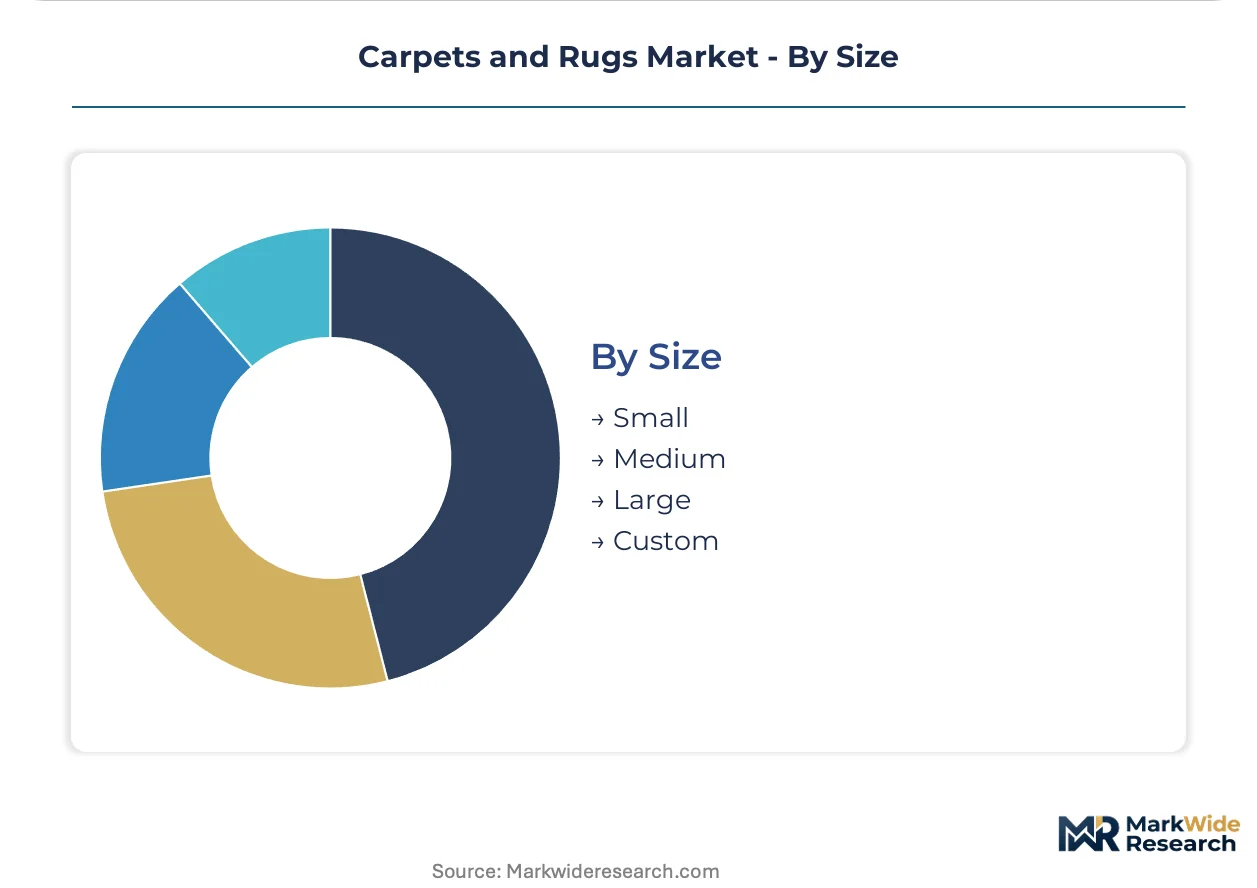
Size:
Dimensional categories separate stock-keeping units from project-engineered systems with field-measured installation requirements.
- Small:Area rugs under 6x9 feet for residential accent and hospitality guest room applications. E-commerce fulfillment centers in the United States stock small sizes for direct-to-consumer replacement cycles.
- Medium:Standard room dimensions serving residential wall-to-wall and commercial modular installations.
- Large:Broadloom rolls and oversized custom pieces for ballroom, atrium, and executive suite specifications.
- Custom:Field-measured and digitally patterned installations for irregular geometries and branded environments.
Medium sizes command the broadest distribution today; custom specifications are expanding most quickly in branded hospitality environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Zhejiang-Jiangsu manufacturing corridor anchors global tufting equipment and synthetic fiber supply chains, concentrating production infrastructure for both domestic consumption and export markets across residential and commercial segments.
United States
Post-pandemic hospitality refurbishment cycles in Las Vegas and Miami are accelerating specification-grade carpet replacements. EPA indoor air quality frameworks regulate VOC emissions from adhesives and backing materials. The American Southeast hosts extensive extrusion capacity where producers stabilize input costs through captive recycling infrastructure.
China
Urban residential construction in Shanghai and Shenzhen sustains volume demand for polyester broadloom and area rugs. MEE oversight of chemical emissions influences adhesive formulation choices among manufacturers. The Yangtze River Delta clusters tufting equipment suppliers and synthetic fiber production for domestic and export markets.
Germany
Commercial office repositioning in Berlin and Frankfurt drives carpet tile specifications aligned with LEED waste diversion credits. REACH Annex XVII restrictions on phthalate plasticizers redirect adhesive formulations toward bio-based polyurethane alternatives. The North Rhine-Westphalia region concentrates reclamation infrastructure serving extended producer responsibility frameworks.
India
Office and retail development in Mumbai and Bangalore is outpacing domestic carpet manufacturing capacity. BIS quality standards shape import requirements for synthetic fiber inputs. The Gujarat corridor hosts emerging tufting operations targeting hospitality and commercial specifications for Middle East export.
France
Public procurement eligibility requirements prioritize ECHA-registered supply chains for carpet tile programs in Paris and Lyon. EU Green Deal frameworks elevate biogenic carbon credentials in hospitality specifications. The Hauts-de-France region maintains traditional wool processing capacity serving luxury hotel channel demand.
Carpets and Rugs Market Vendor Landscape
Capacity expansion dominates the current landscape as manufacturers scale mechanical recycling infrastructure to decouple polyester fiber from petroleum price volatility. The market structures around three tiers: integrated multinationals with captive raw material supply, regional specialists concentrating on hospitality custom specifications, and private-label suppliers serving mass-market residential channels. M&A activity targets reclamation network assets, while portfolio diversification into carpet tile systems separates commercial-grade competitors from residential-only operators.
Among integrated North American manufacturers, Mohawk Industries and Shaw Industries Group exemplify the scale-driven archetype through upstream control over recycling and extrusion infrastructure. Interface occupies a distinct position within the closed-loop manufacturing tier, reclaiming post-consumer nylon for commercial carpet tile programs. These three anchors represent divergent strategic responses to regulatory pressure on embodied carbon and chemical emissions across specification channels.
| Leading Market Players |
|---|
| Mohawk Industries |
| Shaw Industries Group |
| Interface |
| Beaulieu International Group |
| Oriental Weavers |
| Tarkett Group |
| The Dixie Group |
| Balta Industries |
| Milliken & Company |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap specialists in Belgium and northern Italy anchor premium wool processing, wielding pricing discipline through generational supplier relationships while resisting margin compression from petroleum-linked synthetic fiber volatility. Their concentrated ownership structures enable long-term contract pricing with hospitality specifiers that integrated multinationals cannot match, creating a bifurcated market where artisan credentials command sustainable premiums.
Pricing Analysis
Input-cost pass-through from benzene-derived nylon 6,6 resin and recycled PET bale prices dominates pricing dynamics across specification tiers. Three-tier pricing structure across premium, standard, and economy levels separates solution-dyed nylon with LEED certification from commodity polyester broadloom and builder-grade tract housing products. Cost compression in mass-market residential channels is intensifying because Chinese polyester extrusion capacity expansion outpaces Western mechanical recycling scale-up. Home center buyers exhibit highest price sensitivity, while hospitality procurement teams prioritize lifecycle cost and waste diversion credits over first-cost optimization.
Supply Chain Analysis
Regional distribution centers in Dalton, Georgia and Tielt, Belgium operate hub-and-spoke patterns feeding installer networks across North American and European commercial corridors. Manufacturing concentrates in China, the United States, and Belgium, with the Zhejiang-Jiangsu corridor dominating tufting equipment and synthetic fiber supply. Raw material dependencies center on caprolactam for nylon polymerization, post-consumer PET flake for polyester extrusion, and jute bast from Bangladesh and India for natural-fiber backings. Single-source vulnerability clusters in Zhejiang province tufting machinery suppliers, where equipment lead times feed from concentrated production. Distribution runs through specification house networks for commercial projects and big-box retail for residential replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where REACH compliance investments in Germany and France create specification access premiums unavailable to late-adopting southern European competitors. The regulatory cost differential between early-certification markets and lagging regions rewards preemptive formulation reformulation.
For Market Incumbents: Extend reclamation network coverage through acquisition of regional carpet removal contractors in California and New York, bundling installation with end-of-life service to lock out competitors from LEED waste diversion credit capture. Invest in captive mechanical recycling capacity for polyester extrusion to decouple from petroleum price volatility threatening margin stability in residential portfolios. Hard flooring substitution in moisture-prone applications demands defensive positioning through performance warranty differentiation. For New Entrants and Emerging Players: Capture white-space in Indian commercial construction where office and retail development in Mumbai and Bangalore outpaces domestic carpet manufacturing capacity. Target hospitality specification channels in Dubai and Singapore demanding rapid-turn digital textile printing capabilities that incumbent broadloom manufacturers cannot fulfill. Lead with piezoelectric inkjet systems combined with solution-dyed yarns enabling micro-batch customization for renovation cycles. For Investors and Strategic Acquirers: Valuations sit cheapest among regional reclamation network operators lacking closed-loop extrusion integration but holding critical waste diversion relationships with Class A office facility managers. Long-term viability over the coming decade rests on mechanical recycling infrastructure ownership as extended producer responsibility frameworks harden across Germany and France. Watch for California Section 01350 alignment deadlines compressing product launch cycles as the inflection signal favoring pre-certified low-VOC inventory holders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycling Infrastructure | Mohawk Industries stabilizes polyester input costs through captive PET mechanical recycling capacity in the American Southeast. |
| Bio-based Adhesive Formulation | German manufacturers redirect toward polyurethane alternatives to maintain ECHA-registered supply chain eligibility under REACH Annex XVII. |
| Digital Textile Printing Convergence | Piezoelectric inkjet systems enable Singapore hospitality specifiers to execute rapid-turn renovation projects with micro-batch customization. |
| Reclamation Network Acquisition | Facility managers in California bundle installation with end-of-life service to capture LEED waste diversion credits in Class A office repositioning. |
| Extended Producer Responsibility Compliance | Closed-loop reclamation infrastructure in France and Germany rewards manufacturers with public procurement eligibility under EU Green Deal frameworks. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation across regulatory and trade databases. Primary interviews engaged carpet manufacturing plant managers, hospitality procurement directors, commercial facility managers, and distribution channel partners. Secondary sources included EPA emission filings, ECHA REACH registration databases, customs trade records, and SEC 10-K disclosures from listed manufacturers. Bottom-up and top-down triangulation cross-validated segment-level production estimates against macroeconomic construction indicators.
Rate-of-change decomposition framed volume and value projections across material type, application channel, and regional regulatory cluster throughout the forecast period. Segmentation dimensions modeled included fiber chemistry, end-use vertical, style positioning, and dimensional category. CAGRs derived from historical elasticity analysis applied to construction spending forecasts and hospitality refurbishment cycle timing. Industry-specific inputs encompassed tufting capacity utilization rates and recycled PET feedstock availability curves.
Petroleum price volatility, REACH restriction timeline acceleration, and hard flooring substitution rates are the dominant revision risks requiring ongoing monitoring. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and mechanical recycling infrastructure buildout schedules. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
Saudi Arabia Carpet and Rugs Market
Flooring, Carpets, and Rugs
United Kingdom Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Luxury Vinyl Plank (LVP) Market
Flooring, Carpets, and Rugs
Stone Flooring Market
Flooring, Carpets, and Rugs
Germany Resilient Flooring Market
Flooring, Carpets, and Rugs
United States Laminate Flooring Market
Flooring, Carpets, and Rugs
Textured Variegates Market
Flooring, Carpets, and Rugs
China Luxury Vinyl Tile (LVT) Market
Flooring, Carpets, and Rugs
Europe Vinyl Flooring Market
Flooring, Carpets, and Rugs
Wood Plastic Composite (WPC) Floorings Market
Flooring, Carpets, and Rugs
Europe Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Netherlands Floor Covering Market
Flooring, Carpets, and Rugs
Terrazzo Flooring Market
Flooring, Carpets, and Rugs
United Kingdom Floor Covering Market
Flooring, Carpets, and Rugs
Fiberglass Flooring Market
Flooring, Carpets, and Rugs
China Non-Resilient Floor Covering Market