
 Luxury Vinyl Tiles Market | 2026-2036
Luxury Vinyl Tiles Market Size, Share, and Industry Trends Forecast 2026-2036
Luxury Vinyl Tiles Market Outlook
Multi-source resin procurement is decoupling from traditional petroleum-dependent supply chains as manufacturers diversify plasticizer inputs. Mohawk Industries leverages captive PVC compounding capacity to insulate margin volatility, while Tarkett anchors its European position through bio-circular feedstock partnerships. Shaw Industries Group competes on domestic manufacturing scale, sustaining shorter lead times for North American commercial contractors.
Luxury vinyl tiles are multi-layer synthetic flooring products comprising a PVC wear layer, printed decorative film, and stabilized core, typically manufactured through calendering or extrusion processes to achieve dimensional stability under thermal cycling. Their primary commercial purpose is delivering hardwood or stone aesthetics with superior moisture resistance and lower lifecycle cost than natural materials. Click-lock systems now dominate residential retrofit channels where floating-floor installation reduces labor dependency, while glue-down formats retain specification preference in healthcare and hospitality applications where subfloor adhesion prevents microbial harborage beneath planks. The 5 mm thickness tier captures the fastest-growing specification band, balancing underfoot comfort with transition-height compatibility against existing flooring.
REACH restrictions on orthophthalate plasticizers and California Department of Public Health Section 01350 VOC emissions protocols are forcing reformulation across European and North American supply bases, elevating compliance costs for imported products. ECHA substance evaluations and EPA TSCA Section 6 risk management for PVC additives are converging toward tighter migration limits, reshaping qualification requirements for hospitality and retail specification channels. Stakeholders must monitor pending bio-based content verification standards and polymer recycling infrastructure scale-up as these will determine which core technologies retain cost competitiveness against laminate and engineered hardwood alternatives.
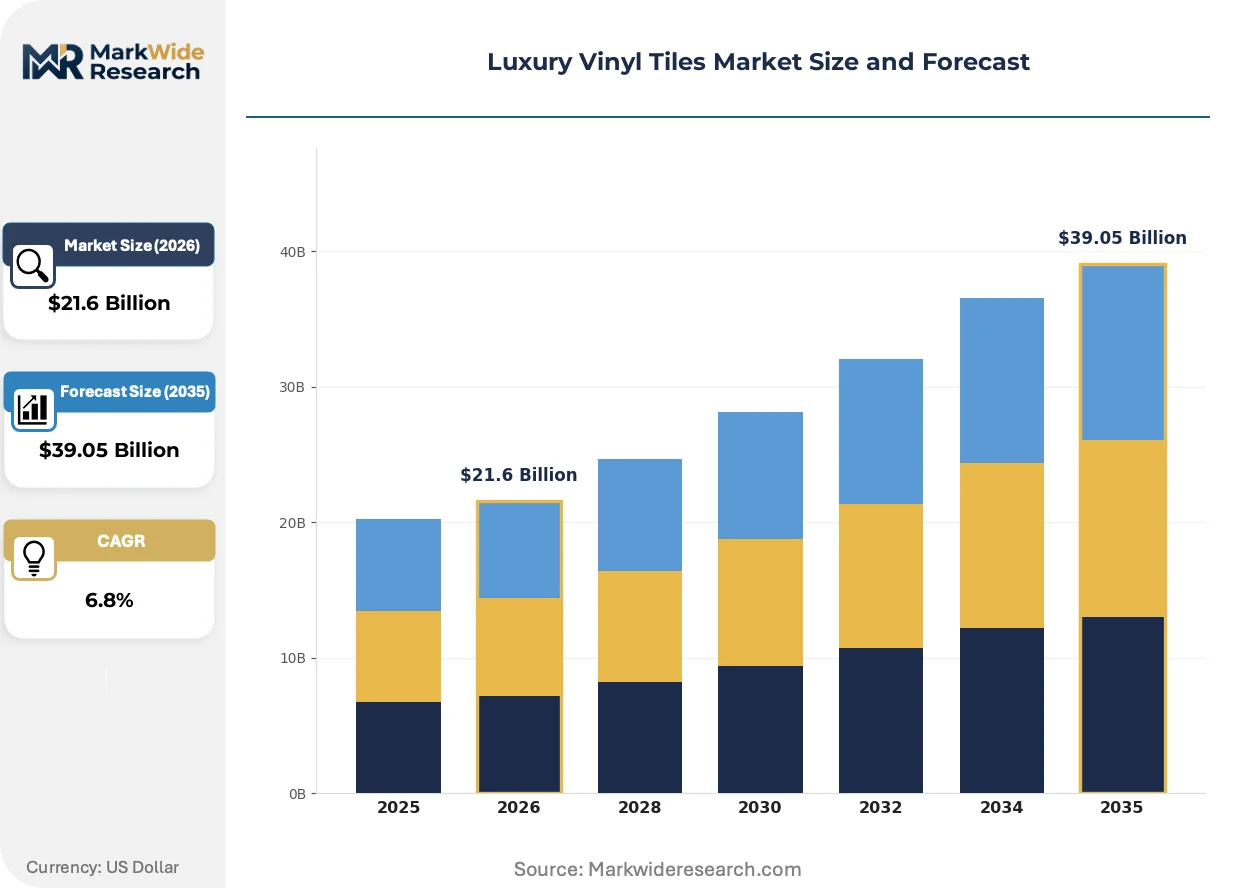
Market Dynamics
Phthalate-free reformulation mandates under REACH and California Department of Public Health Section 01350 are forcing capital reallocation across compounding operations, compressing margins for non-compliant imports while rewarding domestic bio-based plasticizer investments.
Growth Catalysts
- Healthcare sterilization protocols:Commercial medical facilities specify resilient flooring that withstands aggressive chemical cleaning cycles without surface degradation, locking in replacement demand.
- REACH orthophthalate restrictions:Migration limits on DEHP and DINP plasticizers redirect procurement toward bio-circular feedstock suppliers with verified compliance documentation.
- LEED specification concentration:United States, Germany, and China building codes embed green certification requirements that privilege low-VOC LVT over conventional vinyl sheet alternatives.
Market Restraints
- Petroleum-dependent resin costs:PVC suspension-grade feedstock pricing tracks ethylene-cracker margins, exposing compounders to naphtha volatility without hedge mechanisms.
- Chinese additive concentration:60-70% of global DOTP plasticizer capacity sits in Shandong and Jiangsu provinces, creating single-source vulnerability for European calendering lines.
- Laminate moisture resistance convergence:Water-resistant HDF core boards from Austrian and German producers narrow the performance gap at 30-40% lower installed cost in residential channels.
Strategic Opportunities
- Indian commercial real estate buildout:LEED-registered floor area in Mumbai and Bangalore is expanding faster than domestic LVT compounding capacity, opening import substitution windows.
- Digital printing convergence:Single-pass UV inkjet decoration onto SPC cores enables batch-size-one customization for hospitality renovation contracts.
- Extended Producer Responsibility tailwinds:EU Green Deal circular economy action plan mandates post-consumer PVC collection targets that favor domestic reprocessing infrastructure investors.
Industry Challenges
- Calendering operator scarcity:Four-roll PVC sheet production requires 8-10 year apprenticeship pipelines that collapsed in Western Europe during 2010s offshoring waves.
- Multi-jurisdiction certification timelines:Simultaneous ECHA substance evaluation, EPA TSCA Section 6 risk management, and state-level VOC protocols create 18-24 month qualification backlogs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Luxury Vinyl Tiles Market |
| Market Size in 2026 | $21.6 Billion |
| Market Size in 2035 | $39.05 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glue-down, Loose lay, Click-lock, Plank Application: Residential, Commercial, Hospitality, Retail Thickness: 3 mm, 4 mm, 5 mm, 6 mm Finish Type: Semi-gloss, Matte, Textured, Embossed |
| Companies Covered | Mohawk Industries, Armstrong Flooring, Tarkett, Mannington Mills, Shaw Industries Group, Gerflor, Forbo Group, Interface, LG Hausys, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Luxury Vinyl Tiles Market Strategic Shifts
Digital decoration and rigid core engineering are collapsing the traditional tradeoff between aesthetic fidelity and installation speed, while regulatory chemistry restrictions accelerate feedstock diversification beyond petroleum-based plasticizers.
Photorealistic embossed-in-register (EIR) surface texturing is absorbing the specification premium previously captured by engineered hardwood in multi-family housing channels. Property developers in Texas and Florida specify 5 mm SPC planks with registered embossing for rental unit renovations where moisture exposure rules out organic materials. This technology is absorbing market share from laminate in water-prone applications while compressing the price premium against LVT.
California Department of Public Health Section 01350 VOC emissions protocols and ECHA substance evaluations are converging toward 0.5 mg/m³ total limit thresholds for plasticizer migration. Compounders in Germany and the Netherlands are qualifying bio-based DOTP alternatives derived from soybean and castor oil feedstocks. Hospitality specification channels in California and New York now require third-party certification against CDPH/EHLB Standard Method V1.2, filtering out Asian imports lacking documentation.
Specification-driven procurement is consolidating around certified low-emitting materials in healthcare and education verticals. Hospital facility managers in the United States increasingly delegate flooring selection to infection-control committees that mandate CDPH-compliant documentation before bid consideration. This pattern concentrates volume with domestic manufacturers maintaining in-house emissions testing laboratories, marginalizing distributors reliant on imported certificate translations.
Luxury Vinyl Tiles Market Segmentation
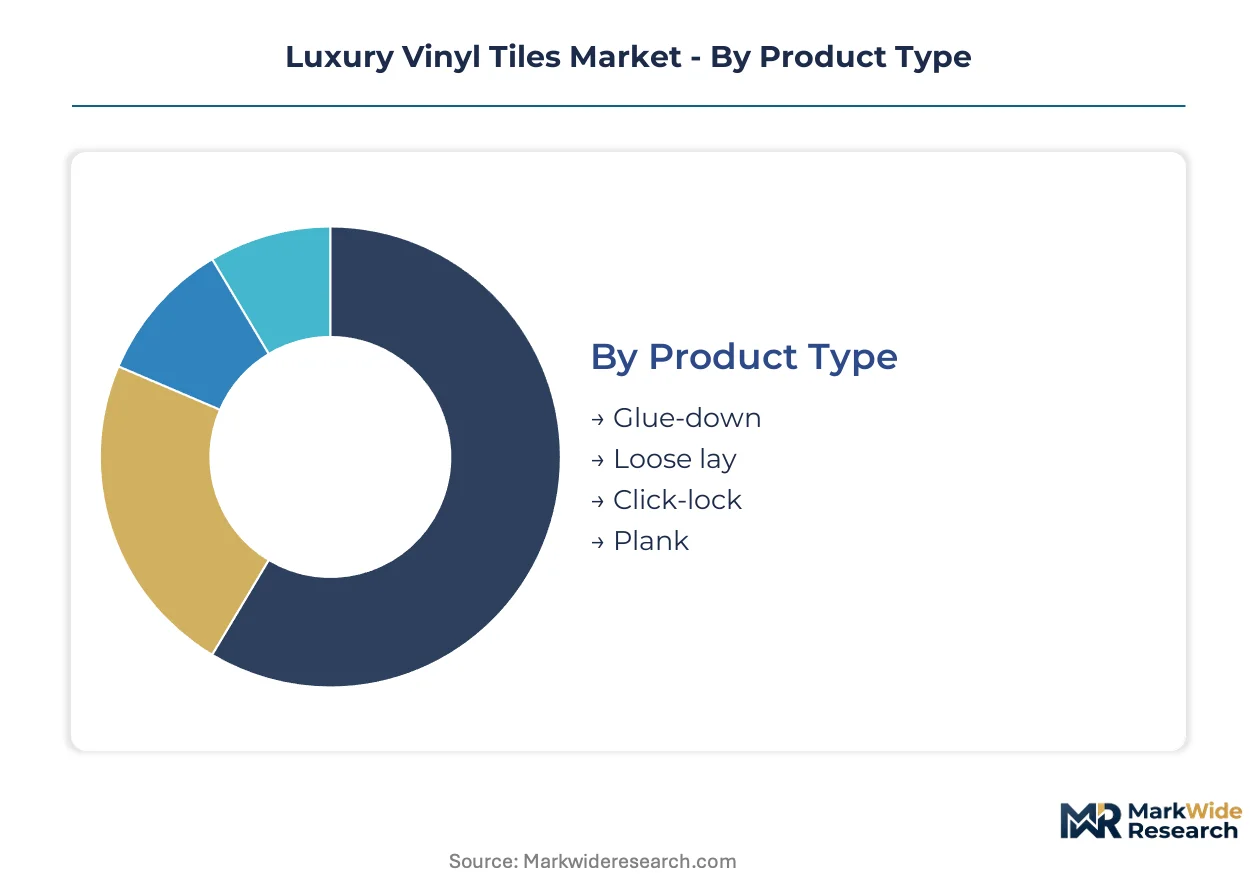
Segmentation in the luxury vinyl tiles market tracks divergent specification requirements across installation environments, where healthcare sterilization protocols, residential retrofit labor constraints, and hospitality aesthetic demands create distinct procurement channels with incompatible performance priorities.
Product Type:
Installation method determines labor economics, subfloor compatibility, and replacement cycle frequency for facility managers and contractors.
- Click-lock:Tongue-and-groove mechanical fastening enables floating-floor installation without adhesive, reducing skilled labor dependency in residential retrofit channels. Demand concentrates in United States multi-family housing renovations where moisture-prone basements and bathrooms rule out laminate alternatives, driven by property management firms seeking tenant-turn speed.
- Glue-down:Full-spread adhesive application creates permanent subfloor bonds preferred in commercial healthcare and hospitality specifications. United States hospital infection-control committees mandate this format for operating suites and patient rooms where microbial harborage beneath planks poses liability risks, constrained by 24-48 hour cure times that extend project schedules.
- Loose lay:Friction-based installation using rubber backing eliminates adhesive entirely, suiting temporary retail pop-ups and exhibition spaces requiring rapid deployment and removal.
- Plank:Rectangular format mimicking hardwood dimensions dominates residential aesthetic preferences, with longer boards commanding specification premiums in high-end single-family construction.
Click-lock leads on scale; glue-down leads on specification premium capture.
Application:
End-use environment dictates wear layer thickness, slip resistance ratings, and chemical compatibility requirements that compounders must certify against.
- Commercial:Healthcare facilities, corporate offices, and educational institutions specify 20+ mil wear layers with enhanced scratch resistance. Germany's LEED-registered office construction in Frankfurt and Munich concentrates procurement with domestic manufacturers maintaining ECHA-compliant bio-plasticizer documentation.
- Hospitality:Hotels and restaurants prioritize acoustic underlayment integration and photorealistic stone aesthetics. China's Shanghai and Beijing luxury hotel pipelines specify 5 mm SPC cores with embossed-in-register texturing, constrained by CDPH-equivalent emissions testing requirements for international brand compliance.
- Residential:Single-family and multi-family housing channels balance cost sensitivity with moisture performance, with click-lock formats capturing renovation volume.
- Retail:High-traffic storefronts demand rapid installation turnaround and modular replacement capability for visual merchandising refreshes.
Commercial leads on specification rigor; hospitality leads on aesthetic innovation adoption.
Thickness:
Core dimension determines underfoot comfort, transition height compatibility with existing flooring, and structural stability under thermal cycling.
- 5 mm:Rigid SPC or WPC core construction balances dimensional stability with transition-height compatibility against 3-4 mm resilient flooring or 12 mm laminate. United States property developers in Texas and Florida specify this tier for rental unit renovations where moisture exposure and tenant comfort both factor into lease rates, climbing the fastest as the specification sweet spot.
- 4 mm:Traditional LVT core thickness retains cost advantage in budget commercial installations where subfloor preparation can achieve flatness tolerances.
- 3 mm:Glue-down flexible format dominates healthcare refurbishment projects with strict height constraints at door thresholds and elevator transitions.
- 6 mm:Enhanced acoustic performance and underfoot cushioning target high-rise residential construction with sound transmission class requirements.
5 mm leads on specification momentum; 4 mm leads on installed base volume.
Finish Type:
Surface treatment determines maintenance protocol, slip resistance, and aesthetic differentiation against competing flooring categories.
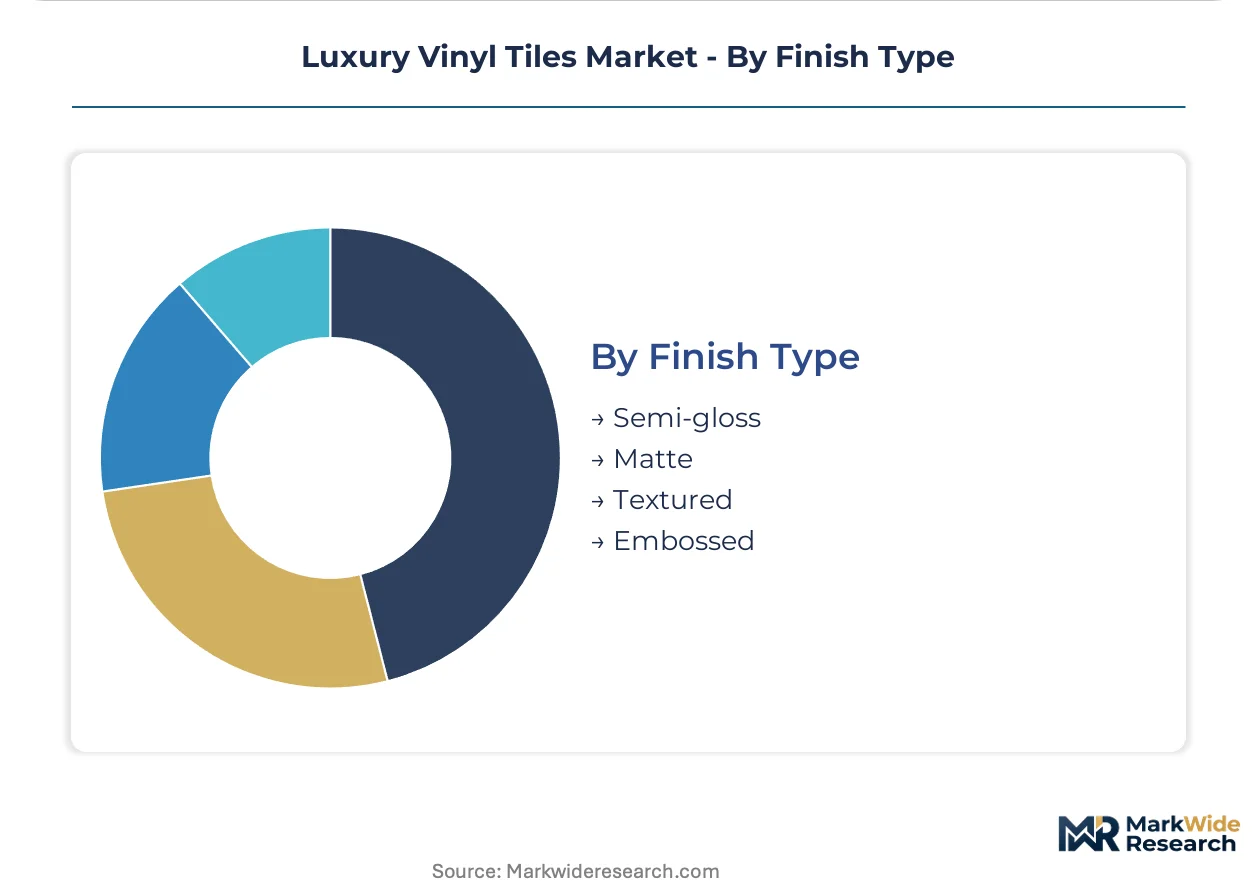
- Embossed-in-register (EIR):Synchronized surface texture matching printed grain patterns commands specification premiums previously captured by engineered hardwood. Germany's multi-family housing developers specify EIR for rental properties where hardwood maintenance costs are prohibitive.
- Matte:Low-sheen surface minimizes glare and visible scratching in high-traffic commercial environments with aggressive cleaning schedules.
- Textured:General embossed surface provides basic slip resistance for residential bathrooms and kitchens without EIR registration precision.
- Semi-gloss:Moderate reflectivity suits retail environments where lighting design enhances merchandise presentation.
Matte leads on commercial specification volume; EIR leads on premium capture rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Jiangsu-Shandong corridor concentrates global plasticizer capacity and calendering infrastructure for luxury vinyl tile substrate production. Demand fragmentation across specification channels creates divergent procurement patterns between healthcare sterilization markets and residential retrofit channels. Regulatory chemistry restrictions in multiple jurisdictions are forcing regional supply base reconfiguration.
United States
Hospital infection-control committees in Texas and Florida specify glue-down formats for operating suites where microbial harborage poses liability exposure. California Department of Public Health Section 01350 VOC protocols filter Asian imports lacking emissions documentation. The Dallas-Fort Worth metroplex anchors multi-family housing renovation demand where 5 mm click-lock formats reduce tenant-turn labor dependency.
Germany
Frankfurt and Munich LEED-registered office construction concentrates procurement with domestic compounders maintaining ECHA-compliant bio-plasticizer documentation. REACH orthophthalate migration limits redirect procurement toward verified bio-circular feedstock suppliers. The Rhine-Ruhr industrial region hosts calendering lines qualifying for hospitality specification channels requiring third-party emissions certification.
China
Shanghai and Beijing luxury hotel pipelines specify 5 mm SPC cores with embossed-in-register texturing for international brand compliance. Domestic dual carbon goals accelerate bio-based plasticizer R&D investment among state-owned resin compounders. The Pearl River Delta manufacturing cluster faces CDPH-equivalent testing requirements for export-oriented production bound for North American specification channels.
India
LEED-registered floor area in Mumbai and Bangalore expands faster than domestic LVT compounding capacity, opening import substitution windows for compliant manufacturers. The Bureau of Indian Standards (BIS) is developing emissions protocols for resilient flooring that will reshape qualification requirements for healthcare and hospitality verticals. The Delhi-NCR corridor concentrates commercial real estate buildout where specification-driven procurement privileges documented low-VOC materials.
United Kingdom
London commercial refurbishment projects specify rigid core products balancing acoustic performance with height constraints at elevator transitions. The UK Construction Products Regulation (CPR) alignment with EU REACH restrictions maintains chemistry compliance barriers for non-European imports. The Midlands manufacturing region retains limited calendering capacity serving domestic healthcare refurbishment channels.
Luxury Vinyl Tiles Market Competitive Environment
Global majors compete with regional champions across specification documentation and feedstock compliance capabilities. The vendor base stratifies between integrated resin compounders with captive PVC capacity and specialized flooring manufacturers dependent on external substrate supply. Three archetypes dominate: vertically integrated petrochemical-to-flooring conglomerates, regional calendering specialists with bio-plasticizer partnerships, and contract manufacturers serving private-label retail channels. Competitive positioning hinges on multi-jurisdiction certification maintenance and backward integration into plasticizer compounding.
Among North American integrated manufacturers, Mohawk Industries and Shaw Industries Group occupy positions anchored by domestic compounding infrastructure that insulates margin volatility from petroleum feedstock swings. Tarkett represents the European archetype of bio-circular feedstock partnerships that secure specification preference under REACH compliance regimes. Armstrong Flooring and Mannington Mills exemplify mid-scale specialists competing on healthcare and hospitality channel certification depth rather than resin integration.
| Leading Market Players |
|---|
| Mohawk Industries |
| Armstrong Flooring |
| Tarkett |
| Mannington Mills |
| Shaw Industries Group |
| Gerflor |
| Forbo Group |
| Interface |
| LG Hausys |
| Others |
Value Chain & Pricing Dynamics
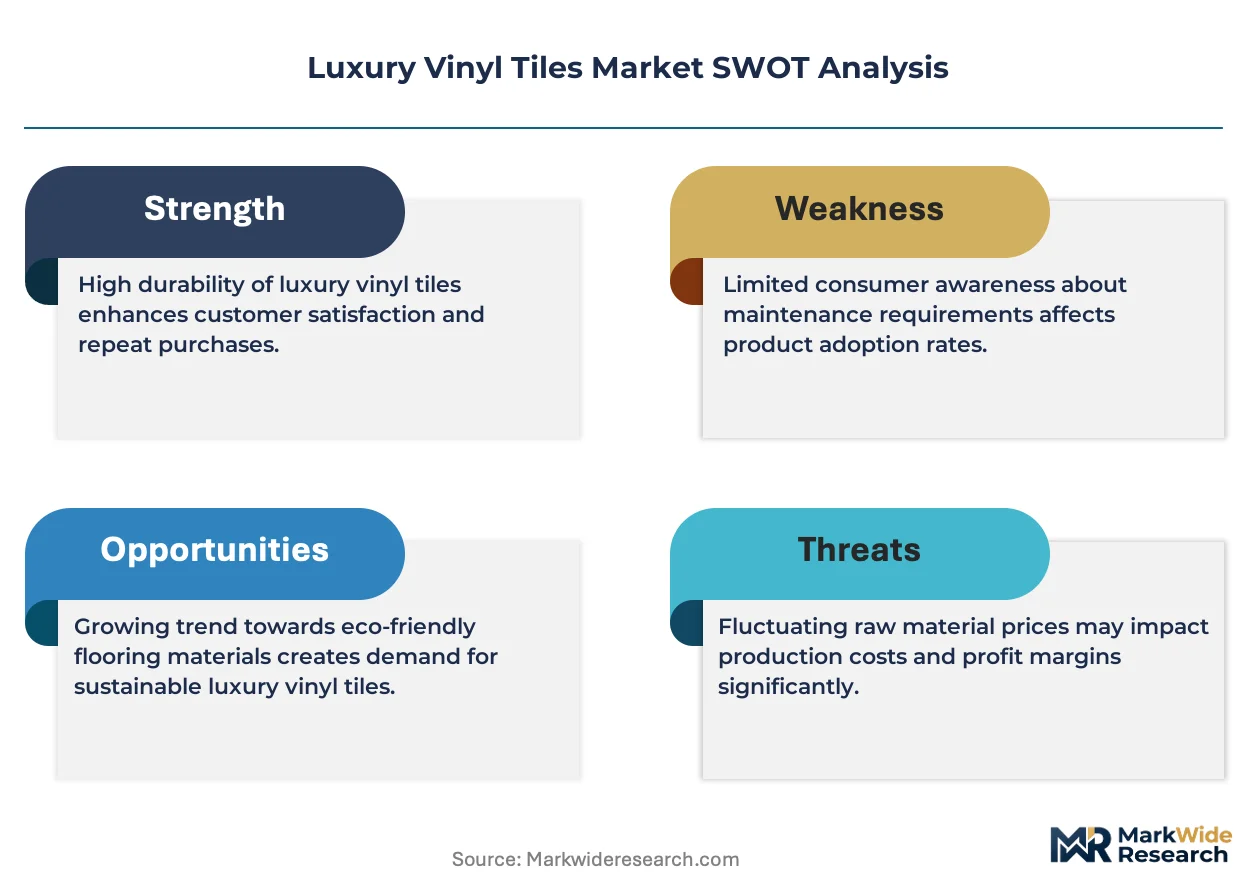
Bio-based DOTP plasticizer feedstock costs cascade through three-tier pricing structures across premium, standard, and economy levels, with REACH-compliant European compounders commanding specification premiums while Shandong-origin imports compete on raw material arbitrage in undifferentiated residential channels.
Pricing Analysis
Input-cost pass-through from naphtha-indexed PVC suspension resin drives margin compression at the economy tier, where Chinese imports absorb ethylene-cracker volatility without hedge mechanisms. Price differentiation rests on CDPH Section 01350 certification grade and ECHA bio-plasticizer documentation, with domestic North American manufacturers capturing 15-20 point premiums in healthcare specification channels. Pricing pressure stems from laminate moisture-resistance convergence at 30-40% lower installed cost, squeezing residential LVT margins. Multi-family housing developers in Texas and Florida exhibit highest price sensitivity, while hospital infection-control committees demonstrate lowest sensitivity due to liability-driven procurement protocols.
Supply Chain Analysis
Certification gating through CDPH/EHLB Standard Method V1.2 and REACH orthophthalate migration limits fragments qualified supplier bases, concentrating compliant calendering capacity in Germany, the Netherlands, and domestic United States facilities. Raw material dependencies center on PVC resin from Gulf Coast ethylene crackers, DOTP plasticizers from Shandong and Jiangsu provinces, and SPC core minerals from Appalachian calcium carbonate deposits. Single-source vulnerability in Chinese additive concentration creates supply chain risk, with 60-70% of global DOTP capacity concentrated in two provincial clusters. Distribution runs through commercial flooring distributors serving specification channels, direct procurement by national retail chains, and regional contractor supply houses for renovation volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Luxury Vinyl Tiles Market functions as a stable compounder anchored by healthcare sterilization protocol mandates that lock in replacement cycles regardless of construction cyclicality.
For Market Incumbents: Cement specification lock-in through captive bio-plasticizer compounding capacity that insulates margin volatility from petroleum feedstock swings. Defend against laminate moisture-resistance convergence by accelerating EIR surface technology deployment in multi-family housing channels where hardwood aesthetics command lease premiums. Prioritize CDPH-compliant documentation investment to filter out Asian import competition in California and New York specification markets.
For New Entrants and Emerging Players: Enter via LEED-registered commercial real estate buildout in Mumbai and Bangalore where domestic Indian compounding capacity lags demand expansion. Target hospitality renovation contracts in Shanghai and Beijing requiring CDPH-equivalent emissions documentation that incumbent Chinese manufacturers lack. Pursue digital printing convergence partnerships enabling batch-size-one customization for boutique hotel chains.
For Investors and Strategic Acquirers: Roll-up economics work for regional calendering specialists with ECHA-compliant bio-plasticizer partnerships because REACH migration limits are permanently elevating compliance barriers against non-integrated imports. Focus acquisition screening on mid-scale German and Dutch compounders with verified feedstock documentation and existing healthcare channel certification. Monitor pending Bureau of Indian Standards emissions protocol development as inflection indicator for Indian market qualification requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Plasticizer Compounding | Captive DOTP production insulates margin volatility from Shandong supply concentration. |
| CDPH Section 01350 Certification Investment | Third-party emissions documentation filters Asian imports from California specification channels. |
| Digital UV Inkjet Decoration Deployment | Single-pass customization captures hospitality renovation contracts requiring rapid aesthetic turnaround. |
| Calendering Operator Apprenticeship Pipeline | Eight-year training programs rebuild Western European production capacity collapsed during 2010s offshoring. |
| Extended Producer Responsibility Infrastructure | Post-consumer PVC collection targets under EU Green Deal favor domestic reprocessing investors. |
Study Parameters
Direct dialogue with flooring procurement managers at hospital systems, commercial real estate developers, hospitality brand specification directors, and residential contractor supply houses grounded qualitative insights in operational reality. Secondary validation drew from EPA TSCA Section 6 filings, ECHA substance evaluation databases, California Department of Public Health emissions protocols, and customs trade data tracking PVC resin and plasticizer flows. Bottom-up volume modeling across installation format, application vertical, and thickness tier triangulated against top-down construction spending forecasts.
Bottom-up segment analysis modeled click-lock, glue-down, loose lay, and plank formats across commercial, hospitality, residential, and retail applications, with thickness stratification at 3 mm, 4 mm, 5 mm, and 6 mm tiers. CAGRs derived from regression against construction permit data, LEED registration trajectories, and healthcare facility capital expenditure patterns. Industry-specific inputs incorporated REACH compliance cost pass-through estimates and laminate price elasticity coefficients from substitution analysis.
Inputs from hospital procurement databases and hospitality brand specification manuals were available through the study window; gaps in real-time Chinese provincial plasticizer production data introduce uncertainty bands around supply-side concentration assumptions. Forecasts reflect documented assumptions regarding regulatory timeline adherence and construction cycle correlation. A model refresh is warranted upon material change in Bureau of Indian Standards emissions protocol finalization or EU Green Deal circular economy collection target enforcement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
Europe Carpet Tile Market
Flooring, Carpets, and Rugs
Indoor Flooring Market
Flooring, Carpets, and Rugs
Global Floor Covering Market
Flooring, Carpets, and Rugs
Global Flooring Market
Flooring, Carpets, and Rugs
Saudi Arabia Floor Covering Market
Flooring, Carpets, and Rugs
Europe Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Global Commercial Flooring Market
Flooring, Carpets, and Rugs
Europe Resilient Floor Covering Market
Flooring, Carpets, and Rugs
China Floor Covering Market
Flooring, Carpets, and Rugs
Global Vinyl Flooring Market
Flooring, Carpets, and Rugs
Global Flooring and Carpet Market
Flooring, Carpets, and Rugs
Hard Surface Flooring Market
Flooring, Carpets, and Rugs
Germany Resilient Flooring Market
Flooring, Carpets, and Rugs
Rigid Core Flooring Market
Flooring, Carpets, and Rugs
Stone Flooring Market
Flooring, Carpets, and Rugs
Wood Flooring Market