
 Europe Flooring Market | 2026-2036
Europe Flooring Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Flooring Market Insights
Multi-source resin procurement is recalibrating how European flooring manufacturers manage input cost volatility and supply security. Tarkett leverages integrated PVC compounding capabilities across its French and Swedish plants to buffer against petrochemical price swings. Gerflor anchors its competitiveness through deep specialization in heterogeneous vinyl rolls for healthcare and education sectors. Mohawk Industries competes by extending its American manufacturing scale into European distribution networks, particularly for laminate and engineered wood.
Europe flooring encompasses surface-covering materials installed over structural subfloors to provide wear resistance, acoustic dampening, and aesthetic finish in residential, commercial, and institutional environments; specifications span wear-layer thickness from 0.3 mm for residential vinyl to 0.7 mm for heavy-traffic commercial sheet, with critical performance parameters including slip resistance (R9–R11 ratings), fire reaction class (Bfl-s1 or Cfl-s1 under EN 13501), and thermal conductivity for underfloor heating compatibility. Vinyl products lead value contribution due to waterproof performance and design versatility, while hardwood commands premium positioning in renovation-driven markets where FSC or PEFC certification unlocks specification in public tenders; click-lock installation methods are displacing glue-down systems in residential retrofit applications because floating floors reduce labor cost and substrate preparation requirements. Laminate occupies a mature volume position in price-sensitive segments, though differentiation increasingly depends on synchronized embossed surface textures and water-resistant core board formulations.
CE marking under the Construction Products Regulation mandates declared performance against EN standards for reaction to fire, formaldehyde emission, and dimensional stability, while the EU Green Deal's evolving embodied carbon thresholds and ECHA scrutiny of PVC plasticizers shape material selection and formulation roadmaps. REACH compliance on phthalate restrictions and the F-Gas Regulation's phase-down of HFC blowing agents for insulation-linked underlay products add layered compliance obligations across the value chain. Stakeholders must monitor how the EU's developing digital product passports and carbon border adjustment mechanisms will restructure sourcing economics for imported wood and synthetic raw materials.
Market Dynamics
The EU Green Deal's embodied carbon thresholds are forcing European flooring manufacturers to reformulate product lines around bio-based binders and certified renewable feedstocks, compressing margins for PVC-dependent producers while opening specification advantages for low-carbon alternatives.
Growth Catalysts
- Renovation wave intensity:German residential retrofit activity is absorbing record volumes of click-lock vinyl and engineered wood systems as energy-efficiency mandates accelerate building envelope upgrades.
- REACH phthalate restrictions:Regulatory pressure on plasticizer chemistry is pulling demand toward bio-based linoleum and natural rubber alternatives in healthcare and education specifications.
- Underfloor heating penetration:Nordic markets are specifying thermally conductive LVT and thin-profile engineered hardwood to optimize heat transfer efficiency in residential new-builds.
Market Restraints
- Petrochemical input volatility:PVC resin and plasticizer costs swing with naphtha and ethylene pricing, compressing margin predictability for vinyl-focused manufacturers without integrated compounding.
- Baltic hardwood supply concentration:FSC-certified oak and ash sourcing clusters in Estonia, Latvia, and Lithuania, creating vulnerability to trade disruption and certification backlog.
- Formaldehyde emission ceilings:EN 13986 Class E1 limits on laminate core boards constrain cost-engineering flexibility for price-competitive producers.
Strategic Opportunities
- Digital product passport readiness:Early compliance with the EU's developing DPP framework will unlock preferential positioning in public procurement tenders requiring full lifecycle disclosure.
- Healthcare-acquired infection protocols:Antimicrobial surface treatments and seamless sheet vinyl systems are capturing specification share in French and Belgian hospital renovation programs.
- Carbon border adjustment positioning:Domestic and near-shore manufacturing of bio-based flooring will avoid CBAM exposure on imported synthetic raw materials.
Industry Challenges
- Skilled flooring installer scarcity:Aging trade workforce across Germany and Benelux is lengthening project timelines and elevating labor cost in premium residential segments.
- Multi-standard certification complexity:Concurrent CE marking, PEFC chain-of-custody, and national building code approvals extend product launch timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Flooring Market |
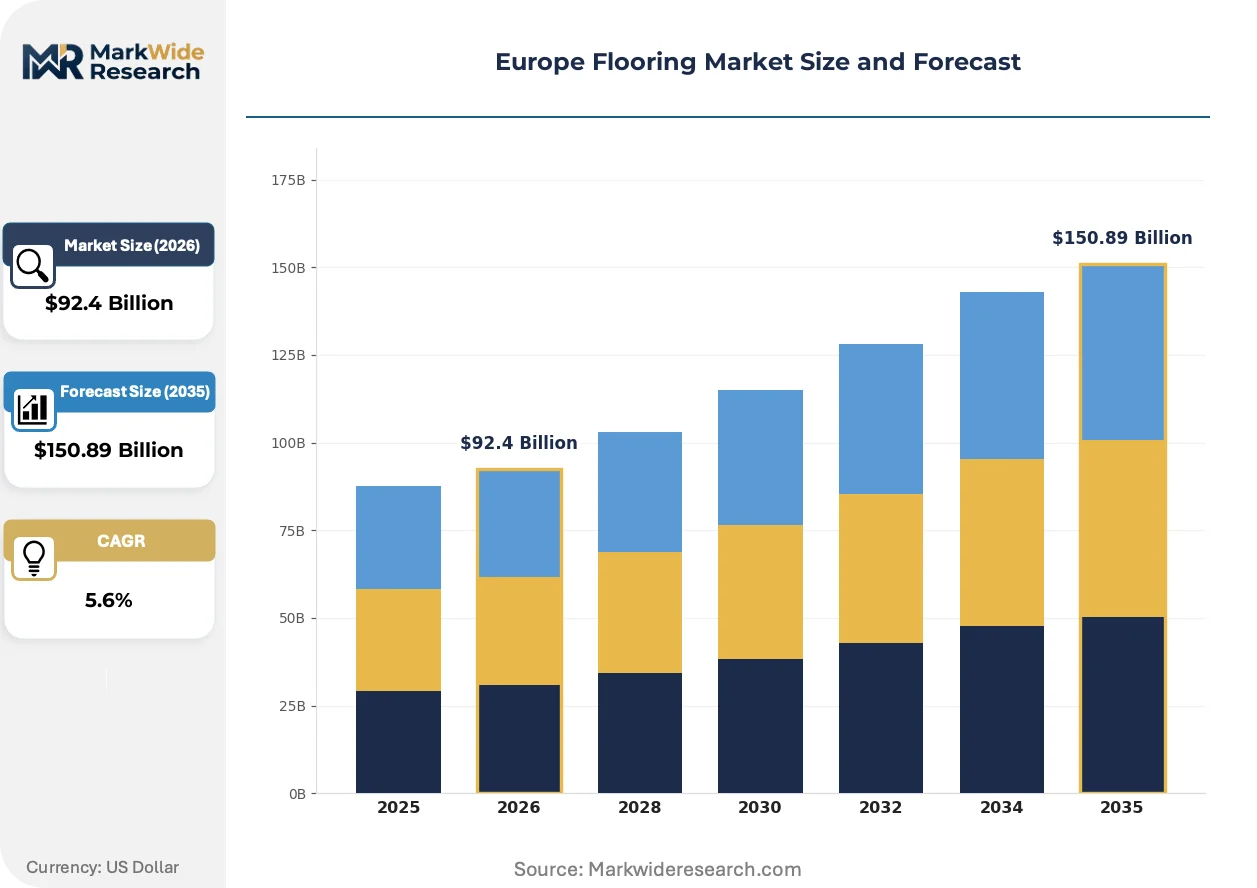
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $150.89 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laminated, Vinyl, Hardwood, Carpet Installation Method: Glue-Down, Floating, Nail-Down, Click-Lock End User: Residential, Commercial, Institutional, Industrial Material: Wood, PVC, Linoleum, Bamboo |
| Companies Covered | Gerflor, Polyflor, Tarkett, Berry Alloc, Parador, Forbo Flooring, Interface, Milliken Flooring, Mohawk Industries, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Flooring Market Trends and Innovations
Surface engineering and installation chemistry are converging to eliminate traditional performance trade-offs between waterproofing, thermal conductivity, and end-of-life recyclability in European flooring systems.
Click-lock rigid core LVT with stone-polymer composite backing is overtaking flexible glue-down sheet vinyl in Scandinavian residential renovation. Property developers in Stockholm and Oslo specify floating SPC systems for their compatibility with underfloor heating and reduced substrate preparation. The technology is compressing demand for traditional wet-installation trades while elevating dry-lay contractor specialization.
REACH restrictions on short-chain chlorinated paraffins and phthalate plasticizers are forcing PVC reformulation toward bio-based plasticizers and calcium-zinc stabilizer systems. Compounders in northern France and western Germany are retooling extrusion lines to handle higher-viscosity bio-additive packages. Heterogeneous vinyl roll producers serving healthcare verticals face the steepest compliance timeline pressure.
Public procurement officers in France and the Netherlands now weight EPD-verified embodied carbon at 15-30% of tender evaluation scoring. This behavioral shift is displacing lowest-price bidding in institutional flooring contracts. Specification consultants in Paris and Rotterdam actively filter manufacturers without third-party verified lifecycle data from shortlists.
Europe Flooring Market Segmentation
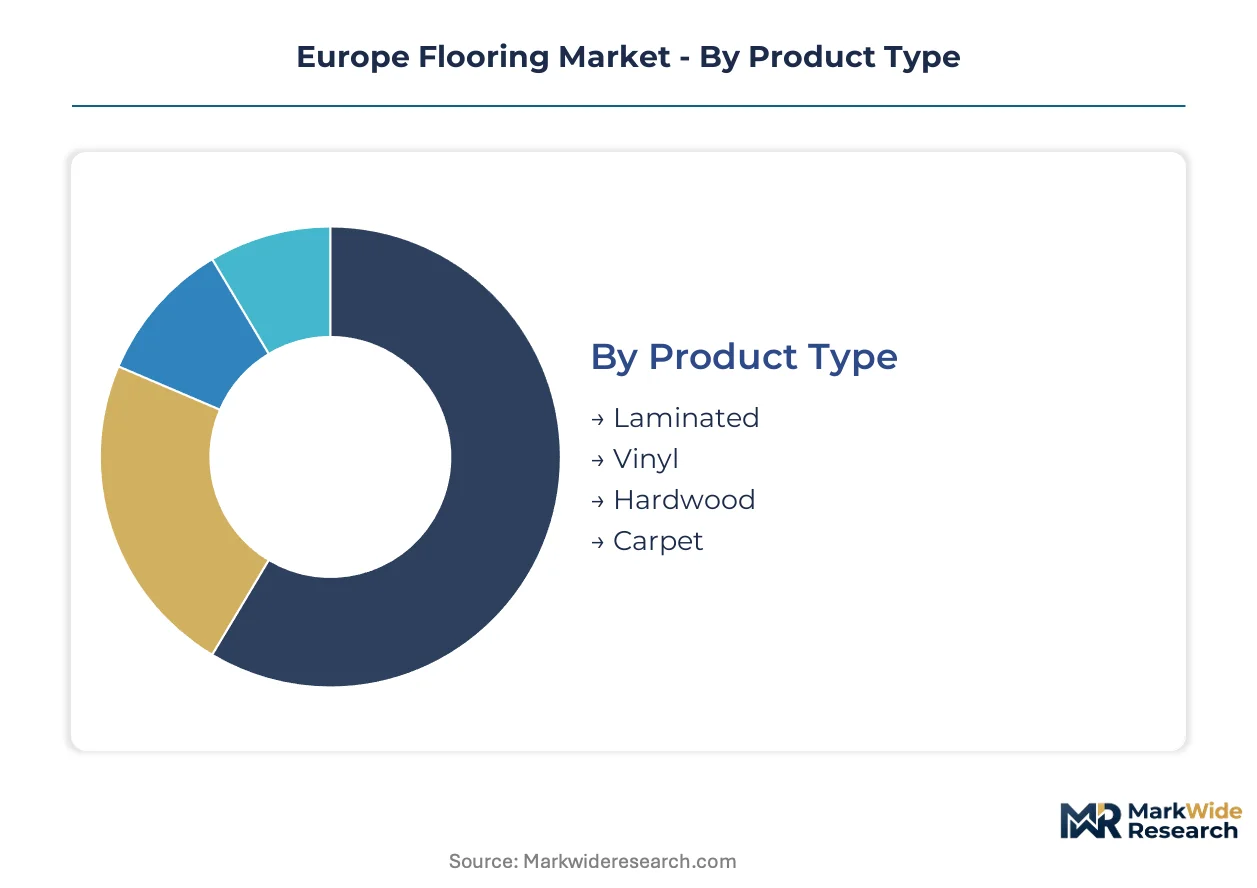
Segmentation in the Europe Flooring Market reveals how specification requirements diverge across installation constraints, regulatory environments, and end-use performance demands. Understanding these divides exposes where margin pools concentrate and where substitution threats emerge.
Product Type:
Cost tier separates specification buyers from price-optimized procurement in residential renovation.
- Vinyl:Waterproof synthetic construction spans flexible sheet, LVT planks, and rigid SPC cores with wear layers from 0.3 mm to 0.7 mm. German and Nordic residential retrofits specify click-lock LVT for underfloor heating compatibility and rapid installation. REACH phthalate restrictions are accelerating bio-plasticizer formulation shifts among compounders in northern France.
- Hardwood:Solid and engineered constructions command premium positioning where FSC or PEFC certification unlocks public tender eligibility. French and Belgian hospital programs specify engineered hardwood for acoustic performance in patient recovery zones; Baltic oak supply concentration in Estonia and Latvia creates certification bottlenecks.
- Laminated:Fiberboard core with decorative paper overlay and aluminum oxide wear layer occupies price-sensitive residential replacement cycles. Synchronized embossed surface textures differentiate mid-tier offerings from commodity imports.
- Carpet:Broadloom and tile formats persist in UK commercial offices and Nordic hospitality, though shrinking share in healthcare due to infection control protocols.
Vinyl leads volumes today; hardwood is gaining share fastest in premium renovation segments.
Installation Method:
Application environment dictates labor cost exposure and substrate preparation requirements.
- Click-Lock:Mechanical joining system enables floating installation without adhesive, compressing project timelines in German residential retrofit. Rigid SPC variants with stone-polymer composite backing dominate Scandinavian new-build specifications for thermal conductivity optimization.
- Glue-Down:Full-surface adhesive bonding delivers maximum stability for heavy rolling loads in healthcare corridors and industrial logistics facilities. Wet-installation trade scarcity across Benelux is elevating labor premiums.
- Floating:Interlocking systems laid over underlayment without mechanical fixation to subfloor, prevalent in residential laminate and engineered wood deployment.
- Nail-Down:Traditional mechanical fastening for solid hardwood over wooden subfloors, contracting to heritage restoration and high-end residential new construction.
Click-lock dominates residential retrofit volume; glue-down retains institutional specification share.
End User:
Customer type determines compliance burden, performance certification depth, and contract duration.
- Residential:Single-family and multi-family housing drives volume through renovation waves and energy-efficiency envelope upgrades. German homeowners prioritize click-lock vinyl and engineered wood for DIY compatibility and rapid occupancy turnaround.
- Commercial:Offices, retail, and hospitality specify for durability and design flexibility. French public procurement now weights EPD-verified embodied carbon at 15-30% of tender scoring.
- Institutional:Healthcare and education demand antimicrobial treatments, seamless sheet systems, and fire reaction class Bfl-s1 under EN 13501. Belgian hospital renovation programs specify heterogeneous vinyl rolls for infection control.
- Industrial:Manufacturing and logistics facilities prioritize chemical resistance and point-load bearing capacity, typically specifying epoxy or polyurethane alternatives to conventional flooring.
Residential absorbs the largest volume; institutional specifications are climbing fastest on green procurement mandates.
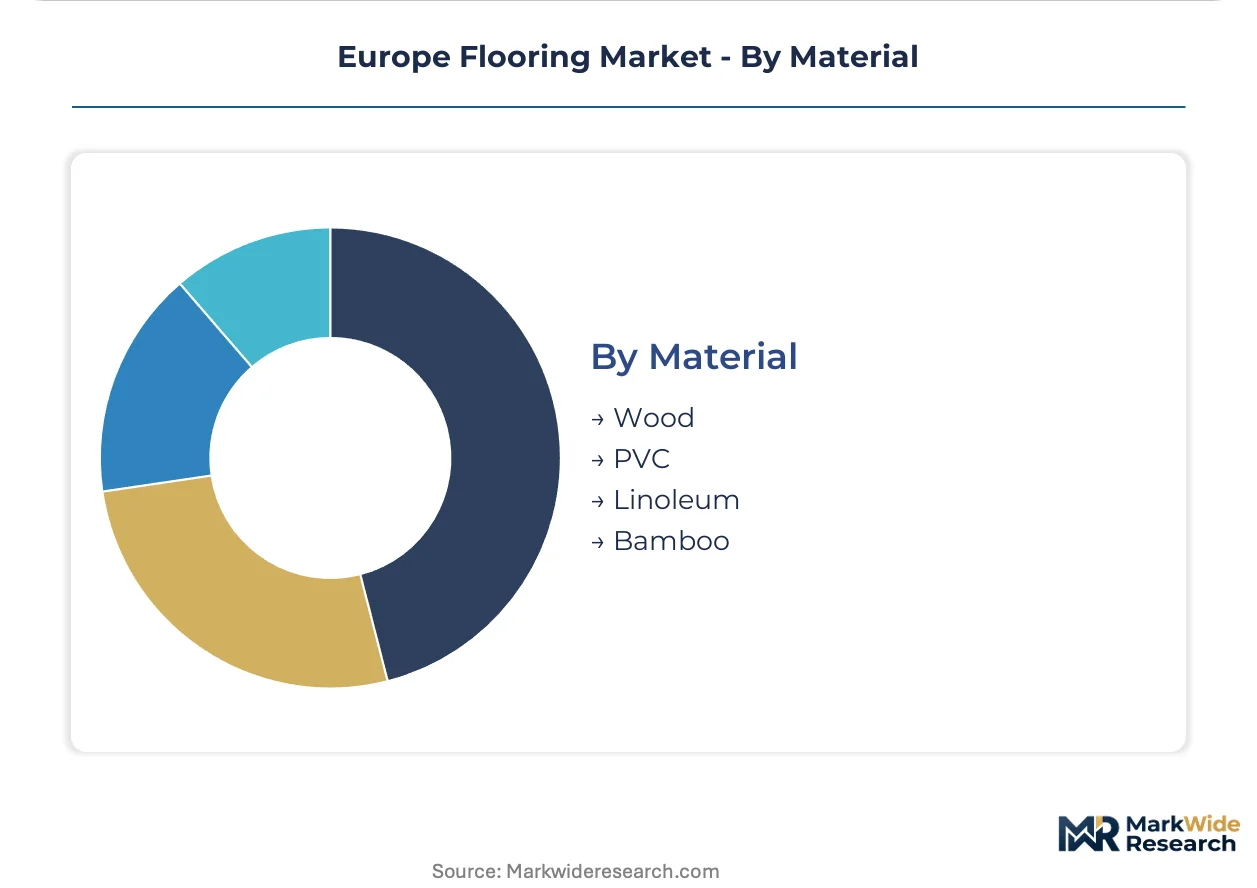
Material:
Supply concentration and regulatory exposure differentiate input cost trajectories.
- PVC:Petrochemical-derived polymer dominates vinyl flooring production. Integrated compounding capabilities at Tarkett's French and Swedish plants buffer against naphtha price volatility.
- Wood:Solid hardwood and engineered core construction depend on Baltic oak and ash clusters. FSC certification backlogs in Estonia and Lithuania constrain specification-ready supply.
- Linoleum:Bio-based composition of linseed oil, cork, and wood flour captures healthcare and education share as REACH restricts phthalate plasticizers in PVC alternatives.
- Bamboo:Rapid-renewable grass construction offers hardness comparable to hardwood with shorter harvest cycles, though moisture sensitivity limits specification in Nordic climates.
PVC retains volume leadership; linoleum is expanding most quickly on regulatory tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr industrial corridor anchors European flooring manufacturing capacity, with compounders and laminate producers clustering around Cologne and Düsseldorf to access petrochemical feedstocks and hardwood distribution networks.
Germany
Residential retrofit waves in North Rhine-Westphalia and Bavaria absorb record volumes of click-lock vinyl and engineered wood as building energy-efficiency mandates accelerate envelope upgrades. The country's national building code enforces strict thermal conductivity standards for underfloor heating compatibility. Manufacturing clusters around Cologne leverage integrated PVC compounding to buffer against naphtha price volatility.
France
Public procurement officers in Île-de-France and Auvergne-Rhône-Alpes weight EPD-verified embodied carbon at 15-30% of tender evaluation scoring, displacing lowest-price bidding in institutional contracts. The EU Green Deal's evolving thresholds shape specification behavior in Paris hospital renovation programs. Heterogeneous vinyl roll producers serving healthcare verticals face compressed compliance timelines around REACH phthalate restrictions.
Sweden
Stockholm and Oslo property developers specify rigid SPC core LVT for thermal conductivity optimization in residential new-builds with underfloor heating systems. The country's environmental protection agency enforces stringent formaldehyde emission ceilings on imported laminate products. Dry-lay contractor specialization is displacing traditional wet-installation trades across Scandinavian retrofit markets.
Netherlands
Rotterdam specification consultants actively filter manufacturers without third-party verified lifecycle data from public tender shortlists. The national building code mandates fire reaction class Bfl-s1 under EN 13501 for institutional flooring applications. Distribution clusters around the Port of Rotterdam facilitate bio-based linoleum imports serving healthcare and education sectors.
Belgium
Antwerp and Brussels hospital renovation programs specify seamless sheet vinyl systems for infection control protocols in patient recovery zones. REACH restrictions on short-chain chlorinated paraffins force PVC reformulation toward bio-based plasticizers. The country's central location enables just-in-time delivery to Benelux commercial construction projects facing skilled installer scarcity.
Europe Flooring Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue bio-based material specialization and digital product passport readiness. The vendor base organizes around three archetypes: integrated petrochemical compounders with captive resin supply, hardwood specialists dependent on Baltic certification chains, and linoleum revivalists capitalizing on REACH plasticizer restrictions. Competitive moves concentrate on M&A for geographic footprint expansion and backward integration into raw material compounding.
Among French flooring manufacturers, Tarkett and Gerflor exemplify divergent strategic positioning within the vinyl segment. Tarkett anchors integrated production capabilities across French and Swedish plants. Gerflor occupies a specialized position in heterogeneous vinyl rolls for healthcare and education verticals. Forbo Flooring represents the bio-based alternative archetype, with linoleum composition aligning with regulatory tailwinds from ECHA phthalate scrutiny. Mohawk Industries extends American manufacturing scale into European distribution networks, primarily for laminate and engineered wood categories.
| Leading Market Players |
|---|
| Gerflor |
| Polyflor |
| Tarkett |
| Berry Alloc |
| Parador |
| Forbo Flooring |
| Interface |
| Milliken Flooring |
| Mohawk Industries |
| Others |
Pricing and Supply Chain Analysis
The EU Green Deal's embodied carbon thresholds gate qualified supply and premium-tier pricing access, compressing margins for PVC-dependent producers while rewarding bio-based linoleum and certified hardwood with specification premiums in French and Dutch public tenders.
Pricing Analysis
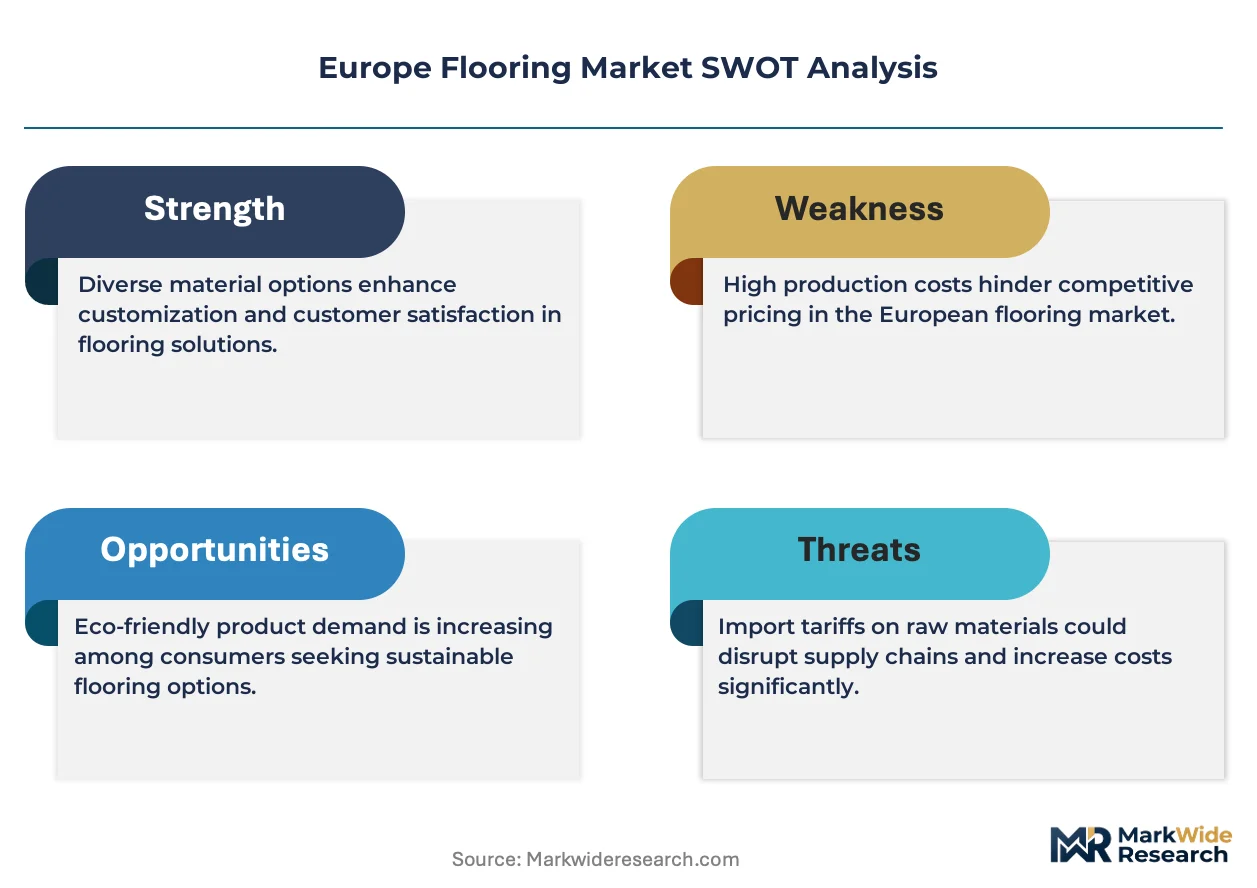
Petrochemical input-cost pass-through dominates vinyl flooring economics, with naphtha and ethylene price swings compressing margin predictability for manufacturers lacking integrated compounding capabilities. Three-tier pricing structure across premium, standard, and economy levels separates FSC-certified engineered hardwood from commodity laminate and imports. Pricing pressure stems from REACH phthalate restrictions forcing reformulation toward bio-plasticizers with higher raw material costs. Residential renovation buyers exhibit highest price sensitivity; institutional healthcare procurement prioritizes lifecycle cost over unit price.
Supply Chain Analysis
Direct-to-distributor channels handle volume demand from German residential retrofit contractors, while specification consultants in Paris and Rotterdam filter manufacturers for public tender eligibility. Baltic oak and ash clusters in Estonia, Latvia, and Lithuania anchor hardwood supply, with PVC resin sourcing concentrated in Rhine-Ruhr petrochemical corridors. Stone-polymer composite backing materials and bio-based linseed oil formulations constitute critical input dependencies. Single-source vulnerability runs through FSC certification backlogs in Baltic states. Distribution runs through Cologne-Düsseldorf logistics hubs serving Benelux and Nordic markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage positioning favors near-shore manufacturing in France and Sweden to exploit carbon border adjustment exemptions while accessing premium procurement channels in Paris and Stockholm that weight embodied carbon in tender scoring.
For Market Incumbents: Anchor competitiveness through backward integration into bio-plasticizer compounding and captive PVC resin supply, defending against REACH-driven substitution toward linoleum. Prioritize digital product passport readiness to maintain specification access in Dutch and French institutional procurement. Capacity consolidation in Nordic markets captures underfloor heating-driven demand for thermally conductive rigid core systems. For New Entrants and Emerging Players: Stone-polymer composite thermal conductivity optimization offers a technology-first wedge into Scandinavian residential new-build specifications underserved by traditional flexible vinyl producers. Target Belgian and French hospital renovation programs with antimicrobial surface treatment specialization. Go-to-market through specification consultant relationships in Rotterdam and Paris bypasses established distribution gatekeepers. For Investors and Strategic Acquirers: Roll-up economics work for bio-based flooring specialists because ECHA phthalate scrutiny creates durable regulatory tailwinds displacing conventional PVC over a multi-year horizon. Target acquisition archetype: linoleum manufacturers with EPD-verified lifecycle data and healthcare sector relationships. Watch for carbon border adjustment implementation timeline as inflection indicator for domestic manufacturing valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Bio-Plasticizer Formulation Shift | REACH compliance secures healthcare specification access in France and Belgium. |
| Digital Product Passport Investment | Early compliance unlocks preferential positioning in Dutch public procurement. |
| Baltic Certification Chain Integration | FSC chain-of-custody control mitigates supply bottleneck risk in Estonia. |
| Rigid SPC Capacity Expansion | Thermal conductivity optimization captures Nordic underfloor heating demand. |
| Healthcare Vertical Specialization | Antimicrobial treatments address infection control protocols in Belgian hospitals. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with flooring procurement managers at German residential developers, specification consultants in Paris and Rotterdam, plant managers at Rhine-Ruhr compounding facilities, and healthcare facilities directors in Belgium with secondary validation against CE marking databases, EPD registry filings, ECHA restriction proposals, and customs trade data. Bottom-up volume builds across product categories triangulated against top-down macroeconomic indicators.
Comparable-period anchoring tied projection models to historical renovation cycle patterns and regulatory implementation timelines across the analysis window. Segmentation dimensions modeled included product type, installation method, end-user vertical, material composition, and geographic procurement cluster. CAGRs derived from elasticity-adjusted demand curves incorporating energy-efficiency mandate intensity and green procurement weighting evolution. Industry-specific inputs encompassed underfloor heating penetration rates and phthalate restriction compliance cost curves.
The model holds under steady regulatory implementation schedules; deviation in EU Green Deal threshold acceleration or Baltic trade disruption would shift volume trajectories. Forecasts reflect base-case assumptions on raw material cost normalization and installer labor availability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
Turkey Floor Covering Market
Flooring, Carpets, and Rugs
US Terrazzo Market
Flooring, Carpets, and Rugs
Flooring Wood Panels Market
Flooring, Carpets, and Rugs
Carpets and Rugs Market
Flooring, Carpets, and Rugs
Hardwood Flooring Market
Flooring, Carpets, and Rugs
Foam Flooring Products Market
Flooring, Carpets, and Rugs
United States Laminate Flooring Market
Flooring, Carpets, and Rugs
China Wood Flooring Market
Flooring, Carpets, and Rugs
Netherlands Floor Covering Market
Flooring, Carpets, and Rugs
India Carpets and Rugs Market
Flooring, Carpets, and Rugs
Stone Flooring Market
Flooring, Carpets, and Rugs
Wood Flooring Market
Flooring, Carpets, and Rugs
Luxury Vinyl Tiles Market
Flooring, Carpets, and Rugs
Global Carpet Tile Market
Flooring, Carpets, and Rugs
GCC Floor Covering Market
Flooring, Carpets, and Rugs
United Kingdom Non-Resilient Floor Covering Market