
 Europe Carpet Tile Market | 2026-2036
Europe Carpet Tile Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Carpet Tile Market Foresight
Contractor and specifier channels in Europe is fragmenting as digital procurement platforms and direct manufacturer relationships displace traditional distribution hierarchies. Interface, Inc. leverages its Climate Take Back sustainability platform to anchor specification decisions with environmentally committed architects. Mohawk Industries competes through manufacturing scale across its European production footprint. Forbo Holding AG differentiates via integrated linoleum and carpet tile portfolios that sustain cross-selling momentum in healthcare and education sectors.
Europe carpet tile denotes modular floor coverings manufactured in standardized dimensions, typically 500mm x 500mm or 600mm x 600mm, composed of nylon, polypropylene, or wool face fibers bonded to bitumen, PVC, or polyurethane cushion backing for dimensional stability and acoustic dampening. These units install without full-spread adhesive, enabling selective replacement and reduced lifecycle waste in high-traffic commercial environments. Synthetic fiber products dominate volume shipments across the region, while natural fiber segments command premium positioning in Scandinavian public buildings and Dutch sustainable architecture. Interlocking installation systems represent the fastest-growing mechanical category, displacing glue-down methods where subfloor moisture or tenant turnover accelerates renovation cycles.
EU Green Deal carbon performance benchmarks, ECHA REACH chemical compliance protocols, and national building codes in Germany and France collectively mandate reduced embodied carbon and restricted substance content in commercial interior materials. CE marking under the Construction Products Regulation governs fire reaction, slip resistance, and VOC emission declarations required for market access across member states. Specifiers and procurement directors must monitor evolving Extended Producer Responsibility frameworks and digital product passport requirements that will reshape supplier qualification criteria and contract terms.
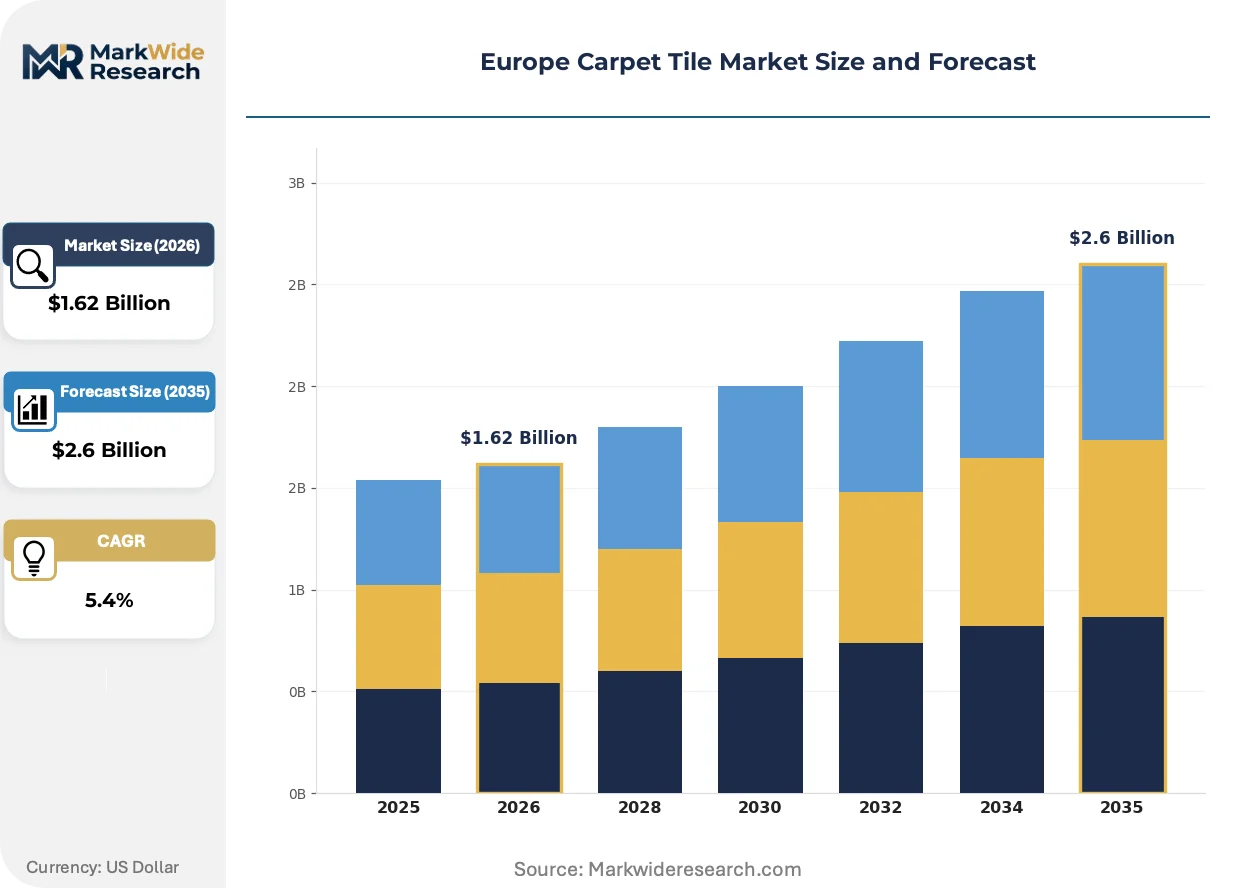
Market Dynamics
EU Green Deal carbon performance benchmarks and ECHA REACH chemical compliance protocols are compressing specification timelines across European commercial interiors, forcing rapid transitions in backing chemistry and fiber sourcing.
Growth Catalysts
- Corporate refurbishment cycles:Germany's corporate headquarters clusters and Dutch sustainable architecture projects are replacing broadloom with modular systems to accelerate tenant fit-outs and reduce downtime.
- EU Green Deal mandates:Carbon performance benchmarks for commercial buildings are elevating bio-based backing materials and recycled nylon content in specification criteria.
- Interlocking installation systems:Mechanical attachment methods are gaining share in Nordic healthcare and education sectors where moisture-prone subfloors and frequent renovation cycles demand glue-free alternatives.
Market Restraints
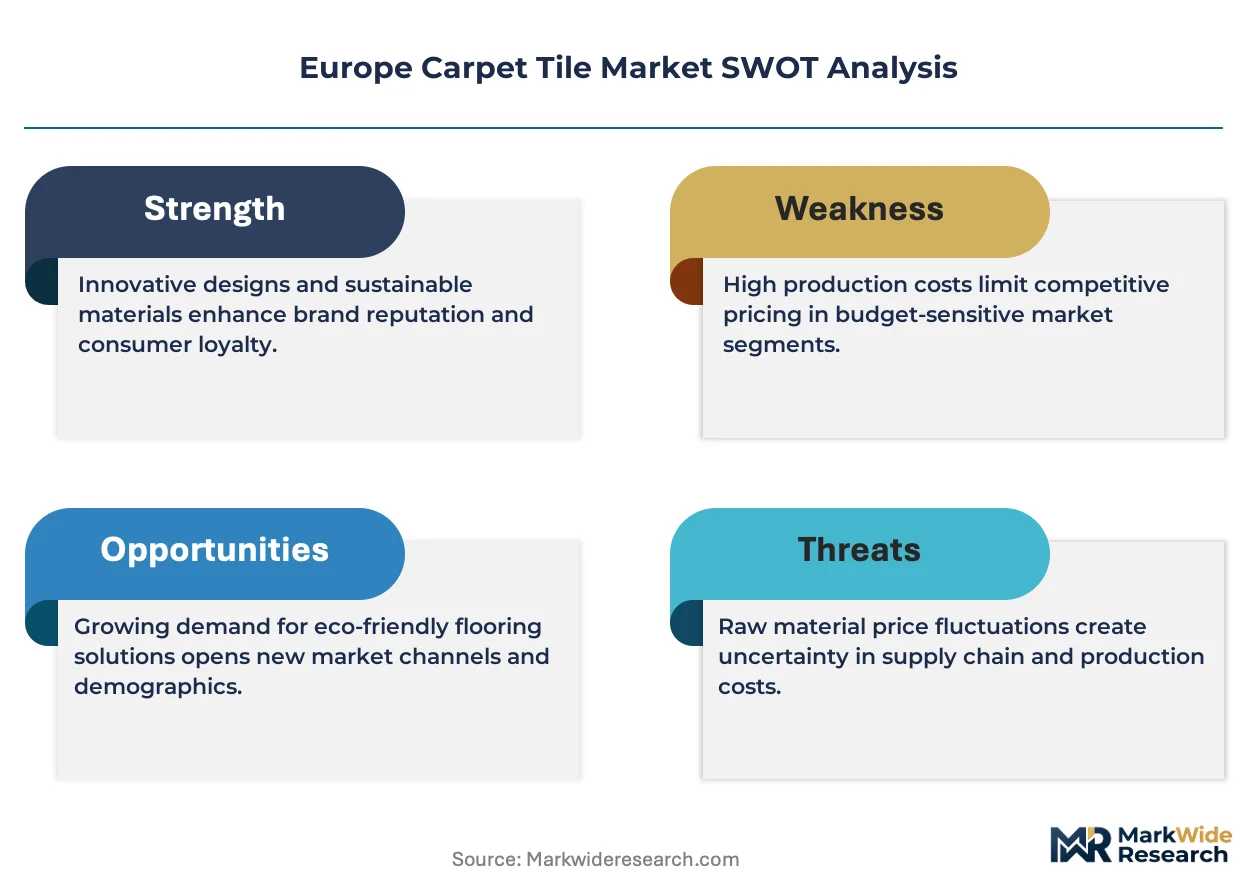
- Caprolactam price volatility:Nylon 6,6 fiber production depends on petrochemical feedstock costs that swing with crude oil and natural gas benchmarks, compressing margin predictability for manufacturers.
- Bitumen supply concentration:European bitumen for carpet tile backing concentrates among a limited set of refiners in the Netherlands and Belgium, creating single-source vulnerability.
- PVC substitution pressure:ECHA REACH restrictions on phthalate plasticizers and chlorine content are forcing costly reformulation of legacy PVC cushion backings ahead of viable alternatives.
Strategic Opportunities
- Polish and Romanian commercial construction:Underpenetrated markets in Central Europe present first-mover positioning for manufacturers establishing regional distribution hubs ahead of EU cohesion fund infrastructure deployment.
- Digital product passports:Extended Producer Responsibility frameworks and blockchain-tracked material provenance will differentiate suppliers in French and German public procurement.
- Acoustic performance convergence:Integration of carpet tile with raised access flooring and underfloor air distribution systems creates specification bundles for data center and laboratory verticals.
Industry Challenges
- Polymer chemist scarcity:Formulation expertise for bio-based polyurethane backings and recycled nylon quality stabilization is concentrated among retiring specialists in Germany and Italy.
- CE marking timeline compression:Construction Products Regulation fire reaction and VOC emission testing protocols are extending product launch cycles by eight to fourteen months.
- Legacy inventory reconciliation:Distributors face write-down pressure on pre-REACH bitumen-backed stock as specifier preference shifts toward compliant alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Carpet Tile Market |
| Market Size in 2026 | $1.62 Billion |
| Market Size in 2035 | $2.6 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Fiber, Synthetic Fiber, Vinyl, Carpet Tiles Installation Type: Glue-down, Interlocking, Loose Lay, Staple-down End User: Commercial, Residential, Institutional, Educational Style: Modern, Traditional, Abstract, Textured |
| Companies Covered | Mohawk Industries, Forbo Holding AG, Interface, Inc., Beaulieu International Group, Gerflor SAS, Tarkett S.A., Milliken & Company, Ege Carpets A/S, Shaw Industries, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Carpet Tile Market Shifts & Advancements
Material science advances and procurement digitization are restructuring how carpet tile is specified, manufactured, and installed across European commercial interiors.
Polyurethane cushion backing is hybridizing bitumen's dimensional stability with PVC's acoustic performance while eliminating hazardous substance content. Healthcare and education specifiers in France and the Netherlands are specifying these systems for high-traffic corridors. The technology is compressing the performance gap between synthetic and natural fiber face constructions.
ECHA REACH restrictions on hazardous substances are accelerating shifts toward bio-based backing materials and closed-loop nylon recycling. Manufacturers must reformulate existing product lines or exit the European market. German corporate headquarters clusters and Nordic sustainable building projects are enforcing these compliance thresholds in procurement criteria.
Digital procurement platforms are displacing traditional distributor hierarchies in contractor and specifier channels. Direct manufacturer relationships now anchor large commercial refurbishment contracts in the Netherlands and Belgium. French public building tenders are piloting automated specification matching against carbon performance databases.
Europe Carpet Tile Market Segmentation
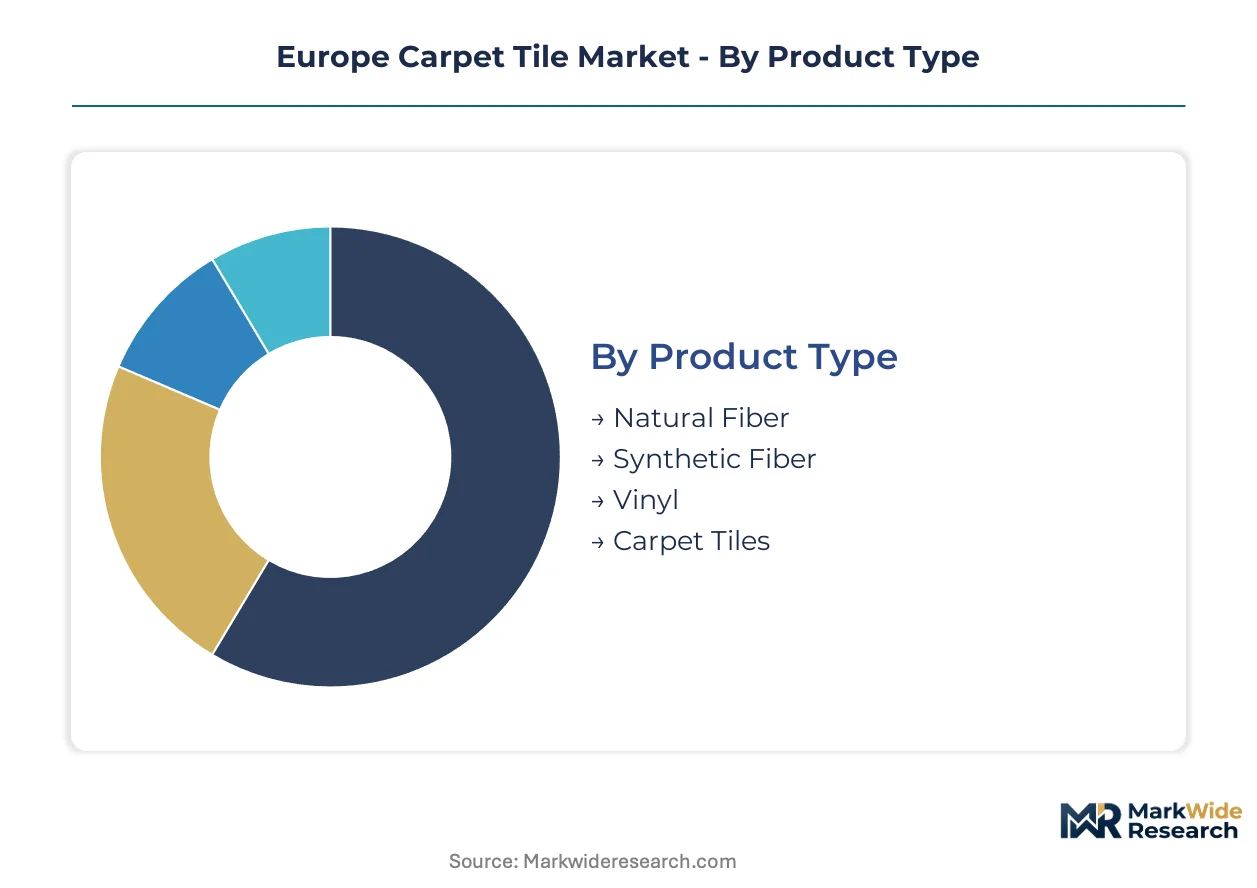
Segmentation in the Europe carpet tile market reveals how specification criteria fragment across installation constraints, regulatory exposure, and aesthetic positioning. Procurement directors and architects navigate these dimensions to align modular flooring choices with project-specific performance requirements and compliance obligations.
Product Type:
Material composition determines acoustic performance, lifecycle durability, and regulatory compliance exposure across European commercial interiors.
- Natural Fiber:Wool and sisal face fibers bonded to bio-based backings serve Scandinavian public buildings and Dutch sustainable architecture where EU Green Deal carbon benchmarks elevate embodied carbon scrutiny. Procurement in Germany's corporate headquarters clusters prioritizes these materials for LEED-equivalent certification pathways despite premium pricing.
- Synthetic Fiber:Nylon 6,6 and polypropylene constructions dominate volume shipments across the region, with recycled content grades gaining specification share under ECHA REACH compliance protocols. France and the Netherlands drive demand for closed-loop nylon with verified post-consumer content.
- Vinyl:PVC cushion backings face substitution pressure from polyurethane hybrids as phthalate restrictions tighten formulation options.
- Carpet Tiles:Broadloom-to-modular conversion accelerates in commercial refurbishment cycles where selective replacement reduces lifecycle waste.
The dominant share belongs to Synthetic Fiber, while Natural Fiber is closing the gap fastest.
Installation Type:
Attachment method selection hinges on subfloor moisture conditions, tenant turnover frequency, and renovation timeline compression.
- Interlocking:Mechanical attachment systems eliminate adhesive curing periods and enable rapid tenant repositioning in Nordic healthcare and education sectors where moisture-prone concrete subfloors complicate glue-down alternatives. These systems are expanding fastest in Belgian and Dutch commercial refurbishment.
- Glue-down:Full-spread adhesive methods retain share in permanent installations with stable subfloor conditions and extended lease terms.
- Loose Lay:Friction-based systems suit temporary event spaces and exhibition halls requiring rapid deployment and removal.
- Staple-down:Wood subfloor attachment persists in heritage building conversions where substrate preservation limits adhesive options.
Interlocking systems command the steepest expansion trajectory as glue-free specification spreads from healthcare into general commercial.
End User:
Occupancy patterns and regulatory exposure differentiate procurement priorities across building typologies.
- Commercial:Corporate offices, retail, and hospitality drive volume demand in Germany's headquarters corridors and French business districts where refurbishment cycles compress downtime windows. Modular systems accelerate tenant fit-outs in Amsterdam and Frankfurt financial centers.
- Institutional:Government and healthcare facilities in France and Belgium enforce strict ECHA REACH compliance and fire reaction standards through public procurement frameworks.
- Educational:Schools and universities in the Netherlands specify acoustic-rated systems for open-plan learning environments.
- Residential:Multi-family housing and home offices represent emerging adoption in urban densification projects across Nordic capitals.
Commercial installations retain volume leadership, though Institutional procurement is tightening compliance requirements fastest.
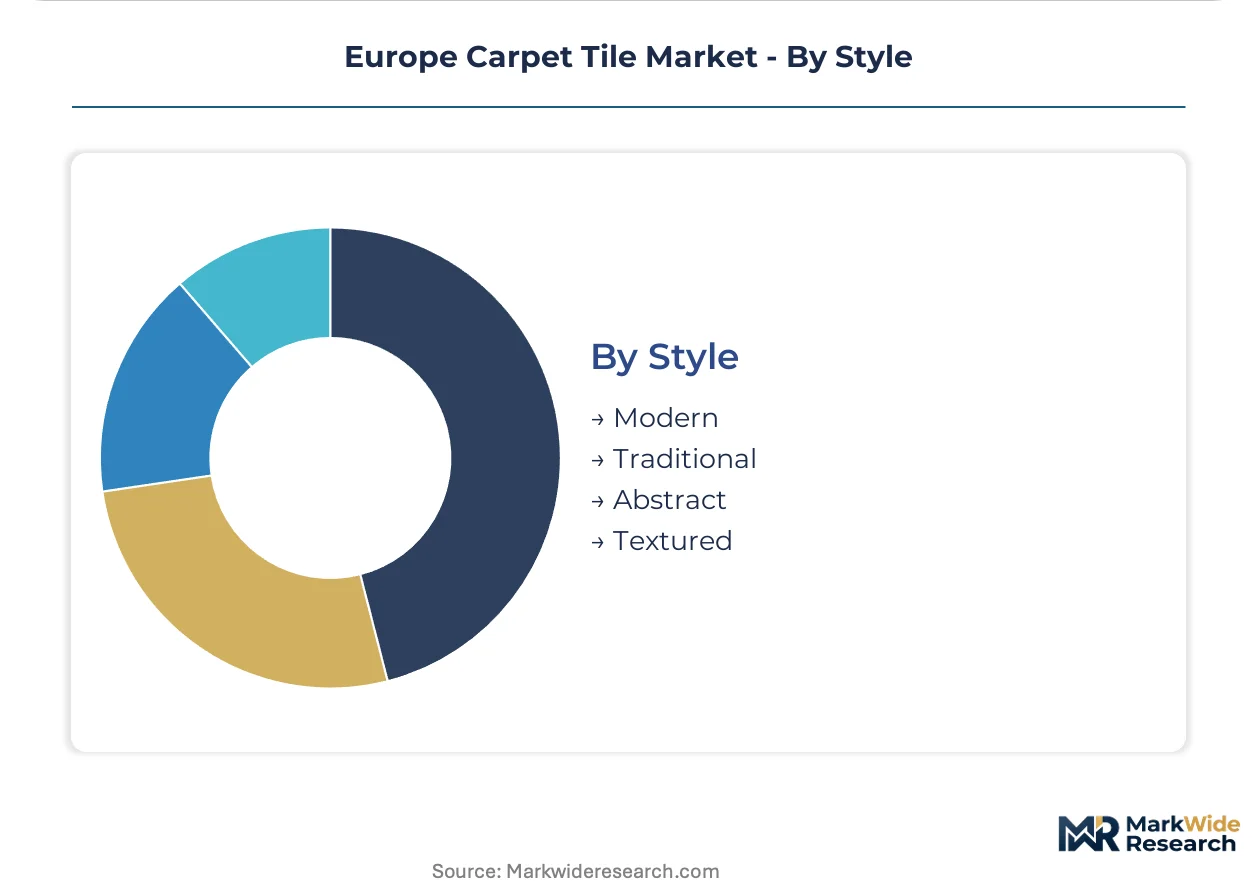
Style:
Aesthetic positioning aligns with building identity, wayfinding requirements, and biophilic design integration.
- Modern:Clean lines and neutral palettes dominate German corporate interiors and Dutch minimalist architecture where specification favors understated modularity.
- Abstract:Non-representational patterns enable wayfinding and zone differentiation in French healthcare and Belgian education corridors without figurative distraction.
- Textured:Dimensional surfaces address acoustic dampening and underfoot comfort in Nordic institutional settings.
- Traditional:Classic motifs persist in heritage-sensitive renovations across historic European city centers.
Modern styling holds the largest specification share, while Abstract applications are climbing fastest in healthcare wayfinding projects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Alpine freight corridor underwrites Germany's centrality in European carpet tile distribution, connecting Rotterdam's petrochemical terminals to manufacturing clusters along the Upper Rhine. This infrastructure backbone positions the region for rapid specification turnaround across corporate refurbishment cycles.
Germany
Corporate headquarters clusters in Frankfurt and Munich are replacing broadloom with modular systems to compress tenant fit-out timelines. The country's national building codes mandate fire reaction and VOC emission standards that exceed baseline CE marking requirements. Manufacturing concentration in North Rhine-Westphalia supplies rapid-turn specification for Rhine-Ruhr metropolitan commercial corridors.
Netherlands
Amsterdam's financial district and Rotterdam's port-adjacent logistics centers drive demand for glue-free interlocking systems. Dutch sustainable architecture procurement frameworks enforce EU Green Deal carbon performance benchmarks in public building tenders. Bitumen refiners in the Port of Rotterdam supply backing material to regional manufacturers serving Benelux refurbishment markets.
France
Paris business districts and Lyon healthcare complexes specify acoustic-rated modular flooring for open-plan environments. ECHA REACH restrictions on phthalate plasticizers are forcing reformulation of legacy PVC cushion backings ahead of viable alternatives. Manufacturing presence in Hauts-de-France serves northern European export markets with REACH-compliant product lines.
Belgium
Brussels institutional procurement and Antwerp port logistics facilities prioritize rapid-install mechanical attachment systems. CE marking under the Construction Products Regulation governs fire reaction declarations required for market access across member states. Carpet tile distribution hubs in Flanders coordinate just-in-time delivery to Benelux commercial refurbishment sites.
Poland
Warsaw corporate offices and Kraków shared service centers represent underpenetrated conversion opportunities from broadloom to modular systems. EU cohesion fund infrastructure deployment is accelerating commercial construction in Central European markets. Regional distribution hubs in Silesia position manufacturers for first-mover advantage ahead of specification standardization.
Europe Carpet Tile Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in backing chemistry and fiber supply. The vendor base concentrates among integrated flooring conglomerates with European manufacturing footprints and mid-scale specialists with sustainability differentiation. Three archetypes dominate: scale-driven manufacturers with captive raw material access, sustainability-platform specialists anchoring architect specifications, and integrated resilient flooring providers cross-selling modular carpet. Competitive moves center on portfolio diversification into bio-based backings and strategic partnerships with digital procurement platforms.
Within the sustainability-platform tier, Interface, Inc. and Forbo Holding AG exemplify archetype positioning through integrated environmental credentialing systems. Mohawk Industries represents scale-driven manufacturing consolidation with European production footprint coverage. These three entities anchor the competitive structure through contrasting approaches to specification influence, with sustainability credentials, manufacturing scale, and portfolio breadth serving as alternative vectors for market access.
| Leading Market Players |
|---|
| Mohawk Industries |
| Forbo Holding AG |
| Interface, Inc. |
| Beaulieu International Group |
| Gerflor SAS |
| Tarkett S.A. |
| Milliken & Company |
| Ege Carpets A/S |
| Shaw Industries |
| Others |
Supply & Pricing Matrix
Bitumen supply concentration in the Netherlands and Belgium determines both margin compression in standard-grade backings and the geographic clustering of European manufacturing assets. Procurement directors face tiered pricing spreads that widen when Rotterdam refinery output fluctuates, forcing specification shifts toward polyurethane alternatives.
Pricing Analysis
Volume-discount tiering separates premium bio-based systems from standard bitumen-backed and economy PVC constructions across German and French procurement frameworks. Price differentiation rests on ECHA REACH certification grade and recycled nylon content verification, with sustainability premiums expanding as EU Green Deal mandates tighten. Cost compression in standard tiers is intensifying because caprolactam feedstock volatility compresses manufacturer margins. Institutional buyers in healthcare and education sectors demonstrate lowest price sensitivity, while Polish and Romanian commercial developers anchor the economy tier.
Supply Chain Analysis
Tariff exposure between European Union member states and third-country polymer suppliers dominates supply chain risk assessment for carpet tile manufacturers. Raw material sourcing draws from German caprolactam producers, Dutch bitumen refiners, and Italian polyurethane formulators, creating cross-border dependency webs. Single-source vulnerability concentrates in Rotterdam-area bitumen supply, where limited refiner count amplifies disruption risk. Distribution runs through Rhine-Alpine freight corridors connecting manufacturing clusters to Benelux specification hubs, with digital procurement platforms displacing traditional distributor hierarchies in contractor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe carpet tile operates as a regulatory-moat market where ECHA REACH compliance entrenchment and CE marking certification timelines create formidable switching costs for specification relationships.
For Market Incumbents: Pre-empt PVC substitution pressure by accelerating bio-based polyurethane backing capacity in North Rhine-Westphalia manufacturing clusters ahead of ECHA phthalate restriction deadlines. Anchor specification relationships through Climate Take Back sustainability credentialing and digital product passport integration to defend against emerging Polish and Romanian distribution hub entrants. Certification investment in EU Green Deal carbon benchmarking represents the critical defensive lever. For New Entrants and Emerging Players: Central European underpenetration in Warsaw corporate offices and Kraków shared service centers offers first-mover positioning before specification standardization solidifies. Target acoustic-rated interlocking systems for Nordic healthcare and education sectors where glue-free installation demand outpaces incumbent supply capacity. Establish direct manufacturer relationships with Dutch digital procurement platforms to bypass entrenched distributor hierarchies. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors sustainability-platform specialists with integrated environmental credentialing systems. Long-term viability over the next decade hinges on bio-based backing formulation expertise and closed-loop nylon recycling infrastructure. Watch for digital product passport mandate acceleration as the signal indicating regulatory entrenchment deepening.| Strategic Initiative | Industry Significance |
|---|---|
| Bio-Based Backing Capacity Expansion | North Rhine-Westphalia manufacturing investments align with ECHA REACH phthalate restriction timelines. |
| Closed-Loop Nylon Recycling Infrastructure | Post-consumer content verification systems satisfy French and Dutch public procurement frameworks. |
| Digital Product Passport Integration | Blockchain-tracked material provenance differentiates suppliers in German sustainable building tenders. |
| Interlocking Installation System Development | Glue-free mechanical attachment captures Nordic healthcare and education specification share. |
| Central European Distribution Hub Establishment | Silesia-based logistics positioning targets EU cohesion fund infrastructure deployment cycles. |
Research Methodology
Operator-level perspectives from carpet tile plant managers, commercial flooring procurement directors, architect specification consultants, and ECHA regulatory compliance officers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through EU Construction Products Regulation databases, ECHA REACH substance restriction filings, Benelux customs trade records, and German national building code documentation. Bottom-up shipment analysis triangulated against top-down construction spend models across the analysis window.
Scenario-bracketing around EU Green Deal implementation pace and caprolactam price volatility shaped the analytical framework. Segmentation dimensions modeled include fiber composition, backing chemistry, installation method, end-use building typology, and regional regulatory cluster. CAGRs were derived from installed base replacement cycles and commercial construction permit trajectories, with input variables spanning embodied carbon benchmark adoption rates and digital procurement platform penetration.
Practitioners should monitor ECHA substance restriction expansion, Rotterdam bitumen refinery capacity utilization, and Polish commercial construction permit acceleration for early signals of forecast revision. Forecasts reflect assumptions about regulatory timeline adherence and raw material supply continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
Saudi Arabia Floor Covering Market
Flooring, Carpets, and Rugs
United States Laminate Flooring Market
Flooring, Carpets, and Rugs
Global Luxury Vinyl Tile Floor Covering Market
Flooring, Carpets, and Rugs
Bath Rugs and Mats Market
Flooring, Carpets, and Rugs
Entrance Matting Market
Flooring, Carpets, and Rugs
Wood and Laminate Flooring Market
Flooring, Carpets, and Rugs
Luxury Vinyl Tiles Market
Flooring, Carpets, and Rugs
India Wood Flooring Market
Flooring, Carpets, and Rugs
Quarter Sawn Flooring Market
Flooring, Carpets, and Rugs
Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Australia & New Zealand Flooring Market
Flooring, Carpets, and Rugs
Fiberglass Flooring Market
Flooring, Carpets, and Rugs
Global Flooring and Carpet Market
Flooring, Carpets, and Rugs
Europe Vinyl Flooring Market
Flooring, Carpets, and Rugs
Global Flooring Market
Flooring, Carpets, and Rugs
Rugs Market