
 Brazil Floor Covering Market | 2026-2036
Brazil Floor Covering Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Floor Covering Market Outlook
Skilled ceramic tile installer availability is bifurcating the Brazil floor covering landscape, with metropolitan São Paulo facing acute labor shortages while northeastern production hubs retain surplus craft capacity. Eucatex leverages its integrated wood-fiber supply chain to dominate engineered flooring in southern Brazil. Portobello SA anchors premium ceramic exports through sustained design-led positioning. Dexco competes across multiple price tiers through extensive distribution control in the residential channel.
Brazil floor covering encompasses surface materials installed to protect, finish, and aesthetically enhance interior substrates, with ceramic tiles typically fired at 1,100–1,200°C for vitrification and vinyl products calendered into multi-layer PVC constructions with wear-layer thicknesses ranging from 0.3 mm to 0.7 mm. These materials serve primarily to provide durable, hygienic, and visually specified walking surfaces across residential, commercial, and industrial environments. Tiles command the largest installed base in Brazil's humid coastal climates where moisture resistance proves critical. Vinyl represents the fastest-expanding material category as click-lock installation systems reduce labor dependency and accelerate project completion. Natural fiber carpets occupy a narrowing premium niche concentrated in hospitality applications seeking acoustic and tactile differentiation.
ANVISA governs chemical emissions and indoor air quality standards for flooring materials sold in Brazil, while the Brazilian Institute of Metrology, Standardization and Industrial Quality (INMETRO) administers conformity assessment and labeling requirements that manufacturers must satisfy for market access. The National Sanitary Surveillance Agency's tightening VOC thresholds are redirecting formulation investments toward water-based adhesives and solvent-free surface treatments. INMETRO's mandatory certification cycles create compliance barriers that favor scaled producers with dedicated regulatory affairs capabilities. Stakeholders must monitor pending updates to Brazil's Consumer Protection Code provisions on product durability claims, as these will reshape warranty obligations and liability exposure across the supply chain.
Market Dynamics
ANVISA's tightening VOC emission thresholds are forcing wholesale reformulation of adhesives and surface treatments across Brazil's floor covering supply chain, compressing margins for non-compliant producers while rewarding scaled manufacturers with dedicated regulatory affairs capabilities.
Growth Catalysts
- São Paulo residential construction:New housing starts in Brazil's wealthiest state are absorbing record volumes of ceramic tile and luxury vinyl plank, with developers specifying moisture-resistant materials for coastal humidity zones.
- Click-lock vinyl systems:Mechanical fastening technology is reducing installation labor dependency by eliminating adhesive curing times, accelerating project completion for commercial fit-out contractors facing tight deadlines.
- INMETRO certification cycles:Mandatory conformity assessment creates compliance barriers that favor established producers, concentrating market access among manufacturers with dedicated testing infrastructure and regulatory staff.
Market Restraints
- Ceramic tile input volatility:Natural gas and kaolin clay costs fluctuate with global energy markets, squeezing margins for producers without long-term supply contracts or captive mineral reserves.
- Northeastern labor surplus concentration:Skilled installer capacity pools in Ceará and Pernambuco while metropolitan São Paulo faces acute shortages, creating regional price divergence and project delays.
- Vinyl wear-layer technical limits:Current calendering technology caps commercial-grade durability at 0.7 mm thickness, restricting specification in high-traffic airport and hospital corridors where rubber or epoxy alternatives dominate.
Strategic Opportunities
- Minas Gerais industrial corridor:Underpenetrated commercial flooring demand from Belo Horizonte's expanding logistics and manufacturing hubs offers volume growth outside saturated São Paulo markets.
- Water-based adhesive convergence:Formulation chemistry advances combining polyurethane dispersion with silane termination are enabling solvent-free installation systems that meet ANVISA thresholds without performance sacrifice.
- Direct-to-contractor digital channels:B2B platforms bypass traditional distributor markups for midsize installation firms, capturing margin and building loyalty through project financing and real-time inventory visibility.
Industry Challenges
- Certified installer scarcity:ABNT NBR 13755 ceramic tile installation standards require trained craftspersons, but vocational pipeline output lags retirement rates in southeastern Brazil.
- Legacy distributor integration:ERP system harmonization between manufacturer SAP deployments and independent wholesaler accounting software creates order-processing friction and inventory visibility gaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Floor Covering Market |
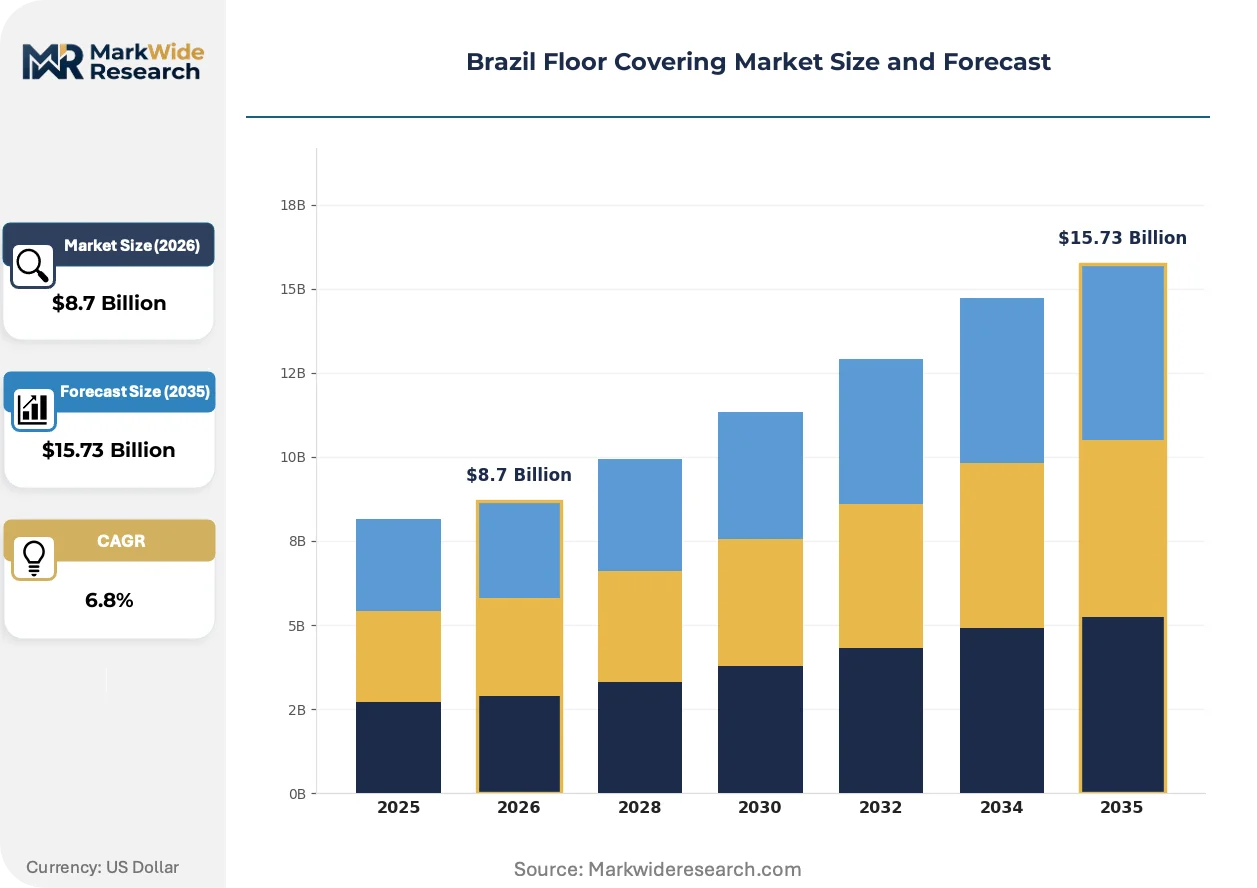
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carpets, Tiles, Laminate, Vinyl Material: Natural Fibers, Synthetic Fibers, Wood, PVC Installation Type: Glue-Down, Click-Lock, Loose Lay, Staple Down End User: Residential, Commercial, Hospitality, Industrial |
| Companies Covered | Eucatex, Ceramica Almeida, Portobello SA, Grupo Fragnani, Grupo Cedasa, Mohawk Industries, Dexco, Castelatto, Tarkett Brasil, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Floor Covering Market Strategic Shifts
Digital surface printing and modular installation systems are compressing traditional material hierarchies in Brazil, enabling specification flexibility that rewards responsive supply chains over asset-heavy manufacturing scale.
Dry-back adhesive-free vinyl plank is decomposing the ceramic tile installation value chain by eliminating substrate preparation and curing delays. Commercial property managers in Rio de Janeiro's retail sector are specifying floating floor systems to minimize tenant improvement downtime. This technology is decomposing the traditional 72-hour project timeline into same-day occupancy handovers, compressing labor cost structures and redirecting specification authority from installers toward facility managers.
ANVISA's updated chemical emission protocols for indoor building materials are redirecting R&D investment toward water-based polyurethane and silane-modified polymer formulations. Manufacturers must reformulate adhesives and surface coatings to meet tightening TVOC thresholds or face market exclusion. Southern Brazilian production facilities are responding fastest, leveraging proximity to petrochemical feedstocks and established technical service infrastructure to accelerate compliance certification.
Facility managers are consolidating flooring procurement under single-source national contracts with performance-based maintenance riders, displacing project-by-project competitive bidding. Large retail chains and hospital networks are bundling material supply with scheduled refinishing and damage replacement services. This consolidation is most visible in São Paulo state's healthcare vertical, where integrated service contracts now govern over half of new hospital construction flooring specifications.
Brazil Floor Covering Market Segmentation
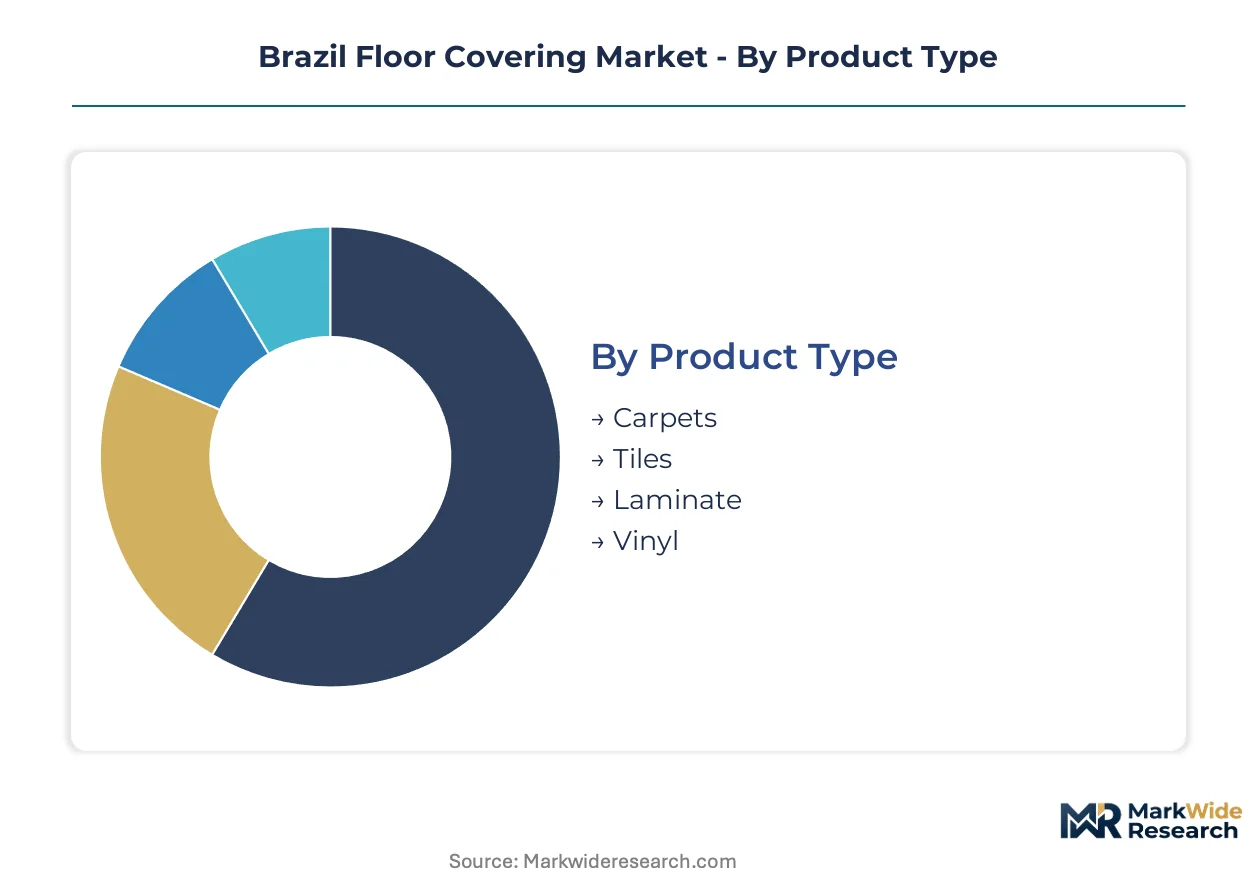
Floor covering demand in Brazil fragments across material performance requirements, installation labor availability, and regional climate conditions. Segment boundaries blur as click-lock systems and water-based formulations reshape traditional specification hierarchies across São Paulo's construction corridor.
Product Type:
Tiles dominate domestic absorption in southeastern states, while vinyl exports gain traction across Mercosur markets seeking Brazilian manufacturing scale.
- Tiles:Ceramic and porcelain products fired at 1,100–1,200°C deliver vitrified moisture resistance essential for Brazil's humid coastal climates. São Paulo residential developers specify large-format tiles for high-rise bathrooms and kitchens, though installer scarcity in metropolitan zones constrains project velocity.
- Vinyl:Multi-layer PVC constructions with wear-layer thicknesses from 0.3 mm to 0.7 mm enable rapid commercial fit-outs without adhesive curing delays. Rio de Janeiro retail property managers favor floating vinyl systems to compress tenant improvement timelines into same-day handovers.
- Carpets:Natural and synthetic fiber constructions occupy narrowing premium niches concentrated in hospitality acoustic applications.
- Laminate:HDF-core products with melamine wear surfaces compete on price in residential renovation segments where moisture exposure remains limited.
Tiles hold the largest share; momentum sits with vinyl.
Material:
Raw material sourcing geography dictates formulation strategies, with southern Brazilian petrochemical corridors feeding PVC expansion while northeastern fiber production serves carpet remnants.
- PVC:Calendered vinyl formulations leverage Rio Grande do Sul's integrated petrochemical infrastructure for cost-competitive multi-layer construction. ANVISA's tightening VOC thresholds are redirecting plasticizer selection toward phthalate-free alternatives without sacrificing calendering throughput.
- Wood:Engineered flooring combines tropical hardwood veneers with plantation eucalyptus cores, exploiting southern Brazil's captive fiber supply. Eucatex's integrated pulp-to-panel operations dominate this segment through backward control over raw material flows.
- Natural Fibers:Sisal and wool constructions serve boutique hospitality specifications seeking tactile differentiation in São Paulo's luxury hotel sector.
- Synthetic Fibers:Nylon and polypropylene carpet face yarns face substitution pressure from vinyl in commercial maintenance-conscious environments.
Wood maintains established share; PVC climbs the fastest on formulation flexibility and regulatory compliance velocity.
Installation Type:
Labor cost structures and project timeline pressures determine system selection, with adhesive-free methods gaining preference where skilled installer pools contract.
- Click-Lock:Mechanical fastening systems eliminate substrate preparation and curing delays, compressing commercial project schedules. Facility managers in Belo Horizonte's expanding logistics hubs specify floating floors to minimize operational downtime during tenant rotations.
- Glue-Down:Full-spread adhesive application remains standard for ceramic tile in wet-area specifications, though ANVISA-compliant water-based polyurethane formulations now displace solvent-bearing predecessors.
- Loose Lay:Friction-based installation suits temporary commercial deployments and exhibition spaces requiring rapid material recovery.
- Staple Down:Traditional carpet attachment persists in residential applications where subfloor conditions permit mechanical fastening economics.
Glue-down retains volume dominance; click-lock gains share fastest through labor arbitrage and schedule compression.
End User:
Customer procurement sophistication varies sharply, with national retail chains and hospital networks consolidating under single-source service contracts while fragmented residential demand flows through distributor channels.
- Commercial:Office and retail fit-outs specify modular systems enabling rapid reconfiguration, with Rio de Janeiro shopping center operators prioritizing minimize downtime during tenant churn. Performance-based maintenance riders now accompany material supply in negotiated national contracts.
- Residential:São Paulo state housing starts absorb record ceramic tile volumes, though first-time buyer segments show price-driven migration toward vinyl alternatives. Northeastern production hubs retain surplus installer capacity while southeastern metropolitan zones face acute craft shortages.
- Hospitality:Boutique hotels and resort properties specify natural fiber carpets for acoustic and tactile differentiation, though volume remains constrained by narrow premium positioning.
- Industrial:Manufacturing and logistics facilities in Minas Gerais prioritize durability over aesthetics, specifying epoxy and rubber alternatives where vinyl wear-layer limits prove restrictive.
Residential commands absolute volume; commercial shows steepest expansion trajectory through procurement consolidation and service bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANVISA governs chemical emission standards across Brazil's floor covering supply chain, concentrating regulatory scrutiny on southeastern manufacturing corridors where production volumes intersect with dense residential construction.
São Paulo
São Paulo state absorbs record ceramic tile volumes from new housing starts, with developers specifying moisture-resistant materials for high-rise bathrooms and coastal humidity zones. INMETRO's mandatory certification cycles create compliance barriers that favor established producers with dedicated testing infrastructure. Metropolitan São Paulo faces acute installer shortages while production clusters in the interior maintain surplus craft capacity.
Minas Gerais
Belo Horizonte's expanding logistics and manufacturing hubs generate underpenetrated commercial flooring demand outside saturated southeastern markets. ANVISA's tightening VOC thresholds redirect formulation investments toward water-based adhesives in regional production facilities. The state's industrial corridor attracts specification from facility managers consolidating procurement under performance-based maintenance contracts.
Rio de Janeiro
Rio de Janeiro retail property managers prioritize floating vinyl systems to compress tenant improvement timelines into same-day handovers. The state's humid coastal climate sustains ceramic tile specification for moisture-critical applications. Portobello SA anchors premium ceramic exports through sustained design-led positioning from production bases in the metropolitan region.
Rio Grande do Sul
Southern Brazil's integrated petrochemical infrastructure feeds cost-competitive PVC calendering operations for multi-layer vinyl construction. Eucatex leverages captive wood-fiber supply chains to dominate engineered flooring through backward integration into plantation eucalyptus pulp. Regional production facilities respond fastest to ANVISA compliance deadlines, leveraging proximity to technical service infrastructure.
Bahia
Northeastern production hubs in Ceará and Pernambuco retain surplus ceramic tile installer capacity while southeastern metropolitan zones face acute craft shortages. The regional labor pool creates price divergence and project velocity advantages for developers willing to source cross-region. Dexco competes across multiple price tiers through extensive distribution control penetrating residential channels in Salvador's construction market.
Brazil Floor Covering Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across Brazil's floor covering sector. Ceramic specialists with captive mineral reserves and long-firing kilns compete against vinyl producers leveraging petrochemical integration and rapid calendering throughput. The market structures around three archetypes: integrated forest-product conglomerates, design-led ceramic exporters, and multi-category distributors with channel control. Dominant competitive moves include backward integration into raw material supply and strategic consolidation of installer networks through vocational training partnerships.
Within the integrated fiber-processing tier, Eucatex exemplifies vertical control from plantation to finished panel. Among ceramic specialists, Portobello SA occupies a position anchored in export-oriented design differentiation. Dexco sits within the multi-category distribution archetype, spanning price tiers through residential channel penetration. These three players represent distinct strategic vectors: captive supply security, premium specification authority, and mass-market access scale.
| Leading Market Players |
|---|
| Eucatex |
| Ceramica Almeida |
| Portobello SA |
| Grupo Fragnani |
| Grupo Cedasa |
| Mohawk Industries |
| Dexco |
| Castelatto |
| Tarkett Brasil |
| Others |
Value Chain & Pricing Dynamics
Water-based adhesive substitution for solvent-bearing formulations is redrawing raw material procurement maps across Brazil's floor covering sector, simultaneously elevating southern petrochemical corridors as formulation hubs and compressing margins for non-compliant producers facing reformulation costs. This chemistry transition concentrates pricing power among manufacturers with captive technical service infrastructure while penalizing distributors dependent on legacy inventory.
Pricing Analysis
São Paulo metropolitan zones command premium pricing over northeastern production hubs, with installer scarcity in the southeast inflating project quotes by substantial spreads. Pricing stratifies across premium, standard, and economy tiers, with differentiation driven by ANVISA certification grade and wear-layer thickness specifications. Cost compression in economy vinyl tiers is intensifying because kaolin clay and natural gas input volatility squeezes ceramic competitors. Residential first-time buyers exhibit highest price sensitivity, while hospital networks under national service contracts show least.
Supply Chain Analysis
Port congestion at Santos and Paranaguá elevates inbound logistics costs for titanium dioxide and specialty plasticizers sourced from Asian chemical producers. Manufacturing concentrates in Brazil, with southern Rio Grande do Sul feeding PVC calendering and southeastern São Paulo anchoring ceramic tile firing. Raw material dependencies center on imported pigments, domestic kaolin reserves, and regional petrochemical feedstocks. Single-source vulnerability runs through containerized specialty chemical lanes. Distribution runs through independent wholesaler networks with fragmented ERP integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's floor covering market demands substitution defense against click-lock vinyl systems decomposing traditional ceramic tile value chains. Incumbents must navigate this technology threat while reformulating for ANVISA compliance.
For Market Incumbents: Consolidate installer networks through vocational training partnerships in southeastern Brazil, addressing ABNT NBR 13755 certification scarcity that constrains project velocity. Deepen backward integration into captive mineral reserves or petrochemical feedstocks to buffer input cost volatility. Defensive positioning requires preemptive water-based adhesive certification before regulatory deadlines exclude solvent-bearing competitors. For New Entrants and Emerging Players: Anchor in Minas Gerais industrial corridor commercial flooring, where underpenetrated logistics and manufacturing hubs offer volume growth outside saturated São Paulo markets. Target facility managers consolidating procurement under performance-based maintenance contracts, bypassing fragmented distributor channels through direct B2B platforms with project financing capabilities. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors scaled producers with regulatory affairs capabilities over fragmented distributors. Long-term viability across the analysis window hinges on compliance velocity rather than manufacturing scale alone. Acquisition target archetype: southern Brazilian vinyl producers with ANVISA-certified formulation infrastructure. Signal to watch: INMETRO certification cycle backlogs as indicator of regulatory capacity constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Adhesive Certification | ANVISA compliance unlocks market access while excluding solvent-dependent competitors from specification. |
| Installer Network Consolidation | Vocational training partnerships address craft scarcity constraining project velocity in metropolitan São Paulo. |
| Direct-to-Contractor Platform Launch | B2B channels bypass distributor markups while capturing margin through project financing services. |
| Captive Mineral Reserve Acquisition | Backward integration into kaolin deposits buffers ceramic producers against global energy market volatility. |
| Performance-Based Service Contracting | Maintenance riders bundled with material supply lock in hospital and retail chain procurement consolidation. |
Study Parameters
A standing panel of ceramic tile plant managers, vinyl calendering technical directors, commercial property facility managers, and INMETRO certification specialists provided ongoing calibration across primary fieldwork. Secondary validation drew from ANVISA regulatory filings, INMETRO conformity assessment databases, Brazilian customs trade records, and ABNT technical standard documentation. Bottom-up volume modeling triangulated against top-down construction sector expenditure benchmarks.
Consistency checks validated outputs against external construction materials indices and regional housing start data across the projection horizon. The analytical framework segmented by material type, installation system, end-use vertical, and regional climate zone throughout the forecast period. CAGRs derived from elasticity-adjusted demand curves incorporating installer labor availability constraints and regulatory compliance cost pass-through assumptions.
Decision-makers should treat outputs as directional under stable ANVISA enforcement timelines and construction credit availability assumptions; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as INMETRO certification cycle durations and petrochemical feedstock pricing evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
US Wood Flooring Market
Flooring, Carpets, and Rugs
Indoor Flooring Market
Flooring, Carpets, and Rugs
Lightweight Acoustic Floor Systems Market
Flooring, Carpets, and Rugs
India Floor Covering Market
Flooring, Carpets, and Rugs
Global Vinyl Floor Covering Market
Flooring, Carpets, and Rugs
North America Carpet Tile Market
Flooring, Carpets, and Rugs
Global Floor Covering Market
Flooring, Carpets, and Rugs
US Vinyl Floorings Market
Flooring, Carpets, and Rugs
Global Carpet Tile Market
Flooring, Carpets, and Rugs
China Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
China Luxury Vinyl Tile (LVT) Market
Flooring, Carpets, and Rugs
Saudi Arabia Vinyl Flooring Market
Flooring, Carpets, and Rugs
Flooring for Tile and Stone Market
Flooring, Carpets, and Rugs
US Resilient Flooring Market
Flooring, Carpets, and Rugs
North America Wood Flooring Market
Flooring, Carpets, and Rugs
United States Floor Covering Market