
 Fiberglass Flooring Market | 2026-2036
Fiberglass Flooring Market Size, Share, and Industry Trends Forecast 2026-2036
Fiberglass Flooring Market Analysis
Buyer concentration among large-scale commercial contractors is restructuring procurement patterns across the fiberglass flooring supply chain. Armstrong World Industries leverages its vertical integration into raw fiberglass mat production to secure cost advantages on large healthcare and education projects. Shaw Floors anchors its position through proprietary fiberglass backing technologies that reduce installation labor hours. Mannington Mills differentiates via regional manufacturing scale that shortens lead times for southeastern United States commercial developers.
Fiberglass flooring comprises a composite structure of woven or non-woven glass fiber mat embedded within vinyl or thermoplastic polymer layers, typically measuring 2–4 mm in total thickness with fiberglass content ranging from 15–25 percent by weight, engineered to provide dimensional stability across temperature fluctuations and resist moisture-induced expansion. The product serves primarily as a durable, dimensionally stable substrate for luxury vinyl tile and sheet goods in high-traffic commercial environments. Sheets command the largest volume share within product types due to their seamless installation in healthcare and cleanroom settings where microbial control matters. Planks represent the fastest-expanding category as click-lock systems displace traditional glue-down methods in retail and hospitality renovation cycles. Residential end users generate thinner margin pools compared to institutional buyers, where specification lock-in through architect relationships creates multi-year revenue visibility.
The EPA oversees volatile organic compound emissions from flooring adhesives and finished products through its Indoor airPLUS program, while OSHA workplace safety standards influence installer exposure limits during fiberglass handling and cutting operations. California's Air Resources Board maintains the nation's most stringent formaldehyde emission thresholds, effectively setting the compliance ceiling for products sold across multiple state jurisdictions. Stakeholders must monitor evolving state-level procurement preferences that increasingly prioritize Environmental Product Declarations and Health Product Declarations as bid qualification criteria.
Market Dynamics
Healthcare construction specifications are consolidating procurement power among national contractors, while California's Title 24 efficiency mandates and EU REACH chemical restrictions simultaneously reshape material selection criteria across two major demand centers.
Growth Catalysts
- Title 24 Building Standards:California's energy efficiency code mandates high-performance flooring substrates in commercial buildings, creating specification pull for dimensionally stable fiberglass-backed products in healthcare and education verticals.
- Healthcare Facility Construction:Hospital and clinic expansion across North America and Europe prioritizes seamless sheet flooring with microbial control properties, locking in fiberglass-backed vinyl specifications through architect relationships.
- LEED-Equivalent Certification:Germany's commercial renovation sector embeds environmental performance requirements into tender documents, filtering procurement toward premium fiberglass flooring with verified Environmental Product Declarations.
Market Restraints
- Petrochemical Input Volatility:Vinyl polymer resins and plasticizers constitute 60-70 percent of finished product weight, exposing margins to ethylene and propylene price swings from Gulf Coast crackers.
- Fiberglass Mat Supply Concentration:Woven glass fiber mat production clusters among three North American suppliers, creating bottleneck risk for flooring manufacturers without captive supply arrangements.
- Formaldehyde Emission Thresholds:California Air Resources Board maintains the nation's most stringent limits, forcing reformulation investments that compress margins on economy-tier product lines.
Strategic Opportunities
- Click-Lock Plank Systems:Floating installation methods are capturing share from glue-down sheet goods in retail and hospitality renovation cycles, opening margin expansion through reduced labor content.
- Health Product Declaration Adoption:US institutional buyers increasingly require HPD documentation as bid qualification criteria, favoring suppliers with pre-submitted transparency data.
- Southeastern US Manufacturing Proximity:Regional production scale shortens lead times for Atlanta and Charlotte commercial developers, defending share against imports through logistics responsiveness.
Industry Challenges
- Installer Certification Gaps:Seam welding and flash coving techniques for healthcare sheet installations require skilled labor pools that are thinning as veteran installers exit the workforce.
- Multi-Jurisdiction Compliance Burden:Products crossing California, New York, and EU markets must satisfy divergent VOC and chemical content rules, fragmenting SKU portfolios and inventory management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiberglass Flooring Market |
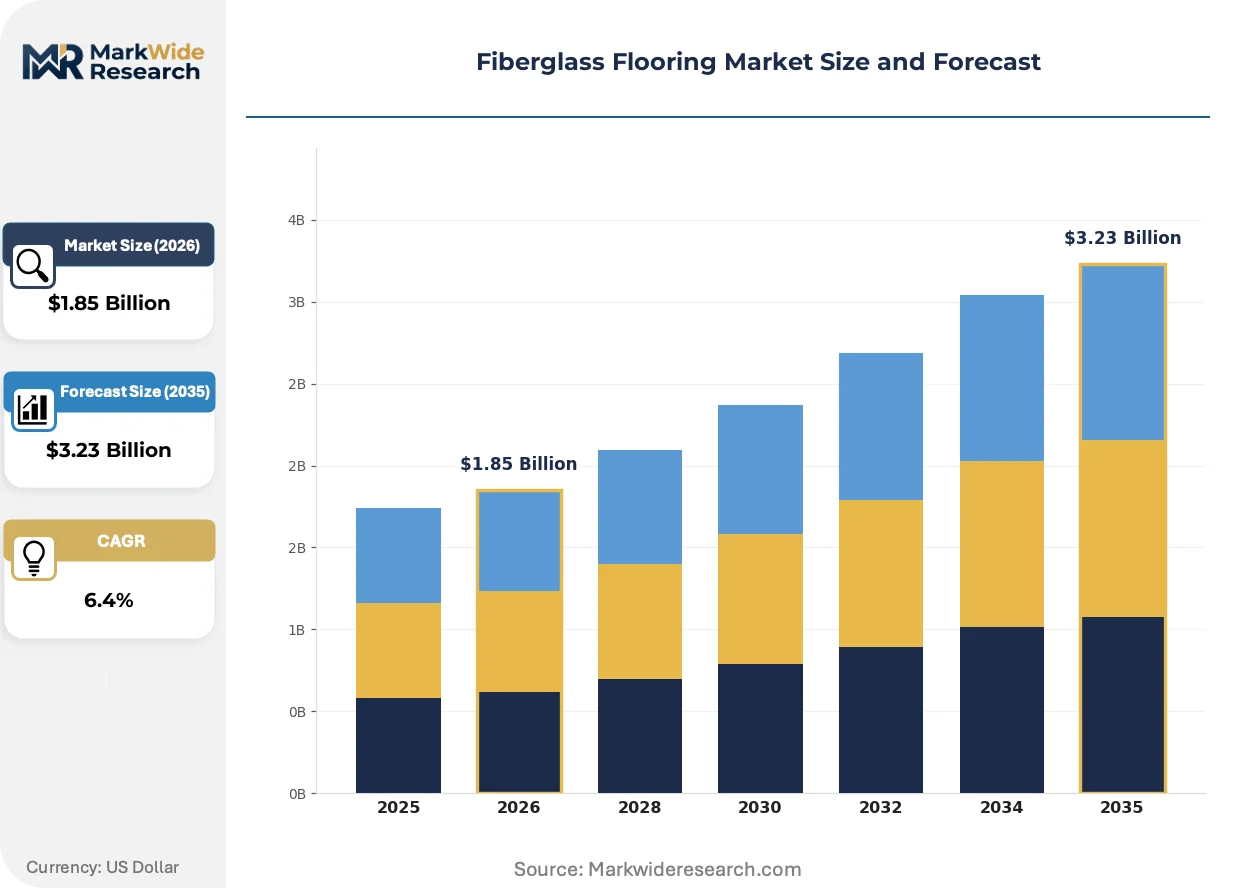
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tiles, Sheets, Planks, Panels End User: Residential, Commercial, Industrial, Institutional Application: Flooring, Wall Covering, Waterproofing, Insulation Distribution Channel: Online Retail, Offline Retail, Direct Sales, Wholesalers |
| Companies Covered | Milliken, Armstrong World Industries, Shaw Floors, NOX Corporation, IVC Group, Mannington Mills, Gerflor, Owens Corning, Tarkett, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiberglass Flooring Market Emerging Trajectories
Material science advances and specification transparency requirements are compressing traditional product lifecycles while elevating performance verification standards across institutional buyer segments.
Glass fiber mat reinforcement is absorbing installation stress in luxury vinyl plank constructions, enabling thinner overall profiles without sacrificing dimensional stability. Retail and hospitality renovators are specifying these products for faster turnaround cycles. The technology is absorbing market share from traditional felt-backed alternatives by reducing jobsite labor hours.
REACH chemical restrictions are forcing substitution of legacy plasticizers and stabilizers in formulations sold across EU member states. Flooring manufacturers are qualifying bio-based and non-phthalate alternatives through accelerated aging protocols. Healthcare and education segments in Germany and France are absorbing reformulation costs through specification lock-in.
Architect specification influence is consolidating around firms with in-house sustainability consulting capabilities, filtering product selection through EPD and HPD documentation quality. National commercial contractors are building preferred supplier lists around pre-verified transparency data. This concentration is most visible in US healthcare and K-12 construction, where master specifications now embed environmental disclosure requirements as default language.
Fiberglass Flooring Market Segmentation
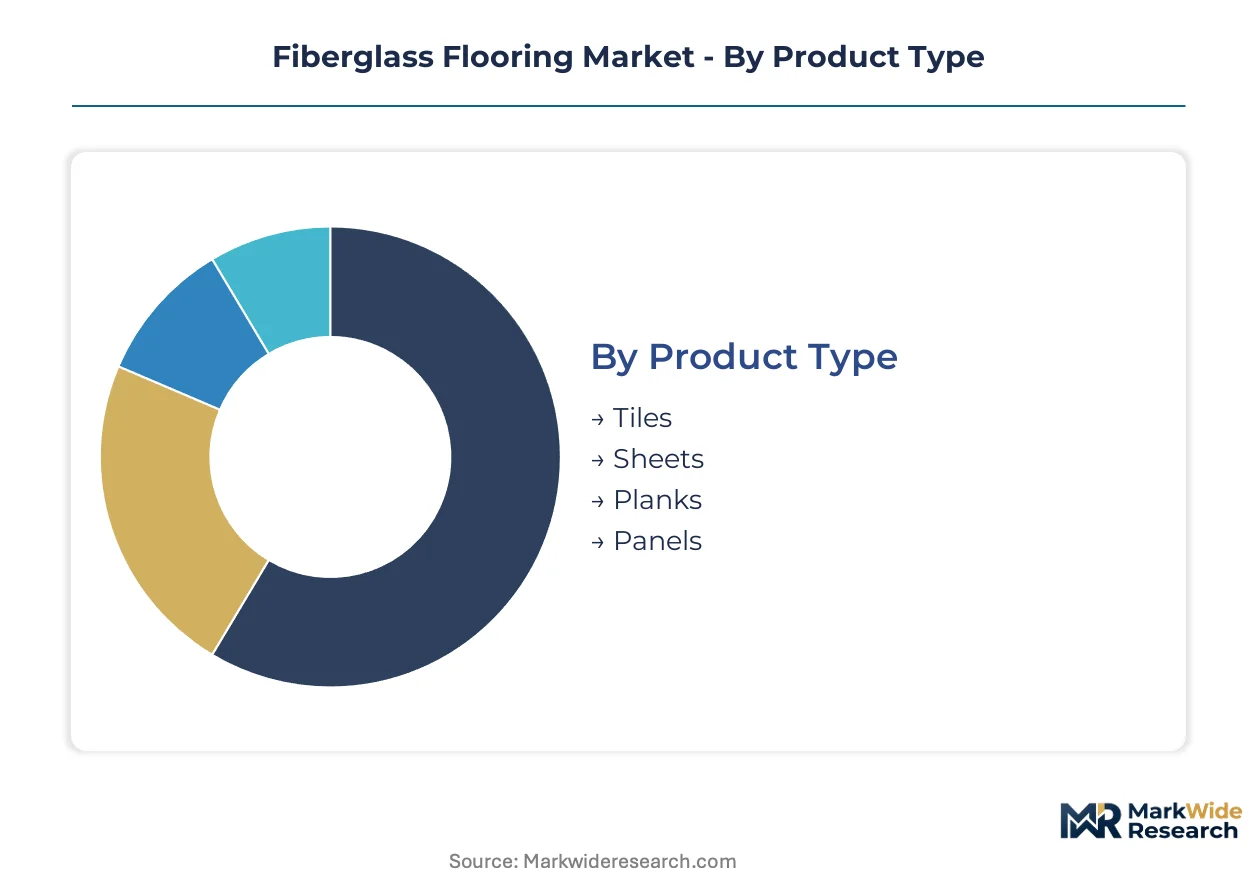
Specification requirements diverge sharply across fiberglass flooring segments, with institutional buyers demanding certified dimensional stability while residential renovators prioritize installation speed. Material thickness, fiberglass content percentage, and backing chemistry separate premium specifications from economy tiers.
Product Type:
Glass fiber mat integration determines structural performance across installation formats, with seamless applications commanding stricter dimensional tolerances than floating systems.
- Sheets:Continuous fiberglass-reinforced vinyl rolls, typically 2-3.5 mm thick with woven mat content near 20 percent by weight, deliver seamless surfaces for healthcare cleanrooms and surgical suites where microbial control is mandatory. Hospital construction specifications in California and Germany lock in sheet goods through architect master specifications.
- Planks:Rigid fiberglass-core luxury vinyl planks with click-lock edge profiles enable floating installation without adhesive, cutting labor hours for retail and hospitality renovation cycles. The format is climbing fastest as commercial renovators prioritize speed-to-occupancy.
- Tiles:Modular 12x12 or 18x18 inch fiberglass-backed units permit patterned layouts and selective replacement in high-wear zones.
- Panels:Large-format rigid substrates serve specialized industrial and raised-access flooring applications requiring elevated load distribution.
Mature deployment sits with sheets in healthcare and education verticals. Newer deployment is concentrated in planks across retail and hospitality renovation.
End User:
Procurement sophistication and specification authority create four distinct margin tiers, with institutional buyers embedding multi-year performance guarantees into contract language.
- Commercial:Office towers, retail chains, and hospitality properties specify fiberglass-backed flooring for 10-15 year wear warranties, with LEED documentation increasingly required for Class A developments. Procurement concentrates among national contractors with pre-approved product lists.
- Institutional:Hospitals, schools, and government facilities demand the highest dimensional stability ratings and formaldehyde emission certifications, accepting premium pricing for specification lock-in through architect relationships.
- Residential:Single-family and multifamily builders select thinner-profile products with shorter warranty periods, prioritizing first-cost over lifecycle performance.
- Industrial:Manufacturing and warehouse applications require chemical resistance and static control properties beyond standard commercial grades.
Volume concentrates in commercial buildouts. Steepest expansion trajectory belongs to institutional healthcare construction.
Application:
Functional performance requirements extend fiberglass mat reinforcement beyond traditional floor loading into moisture management and thermal barriers.
- Flooring:Primary application combining dimensional stability under rolling loads with moisture resistance for slab-on-grade installations.
- Waterproofing:Fiberglass mat serves as reinforcement layer in below-grade membrane systems for commercial foundations.
- Wall Covering:Thin-profile fiberglass-backed vinyl provides impact resistance for healthcare corridors and cleanroom vertical surfaces.
- Insulation:Specialized high-density fiberglass composites contribute thermal and acoustic performance in building envelope applications.
Revenue concentration remains with flooring substrates. Waterproofing and wall covering applications are gaining specification share in healthcare and laboratory construction.
Distribution Channel:
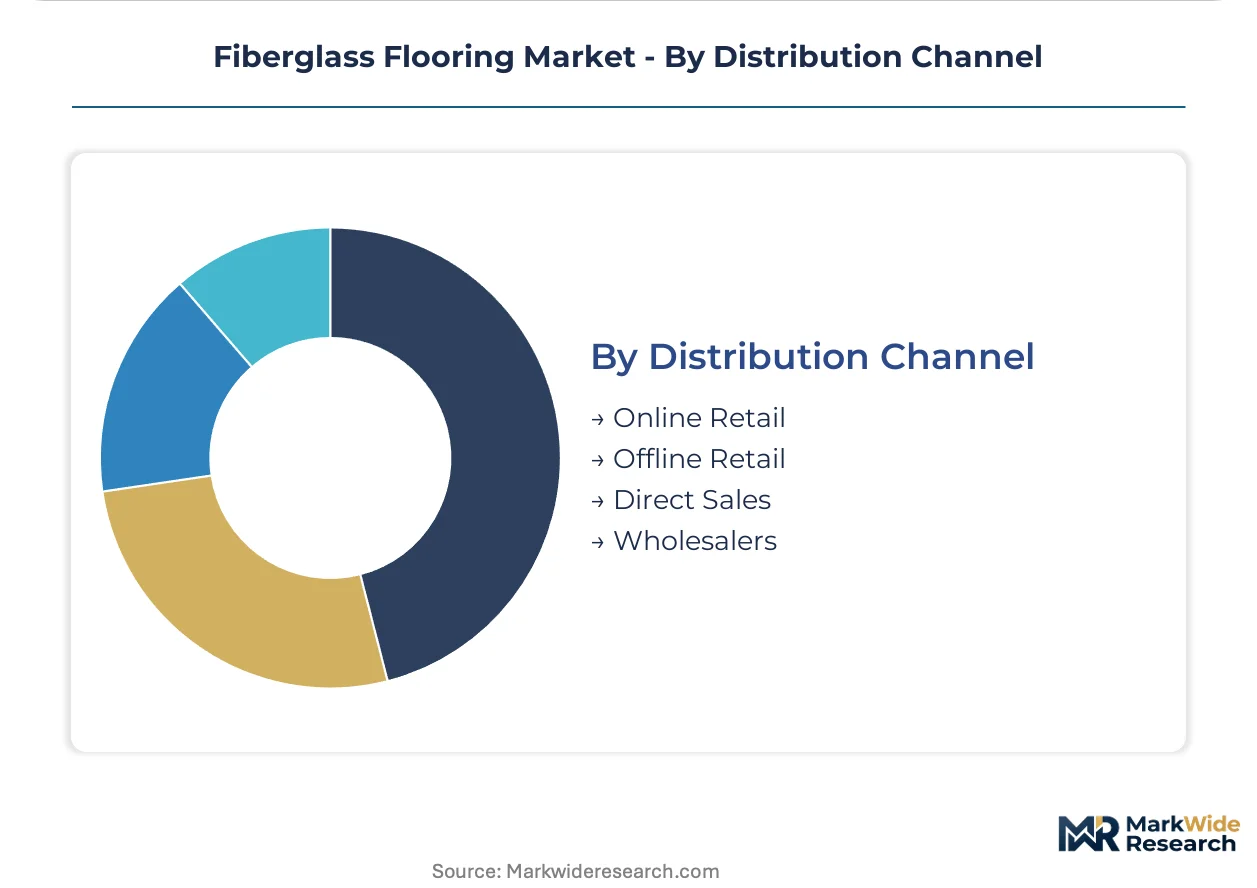
Channel selection tracks project scale and specification complexity, with large institutional contracts bypassing traditional wholesale tiers.
- Direct Sales:National commercial contractors and healthcare systems negotiate mill-direct contracts for volume pricing and specification compliance, supported by manufacturer technical field teams.
- Wholesalers:Regional flooring distributors maintain inventory positions for contractor spot purchases and renovation project fulfillment.
- Offline Retail:Specialty flooring showrooms serve residential and light commercial buyers with physical sample evaluation.
- Online Retail:E-commerce platforms capture residential renovation demand and small commercial projects with expedited shipping.
High-volume procurement flows through direct sales with embedded technical support. Online retail is expanding fastest among residential renovation segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Glass fiber mat production clusters along the Gulf Coast of the United States, anchoring raw material flows for flooring manufacturers serving healthcare and commercial construction corridors.
United States
Hospital construction in California and Texas absorbs dimensionally stable sheet goods for cleanroom specifications. The EPA's Indoor airPLUS program enforces VOC emission thresholds that filter product eligibility for federal building projects. The Atlanta-Charlotte corridor concentrates commercial renovation activity where regional manufacturing proximity shortens contractor lead times.
Germany
Commercial renovation in Bavaria and North Rhine-Westphalia embeds LEED-equivalent certification requirements into tender documents. The EU's REACH chemical restrictions force reformulation of legacy plasticizers for products sold across member states. The Stuttgart industrial cluster hosts flooring manufacturers qualifying bio-based stabilizers through accelerated aging protocols.
China
Rapid hospital infrastructure expansion in the Yangtze River Delta and Pearl River Delta generates specification demand for microbial-control flooring substrates. The Ministry of Ecology and Environment enforces dual carbon goals that elevate energy efficiency requirements for commercial building materials. The Shanghai metropolitan area concentrates luxury vinyl plank production for retail and hospitality export markets.
France
Healthcare facility modernization in Île-de-France and Auvergne-Rhône-Alpes prioritizes seamless installation formats for surgical suite applications. ANSM maintains chemical content disclosure requirements for products specified in public hospital procurement. The Lyon cluster anchors technical flooring distribution networks serving continental European renovation cycles.
United Kingdom
Education sector refurbishment across London and the Southeast specifies fiberglass-backed vinyl for 15-year wear warranty compliance. The Health and Safety Executive influences installer exposure protocols during fiberglass handling operations. The Midlands manufacturing corridor supplies dimensionally stable substrates for national healthcare construction frameworks.
Fiberglass Flooring Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue click-lock installation technology and bio-based formulation spaces. The vendor base separates into three functional tiers: multinational flooring conglomerates with captive fiberglass supply, regional specialists with specification relationships, and raw material suppliers extending downstream into finished goods. Three strategic archetypes dominate: backward-integrated manufacturers controlling mat production, technology licensors of proprietary backing systems, and regional scale players optimizing logistics responsiveness. Consolidation pressure operates through M&A activity targeting specification lock-in capabilities, while capacity expansion concentrates in southeastern United States and coastal Chinese manufacturing zones.
Among North American flooring specialists, Armstrong World Industries, Shaw Floors, and Mannington Mills occupy positions within the integrated manufacturing tier. Armstrong exemplifies backward integration into raw fiberglass mat production. Shaw represents proprietary backing technology development. Mannington anchors regional manufacturing scale advantages. These three entities sit within the competitive structure as reference points for procurement consolidation among national commercial contractors and healthcare systems.
| Leading Market Players |
|---|
| Milliken |
| Armstrong World Industries |
| Shaw Floors |
| NOX Corporation |
| IVC Group |
| Mannington Mills |
| Gerflor |
| Owens Corning |
| Tarkett |
| Others |
Supply Flow & Price Mechanics
Ethylene and propylene price indices from Gulf Coast crackers cascade through fiberglass flooring supply chains into three-tier pricing structures across premium, standard, and economy levels. California's Title 24 compliance costs and EU REACH reformulation investments compress margins at the economy tier while specification-locked institutional buyers absorb premium pricing.
Pricing Analysis
Warranty bundling separates premium specifications from unbundled economy tiers, with 10-15 year wear guarantees and installation labor coverage commanding price premiums. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade—California Air Resources Board compliance and Health Product Declaration documentation filter procurement toward verified suppliers. Cost compression in economy-tier sheet goods is intensifying because petrochemical input volatility exposes manufacturers without captive resin supply. Residential renovators exhibit highest price sensitivity, while institutional healthcare buyers prioritize lifecycle performance over first-cost.
Supply Chain Analysis
Certification gating through EPA Indoor airPLUS and EU REACH documentation requirements fragments supplier eligibility across North American and European markets. Raw material flows draw from United States fiberglass mat production clusters, German chemical stabilizer suppliers, and Chinese vinyl resin processors. Woven glass fiber mat concentration among three North American suppliers creates single-source vulnerability for flooring manufacturers lacking backward integration. Distribution runs through mill-direct contracts for national healthcare contractors and regional wholesale tiers for spot commercial purchases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
California's Title 24 building efficiency standards erect a cost-of-compliance barrier that rewards pre-certified incumbents while filtering speculative entrants from institutional specification channels.
For Market Incumbents: Anchor specification lock-in through architect master specification maintenance and captive fiberglass mat production investments. Defend against click-lock plank disruption by acquiring floating installation technology licensors. Prioritize southeastern United States capacity expansion to compress lead times for Atlanta-Charlotte commercial developers.
For New Entrants and Emerging Players: The premium-economy price-point gap in residential renovation channels offers white-space entry below institutional certification thresholds. Target multifamily builders in Sun Belt markets with thinner-profile planks emphasizing speed-to-occupancy. Pursue private-label partnerships with regional distributors lacking in-house fiberglass backing capabilities.
For Investors and Strategic Acquirers: Distressed-cycle entries favor regional scale players with specification relationships in Germany's commercial renovation sector. Long-term viability rests on REACH-compliant formulation assets and pre-submitted Environmental Product Declaration libraries. Watch Health Product Declaration adoption rates in US K-12 construction as inflection signal for transparency-premium expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fiberglass Mat Production | Captive supply from Owens Corning or Johns Manville insulates margin against raw material bottlenecks. |
| Click-Lock Installation Technology Licensing | Proprietary edge-profile patents from Unilin or Välinge accelerate plank category share capture. |
| Health Product Declaration Pre-Submission | Pre-verified transparency data qualifies suppliers for US institutional bid pools. |
| Southeastern US Manufacturing Expansion | Regional production scale defends share against imports through logistics responsiveness to Charlotte developers. |
| Bio-Based Plasticizer Qualification | REACH-compliant stabilizer substitution opens EU healthcare specification channels. |
Methodological Framework
Independent corroboration across plant managers at fiberglass mat production facilities, procurement leads at national commercial flooring contractors, and regulatory affairs specialists at vinyl resin suppliers underwrites the qualitative findings. Primary interviews with hospital purchasing committee members, architect specification consultants, and distribution channel partners combined with secondary validation from EPA Indoor airPLUS certification databases, California Air Resources Board emission test reports, and EU REACH registration dossiers. Bottom-up volume modeling triangulates against top-down construction spending forecasts.
Rate-of-change decomposition across product type, end-user sophistication tier, and application format drives the analytical framework over the projection horizon. Modeled segmentation spans sheets-planks-tiles-panels, commercial-institutional-residential-industrial buyer categories, and flooring-waterproofing-wall covering-insulation applications. CAGRs derive from elasticity-adjusted demand curves incorporating hospital construction permit flows and commercial renovation cycle timing. Industry-specific inputs include architect specification influence indices and installer certification gap metrics.
Inputs from EPA emission certification databases and EU REACH substance registrations were available through the study window; gaps in real-time petrochemical price transmission data introduce uncertainty bands around margin compression scenarios. Forecasts reflect documented assumptions on regulatory enforcement consistency and healthcare construction funding continuity. A model refresh is warranted upon material change in California Title 24 amendment timing or REACH authorization list expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
India Wood Flooring Market
Flooring, Carpets, and Rugs
Egypt Floor Covering Market
Flooring, Carpets, and Rugs
Asia-Pacific Floor Covering Market
Flooring, Carpets, and Rugs
Saudi Arabia Carpet and Rugs Market
Flooring, Carpets, and Rugs
Sheet Flooring Market
Flooring, Carpets, and Rugs
GCC Floor Covering Market
Flooring, Carpets, and Rugs
United States Floor Covering Market
Flooring, Carpets, and Rugs
Germany Flooring Market
Flooring, Carpets, and Rugs
India Laminate Flooring Market
Flooring, Carpets, and Rugs
Europe Carpet and Rugs Market
Flooring, Carpets, and Rugs
Rigid Core Flooring Market
Flooring, Carpets, and Rugs
China Floor Covering Market
Flooring, Carpets, and Rugs
Area Rugs Market
Flooring, Carpets, and Rugs
Hardwood Flooring Market
Flooring, Carpets, and Rugs
Luxury Vinyl Tile (LVT) Flooring Market
Flooring, Carpets, and Rugs
Global Non-Resilient Flooring Market