
 China Wood Flooring Market | 2026-2036
China Wood Flooring Market Size, Share, and Industry Trends Forecast 2026-2036
China Wood Flooring Market Analysis
Maintenance subscription packages for refinishing and moisture protection is rebalancing how flooring value gets captured in China. Power Dekor leverages its national service network to lock in repeat revenue from commercial clients. Nature Wood anchors its position through R&D intensity in low-emission adhesive systems. Lianfeng dominates the engineered wood segment with manufacturing scale advantages across Jiangsu province.
China wood flooring comprises timber-based surface materials manufactured through sawing, drying, pressing, and finishing processes, with engineered variants bonding multiple wood layers for dimensional stability under humidity fluctuations. Solid wood commands premium positioning in high-end residential projects, while engineered wood captures the fastest expansion through cost-performance optimization for multi-story buildings. Click lock installation systems are displacing traditional glue-down methods in renovation applications across tier-one cities.
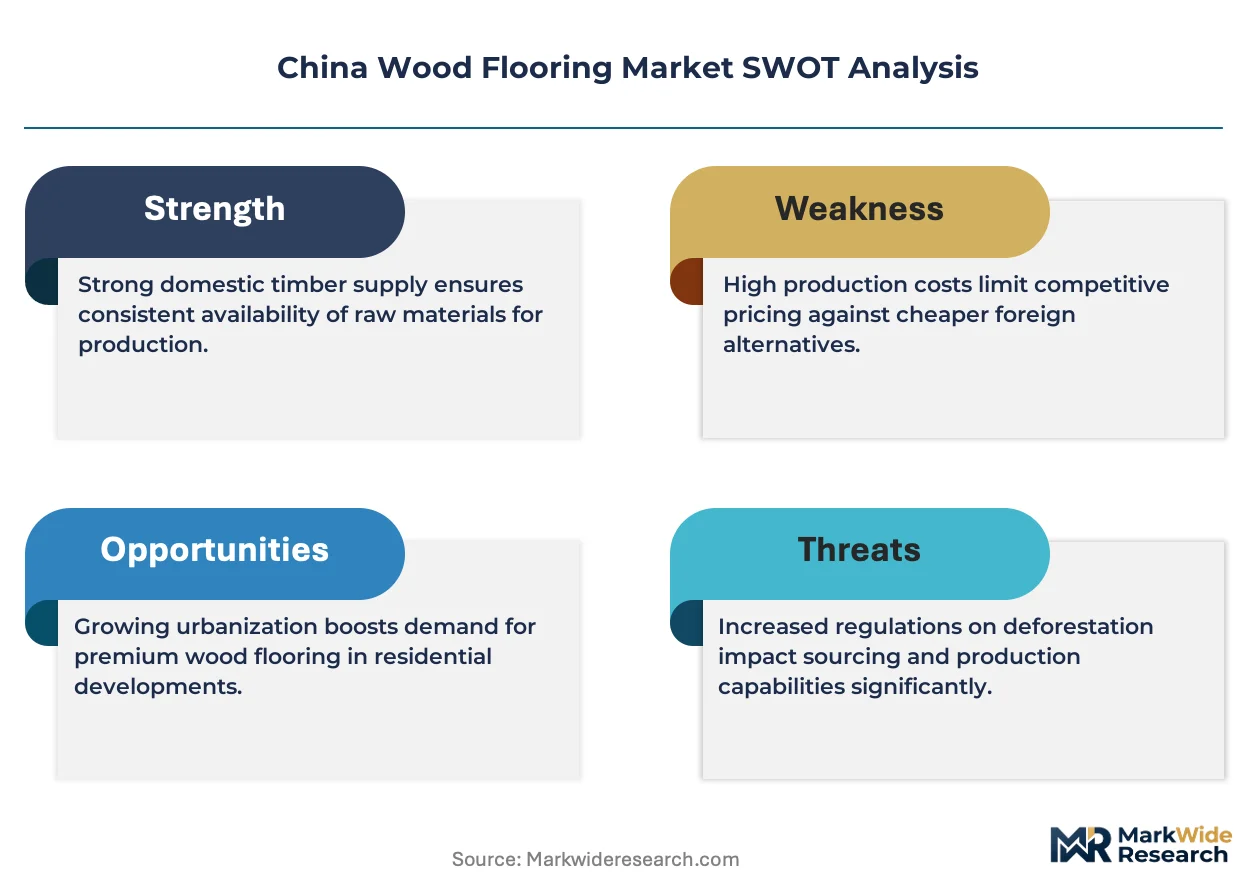
GB standards issued by SAMR and environmental compliance rules enforced by MEE are elevating product certification requirements for domestic manufacturers. The country's national forestry regulator restricts raw timber imports, pushing supply chains toward certified plantation sources. Stakeholders must monitor how evolving carbon accounting rules reshape material sourcing economics and factory location decisions.
Market Dynamics
GB standards tightening formaldehyde emission limits are forcing manufacturers to reconfigure adhesive chemistries and raw material sourcing across the Yangtze River Delta manufacturing cluster.
Growth Catalysts
- Residential renovation in tier-one cities:Property upgrade cycles in Shanghai and Beijing are accelerating engineered wood uptake for multi-story apartment retrofits.
- MEE environmental enforcement:Stricter factory emission audits are pushing consolidation toward certified producers with compliant supply chains.
- Click-lock installation systems:Dry-fit methods are reducing skilled labor dependency and cutting project timelines for commercial fit-outs.
Market Restraints
- Raw timber import restrictions:National forestry regulator quotas on tropical hardwoods are constraining solid wood production capacity.
- Adhesive cost volatility:Isocyanate and phenol resin prices fluctuate with petrochemical feedstock markets, squeezing margin predictability.
- Substitution by SPC flooring:Stone-polymer composite alternatives capture price-sensitive segments with superior moisture resistance.
Strategic Opportunities
- Carbon accounting integration:Dual carbon goals are creating certification premiums for plantation-sourced materials with traceable chain-of-custody documentation.
- Maintenance subscription models:Refinishing and moisture protection services lock in recurring revenue from commercial property managers.
- Western China expansion:Chengdu and Chongqing construction pipelines remain underpenetrated relative to coastal saturation.
Industry Challenges
- Low-emission adhesive R&D timelines:Developing GB-compliant soy and lignin-based binders requires extended validation cycles before commercial deployment.
- Skilled installation labor scarcity:Traditional glue-down craftsmanship is aging out faster than click-lock training programs can replace capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Wood Flooring Market |
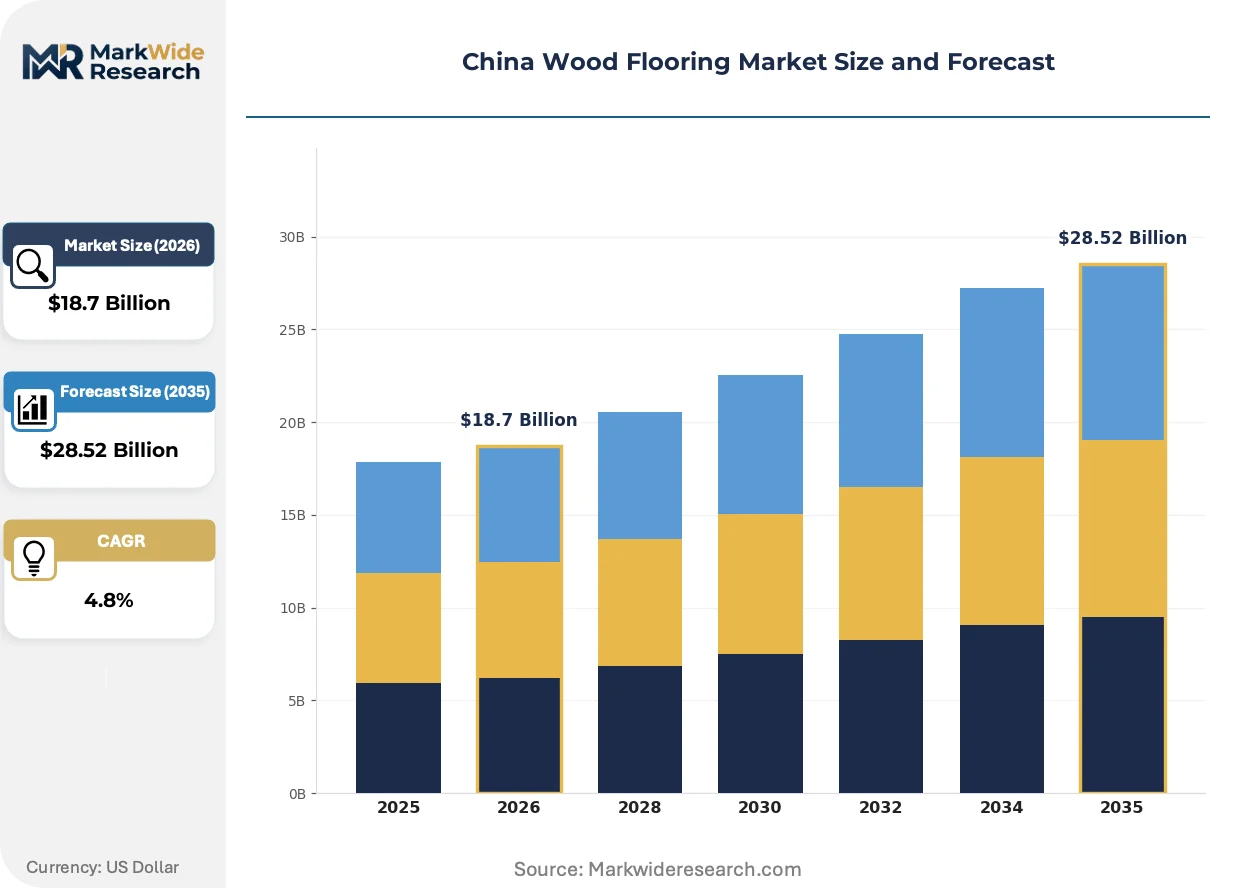
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid Wood, Engineered Wood, Laminate, Bamboo End User: Residential, Commercial, Institutional, Hospitality Installation Type: Glue-Down, Nail-Down, Floating, Click Lock Finish Type: Unfinished, Pre-finished, Matte, Glossy |
| Companies Covered | Lianfeng, Elegant Living, Kentier, Nature Wood, Gaopai Wood, Power Dekor, Gloria Floor, Yangzi Flooring, Anxin Flooring, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Wood Flooring Market Emerging Trajectories
Digital manufacturing controls and material traceability systems are redefining quality assurance and supply chain transparency across Chinese wood flooring production.
Cross-laminated timber core technology is consolidating engineered wood structural performance. High-rise residential developers in Shenzhen and Guangzhou specify these products for dimensional stability under humidity cycling. The technology is consolidating mid-market positioning away from traditional plywood-core alternatives.
SAMR's revised GB standards for indoor air quality are elevating third-party certification requirements. Manufacturers must now submit batch-level emission testing to accredited laboratories. Solid wood flooring lines face the steepest compliance cost increases as natural material variability complicates consistent certification.
Property management companies now bundle flooring lifecycle services into lease agreements. Facility operators in Beijing commercial towers prefer vendors offering refinishing and damage replacement under fixed annual contracts. This service integration is most advanced in premium office segments where tenant turnover demands rapid aesthetic refresh cycles.
China Wood Flooring Market Segmentation
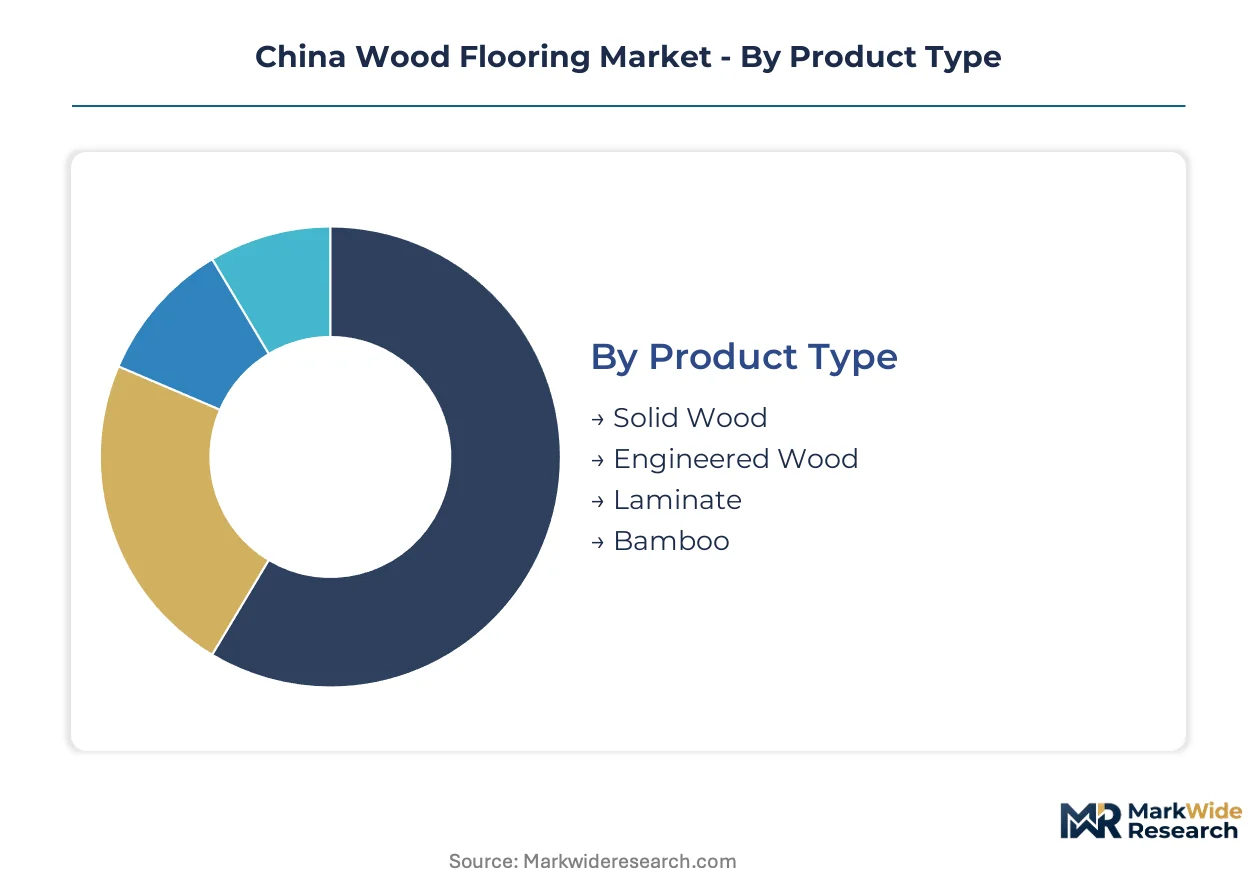
Product specifications and installation methods determine margin profiles and customer switching costs across China's wood flooring value chain. Segment boundaries are blurring as engineered wood absorbs laminate price points while click-lock systems reshape labor economics for renovation contractors.
Product Type:
Material composition and layer bonding technology separate premium positioning from mass-market penetration in Chinese flooring procurement.
- Engineered Wood:Multi-layer construction bonds a hardwood veneer to plywood or high-density fiberboard cores, delivering dimensional stability against Jiangsu province's humidity fluctuations. Cross-laminated timber variants specified by Shenzhen high-rise developers are displacing solid wood in luxury residential towers above the 20th floor.
- Solid Wood:Single-species planks milled from tropical hardwoods face supply constraints from national forestry regulator import quotas. Beijing and Shanghai high-end villa projects still specify teak and oak for acoustic warmth, though GB formaldehyde compliance costs squeeze margins on natural material variability.
- Laminate:Melamine-impregnated decorative paper fused to particleboard cores dominates price-sensitive renovation segments in tier-two cities.
- Bamboo:Strand-woven and horizontal-grain variants from Anhui province plantations compete on carbon certification credentials under dual carbon goals.
Engineered wood leads on scale; bamboo flooring leads on momentum from plantation traceability premiums.
End User:
Project scale and specification authority create divergent procurement patterns across China's construction pipeline.
- Residential:Individual homeowners in Shanghai and Beijing renovation cycles prioritize click-lock engineered wood for rapid installation without building management approval delays. Multi-story apartment constraints on structural load limits solid wood uptake.
- Commercial:Office fit-out contractors in Beijing commercial towers bundle refinishing subscriptions into five-year lease terms. Power Dekor's national service network captures recurring revenue from facility managers facing tenant turnover refresh cycles.
- Institutional:School and hospital procurement through government tender systems emphasizes GB standard certification batch documentation.
- Hospitality:Hotel chains in Chengdu and Chongqing specify engineered wood for guest room durability under high-turnover cleaning protocols.
Residential commands volume concentration; commercial offers the steepest expansion trajectory from service bundling.
Installation Type:
Labor skill requirements and project timeline flexibility determine contractor preference and total installed cost structures.
- Click Lock:Tongue-and-groove profiles with mechanical locking edges enable dry-fit assembly without adhesives, cutting skilled labor dependency. Tier-one city renovation contractors report 40% timeline compression versus glue-down methods for commercial fit-outs.
- Glue-Down:Full-surface adhesive application demands experienced craftsmen aging out faster than training programs replace capacity. Still specified for solid wood in high-end residential where acoustic performance justifies premium labor costs.
- Nail-Down:Pneumatic fastening to plywood subfloors dominates new construction wood-frame housing in suburban Beijing developments.
- Floating:Underlayment-cushioned systems without perimeter fastening suit rental property renovations requiring future removal.
Click lock leads on adoption velocity; glue-down retains margin premiums where craftsmanship scarcity persists.
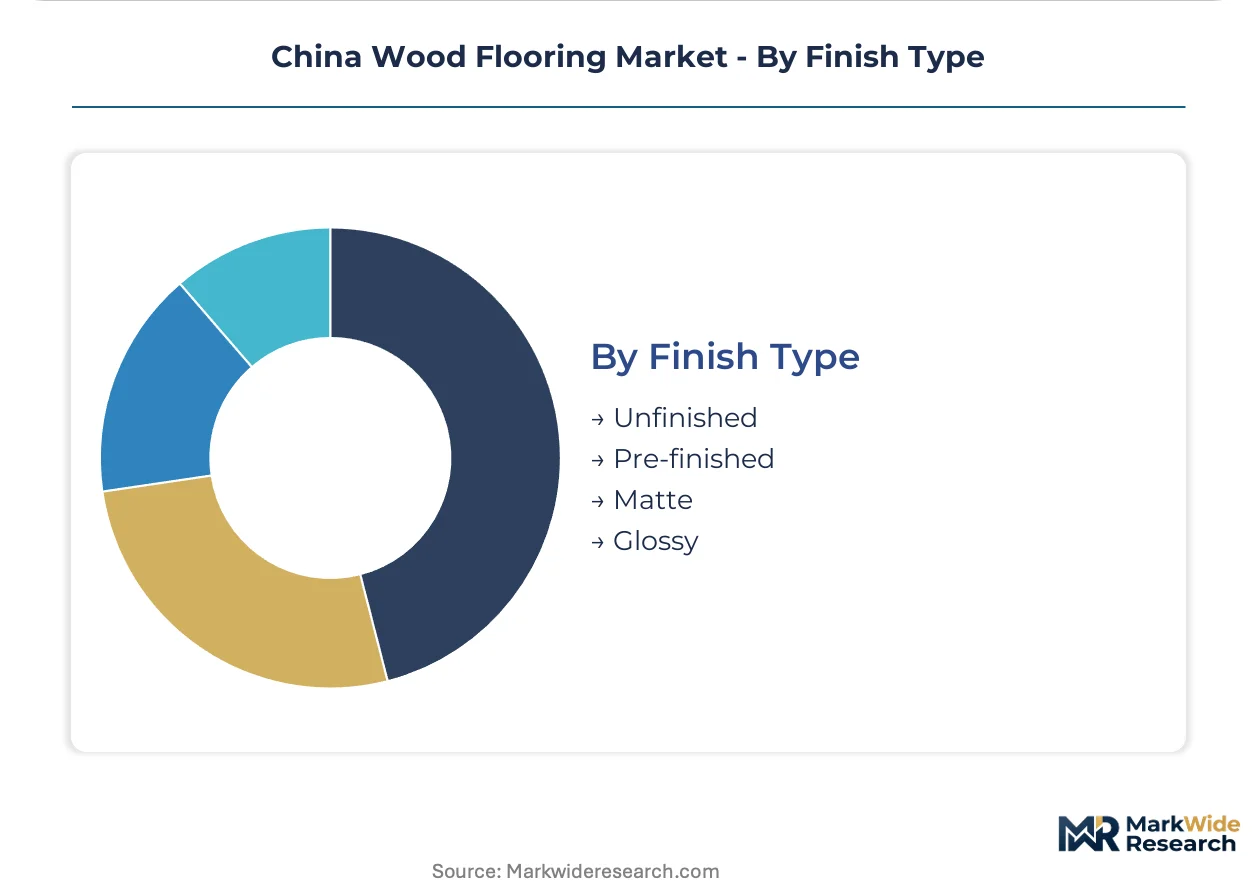
Finish Type:
Surface treatment timing and aesthetic specification divide factory-controlled quality from site-applied customization.
- Pre-finished:UV-cured aluminum oxide coatings applied under factory conditions deliver consistent scratch resistance and GB emission certification. Accounts for majority of engineered wood volume through Yangtze River Delta manufacturing clusters.
- Unfinished:Raw planks sanded and site-finished with oil or water-based polyurethane allow color matching to existing millwork. Retains niche in historic Beijing courtyard renovations where dimensional irregularities demand custom treatment.
- Matte:Low-sheen lacquers specified by Shanghai interior designers for contemporary minimalist aesthetics.
- Glossy:High-build varnish finishes dominate hospitality segments seeking reflective surface drama.
Pre-finished dominates manufacturing scale; matte finishes gain share fastest from design trend alignment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's wood flooring demand concentrates in coastal manufacturing belts, while interior provinces lag in per-capita uptake despite faster construction velocity. Provincial regulatory variations and sub-regional industrial clustering create divergent competitive environments across the country's economic geography.
Yangtze River Delta
Jiangsu province manufacturing clusters supply engineered wood products to Shanghai and Hangzhou renovation markets. SAMR's GB standards enforcement elevates certification costs for formaldehyde compliance across Changzhou and Suzhou factory zones. Lianfeng leverages scale advantages in Jiangsu to dominate multi-layer board production for high-rise residential towers.
Pearl River Delta
Shenzhen and Guangzhou developers specify cross-laminated timber cores for luxury apartments above the 20th floor. MEE environmental audits accelerate consolidation toward certified producers in Dongguan and Foshan. Factory automation investments in Guangdong province compress lead times for commercial fit-out contractors serving Hong Kong-linked property managers.
Beijing-Tianjin-Hebei
Capital region property upgrade cycles drive engineered wood uptake in multi-story apartment retrofits. Dual carbon goals elevate plantation-sourced material premiums for government and institutional procurement through Beijing tender systems. Power Dekor's national service network captures recurring maintenance revenue from commercial tower facility managers.
Sichuan-Chongqing
Chengdu and Chongqing construction pipelines remain underpenetrated relative to coastal saturation, offering expansion headroom for tier-one brands. Western China development programs channel infrastructure investment toward residential and hospitality segments. Local distributors in Sichuan province compete on price for laminate volume in tier-two city renovation markets.
Shandong Peninsula
Qingdao and Yantai port access supports imported hardwood processing for solid wood flooring lines facing national forestry regulator quotas. Shandong manufacturers balance export orientation with domestic GB compliance investments. Regional adhesive suppliers in Weifang encounter margin pressure from isocyanate price volatility tied to petrochemical feedstock markets.
China Wood Flooring Market Vendor Landscape
Top-tier vendors anchor national distribution networks, while regional specialists defend niche positions through manufacturing scale or service bundling. The vendor base stratifies across three tiers: integrated manufacturers with captive supply chains, mid-scale engineered wood specialists, and price-focused laminate producers. Strategic archetypes include certification-driven premium players, maintenance-service bundlers, and plantation-integrated cost leaders. Competitive moves concentrate on backward integration into adhesive production and geographic expansion into western provinces.
Within the premium-tier vector, Nature Wood exemplifies low-emission R&D positioning through adhesive system innovation. Power Dekor occupies the service-bundling archetype with maintenance subscription models for commercial clients. Lianfeng anchors the scale-driven segment with Jiangsu province manufacturing concentration. These three entities represent divergent strategic responses to GB standards tightening and dual carbon compliance requirements.
| Leading Market Players |
|---|
| Lianfeng |
| Elegant Living |
| Kentier |
| Nature Wood |
| Gaopai Wood |
| Power Dekor |
| Gloria Floor |
| Yangzi Flooring |
| Anxin Flooring |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between GB-compliant engineered wood and uncertified laminate alternatives manifests in pricing power concentration among Yangtze River Delta manufacturers while supply chains reconfigure around formaldehyde testing batch documentation. Premium tiers capture margin from SAMR compliance investments as commodity segments face cost compression from SPC substitution.
Pricing Analysis
Capacity additions in Jiangsu province are reshaping price floors for multi-layer engineered boards as Lianfeng's scale advantages compress mid-market positioning. Three-tier pricing structure across premium, standard, and economy levels separates plantation-certified products from import-dependent solid wood and particleboard-core laminate. Cost compression in economy tiers is intensifying because SPC flooring captures moisture-sensitive applications with superior price-performance. Institutional buyers through Beijing tender systems exhibit lowest price sensitivity while tier-two city renovation contractors drive hardest bargain on laminate volume.
Supply Chain Analysis
Freight cost differentials between coastal manufacturing clusters and western China expansion zones are redrawing distribution economics for national service networks. Raw material sourcing draws from certified Anhui province plantations, tropical hardwood imports through Qingdao port, and petrochemical-derived adhesive feedstocks from Shandong Peninsula refineries. Single-source vulnerability concentrates in isocyanate resin supply tethered to volatile feedstock markets. Distribution runs through factory-direct channels to commercial property managers and wholesale networks serving renovation contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in maintenance subscription bundling and low-emission adhesive premiums as cost-down pressure shifts toward plantation-sourced material substitution. GB compliance investments now separate viable national players from regional price competitors.
For Market Incumbents: Acquire plantation certification assets and captive adhesive production capacity to lock in dual carbon goal compliance before MEE enforcement tightens. Consolidate click-lock installation training networks to offset aging glue-down craftsmanship scarcity. Defensive positioning requires backward integration into Anhui province bamboo sourcing and Jiangsu multi-layer board manufacturing scale. For New Entrants and Emerging Players: Digital material traceability platforms offer white-space entry against incumbent quality assurance systems. Target Chengdu and Chongqing commercial fit-out segments where national service network coverage remains thin. Go-to-market leverage centers on carbon accounting documentation premiums for government procurement channels. For Investors and Strategic Acquirers: Consolidation pressure builds where SAMR batch testing investments exceed RMB thresholds for mid-scale Jiangsu manufacturers. Five-to-ten year viability favors vertically integrated specialists with captive plantation supply and certified distribution networks. Monitor MEE factory audit failure rates as inflection indicator for forced exit velocity among non-compliant producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adhesive Production | Captive isocyanate and soy-based binder manufacturing insulates margin from petrochemical feedstock volatility. |
| Plantation Certification Program | Chain-of-custody documentation unlocks dual carbon goal premiums in Beijing institutional tender systems. |
| Maintenance Subscription Launch | Recurring refinishing revenue from commercial tower facility managers extends customer lifetime value. |
| Western China Distribution Expansion | Chengdu and Chongqing channel development captures underpenetrated construction pipeline relative to coastal saturation. |
| Cross-Laminated Timber Core Investment | Shenzhen high-rise developer specifications above 20th floor displace plywood-core alternatives in luxury residential. |
Methodological Framework
Bottom-up residential and commercial procurement modeling reconciled against top-down Yangtze River Delta manufacturing capacity tracking forms the analytical core. Primary interviews with flooring procurement managers at Beijing and Shanghai property developers, plant managers at Jiangsu engineered wood facilities, commercial facility operators, and renovation contractors combined with secondary validation from SAMR GB standard filings, MEE environmental audit disclosures, customs import records for tropical hardwoods, and provincial construction pipeline databases.
Input-output matrices map engineered wood, solid wood, laminate, and bamboo production volumes against end-use absorption across residential renovation, commercial fit-out, institutional, and hospitality segments throughout the projection horizon. CAGRs derive from elasticity-adjusted demand curves incorporating click-lock adoption velocity, GB compliance cost pass-through, and substitution effects from SPC flooring. Industry-specific forecast inputs include MEE enforcement intensity scenarios and dual carbon goal plantation certification penetration rates.
The model holds under stable GB standard enforcement and petrochemical feedstock pricing; deviation in SAMR emission limit revisions or tropical hardwood import quota tightening would shift volume and value trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
Saudi Arabia Vinyl Flooring Market
Flooring, Carpets, and Rugs
Germany Flooring Market
Flooring, Carpets, and Rugs
Europe Laminate Flooring Market
Flooring, Carpets, and Rugs
GCC Floor Covering Market
Flooring, Carpets, and Rugs
GCC Flooring Market
Flooring, Carpets, and Rugs
Rigid Core Flooring Market
Flooring, Carpets, and Rugs
Resilient Flooring Market
Flooring, Carpets, and Rugs
US Vinyl Floorings Market
Flooring, Carpets, and Rugs
Wood Plastic Composite (WPC) Floorings Market
Flooring, Carpets, and Rugs
Brazil Floor Covering Market
Flooring, Carpets, and Rugs
Egypt Floor Covering Market
Flooring, Carpets, and Rugs
US Resilient Flooring Market
Flooring, Carpets, and Rugs
US Flooring Market
Flooring, Carpets, and Rugs
Sheet Flooring Market
Flooring, Carpets, and Rugs
Europe Floor Covering Market
Flooring, Carpets, and Rugs
Europe Flooring Market