
 China Do-It-Yourself (DIY) Home Improvement Retailing Market | 2026-2036
China Do-It-Yourself (DIY) Home Improvement Retailing Market Size, Share, and Industry Trends Forecast 2026-2036
China Do-It-Yourself (DIY) Home Improvement Retailing Market Insights
The capital-intensity gap between multinational hypermarket operators and domestic e-commerce platforms is collapsing. JD.com leverages its logistics backbone to offer same-day delivery of power tools and fixtures across provincial capitals. Leroy Merlin sustains premium positioning through experiential store formats that blend showroom displays with hands-on workshops. B&Q China anchors its coastal presence with localized inventory tailored to humid-climate construction needs.
China Do-It-Yourself (DIY) Home Improvement Retailing encompasses the sale of paint, tools, fixtures, and adhesives through physical and digital channels to non-professional renovators, with product specifications typically covering water-based acrylic emulsions, lithium-ion cordless systems, and ANSI-rated fastener grades for residential-grade applications. The primary commercial purpose is enabling consumers to execute structural, cosmetic, and functional upgrades without contracted labor. Online retail channels now capture the fastest expansion as live-streaming commerce and algorithmic recommendation engines reshape discovery patterns for DIY enthusiasts. Brick-and-mortar specialty stores retain margin concentration in premium paint and precision tooling segments where tactile evaluation drives purchase confidence.
MIIT enforces GB standards for cordless tool battery safety and electromagnetic compatibility, while SAMR monitors labeling accuracy and consumer protection compliance across e-commerce listings. MEE-administered dual carbon goals tighten VOC emission thresholds for architectural coatings, directly elevating demand for water-based and plant-derived formulations. Stakeholders must monitor how provincial implementation timelines for carbon intensity targets will reshape supplier qualification requirements and category mix decisions.
Market Dynamics
Live-streaming commerce is compressing the path from product discovery to purchase for DIY consumers, collapsing traditional retail margins while elevating algorithmic curation as the primary competitive battleground.
Growth Catalysts
- Dual carbon goals:MEE-administered emission reduction targets mandate low-VOC coatings and energy-efficient building materials, creating regulatory pull for water-based paint formulations and certified sustainable lumber.
- Lithium-ion cordless tool adoption:MIIT battery safety standards (GB 31241) have stabilized power tool electrification, enabling homeowners to abandon pneumatic systems for portable drilling and fastening equipment.
- Yangtze River Delta manufacturing density:Proximity between Shanghai consumption hubs and Zhejiang/Jiangsu production clusters compresses logistics costs and same-day fulfillment windows for fixtures and hardware.
Market Restraints
- GB standard compliance costs:MIIT electromagnetic compatibility testing and SAMR labeling accuracy requirements impose fixed certification burdens that disproportionately constrain small-format tool importers.
- Adhesive raw material volatility:Petrochemical feedstock price swings for epoxy resins and polyurethane foams compress margin predictability for sealant and bonding product lines.
- Substitution by turnkey renovation services:Full-service contractors in tier-one cities capture time-constrained homeowners who abandon self-execution for packaged design-build solutions.
Strategic Opportunities
- Tier-two city underpenetration:Chengdu, Xi'an, and Changsha exhibit rising homeownership rates among millennials with limited access to experiential retail formats, creating whitespace for workshop-anchored store concepts.
- Plant-derived coating formulations:Bio-based acrylic emulsions and natural oil finishes align with MEE carbon intensity trajectories while commanding premium positioning in environmentally segmented assortments.
- Social commerce integration:Douyin and Xiaohongshu algorithmic recommendation engines enable discovery-to-purchase loops that bypass traditional search-based e-commerce infrastructure.
Industry Challenges
- Skilled installation guidance gap:Retail staff lack technical depth to advise on structural load calculations and moisture-barrier sequencing, eroding consumer confidence in complex projects.
- Legacy inventory systems:ERP fragmentation between physical stores and digital fulfillment centers creates stock visibility failures that trigger cancellation rates in same-day delivery promises.
- Cross-provincial carbon compliance:Inconsistent provincial implementation timelines for MEE emission thresholds force suppliers to maintain multiple formulation SKUs for identical product categories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Do-It-Yourself (DIY) Home Improvement Retailing Market |
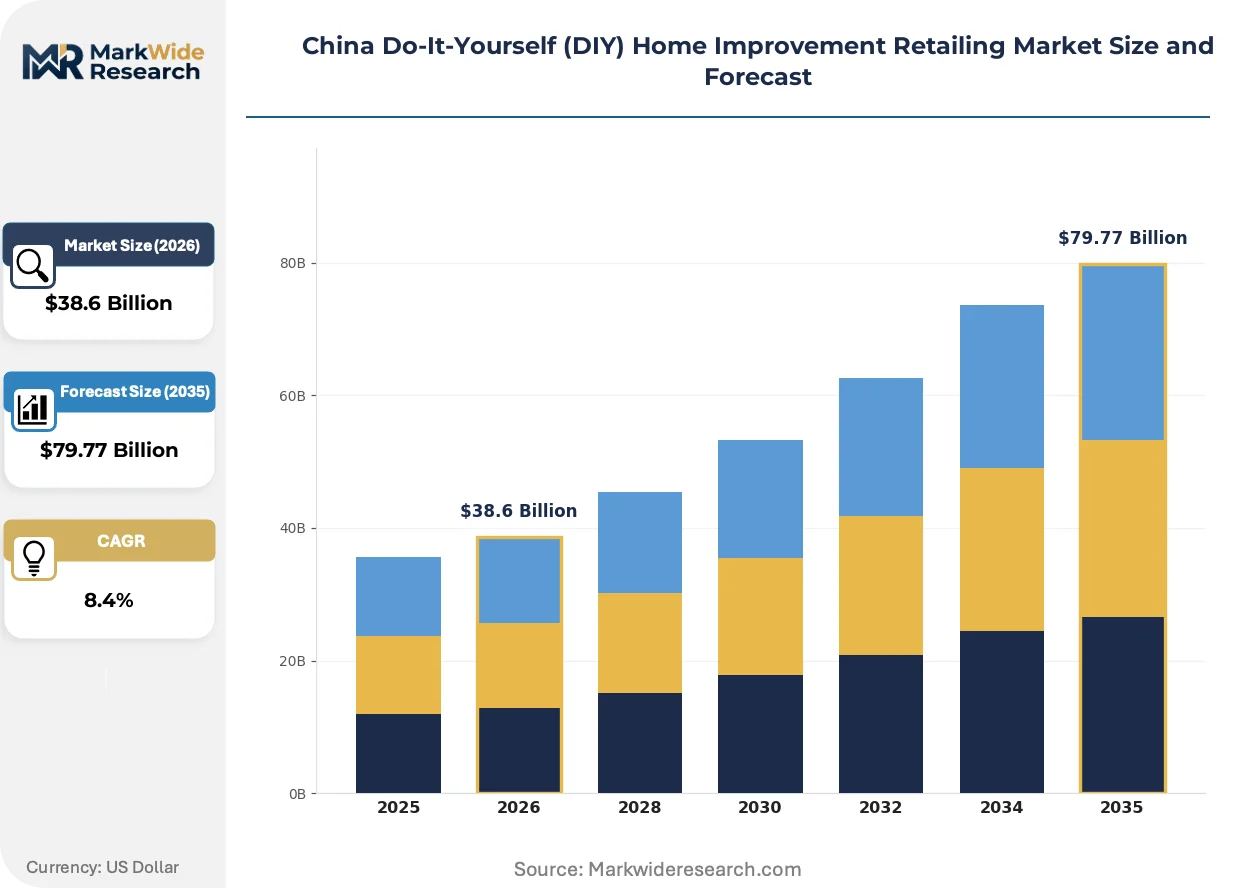
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $79.77 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paint, Tools, Fixtures, Adhesives Distribution Channel: Online Retail, Brick-and-Mortar, Wholesale, Specialty Stores Customer Type: Homeowners, Contractors, Interior Designers, DIY Enthusiasts Price Tier: Premium, Mid-Range, Budget, Discount |
| Companies Covered | Leroy Merlin, B&Q China, JD.com, Tmall, Pinduoduo, Kingfisher plc, Raamattu, OBI China, Ace Hardware, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Do-It-Yourself (DIY) Home Improvement Retailing Market Trends and Innovations
Algorithmic personalization and regulatory tightening are simultaneously elevating product specificity and compliance complexity, reshaping how DIY consumers discover, evaluate, and acquire home improvement materials.
Brushless motor technology is fragmenting the power tool category by enabling compact, high-torque systems that replace corded equivalents in drilling, cutting, and fastening applications. Young homeowners in tier-two cities adopt these systems for weekend renovation projects that previously required contractor equipment rental. The technology is fragmenting traditional rental-based access models by collapsing the cost barrier to professional-grade tool ownership.
MEE dual carbon goals are tightening VOC emission thresholds for architectural coatings through phased implementation of provincial carbon intensity targets. Water-based and plant-derived formulations gain shelf space as compliant alternatives to solvent-based systems. Paint manufacturers in the Yangtze River Delta are responding by reformulating product lines and pursuing third-party environmental certifications ahead of mandatory compliance windows.
Content-driven discovery is displacing search-based procurement as the dominant DIY consumer behavior. Short-form video tutorials on installation techniques generate direct product links that bypass traditional category navigation. This pattern concentrates in coastal metropolitan markets where platform penetration and homeownership rates among digital-native demographics achieve simultaneous density.
China Do-It-Yourself (DIY) Home Improvement Retailing Market Segmentation
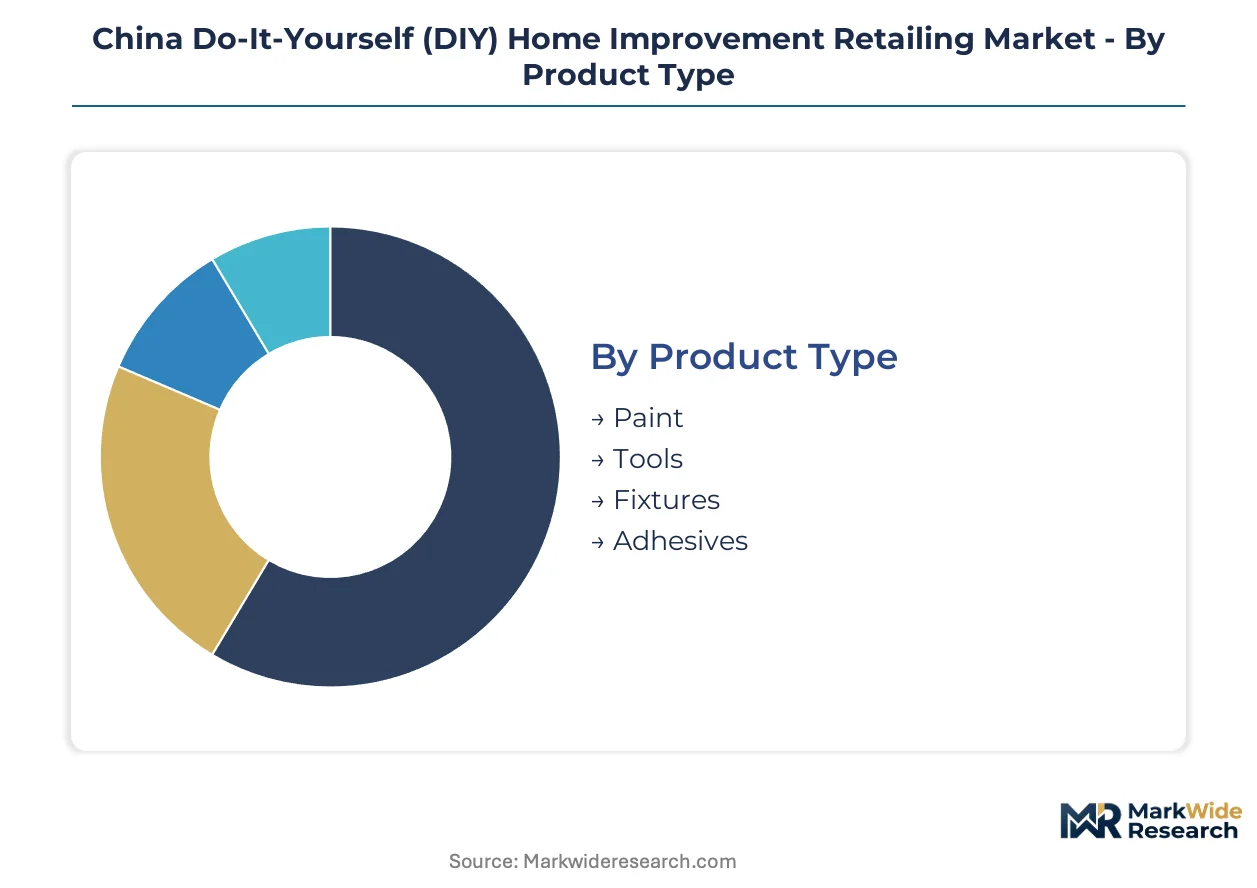
Segmentation in China's DIY home improvement retailing market reveals how MIIT battery standards, MEE carbon thresholds, and SAMR labeling requirements create divergent compliance burdens across product categories. Retailers must align inventory depth with the technical sophistication and regulatory exposure of each segment.
Product Type:
MIIT-administered GB 31241 battery safety standards and MEE dual carbon VOC thresholds impose distinct certification timelines across product categories, reshaping supplier qualification requirements.
- Paint:Water-based acrylic emulsions and plant-derived oil finishes dominate reformulation efforts as MEE tightens emission thresholds for architectural coatings. Demand concentrates in Shanghai and the Yangtze River Delta, where manufacturers pursue third-party environmental certifications ahead of provincial compliance windows.
- Tools:Lithium-ion cordless systems with brushless motor technology fragment traditional equipment access models by collapsing cost barriers to professional-grade ownership. Young homeowners in Chengdu and Xi'an adopt these systems for weekend renovation projects that previously required contractor rental arrangements.
- Fixtures:Residential-grade hardware and lighting assemblies face SAMR labeling accuracy scrutiny across e-commerce listings, with humidity-resistant specifications tailored to coastal climate conditions.
- Adhesives:Epoxy resins and polyurethane foams encounter petrochemical feedstock volatility that compresses margin predictability for sealant product lines.
Established volume favors paint; emerging adoption favors cordless tool systems.
Distribution Channel:
Channel economics in China fragment sharply between algorithmic curation platforms and experiential retail formats, with logistics infrastructure determining fulfillment viability.
- Online Retail:JD.com leverages its logistics backbone to offer same-day delivery of power tools and fixtures across provincial capitals. Live-streaming commerce on Douyin compresses discovery-to-purchase paths while collapsing traditional retail margins.
- Brick-and-Mortar:Leroy Merlin sustains premium positioning through showroom displays blended with hands-on workshops. B&Q China anchors coastal presence with localized inventory for humid-climate construction needs.
- Wholesale:Bulk procurement channels serve contractor segments with volume pricing, though ERP fragmentation between physical and digital systems creates stock visibility failures.
- Specialty Stores:Precision tooling and premium paint segments retain margin concentration where tactile evaluation drives purchase confidence.
Online retail captures the steepest expansion trajectory; specialty stores defend margin concentration.
Customer Type:
Customer sophistication tiers determine whether procurement prioritizes technical guidance, design integration, or pure cost efficiency.
- Homeowners:Millennials in tier-two cities exhibit rising renovation frequency but limited access to experiential retail formats, creating whitespace for workshop-anchored concepts.
- Contractors:Full-service providers in tier-one cities capture time-constrained homeowners who abandon self-execution for packaged design-build solutions.
- Interior Designers:Specification authority over fixture and finish selections influences premium product placement in residential projects.
- DIY Enthusiasts:Algorithmic recommendation engines on Xiaohongshu enable discovery loops that bypass traditional search-based e-commerce infrastructure.
Contractors anchor volume throughput; DIY enthusiasts drive algorithmic curation investment.
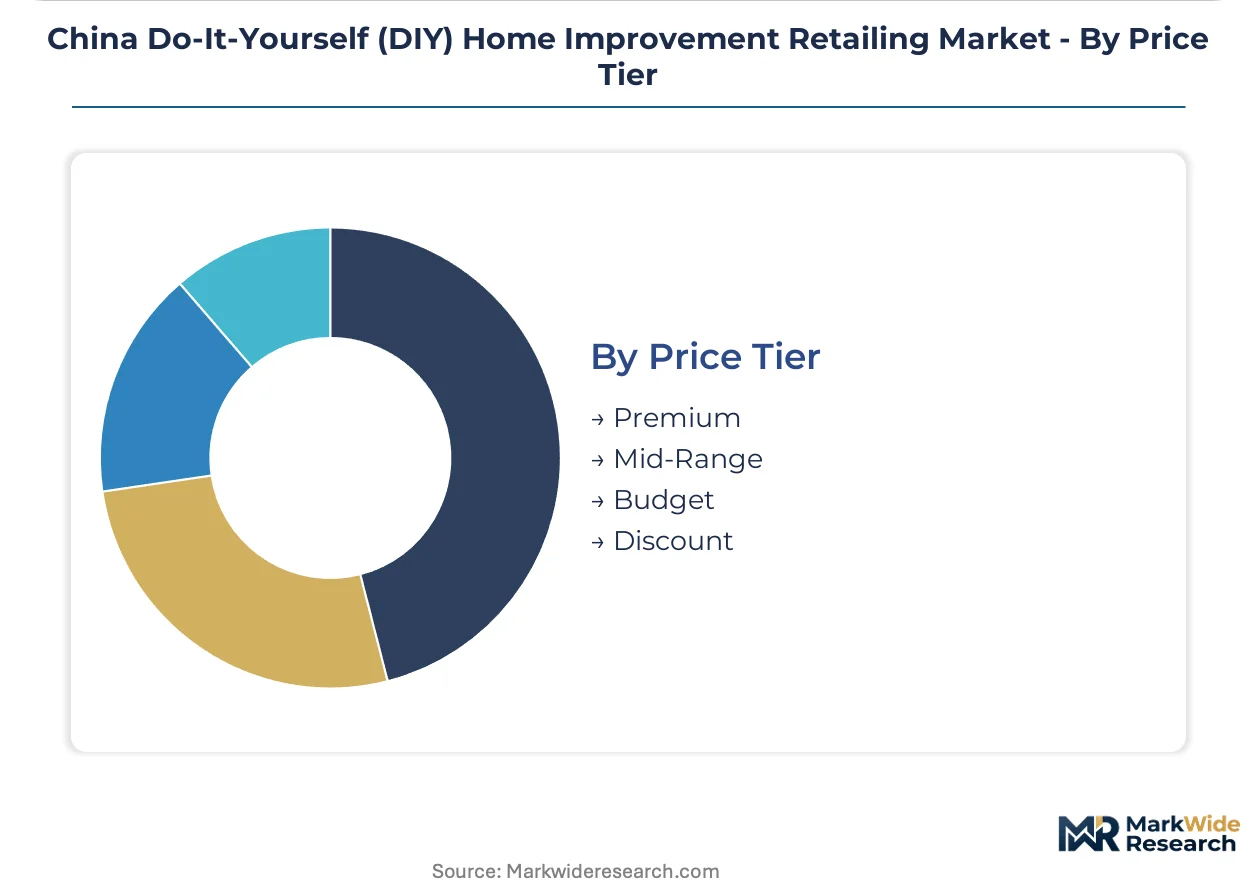
Price Tier:
Price stratification aligns with certification grade, environmental compliance status, and performance specifications rather than simple feature differentiation.
- Premium:Certified sustainable lumber and third-party-validated low-VOC coatings command positioning in environmentally segmented assortments.
- Mid-Range:Water-based paint formulations and lithium-ion cordless systems balance compliance readiness with accessibility for tier-two city adopters.
- Budget:Standard-grade fasteners and conventional solvent-based products face margin pressure from regulatory transition timelines.
- Discount:Unbranded imports encounter disproportionate constraints from MIIT electromagnetic compatibility testing and SAMR labeling requirements.
Premium tiers expand shelf space fastest; discount tiers face compliance-driven consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across China's DIY home improvement retailing market diverge sharply between coastal manufacturing belts and interior urban centers, with regulatory enforcement intensity and logistics infrastructure determining category penetration depth.
Yangtze River Delta
Shanghai and surrounding Zhejiang-Jiangsu manufacturing clusters generate simultaneous supply and consumption density for water-based paints and lithium-ion cordless tools. MEE-administered provincial carbon intensity targets accelerate reformulation timelines for architectural coatings ahead of national mandates. Suzhou and Ningbo production facilities now ship certified low-VOC formulations to tier-two city distributors within same-day windows.
Pearl River Delta
Guangzhou and Shenzhen homeowners exhibit elevated demand for humidity-resistant fixtures and precision tooling suited to subtropical construction conditions. SAMR labeling accuracy enforcement across e-commerce listings intensified following 2023 consumer protection audits. Dongguan hardware manufacturers coordinate with JD.com fulfillment centers to compress delivery lead times for cordless power tool systems.
Beijing-Tianjin-Hebei
Capital-region consumers prioritize energy-efficient building materials aligned with municipal green building codes under MEE oversight. MIIT electromagnetic compatibility testing requirements for imported power tools create certification bottlenecks at Tianjin port facilities. Langfang distribution hubs increasingly serve as compliance screening nodes for northern provincial markets.
Sichuan-Chongqing
Chengdu and Chongqing millennial homeowners drive adoption of weekend renovation formats with limited access to experiential retail formats. Provincial implementation timelines for MEE emission thresholds lag coastal counterparts by 12-18 months, extending market windows for conventional solvent-based products. Local distributors experiment with workshop-anchored store concepts to bridge technical guidance gaps.
Shandong Peninsula
Qingdao and Jinan construction material markets exhibit wholesale channel dominance serving contractor segments with volume pricing. SAMR monitors labeling accuracy across Pinduoduo listings originating from regional adhesive manufacturers. Yantai port facilities handle petrochemical feedstock imports for epoxy resin production facing margin compression from price volatility.
China Do-It-Yourself (DIY) Home Improvement Retailing Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in China's DIY home improvement retailing market, with platform scale and experiential format differentiation determining margin capture. JD.com and Tmall anchor the integrated tier through logistics backbone ownership and algorithmic curation infrastructure. Specialist tiers fragment between hypermarket operators with workshop-anchored formats and vertical e-commerce platforms with live-streaming commerce integration. Dominant competitive moves include same-day delivery network expansion and third-party environmental certification pre-positioning ahead of MEE compliance windows.
Among multinational hypermarket operators, Leroy Merlin and B&Q China occupy positions emphasizing experiential retail formats with hands-on workshop programming. JD.com represents the integrated platform archetype leveraging captive logistics infrastructure for fulfillment velocity. These three companies exemplify contrasting strategic postures: format-driven premium positioning versus scale-driven algorithmic curation.
| Leading Market Players |
|---|
| Leroy Merlin |
| B&Q China |
| JD.com |
| Tmall |
| Pinduoduo |
| Kingfisher plc |
| Raamattu |
| OBI China |
| Ace Hardware |
| Others |
Pricing and Supply Chain Analysis
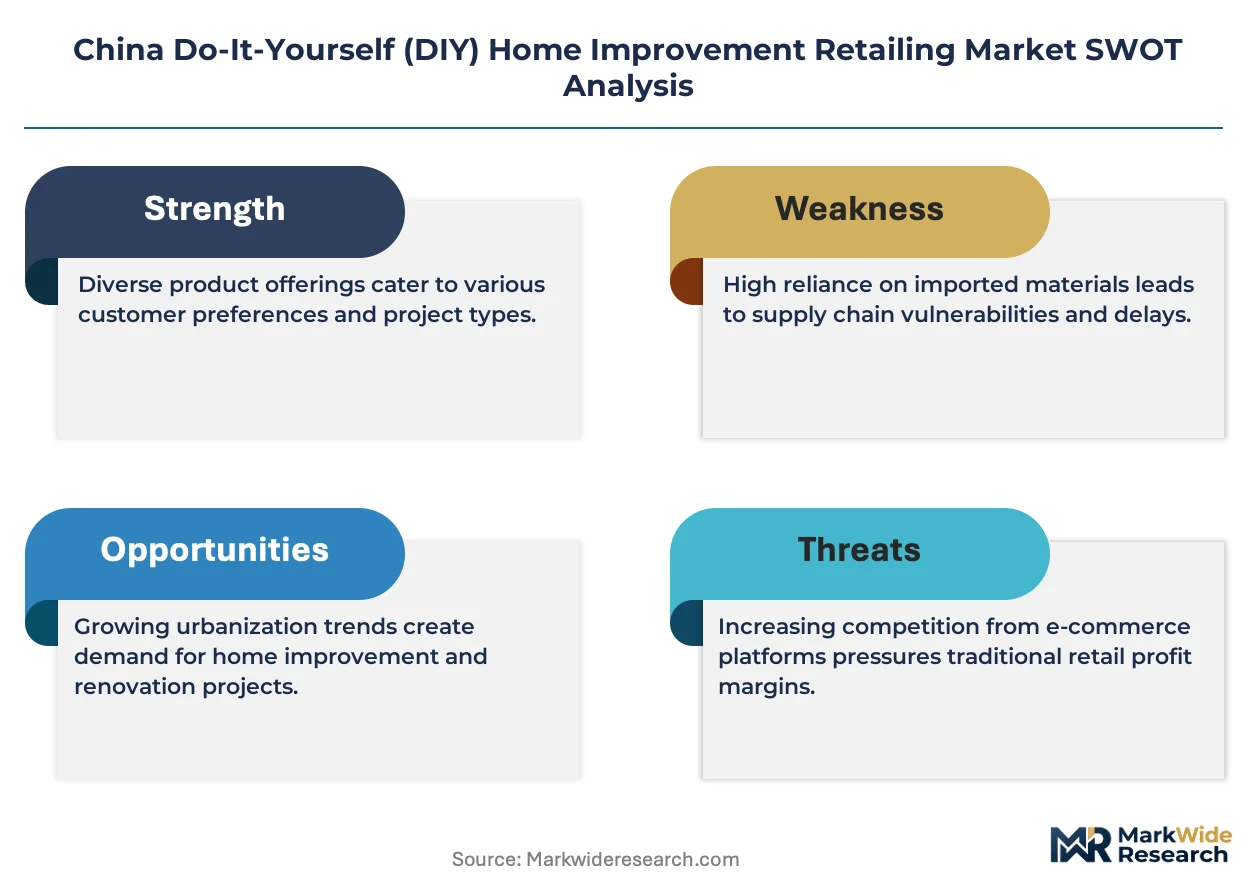
MEE-administered dual carbon goals and MIIT GB 31241 battery safety standards gate both supplier qualification and price differentiation simultaneously. Water-based paint formulations and certified lithium-ion cordless systems command shelf space premiums while conventional solvent-based products face margin compression from compliance transition timelines. Retailers must align procurement decisions with certification-ready supplier pools that concentrate in the Yangtze River Delta manufacturing belt.
Pricing Analysis
Long-term offtake contracts dominate paint and adhesive procurement between Yangtze River Delta manufacturers and national distributors, while spot purchasing governs emergency hardware replenishment. Three-tier pricing structure across premium, standard, and economy levels separates third-party-certified low-VOC coatings from reformulation-in-progress mid-tier products and conventional solvent-based budget lines. Price differentiation hinges on environmental certification grade and volume scale, with bulk contractor segments extracting steepest discounts. Cost compression in the discount tier intensifies because SAMR labeling accuracy enforcement has eliminated unbranded import channels that previously undercut domestic suppliers. Professional contractors exhibit highest price sensitivity due to thin project margins, while millennial homeowners in tier-two cities prioritize performance specifications over unit economics.
Supply Chain Analysis
Yangtze River Delta port congestion at Shanghai-Ningbo anchors supply risk for water-based paint resin feedstocks and lithium-ion battery cell imports. Manufacturing concentrates in China, South Korea, and Japan for cordless power tool systems, while Germany and Italy anchor precision tooling component sourcing. Raw material dependencies span petrochemical-derived acrylic emulsions, rare earth magnet powders for brushless motors, and copper wiring for battery management systems. Single-source vulnerability runs through Ningbo-based epoxy resin producers that supply sealant manufacturers across provincial markets. Distribution runs through JD.com's captive logistics backbone for same-day fulfillment, with wholesale channels serving contractor segments through regional distribution hubs in Langfang and Dongguan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's DIY home improvement retailing market reads as a service-attach opportunity where installation guidance subscriptions and extended tool warranty programs expand faster than hardware unit sales. Recurring revenue layers from workshop membership fees and on-demand technical consultation are capturing margin that transactional product sales cannot defend.
For Market Incumbents: Fortify experiential retail formats with hands-on workshop programming to defend against algorithmic curation platforms that collapse discovery-to-purchase paths. Deepen backward integration into water-based paint formulation capabilities ahead of MEE provincial compliance windows. Channel control through captive logistics infrastructure remains the priority lever against JD.com's same-day delivery velocity. For New Entrants and Emerging Players: Lead with workshop-anchored store concepts in Chengdu and Xi'an where millennial homeowners exhibit rising renovation frequency but limited access to tactile evaluation formats. The most penetrable segment is precision tooling for weekend renovation projects that substitutes rental-based access models. A go-to-market angle combining Douyin live-streaming discovery with in-store technical certification drives initial traction. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cordless tool manufacturing as brushless motor standardization collapses R&D replication costs. Long-term viability favors platform-scale operators with algorithmic curation infrastructure or specialist retailers with third-party environmental certification pre-positioning. Acquisition targets include vertically integrated paint formulators with MEE compliance-ready product lines. The signal to watch is provincial implementation timelines for carbon intensity targets that will force supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Workshop-Anchored Store Expansion | Leroy Merlin's hands-on programming builds purchase confidence that algorithmic platforms cannot replicate. |
| Third-Party Environmental Certification | Pre-positioning ahead of MEE compliance windows secures shelf space as VOC thresholds tighten. |
| Same-Day Delivery Network Buildout | JD.com's logistics backbone compresses fulfillment windows for cordless tools across provincial capitals. |
| Water-Based Paint Formulation Investment | Yangtze River Delta manufacturers reformulate product lines to meet dual carbon goal trajectories. |
| Social Commerce Platform Integration | Douyin and Xiaohongshu algorithmic engines enable discovery loops that bypass search-based procurement. |
Research Methodology
Cross-validation between regulatory filing analysis and distributor procurement data anchors the qualitative findings in this study. Primary interviews with paint formulation chemists, cordless tool product managers, JD.com logistics planners, and SAMR compliance officers combined with secondary validation from MIIT GB standard documentation, MEE emission threshold announcements, and customs trade records. Bottom-up triangulation across provincial distributor sales data and top-down reconciliation against national retail channel estimates produced volume and value outputs.
Sensitivity analysis around provincial implementation timelines for carbon intensity targets tested forecast robustness across the projection horizon. Segmentation dimensions modeled include product type, distribution channel, customer sophistication tier, and price positioning relative to certification grade. CAGRs were derived from trend extrapolation of adoption curves for lithium-ion cordless systems and water-based paint formulations. Industry-specific forecast inputs incorporated brushless motor technology penetration rates and live-streaming commerce platform growth trajectories.
The analysis sits within stated boundaries; outcomes outside sustained MEE enforcement intensity or logistics infrastructure investment levels would require recalibration. Forecasts reflect assumptions about regulatory compliance timelines and platform algorithmic curation adoption that could shift with policy acceleration or technology disruption. Revision becomes warranted when provincial carbon intensity target implementation crosses thresholds that force supplier qualification changes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Improvement and Renovation
Home Improvement Market
Home Improvement and Renovation
Vietnam DIY Home Improvement Market
Home Improvement and Renovation
Melamine Door Market
Home Improvement and Renovation
North America Fiberglass Doors Market
Home Improvement and Renovation
Double-Hung Windows Market
Home Improvement and Renovation
Brazil Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
Residential Interior Wood Doors Market
Home Improvement and Renovation
DIY Furnitures Market
Home Improvement and Renovation
United Kingdom Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
External Blinds Market
Home Improvement and Renovation
DIY Home Decor Market
Home Improvement and Renovation
Bays and Bows Window Market
Home Improvement and Renovation
South Africa Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
Interior Doors Market
Home Improvement and Renovation
Vietnam Home Improvement Market
Home Improvement and Renovation
US Home Remodeling Market