
 Europe Floor Covering Market | 2026-2036
Europe Floor Covering Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Floor Covering Market Foresight
Specialist flooring distributors across Northern Europe are reshaping procurement relationships by consolidating specification influence among architects and main contractors. Tarkett leverages integrated recycling infrastructure to secure circular economy contracts with public-sector buyers. Mohawk Industries anchors its European position through manufacturing scale in laminate and broadloom carpet segments. Gerflor competes on healthcare-specific vinyl formulations that meet stringent hygiene protocols.
Europe floor covering encompasses surface materials installed to protect subfloors, provide thermal and acoustic insulation, and define interior aesthetics, with products typically specified by wear-layer thickness, slip-resistance rating, and formaldehyde emission class under EN standards. The primary commercial purpose spans new construction fit-outs, renovation replacements, and sector-specific performance requirements from heavy industrial loading to sterile medical environments. Laminates occupy the value-oriented residential renovation segment where price sensitivity dominates homeowner decisions. Vinyl captures commercial specification share through water resistance and design versatility in hospitality and healthcare settings. Hardwood sustains premium positioning in heritage restoration and high-end residential projects where natural material authenticity commands specification priority.
REACH restrictions on phthalate plasticizers and the EU Green Deal's building-material carbon disclosure rules are forcing reformulation of PVC-based products and accelerating recycled-content verification requirements. ECHA's candidate list updates for SVHCs directly impact adhesive and coating selections across the supply chain. CE marking under the Construction Products Regulation governs market access for fire performance and slip resistance claims. Stakeholders must monitor evolving EPD requirements and bio-based content thresholds as procurement criteria in public tenders tighten ahead of anticipated regulatory phases.
Market Dynamics
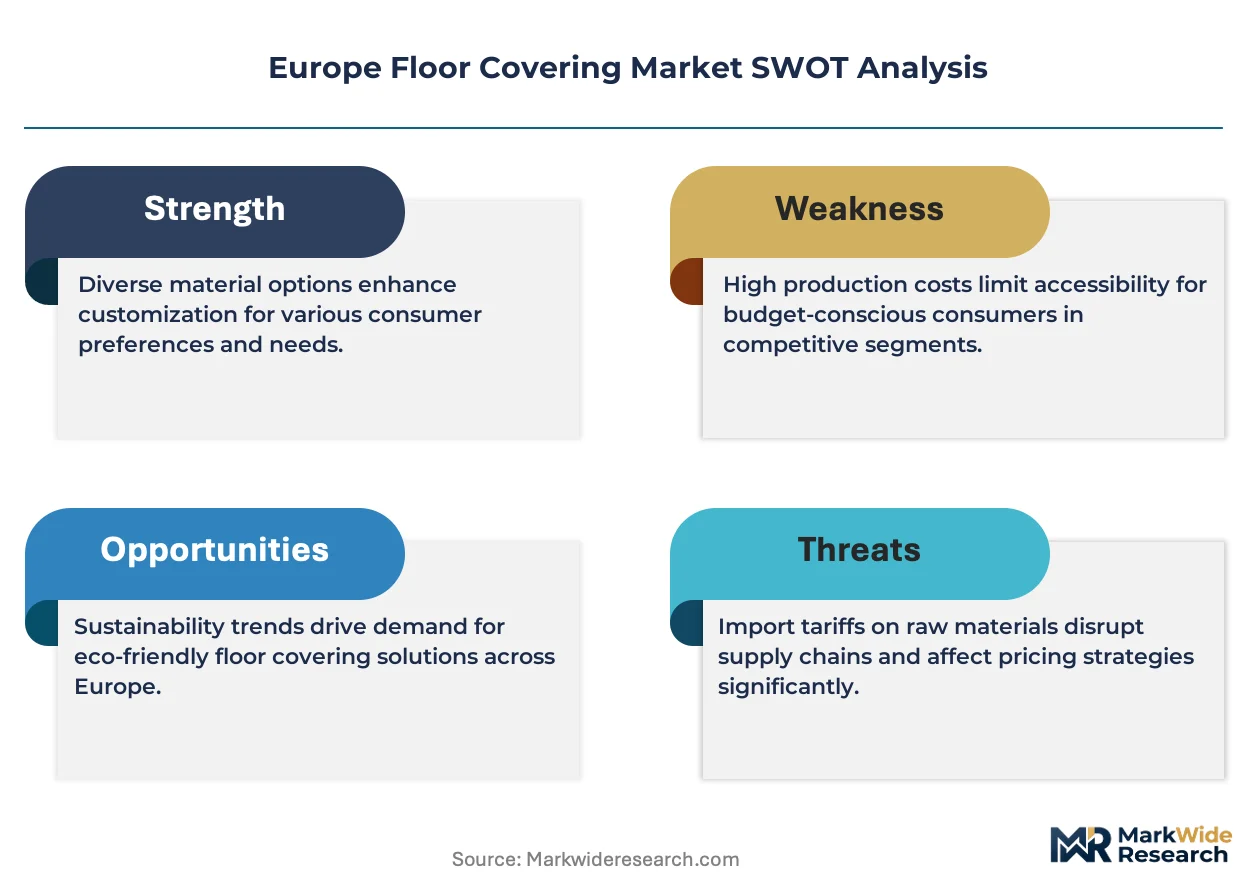
Renovation cycles across Europe's hospitality and healthcare sectors are compressing replacement timelines while EU Green Deal carbon thresholds force rapid material reformulation, creating simultaneous demand pull and supply-side compliance pressure.
Growth Catalysts
- Urban Renewal Corridors:France's mixed-use development zones specify modular carpet tile and luxury vinyl plank systems at scale, concentrating specification volume among integrated distributors.
- REACH Phthalate Restrictions:ECHA's SVHC candidate list updates accelerate bio-based plasticizer adoption, opening procurement pathways for reformulated resilient surfaces in public tenders.
- Healthcare Hygiene Protocols:Stringent infection-control standards in German and Dutch medical facilities drive specification of welded-sheet vinyl with antimicrobial wear layers.
Market Restraints
- Raw Material Concentration:PVC resin supply clusters in Northwest European petrochemical corridors expose manufacturers to feedstock volatility and single-source dependency.
- Technical Performance Gaps:Bio-based backing materials currently fail to match fossil-derived alternatives in dimensional stability under heavy rolling loads.
- Substitution Pressure:Polished concrete and epoxy systems capture specification share in industrial and logistics environments where lifecycle cost dominates aesthetic preference.
Strategic Opportunities
- Eastern European Renovation Wave:Poland and Romania's aging public building stock presents untapped demand for cost-optimized laminate and entry-level vinyl systems.
- Digital Specification Platforms:Building information modeling integrations allow manufacturers to embed EPD data directly into architect workflows, preempting competitor positioning.
- Circular Economy Mandates:Extended producer responsibility frameworks in the Netherlands and Belgium create first-mover advantage for take-back and recycling infrastructure.
Industry Challenges
- Skilled Installer Shortage:Subfloor preparation and heat-welding competencies for commercial vinyl contract across Germany and Scandinavia, extending project timelines.
- EPD Verification Bottlenecks:Third-party certification for environmental product declarations creates six-to-nine month delays in qualifying for green public procurement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Floor Covering Market |
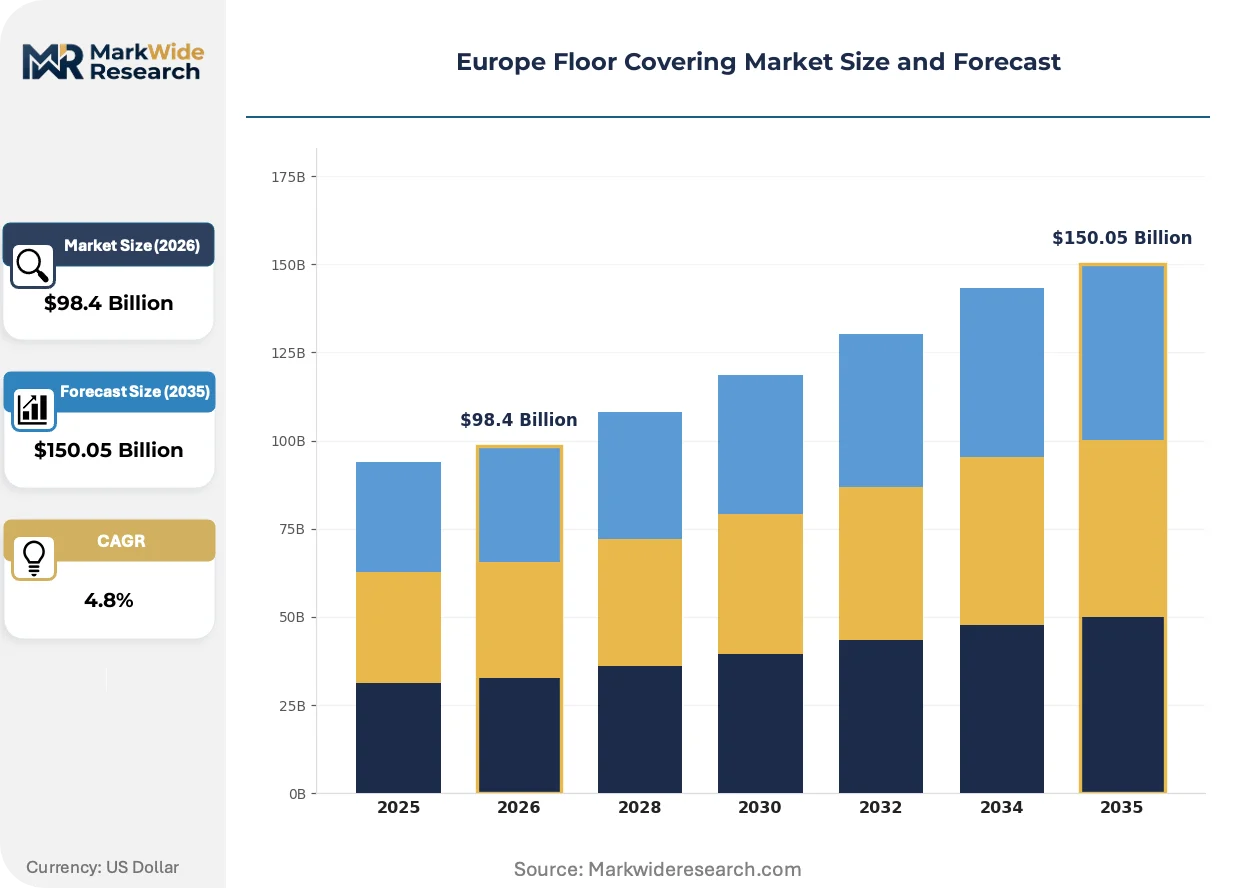
| Market Size in 2026 | $98.4 Billion |
| Market Size in 2035 | $150.05 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carpets, Laminates, Vinyl, Hardwood End User: Residential, Commercial, Industrial, Hospitality Distribution Channel: Retail, Online, Wholesale, Direct Sales Design Style: Modern, Traditional, Rustic, Minimalist |
| Companies Covered | Gerflor, Polyflor, Tarkett, Balta Group, Parador, Mohawk Industries, Interface, Beaulieu International Group, Forbo Flooring, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Floor Covering Market Shifts & Advancements
Digital tools and material science advances are compressing traditional specification and installation workflows, while regulatory disclosure requirements embed sustainability verification into every procurement decision.
Digital printing technology is collapsing the cost structure of custom surface design, enabling batch-size-one production of wood-grain and stone visuals without cylinder engraving investment. Hospitality chains in Spain and Italy adopt this capability for property-specific branding at renovation scale. The technology is collapsing minimum order thresholds that previously protected centralized manufacturing economics.
EU Green Deal building-material carbon disclosure rules mandate embodied carbon reporting across the construction product lifecycle. EPD program operators expand verification capacity to meet manufacturer backlog. Flooring categories with established recycled-content supply chains—particularly carpet tile and rubber—capture preferential positioning in French and Dutch public tenders ahead of anticipated threshold tightening.
Specification influence migrates from independent retailers to consolidated distributor-architect relationships, compressing the traditional two-step distribution model. Northern European main contractors centralize flooring procurement through framework agreements with technical specialists. This concentration is most visible in Germany's healthcare and education verticals, where single-source accountability reduces interface risk on complex fit-out programs.
Europe Floor Covering Market Segmentation
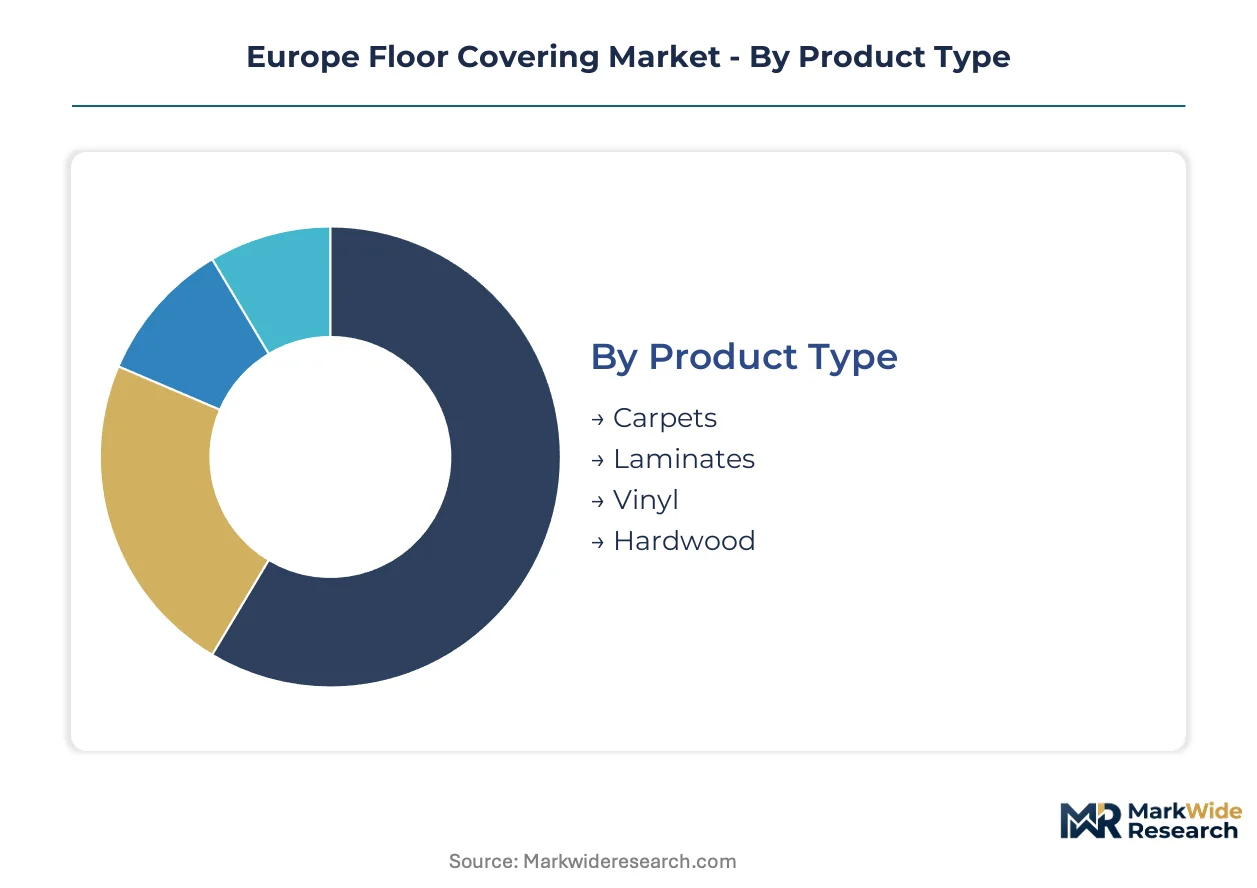
Floor covering procurement in Europe diverges sharply across application contexts, with specification criteria shifting from price sensitivity in residential renovation to performance certification in healthcare and hospitality fit-outs. Understanding these segment boundaries reveals where margin pools concentrate and where volume expansion is accelerating.
Product Type:
Cost tier separates the four material categories, with fossil-derived synthetics anchoring the mid-market and natural materials commanding premium positioning.
- Carpets:Broadloom and modular systems incorporate recycled nylon face fibers and bio-based backings to meet EU Green Deal carbon disclosure thresholds. German healthcare facilities and Dutch office complexes specify carpet tile for acoustic performance and ease of zone replacement.
- Vinyl:Resilient sheet and luxury vinyl plank formulations dominate hospitality and medical environments where slip resistance, water impermeability, and heat-welded hygiene seams are non-negotiable. REACH phthalate restrictions are forcing rapid plasticizer reformulation across Belgian and French manufacturing plants.
- Laminates:Fiberboard-core floating floors capture residential renovation demand in Poland and Romania where cost optimization outweighs longevity concerns.
- Hardwood:Engineered and solid oak planks sustain heritage restoration projects in France and premium residential specifications in Scandinavian urban centers.
Vinyl commands the established base. The steepest expansion runs through carpet tile systems.
End User:
Application context dictates specification complexity, with regulated environments imposing testing regimes that exclude commodity suppliers.
- Residential:Homeowner-driven replacement cycles favor laminate and entry-level vinyl in Eastern European markets, while Western European renovation concentrates on engineered hardwood and LVT for open-plan living zones.
- Commercial:Office and retail fit-outs in France's urban renewal corridors specify modular carpet and LVT through consolidated distributor-architect relationships that compress traditional retail channels.
- Industrial:Logistics facilities and manufacturing plants in Germany's automotive belt increasingly specify polished concrete and epoxy systems where lifecycle cost trumps aesthetic considerations.
- Hospitality:Hotel renovation cycles across Spain and Italy leverage digital printing technology for property-specific surface branding at batch-size-one economics.
Commercial applications anchor current volume. Hospitality renovation is climbing the fastest.
Distribution Channel:
Customer type and project scale determine channel selection, with main contractors centralizing procurement for complex fit-outs while homeowners retain retail relationships.
- Retail:Independent flooring specialists and home improvement chains serve residential replacement demand, though specification influence is migrating toward distributor-consolidated networks in Northern Europe.
- Online:Digital platforms capture sample ordering and standard product replenishment, particularly for laminate and click-system vinyl where tactile evaluation is less critical than for textile surfaces.
- Wholesale:Specialist distributors in Germany and the Netherlands consolidate framework agreements with main contractors, embedding EPD data directly into BIM workflows for public-sector tenders.
- Direct Sales:Manufacturers with recycling infrastructure pursue circular economy contracts through direct relationships with hospital groups and education authorities in Belgium and the Netherlands.
Wholesale channels command the established base. Direct sales to institutional buyers is gaining share fastest.
Design Style:
Volume concentration varies by geography and building vintage, with specification trends diverging between heritage restoration and new construction aesthetics.
- Modern:Clean lines and large-format surfaces dominate new mixed-use developments in French urban renewal zones, specifying rectified LVT and minimalist carpet tile.
- Traditional:Parquet patterns and classic woven textures sustain demand in heritage building restoration across Vienna, Prague, and Parisian Haussmann renovations.
- Rustic:Distressed wood visuals and hand-scraped textures capture Alpine hospitality and rural hospitality specifications in Bavaria and Tyrol.
- Minimalist:Monolithic surfaces and neutral palettes align with Scandinavian residential norms and Dutch healthcare hygiene protocols that reject visual clutter.
Modern styling commands the established base. Minimalist specifications are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Alpine corridor's freight rail network underwrites Germany's centrality in European floor covering distribution, connecting Belgian petrochemical feedstock to manufacturing clusters across the continent.
Germany
Healthcare renovation in the Rhine-Ruhr and Bavaria drives specification of welded-sheet vinyl with antimicrobial properties. REACH phthalate restrictions through ECHA accelerate bio-based plasticizer adoption among domestic formulators. Stuttgart's automotive belt increasingly specifies polished concrete for logistics facilities where lifecycle cost dominates.
France
Urban renewal corridors in Île-de-France and Lyon concentrate mixed-use development specifying modular carpet tile and luxury vinyl plank. EU Green Deal carbon disclosure rules mandate embodied carbon reporting for public tenders. The Parisian Haussmann restoration cluster sustains premium engineered hardwood demand for heritage compliance.
Netherlands
Extended producer responsibility frameworks in Randstad create first-mover advantage for take-back and recycling infrastructure. EPD verification requirements tighten ahead of anticipated threshold phases in public procurement. Rotterdam's port logistics hub channels imported PVC resin to domestic vinyl manufacturers.
Belgium
Circular economy mandates in Flanders and Wallonia drive direct manufacturer relationships with hospital groups and education authorities. CE marking under the Construction Products Regulation governs fire performance claims for commercial specification. The Antwerp petrochemical corridor anchors PVC resin supply for regional formulators.
Poland
Aging public building stock in Warsaw and Kraków presents demand for cost-optimized laminate and entry-level vinyl systems. EU cohesion funds accelerate municipal renovation timelines. The Silesian industrial zone concentrates distribution infrastructure serving Eastern European replacement cycles.
Europe Floor Covering Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream on material formulation and recycling infrastructure. The vendor base organizes around three archetypes: integrated manufacturers with captive recycling networks, specification-focused specialists in healthcare and hospitality verticals, and scale-driven laminate producers serving price-sensitive renovation demand. Consolidation pressure runs through distributor-architect relationships that compress traditional two-step channels. Geographic expansion and circular economy contracting represent the dominant competitive vectors.
Among integrated French manufacturers, Tarkett and Gerflor occupy positions defined by recycling infrastructure and sector-specific formulation expertise. Tarkett exemplifies the circular economy archetype through integrated take-back systems, while Gerflor represents healthcare-specialized vinyl formulation. Mohawk Industries anchors the scale-driven laminate segment with manufacturing presence across multiple European production sites. These three companies illustrate the structural divergence between sustainability-integrated platforms and volume-oriented producers.
| Leading Market Players |
|---|
| Gerflor |
| Polyflor |
| Tarkett |
| Balta Group |
| Parador |
| Mohawk Industries |
| Interface |
| Beaulieu International Group |
| Forbo Flooring |
| Others |
Supply & Pricing Matrix
The Antwerp petrochemical corridor anchors PVC resin supply for European flooring formulators, concentrating upstream pricing power among integrated resin producers while downstream manufacturers absorb volatility through contract structures. REACH phthalate restrictions and ECHA's SVHC candidate list updates are forcing rapid reformulation costs that compress margins across mid-tier vinyl producers unable to pass through compliance investments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates heritage-certified hardwood from commodity laminate and entry-level vinyl. Certification grade under EU Green Deal carbon disclosure rules and volume scale through framework agreements with German healthcare consortia drive price differentiation. Cost compression in the economy tier is intensifying because Polish and Romanian municipal buyers prioritize first-cost minimization over lifecycle value. Residential renovation segments in Eastern Europe exhibit highest price sensitivity, while Dutch hospital procurement committees prioritize performance certification over unit cost.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard for distributor relationships with main contractors in France and Germany, straining working capital for smaller formulators. PVC resin supply clusters in Belgium, the Netherlands, and Germany, while bio-based plasticizer feedstocks draw from rapeseed and castor oil cultivation in France and Eastern Europe. Single-source vulnerability in Northwest European petrochemical corridors exposes manufacturers to feedstock disruption. Distribution runs through specialist wholesalers consolidating framework agreements with architect-specifier networks across Northern Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polished concrete and epoxy systems are capturing specification share in industrial and logistics environments, forcing traditional resilient flooring incumbents to defend their core commercial and healthcare positions through performance differentiation rather than cost competition.
For Market Incumbents: Harden specification influence through embedded EPD data in BIM workflows that preempt competitor positioning in Dutch and Belgian public tenders. Deepen backward integration into bio-based backing material supply chains to secure circular economy contracts ahead of anticipated EU Green Deal threshold tightening. Defend against substitution by welded-sheet vinyl specialists through antimicrobial formulation investments targeting German healthcare renovation cycles. For New Entrants and Emerging Players: Establish a beachhead in Poland and Romania's aging public building stock by offering cost-optimized laminate systems that qualify for EU cohesion fund procurement. Target direct sales relationships with hospital groups in Belgium and the Netherlands where extended producer responsibility frameworks create first-mover advantage for take-back infrastructure. Lead with digital specification platforms that compress traditional distributor-architect relationship barriers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated manufacturers with captive recycling networks and healthcare-specific formulation expertise over scale-driven commodity producers. Long-term viability hinges on circular economy contracting capability and bio-based material substitution readiness. Monitor EPD verification backlog duration as an inflection indicator for green public procurement qualification delays that would advantage pre-certified incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Plasticizers | REACH compliance secures public tender access ahead of ECHA threshold tightening. |
| BIM-embedded EPD Data Integration | Preempts competitor positioning in French and Dutch architect-specifier networks. |
| Take-back Infrastructure Buildout | Captures circular economy contracts under Netherlands extended producer responsibility. |
| Healthcare-specific Antimicrobial Formulation | Meets German infection-control standards driving welded-sheet vinyl specification. |
| Eastern European Distribution Expansion | Channels cost-optimized product to Poland and Romania municipal renovation demand. |
Research Methodology
Operator-level perspectives from flooring procurement managers at German hospital groups, specification architects in French urban renewal corridors, and technical directors at Belgian PVC formulators anchored the qualitative base. Primary interviews combined with secondary validation through ECHA regulatory filings, EU Green Deal implementation documents, and Construction Products Regulation CE marking databases. Customs data from Eurostat, industry association reports from Cefic and ERFMI, and tender documentation from Dutch and Belgian public procurement portals supported bottom-up and top-down triangulation.
Scenario-bracketing framed volume and value outputs across the projection horizon, modeling product type segmentation by material category, end-use application by building sector, and distribution channel by customer archetype. CAGRs were derived from installed base replacement cycles, new construction fit-out ratios, and sector-specific specification intensity indices. Forecast inputs included REACH regulatory phase-in schedules, EU Green Deal embodied carbon threshold trajectories, and Eastern European cohesion fund disbursement patterns.
Sensitivities concentrate around EPD verification capacity bottlenecks, bio-based material performance gap closure timelines, and substitution acceleration in industrial applications. Forecasts reflect documented assumptions regarding regulatory implementation pacing and renovation cycle compression. Macroeconomic deviation, regulatory acceleration or delay, or breakthroughs in alternative surface technologies would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
United States Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
North America Vinyl Flooring Market
Flooring, Carpets, and Rugs
Saudi Arabia Carpet and Rugs Market
Flooring, Carpets, and Rugs
Middle East Flooring and Carpet Market
Flooring, Carpets, and Rugs
Taiwan Floor Covering Market
Flooring, Carpets, and Rugs
India Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
North America Laminate Flooring Market
Flooring, Carpets, and Rugs
Germany Resilient Flooring Market
Flooring, Carpets, and Rugs
North America Carpet Tile Market
Flooring, Carpets, and Rugs
China Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Laminate Flooring Market
Flooring, Carpets, and Rugs
United States Floor Covering Market
Flooring, Carpets, and Rugs
Hard Surface Flooring Market
Flooring, Carpets, and Rugs
Sheet Flooring Market
Flooring, Carpets, and Rugs
Global Flooring Market
Flooring, Carpets, and Rugs
US Flooring Market