
 Asia Pacific Flooring Market | 2026-2036
Asia Pacific Flooring Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Flooring Market Insights
Commercial facility managers and institutional buyers is bifurcating demand away from traditional residential contractors across the Asia Pacific Flooring Market. Mohawk Industries leverages its integrated supply chain to dominate engineered hardwood distribution in Australia and Japan. Kajaria Ceramics Limited anchors India's ceramic tile production with captive raw material sourcing from Gujarat's mineral belt. Tarkett competes through specialized vinyl recycling technology that addresses commercial sustainability mandates.
Asia Pacific flooring encompasses surface covering materials installed for structural support, aesthetic finish, and functional performance across built environments, with products engineered to specific abrasion class ratings, slip resistance coefficients, and thermal conductivity values for climate-adapted commercial and residential use. Vinyl leads volume growth across the region due to water resistance and rapid floating installation methods suited to Southeast Asia's humid construction cycles. Hardwood maintains premium positioning in Japan and South Korea where JIS standards and architectural preference for natural materials sustain higher margin pools. Carpet faces structural compression in commercial applications as facility managers prioritize hard surfaces for hygiene and lifecycle cost management.
Japan's METI enforces building material energy efficiency standards that directly shape product specification for commercial flooring retrofits. India's BIS certification requirements for ceramic tiles create compliance barriers that concentrate supply among large-scale domestic manufacturers. China's GB standards for formaldehyde emissions in laminate products constrain import access and elevate local production. Stakeholders must monitor divergence between national certification regimes as regional procurement platforms expand cross-border specification.
Market Dynamics
Commercial facility managers across Southeast Asia are accelerating specification of low-VOC resilient flooring as green building codes tighten, compressing traditional residential contractor channels and elevating institutional procurement platforms.
Growth Catalysts
- Green building mandates:Thailand's TREES certification and Singapore's Green Mark standards compel developers to specify certified low-emission materials, expanding specification-grade vinyl and rubber flooring volumes in Bangkok and Jakarta commercial towers.
- Captive raw material clusters:Gujarat's mineral belt and Jiangsu province's kaolin deposits concentrate ceramic tile feedstock access, reducing landed costs for institutional buyers sourcing at scale for healthcare and education footprints.
- Floating installation methods:Click-lock LVT and SPC systems eliminate adhesive curing cycles, compressing project timelines for Southeast Asian contractors facing monsoon-constrained construction windows.
Market Restraints
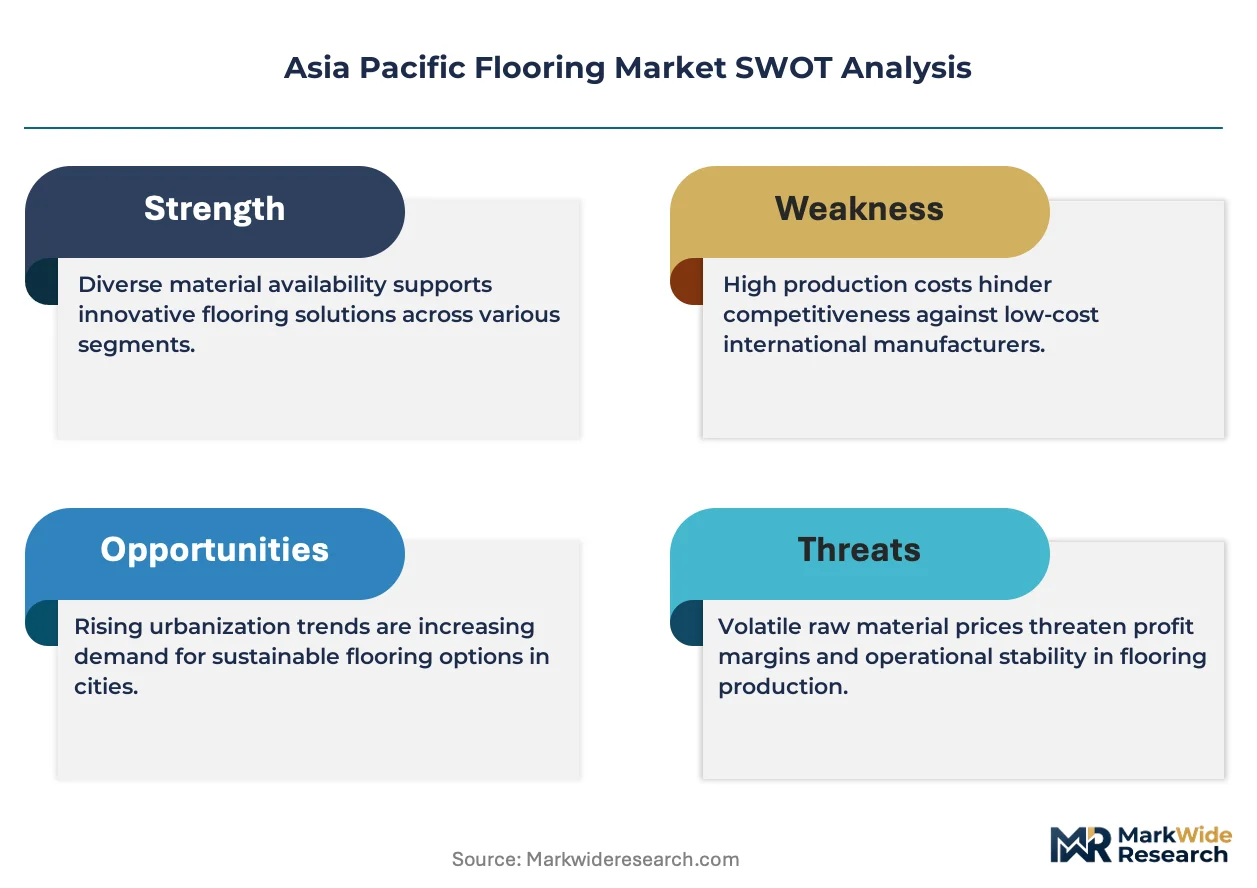
- Petrochemical input volatility:PVC resin and plasticizer costs track naphtha and ethylene spreads, compressing margin stability for vinyl flooring manufacturers serving price-sensitive Southeast Asian residential segments.
- Supply concentration risk:China's Jiangsu and Shandong provinces host over 60% of regional laminate substrate capacity, exposing procurement continuity to provincial environmental inspection cycles and power rationing protocols.
- Formaldehyde emission constraints:China's GB 18580-2017 standard and Japan's JIS A 1460 create non-tariff barriers that fragment cross-border product flows and elevate compliance costs for multi-country specification.
Strategic Opportunities
- Vietnam manufacturing migration:Labor cost differentials and EU-Vietnam FTA tariff advantages attract tile and resilient flooring investment to Binh Duong province, creating export-oriented capacity for European commercial procurement.
- Recyclable vinyl systems:Post-installation and post-consumer PVC recovery programs align with Australia's National Waste Policy Action Plan, opening specification pathways for circular-economy-certified products in Melbourne and Sydney public infrastructure.
- Healthcare antimicrobial surfaces:Silver-ion and copper-embedded flooring technologies address infection control protocols in Japan's aging-care facilities and India's hospital expansion programs, commanding premium positioning over standard commercial grades.
Industry Challenges
- Skilled installer scarcity:Floating LVT and polished concrete systems require specialized substrate preparation and moisture mitigation expertise, creating bottlenecks in Indonesia and Philippines markets where training infrastructure lags specification demand.
- Multi-certification timelines:Simultaneous BIS, JIS, and GB standard compliance testing extends product launch cycles by 8-14 months for manufacturers targeting cross-border specification platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Flooring Market |
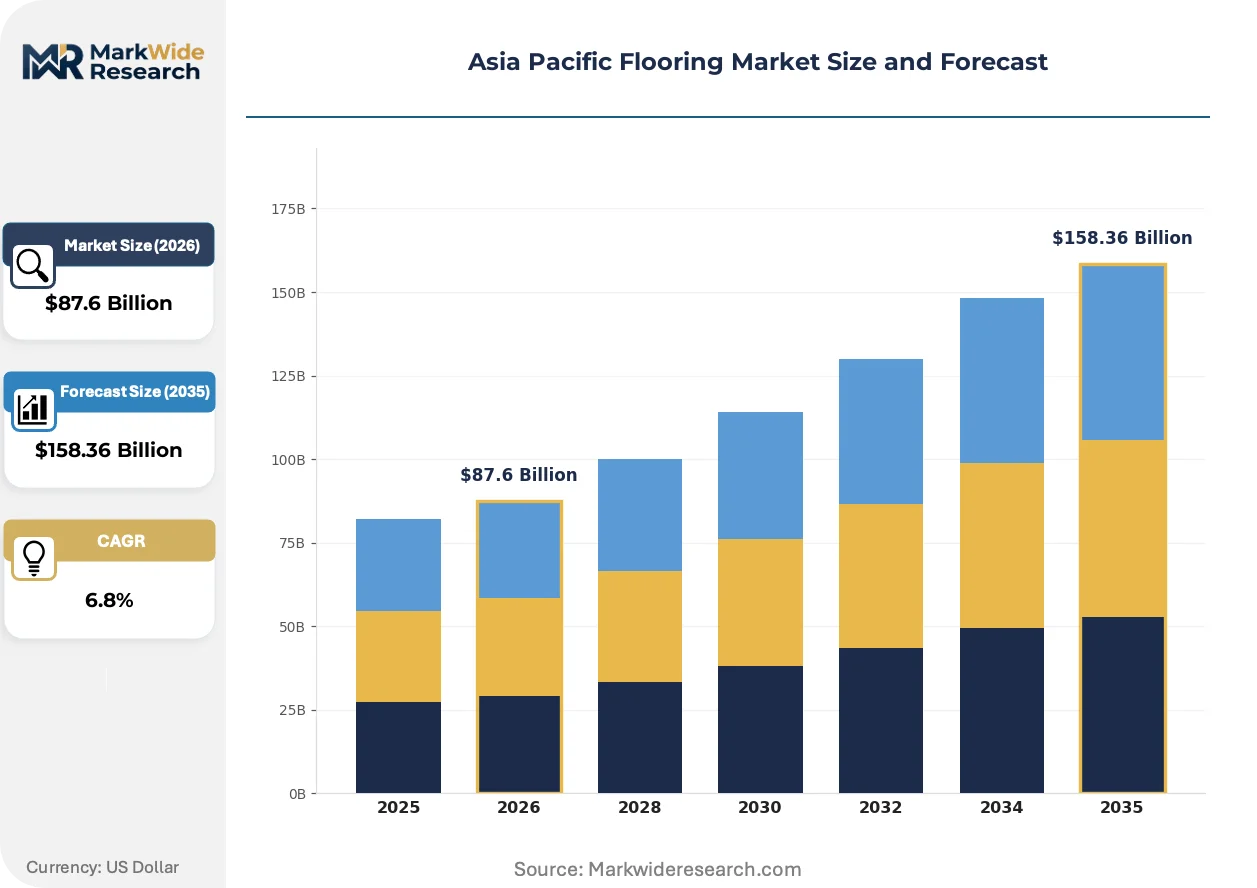
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $158.36 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardwood, Laminate, Vinyl, Carpet Application: Residential, Commercial, Industrial, Institutional End User: Contractors, Architects, Homeowners, Facility Managers Installation Method: Glue Down, Nail Down, Floating, Loose Lay |
| Companies Covered | Mohawk Industries, Inc., Tarkett, Kajaria Ceramics Limited, DAIKEN Corporation, Forbo Flooring Systems, TOLI Corporation, Shaw Industries Group, Inc., CERA Sanitaryware Limited, RAK Ceramics, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Flooring Market Trends and Innovations
Material science advances and procurement platform digitization are compressing traditional specification cycles while elevating performance-certified products across institutional verticals in the Asia Pacific Flooring Market.
Dry-back and loose-lay vinyl flooring is bifurcating specification authority between adhesive-dependent traditional systems and floating installations. Facility managers in Singapore and Hong Kong commercial retrofits are specifying click-lock SPC at 3-4x the pace of conventional glue-down LVT. This technology is bifurcating installer capability requirements and compressing maintenance contractor revenue pools tied to seam repair and adhesive failure remediation.
Japan's METI building material energy efficiency standards and Australia's NCC Section J provisions are mandating thermal performance disclosure for commercial flooring systems. Manufacturers must now publish R-values and embodied carbon data to maintain specification eligibility in Sydney and Tokyo commercial towers. Healthcare and education verticals in both markets are prioritizing products with verified Environmental Product Declarations over uncertified alternatives.
Consolidated procurement through facility management platforms is displacing fragmented contractor purchasing across Southeast Asian commercial real estate. JLL and CBRE-managed portfolios in Bangkok, Kuala Lumpur, and Manila are centralizing flooring specification through master service agreements with tier-1 manufacturers. This concentration is most visible in Grade A office and logistics warehouse segments where lifecycle cost modeling overrides first-cost contractor preferences.
Asia Pacific Flooring Market Segmentation
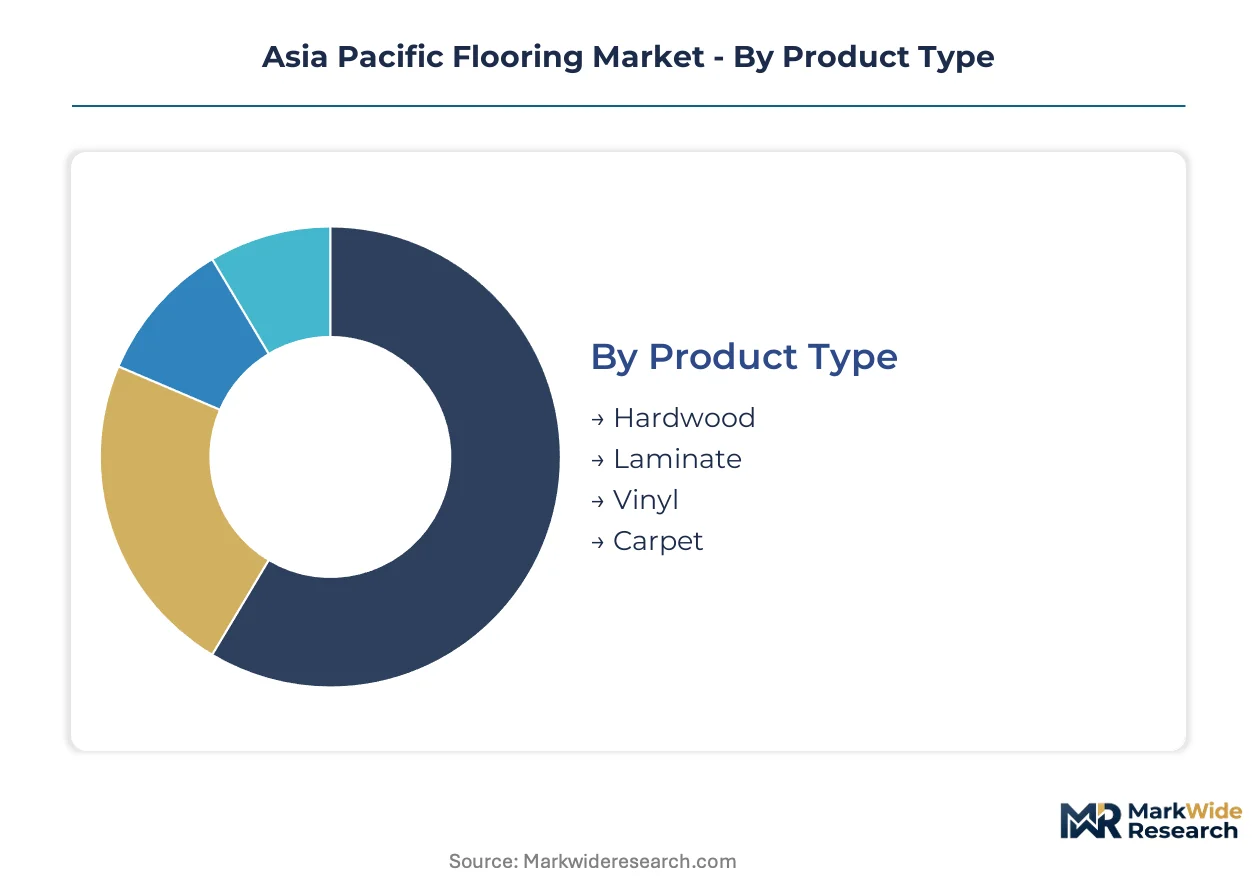
Asia Pacific flooring procurement flows through distinct channel architectures where product type determines whether specification authority rests with contractors, architects, or facility management platforms. Understanding these segment intersections reveals where margin pools concentrate and where specification influence is shifting.
Product Type:
Vinyl and laminate dominate contractor procurement channels across Southeast Asia, while hardwood and carpet flow through architect-led specification for premium residential and commercial projects.
- Vinyl:Polymer-based resilient flooring combining PVC or SPC cores with printed wear layers, engineered for moisture resistance and rapid installation. Demand concentrates in Singapore and Bangkok commercial towers where Green Mark and TREES certification mandates specify low-VOC resilient systems for healthcare and education footprints. Facility managers prioritize vinyl's lifecycle cost advantages over traditional materials in high-traffic institutional environments.
- Hardwood:Solid or engineered timber products meeting JIS standards for dimensional stability and finish durability. Specification authority rests with architects in Tokyo and Seoul residential developments where natural material preference sustains premium positioning despite higher installed costs. Japan's METI energy efficiency standards for building materials directly shape product eligibility for commercial retrofits.
- Laminate:High-density fiberboard substrates with melamine-impregnated decorative layers, constrained by China's GB 18580-2017 formaldehyde emission limits that fragment cross-border supply flows.
- Carpet:Tufted or woven textile floor coverings facing structural compression as hard surfaces gain preference for hygiene and maintenance cost management in commercial applications.
By volume, vinyl leads. By growth pace, engineered hardwood variants are expanding most quickly in Japan's aging-care facility sector.
Application:
Cost tier stratification separates specification-grade products for institutional and commercial use from economy-grade materials serving residential replacement cycles.
- Commercial:Grade A office towers, retail footprints, and hospitality spaces requiring abrasion class ratings and slip resistance certification. JLL and CBRE-managed portfolios in Bangkok, Kuala Lumpur, and Manila centralize procurement through master service agreements, compressing traditional contractor channel influence. Lifecycle cost modeling overrides first-cost preferences in this segment.
- Institutional:Healthcare, education, and government facilities governed by antimicrobial surface protocols and thermal performance disclosure requirements under Australia's NCC Section J and Japan's METI standards. Silver-ion and copper-embedded technologies command premium positioning in this tier.
- Residential:New construction and renovation demand channeled through contractor networks and retail distribution, with floating installation methods gaining share for speed-to-completion in monsoon-constrained construction windows.
- Industrial:Manufacturing and logistics warehouses prioritizing durability and chemical resistance over aesthetic finish, with procurement consolidating through facility management platforms in Vietnam's Binh Duong export-oriented manufacturing zones.
Commercial applications generate the highest margin per square meter. Institutional projects show the steepest specification-grade conversion rate.
End User:
Customer type determines whether procurement flows through fragmented retail channels or consolidated specification platforms with diverging technical support requirements.
- Facility Managers:Professional procurement for multi-site commercial and institutional portfolios, driving centralized specification through sustainability-certified master agreements. This segment demands Environmental Product Declarations and embodied carbon data for Sydney and Tokyo commercial tower eligibility.
- Architects:Design-phase specification authority for premium residential and landmark commercial projects, particularly in Japan and South Korea where JIS standards and aesthetic preference for natural materials shape product selection.
- Contractors:Execution-phase procurement for residential and light commercial installation, with floating LVT and SPC systems compressing project timelines but creating skilled installer scarcity bottlenecks in Indonesia and Philippines markets.
- Homeowners:Retail-channel demand for replacement and renovation, price-sensitive and influenced by visual merchandising rather than technical certification.
Facility managers command the largest average order values. Contractors move the highest transaction volumes.
Installation Method:
Supply concentration in adhesive and substrate technologies creates diverging margin structures between traditional glue-dependent systems and mechanical fastening alternatives.
- Floating:Click-lock LVT and SPC systems eliminating adhesive curing cycles, specified at accelerated pace in Singapore and Hong Kong commercial retrofits. This method compresses maintenance contractor revenue pools tied to seam repair while requiring specialized substrate preparation expertise.
- Glue Down:Traditional adhesive-dependent installation for sheet vinyl and carpet, maintaining share in healthcare and cleanroom applications where seam integrity and static control are critical.
- Nail Down:Solid hardwood and engineered plank installation, dominant in Japan and Australia residential construction where subfloor conditions and building code requirements favor mechanical fastening.
- Loose Lay:Friction-fit systems for temporary or modular commercial spaces, gaining traction in Australia's flexible office fit-out market under National Waste Policy Action Plan circular economy procurement guidelines.
Floating methods lead in new specification. Glue down retains dominance in renovation and healthcare verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnamese tile exports to European markets accelerate as Binh Duong province absorbs manufacturing migration from China's Jiangsu cluster, reshaping procurement corridors across the Asia Pacific Flooring Market.
China
Jiangsu and Shandong provinces concentrate over 60% of regional laminate substrate capacity, drawing institutional procurement from facility managers upgrading healthcare footprints. GB 18580-2017 formaldehyde emission standards constrain cross-border product flows and elevate compliance costs for specification-grade materials. Kaolin deposits around Suzhou anchor ceramic tile feedstock access for large-scale manufacturers serving domestic commercial towers.
Japan
Aging-care facility expansion and commercial retrofit cycles sustain premium demand for engineered hardwood meeting JIS dimensional stability standards. METI building material energy efficiency mandates directly shape product eligibility for Tokyo commercial tower specification. Kansai region manufacturers supply Osaka and Nagoya institutional projects with thermal-performance-certified flooring systems.
India
Gujarat's mineral belt concentrates ceramic tile manufacturing capacity with captive raw material sourcing from the state's feldspar and quartz deposits. BIS certification requirements create compliance barriers that concentrate supply among large-scale domestic manufacturers. Facility managers in Maharashtra and Karnataka source specification-grade materials for hospital and education verticals through centralized procurement platforms.
Vietnam
EU-Vietnam FTA tariff advantages attract resilient flooring investment to Binh Duong province, creating export-oriented capacity for European commercial procurement. Labor cost differentials relative to China accelerate manufacturing migration for click-lock LVT and SPC systems. Ho Chi Minh City logistics infrastructure supports just-in-time delivery for Southeast Asian contractor networks facing monsoon-constrained construction windows.
Australia
NCC Section J thermal performance disclosure mandates require R-value and embodied carbon data for commercial flooring specification in Sydney and Melbourne towers. National Waste Policy Action Plan circular economy guidelines open procurement pathways for recyclable vinyl systems in public infrastructure. Victoria and New South Wales facility managers prioritize Environmental Product Declarations over uncertified alternatives in master service agreements.
Asia Pacific Flooring Market Competitive Landscape
Player mix skews toward integrated material specialists and regional ceramic tile manufacturers with captive raw material access. Market structure concentrates specification-grade supply among tier-1 manufacturers with multi-certification capabilities, while economy-grade segments fragment across price-competitive local fabricators. Strategic archetypes include vertically integrated resin-to-flooring producers, mineral-belt-anchored ceramic specialists, and sustainability-certified resilient systems providers. Dominant competitive moves encompass capacity migration to Vietnam and Indonesia, plus backward integration into PVC compounding and kaolin mining.
Among Asia-Pacific ceramic specialists, Kajaria Ceramics Limited and RAK Ceramics exemplify mineral-belt-anchored production models with captive sourcing advantages. DAIKEN Corporation occupies a position within the engineered hardwood tier serving Japan's JIS-certified institutional markets. Tarkett represents the sustainability-certified resilient systems archetype, with recycling technology aligning with Australia's circular economy procurement mandates. These three companies illustrate how geographic clustering and certification capabilities determine specification access across diverging national regulatory regimes.
| Leading Market Players |
|---|
| Mohawk Industries, Inc. |
| Tarkett |
| Kajaria Ceramics Limited |
| DAIKEN Corporation |
| Forbo Flooring Systems |
| TOLI Corporation |
| Shaw Industries Group, Inc. |
| CERA Sanitaryware Limited |
| RAK Ceramics |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between facility management platforms and tier-1 manufacturers lock in supply access and price visibility for specification-grade vinyl and ceramic tile across Southeast Asian commercial towers. These contracts compress spot-market exposure while embedding volume commitments that stabilize procurement costs for JLL and CBRE-managed portfolios in Bangkok and Jakarta.
Pricing Analysis
Prior-generation glue-down LVT systems trade at substantial discounts to click-lock SPC and next-generation antimicrobial-embedded surfaces. Three-tier pricing structure across premium, standard, and economy levels separates JIS-certified engineered hardwood from BIS-compliant ceramic tile and unbranded laminate imports. Pricing pressure stems from petrochemical input volatility tracking naphtha spreads, compressing margins for vinyl manufacturers serving price-sensitive residential contractors. Facility managers demonstrate lowest price sensitivity due to lifecycle cost modeling mandates, while homeowners in retail channels exhibit highest elasticity.
Supply Chain Analysis
Strategic stockpile preferences dominate institutional procurement for ceramic tile feedstock, with Gujarat's mineral belt and Jiangsu's kaolin deposits anchoring raw material security. Supply draws from China, India, and Vietnam, with PVC resin and plasticizer dependencies tethered to ethylene chain volatility. Single-source vulnerability concentrates in Jiangsu and Shandong laminate substrate capacity, exposing continuity to provincial environmental inspection cycles. Distribution runs through consolidated facility management platforms for commercial verticals and fragmented contractor networks for residential replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through JLL and CBRE-managed portfolio consolidation, fragmenting traditional contractor channel influence and elevating specification-grade manufacturers with multi-certification capabilities.
For Market Incumbents: Shield specification access by deepening captive raw material control over Gujarat feldspar deposits and Jiangsu kaolin reserves. Accelerate BIS-JIS-GB tri-certification investment to compress product launch timelines and defend against emerging Vietnamese manufacturers leveraging EU-Vietnam FTA tariff advantages. Capacity addition in Binh Duong province represents the priority defensive lever against supply chain disruption. For New Entrants and Emerging Players: Anchor in Australia's circular economy procurement pathways under National Waste Policy Action Plan guidelines, where recyclable vinyl systems face limited domestic competition. Target healthcare antimicrobial surfaces in Japan's aging-care facility expansion as the most penetrable premium segment. Lead with Environmental Product Declaration certification as the differentiated go-to-market angle for Sydney and Melbourne facility managers. For Investors and Strategic Acquirers: Mineral-belt-anchored ceramic specialists with captive sourcing advantages and established BIS compliance infrastructure represent the highest-conviction acquisition archetype. Long-term viability hinges on backward integration depth and multi-certification capability spanning the projection horizon. The signal to watch is provincial environmental inspection intensity in China's Jiangsu cluster crossing thresholds that trigger supply rationing and price volatility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PVC Compounding | Captive resin production insulates margin stability against naphtha price volatility for Southeast Asian vinyl manufacturers. |
| Multi-Certification Investment | Simultaneous BIS-JIS-GB compliance compresses cross-border product launch cycles by 8-14 months. |
| Manufacturing Migration to Binh Duong | EU-Vietnam FTA tariff advantages create export-oriented capacity for European commercial procurement. |
| Antimicrobial Surface Development | Silver-ion and copper-embedded technologies command premium positioning in Japan's aging-care facilities. |
| Circular Economy Certification | Post-consumer PVC recovery programs align with Australia's National Waste Policy Action Plan procurement mandates. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with commercial facility managers, ceramic tile procurement leads, resilient flooring plant engineers, and healthcare infrastructure planners; and secondary validation through customs trade databases, BIS certification registries, JIS standard documentation, and SEC filings from listed flooring manufacturers. Bottom-up volume triangulation across product type, application, and installation method segments converged with top-down macroeconomic anchoring.
Across the analysis window, the forecasting framework modeled demand trajectories by product type, application vertical, end-user archetype, and national regulatory cluster. CAGRs were derived from segment-level growth rate synthesis and cross-referenced against petrochemical input cost elasticity and construction cycle patterns. Industry-specific inputs included monsoon-constrained installation seasonality and green building certification adoption curves.
Decision-makers should treat outputs as directional under assumptions of continued green building code tightening and stable EU-Vietnam FTA tariff schedules; material deviation would warrant model refresh. Forecasts reflect these base conditions alongside acknowledged sensitivity to provincial environmental inspection intensity and naphtha-ethylene spread volatility. Revision becomes warranted when formaldehyde emission standard divergence crosses thresholds that fragment cross-border specification flows.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
United States Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
North America Laminate Flooring Market
Flooring, Carpets, and Rugs
United Kingdom Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Global Luxury Vinyl Tile Floor Covering Market
Flooring, Carpets, and Rugs
North America Vinyl Flooring Market
Flooring, Carpets, and Rugs
Global Floor Covering Market
Flooring, Carpets, and Rugs
US Flooring Market
Flooring, Carpets, and Rugs
North America Carpet Tile Market
Flooring, Carpets, and Rugs
Terrazzo Flooring Market
Flooring, Carpets, and Rugs
Wood and Laminate Flooring Market
Flooring, Carpets, and Rugs
Japan Floor Covering Market
Flooring, Carpets, and Rugs
US Terrazzo Market
Flooring, Carpets, and Rugs
Global Carpet Tile Market
Flooring, Carpets, and Rugs
Saudi Arabia Floor Covering Market
Flooring, Carpets, and Rugs
Bath Mats Market
Flooring, Carpets, and Rugs
Bath Rugs and Mats Market