
 US Vinyl Floor Covering Market | 2026-2036
US Vinyl Floor Covering Market Size, Share, and Industry Trends Forecast 2026-2036
US Vinyl Floor Covering Market Analytics
Multi-family housing developers is unwinding the historical dominance of single-family residential buyers in vinyl flooring procurement. Mohawk Industries leverages captive resin compounding and in-house extrusion to control input costs across its rigid core portfolio. Shaw Industries Group anchors its position through advanced digital printing lines that replicate hardwood aesthetics at scale. Tarkett North America competes via specialized healthcare-grade sheet vinyl with enhanced slip resistance and antimicrobial top layers.
Vinyl floor covering comprises polyvinyl chloride-based surfacing materials manufactured through calendering, extrusion, or coating processes, typically incorporating wear layers measured in mils for durability classification and printed design films for aesthetic replication. Luxury Vinyl Tile dominates value contribution due to premium positioning in commercial retrofits, while Vinyl Plank sustains the fastest volume expansion through click-lock floating installations in residential replacement cycles. Glue Down installation methods retain share in healthcare and hospitality segments where subfloor preparation standards and rolling load requirements demand permanent adhesion.
The EPA enforces TSCA Title VI formaldehyde emission limits on composite wood substrates bonded to vinyl flooring, while OSHA maintains workplace exposure thresholds during installation adhesive application. The FTC's Green Guides constrain environmental marketing claims around recyclability and bio-based content, forcing substantiation of sustainability positioning. Stakeholders must monitor evolving state-level extended producer responsibility proposals in California and New York that could impose end-of-life collection obligations on manufacturers.
Market Dynamics
Waterproof rigid core technology has reconfigured residential specification patterns, compressing traditional sheet vinyl volumes while elevating composite product margins across multi-family and single-family channels.
Growth Catalysts
- Multi-family housing acceleration:Developers in Texas and Florida specify rigid core products for moisture-prone units, displacing carpet in bathrooms and kitchens.
- TSCA Title VI compliance infrastructure:Manufacturers investing in certified substrate sourcing capture specification from builders facing heightened third-party verification requirements.
- Click-lock installation protocols:Floating floor systems reduce skilled labor dependency, shortening project timelines for residential replacement cycles.
Market Restraints
- Resin cost volatility:Polyvinyl chloride feedstock prices track ethylene and chlorine market swings, compressing margin predictability for extrusion-dependent producers.
- Substrate supply concentration:Composite wood core production clusters in Southeast Asia, exposing manufacturers to ocean freight rate fluctuations and port congestion.
- Ceramic tile substitution:Porcelain plank formats with enhanced realism threaten premium vinyl plank positioning in above-grade residential applications.
Strategic Opportunities
- Sun Belt state expansion:Elevated permitting activity in Arizona and Nevada creates white space for waterproof product lines targeting pool-adjacent installations.
- Healthcare-grade sheet vinyl:Antimicrobial top layer technology addresses infection control protocols in acute care facilities and senior living construction.
- Extended producer responsibility frameworks:California and New York legislative proposals could establish first-mover advantages for manufacturers with closed-loop collection infrastructure.
Industry Challenges
- Digital printing technician scarcity:Advanced rotogravure and inkjet line operation requires specialized skill sets concentrated among legacy wallpaper and packaging converters.
- Wear layer certification timelines:ASTM D4060 and D3884 testing protocols extend product development cycles for mil-thickness claims in commercial specification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Vinyl Floor Covering Market |
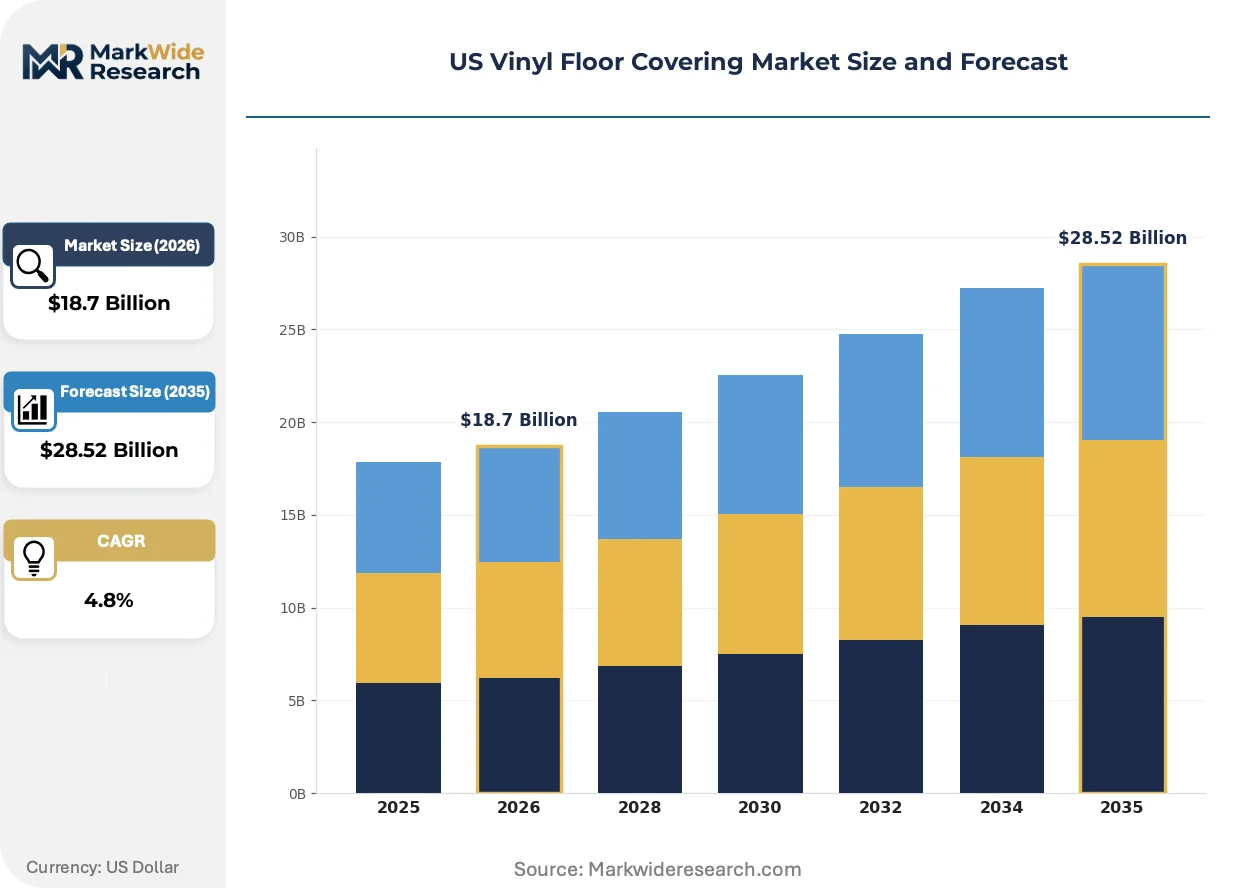
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Luxury Vinyl Tile, Vinyl Plank, Vinyl Sheet, Composite Vinyl End User: Residential, Commercial, Hospitality, Healthcare Installation Type: Glue Down, Floating, Click Lock, Loose Lay Thickness: Thin, Medium, Thick, Extra Thick |
| Companies Covered | Mohawk Industries Inc., Shaw Industries Group Inc., Armstrong Flooring, Mannington Mills Inc., Tarkett North America, AHF Products, Interface Inc., Gerflor USA, HMTX Industries, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Vinyl Floor Covering Market Evolving Landscape
Material science advances and regulatory stringency are compressing traditional product lifecycles while opening specification pathways previously blocked by performance limitations.
Stone-polymer composite cores are supplanting wood-plastic composites in below-grade applications, delivering dimensional stability against hydrostatic pressure. Basement finishing contractors in flood-prone Gulf Coast counties specify SPC exclusively, collapsing the addressable market for traditional glue-down sheet vinyl in residential retrofits.
EPA formaldehyde emission testing under TSCA Title VI has forced substrate supplier consolidation, as small mills lack capital for third-party certification infrastructure. Large-scale vinyl flooring manufacturers now integrate composite core production or lock in exclusive supply agreements, raising barriers for regional competitors.
Builder procurement teams consolidate flooring specifications across multi-state development portfolios, replacing distributor relationships with direct manufacturer contracts. National homebuilders in the Sun Belt bypass traditional two-step distribution, compressing channel margins while demanding volume-based pricing guarantees and dedicated inventory buffers.
US Vinyl Floor Covering Market Segmentation
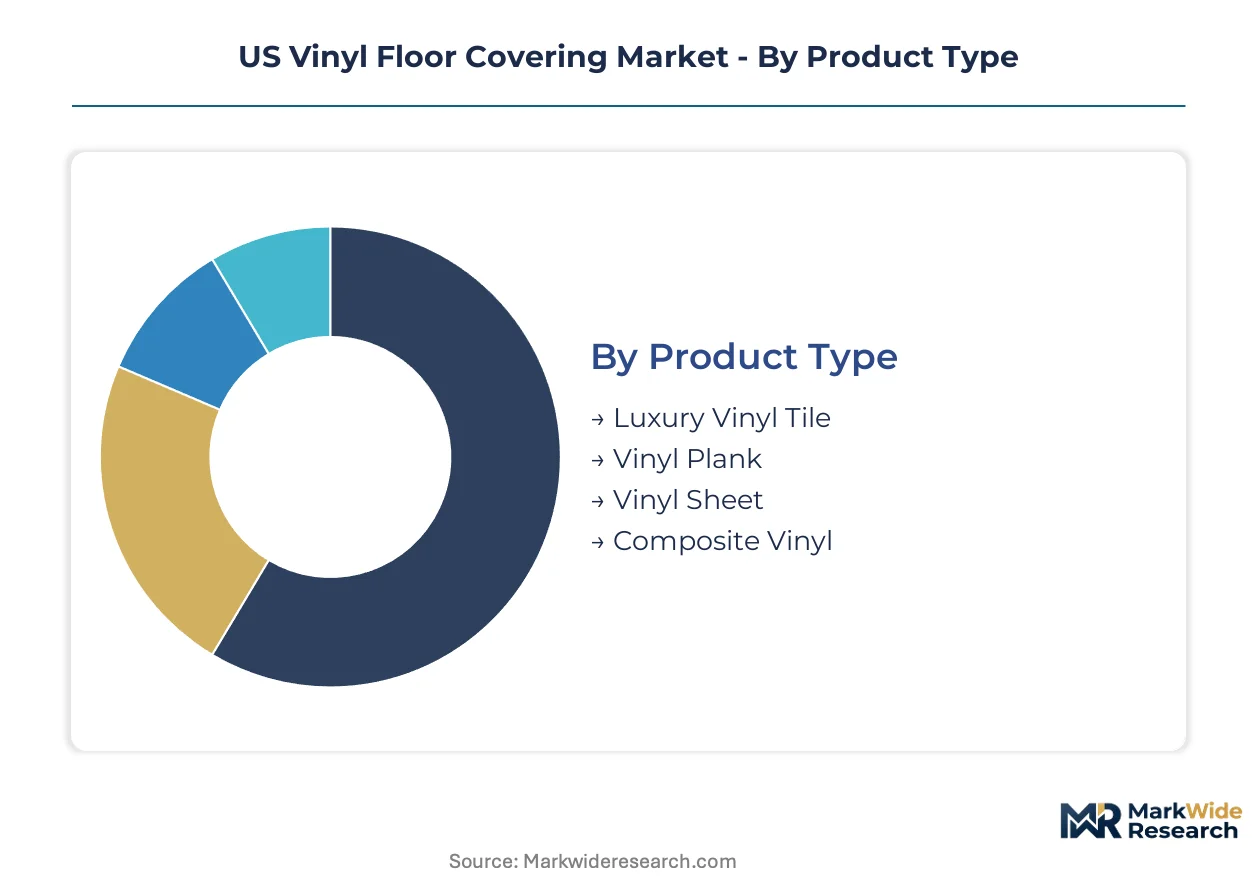
Vinyl flooring procurement channels fragment sharply by product format and end-use specification. Understanding which segments flow through distributor networks versus direct manufacturer contracts determines margin capture and inventory positioning strategies.
Product Type:
Channel mix varies dramatically across formats, with rigid core products increasingly bypassing traditional distribution while sheet vinyl maintains wholesale dependency.
- Luxury Vinyl Tile:Rectangular format with high-definition printed design layers and urethane wear surfaces measured in mils. Commercial retrofit projects in Texas and Florida healthcare facilities specify 20-mil wear layers for rolling load compliance, driving premium specification through direct manufacturer contracts.
- Vinyl Plank:Linear plank configuration replicating hardwood dimensions through rotogravure or digital printing. Click-lock floating installations dominate residential replacement cycles in Sun Belt states, compressing project timelines and reducing skilled labor requirements for multi-family developers.
- Vinyl Sheet:Continuous roll format manufactured through calendering processes with homogeneous or heterogeneous layer construction. Healthcare and hospitality segments in Florida retain specification for seamless installations meeting infection control protocols.
- Composite Vinyl:Multi-layer construction incorporating stone-polymer or wood-polymer cores for dimensional stability. Below-grade residential applications in flood-prone Gulf Coast counties specify SPC exclusively for hydrostatic pressure resistance.
Luxury Vinyl Tile dominates installed base. Vinyl Plank is where expansion concentrates.
End User:
Cost tier stratification separates specification-grade products from commodity residential offerings, with compliance requirements driving margin differentiation.
- Residential:Single-family and multi-family housing replacement cycles, with waterproof rigid core products displacing carpet in moisture-prone areas. Sun Belt permitting activity in Texas and Arizona elevates volume throughput.
- Commercial:Office, retail, and institutional applications requiring ASTM D4060 wear layer certification. Rolling load specifications and third-party verification requirements compress eligible supplier pools.
- Hospitality:Hotel and resort installations demanding acoustic underlayment integration and rapid installation protocols. Casino and entertainment properties in Nevada specify high-traffic wear surfaces.
- Healthcare:Acute care facilities and senior living construction requiring antimicrobial top layers and slip-resistant surfaces. EPA TSCA Title VI substrate compliance is mandatory for Medicare-funded projects.
Residential channels move the highest unit volumes. Healthcare specification commands the steepest price premiums.
Installation Type:
Volume concentration tracks labor availability, with floating systems gaining share where skilled installer scarcity constrains project timelines.
- Glue Down:Permanent adhesive application requiring subfloor preparation and cure time. Healthcare and hospitality segments retain this method for rolling load requirements and seamless sheet vinyl installation.
- Floating:Interlocking systems resting on underlayment without subfloor adhesion. Residential replacement cycles in multi-family housing accelerate project completion.
- Click Lock:Precision-milled edge profile enabling tool-free assembly. DIY residential renovation and contractor-installed multi-family projects in Florida and Texas standardize on this protocol.
- Loose Lay:Friction and weight-based installation without adhesive or locking mechanisms. Temporary commercial applications and rapid-turn hospitality renovations utilize this method.
Click Lock systems dominate new residential construction. Glue Down methods retain institutional specification.
Thickness:
Margin structure correlates directly with mil specification, as wear layer thickness determines commercial warranty eligibility and replacement cycle longevity.
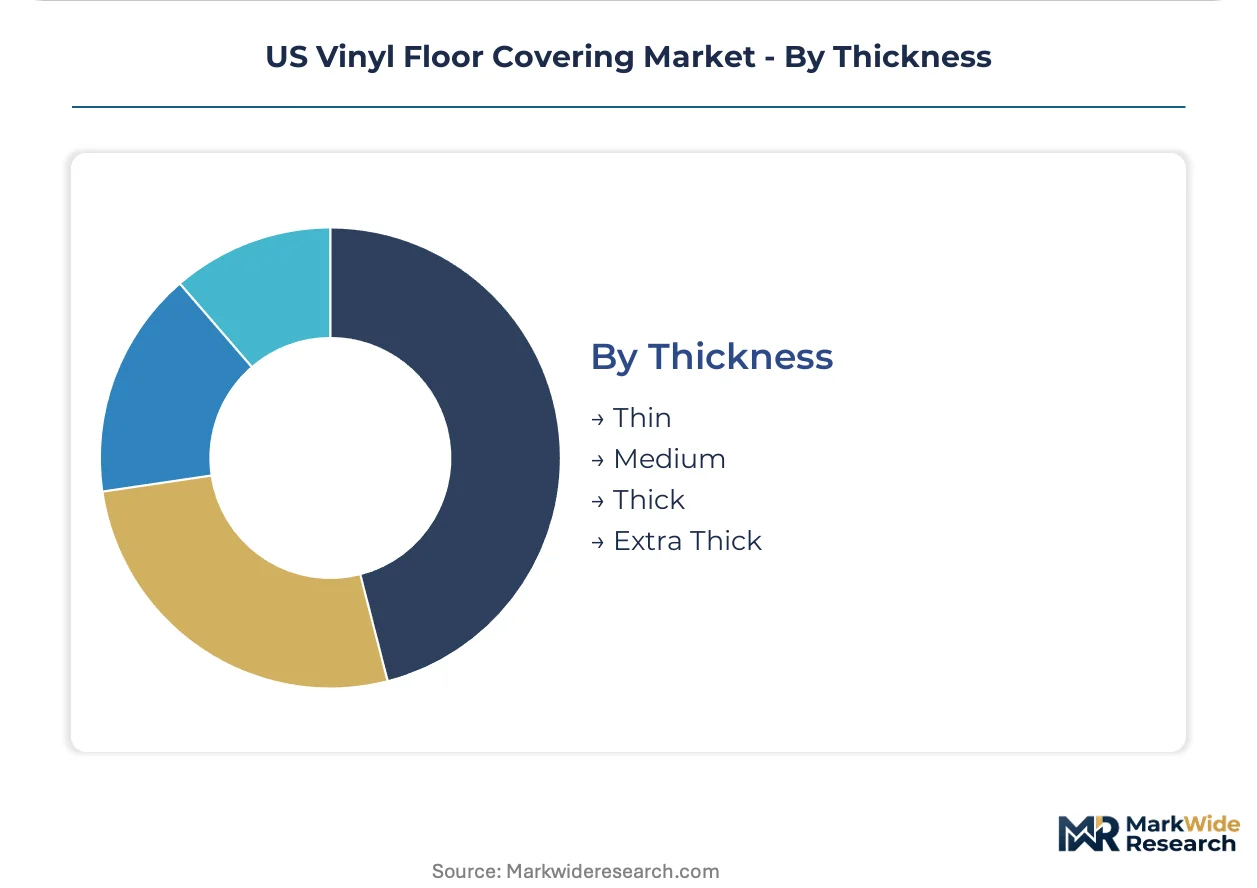
- Thin:Sub-4mm total construction with minimal wear layer protection. Budget residential applications and short-term rental property turnover.
- Medium:4-6mm total thickness with 12-mil wear layers. Standard multi-family specification balancing cost and durability.
- Thick:6-8mm construction incorporating SPC or WPC cores. Premium residential and light commercial applications requiring enhanced acoustic performance.
- Extra Thick:Exceeding 8mm with 20-mil+ wear surfaces. Healthcare and hospitality specification demanding rolling load compliance and extended warranty coverage.
Medium thickness captures the broadest addressable market. Extra Thick products command specification in premium commercial channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Houston anchors vinyl flooring distribution across the Gulf Coast, channeling resin feedstocks and finished goods into Texas, Louisiana, and Florida markets where multi-family construction permits remain elevated.
Texas
Metro Dallas and Houston multi-family developers specify rigid core waterproof products for moisture-prone units, displacing carpet in bathrooms and kitchens. The Texas Commission on Environmental Quality enforces volatile organic compound limits on installation adhesives in non-attainment counties. Manufacturing concentration clusters in the Dallas-Fort Worth metroplex where extrusion facilities serve Sun Belt distribution networks.
Florida
Orlando and Tampa senior living construction drives healthcare-grade sheet vinyl demand for infection control compliance. The Florida Building Code mandates moisture barrier specifications in below-grade installations that favor stone-polymer composite cores. Miami-Dade County contractors source through Port Everglades logistics hubs serving Caribbean hospitality renovation projects.
California
Los Angeles and San Francisco Bay Area commercial retrofits prioritize low-VOC products meeting California Air Resources Board emission standards. The state's proposed extended producer responsibility legislation threatens end-of-life collection obligations on manufacturers. Central Valley distribution centers buffer inventory for Pacific Coast multi-family pipelines.
Arizona
Phoenix and Tucson new construction permits elevate click-lock floating installation volumes for residential replacement cycles. The Arizona Department of Environmental Quality aligns with federal TSCA Title VI substrate certification requirements. Pool-adjacent installations in Scottsdale and Paradise Valley specify enhanced waterproof rigid core lines exclusively.
Nevada
Las Vegas hospitality renovation cycles demand rapid-install loose lay and click-lock systems for casino floor turnovers. The Nevada Division of Environmental Protection oversees workplace exposure thresholds during adhesive application in commercial settings. Reno-Sparks distribution nodes serve northern California and Pacific Northwest spillover demand.
US Vinyl Floor Covering Market Competitive Landscape
Listed leaders compete with private specialists across capital access and operational flexibility dimensions. The vendor base consolidates around integrated resin compounders and specialized sheet vinyl fabricators. Three archetypes dominate: captive resin producers controlling input costs, digital printing specialists replicating hardwood aesthetics, and healthcare-grade specification houses. Capacity expansion and direct-to-builder contracting constitute the dominant competitive moves.
Within the integrated manufacturing tier, Mohawk Industries Inc. and Shaw Industries Group Inc. exemplify scale-driven positions, while Tarkett North America anchors the healthcare-specialist vector. These three entities represent contrasting strategic postures—resin integration, printing technology scale, and antimicrobial surface engineering—without implying specific market share or revenue figures.
| Leading Market Players |
|---|
| Mohawk Industries Inc. |
| Shaw Industries Group Inc. |
| Armstrong Flooring |
| Mannington Mills Inc. |
| Tarkett North America |
| AHF Products |
| Interface Inc. |
| Gerflor USA |
| HMTX Industries |
| Others |
Value Network & Pricing Analysis
EPA TSCA Title VI certification gates both substrate supplier qualification and price tier differentiation, forcing manufacturers to absorb third-party testing costs or forfeit specification in Medicare-funded healthcare projects. Builders facing heightened verification requirements now pay measurable premiums for certified supply chains, compressing margins for non-compliant regional competitors while rewarding integrated producers with pricing power in institutional channels.
Pricing Analysis
Volume-discount tiering structures separate national homebuilders procuring rigid core products through direct manufacturer contracts from regional distributors serving fragmented residential replacement cycles. Pricing stratifies across premium, standard, and economy tiers based on wear layer mil specification and ASTM D4060 certification status. Cost compression in the economy tier is intensifying because resin feedstock volatility tracks ethylene and chlorine market swings. Multi-family developers exhibit highest price sensitivity, while acute care facilities purchasing healthcare-grade sheet vinyl demonstrate minimal elasticity due to infection control mandates.
Supply Chain Analysis
Southeast Asia anchors composite wood core production for stone-polymer and wood-polymer substrates, while domestic extrusion facilities cluster in Texas and the Dallas-Fort Worth metroplex. Polyvinyl chloride resin feedstock draws from Gulf Coast petrochemical complexes, with urethane wear layer chemicals sourced from specialized coatings manufacturers. Single-source vulnerability concentrates in ocean freight lanes connecting Vietnamese substrate mills to Port of Houston distribution nodes. Distribution runs through direct-to-builder contracting for national multi-family portfolios, bypassing traditional two-step wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized digital printing technician pools remain critically thin, constraining capacity expansion for rotogravure and inkjet line operators seeking to replicate hardwood aesthetics at scale. This capability scarcity elevates acquisition premiums for technical talent and equipment access.
For Market Incumbents: Shield specification-grade positioning by locking in exclusive substrate supply agreements with TSCA Title VI-certified mills before regulatory consolidation completes. Prioritize captive resin compounding capacity in the Dallas-Fort Worth corridor to offset ethylene cost volatility threatening margin predictability in extrusion-dependent product lines. For New Entrants and Emerging Players: Lead with below-grade waterproof rigid core systems targeting flood-prone Gulf Coast counties where stone-polymer composite specifications have collapsed traditional glue-down sheet vinyl demand. Arizona and Nevada pool-adjacent installations present the most penetrable white space, accessible through contractor-direct sampling programs bypassing established distributor relationships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed flooring specialists lacking integrated substrate production or certified supply chain infrastructure. Long-term viability hinges on regulatory compliance moats deepening through EPA enforcement expansion and state-level extended producer responsibility adoption. Monitor California and New York legislative committee calendars for collection obligation inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Mohawk Industries controls input costs across rigid core portfolios through captive PVC production. |
| Healthcare-Grade Certification Investment | Tarkett North America captures Medicare-funded project specification via antimicrobial surface engineering. |
| Direct-to-Builder Contracting Expansion | National homebuilders in Texas and Florida bypass distributors, demanding volume pricing and inventory buffers. |
| Digital Printing Line Acquisition | Shaw Industries replicates hardwood aesthetics at scale through advanced rotogravure capacity. |
| Extended Producer Responsibility Infrastructure | First-mover collection systems in California and New York preempt legislative collection mandates. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with vinyl flooring procurement managers, multi-family development executives, healthcare facility planners, and distributor inventory specialists; and secondary validation through EPA TSCA Title VI certification databases, SEC 10-K filings from listed manufacturers, Port of Houston customs records, and Texas and Florida construction permitting data. Bottom-up volume modeling across product formats triangulated against top-down value estimates from channel margin analysis.
Across the analysis window, the forecasting framework modeled demand trajectories by product type, installation method, end-use segment, and state-level permitting activity. CAGRs were derived from regression analysis of historical construction cycle correlations and forward projection of multi-family housing starts. Key inputs included resin feedstock price indices, ocean freight rate volatility assumptions, and regulatory enforcement intensity scoring for formaldehyde emission standards.
Forecasts assume regulatory continuity in EPA TSCA Title VI and OSHA workplace exposure regimes; material policy shifts including California extended producer responsibility enactment would require re-modeling. Recalibration cycles align with material shifts in construction permitting data, resin cost volatility spikes, and substrate supply disruption events.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
Wood Flooring Market
Flooring, Carpets, and Rugs
Turkey Floor Covering Market
Flooring, Carpets, and Rugs
Wooden Floor Market
Flooring, Carpets, and Rugs
Quarter Sawn Flooring Market
Flooring, Carpets, and Rugs
Terrazzo Flooring Market
Flooring, Carpets, and Rugs
United Arab Emirates Floor Covering Market
Flooring, Carpets, and Rugs
Carpet Floor Mats Market
Flooring, Carpets, and Rugs
Netherlands Floor Covering Market
Flooring, Carpets, and Rugs
India Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Saudi Arabia Floor Covering Market
Flooring, Carpets, and Rugs
Global Flooring Market
Flooring, Carpets, and Rugs
Brazil Floor Covering Market
Flooring, Carpets, and Rugs
Bath Mats Market
Flooring, Carpets, and Rugs
North America Vinyl Flooring Market
Flooring, Carpets, and Rugs
GCC Flooring Market
Flooring, Carpets, and Rugs
Saudi Arabia Vinyl Flooring Market