
 Global Soft Covering Flooring Market | 2026-2036
Global Soft Covering Flooring Market Size, Share, and Industry Trends Forecast 2026-2036
Global Soft Covering Flooring Market Foresight
The EU Green Deal is pivoting commercial flooring procurement toward low-carbon materials across European Union member states. Mohawk Industries leverages recycled nylon feedstocks to anchor its position in contract carpet tiles. Shaw Industries Group competes through Cradle to Cradle certification across its commercial roll carpet lines. Interface specializes in carbon-neutral carpet tile systems for corporate office fit-outs.
Soft covering flooring comprises textile-based floor finishes manufactured through tufting, weaving, or needlepunch processes using pile heights typically ranging from 3mm to 15mm, serving primarily to provide thermal insulation, acoustic dampening, and aesthetic surface finishing in built environments. Nylon dominates material selection for high-traffic commercial applications due to superior resilience and stain resistance, while carpet tiles represent the fastest-growing product format as facility managers prioritize modular replacement over full-floor renovation. Roll carpets retain margin concentration in residential complexes where broadloom installation remains cost-competitive for large surface areas.
The US EPA oversees VOC emissions standards through FloorScore and GREENGUARD certification pathways, while REACH regulates phthalate and heavy metal content in European-manufactured products, and China's GB standards govern formaldehyde release limits for indoor flooring materials. These frameworks collectively raise compliance costs for polypropylene and polyester suppliers while creating preferential market access for wool and bio-based alternatives. Stakeholders must monitor evolving extended producer responsibility schemes that will reshape collection and recycling infrastructure requirements.
Market Dynamics
The EU Green Deal's embodied carbon mandates are compressing demand toward bio-based and recycled-content alternatives, while China's tier-one commercial construction boom concentrates procurement power in facility management consortia across Beijing, Shanghai, and Shenzhen.
Growth Catalysts
- REACH compliance premiums:European manufacturers reformulating phthalate-free backings capture preferential access to public sector tenders in Germany and France.
- Acoustic specification in hospitality:Dubai and Singapore hotel developers now mandate carpet installations for noise attenuation in guest corridors and ballrooms.
- Nylon resilience engineering:Advanced polymer stabilization extends replacement cycles in high-traffic airport terminals and healthcare corridors.
Market Restraints
- Petrochemical input volatility:Caprolactam and adipic acid price swings compress margin predictability for synthetic fiber producers.
- Collection infrastructure gaps:Extended producer responsibility schemes in the EU lack unified sorting facilities, raising compliance costs for carpet tile suppliers.
- Rigid LVT substitution:Luxury vinyl tile manufacturers target the same commercial fit-out budgets with lower installed cost per square meter.
Strategic Opportunities
- India's commercial real estate pipeline:Bengaluru and Mumbai office stock expansion creates first-mover advantage for carpet tile specification.
- Digital specification platforms:BIM-integrated product libraries enable architects to embed carbon data directly into design workflows.
- EU taxonomy alignment:Green bond financing for renovation projects prioritizes materials with verified environmental product declarations.
Industry Challenges
- Installer certification bottlenecks:Modular carpet tile adhesion and seam welding require skilled labor pools that remain thin in secondary Chinese cities.
- Cross-border recycling complexity:Differing national interpretations of waste shipment regulations fragment circular economy implementation across EU member states.
- Legacy specification inertia:Roll carpet dominates residential developer procurement manuals, slowing modular format penetration in multi-family housing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Soft Covering Flooring Market |
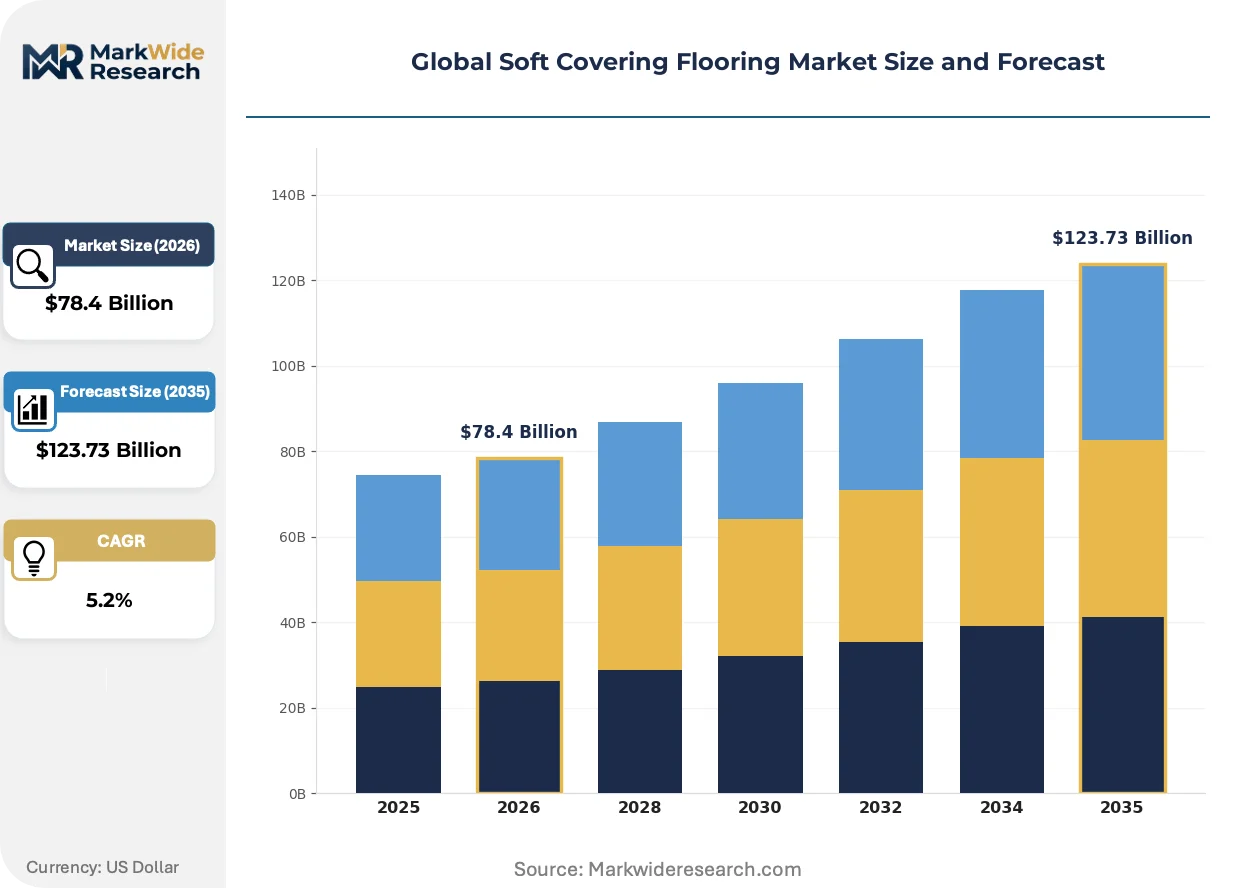
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $123.73 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
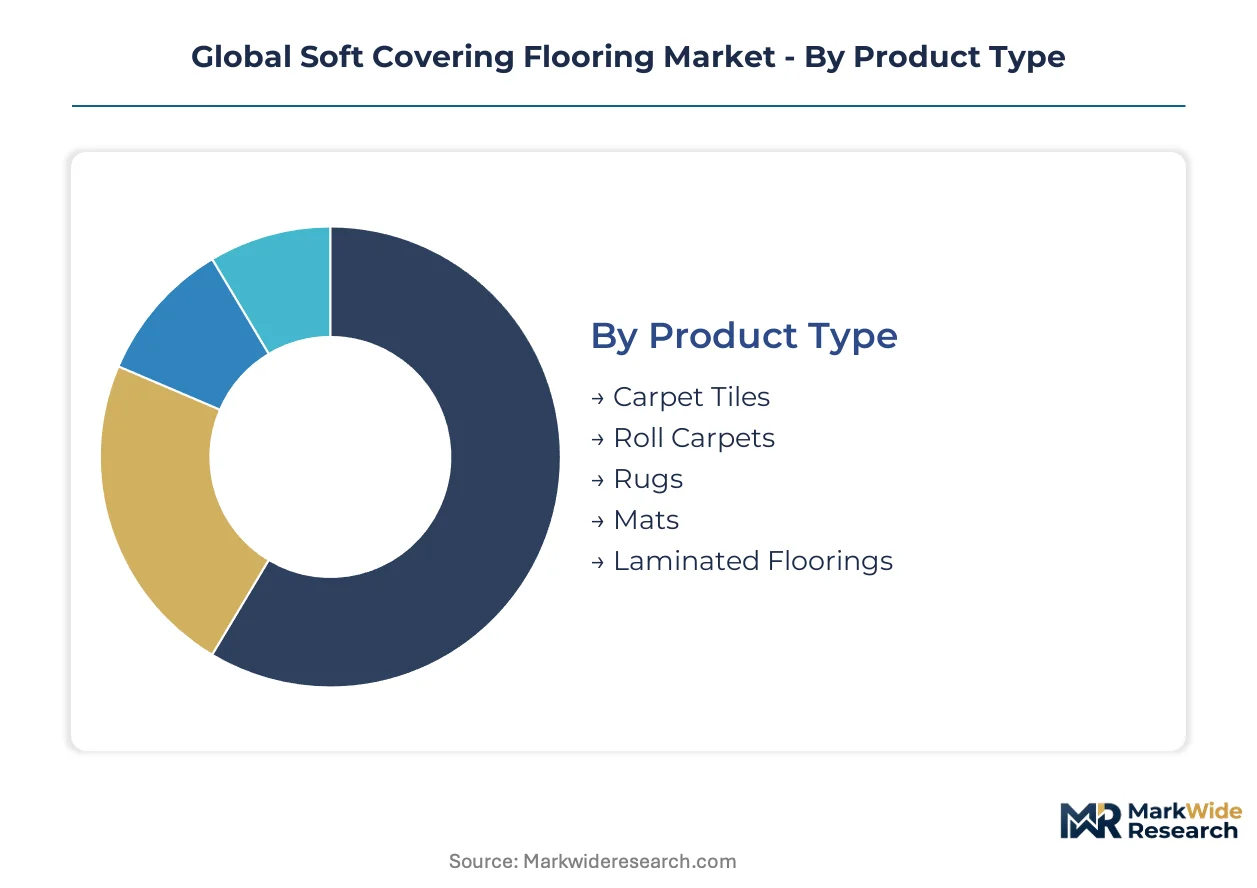
| Segmentation | Product Type: Carpet Tiles, Roll Carpets, Rugs, Mats, Laminated Floorings Application: Hospitality Venues, Educational Institutions, Corporate Offices, Residential Complexes, Entertainment Centers Material: Nylon, Polypropylene, Wool, Polyester, Acrylic Distribution Channel: Specialty Retailers, Home Improvement Centers, Online Marketplaces, Direct Sales, Wholesale Distributors |
| Companies Covered | Mohawk Industries Inc., Shaw Industries Group Inc., Interface Inc., Tarkett, Beaulieu International Group, Milliken & Company, Forbo Holding AG, Gerflor, Engineered Floors LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Soft Covering Flooring Market Shifts & Advancements
Digital tools and bio-based material science are compressing traditional specification cycles while regulatory carbon accounting forces transparency through the value chain.
Recycled nylon feedstock processing is decentralizing supply chain control away from virgin polymer producers. Commercial facility managers in Northern Europe now specify closed-loop carpet tile take-back programs as standard contract terms. This shift compresses virgin material demand while elevating regional recycling operators to tier-one supplier status.
REACH substance restriction updates are tightening heavy metal thresholds in carpet dyes and flame retardants. German and Dutch manufacturers face reformulation deadlines that favor water-based latex backing systems. The contract segment responds by accelerating third-party Cradle to Cradle certification to preempt procurement exclusion.
Building information modeling integration is compressing traditional specification timelines for flooring selection. Architects in Singapore and Sydney now embed carbon performance data directly into digital material libraries, displacing static product catalogs. This behavioral shift concentrates influence among sustainability consultants who validate environmental product declarations.
Global Soft Covering Flooring Market Segmentation
Soft covering flooring segmentation reveals how material chemistry, installation format, and procurement channel each concentrate margin in distinct supply chain nodes. Facility managers, architects, and residential developers navigate these categories through divergent specification workflows and compliance requirements.
Product Type:
Manufacturing assets for modular formats concentrate in Belgium, the Netherlands, and Georgia, while broadloom production clusters in lower-cost textile regions.
- Carpet Tiles:Modular 50cm x 50cm units with bitumen or PVC backing enable selective replacement in high-traffic zones. Demand concentrates in corporate office fit-outs across London, Frankfurt, and Singapore where facility managers prioritize reduced downtime during renovation cycles.
- Roll Carpets:Continuous broadloom manufactured in 3.66m or 4m widths requires specialized seaming equipment for installation. Residential developers in US suburban markets specify roll formats for cost efficiency across large surface areas in multi-family housing.
- Rugs:Finished textile floor coverings without permanent attachment systems serve decorative and acoustic functions in hospitality lobbies.
- Mats:Entryway and anti-fatigue products with rubber or vinyl backing target commercial building maintenance contracts.
- Laminated Floorings:Multi-layer synthetic products with textile surface finishes bridge hard and soft flooring categories for budget-conscious retail environments.
Roll carpets absorb the bulk of installed capacity; carpet tiles are expanding most quickly.
Application:
End-use specifications diverge sharply between performance-driven commercial segments and cost-sensitive residential procurement.
- Hospitality Venues:Hotels and resorts in Dubai and Singapore mandate carpet installations for acoustic attenuation in guest corridors, ballrooms, and conference facilities. Procurement teams prioritize stain-resistant nylon pile with extended replacement warranties.
- Corporate Offices:Workplace fit-outs in China's tier-one cities specify modular carpet tiles with carbon-neutral certification to satisfy ESG reporting requirements.
- Educational Institutions:Schools and universities balance durability against budget constraints through polypropylene-heavy specifications in high-traffic circulation areas.
- Residential Complexes:Multi-family housing developers in India and Brazil source broadloom polyester for cost-competitive unit turnover.
- Entertainment Centers:Cinemas, casinos, and gaming venues require specialized flame-retardant treatments meeting local building codes.
Corporate offices absorb the bulk of specification volume; hospitality venues are climbing the fastest.
Material:
Polymer feedstock availability and REACH compliance costs reshape competitive positioning across fiber categories.
- Nylon:Polyamide 6 and 6,6 polymers deliver superior resilience and stain resistance through solution-dyed constructions. Airport terminals and healthcare corridors in Germany and Japan specify nylon for extended replacement cycles under intensive foot traffic.
- Polypropylene:Olefin fibers offer moisture resistance and chemical stability at lower price points. Educational and institutional buyers in cost-sensitive markets favor polypropylene for utility-grade installations.
- Wool:Natural protein fibers with inherent flame resistance and acoustic properties serve premium residential and heritage building restoration projects.
- Polyester:PET fibers from recycled bottle feedstocks attract sustainability-focused procurement in Northern European markets.
- Acrylic:Synthetic wool substitutes with colorfast properties occupy niche decorative applications.
Nylon absorbs the bulk of commercial-grade capacity; wool is gaining share fastest in premium segments.
Distribution Channel:
Channel power concentrates where specification influence and logistics infrastructure overlap.
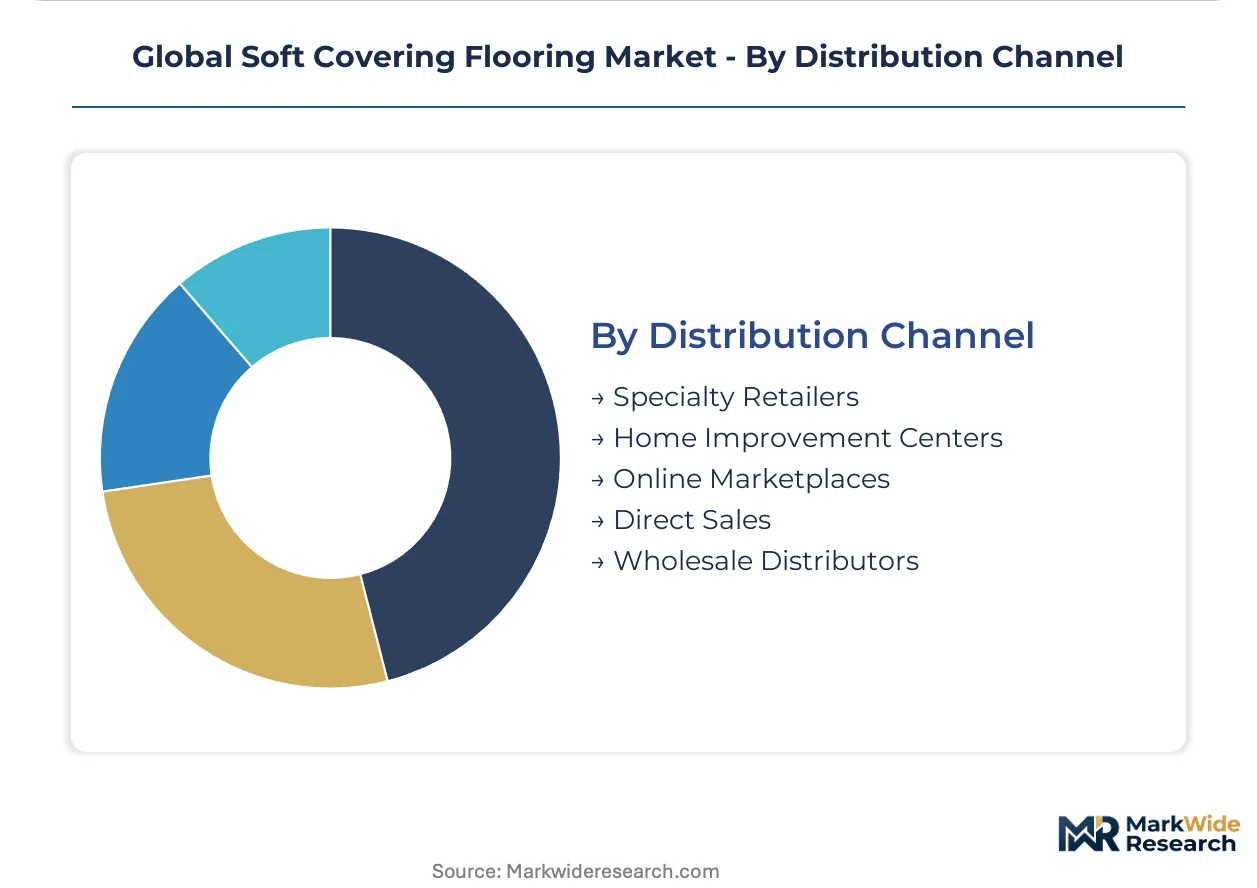
- Specialty Retailers:Independent flooring showrooms with trained sales staff dominate residential replacement purchases in suburban US and Australian markets.
- Home Improvement Centers:Big-box retailers capture volume residential sales through private label programs and installation service bundling.
- Online Marketplaces:Digital platforms enable direct-to-consumer rug and mat sales with visualizer tools for pattern selection.
- Direct Sales:Manufacturer specification teams engage architects and facility managers for large commercial contracts.
- Wholesale Distributors:Regional inventory holders serve contractor networks with just-in-time delivery for renovation timelines.
Specialty retailers absorb the bulk of residential transaction volume; direct sales are expanding most quickly in commercial specification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai's hospitality construction pipeline anchors Middle Eastern specification volume, while China's tier-one commercial real estate boom concentrates procurement influence in facility management consortia across Beijing, Shanghai, and Shenzhen.
United States
Corporate office renovation cycles in Manhattan and Chicago drive carpet tile specification for ESG-compliant fit-outs. The EPA's FloorScore certification governs VOC emissions for federal building procurement. Georgia's carpet manufacturing corridor supplies broadloom and modular formats to domestic and export markets.
Germany
REACH substance restrictions accelerate reformulation of phthalate-free backing systems for public sector tenders. The EU Green Deal's embodied carbon rules compress demand toward recycled-content alternatives. The Rhine-Ruhr industrial region hosts specialized recycling operators processing post-consumer nylon feedstocks.
China
Tier-one city commercial construction concentrates procurement power in Beijing, Shanghai, and Shenzhen facility management consortia. GB standards govern formaldehyde release limits for indoor flooring materials. The Yangtze River Delta manufacturing base supplies both domestic installation and export markets.
India
Bengaluru and Mumbai office stock expansion creates specification opportunities for modular carpet tile systems. The BIS certification framework establishes quality benchmarks for imported and domestic products. Maharashtra's industrial corridor attracts carpet tile manufacturing investment to serve South Asian markets.
Singapore
Hotel developers mandate carpet installations for acoustic attenuation in guest corridors and ballrooms. Building information modeling integration compresses specification timelines for sustainable material selection. The city-state's position as a regional headquarters hub concentrates procurement decision-making for Southeast Asian rollouts.
Global Soft Covering Flooring Market Competitive Landscape
The competitive structure tilts toward diversified material conglomerates with captive polymer supply. Consolidation among nylon fiber producers and backing system suppliers has compressed the vendor base into three tiers: integrated polymer-to-flooring conglomerates, specialized carpet tile system designers, and regional broadloom fabricators. Dominant competitive moves include backward integration into recycled feedstock processing and strategic partnerships with facility management consortia for take-back program deployment.
Within the integrated conglomerate tier, Mohawk Industries Inc. and Shaw Industries Group Inc. exemplify scale-driven positioning through captive nylon supply chains. Interface Inc. occupies a distinct position as a modular system specialist with carbon-neutral certification anchoring corporate office specification. These three companies collectively represent the strategic archetypes shaping procurement influence: polymer-integrated volume production, sustainability-certified modular systems, and regional broadloom cost leadership.
| Leading Market Players |
|---|
| Mohawk Industries Inc. |
| Shaw Industries Group Inc. |
| Interface Inc. |
| Tarkett |
| Beaulieu International Group |
| Milliken & Company |
| Forbo Holding AG |
| Gerflor |
| Engineered Floors LLC |
| Others |
Supply & Pricing Matrix
Facility management consortia in China's tier-one cities now mandate carbon-neutral certification as standard contract terms, forcing suppliers to absorb recycled-content premiums while defending price positions against rigid LVT alternatives. This procurement shift compresses margin pools for virgin nylon producers while elevating regional recycling operators to tier-one supplier status.
Pricing Analysis
Replacement-cycle guarantees anchor value-based pricing in commercial carpet tile contracts, with facility managers paying premiums for extended wear warranties in airport terminals and healthcare corridors. Three-tier pricing structure across premium, standard, and economy levels separates Cradle to Cradle-certified systems from REACH-compliant mid-tier offerings and utility-grade polypropylene alternatives. Cost compression in standard-tier broadloom intensifies because polyester feedstock volatility undercuts fixed-price residential contracts. Educational institutions exhibit highest price sensitivity due to budget caps, while hospitality developers in Dubai and Singapore show lowest sensitivity given acoustic specification mandates.
Supply Chain Analysis
EU Green Deal domestic-content rules for embodied carbon accounting are reshaping sourcing patterns, with German and Dutch manufacturers now prioritizing regional recycled nylon feedstock over Asian virgin polymer imports. Manufacturing assets concentrate in Belgium, the Netherlands, and Georgia, drawing from caprolactam and adipic acid inputs sourced from petrochemical complexes in Germany and the US. Single-source vulnerability runs through China's Yangtze River Delta for backing system components. Distribution runs through wholesale distributor networks serving contractor networks with just-in-time delivery for renovation timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Recycled-content processing capacity bottlenecks in Northern Europe prop pricing premiums for closed-loop carpet tile systems, constraining supply expansion despite procurement demand from ESG-mandated corporate fit-outs.
For Market Incumbents: Cement backward integration into post-consumer nylon recycling infrastructure to defend margin pools against virgin polymer price volatility. Lock in multi-year take-back program partnerships with facility management consortia in London and Frankfurt before collection infrastructure gaps close. Prioritize Cradle to Cradle certification investment to preempt REACH reformulation exclusion from public sector tenders. For New Entrants and Emerging Players: The mid-tier price-point gap between premium carbon-neutral systems and economy polyester broadloom offers white-space entry for REACH-compliant recycled-content alternatives. India's Bengaluru and Mumbai commercial real estate pipeline represents the most penetrable geography given thin installer certification pools slowing incumbent expansion. Pursue digital specification platform partnerships to embed carbon data directly into architect BIM workflows. For Investors and Strategic Acquirers: Re-rating potential sits with specialized recycling operators given EU extended producer responsibility schemes elevating their tier-one supplier status. Five-to-ten year viability favors assets with verified environmental product declarations aligned to EU taxonomy green bond financing. Watch for inflection when unified sorting facility investments in Germany and France resolve collection infrastructure fragmentation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Feedstock | Captures margin from post-consumer nylon processing in Rhine-Ruhr industrial clusters. |
| Cradle to Cradle Certification Investment | Preempts procurement exclusion from German and French public sector tenders under REACH updates. |
| Digital Specification Platform Partnership | Embeds carbon performance data into Singapore and Sydney architect BIM workflows. |
| Take-Back Program Deployment | Locks in facility management consortia contracts across London, Frankfurt, and Singapore. |
| Regional Manufacturing Footprint Expansion | Positions capacity in Maharashtra's industrial corridor to serve Bengaluru and Mumbai demand. |
Research Methodology
Trade association filings, customs databases, and SEC 10-K disclosures formed the secondary backbone, cross-referenced with primary interviews involving carpet manufacturing plant managers, facility management procurement leads, distribution channel partners, and technical R&D directors specializing in polymer stabilization. Bottom-up installation volume estimates triangulated against top-down construction spending data across commercial real estate segments.
Historical trendline analysis tracked replacement cycle patterns and specification format shifts across the projection horizon. The analytical framework modeled segmentation across product type, material chemistry, installation format, end-use application, and regional procurement cluster. CAGRs derived from elasticity-adjusted demand curves incorporating EU Green Deal compliance cost pass-through and China's tier-one commercial construction pipeline. Industry-specific inputs included REACH substance restriction timelines and BIM adoption rates in architect specification workflows.
Inputs from ECHA regulatory filings and China GB standard updates were available through the study window; gaps in post-consumer collection volume data introduce uncertainty bands around circular economy penetration forecasts. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Luxury Vinyl Tile (LVT) Flooring Market
Flooring, Carpets, and Rugs
Fiberglass Flooring Market
Flooring, Carpets, and Rugs
Flooring for Tile and Stone Market
Flooring, Carpets, and Rugs
Bamboo Flooring Market
Flooring, Carpets, and Rugs
Turkey Carpet and Rugs Market
Flooring, Carpets, and Rugs
India Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
United Kingdom Floor Covering Market
Flooring, Carpets, and Rugs
Quarter Sawn Flooring Market
Flooring, Carpets, and Rugs
Global Flooring Market
Flooring, Carpets, and Rugs
India Vinyl Flooring Market
Flooring, Carpets, and Rugs
China Engineered Wood Flooring Market
Flooring, Carpets, and Rugs
Global Luxury Vinyl Tile Floor Covering Market
Flooring, Carpets, and Rugs
Decorative Rugs Market
Flooring, Carpets, and Rugs
Europe Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Hard Surface Flooring Market