
 China Luxury Vinyl Tile (LVT) Market | 2026-2036
China Luxury Vinyl Tile (LVT) Market Size, Share, and Industry Trends Forecast 2026-2036
China Luxury Vinyl Tile (LVT) Market Outlook
Guangdong Province is reconfiguring China's LVT production map through expanded extrusion capacity and resin compounding investments. Jiangsu Taide Decoration Materials Co Ltd leverages integrated PVC sourcing from nearby petrochemical corridors to sustain cost advantages in glue-down and rigid core lines. CFL Flooring anchors export competitiveness through European and North American distribution partnerships. Zhejiang Walrus New Material differentiates via embossed surface finish capabilities that serve premium hospitality specifications.
China Luxury Vinyl Tile comprises multi-layer synthetic flooring systems built from PVC wear layers, printed decorative films, and mineral-composite or foam cores, typically installed with thicknesses from 2mm to 5mm depending on traffic load and subfloor condition. The material replicates wood or stone aesthetics while delivering water resistance, acoustic dampening, and reduced installation labor versus traditional hard surfaces. Rigid core formats now lead value growth due to superior dimensional stability over click-lock and loose lay alternatives in commercial applications. The 4mm and 5mm thickness bands concentrate margin pools as contractors and specifiers prioritize underfoot comfort and sound transmission ratings in mixed-use developments. Residential end users remain the volume base, though hospitality and retail segments are expanding fastest as branded hotel chains and franchise operators standardize on LVT for renovation cycles.
China's SAMR enforces GB standards for building material emissions, while MEE oversight of PVC resin production shapes upstream cost structures and environmental compliance burdens for manufacturers. The country's dual carbon goals are pressuring energy-intensive calendaring and extrusion operations toward efficiency upgrades or geographic consolidation. Stakeholders must monitor how provincial enforcement of indoor air quality certifications redirects procurement decisions among tier-one property developers and state-backed infrastructure contractors.
Market Dynamics
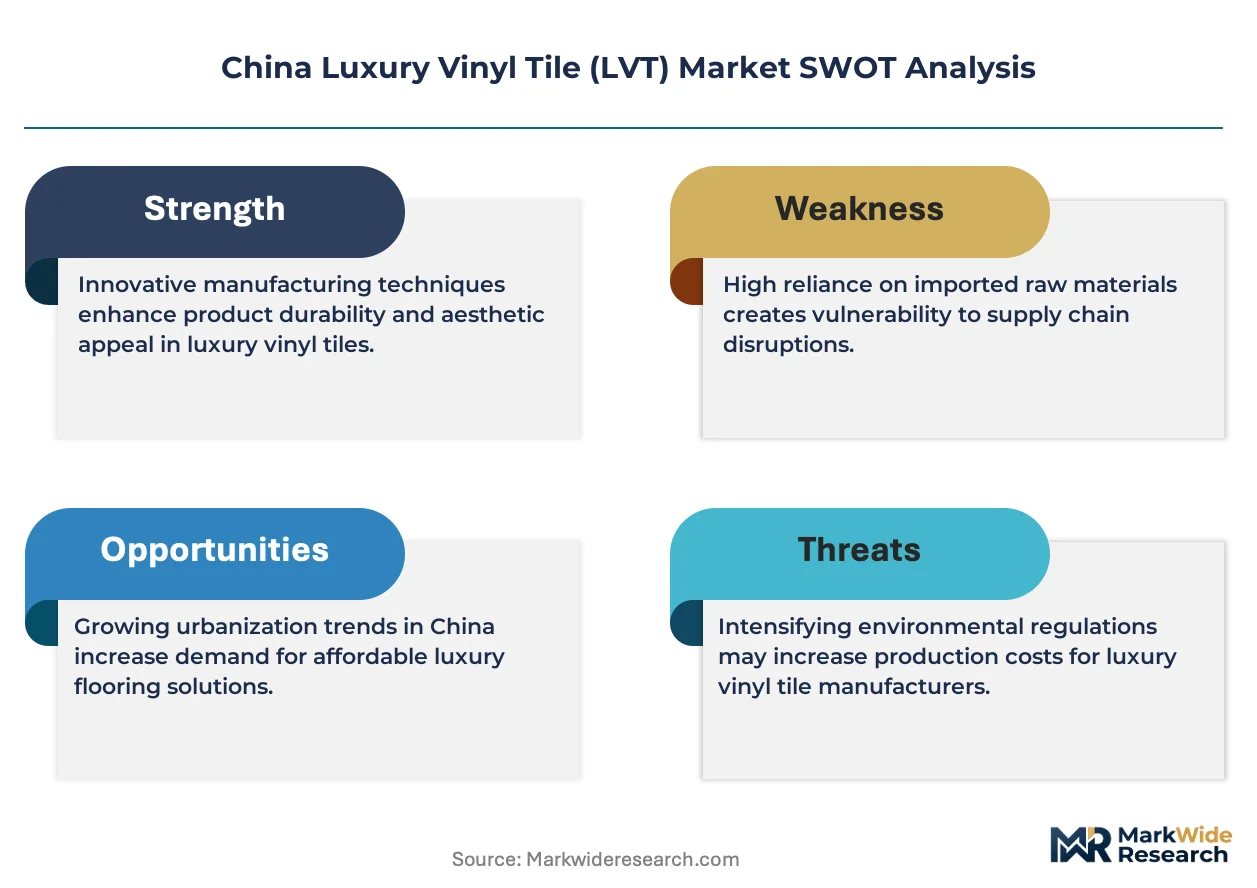
China's LVT sector faces a structural pivot as provincial enforcement of GB standards for indoor air quality and formaldehyde emissions forces manufacturers toward cleaner resin formulations and upgraded calendaring equipment.
Growth Catalysts
- Dual carbon policy pressure:MEE oversight of PVC resin production is accelerating energy efficiency investments in extrusion operations across the Yangtze River Delta.
- Hospitality renovation standardization:Branded hotel chains in Shanghai and Shenzhen are specifying rigid core LVT for compressed renovation cycles in mixed-use developments.
- Integrated supply corridors:Petrochemical feedstock proximity in Jiangsu Province enables rapid order fulfillment for export-bound rigid core and glue-down formats.
Market Restraints
- Resin price volatility:PVC feedstock costs fluctuate with crude oil movements and domestic petrochemical scheduling, squeezing margin pools in standard-thickness segments.
- Upstream concentration risk:Calendaring capacity clusters heavily in Guangdong Province, creating geographic vulnerability to regional power rationing or environmental enforcement surges.
- Ceramic tile substitution:Polished porcelain retains preference in premium residential applications where thermal mass and perceived durability outweigh LVT's installation speed.
Strategic Opportunities
- Western China penetration:Chengdu and Chongqing construction markets show underdeveloped LVT specification rates relative to coastal tiers, offering first-mover positioning for rigid core distribution.
- Healthcare flooring mandates:SAMR's evolving GB standards for antimicrobial surface performance create compliance-driven demand in hospital and eldercare retrofit segments.
- Digital specification platforms:BIM-integrated product libraries are compressing architect decision cycles and displacing traditional sample-based selection in commercial projects.
Industry Challenges
- Emissions certification timelines:Third-party testing for GB/T 39600-2021 formaldehyde compliance extends 6-8 weeks, delaying project bids for state-backed infrastructure contractors.
- Skilled installation gaps:Rigid core click-lock systems require specialized subfloor preparation expertise that remains scarce in tier-three city contractor networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Luxury Vinyl Tile (LVT) Market |
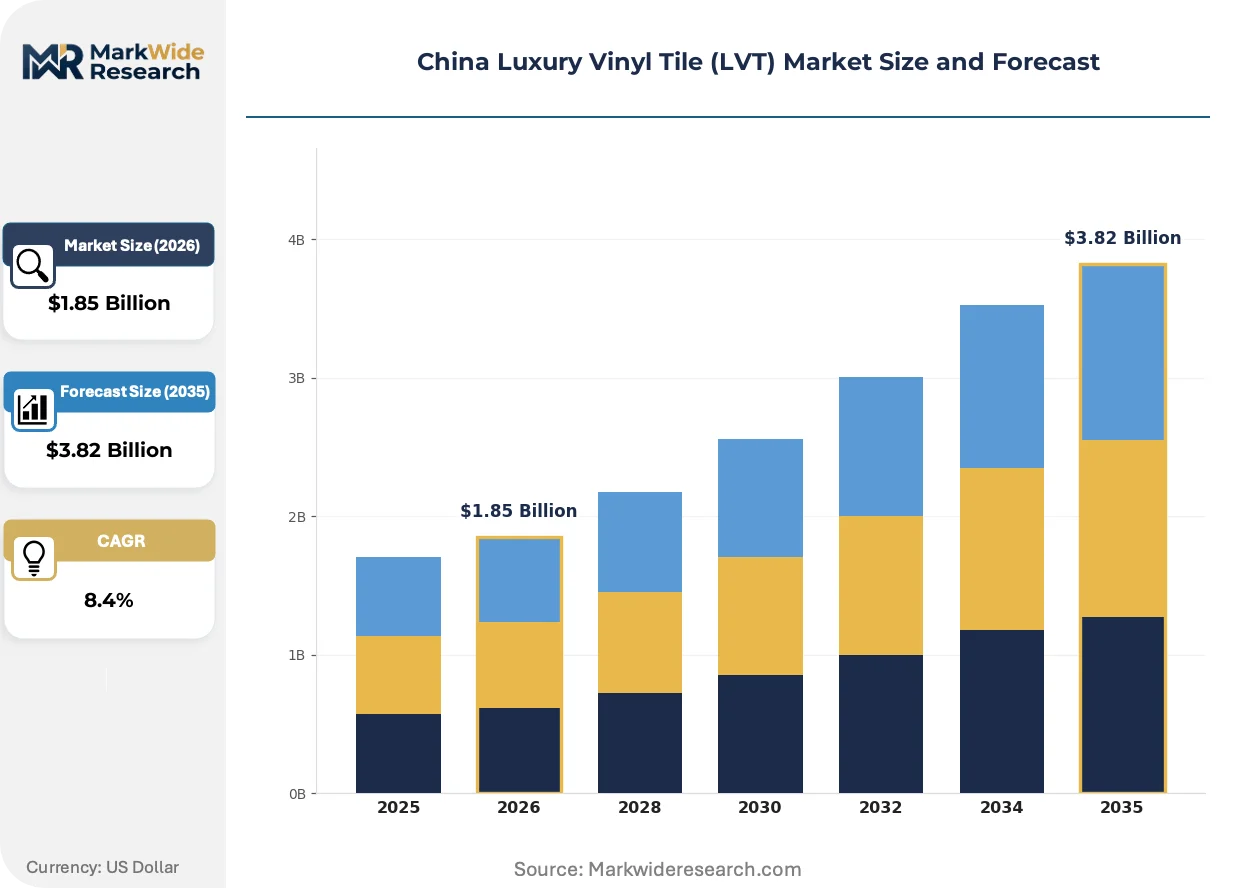
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.82 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glue-Down, Click-Lock, Loose Lay, Rigid Core End User: Residential, Commercial, Hospitality, Retail Thickness: 2mm, 3mm, 4mm, 5mm Surface Finish: Embossed, Smooth, Textured, High Gloss |
| Companies Covered | Jiangsu Taide Decoration Materials Co Ltd, CFL Flooring, Chiping Xinlida New Decoration Materials Co Ltd, Zhejiang Walrus New Material, Novalis Innovative Flooring, Protex Flooring, Shanghai 3C Industry Co Ltd, Hanflor, Zhejiang Kingdom Plastics Industry Co Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Luxury Vinyl Tile (LVT) Market Strategic Shifts
Surface finishing and core engineering advances are compressing the performance gap between synthetic flooring and traditional materials. Digital decoration technologies and regulatory compliance automation now determine competitive positioning.
Digital printing systems are digitizing decorative film production by enabling micro-batch customization with wood-grain and stone-vein variations previously requiring dedicated cylinder engraving. High-end hospitality specifiers in Shanghai are adopting these digitally customized surfaces for boutique property differentiation. This capability is digitizing how regional manufacturers compete on aesthetic breadth without capital-intensive cylinder inventories.
SAMR's tightened GB standards for indoor air quality are forcing domestic manufacturers to reformulate stabilizer packages and accelerate low-emission adhesive development. The industrial consequence is a bifurcation between compliant premium lines and discounted export-oriented production. Rigid core manufacturers serving domestic commercial real estate are most affected, redirecting R&D budgets toward third-party emissions certification.
Specification behavior is consolidating around performance-certified product tiers as tier-one property developers centralize procurement through approved vendor lists. Traditional distributor relationships are losing ground to direct manufacturer engagement with state-backed contractors. This pattern is most visible in Shenzhen and Guangzhou, where mixed-use developers now require documented acoustic and slip-resistance ratings upfront.
China Luxury Vinyl Tile (LVT) Market Segmentation
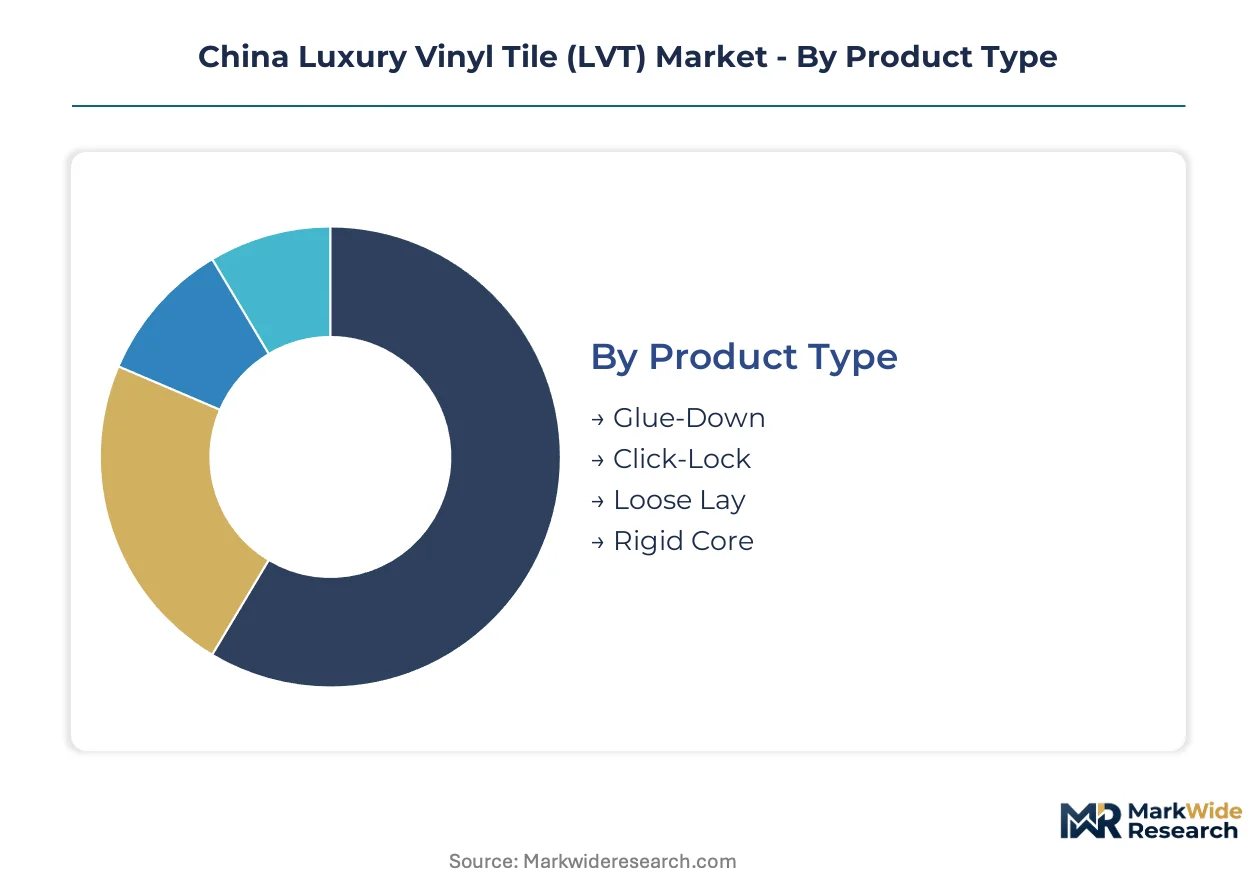
LVT purchasing decisions in China diverge sharply across installation method, end-use environment, and performance specifications. Understanding these splits reveals where margin pools concentrate and which technical attributes command specification premiums.
Product Type:
Installation mechanics define project suitability across renovation versus new construction workflows.
- Glue-Down:Permanent adhesive bonding delivers superior dimensional stability for high-traffic commercial corridors in Shanghai office towers. SAMR's GB compliance timelines delay bids, but specifiers accept the trade-off for acoustic performance in mixed-use developments.
- Rigid Core:Mineral-composite or SPC cores provide click-lock installation speed without subfloor perfection. Shenzhen hospitality renovators specify 4mm and 5mm variants for compressed project schedules where moisture resistance outweighs first-cost sensitivity.
- Click-Lock:Floating floor systems target residential replacement cycles in tier-two cities where DIY installation reduces labor costs.
- Loose Lay:Friction-backed sheets enable rapid deployment in temporary retail pop-ups and exhibition spaces requiring future repositioning.
Established volume favors glue-down formats in commercial retrofits; emerging adoption favors rigid core systems in hospitality renovation cycles.
End User:
Performance certification requirements fragment procurement behavior across property types.
- Residential:Cost-conscious homeowners in Jiangsu Province drive volume through 2mm and 3mm glue-down selections, with price sensitivity amplified by ceramic tile substitution in premium renovations.
- Hospitality:Branded hotel chains standardize on rigid core LVT with embossed finishes for compressed renovation timelines in Chengdu and Chongqing expansion markets.
- Commercial:State-backed infrastructure contractors in the Yangtze River Delta demand documented acoustic and slip-resistance ratings upfront, centralizing procurement through approved vendor lists.
- Retail:Franchise operators prioritize loose lay formats for rapid store rollout programs where future layout flexibility retains value.
Residential channels anchor unit volume; hospitality and retail segments climb the fastest as branded operators consolidate flooring specifications.
Thickness:
Underfoot comfort and sound transmission ratings concentrate margin in thicker product bands.
- 4mm:Balanced performance specifications dominate mixed-use commercial specifications where impact sound reduction meets moderate traffic loads.
- 5mm:Maximum acoustic dampening and subfloor forgiveness command premium positioning in Shenzhen luxury residential and hospitality applications.
- 3mm:Economy-tier glue-down formats serve high-volume residential replacement cycles with minimal subfloor preparation.
- 2mm:Ultra-thin sheets penetrate price-sensitive renovation segments where existing floor height constraints limit upgrade options.
4mm products capture the broadest specification base; 5mm variants gain share fastest as acoustic ratings become mandatory in tier-one commercial projects.
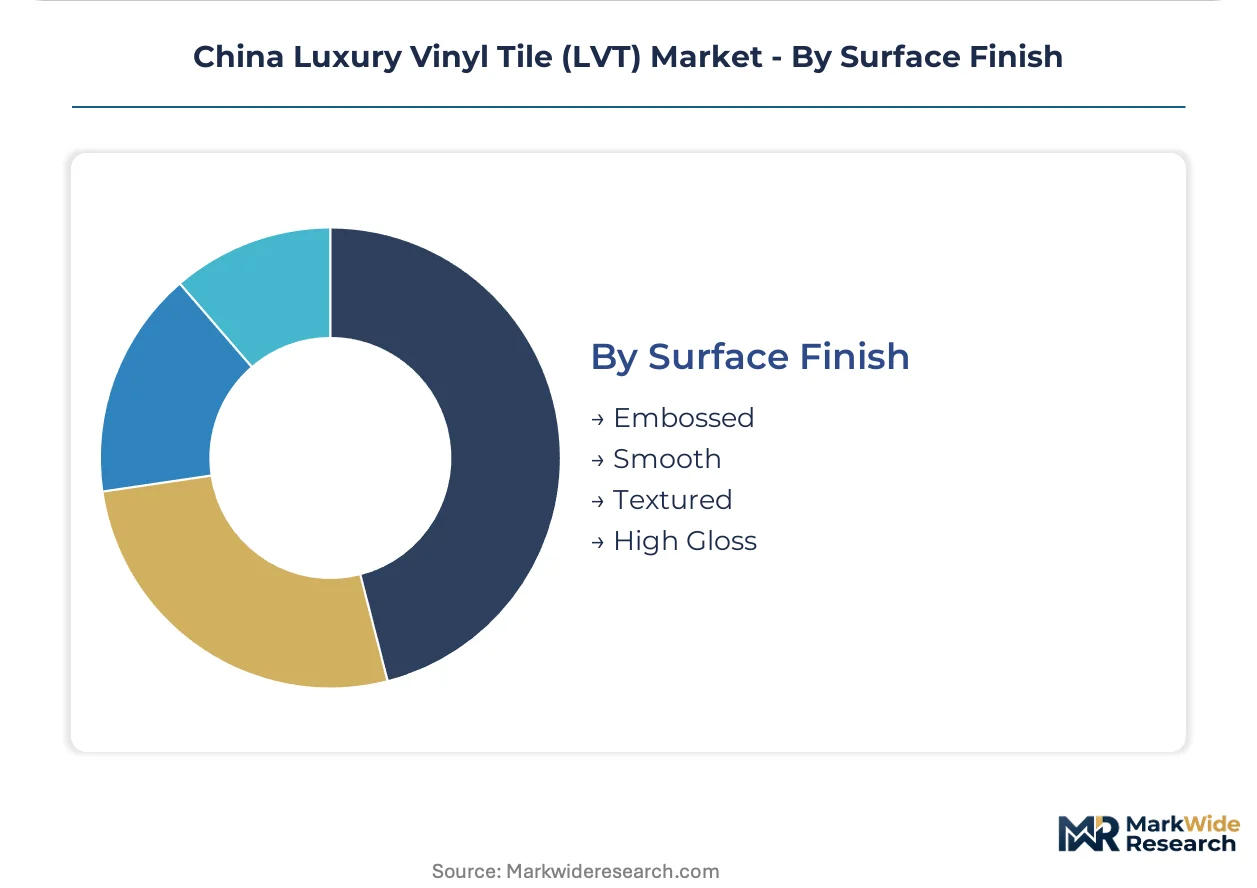
Surface Finish:
Aesthetic differentiation and maintenance characteristics drive finish selection across end-use environments.
- Embossed:Registered texture alignment with printed grain patterns replicates authentic wood and stone visuals for premium hospitality specifications in Shanghai boutique properties.
- Textured:Slip-resistant surfaces meet SAMR's evolving healthcare flooring mandates for hospital and eldercare retrofit segments.
- Smooth:Low-maintenance surfaces dominate high-turnover retail and food service environments where cleaning protocols prioritize speed.
- High Gloss:Polished aesthetics target residential statement installations where visual impact outweighs scratch visibility concerns.
Embossed finishes command specification premiums; textured surfaces expand most quickly as safety compliance tightens in institutional segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Extrusion capacity clusters heavily in Guangdong Province, while specification demand concentrates in coastal tier-one cities. Provincial enforcement of GB standards is redrawing procurement geography across China's construction markets.
Yangtze River Delta
Jiangsu Province anchors domestic production through integrated PVC supply corridors serving export and domestic rigid core orders. SAMR emissions certification timelines compress bidding windows for Shanghai commercial developers. Changzhou and Zhenjiang manufacturing clusters sustain rapid fulfillment for hospitality renovation cycles.
Pearl River Delta
Shenzhen and Guangzhou mixed-use developers standardize rigid core LVT for compressed project schedules. MEE oversight of resin production elevates compliance costs for Guangdong extrusion operators. Foshan calendaring capacity faces geographic vulnerability to regional power rationing.
Sichuan-Chongqing
Chengdu construction markets show underdeveloped LVT specification rates relative to coastal tiers. Dual carbon policy pressure shapes procurement decisions among state-backed infrastructure contractors. Chongqing's emerging manufacturing base targets first-mover positioning in western China distribution.
Beijing-Tianjin-Hebei
Capital region commercial real estate prioritizes documented acoustic ratings in approved vendor lists. GB/T 39600-2021 formaldehyde compliance extends third-party testing timelines for northern contractors. Tianjin petrochemical corridors supply resin feedstock to regional calendaring operations.
Shandong Peninsula
Qingdao and Yantai manufacturing bases exploit coastal logistics for export-bound glue-down formats. Provincial energy efficiency mandates accelerate equipment upgrades in extrusion operations. Local producers compete on cost positioning for residential replacement cycles in northern provinces.
China Luxury Vinyl Tile (LVT) Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in resin and decorative film supply. The vendor base spans vertically integrated extrusion operators, regional calendaring specialists, and specification-focused distributors. Three archetypes dominate: integrated PVC compounders with captive supply chains, rigid core engineering specialists, and hospitality-focused surface finish innovators. Competitive moves concentrate on geographic expansion into western China and portfolio diversification toward antimicrobial healthcare grades.
Among Jiangsu-based integrated manufacturers, Jiangsu Taide Decoration Materials Co Ltd exemplifies the captive supply chain archetype. CFL Flooring anchors export competitiveness through distribution partnerships in European and North American markets. Zhejiang Walrus New Material occupies a position in the premium surface finish tier, serving hospitality specifiers with embossed texture capabilities.
| Leading Market Players |
|---|
| Jiangsu Taide Decoration Materials Co Ltd |
| CFL Flooring |
| Chiping Xinlida New Decoration Materials Co Ltd |
| Zhejiang Walrus New Material |
| Novalis Innovative Flooring |
| Protex Flooring |
| Shanghai 3C Industry Co Ltd |
| Hanflor |
| Zhejiang Kingdom Plastics Industry Co Ltd |
| Others |
Value Chain & Pricing Dynamics
The Shanghai-Ningbo freight corridor's container rate volatility feeds directly into Guangdong extrusion operators' landed cost calculations, compressing margin pools for standard-thickness exports while amplifying price premiums for SAMR-certified domestic lines.
Pricing Analysis
GB/T 39600-2021 dictates the pricing tier structure across China's LVT market, separating emission-certified premium lines from export-oriented economy grades. Price differentiation hinges on third-party certification status and rigid core thickness specifications, with 5mm acoustic-rated products commanding substantial premiums over 2mm residential alternatives. Cost compression in glue-down segments is intensifying because PVC resin price volatility squeezes converters without backward integration into petrochemical feedstock. Tier-two city residential contractors exhibit highest price sensitivity, while Shenzhen mixed-use developers prioritize performance documentation over first-cost considerations.
Supply Chain Analysis
Extended payment terms from state-backed infrastructure contractors are reshaping working capital requirements for Jiangsu and Guangdong extrusion operators. Geographic supply concentration centers on China, with resin feedstock drawn from Tianjin and Ningbo petrochemical corridors and decorative films sourced from Zhejiang printing clusters. Single-source vulnerability in Guangdong calendaring capacity exposes the market to regional power rationing disruptions. Distribution runs through specification-focused distributors in coastal tier-one cities, with direct manufacturer engagement displacing traditional channel relationships for commercial projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among tier-one property developers and state-backed infrastructure contractors, with procurement centralization through approved vendor lists fragmenting traditional distributor influence.
For Market Incumbents: Harden defensive positioning through captive PVC compounding investments in Jiangsu Province and accelerated third-party emissions certification for rigid core lines. Ceramic tile substitution in premium residential segments and emerging hospitality-focused surface finish competitors threaten margin pools. Certification investment represents the critical lever for maintaining specification access among SAMR-compliant procurement channels. For New Entrants and Emerging Players: Pursue underdeveloped specification rates in Chengdu and Chongqing construction markets, where rigid core LVT penetration lags coastal tiers substantially. Healthcare flooring mandates for antimicrobial surface performance create the most penetrable compliance-driven segment. Digital specification platform partnerships with BIM-integrated product libraries offer the strongest go-to-market angle for compressing architect decision cycles. For Investors and Strategic Acquirers: Rigid core engineering specialists with established European distribution partnerships anchor the most attractive acquisition target archetype for long-term viability across the projection horizon. Monitor provincial enforcement patterns of dual carbon policy pressure as the primary inflection indicator for upstream consolidation timing and energy-intensive asset stranded risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PVC Resin Compounding | Jiangsu petrochemical corridor proximity enables cost control against feedstock volatility. |
| Third-Party Emissions Certification Acceleration | GB/T 39600-2021 compliance secures access to tier-one developer approved vendor lists. |
| Western China Distribution Network Buildout | Chengdu and Chongqing first-mover positioning captures underdeveloped specification demand. |
| Healthcare-Grade Antimicrobial Surface Development | SAMR evolving mandates create compliance-driven demand in hospital retrofit segments. |
| BIM-Integrated Digital Specification Platform Launch | Direct architect engagement displaces traditional sample-based selection in commercial projects. |
Study Parameters
Cross-validation between primary interviews with industry stakeholders and secondary data sources anchors the qualitative findings in this study. Conversations with plant managers at extrusion operations, procurement leads at commercial real estate developers, distribution channel partners in the Yangtze River Delta, and technical R&D directors at decorative film suppliers informed demand-side and supply-side dynamics. Secondary validation drew from customs and trade data, SAMR regulatory filings, provincial energy efficiency mandate disclosures, and construction project specification databases. Bottom-up volume modeling and top-down value triangulation ensured convergence across independent estimation approaches.
Calibration against historical production capacity utilization and specification trend data shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include installation method, end-use environment, thickness specification, and surface finish category, with provincial regulatory enforcement intensity as an industry-specific overlay. CAGRs were derived through trend extrapolation adjusted for policy inflection points. Key forecast inputs encompassed PVC resin price trajectory assumptions and hospitality renovation cycle standardization patterns among branded hotel chains.
Sensitivities concentrate around provincial enforcement intensity of GB standards and dual carbon policy implementation timelines. Forecasts reflect documented assumptions regarding resin feedstock cost structures and commercial real estate development schedules. Macroeconomic deviation, regulatory enforcement surges, or technological substitution acceleration would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
Laminate Flooring Market
Flooring, Carpets, and Rugs
Netherlands Floor Covering Market
Flooring, Carpets, and Rugs
United States Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Global Floor Covering Market
Flooring, Carpets, and Rugs
Europe Carpet and Rugs Market
Flooring, Carpets, and Rugs
Turkey Carpet and Rugs Market
Flooring, Carpets, and Rugs
Rigid Core Flooring Market
Flooring, Carpets, and Rugs
Entrance Matting Market
Flooring, Carpets, and Rugs
Wood and Laminate Flooring Market
Flooring, Carpets, and Rugs
Germany Floor Covering Market
Flooring, Carpets, and Rugs
India Vinyl Flooring Market
Flooring, Carpets, and Rugs
India Wood Flooring Market
Flooring, Carpets, and Rugs
Europe Vinyl Flooring Market
Flooring, Carpets, and Rugs
Area Rugs Market
Flooring, Carpets, and Rugs
Flooring for Tile and Stone Market
Flooring, Carpets, and Rugs
Foam Flooring Products Market