
 GCC Floor Covering Market | 2026-2036
GCC Floor Covering Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Floor Covering Market Foresight
Market Context
Saudi Building Code enforcement is hardening material certification requirements for interior surface finishes across the Kingdom. RAK Ceramics leverages its integrated manufacturing base in Ras Al Khaimah to sustain cost advantages in ceramic tile supply throughout the Gulf. Mohawk Industries anchors its position through broad laminate and hardwood distribution networks serving Saudi and UAE project pipelines. Al Sorayai Group specializes in carpet and soft flooring solutions tailored to regional aesthetic preferences and climate conditions.
Technical Definition and Structural Segments
Floor covering encompasses finished surface materials installed over structural subfloors to provide wear resistance, thermal insulation, acoustic dampening, and aesthetic finish in built environments. Ceramic tiles, formed from clay bodies fired at temperatures exceeding 1,000°C with glazed or unglazed surfaces, dominate commercial applications requiring moisture resistance and heavy traffic durability. Vinyl flooring leads residential retrofit activity across the GCC due to cost efficiency and water resistance suited to Gulf climates. Hardwood commands premium positioning in hospitality and high-end residential segments where natural material authenticity supports brand differentiation. Carpet retains stronghold in hospitality guest rooms and commercial offices seeking acoustic performance and underfoot comfort.
Regulatory Framework
Gulf Standardization Organization (GSO) technical regulations govern product safety, fire performance, and volatile organic compound emissions for floor coverings circulated across GCC member states. Saudi Standards, Metrology and Quality Organization (SASO) and Emirates Authority for Standardization and Metrology (ESMA) implement country-specific conformity assessment procedures that shape import clearance timelines and certification costs. Facility managers and procurement directors must monitor evolving GSO harmonization timelines and SASO Saber platform updates to avoid supply chain disruptions and project delays.
Market Dynamics
Saudi Building Code enforcement is hardening material certification requirements for interior surface finishes across the Kingdom. Facility managers and procurement directors must navigate evolving GSO harmonization timelines and SASO Saber platform updates to avoid supply chain disruptions and project delays.
Growth Catalysts
- Hospitality Construction Pipeline:Hotel construction accelerates across Dubai and Abu Dhabi, expanding floor covering procurement volumes for guest rooms, lobbies, and conference facilities.
- SASO Saber Platform:Saudi Arabia's digital conformity assessment system streamlines import clearance for certified materials, reducing certification timeline uncertainty for compliant suppliers.
- Ceramic Tile Performance:Fired clay bodies with glazed surfaces deliver moisture resistance and heavy traffic durability that commercial developers prioritize in Gulf climates.
Market Restraints
- Petrochemical Input Volatility:Vinyl flooring production depends on ethylene and propylene derivatives whose price swings compress margin predictability for manufacturers.
- Fire-Resistance Certification Costs:Stricter Saudi Building Code ratings for interior finishes extend testing timelines and raise compliance expenditure for imported products.
- Hardwood Substitution Pressure:Engineered wood and high-pressure laminate alternatives capture premium positioning at lower installed cost, constraining solid hardwood volume.
Strategic Opportunities
- Qatar Hospitality Recovery:Post-event infrastructure repurposing generates retrofit demand for acoustic flooring in converted exhibition and conference venues.
- Kuwait Residential Retrofit:Aging villa stock drives replacement cycles for water-resistant vinyl plank in residential applications underserved by current distribution.
- GSO Harmonization Timeline:Unified technical regulations across GCC member states reduce duplicate testing burdens for manufacturers achieving single-territory certification.
Industry Challenges
- Certification Timeline Compression:SASO Saber platform updates and GSO technical regulation revisions create uncertainty in import clearance scheduling for project-critical deliveries.
- Skilled Installation Shortage:Complex large-format tile and precision hardwood installation techniques face labor scarcity in Saudi Arabia's accelerated construction pipeline.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Floor Covering Market |
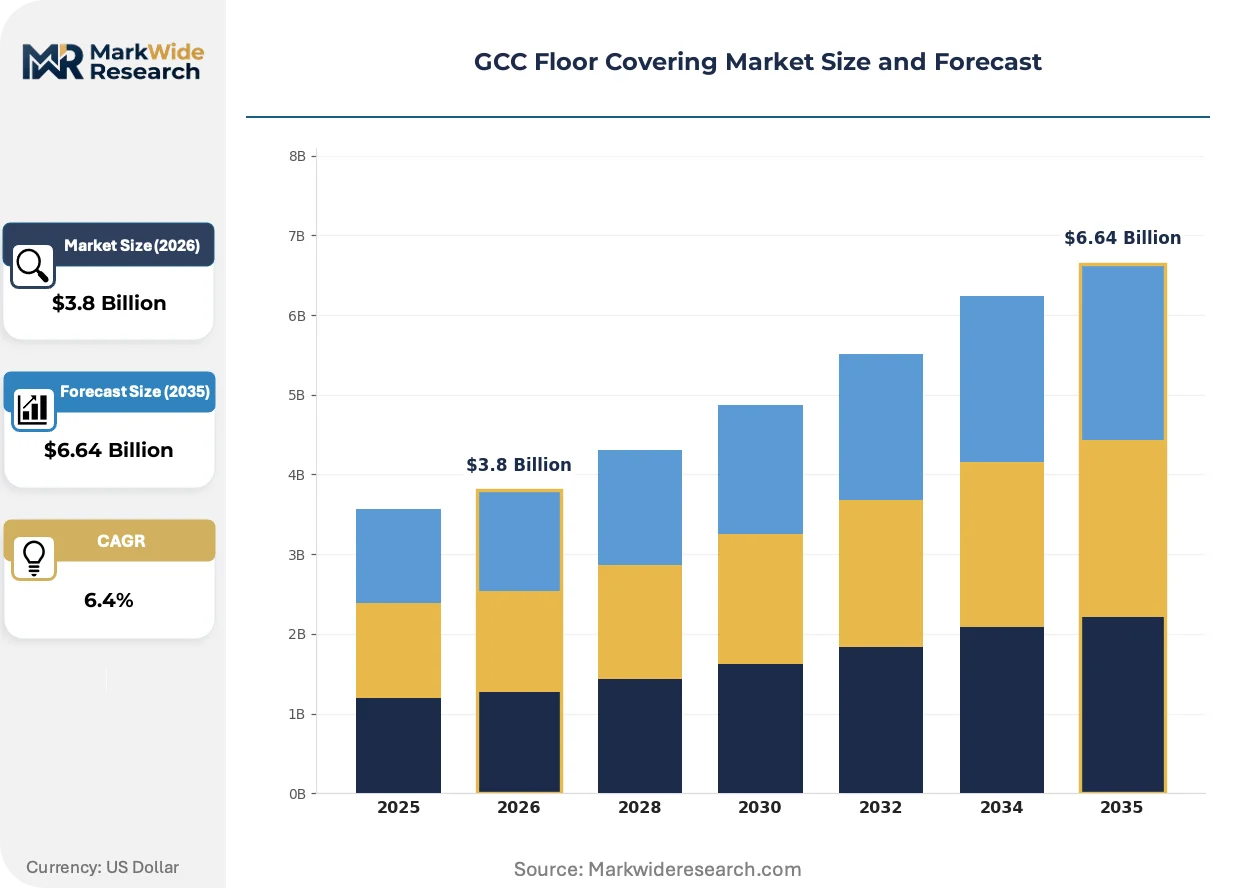
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vinyl, Laminate, Hardwood, Ceramic Tiles, Carpet, Bamboo Application: Residential Buildings, Commercial Complexes, Hospitality Facilities, Educational Institutions, Government Offices, Healthcare Centers Installation Type: Glue-down, Floating, Nail-down, Click-lock, Loose Lay End User: Property Developers, Interior Designers, Facility Managers, Retailers, Contractors, Renovators |
| Companies Covered | Floorworld LLC, AB Gustaf Kähr, RAK Ceramics, Mohawk Industries, Swiss Hardwoods, Al Sorayai Group, Swiss Krono AG, Tarkett S.A., Carpetland, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Floor Covering Market Shifts & Advancements
Digital specification tools and sustainability certification are reshaping how architects and facility managers select surface materials for Gulf projects. Material innovation now centers on performance verification and embodied carbon transparency rather than aesthetic differentiation alone.
Luxury vinyl tile (LVT) with rigid core construction is expanding into hospitality corridors and healthcare facilities where moisture resistance and acoustic underlayment prove critical. Hotel operators in Dubai specify these products for rapid renovation cycles that minimize guest room downtime. The technology is expanding into segments previously dominated by ceramic and carpet, compressing traditional category boundaries.
GSO technical regulations governing volatile organic compound emissions are tightening conformity assessment procedures for floor coverings circulated across GCC member states. ESMA in the UAE and SASO in Saudi Arabia implement country-specific testing protocols that extend pre-market authorization timelines. Vinyl and adhesive manufacturers face the steepest compliance burden as emission thresholds harden for interior air quality certification.
Direct-to-developer specification relationships are displacing traditional distributor-led selling in Saudi Arabia's megaproject pipeline. Major contractors in Riyadh and Jeddah now engage manufacturers for volume commitments bypassing wholesale channels. This pattern concentrates most visibly in the Kingdom's giga-project developments where procurement centralization favors suppliers with technical service capabilities and local inventory positioning.
GCC Floor Covering Market Segmentation
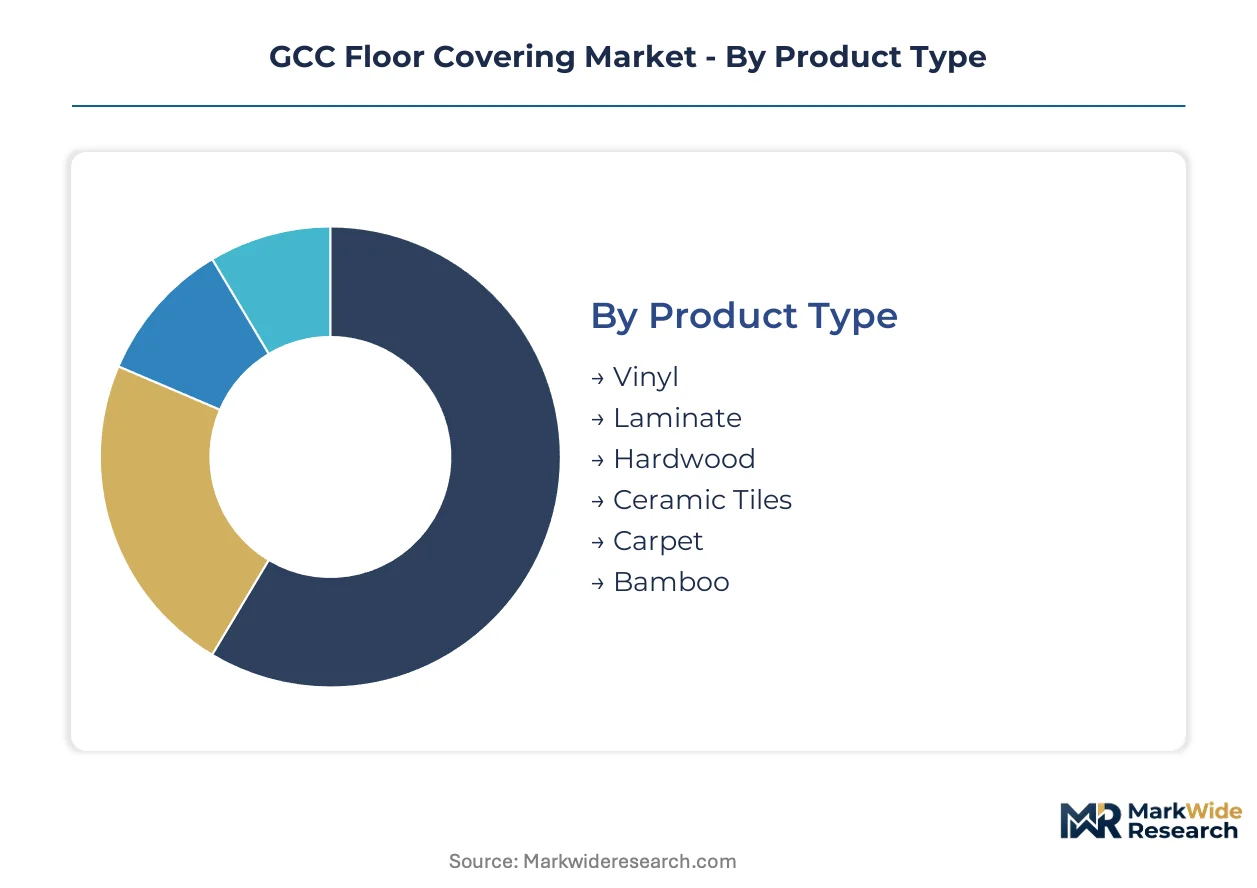
Floor covering procurement in the GCC splits across material performance requirements, installation complexity, and stakeholder decision authority. Understanding these divides clarifies where specification power concentrates and which technical standards govern purchase criteria.
Product Type:
Standardization dominates commodity categories while premium segments reward customization capabilities and technical service depth.
- Ceramic Tiles:Fired clay bodies with glazed or unglazed surfaces withstand Gulf humidity and heavy commercial traffic. Saudi giga-projects and Dubai hospitality developments specify large-format porcelain for lobbies and circulation areas where durability thresholds are non-negotiable.
- Vinyl:Polymer-based resilient flooring offers water resistance and rapid installation suited to residential retrofit cycles across Kuwait and Bahrain. Cost efficiency and climate adaptability drive volume in villa renovations and mid-market commercial fit-outs.
- Laminate:High-density fiberboard cores with decorative overlays capture wood aesthetics at reduced installed cost.
- Hardwood:Solid timber planks command premium positioning in Riyadh luxury residential and Abu Dhabi hospitality where natural material authenticity differentiates brand positioning.
- Carpet:Tufted and woven textile surfaces deliver acoustic dampening for hospitality guest rooms and corporate offices across Doha and Jeddah.
- Bamboo:Rapid-renewal grass flooring appeals to sustainability-specified projects seeking alternative hardwood aesthetics.
Most installed capacity flows through Ceramic Tiles. Expansion is steepest in Vinyl.
Application:
Project scale and finish durability requirements create distinct procurement workflows across building typologies.
- Hospitality Facilities:Hotels, resorts, and serviced apartments demand coordinated material specifications across guest rooms, corridors, and public areas. Dubai and Abu Dhabi construction pipelines prioritize rapid-renovation products that minimize operational downtime during property refreshes.
- Commercial Complexes:Office towers and retail centers require hard-wearing surfaces for 24-hour operational cycles. Saudi Arabia's Riyadh Financial District and Jeddah commercial zones specify ceramic and luxury vinyl tile for heavy traffic zones.
- Residential Buildings:Villa compounds and apartment towers across Kuwait and Bahrain drive replacement demand for water-resistant flooring in kitchens and bathrooms.
- Healthcare Centers:Hospitals and clinics mandate infection-control surfaces with seamless installation and chemical resistance.
- Educational Institutions:Schools and universities balance durability against maintenance accessibility across high-traffic circulation routes.
- Government Offices:Public sector procurement follows standardized technical specifications with extended tender timelines.
Procurement volume concentrates in Commercial Complexes. Healthcare Centers are gaining share fastest.
Installation Type:
Skill availability and substrate conditions determine method selection across project geographies.
- Glue-down:Adhesive-bonded application delivers permanent stability for commercial sheet vinyl and carpet in high-traffic healthcare and hospitality environments.
- Click-lock:Mechanically interlocking plank systems enable rapid floating installation without adhesives, reducing skilled labor dependency in Saudi Arabia's accelerated construction pipeline.
- Floating:Loose-laid systems over underlayment accommodate subfloor irregularity in residential retrofit applications.
- Nail-down:Fastened hardwood installation requires seasoned carpentry crews increasingly scarce in Gulf construction markets.
- Loose Lay:Friction-based placement suits temporary or rapid-turnover commercial environments.
Click-lock systems dominate residential and light commercial volume. Glue-down retains hold in institutional specifications.
End User:
Decision authority fragments between design-phase specification and procurement-phase execution.
- Property Developers:Master developers of Saudi giga-projects and UAE mixed-use towers centralize material selection for cost optimization and brand consistency across multiple assets.
- Contractors:Main contractors and specialty flooring subcontractors execute specifications with margin pressure driving substitution toward functionally equivalent lower-cost alternatives.
- Facility Managers:Operating companies in hospitality and commercial real estate influence replacement cycles based on maintenance cost experience and guest feedback metrics.
- Interior Designers:Design consultants specify aesthetic and performance criteria with varying technical depth in material selection.
- Retailers:Distribution channel partners stock inventory for residential renovation projects with shorter decision cycles.
- Renovators:Small-scale property owners drive replacement demand through retail and direct-installation channels.
Property Developers control the largest project pipelines. Facility Managers are expanding influence fastest as operating companies retain assets longer.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Floor covering manufacturing scaled first in the UAE's Ras Al Khaimah ceramic belt during the 1990s, establishing production infrastructure that now serves Gulf-wide distribution networks. Saudi Arabia's giga-project pipeline and Qatar's hospitality retrofit cycles now rival UAE commercial demand volumes.
Saudi Arabia
Riyadh's giga-project developments and Jeddah commercial towers drive specification volume for fire-rated ceramic and luxury vinyl surfaces. SASO Saber platform mandates digital conformity assessment for all imported floor coverings, extending pre-market authorization timelines. Eastern Province industrial zones host distributor consolidation as contractors centralize procurement for Red Sea coastal developments.
United Arab Emirates
Dubai hospitality construction and Abu Dhabi commercial real estate outpace other Gulf states in floor covering procurement intensity. ESMA implements country-specific volatile organic compound testing protocols that shape import clearance schedules. Ras Al Khaimah ceramic manufacturing clusters supply large-format porcelain across GCC markets from integrated clay-to-tile production bases.
Qatar
Post-event infrastructure repurposing generates retrofit demand for acoustic flooring in converted exhibition venues and conference centers. The country's national standardization body enforces Gulf Standardization Organization technical regulations for interior finish materials. Doha hospitality operators specify rapid-installation vinyl products to minimize operational downtime during property refreshes.
Kuwait
Aging villa stock drives replacement cycles for water-resistant vinyl plank in residential applications underserved by current distribution networks. The central agency for standardization oversees conformity assessment procedures that extend certification timelines for imported resilient flooring. Kuwait City retail corridors concentrate specialty flooring showrooms serving renovation-driven consumer demand.
GCC Floor Covering Market Competitive Landscape
The competitive structure tilts toward integrated manufacturers with captive raw material supply and established Gulf distribution infrastructure. Ceramic specialists leverage Ras Al Khaimah production bases to sustain cost advantages in tile supply throughout the region. Three archetypes dominate: integrated clay-to-tile manufacturers, global resilient flooring multinationals with regional distribution partnerships, and specialty carpet and soft flooring providers. Capacity expansion and direct-to-developer specification relationships represent the dominant competitive moves as Saudi giga-projects centralize procurement.
Among UAE-based integrated manufacturers, RAK Ceramics occupies a position exemplifying captive supply chain advantages from Ras Al Khaimah clay reserves and firing infrastructure. Mohawk Industries represents the multinational archetype with broad laminate and hardwood distribution networks serving Saudi and UAE project pipelines. Al Sorayai Group anchors the soft flooring specialist tier, with regional manufacturing capabilities tailored to Gulf aesthetic preferences and climate conditions.
| Leading Market Players |
|---|
| Floorworld LLC |
| AB Gustaf Kähr |
| RAK Ceramics |
| Mohawk Industries |
| Swiss Hardwoods |
| Al Sorayai Group |
| Swiss Krono AG |
| Tarkett S.A. |
| Carpetland |
| Others |
Supply & Pricing Matrix
Ethylene and propylene derivative indices cascade through vinyl flooring production into three distinct pricing tiers across the GCC. Ceramic tile manufacturers in Ras Al Khaimah leverage captive clay reserves to buffer margin pressure, while imported hardwood and laminate products absorb freight and certification premiums that compress distributor margins.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs procurement across Saudi giga-projects and UAE hospitality developments. Price differentiation centers on fire-resistance certification grade under SASO Saber and volume scale commitments from master developers. Cost compression in mid-market vinyl segments is intensifying because petrochemical input volatility feeds directly into polymer flooring production economics. Property developers controlling Saudi megaproject pipelines exhibit lowest price sensitivity, while residential renovators in Kuwait and Bahrain drive hardest bargain on per-square-meter costs.
Supply Chain Analysis
Saudi Arabia's escalating local-content mandates for construction materials are reshaping sourcing patterns for imported floor coverings. Manufacturing concentrates in the UAE's Ras Al Khaimah ceramic belt, Saudi Arabia's emerging industrial zones, and Chinese vinyl production hubs serving Gulf distribution networks. Raw material flows draw from UAE clay deposits, Saudi petrochemical derivatives, and European decorative paper for laminate overlays. Single-source vulnerability runs through Ras Al Khaimah's concentrated ceramic firing capacity. Distribution runs through direct-to-developer specification channels in Riyadh and Jeddah alongside traditional wholesale networks serving smaller contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The GCC floor covering market functions as a stable compounder anchored by Saudi Arabia's decade-long giga-project construction pipeline. Hospitality and commercial real estate development across Dubai, Abu Dhabi, and Riyadh generates predictable replacement and new-build demand cycles.
For Market Incumbents: To counter direct-to-developer specification relationships displacing wholesale channels, ceramic manufacturers should deepen captive supply control over Ras Al Khaimah clay reserves and firing infrastructure. RAK Ceramics and integrated UAE producers must invest in technical service teams embedded within Saudi giga-project procurement offices to defend specification authority against emerging Turkish and Chinese competitors. For New Entrants and Emerging Players: Digital specification tools and rapid-installation vinyl systems offer technology-first entry points into Qatar's hospitality retrofit cycle and Kuwait's aging villa replacement market. White-space concentration sits in acoustic flooring for converted Doha exhibition venues and water-resistant vinyl plank distribution gaps across Bahrain residential corridors. New entrants should pursue facility manager relationships in operating hospitality assets rather than competing for developer-led new construction. For Investors and Strategic Acquirers: Asymmetric upside sits with specialty carpet and soft flooring providers possessing regional manufacturing capabilities tailored to Gulf climate conditions. Al Sorayai Group exemplifies the target archetype: local production assets, established distribution relationships, and technical adaptation to regional humidity and sand exposure. Investors should monitor SASO Saber platform expansion timelines as inflection signal — accelerated digital certification mandates favor scaled incumbents with compliance infrastructure over fragmented importers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Clay Reserves | RAK Ceramics secures captive supply from Ras Al Khaimah deposits against freight volatility. |
| Direct-to-Developer Technical Service Teams | Mohawk Industries embeds specification support within Saudi giga-project procurement offices. |
| Rapid-Installation Vinyl Product Lines | Tarkett S.A. targets Qatar hospitality retrofit cycles minimizing operational downtime. |
| SASO Saber Certification Infrastructure Investment | Al Sorayai Group accelerates import clearance timelines for compliant carpet shipments. |
| Acoustic Flooring Development for Converted Venues | Specialty manufacturers capture Doha exhibition center repurposing demand. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to construct demand estimates for the GCC floor covering market. Primary fieldwork engaged procurement directors at Saudi giga-project developers, facility managers across Dubai and Abu Dhabi hospitality portfolios, flooring contractors in Riyadh and Jeddah, and distribution channel partners in Kuwait and Bahrain. Secondary validation drew from SASO Saber platform disclosure patterns, ESMA technical regulation updates, Gulf Standardization Organization harmonization timelines, and customs trade data for ceramic tile and resilient flooring imports. Bottom-up project pipeline enumeration and top-down construction spending allocation triangulated volume estimates.
Comparable-period anchoring linked historical installation data to forward projection assumptions across the analysis window. Segmentation modeling incorporated material type, application vertical, installation complexity, and end-user decision authority. CAGRs derived from fitted growth curves applied to construction pipeline schedules and replacement cycle assumptions. Industry-specific inputs included Saudi Building Code enforcement trajectories, hospitality construction permit flows in Dubai, and petrochemical derivative price correlation effects on vinyl flooring economics.
The model holds under stable regulatory enforcement and continued giga-project execution; deviation in SASO Saber platform disruption or petrochemical input spike would shift volume and margin assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
China Laminate Flooring Market
Flooring, Carpets, and Rugs
Wood and Laminate Flooring Market
Flooring, Carpets, and Rugs
North America Laminate Flooring Market
Flooring, Carpets, and Rugs
ASEAN Laminate Flooring Market
Flooring, Carpets, and Rugs
Middle East Flooring and Carpet Market
Flooring, Carpets, and Rugs
United Kingdom Floor Covering Market
Flooring, Carpets, and Rugs
Bath Mats Market
Flooring, Carpets, and Rugs
Europe Laminate Flooring Market
Flooring, Carpets, and Rugs
India Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Fiberglass Flooring Market
Flooring, Carpets, and Rugs
North America Carpet Tile Market
Flooring, Carpets, and Rugs
Global Flooring Market
Flooring, Carpets, and Rugs
Asia Pacific Flooring Market
Flooring, Carpets, and Rugs
India Laminate Flooring Market
Flooring, Carpets, and Rugs
Global Vinyl Floor Covering Market
Flooring, Carpets, and Rugs
Global Commercial Flooring Market