
 China Engineered Wood Flooring Market | 2026-2036
China Engineered Wood Flooring Market Size, Share, and Industry Trends Forecast 2026-2036
China Engineered Wood Flooring Market Insights
Modular click-lock installation systems are repositioning buyer preferences toward faster, less labor-intensive flooring deployment. Power Dekor leverages its manufacturing scale to dominate the stratified product tier across eastern provinces. Elegant Living anchors its competitiveness through specialized contemporary design collections that command premium positioning in urban residential projects. Kentier differentiates via vertical control over timber sourcing, ensuring consistent raw material quality for multi-layered output.
Engineered wood flooring consists of a real hardwood veneer bonded over a plywood or high-density fiberboard core, typically measuring 10-15mm in total thickness with wear layers ranging from 2mm to 6mm. This construction delivers dimensional stability against humidity fluctuations while preserving the aesthetic and tactile properties of solid hardwood for residential and commercial interior applications. Stratified products lead volume shipments due to their cost efficiency, yet tripled-layered configurations capture expanding margin pools as consumers prioritize thicker wear layers for refinishing longevity. Click-lock installation methods are displacing traditional glue-down approaches in new residential construction, driven by contractor demand for accelerated project timelines and reduced adhesive costs.
GB standards administered by SAMR enforce strict formaldehyde emission limits that reshape product formulation and testing protocols across domestic manufacturing. MEE environmental compliance requirements and MIIT industrial policy directives jointly pressure mills toward cleaner production technologies and certified sustainable timber sourcing. Stakeholders must monitor how dual carbon goals and evolving provincial green building codes will recalibrate material specifications and factory certification requirements across China's major production basins.
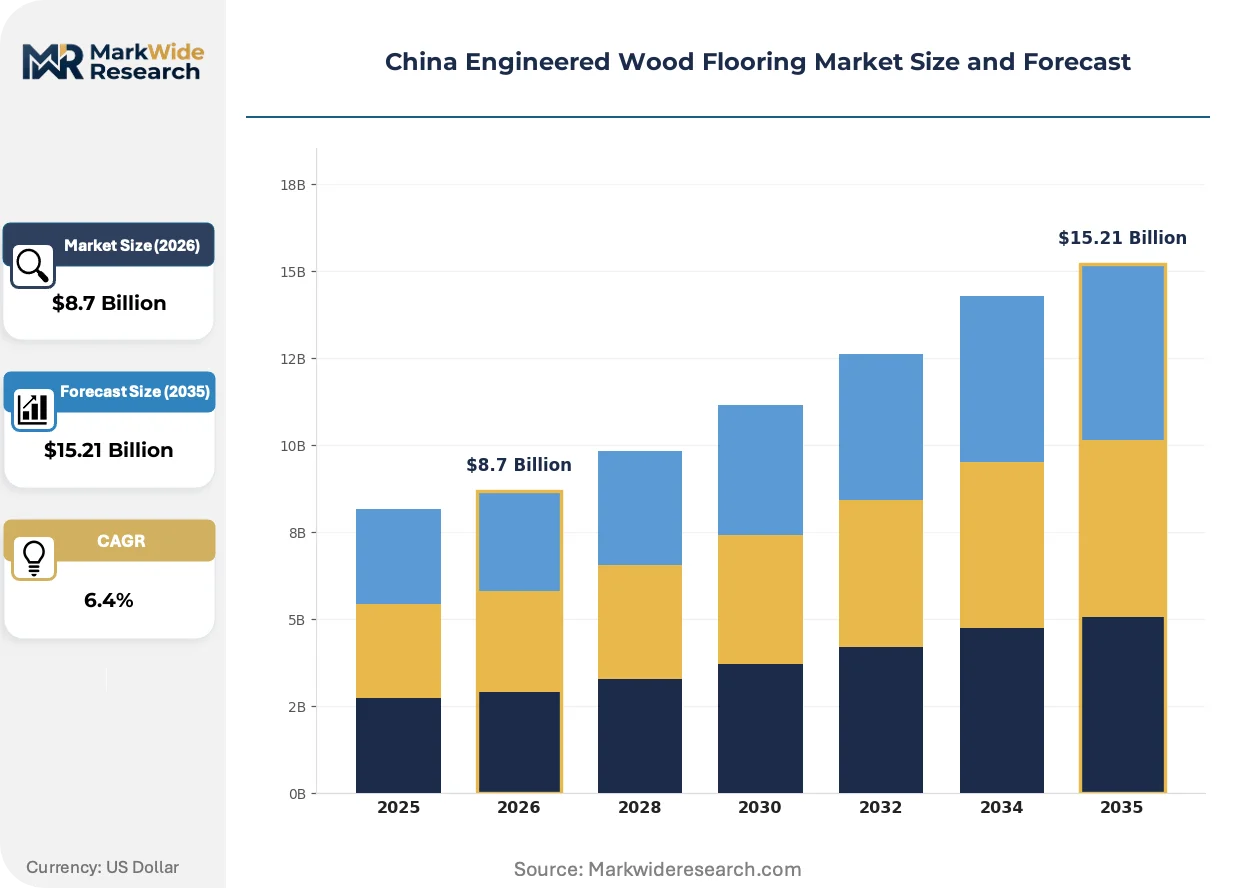
Market Dynamics
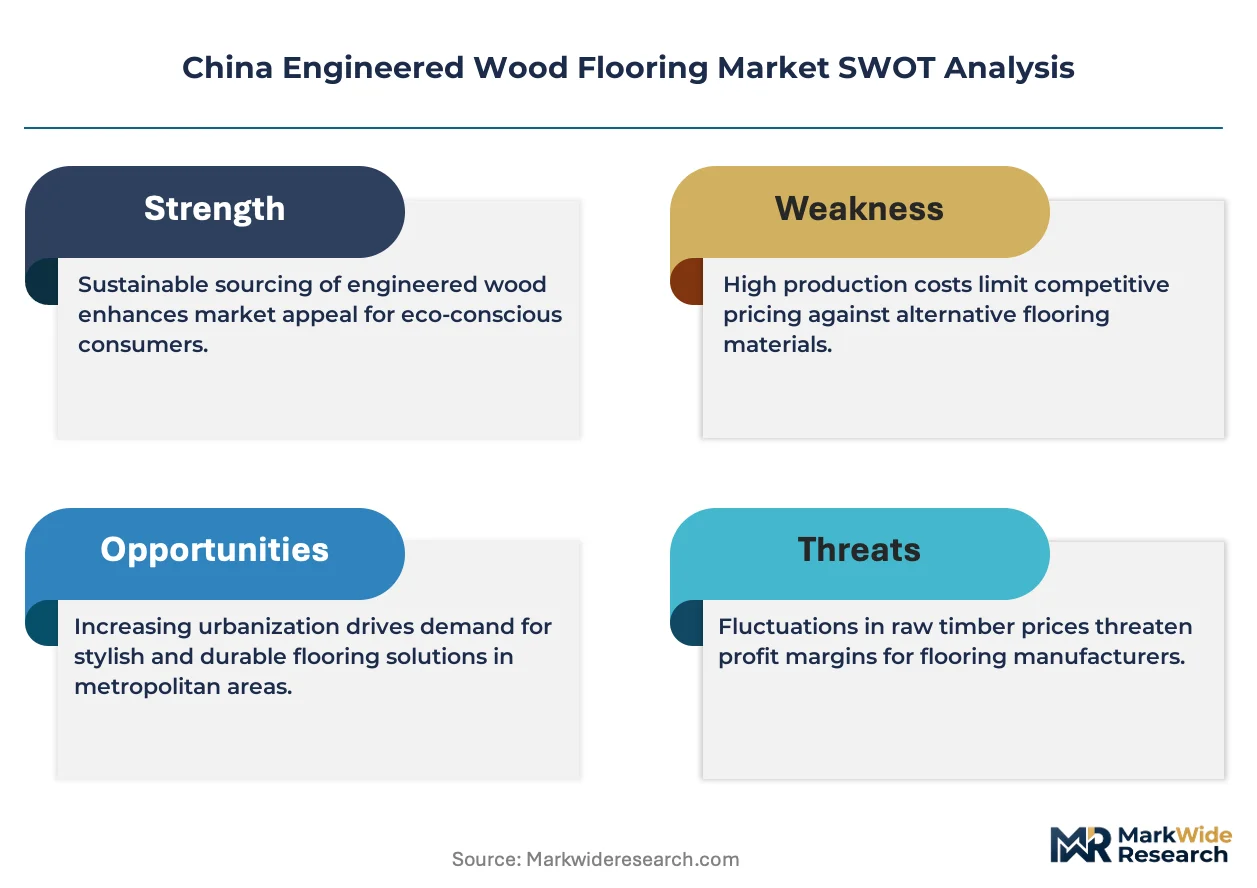
Urban renewal policies in tier-one Chinese cities are accelerating residential renovation cycles, pulling premium multi-layered engineered wood products into high-margin replacement demand while GB standards for formaldehyde emissions tighten formulation requirements across domestic manufacturing.
Growth Catalysts
- MIIT Green Building Directives:Industrial policy mandates for cleaner construction materials are redirecting public and private project specifications toward certified low-emission engineered wood products.
- Click-Lock Installation Systems:Modular mechanical fastening technologies are compressing project timelines for residential contractors and reducing skilled labor dependency in renovation markets.
- Yangtze River Delta Concentration:Shanghai and surrounding Jiangsu and Zhejiang manufacturing clusters anchor both production capacity and affluent consumer demand within a single logistics radius.
Market Restraints
- Timber Input Volatility:Imported hardwood veneer supply faces price instability from Southeast Asian export restrictions and Baltic birch plywood sourcing disruptions.
- Formaldehyde Testing Compliance Costs:SAMR-administered GB standards require batch-level emission certification that elevates quality control overhead for mid-scale mills.
- Ceramic Tile Substitution:Large-format porcelain flooring advances in moisture-prone applications, particularly in southern China's humid coastal provinces.
Strategic Opportunities
- Western China Penetration:Chengdu and Xi'an metro areas exhibit underdeveloped engineered wood adoption relative to eastern tier-one cities, creating whitespace for distribution expansion.
- Dual Carbon Policy Tailwinds:National carbon neutrality targets are elevating timber-based materials in green building certification schemes that favor renewable feedstocks.
- Digital Specification Platforms:Architect and designer software integration is emerging as a channel innovation that locks product selection into project planning phases.
Industry Challenges
- Skilled Installation Labor Scarcity:Traditional glue-down craftsmanship is aging out faster than click-lock training programs can replenish competent contractor networks.
- Multi-Certification Timeline Compression:Mills must simultaneously secure MEE environmental compliance, GB quality marks, and green building label approvals to access premium project tiers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Engineered Wood Flooring Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stratified, Multi-Layered, Tripled-Layered, High-Density Fiberboard Application: Residential, Commercial, Industrial, Hospitality Installation Method: Floating, Glue-Down, Nail-Down, Click-Lock Design Style: Traditional, Contemporary, Rustic, Modern |
| Companies Covered | Lianfeng, Elegant Living, Kentier, Nature Wood, Gaopai Wood, Power Dekor, Gloria Floor, Yangzi Flooring, Anxin Flooring, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Engineered Wood Flooring Market Trends and Innovations
Product formulation and installation methodology are converging around speed-to-deploy systems and emission transparency, with regulatory pressure and contractor economics jointly selecting for thinner, faster, cleaner solutions.
Water-based UV curing coatings are expanding into mainstream engineered wood finishing, replacing solvent-based alternatives that struggle with GB volatile organic compound limits. High-volume manufacturers in Jiangsu province are adopting these systems to maintain throughput while satisfying SAMR emission testing protocols. The technology is expanding into mid-tier product lines previously reserved for solvent-cured premium grades, compressing the historical performance gap between price segments.
MIIT industrial policy directives on green building materials are forcing mills to reconfigure adhesive formulations toward soy-based and phenol-resin alternatives. Production lines in Zhejiang and Fujian are retooling hot-press operations to accommodate lower-formaldehyde bonding chemistry. Multi-layered product categories face the steepest compliance curve, as thicker core constructions require more adhesive volume per square meter.
Contractor procurement patterns are consolidating around pre-finished, site-ready engineered wood packages that bundle underlayment and trim components. Traditional distributor relationships that separated material sourcing from installation support are losing share to integrated supply agreements in Shanghai and Hangzhou residential developments. This bundling behavior is most visible in high-rise renovation projects where elevator logistics and waste disposal constraints favor single-source accountability.
China Engineered Wood Flooring Market Segmentation
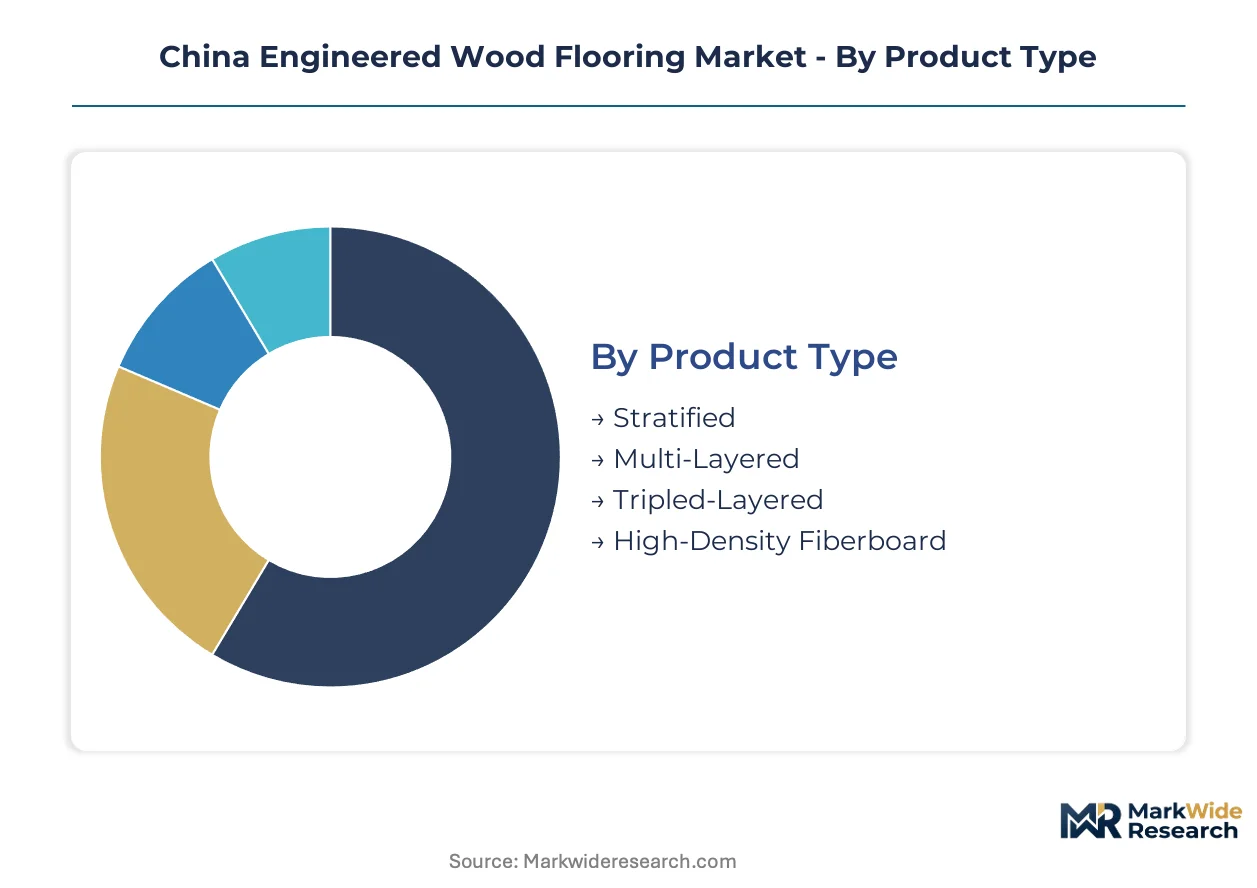
Product architecture and installation methodology drive margin stratification across China's engineered wood flooring sector. Specification choices cascade through material costs, labor requirements, and compliance burdens that reshape project economics.
Product Type:
Customization intensity rises with layer count as thicker wear layers demand specialized timber sourcing and extended press cycles.
- Stratified:Three-ply construction with 2-3mm hardwood veneer over cross-laminated softwood cores dominates volume shipments. Shanghai and Jiangsu manufacturing clusters absorb the bulk of tier-one residential renovation demand where cost efficiency outweighs refinishing longevity.
- Multi-Layered:Five to seven-ply configurations with 3-4mm wear layers balance dimensional stability against material cost. Chengdu and Xi'an metro areas pull expanding volumes as western China developers specify mid-tier products for new residential towers.
- Tripled-Layered:Premium 6mm+ wear layer products command specification in high-end urban renewal projects.
- High-Density Fiberboard:Compressed wood fiber cores serve budget-conscious commercial fit-outs.
Most installed capacity flows through Stratified. Expansion is steepest in Multi-Layered.
Application:
End-use requirements diverge sharply on durability ratings, fire codes, and aesthetic specifications that filter back to factory production scheduling.
- Residential:Single-family and multi-family housing absorbs the majority of click-lock engineered wood volumes. Yangtze River Delta urban renewal policies accelerate replacement cycles in Shanghai's aging housing stock.
- Commercial:Office and retail fit-outs prioritize abrasion-resistant finishes and rapid installation turnaround. MIIT green building directives redirect public sector specifications toward certified low-emission products.
- Industrial:Warehouse and light manufacturing facilities specify economy-grade HDF-core products.
- Hospitality:Hotel and serviced apartment chains demand consistent batch coloring and acoustic underlayment integration.
Residential commands the dominant share of production capacity. Hospitality is climbing the fastest as branded hotel chains expand into second-tier cities.
Installation Method:
Labor economics and project timeline pressure are compressing traditional glue-down approaches into niche restoration applications.
- Floating:Interlocking planks rest on foam underlayment without subfloor adhesion, enabling rapid deployment and future removal. Zhejiang contractors favor this method for high-rise renovations where structural constraints prohibit permanent fastening.
- Click-Lock:Precision-milled tongue-and-groove mechanical fastening eliminates adhesive curing time and reduces skilled labor dependency. New residential construction across eastern provinces is standardizing on this approach.
- Glue-Down:Full-spread adhesive application persists in historic building restoration.
- Nail-Down:Pneumatic fastening requires plywood subflooring and remains concentrated in low-rise wood-frame construction.
Floating systems anchor the majority of current installations. Click-Lock is gaining share fastest as contractor training programs scale.
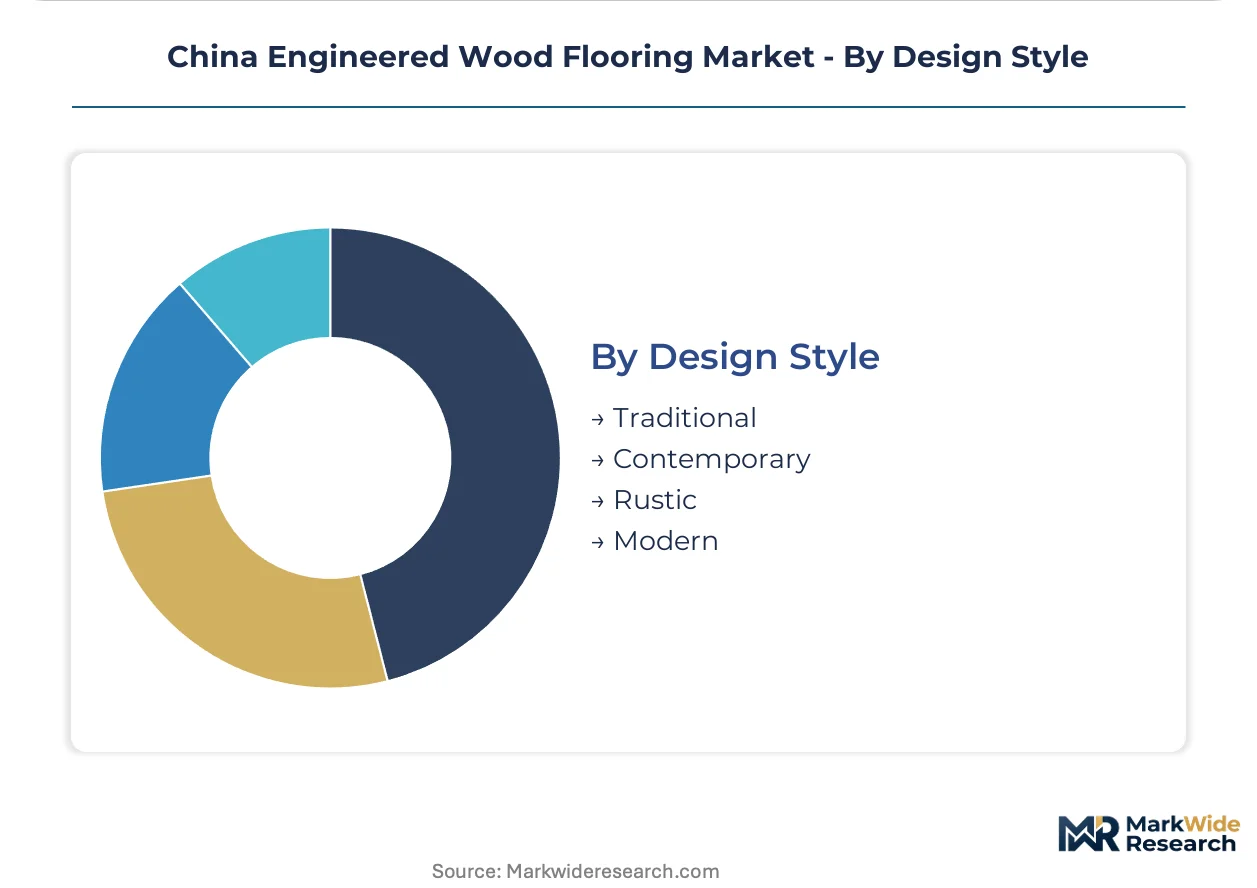
Design Style:
Aesthetic positioning correlates with regional architectural preferences and developer branding strategies that segment price tiers.
- Contemporary:Clean lines, wide planks, and matte finishes dominate Shanghai and Hangzhou premium residential projects. Elegant Living and similar design-forward mills command specification through architect relationships.
- Modern:Minimalist gray and white-washed tones target younger demographics in Shenzhen and Guangzhou new-build apartments.
- Traditional:Classic oak and walnut staining persists in northern China heritage renovations.
- Rustic:Distressed surfaces and reclaimed-weathered aesthetics serve boutique hospitality and rural tourism developments.
Contemporary styling channels the largest production volume. Modern is expanding most quickly as generational turnover accelerates in southern markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's engineered wood flooring industry traces its commercial scale to Jiangsu and Zhejiang manufacturing clusters that emerged during the 1990s export boom, later pivoting toward domestic consumption as urban housing stock aged and renovation cycles accelerated.
Yangtze River Delta
Shanghai's urban renewal policies are absorbing premium tripled-layered products as aging residential towers undergo systematic refurbishment. MIIT green building directives redirect public housing specifications toward certified low-emission engineered wood. Manufacturing concentration in Suzhou and Changzhou anchors both production capacity and affluent consumption within a single logistics radius.
Pearl River Delta
Shenzhen and Guangzhou developers specify contemporary-styled engineered wood for new-build apartments targeting younger demographics. GB standards administered by SAMR enforce batch-level formaldehyde certification that elevates quality control overhead for regional mills. Foshan manufacturing bases are retooling adhesive formulations to accommodate soy-based and phenol-resin bonding chemistry.
Sichuan-Chongqing
Chengdu metro area exhibits underdeveloped engineered wood adoption relative to eastern tier-one cities, creating whitespace for distribution expansion. Provincial green building codes are recalibrating material specifications for commercial and hospitality fit-outs. Local manufacturing clusters in Deyang and Mianyang are scaling mid-tier multi-layered production for western China developers.
Beijing-Tianjin-Hebei
Heritage renovation projects in Beijing's historic districts sustain niche demand for traditional glue-down installation methods. MEE environmental compliance requirements pressure mills toward cleaner production technologies and certified sustainable timber sourcing. Langfang and Baoding industrial zones supply stratified products to northern China replacement markets.
Shandong Peninsula
Qingdao and Yantai ports facilitate imported hardwood veneer supply chains facing price instability from Southeast Asian export restrictions. Dual carbon policy tailwinds elevate timber-based materials in provincial green building certification schemes. Weihai manufacturing bases specialize in water-based UV curing coatings that satisfy SAMR volatile organic compound limits.
China Engineered Wood Flooring Market Competitive Landscape
Premium-margin players sit above commodity-margin players across design specialization and timber sourcing control, with the vendor base fragmenting across scale-driven national brands, regionally anchored specialists, and vertically integrated timber processors. Three strategic archetypes dominate: manufacturing-scale leaders commanding distribution breadth, design-forward mills capturing architect-specified projects, and upstream-integrated players controlling veneer supply chains. Competitive moves concentrate on portfolio diversification into installation systems and geographic expansion into underpenetrated western provinces.
Among manufacturing-scale leaders, Power Dekor occupies a position exemplifying production breadth across eastern provinces, while Elegant Living represents the design-specialist archetype through contemporary collection positioning. Kentier anchors the upstream-control segment via captive timber sourcing arrangements. These three patterns illustrate how competitive differentiation maps onto margin-tier stratification rather than pure scale competition.
| Leading Market Players |
|---|
| Lianfeng |
| Elegant Living |
| Kentier |
| Nature Wood |
| Gaopai Wood |
| Power Dekor |
| Gloria Floor |
| Yangzi Flooring |
| Anxin Flooring |
| Others |
Pricing and Supply Chain Analysis
Baltic birch plywood import price volatility cascades through Jiangsu and Zhejiang manufacturing clusters, compressing margins on stratified products while pushing premium tripled-layered tiers toward timber-sourcing premiums that reward captive supply arrangements.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates tripled-layered urban renewal specifications from multi-layered western China developer bids and HDF-core commercial fit-outs. Certification grade under GB standards and volume scale in Yangtze River Delta procurement contracts drive price differentiation. Cost compression in stratified tiers is intensifying because Southeast Asian veneer export restrictions elevate input costs. Economy-grade buyers in commercial and industrial segments exhibit highest price sensitivity, while premium residential renovators in Shanghai absorb thicker wear-layer premiums.
Supply Chain Analysis
Skilled press-operator scarcity in Changzhou and Suzhou industrial zones constrains throughput expansion just as water-based UV curing retooling demands specialized technical labor. Manufacturing concentrates in China, with hardwood veneer sourcing tethered to Southeast Asia and Baltic states. Raw material dependencies span birch plywood cores, oak and walnut veneers, and soy-based adhesive formulations. Single-source vulnerability runs through Baltic birch supply chains disrupted by export licensing shifts. Distribution runs through Shanghai and Hangzhou specification platforms that bundle underlayment and trim for high-rise renovation contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where MIIT green building directives and GB formaldehyde standards continuously elevate compliant product premiums, accelerating replacement demand in certified low-emission tiers.
For Market Incumbents: Cement dominance in eastern province distribution by acquiring click-lock installation training networks before contractor labor scarcity worsens. Lock architect specification relationships through digital platform integration that embeds product selection into project planning software. Defensive consolidation should prioritize captive timber sourcing arrangements that insulate against Baltic birch volatility, while certification investment in MEE environmental compliance secures access to public housing renovation tenders. For New Entrants and Emerging Players: The premium-to-economy price-point gap in Chengdu and Xi'an metro areas offers whitespace for mid-tier multi-layered positioning without confronting Power Dekor's eastern scale. Target western China hospitality fit-outs where provincial green building codes recalibrate specifications toward certified products. A designer-centric go-to-market angle through contemporary collection positioning can bypass entrenched distributor relationships that favor incumbent manufacturing-scale players. For Investors and Strategic Acquirers: Asymmetric upside sits with upstream-integrated specialists controlling veneer supply chains amid Baltic sourcing disruptions. Long-term viability over a five-to-ten-year window favors mills with in-house timber arrangements and water-based UV curing capacity already deployed. Acquisition targets should demonstrate dual GB and MEE certification readiness. The signal to watch is MIIT policy acceleration toward stricter green building material mandates that would disqualify non-compliant inventory.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Timber Sourcing | Captive veneer supply from Southeast Asia insulates margin compression from export restriction volatility. |
| Water-Based UV Curing Transition | Jiangsu mills adopting these systems maintain throughput while satisfying SAMR volatile organic compound limits. |
| Click-Lock Installation Training Networks | Contractor skill scarcity in Zhejiang creates first-mover advantage in rapid-deployment specification. |
| Digital Architect Platform Integration | Software embedding locks product selection into Shanghai and Hangzhou project planning phases. |
| Western China Distribution Expansion | Chengdu and Xi'an whitespace offers mid-tier volume without confronting eastern incumbent scale. |
Research Methodology
Multiple input streams — mill production data, customs import records, and provincial green building code filings — were reconciled through bottom-up and top-down triangulation. Primary interviews with plant managers at Jiangsu and Zhejiang manufacturing clusters, procurement leads at Shanghai residential developers, and contractor network heads in Hangzhou renovation markets informed operational dynamics. Secondary validation drew from SAMR GB standard documentation, MIIT industrial policy directives, MEE environmental compliance filings, and Yangtze River Delta urban renewal policy announcements.
Data-stream reconciliation across supply-side capacity assessments and demand-side project pipelines anchored the analytical framework over the projection horizon. Segmentation dimensions modeled include product architecture by layer count, installation methodology, end-use application, and design style tier. CAGRs were derived from reconciling production volume trajectories with provincial construction permit data and green building certification trends. Industry-specific forecast inputs incorporated adhesive formulation retooling timelines and click-lock penetration rates in new residential construction.
Caveats apply where Baltic birch export licensing shifts, MIIT policy acceleration timelines, or contractor training program scale could materially shift the outlook. Forecasts reflect assumptions about continued urban renewal policy execution in tier-one cities and stable Southeast Asian hardwood veneer trade flows. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
Global Floor Covering Market
Flooring, Carpets, and Rugs
India Carpets and Rugs Market
Flooring, Carpets, and Rugs
Wood Plastic Composite (WPC) Floorings Market
Flooring, Carpets, and Rugs
Bath Rugs and Mats Market
Flooring, Carpets, and Rugs
China Laminate Flooring Market
Flooring, Carpets, and Rugs
Europe Carpet and Rugs Market
Flooring, Carpets, and Rugs
Japan Floor Covering Market
Flooring, Carpets, and Rugs
Lightweight Acoustic Floor Systems Market
Flooring, Carpets, and Rugs
Asia Pacific Flooring Market
Flooring, Carpets, and Rugs
Luxury Vinyl Tiles Market
Flooring, Carpets, and Rugs
Europe Carpet Tile Market
Flooring, Carpets, and Rugs
Australia & New Zealand Flooring Market
Flooring, Carpets, and Rugs
Foam Flooring Products Market
Flooring, Carpets, and Rugs
India Wood Flooring Market
Flooring, Carpets, and Rugs
Europe Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Global Flooring and Carpet Market