
 Wireless Temperature Sensor Market | 2026-2036
Wireless Temperature Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless Temperature Sensor Market Intelligence
The balance of end-use applications for wireless temperature sensors is shifting from mature HVAC regulation towards smart agriculture and environmental monitoring. Honeywell International Inc. leverages its deep entrenchment in building automation to defend its position. Siemens AG competes across a wide industrial portfolio, integrating sensors into its digital factory solutions. Meanwhile, Texas Instruments Inc. specializes in the underlying semiconductor components that enable these diverse applications.
A wireless temperature sensor is a device that measures thermal conditions and transmits data without physical connections, often achieving accuracies better than ±0.5°C. Its primary purpose is to enable remote, real-time environmental monitoring for quality control and operational efficiency. While Wi-Fi remains prevalent, technologies like Bluetooth Low Energy and LoRaWAN are expanding for low-power, long-range deployments. Cold chain monitoring and food safety applications command premium value due to strict compliance requirements.
Regulatory frameworks from bodies like the US FDA and the European Medicines Agency (EMA) create non-negotiable demand for validated temperature logging in pharmaceutical supply chains. Similarly, food safety standards under the WHO and local authorities mandate continuous monitoring. The critical decision for end-users now involves balancing sensor cost and battery longevity against the increasing need for robust data security and network interoperability.
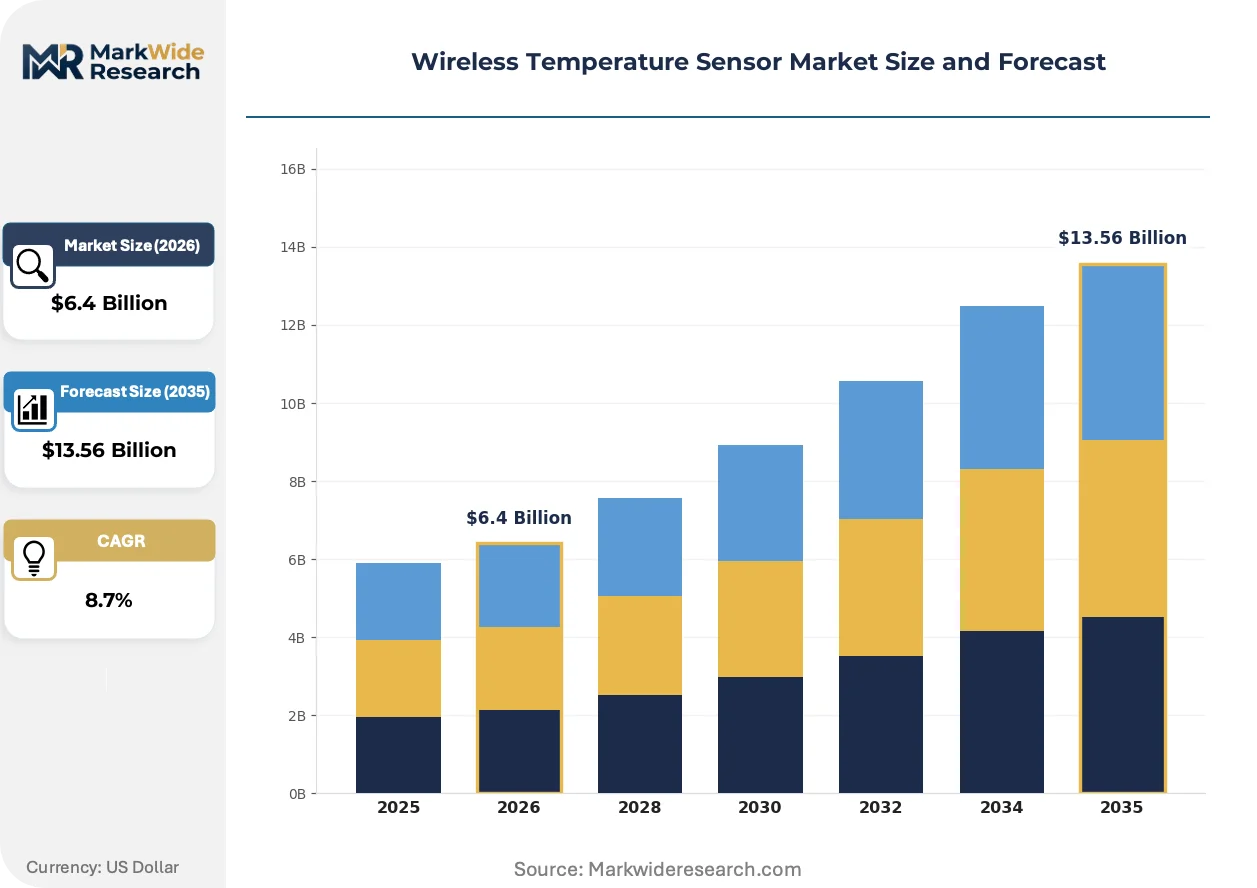
Market Dynamics
The central force shaping the market is the codification of temperature monitoring into non-negotiable regulatory mandates. Frameworks like the EU's Medical Device Regulation (MDR) and food safety standards from the WHO create inelastic demand for validated, high-accuracy sensors in critical supply chains.
Growth Catalysts
- Regulatory Mandates:The EU's Medical Device Regulation (MDR) and similar rules from the US FDA create compulsory demand for precise, auditable temperature logging in pharmaceutical and medical device logistics.
- Technology Proliferation:The expansion of LoRaWAN and other low-power, wide-area networks (LPWAN) enables cost-effective, large-scale deployments in smart agriculture and environmental monitoring across vast geographies.
- Industrial Modernization:Demand for stringent thermal control within advanced electronics and semiconductor fabrication clusters in South Korea and Taiwan accelerates sensor adoption for process quality assurance.
Market Restraints
- Battery Life Limitations:The finite lifespan of batteries in wireless sensors, particularly in applications requiring frequent data transmission, imposes significant operational burdens and total cost of ownership challenges.
- High Validation Costs:The expense associated with certifying sensors for medical or pharmaceutical use, meeting standards from bodies like the EMA, creates a high barrier for new entrants and raises end-user costs.
- Network Interoperability:A lack of universal communication protocols between different manufacturers' systems can lead to vendor lock-in and complicate integration into a unified enterprise monitoring platform.
Strategic Opportunities
- Smart Agriculture Expansion:There is significant opportunity in deploying sensor networks for soil and crop temperature monitoring in emerging agricultural economies like Brazil and Vietnam to improve yields and water management.
- Wearable Health Monitoring:Integrating miniature temperature sensors into smart textiles and wearable devices opens new applications in remote patient monitoring and occupational safety, tracking core body temperature.
- Service Model Innovation:Shifting from a hardware sales model to a subscription-based "Monitoring-as-a-Service" (MaaS) offering, bundling sensors with data analytics and compliance reporting, provides a recurring revenue stream.
Industry Challenges
- Data Security Vulnerabilities:Ensuring the security of data transmitted wirelessly is a major challenge, as a breach could compromise sensitive patient information under HIPAA or falsify compliance logs for food safety.
- Legacy System Integration:End-users face significant complexity and cost when attempting to integrate modern wireless sensor networks with older, proprietary building management systems or industrial control infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless Temperature Sensor Market |
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $13.56 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Battery-Powered, Energy Harvesting, Wired, Hybrid, Self-Powered Technology: Bluetooth Low Energy, Zigbee, LoRaWAN, Wi-Fi, NB-IoT, Thread Application: Cold Chain Monitoring, HVAC Regulation, Food Safety, Smart Agriculture, Electronics Manufacturing, Environmental Monitoring End User: Pharmaceutical Companies, Food Distributors, Agricultural Enterprises, Electronics Manufacturers, Environmental Agencies |
| Companies Covered | Honeywell International Inc., Siemens AG, Emerson Electric Co., Schneider Electric SE, ABB Ltd, Texas Instruments Inc., TE Connectivity, Microchip Technology Inc., Yokogawa Electric Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless Temperature Sensor Market Strategic Shifts & Innovations
The market's evolution is defined by a move away from selling discrete hardware components toward providing integrated data platforms that deliver compliance and operational intelligence. This shift transforms sensors from simple measurement tools into critical nodes of digital enterprise systems.
Multi-protocol System-on-Chip (SoC) solutions are becoming a dominant product architecture. These integrated circuits combine Bluetooth Low Energy, Wi-Fi, and LoRaWAN capabilities onto a single piece of silicon. Industrial automation and medical device OEMs are rapidly adopting these SoCs to build more versatile and future-proof products. This development is consolidating the fragmented connectivity hardware market into fewer, more powerful platforms.
European Union regulations, particularly the F-Gas Regulation and energy efficiency directives, are compelling a greater focus on precise temperature control in HVAC and refrigeration. The rules mandate stricter leak detection and performance monitoring, directly driving investment in wireless sensor networks for continuous oversight. Commercial building management and industrial refrigeration segments are most impacted, upgrading systems to meet new compliance thresholds.
A notable behavioral change is the move toward full-stack solution procurement over discrete component purchasing. End-users in cold chain logistics increasingly prefer single-vendor platforms that bundle validated sensors, cloud software, and automated reporting for regulatory bodies like the EMA or FDA. This trend is most advanced in North America and Europe, where the cost of compliance failure is exceptionally high.
Wireless Temperature Sensor Market Segmentation
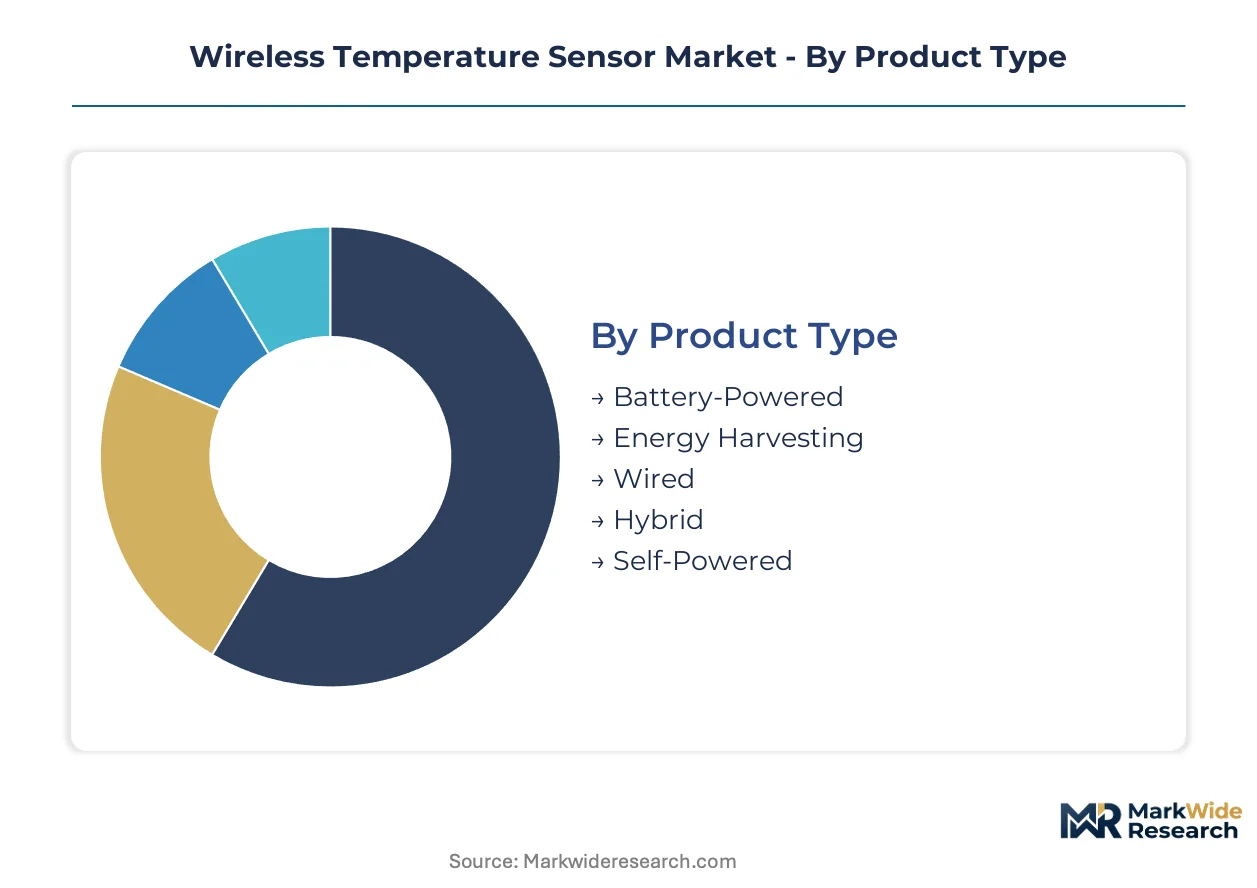
Wireless temperature sensor market segmentation reveals critical distinctions in product design, connectivity protocols, and end-use applications. Understanding these divisions helps stakeholders identify areas of concentrated demand and emerging technological preferences. This granular view informs strategic product development and market entry decisions.
Product Type:
Supply concentration in product type often dictates manufacturing complexity and component sourcing strategies for wireless temperature sensors.
- Battery-Powered:These sensors rely on internal batteries for operation, offering portability and ease of deployment in various environments. Demand concentrates within cold chain logistics and remote environmental monitoring, where consistent power access is challenging.
- Energy Harvesting:These devices capture ambient energy sources like solar, thermal, or kinetic to power operations, significantly extending lifespan without battery replacement. Smart agriculture and industrial IoT deployments increasingly adopt this type to reduce maintenance costs.
- Wired:These sensors maintain a physical connection for power and data transmission, ensuring reliability in fixed installations.
- Hybrid:Hybrid sensors combine both wired and wireless capabilities, offering flexibility for specific industrial automation setups.
- Self-Powered:These sensors generate their own power from the measured environment, suitable for niche applications requiring extreme autonomy.
Today's leader: Battery-Powered. Tomorrow's challenger: Energy Harvesting.
Technology:
Technology choices for wireless temperature sensors are driven by specific application requirements for range, power consumption, and data throughput.
- LoRaWAN:This low-power, wide-area network protocol enables long-range communication with minimal energy consumption, ideal for vast outdoor deployments. Smart agriculture and environmental monitoring across large geographies heavily utilize LoRaWAN for cost-effective data collection.
- Wi-Fi:Wi-Fi connectivity offers high bandwidth and integration with existing network infrastructure, suitable for indoor applications requiring frequent data updates. Commercial building management systems and electronics manufacturing facilities often prefer Wi-Fi for its robust data transfer capabilities.
- Bluetooth Low Energy:This short-range protocol provides efficient data transfer for personal health monitoring and localized industrial applications.
- Zigbee:Zigbee offers low-power mesh networking for smart home devices and building automation systems requiring reliable local communication.
- NB-IoT:Narrowband Internet of Things (NB-IoT) supports low-power, wide-area cellular connectivity for remote asset tracking and utility metering.
- Thread:Thread is an IP-based mesh networking protocol designed for smart home devices, offering secure and reliable connectivity.
The segment expanding most quickly is LoRaWAN, driven by its suitability for vast, low-power deployments.
Application:
The cost tier for wireless temperature sensor applications varies significantly, influenced by regulatory compliance and data criticality.
- Cold Chain Monitoring:This application demands precise, validated temperature logging for perishable goods, particularly pharmaceuticals and biologics, throughout their transport and storage. Stringent regulatory mandates from the US FDA and EMA create inelastic demand for high-accuracy solutions.
- Food Safety:Continuous temperature monitoring in food processing, storage, and distribution prevents spoilage and ensures public health compliance. Global standards from the WHO and local authorities drive the adoption of validated sensors to maintain product integrity.
- HVAC Regulation:This involves optimizing building climate control for energy efficiency and occupant comfort in commercial and residential settings.
- Smart Agriculture:Sensors monitor soil, air, and crop temperatures to optimize irrigation, pest control, and harvest timing for improved yields.
- Electronics Manufacturing:Precise thermal control during semiconductor fabrication and assembly processes ensures product quality and prevents defects.
- Environmental Monitoring:This application tracks ambient temperatures in natural habitats, urban areas, and industrial sites for climate research or pollution control.
Future growth will increasingly stem from Smart Agriculture as technology proliferation enables wider adoption in emerging economies.
End User:
End-user segmentation highlights distinct customer types with varying procurement patterns and compliance requirements for wireless temperature sensors.
- Pharmaceutical Companies:These entities require validated wireless temperature sensors for critical monitoring of drug storage, manufacturing, and logistics. Compliance with regulations like the EU MDR and US FDA mandates drives demand for integrated data platforms and auditable solutions.
- Food Distributors:These businesses utilize sensors to maintain optimal temperatures across their supply chains, from warehouses to retail, preventing spoilage and ensuring product freshness. Food safety standards from entities like the WHO compel investment in reliable, real-time monitoring.
- Agricultural Enterprises:These users deploy sensors for precision farming, monitoring conditions to optimize crop growth and livestock health.
- Electronics Manufacturers:These companies integrate sensors into their production lines for process control and quality assurance in sensitive environments.
- Environmental Agencies:These bodies use sensors for long-term data collection in ecological studies, climate monitoring, and pollution assessment.
The segment with the steepest expansion trajectory is Agricultural Enterprises, driven by the need for data-driven farming practices.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage drives shifts in wireless temperature sensor manufacturing, as companies seek to balance compliance costs with operational efficiency. Strict mandates in developed economies contrast with opportunities for lower-cost production and market entry elsewhere. This dynamic reshapes investment flows and demand concentrations globally.
United States
Demand for validated sensors in pharmaceuticals and food safety drives the US market. The US FDA mandates precise temperature logging for drug supply chains, ensuring product integrity. Major pharmaceutical clusters in New Jersey and biotechnology hubs in California accelerate sensor adoption.
Germany
European industrial modernization and strict environmental regulations create demand for advanced thermal monitoring in Germany. The EU's F-Gas Regulation compels precise temperature control in HVAC and refrigeration systems. Industrial automation centers in Bavaria integrate sensors into smart factory solutions.
South Korea
Advanced electronics and semiconductor manufacturing propel sensor demand in South Korea. The country's strict quality assurance standards for high-tech components necessitate continuous thermal monitoring. Major fabrication clusters in Gyeonggi Province require integrated sensor solutions for process control.
Brazil
Agricultural modernization and cold chain expansion are significant demand drivers in Brazil. The national food safety agency, ANVISA, influences temperature monitoring practices for perishable goods. Large-scale agricultural operations in Mato Grosso adopt sensors for precision farming.
Vietnam
Emerging smart agriculture initiatives and growing food processing industries boost sensor adoption in Vietnam. The country's agricultural policies encourage technology integration for improved crop yields. Technology parks in Ho Chi Minh City develop solutions for localized environmental monitoring.
Wireless Temperature Sensor Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, influencing the competitive structure of the wireless temperature sensor market. The market exhibits a tiered structure, with established industrial giants alongside niche technology providers. Strategic archetypes include diversified industrial conglomerates and specialized component manufacturers. Companies pursue portfolio diversification and strategic partnerships to expand their market reach.
Diversified industrial conglomerates like Germany-based Siemens AG and US-based Honeywell International Inc. occupy positions across numerous industrial and building automation sectors. These entities leverage extensive existing infrastructure and client relationships to integrate wireless temperature sensing solutions. Conversely, US-based Texas Instruments Inc. represents a specialized archetype, focusing on the underlying semiconductor components that enable these diverse applications. This distinct specialization allows Texas Instruments to anchor the foundational technology layer for many end products.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Siemens AG |
| Emerson Electric Co. |
| Schneider Electric SE |
| ABB Ltd |
| Texas Instruments Inc. |
| TE Connectivity |
| Microchip Technology Inc. |
| Yokogawa Electric Corporation |
| Others |
Cost & Logistics Intelligence
EU Medical Device Regulation mandates for precise temperature logging gate qualified sensor supply and drive premium pricing for compliant solutions. These stringent requirements ensure product integrity for sensitive medical products, impacting overall cost structures.
Pricing Analysis
Distributor margins significantly influence the final cost of wireless temperature sensors. The market primarily operates on a project-based pricing model for initial deployments, transitioning to subscription-based services for ongoing data and compliance reporting. Price differentiation stems from the sensor's certification level for regulatory bodies like the FDA or EMA, and the extent of bundled after-sales data analytics. Pricing softness impacts basic, uncertified sensors due to commoditization, while pharmaceutical companies exhibit the lowest price sensitivity for validated solutions, contrasting with higher sensitivity among agricultural enterprises.
Supply Chain Analysis
Domestic content mandates, driven by stringent regulatory validation requirements, influence sourcing decisions for wireless temperature sensors. Supply concentration for critical semiconductor components centers in South Korea and Taiwan, with broader electronic component manufacturing prevalent in China. The market relies heavily on specialized semiconductor components and high-performance battery cells, creating single-source vulnerability for advanced multi-protocol System-on-Chip solutions. Distribution runs through direct-to-OEM channels for major industrial integrators and value-added resellers serving diverse end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wireless temperature sensor market is transitioning into a late-cycle quality story, driven by a demand shift towards premium, validated full-stack solutions. End-users increasingly prioritize integrated platforms that guarantee regulatory compliance and robust data security.
For Market Incumbents: To counter the commoditization of basic sensor hardware, market incumbents must deepen the integration of wireless temperature sensors into their established digital factory and building automation platforms. They should invest heavily in certification for critical regulatory bodies like the FDA and EMA, ensuring compliance with evolving mandates. This defensive strategy leverages existing client relationships and extensive infrastructure, differentiating premium offerings through validated data integrity and comprehensive service bundles.
For New Entrants and Emerging Players: Launch via a 'Monitoring-as-a-Service' (MaaS) model, new entrants can target underserved segments like smart agriculture in emerging economies such as Brazil. This approach bundles low-cost LoRaWAN sensors with data analytics, overcoming high upfront hardware costs. Focus on providing validated solutions for specific crop types or livestock monitoring, building trust through outcome-based pricing rather than discrete hardware sales. Wearable health monitoring also presents a white-space opportunity for specialized, miniature sensor integration.
For Investors and Strategic Acquirers: Roll-up economics work for specialized sensor manufacturers because of the fragmented market for niche applications and the high cost of regulatory validation. Long-term viability in this market is strong, anchored by non-negotiable compliance mandates in cold chain and pharmaceutical logistics. Investors should seek acquisition targets specializing in energy harvesting technology or full-stack MaaS providers with robust data security intellectual property. The consolidation of multi-protocol System-on-Chip providers will be a critical signal to watch for market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration with Building Automation | Honeywell and Siemens can leverage existing infrastructure, enhancing value proposition for commercial building management. |
| Monitoring-as-a-Service (MaaS) Offering | New entrants can lower adoption barriers for agricultural enterprises by bundling sensors with data analytics and compliance reporting. |
| LoRaWAN Technology Specialization | Focusing on LoRaWAN enables cost-effective, long-range deployments crucial for smart agriculture in vast geographies like Brazil. |
| Investment in Regulatory Compliance | Ensuring FDA and EMA validation for sensors unlocks premium value in pharmaceutical cold chain monitoring applications. |
| Energy Harvesting R&D | Developing self-powered sensors reduces battery life limitations, significantly cutting maintenance costs in remote environmental monitoring. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary insights with robust secondary validation. Primary data collection involved discussions with pharmaceutical R&D leads, food safety compliance officers, electronics manufacturing plant managers, and agricultural technology specialists. Secondary research leveraged US FDA filings, EMA guidelines, WHO food safety standards, and national electronics industry reports, enabling bottom-up sizing and top-down validation.
The forecast modeling was anchored by comparable historical reference periods, establishing a baseline for future projections across the analysis window. The analytical framework segmented the market across Product Type, Technology, Application, End User, and Regional Regulatory Cluster. Compound Annual Growth Rates were calculated by assessing historical trends and projected market drivers. Key forecast inputs included regulatory mandate enforcement rates and adoption curves for new LPWAN technologies.
Forecast precision tightens around the base case; tail outcomes carry wider variance under unforeseen regulatory changes or rapid technological obsolescence. These forecasts reflect documented assumptions regarding market dynamics and global supply chain stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Gyro Sensors Market
Sensors and Controls
Middle East and Africa Temperature Sensors Market
Sensors and Controls
Smart Condition Monitoring Market
Sensors and Controls
Middle East and Africa Wearable Sensors Market
Sensors and Controls
Temperature Controller Market
Sensors and Controls
Ingestible Sensor Market
Sensors and Controls
Clamp-On Ultrasonic Gas Flow Meter Market
Sensors and Controls
Differential Pressure Sensor Market
Sensors and Controls
Proximity Sensors Market
Sensors and Controls
Pressure Sensor Market
Sensors and Controls
Biopotential Sensor Market
Sensors and Controls
Global Tactile Sensor Market
Sensors and Controls
Thermo Hygrometer Market
Sensors and Controls
Air Flow Monitoring System Market
Sensors and Controls
Europe Water Detection Sensors Market
Sensors and Controls
Active Vibration Control Market