
 Air Flow Monitoring System Market | 2026-2036
Air Flow Monitoring System Market Size, Share, and Industry Trends Forecast 2026-2036
Air Flow Monitoring System Market Outlook
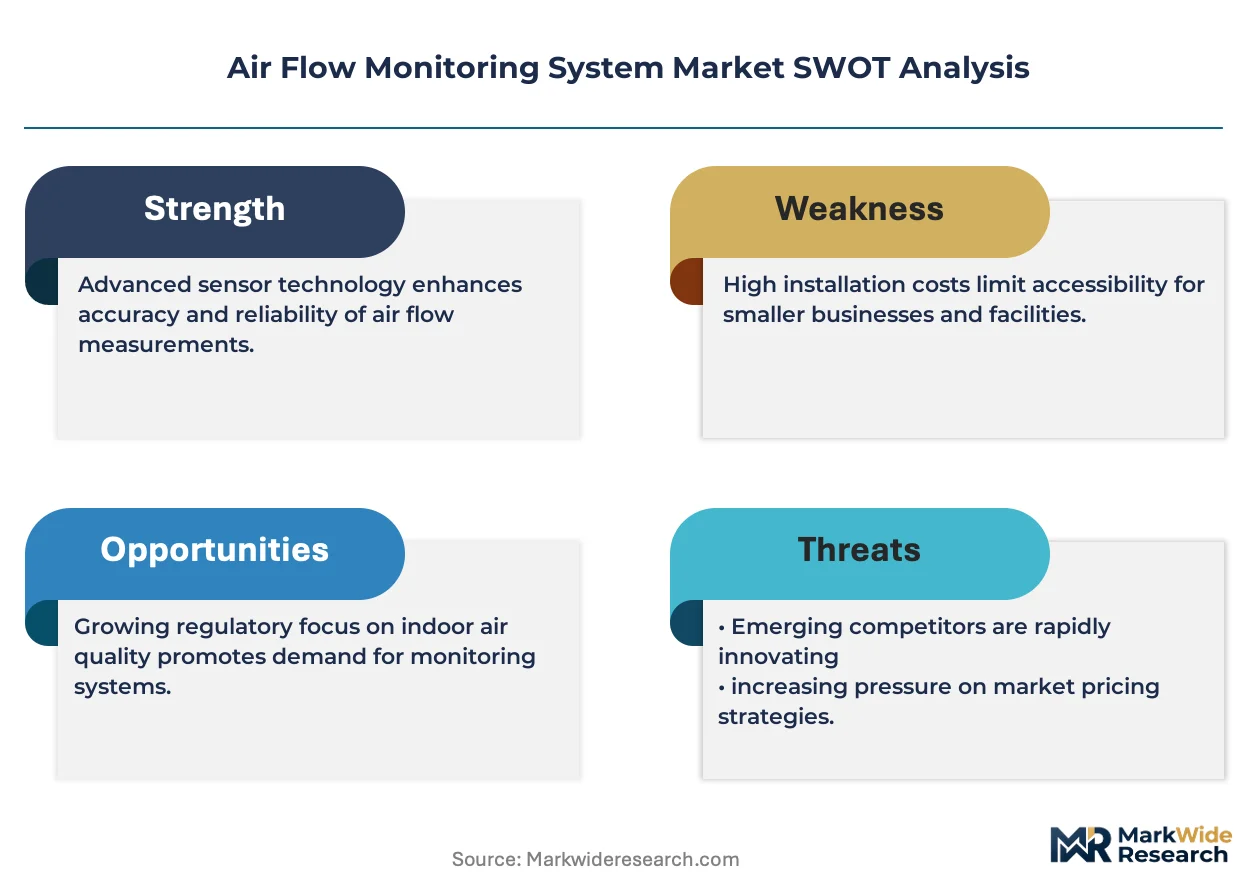
Healthcare facilities are reorganizing their capital allocation toward continuous environmental monitoring, pulling investment away from periodic manual audits. TSI Incorporated leverages its R&D intensity in particle measurement to anchor premium positioning in pharmaceutical cleanroom applications. Siemens competes through building automation integration, extending its controls portfolio into unified air management platforms.
An air flow monitoring system measures velocity, volume, or differential pressure across ductwork and ambient spaces using sensors calibrated to detect deviations as small as 0.01 inches of water column. These systems serve primarily to maintain indoor air quality, optimize energy consumption in HVAC networks, and ensure containment integrity in critical environments. Fixed sensors dominate installed base value due to permanent infrastructure integration in commercial buildings, while software solutions capture expanding margin pools through predictive analytics and remote diagnostics. Thermal technology leads in HVAC applications for its cost efficiency, though ultrasonic methods gain traction where non-intrusive measurement preserves ductwork integrity in heritage or sterile facilities.
The EPA enforces National Ambient Air Quality Standards that mandate continuous emissions monitoring in industrial zones, directly expanding demand for calibrated flow instrumentation. ASHRAE publishes ventilation guidelines that healthcare architects must incorporate, tightening sensor density requirements in operating suites and isolation rooms. OSHA workplace exposure limits for airborne contaminants further compel industrial end users to deploy real-time monitoring rather than reliance on spot measurements. Stakeholders must weigh the capital cost of sensor densification against the operational risk of compliance failure in an enforcement environment where penalties escalate with violation duration.
Market Dynamics
ASHRAE 170 updates and EPA Clean Air Act enforcement are compressing compliance timelines, forcing healthcare and industrial facilities to replace periodic manual audits with continuous sensor networks that demand permanent infrastructure investment rather than disposable instrumentation.
Growth Catalysts
- Healthcare ventilation mandates:ASHRAE 170 revisions tighten sensor density requirements in US operating suites and isolation rooms, compelling hospitals to install differential pressure monitors with real-time alarming.
- Industrial emissions enforcement:The EPA's National Ambient Air Quality Standards mandate continuous monitoring in heavy manufacturing zones, directly expanding demand for calibrated thermal and ultrasonic flow instrumentation.
- Energy efficiency retrofits:Germany's industrial facility certification programs accelerate fixed sensor deployment for HVAC optimization, pulling capital toward permanent infrastructure over portable alternatives.
Market Restraints
- Sensor calibration costs:Annual recertification requirements for 0.01-inch water column accuracy impose recurring operational burdens that offset hardware depreciation schedules.
- Semiconductor input volatility:MEMS thermal sensor chip supply concentrates in East Asian foundries, exposing lead times to geopolitical friction and foundry capacity allocation decisions.
- Wireless substitution pressure:Low-power mesh protocols threaten wired sensor margins by reducing installation labor, though power reliability concerns limit penetration in life-safety applications.
Strategic Opportunities
- Predictive analytics software:Remote diagnostics platforms capture expanding margin pools by converting sensor data into HVAC failure forecasting, shifting revenue from hardware to recurring subscriptions.
- Heritage building preservation:Non-intrusive ultrasonic methods gain traction where ductwork integrity constraints prohibit thermal probe insertion, opening sterile facility and historic infrastructure segments.
- Pharmaceutical cleanroom expansion:US and German facilities reorganize capital allocation toward continuous environmental monitoring, creating pull-through demand for integrated particle and flow verification systems.
Industry Challenges
- Metrology talent scarcity:Calibration technicians with traceable NIST standards expertise command premium wages, constraining service network expansion for distributed sensor deployments.
- Legacy BAS integration:BACnet and Modbus protocol fragmentation forces custom middleware development, extending commissioning timelines and eroding project margins.
- Certification timeline compression:FDA and EPA audit windows for pharmaceutical and industrial facilities shrink below 90 days, requiring pre-staged sensor documentation that strains documentation workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Flow Monitoring System Market |
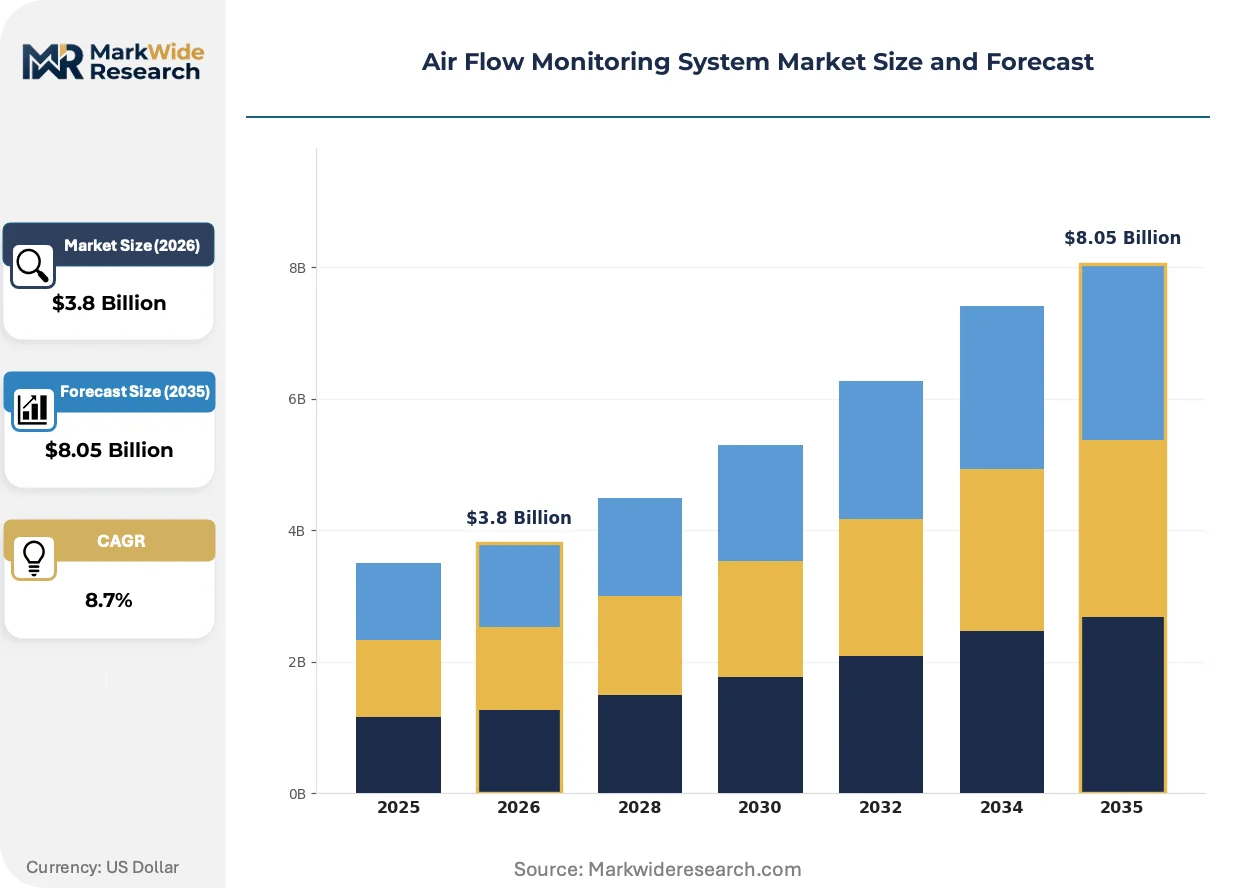
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Sensors, Portable Meters, Software Solutions, Data Loggers Technology: Ultrasonic, Thermal, Differential Pressure, Electromagnetic End User: Industrial, Commercial, Healthcare, HVAC Application: Ventilation Control, Building Management, Environmental Monitoring, Process Optimization |
| Companies Covered | TSI Incorporated, Setra Systems, Vaisala, Honeywell, Siemens, Emerson, Dwyer Instruments, Schneider Electric, Testo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Flow Monitoring System Market Strategic Shifts
Sensor architecture is bifurcating between cost-optimized thermal mass flow for commodity HVAC and precision ultrasonic platforms for regulated environments, with software analytics emerging as the primary value capture mechanism across both tiers.
Thermal anemometry dominates HVAC retrofit volume through cost efficiency at standard accuracy thresholds, yet ultrasonic time-of-flight methods capture specification-driven pharmaceutical and heritage building projects where non-intrusive installation preserves ductwork integrity. Adoption is accelerating among German industrial energy auditors and US hospital facilities managers who face simultaneous pressure for measurement reliability and infrastructure preservation. The technology base is bifurcating the vendor landscape into distinct premium and standard tiers with incompatible service models and margin structures.
The EPA's Clean Air Act enforcement escalation and ASHRAE 170-2021 ventilation updates impose simultaneous compliance obligations on overlapping facility portfolios, particularly acute for US healthcare systems operating surgical suites and airborne infection isolation rooms. Industrial consequence includes mandatory continuous emissions monitoring with documented calibration chains, displacing spot measurement protocols that previously satisfied audit requirements. Pharmaceutical cleanrooms and metropolitan hospital districts represent the most affected segments, responding with capital reallocation toward permanent sensor infrastructure and away from contracted manual verification services.
Facility engineering departments are consolidating vendor relationships under unified building automation platforms, compressing the addressable market for standalone air flow specialists. Siemens and comparable controls integrators capture this consolidation by bundling flow sensors into comprehensive environmental management contracts, while pure-play sensor manufacturers face disintermediation pressure. The shift is most visible in German industrial retrofits and US healthcare capital projects where procurement authority has migrated from departmental engineering to centralized facilities management with enterprise-scale platform preferences.
Air Flow Monitoring System Market Segmentation
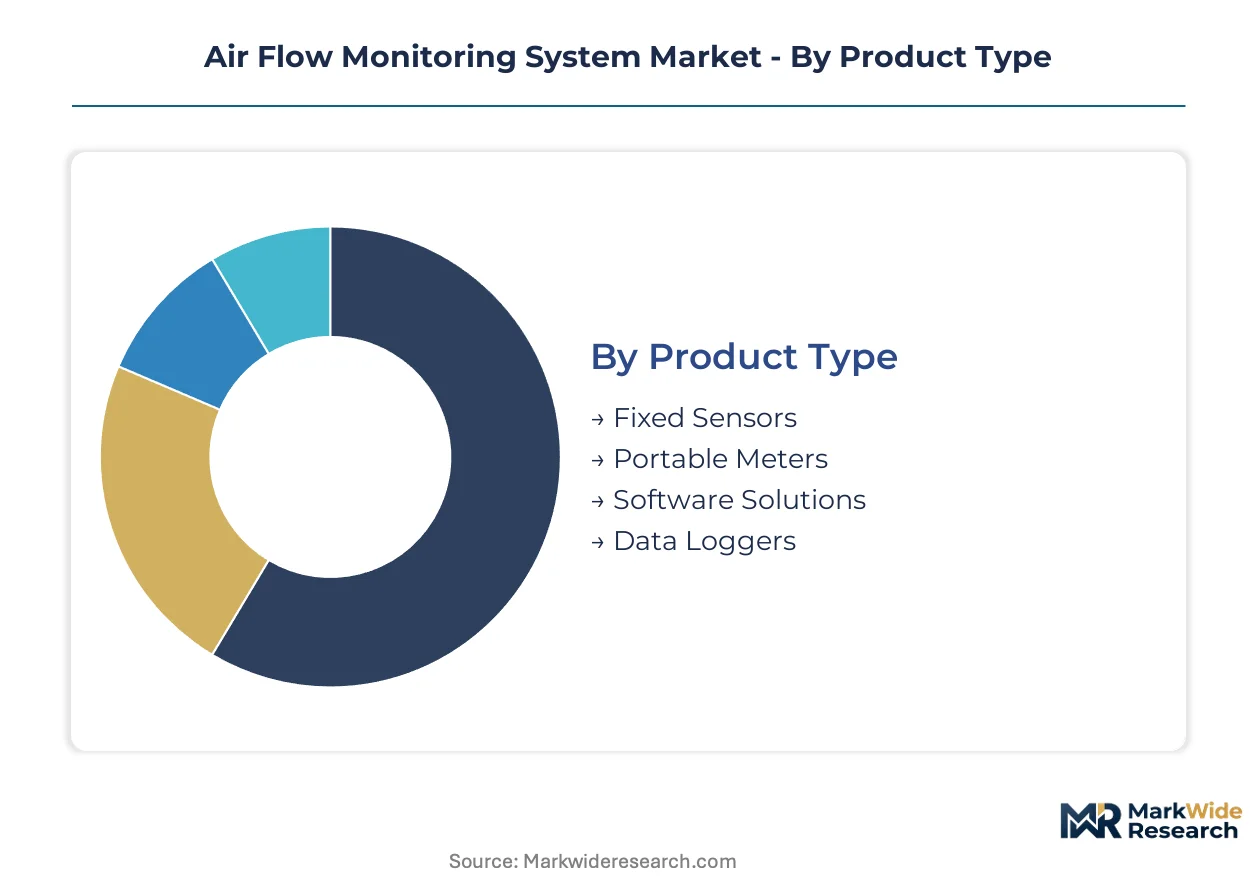
Air flow monitoring systems serve divergent operational requirements across fixed infrastructure, portable fieldwork, and predictive software layers. Channel strategy varies sharply by segment, with permanent sensors flowing through building automation integrators while portable meters and software reach end users through industrial distribution networks.
Product Type:
Fixed sensors move through Siemens and comparable building automation platforms that bundle hardware into enterprise contracts. Portable meters and data loggers reach industrial facilities through specialized instrumentation distributors with calibration service capabilities. Software solutions increasingly deploy via direct subscription models that bypass traditional channel intermediaries entirely.
- Fixed Sensors:Permanent infrastructure components integrate directly into HVAC ductwork and cleanroom architectures with 0.01-inch water column accuracy specifications. Demand concentrates in German industrial retrofits seeking energy efficiency certification, where permanent installation justifies capital allocation over recurring rental expenses.
- Portable Meters:Handheld verification instruments enable spot measurement protocols and commissioning validation without infrastructure modification. Pharmaceutical cleanrooms in the United States deploy these for FDA pre-audit documentation, though procurement is shifting toward continuous monitoring that reduces portable meter utilization.
- Software Solutions:Cloud-based analytics platforms convert sensor data into predictive HVAC failure forecasting and remote diagnostics.
- Data Loggers:Battery-powered recording devices capture time-series flow data for compliance documentation and trend analysis.
Fixed sensors dominate installed base. Software solutions are where expansion concentrates.
Technology:
Technology selection maps directly to cost-performance tiering, with thermal methods saturating standard HVAC applications and ultrasonic platforms commanding specification-driven pharmaceutical and heritage building projects.
- Ultrasonic:Time-of-flight measurement eliminates probe intrusion, preserving ductwork integrity in sterile facilities and historic infrastructure. German energy auditors and US hospital facilities managers specify these where simultaneous measurement reliability and infrastructure preservation requirements apply.
- Thermal:Heated-element anemometry measures cooling effect of air mass flow at lowest hardware cost per measurement point. Commodity HVAC retrofits across commercial building portfolios deploy thermal sensors exclusively, accepting standard accuracy thresholds in exchange for capital efficiency.
- Differential Pressure:Membrane-based sensors detect static pressure variations across filters, dampers, and room envelopes.
- Electromagnetic:Faraday induction principles enable non-intrusive flow measurement in conductive fluid applications with minimal pressure drop.
Thermal technology anchors volume deployment. Ultrasonic methods capture the steepest expansion trajectory in regulated environments.
End User:
End user segmentation reveals divergent procurement authority patterns, with healthcare and HVAC consolidating under centralized facilities management while industrial and commercial segments retain departmental engineering autonomy.
- Healthcare:ASHRAE 170 compliance mandates drive sensor densification in US operating suites and isolation rooms with real-time alarming requirements. Hospital systems reorganize capital allocation toward continuous environmental monitoring, pulling investment from periodic manual audits toward permanent infrastructure.
- Industrial:EPA Clean Air Act enforcement mandates continuous emissions monitoring in heavy manufacturing zones with documented calibration chains. Metal processing and chemical production facilities face the most acute compliance timeline compression.
- Commercial:Office and retail portfolios prioritize energy optimization through building automation integration.
- HVAC:Original equipment manufacturers and service contractors specify flow instrumentation for system commissioning and performance verification.
Healthcare and industrial segments command premium pricing. Commercial deployment scales widest but at compressed margins.
Application:
Application segmentation tracks the operational function hierarchy, from life-safety ventilation control through efficiency-focused building management to regulatory environmental monitoring.
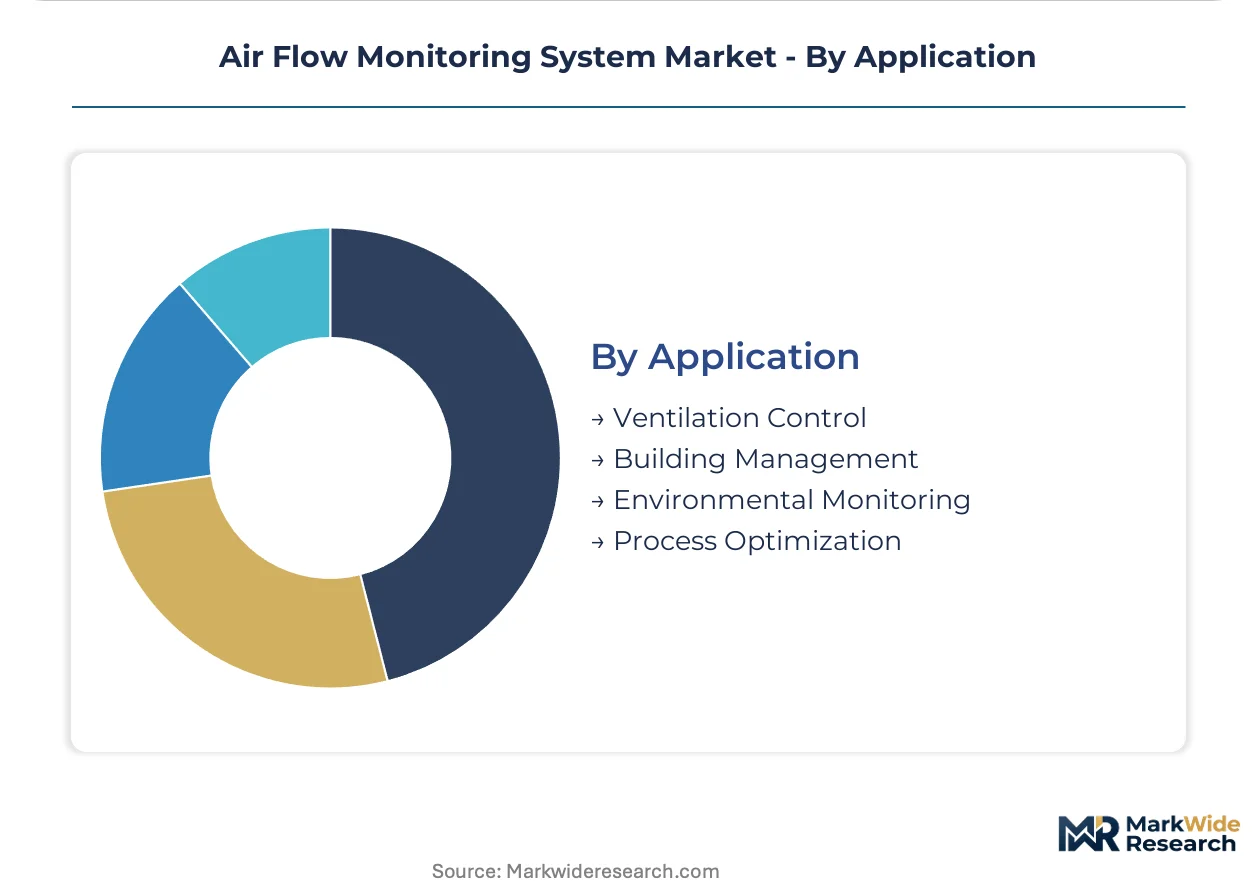
- Ventilation Control:Real-time damper adjustment and fan modulation maintain designed air change rates in critical spaces. Operating suites and pharmaceutical suites depend on these systems for containment integrity with sub-second response to pressure deviations.
- Building Management:Enterprise-wide environmental optimization consolidates HVAC, lighting, and security under unified automation platforms. Siemens and comparable integrators bundle flow sensors into comprehensive contracts that disintermediate standalone sensor vendors.
- Environmental Monitoring:Continuous emissions verification and indoor air quality documentation satisfy EPA and OSHA regulatory exposure limits.
- Process Optimization:Manufacturing throughput enhancement through drying, coating, and thermal process air flow precision.
Ventilation control captures the highest sensor density per square foot. Building management applications are gaining share fastest through platform consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's industrial corridor underwrites Western Europe's calibration infrastructure, while the Texas Gulf Coast petrochemical cluster anchors North American sensor demand. German industrial energy auditors and US hospital facilities managers drive specification intensity across both regions.
United States
Pharmaceutical cleanrooms in Massachusetts and North Carolina expand continuous verification systems. EPA Clean Air Act enforcement mandates documented calibration chains for heavy manufacturing. The Texas Gulf Coast petrochemical corridor deploys differential pressure monitors for containment integrity.
Germany
Industrial facility retrofits for energy efficiency certification accelerate fixed sensor deployment. The country's national environmental regulator tightens emissions monitoring thresholds for metal processing. The Ruhr industrial basin and Bavarian automotive clusters lead HVAC optimization sensor density.
China
Semiconductor foundry construction in Yangtze River Delta cities drives cleanroom air flow instrumentation demand. The national environmental ministry mandates continuous emissions monitoring in designated heavy manufacturing zones. Shanghai and Suzhou pharmaceutical parks specify ultrasonic non-intrusive methods for sterile infrastructure preservation.
Japan
Precision manufacturing facilities in Aichi Prefecture require sub-second pressure deviation response systems. The national industrial standards body updates ventilation guidelines for semiconductor fabrication. The Kansai region's hospital construction pipeline concentrates differential pressure monitor procurement.
India
Active pharmaceutical ingredient manufacturing in Telangana and Gujarat expands environmental monitoring infrastructure. The national pharmaceutical regulator tightens cleanroom compliance documentation requirements. The Mumbai-Pune pharmaceutical corridor reorganizes capital allocation toward permanent sensor networks.
Air Flow Monitoring System Market Competitive Environment
Concentration sits with diversified industrial conglomerates that bundle flow sensors into building automation platforms. The vendor base spans three tiers: precision instrumentation specialists, integrated controls providers, and commodity sensor fabricators. Siemens and comparable conglomerates capture enterprise-scale contracts through unified environmental management offerings. Strategic moves center on building automation integration and predictive analytics software development.
Among precision instrumentation specialists, TSI Incorporated and Setra Systems occupy positions defined by measurement accuracy specialization. Vaisala represents the Nordic environmental instrumentation archetype with meteorological calibration heritage. These three exemplify the premium tier where traceable standards expertise commands pricing power distinct from commodity HVAC alternatives.
| Leading Market Players |
|---|
| TSI Incorporated |
| Setra Systems |
| Vaisala |
| Honeywell |
| Siemens |
| Emerson |
| Dwyer Instruments |
| Schneider Electric |
| Testo |
| Others |
Value Chain & Pricing Dynamics
Ultrasonic time-of-flight sensors displacing thermal anemometry in pharmaceutical and heritage applications simultaneously redraw procurement geography toward German precision manufacturers and compress hardware margins across commodity HVAC tiers. This substitution dynamic forces buyers to recalibrate total-cost-of-ownership models that now weight calibration service density and software attach rates more heavily than unit acquisition price.
Pricing Analysis
Volume-discount tiering structures separate NIST-traceable calibration-grade instrumentation from standard commercial HVAC sensors and economy retrofit units. Price differentiation rests on certification tier and after-sales service bundling, with FDA-audited pharmaceutical facilities absorbing premiums that hospital systems and industrial retrofits resist. Cost compression in the standard tier is intensifying because wireless mesh alternatives reduce installation labor. Healthcare procurement committees demonstrate the highest price sensitivity, while German energy auditors prioritize measurement reliability over unit economics.
Supply Chain Analysis
Inventory lead times for MEMS thermal sensor chips stretch unpredictably because foundry capacity concentrates in Taiwan and South Korea with secondary packaging in China. Raw material dependencies include silicon wafers, platinum sensing elements, and specialized calibration gases. Single-source vulnerability in East Asian semiconductor fabrication exposes lead times to geopolitical friction. Distribution runs through building automation integrators for fixed sensors and industrial instrumentation distributors for portable verification equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software analytics and remote calibration services are expanding faster than hardware shipments, transforming capital equipment vendors into recurring-revenue platforms. This service-attach opportunity rewards manufacturers that pre-integrate predictive maintenance algorithms and subscription diagnostics into sensor deployments.
For Market Incumbents: Secure metrology talent pipelines through accredited technician training programs that lock in service network coverage. Anchor premium positioning by deepening backward integration into MEMS fabrication or captive calibration gas supply, insulating margin structures from semiconductor input volatility. Wireless substitution pressure and platform consolidation by Siemens-type integrators threaten standalone sensor margins.
For New Entrants and Emerging Players: Predictive analytics software layers where incumbents under-serve mid-market hospital systems and regional industrial facilities represent the most penetrable white space. Target Indian pharmaceutical manufacturing corridors where CDSCO compliance documentation requirements are tightening but incumbent service density remains thin. Deploy direct subscription models that bypass traditional distribution markups.
For Investors and Strategic Acquirers: The market sits at a platform-consolidation phase that favors vertically integrated controls providers with software development capabilities. Long-term viability hinges on recurring revenue attachment rates exceeding hardware replacement cycles. Acquisition candidates with NIST-traceable calibration infrastructure and established pharmaceutical cleanroom relationships command scarcity premiums. Monitor EPA enforcement escalation intensity as the inflection signal for compliance-driven sensor densification.
| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Analytics Platform Launch | Converts sensor data into HVAC failure forecasting, shifting revenue from hardware to recurring subscriptions. |
| Calibration Service Network Expansion | Pre-staged NIST-traceable documentation satisfies FDA and EPA audit windows below 90 days. |
| Ultrasonic Product Line Extension | Captures heritage building and sterile facility segments where thermal probe insertion is prohibited. |
| Building Automation Integration Partnership | Bundles flow sensors into Siemens-type enterprise contracts that disintermediate standalone vendors. |
| Backward Integration into MEMS Fabrication | Reduces exposure to Taiwan and South Korea foundry capacity allocation decisions. |
Study Parameters
Initial hypotheses were tested against primary input from facilities management directors, biomedical engineers, pharmaceutical quality assurance leads, and industrial energy auditors, then refined through secondary validation against EPA enforcement databases, ASHRAE guideline publications, FDA warning letter archives, and hospital procurement records. Bottom-up sensor deployment estimates triangulated with top-down HVAC capital spending projections.
Variance-decomposition across product type, technology tier, end-user vertical, and geographic regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate reconciliation with macro HVAC investment patterns. Industry-specific forecast inputs included ASHRAE 170 revision implementation timelines and German energy efficiency certification program enrollment curves.
Underlying assumptions cover continuous emissions monitoring mandate enforcement intensity and MEMS foundry capacity expansion, with deviation risk concentrated in semiconductor supply disruptions and healthcare capital allocation shifts. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Global Fluid Management and Visualization Systems Market
Sensors and Controls
Refrigeration Gauge Market
Sensors and Controls
Automotive Steering Sensors Market
Sensors and Controls
Smart Condition Monitoring Market
Sensors and Controls
Global Wireless Sensors Market
Sensors and Controls
Industrial Sensors Market
Sensors and Controls
Digital Pool Thermometers Market
Sensors and Controls
Position Sensor Market
Sensors and Controls
Smart Pressure Gauge Market
Sensors and Controls
Printed and Flexible Sensors Market
Sensors and Controls
Digital Infrared Thermometer Market
Sensors and Controls
Photonic Sensors and Detectors Market
Sensors and Controls
Global Solid State Lidar Sensor Market
Sensors and Controls
Variable Reluctance Sensor Market
Sensors and Controls
Russia Digital Thermometer Market
Sensors and Controls
Digital Humidity Sensor Market