
 Global Tactile Sensor Market | 2026-2036
Global Tactile Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Global Tactile Sensor Market Outlook
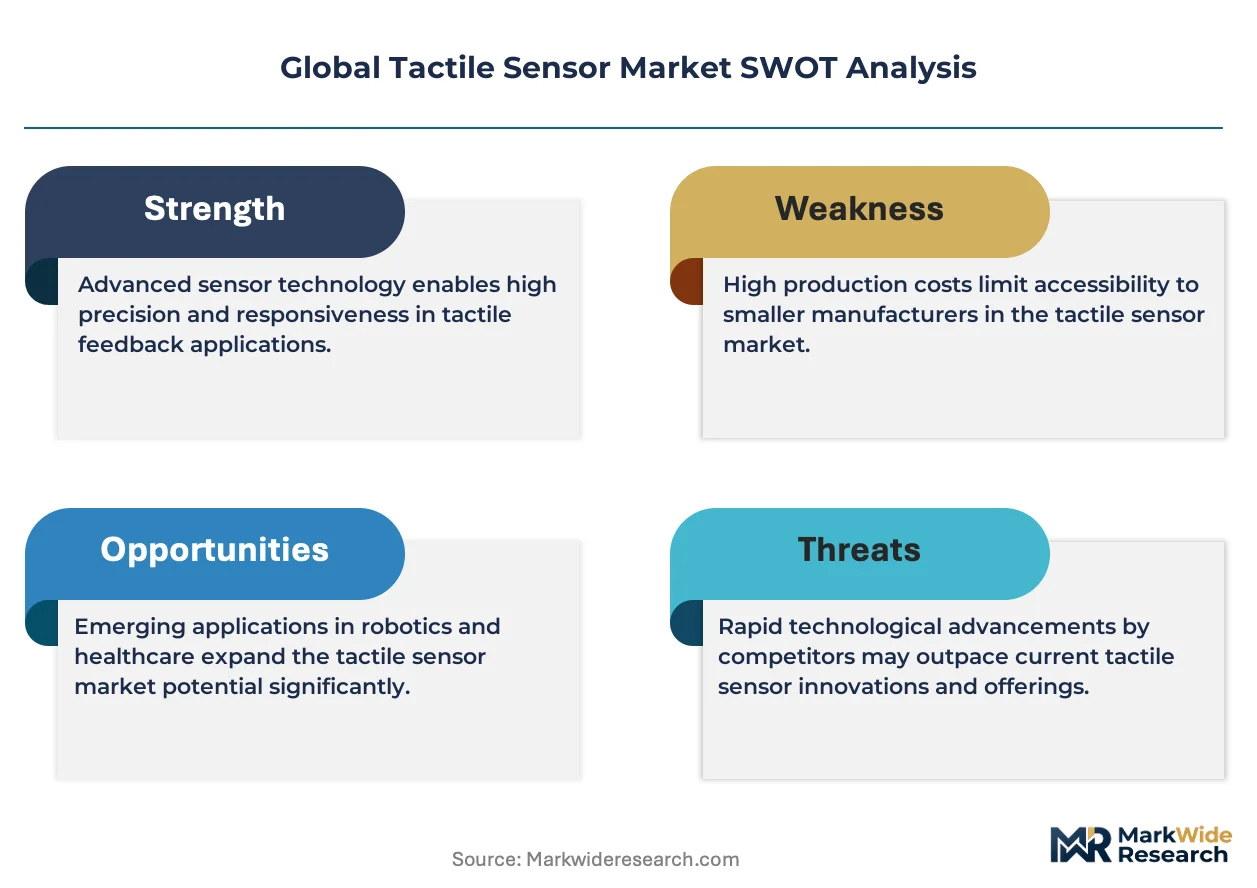
The capability gap between MEMS foundry operators and flexible polymer specialists is collapsing as both camps race toward sub-millimeter spatial resolution. Honeywell International Inc. leverages its aerospace heritage to dominate force-sensitive resistor arrays for safety-critical installations. Synaptics Incorporated anchors its position through capacitive touch controller integration with haptic feedback engines. XELA Robotics differentiates via nanostructured elastomer formulations that achieve multi-modal sensing in soft robotic grippers.
A tactile sensor transduces mechanical contact—pressure, shear, vibration, or temperature—into quantifiable electrical signals through piezoelectric films, conductive elastomer matrices, or optical waveguide deformation, typically resolving forces from millinewtons to hundreds of newtons across spatial densities exceeding one hundred taxels per square centimeter. Capacitive architectures lead consumer electronics deployments where low power and multi-touch recognition dominate design tradeoffs, while piezoelectric variants capture the fastest expansion in robotic manipulation due to dynamic response bandwidth exceeding ten kilohertz. Optical tactile sensing, though presently confined to laboratory and metrology environments, commands the deepest margin pools where GelSight, Inc. occupies a defensible niche in surface topography reconstruction.
FDA device classification for haptic surgical interfaces, the EU AI Act's transparency requirements for autonomous robotic systems, and Japan's METI safety standards for collaborative robots collectively elevate compliance costs while accelerating substitution of legacy switch-based interfaces with compliant tactile arrays. China's NMPA and GB standards for medical electrical equipment impose additional electromagnetic compatibility testing burdens on imported sensor modules. Stakeholders must monitor convergence between ISO robotic safety frameworks and IEC medical device standards as the boundary between industrial automation and clinical assistance dissolves.
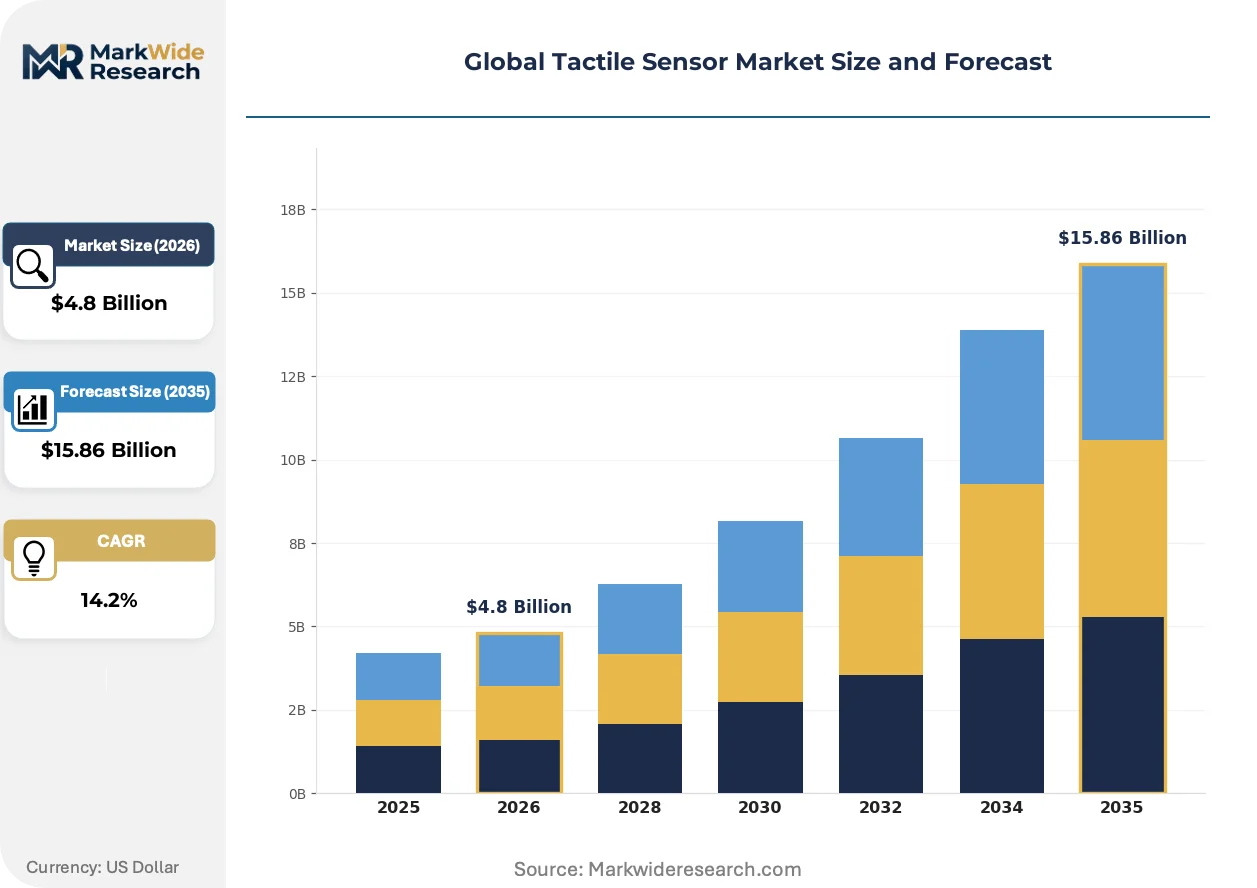
Market Dynamics
The collision between MEMS foundry scaling and flexible polymer innovation is collapsing capability gaps, forcing incumbents to defend haptic integration pipelines against nanostructured elastomer specialists attacking from soft robotics.
Growth Catalysts
- EU AI Act transparency mandates:The EU AI Act's explainability requirements for autonomous robotic systems are accelerating replacement of legacy switch-based interfaces with compliant tactile arrays in collaborative manufacturing.
- Piezoelectric bandwidth expansion:Piezoelectric architectures with dynamic response bandwidth exceeding ten kilohertz are capturing the fastest expansion in robotic manipulation for assembly line precision.
- China's consumer electronics belt:Shenzhen and Dongguan manufacturing clusters are concentrating demand for capacitive multi-touch controllers in wearable device production.
Market Restraints
- Conductive elastomer input volatility:Silver nanoparticle and carbon nanotube feedstock costs fluctuate with semiconductor-grade chemical markets, compressing margins on force-sensitive resistor arrays.
- Optical tactile sensing confinement:GelSight-style optical waveguide deformation systems remain trapped in laboratory and metrology environments due to calibration complexity and unit economics.
- Cross-regional certification stacking:Simultaneous FDA device classification, EU MDR conformity, and China NMPA electromagnetic compatibility testing multiply validation timelines for surgical haptic interfaces.
Strategic Opportunities
- India's precision automation corridor:PLI scheme incentives for industrial robotics are opening white space for taxel-dense sensor arrays in automotive component assembly near Pune and Chennai.
- Capacitive-haptic convergence:Integration of touch controllers with feedback engines creates bundled value propositions for smartphone and automotive dashboard manufacturers.
- Japan's METI collaborative safety standards:Compliance mandates for human-robot proximity sensing are generating regulatory tailwinds for compliant tactile skin deployments in Toyota and Honda production facilities.
Industry Challenges
- Multi-physics simulation talent scarcity:Finite element modeling expertise spanning mechanical, electrical, and thermal domains commands premium compensation, constraining R&D velocity at mid-tier sensor developers.
- Legacy industrial bus integration:Fieldbus and EtherCAT protocol adaptation for real-time tactile data streams requires specialized firmware engineering, extending customer deployment cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Tactile Sensor Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Resistive, Capacitive, Optical, Piezoelectric Application: Consumer Electronics, Robotics, Healthcare, Automotive End User: Manufacturers, Research Institutions, Medical Facilities, Tech Companies Technology: Microelectromechanical Systems, Flexible Sensors, Smart Textiles, Nanostructured Sensors |
| Companies Covered | Touchence Inc., GelSight, Inc., Tekscan, Inc., Honeywell International Inc., Baumer Group, Synaptics Incorporated, XELA Robotics, Omron Corporation, Pressure Profile Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Tactile Sensor Market Strategic Shifts
Material science breakthroughs and regulatory convergence are actively compressing the boundary between industrial automation and clinical assistance, reshaping how tactile data flows through safety-critical systems.
Optical waveguide deformation sensing is supplanting conductive elastomer matrices in surface topography reconstruction applications. Metrology equipment manufacturers and quality assurance departments in German automotive suppliers are adopting GelSight-derived architectures for sub-micron defect detection. This displacement is compressing addressable margins for traditional force-sensitive resistor vendors while opening premium pricing tiers for vision-tactile fusion systems.
REACH substance restrictions on persistent organic pollutants are forcing reformulation of silicone-based sensor skins used in European collaborative robot deployments. Industrial automation OEMs in Stuttgart and Munich are accelerating qualification of fluorine-free elastomer alternatives ahead of 2025 enforcement windows. The medical device segment faces parallel pressure from EU MDR biocompatibility documentation requirements, driving sensor suppliers toward ISO 10993-tested material libraries.
Japanese automotive electronics clusters are consolidating procurement around vertically integrated haptic module suppliers capable of delivering taxel arrays with embedded signal conditioning. Tier-1 suppliers in Toyota City and Hiroshima are rejecting discrete sensor component sourcing in favor of subsystem partnerships that bundle calibration, firmware, and thermal compensation. This concentration is marginalizing standalone MEMS foundries lacking downstream integration capabilities.
Global Tactile Sensor Market Segmentation
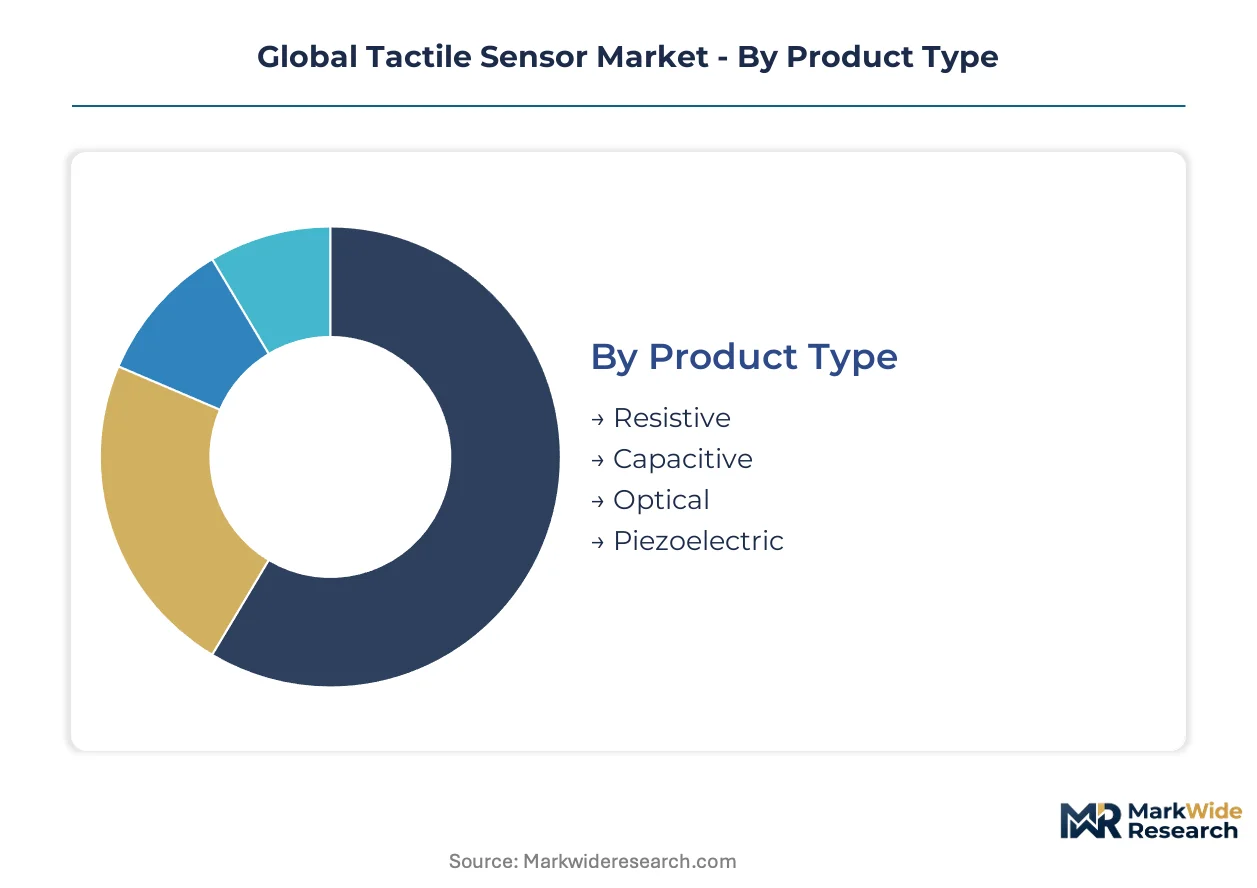
Tactile sensor architectures diverge sharply across force resolution requirements, power budgets, and compliance regimes. Segmentation reveals where MEMS foundry scale competes against nanostructured elastomer flexibility, and which application verticals drive taxel density versus unit cost tradeoffs.
Product Type:
Resistive arrays face acute substitution pressure from piezoelectric and optical alternatives in precision manufacturing, while capacitive dominance in consumer electronics remains structurally entrenched through controller integration economics.
- Resistive:Force-sensitive resistor arrays built on conductive elastomer matrices detect pressure through resistance change in carbon nanotube or silver nanoparticle composites. Demand concentrates in automotive safety-critical installations and legacy industrial automation where cost sensitivity outweighs dynamic response requirements. Automotive suppliers in Stuttgart and Munich favor these for seat occupancy detection despite REACH-driven reformulation costs.
- Capacitive:Capacitive architectures transduce mechanical deformation into measurable capacitance change between parallel plates or interdigitated electrodes. Shenzhen and Dongguan manufacturing clusters drive procurement for smartphone, tablet, and wearable multi-touch controllers where Synaptics and similar vendors bundle haptic feedback engines. Low power consumption and established foundry economics lock in this segment's consumer electronics dominance.
- Optical:GelSight-derived waveguide deformation systems reconstruct surface topography through photometric stereo, commanding metrology applications in German automotive quality assurance despite calibration complexity.
- Piezoelectric:Ceramic or polymer piezoelectric films generate voltage proportional to dynamic strain, capturing robotic manipulation expansion through bandwidth exceeding ten kilohertz.
Capacitive sensors anchor the volume base through consumer electronics procurement scale while piezoelectric variants gain share at the steepest rate via robotic assembly line integration.
Application:
Cost tier stratification separates premium surgical haptic interfaces from commodity touch panels, with regulatory burden intensity determining effective margin capture across verticals.
- Consumer Electronics:Smartphones, tablets, wearables, and automotive dashboards deploy taxel-dense capacitive arrays for gesture recognition and force-touch input. Procurement concentrates in China's Pearl River Delta manufacturing belt where vertically integrated module suppliers bundle calibration and firmware.
- Robotics:Collaborative robots and soft robotic grippers require compliant tactile skin for human proximity detection and delicate object manipulation. Japan's METI safety standards and Toyota production facilities drive compliant array deployments, with XELA Robotics-style nanostructured elastomers penetrating where rigid MEMS fail.
- Healthcare:FDA-classified haptic surgical interfaces and rehabilitation robotics demand ISO 10993-tested materials and electromagnetic compatibility validation. Cross-regional certification stacking elevates compliance costs while opening premium pricing tiers.
- Automotive:Human-machine interface panels, steering wheel controls, and seat occupancy systems split between cost-optimized resistive arrays and capacitive multi-touch controllers. German precision automation corridors favor force-sensitive resistor arrays for safety-critical functions.
Consumer electronics commands the installed base through volume procurement while robotics applications expand most quickly on collaborative automation mandates.
End User:
Customer type determines specification authority—whether procurement flows through OEM engineering teams, institutional research grants, or hospital biomedical departments with divergent validation timelines.
- Manufacturers:Industrial automation OEMs and consumer electronics assemblers specify sensor modules through subsystem partnerships bundling firmware, calibration, and thermal compensation. Tier-1 automotive suppliers increasingly reject discrete component sourcing.
- Research Institutions:University robotics laboratories and national research centers drive early-stage optical tactile sensing adoption for surface topography reconstruction and soft robotics prototyping.
- Medical Facilities:Hospitals and surgical centers procure FDA-validated haptic interfaces through group purchasing organizations, with EU MDR and NMPA electromagnetic compatibility testing multiplying vendor qualification cycles.
- Tech Companies:Platform technology vendors integrate tactile sensing into AR/VR hardware and humanoid robot development programs, prioritizing taxel density and multi-modal fusion capabilities.
Manufacturers anchor procurement volume through production-scale contracts while medical facilities generate the steepest pricing tier on regulatory-validated subsystems.
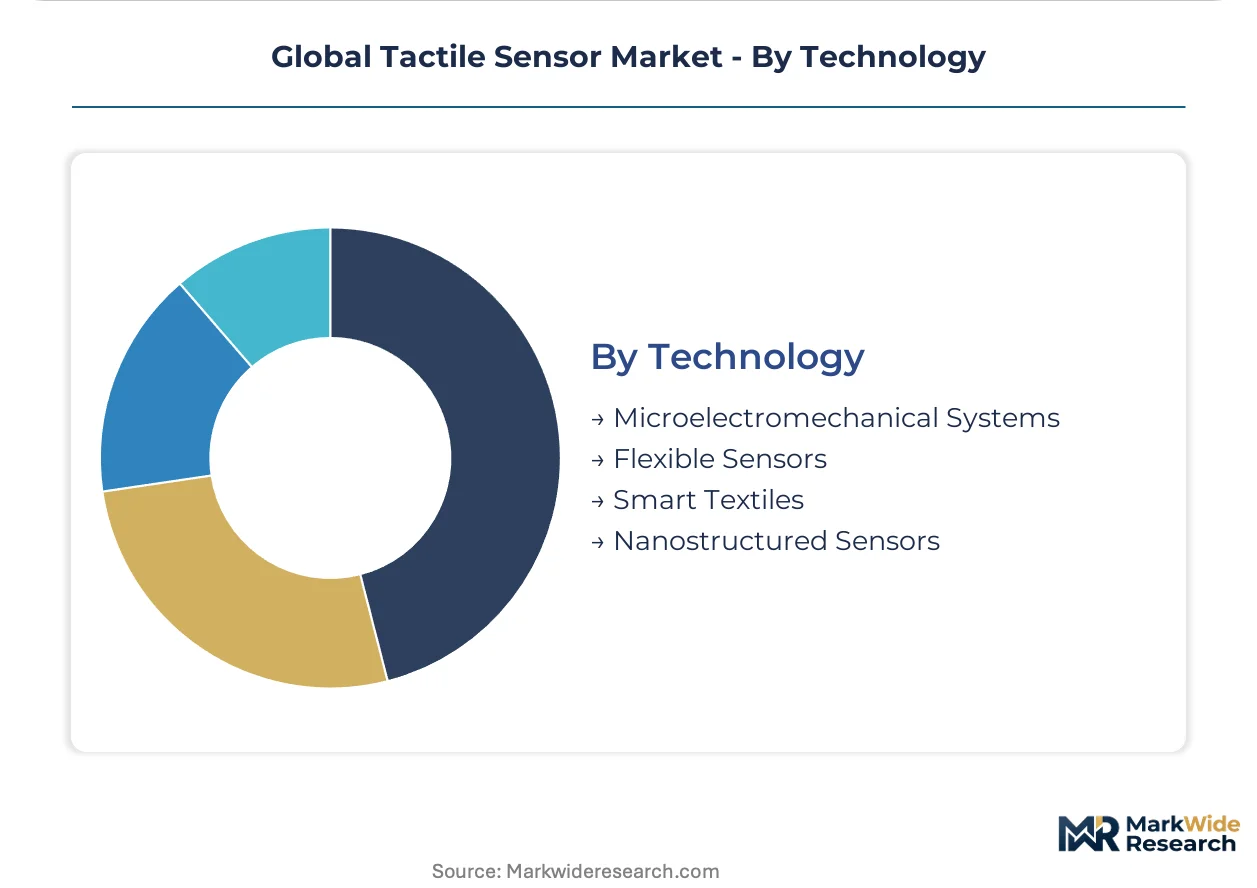
Technology:
Supply concentration in MEMS foundries versus flexible polymer specialists shapes competitive access, with fabrication maturity determining which entrants can achieve sub-millimeter spatial resolution at production economics.
- Microelectromechanical Systems:Silicon-based MEMS fabrication leverages semiconductor foundry scale for piezoelectric and capacitive transducer arrays. Honeywell's aerospace heritage translates into force-sensitive resistor production for safety-critical installations.
- Flexible Sensors:Polyimide, PDMS, and thermoplastic polyurethane substrates enable conformal tactile skin for robotic grippers and wearable devices. REACH substance restrictions on persistent organic pollutants force silicone reformulation ahead of enforcement windows.
- Smart Textiles:Conductive yarn integration and woven electrode arrays embed pressure and stretch sensing into clothing and soft goods for rehabilitation and athletic performance monitoring.
- Nanostructured Sensors:Carbon nanotube networks, graphene foams, and metal nanowire percolation films achieve multi-modal sensing in soft robotic applications where conventional rigid architectures fail.
MEMS technology anchors production volume through foundry economics while nanostructured sensors climb the fastest on soft robotics penetration and material science breakthroughs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China's Pearl River Delta manufacturing belt exhibit extreme price elasticity for capacitive multi-touch controllers, while medical facilities in Germany and Japan absorb substantial premiums for regulatory-validated surgical haptic interfaces. This demand-elasticity contrast shapes regional procurement patterns and vendor qualification timelines.
United States
FDA device classification for haptic surgical interfaces drives premium-tier procurement through hospital group purchasing organizations. The agency's electromagnetic compatibility testing requirements for medical electrical equipment extend vendor qualification cycles. Boston and Minneapolis medical device clusters concentrate demand for ISO 10993-tested tactile subsystems in robotic surgery platforms.
Germany
EU AI Act transparency mandates for autonomous robotic systems accelerate replacement of legacy switch-based interfaces with compliant tactile arrays. ECHA REACH substance restrictions on persistent organic pollutants force silicone-based sensor skin reformulation ahead of enforcement windows. Stuttgart and Munich precision automation corridors favor force-sensitive resistor arrays for automotive safety-critical installations.
China
NMPA electromagnetic compatibility testing burdens multiply validation timelines for imported sensor modules deployed in medical applications. MIIT industrial robot safety standards and GB certification requirements shape domestic procurement specifications. Shenzhen and Dongguan consumer electronics manufacturing clusters concentrate demand for taxel-dense capacitive arrays in smartphone and wearable production.
Japan
METI collaborative robot safety standards generate regulatory tailwinds for compliant tactile skin deployments in automotive production facilities. PMDA device classification parallels FDA frameworks for haptic surgical interfaces, elevating compliance costs for imported subsystems. Toyota City and Hiroshima electronics clusters consolidate procurement around vertically integrated haptic module suppliers bundling calibration and firmware.
India
PLI scheme incentives for industrial robotics open white space for taxel-dense sensor arrays in automotive component assembly. BIS certification requirements for electronic components add domestic testing layers beyond IEC baselines. Pune and Chennai precision automation corridors attract sensor module suppliers targeting cost-optimized resistive arrays for legacy manufacturing upgrades.
Global Tactile Sensor Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with MEMS foundry scale competing against nanostructured elastomer flexibility for sub-millimeter spatial resolution. The vendor base organizes around three strategic archetypes: aerospace-heritage conglomerates with safety-critical installation expertise, capacitive touch controller specialists with haptic feedback integration capabilities, and nanostructured materials startups attacking soft robotics applications. Dominant competitive moves include backward integration into captive elastomer formulation and strategic partnerships bundling firmware, calibration, and thermal compensation.
Among the named participants, Honeywell International Inc. and Synaptics Incorporated exemplify divergent scale-and-specialization strategies, while GelSight, Inc. occupies a defensible laboratory-to-metrology niche in optical waveguide deformation sensing. XELA Robotics represents the nanostructured elastomer specialist archetype, with Omron Corporation and Baumer Group anchoring industrial automation procurement channels. Tekscan, Inc., Pressure Profile Systems, and Touchence Inc. sit within the application-specific sensor array tier, each representing distinct geographic and vertical positioning without overlapping core competencies.
| Leading Market Players |
|---|
| Touchence Inc. |
| GelSight, Inc. |
| Tekscan, Inc. |
| Honeywell International Inc. |
| Baumer Group |
| Synaptics Incorporated |
| XELA Robotics |
| Omron Corporation |
| Pressure Profile Systems |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day calibration lead times for taxel-dense sensor arrays concentrate pricing power with vertically integrated module suppliers in Japan and Germany, while buyers in China's Pearl River Delta manufacturing belt exploit component inventory surpluses to compress force-sensitive resistor margins.
Pricing Analysis
After-sales firmware updates and recalibration service contracts generate lifetime value multiples exceeding initial hardware transaction prices. Three-tier pricing structure across FDA-validated surgical interfaces, industrial automation subsystems, and consumer electronics controllers separates premium compliance-burdened tiers from economy capacitive arrays. Pricing pressure stems from silver nanoparticle feedstock volatility in conductive elastomer formulations. Automotive OEMs in Stuttgart exhibit lowest price sensitivity for safety-critical installations, while smartphone assemblers in Shenzhen drive aggressive unit-cost negotiations.
Supply Chain Analysis
Container availability constraints on the Shanghai-Rotterdam trade lane elevate inbound logistics costs for European industrial automation OEMs sourcing MEMS wafers. Taiwan, South Korea, and Japan anchor piezoelectric ceramic and silicon wafer supply. Conductive elastomer matrices draw from carbon nanotube feedstock concentrated in Chinese chemical processing clusters. Single-source vulnerability pervades nanostructured elastomer formulation expertise. Distribution runs through Tier-1 subsystem partnerships bundling calibration, firmware, and thermal compensation rather than discrete component channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sensor manufacturers capture expanding recurring revenue through cloud-based calibration-as-a-service platforms, where subscription attach rates for haptic firmware updates outpace hardware shipment growth across surgical and collaborative robotics verticals.
For Market Incumbents: Shield installed base relationships by embedding proprietary calibration protocols that raise switching costs for automotive and medical device OEMs. Accelerate backward integration into captive elastomer formulation to offset silver nanoparticle price volatility. Fortify against nanostructured elastomer specialists attacking soft robotics through exclusive subsystem partnerships with Toyota and Honda production facilities.
For New Entrants and Emerging Players: Firmware customization gaps in legacy industrial automation deployments present white-space opportunities for mid-tier sensor developers. India's PLI-subsidized precision automation corridors near Pune and Chennai offer the most penetrable geography for cost-optimized resistive arrays. Pursue hospital system partnerships bypassing GPO procurement channels through direct biomedical engineering engagement.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity play because cross-regional certification stacking elevates compliance costs that favor scaled incumbents with dedicated regulatory affairs infrastructure. Acquisition targets should display ISO 10993-tested material libraries paired with embedded signal conditioning capabilities. Monitor convergence between ISO robotic safety frameworks and IEC medical device standards as the inflection signal for vertical consolidation acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Elastomer Formulation | Captive supply of conductive polymer matrices insulates margin structures from silver nanoparticle commodity volatility. |
| Cloud-Based Calibration-as-a-Service Platform | Recurring firmware subscription revenue attaches to surgical haptic interfaces deployed in Boston medical device clusters. |
| Subsystem Partnership with Tier-1 Automotive Suppliers | Bundled taxel arrays with embedded thermal compensation secure procurement preference in Stuttgart safety-critical installations. |
| ISO 10993 Biocompatibility Certification Investment | Material library qualification opens FDA-validated pricing tiers for haptic surgical interfaces in Minneapolis hospital systems. |
| REACH-Compliant Fluorine-Free Elastomer Development | Reformulation ahead of ECHA enforcement windows defends European collaborative robot deployments from supply disruption. |
Study Parameters
A spread of perspectives from MEMS foundry operations directors, flexible polymer R&D leads, automotive Tier-1 procurement managers, hospital biomedical engineers, and collaborative robot safety compliance officers converged on the working assumptions governing taxel density and force resolution tradeoffs. Primary interview insights triangulated against SEC filings from sensor module suppliers, ECHA REACH substance restriction documentation, FDA 510(k) clearance databases, and METI collaborative robot safety standard drafts. Bottom-up unit economics modeling cross-validated with top-down regional demand aggregation across the analysis window.
Segmentation dimensions modeled span sensor architecture type, application vertical, end-user procurement authority, and fabrication technology platform throughout the forecast period. CAGRs derived from elasticity-adjusted adoption curves incorporating EU AI Act compliance timelines and Japan METI safety standard implementation phases. Price trajectory inputs incorporated silver nanoparticle commodity indices and semiconductor-grade chemical feedstock volatility bands.
Forecasts assume regulatory continuity in FDA device classification, EU MDR conformity assessment, and China NMPA electromagnetic compatibility testing regimes; material policy shifts would require re-modeling adoption timelines for cross-regional surgical haptic interfaces. Technological disruption from optical waveguide deformation sensing or nanostructured elastomer breakthroughs could compress piezoelectric expansion assumptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Latin America Proximity Sensors Market
Sensors and Controls
Rotary Encoders Market
Sensors and Controls
Global Smartphone Sensors Market
Sensors and Controls
United States Pressure Transmitter Market
Sensors and Controls
Global Acceleration and Yaw Rate Sensors Market
Sensors and Controls
Multi-Axis Sensor Market
Sensors and Controls
Photodiode Sensors Market
Sensors and Controls
Nano Positioning System Market
Sensors and Controls
Meteorological Equipment Market
Sensors and Controls
Europe Optical Sensors Market
Sensors and Controls
Wireless Pressure Sensors Market
Sensors and Controls
Semiconductor Pyrometers Market
Sensors and Controls
Digital Angle Gauge Market
Sensors and Controls
Chest Sensors Market
Sensors and Controls
Ceramic Transducers Market
Sensors and Controls
Manifold Absolute Pressure Sensor Market