
 Wearable IP Camera Market | 2026-2036
Wearable IP Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Wearable IP Camera Market Insights
Law enforcement procurement is unwinding legacy analog dependencies as security personnel and healthcare professionals emerge as faster-growing buyer archetypes. Axon Enterprise anchors the body-worn segment through captive software-hardware integration and evidence-management ecosystems. GoPro Inc. competes in the action camera tier by leveraging consumer brand recognition and ruggedized industrial crossover designs. Reveal Media Limited specializes in European public-sector compliance, navigating divergent national data-retention mandates across member states.
Wearable IP cameras combine miniature CMOS sensors, H.265 encoding chipsets, and IP-rated enclosures into devices that stream or store audiovisual evidence for security, recreation, and clinical documentation. Body cameras dominate institutional procurement volumes due to mandatory deployment statutes, while smart glasses capture expanding margin pools in hands-free industrial inspection and surgical training workflows. Edge computing deployments are accelerating among law enforcement end users seeking localized redaction and chain-of-custody controls before cloud upload.
FCC certification governs radio-frequency transmission in US devices, while GDPR and the EU AI Act constrain biometric analytics and automated facial recognition in European deployments. FDA oversight applies to clinical-grade smart glasses used in surgical settings, distinguishing medical devices from consumer electronics in channel access and liability frameworks. Stakeholders must weigh 5G module costs against real-time command-center integration requirements as procurement standards diverge between cloud-native and hybrid deployment models.
Market Dynamics
Law enforcement agencies are dismantling analog evidence systems under pressure from judicial review panels mandating tamper-proof digital audit trails. This institutional pivot is compressing procurement cycles and elevating software-integrated hardware bundles over standalone camera sales.
Growth Catalysts
- Mandatory body-worn camera statutes:US state legislatures and EU member-state policing oversight bodies now require continuous audiovisual documentation during citizen interactions, creating non-discretionary procurement pipelines.
- 5G network densification:Real-time streaming to command centers is replacing store-and-forward workflows, with telecommunications infrastructure investments enabling sub-100-millisecond latency thresholds for field evidence transmission.
- Healthcare documentation protocols:Surgical training programs and clinical observation workflows are adopting smart glasses for first-person procedural capture, expanding addressable demand beyond security applications.
Market Restraints
- CMOS sensor supply concentration:Advanced image sensor fabrication clusters in Taiwan and South Korea expose camera assemblers to geopolitical transit risks and foundry allocation constraints.
- GDPR biometric analytics prohibitions:The EU AI Act's restrictions on automated facial recognition in public spaces limit software feature monetization and force localized processing architectures.
- Lithium-polymer battery cost volatility:Raw material price swings for cobalt and nickel inputs compress hardware margins and complicate long-term municipal contract pricing.
Strategic Opportunities
- German industrial safety mandates:Factory inspection protocols under national occupational safety frameworks are mandating hands-free documentation, opening smart glasses penetration in manufacturing quality assurance.
- Edge-to-cloud hybrid architectures:Convergence of localized AI redaction chipsets with encrypted cloud evidence repositories enables tiered service offerings across budget-constrained and premium procurement segments.
- Direct-to-agency digital distribution:Bypassing traditional security equipment distributors through manufacturer-hosted procurement portals captures margin and accelerates firmware update deployment cycles.
Industry Challenges
- FCC Part 15 certification timelines:Radio-frequency emission testing for 5G-enabled units extends product launch windows by four to six months, delaying revenue recognition against municipal fiscal calendars.
- Chain-of-custody software integration:Legacy evidence management systems in county prosecutor offices require expensive API development and data migration services to accommodate new hardware formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wearable IP Camera Market |
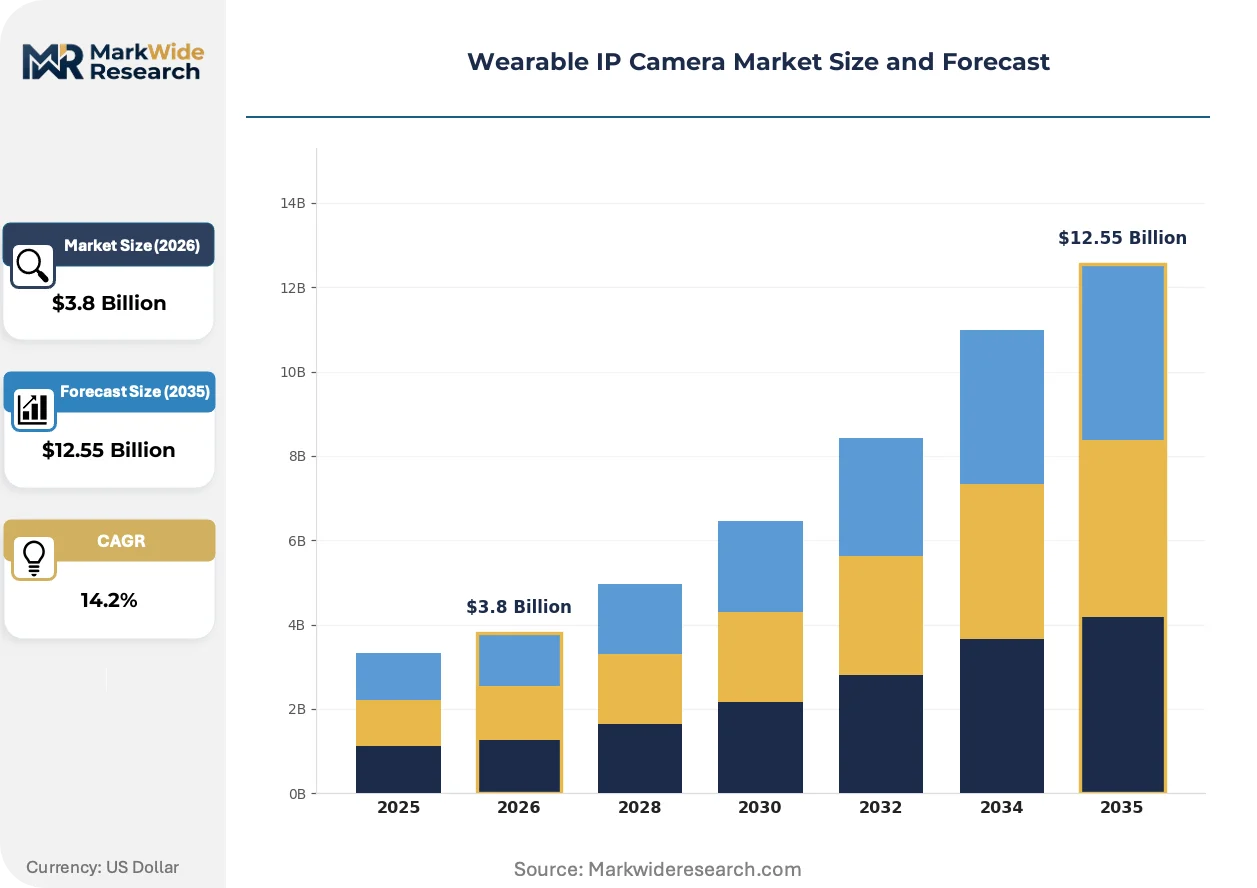
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Body Cameras, Action Cameras, Smart Glasses, Smart Watches Deployment Model: Cloud-based, Edge Computing, On-premises, Hybrid End User: Security Personnel, Outdoor Enthusiasts, Law Enforcement, Healthcare Professionals Technology: Wi-Fi, Bluetooth, 4G LTE, 5G |
| Companies Covered | Axon Enterprise, Inc., GoPro Inc., Sony Corporation, Panasonic Corporation, Garmin Ltd., Xiaomi, Arlo, Nest, Reveal Media Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wearable IP Camera Market Trends and Innovations
Sensor packaging and encoding silicon are undergoing dimensional compression that is redrawing competitive boundaries between consumer electronics crossovers and purpose-built security hardware. These shifts are elevating software-defined feature differentiation over raw optical specifications.
Multi-layer ceramic capacitor arrays and system-in-package designs are miniaturizing power management and image signal processing into sub-5-gram modules. Police departments in Texas and Florida are fast-tracking trials of shirt-clip and eyeglass-integrated form factors that eliminate chest-mounted harnesses. This dimensional compression is collapsing the traditional segmentation between body-worn and consumer action camera categories, forcing vendors to compete on evidence-authentication software rather than hardware ruggedization alone.
The EU AI Act's prohibitions on real-time biometric identification in publicly accessible spaces are redirecting R&D investment toward privacy-preserving edge analytics. Camera firmware must now perform automated redaction of bystander faces before any cloud transmission, adding computational load and thermal design constraints. European public-sector tenders are increasingly specifying on-device processing as a mandatory technical requirement, disadvantaging cloud-native hardware architectures.
Municipal procurement officers are consolidating vendor relationships through multi-year evidence-management subscriptions rather than transactional hardware purchases. Single-source contracts bundling cameras, cloud storage, and audit-trail software are displacing best-of-breed component assembly. This preference consolidation is most pronounced in California and New York metropolitan police departments, where IT security reviews favor integrated stacks over interoperability complexity.
Wearable IP Camera Market Segmentation
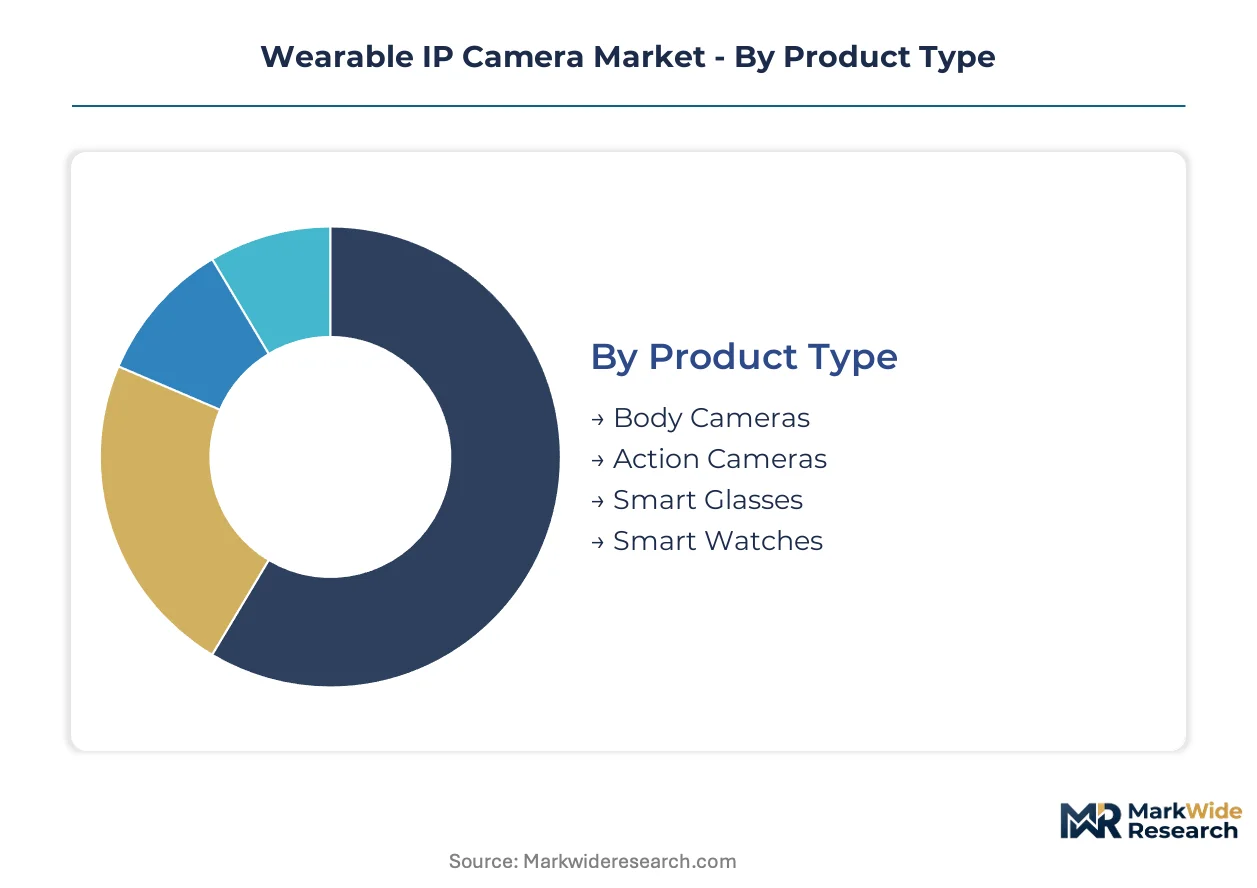
Product architecture and connectivity standards fragment procurement requirements across security, healthcare, and consumer verticals. Deployment model selection dictates evidence-chain compliance and infrastructure investment trajectories. End-user specialization determines form-factor priorities and software integration depth.
Product Type:
Substitution pressure from adjacent consumer electronics categories intensifies as ruggedized smartphones and helmet-mounted displays encroach on dedicated camera territory.
- Body Cameras:Chest-mounted or shoulder-clip devices integrate tamper-evident housing with AES-256 encryption and automated metadata tagging. Metropolitan police departments in California and New York mandate these units under state-level transparency statutes, with procurement concentrating on evidence-authentication software bundles rather than hardware specifications alone.
- Smart Glasses:Optical waveguide displays combined with forward-facing CMOS sensors enable hands-free documentation in surgical training and industrial inspection workflows. German manufacturing quality-assurance protocols under national occupational safety frameworks are accelerating adoption in factory floor environments where manual camera operation disrupts precision tasks.
- Action Cameras:Ruggedized enclosures with wide-angle lenses and electronic image stabilization target outdoor recreation and crossover industrial applications.
- Smart Watches:Wrist-worn form factors with embedded cameras serve discrete documentation needs in clinical observation and personal security contexts.
Body cameras anchor the volume base while smart glasses gain share at the steepest rate.
Deployment Model:
Cost tier stratification separates premium integrated-stack contracts from budget-constrained standalone hardware purchases.
- Cloud-based:Encrypted transmission to remote evidence repositories enables centralized audit-trail management and multi-jurisdictional data sharing. FCC Part 15 certification requirements for radio-frequency emission testing extend launch timelines by four to six months for US municipal contracts.
- Hybrid:Localized AI redaction chipsets perform automated bystander face blurring before cloud upload, satisfying GDPR and EU AI Act prohibitions on biometric analytics in European public-sector tenders. This architecture commands premium pricing in German and French procurement cycles where privacy-preserving edge processing is mandatory.
- Edge Computing:On-device processing architectures minimize latency for real-time command-center streaming in tactical law enforcement scenarios.
- On-premises:Air-gapped storage systems serve agencies with stringent data sovereignty requirements or classified operational mandates.
Cloud-based deployments dominate municipal contract value while hybrid architectures are expanding most quickly in European compliance-driven markets.
End User:
Customer type divergence separates institutional procurement cycles with multi-year software subscriptions from transactional consumer purchases.
- Law Enforcement:Mandatory deployment statutes under US state legislatures and EU policing oversight bodies create non-discretionary procurement pipelines with evidence-management ecosystem lock-in. Chain-of-custody software integration with legacy county prosecutor systems requires expensive API development and data migration services.
- Healthcare Professionals:Surgical training programs and clinical observation workflows adopt smart glasses for first-person procedural capture, with FDA oversight distinguishing medical devices from consumer electronics in channel access and liability frameworks.
- Security Personnel:Private-sector guarding contracts prioritize real-time streaming to centralized monitoring stations over evidence-chain authentication features.
- Outdoor Enthusiasts:Consumer recreation demand concentrates on ruggedization and content-sharing ecosystem compatibility rather than compliance documentation.
Law enforcement anchors the volume base while healthcare professionals are climbing the fastest as training program digitization accelerates.
Technology:
Maturity gradients separate established connectivity standards from next-generation infrastructure dependencies.
- 5G:Sub-100-millisecond latency thresholds enable real-time field evidence transmission to command centers, with telecommunications infrastructure densification in North American metropolitan areas driving module integration. Lithium-polymer battery cost volatility for cobalt and nickel inputs compresses hardware margins and complicates long-term municipal contract pricing.
- Wi-Fi:Local area network dependency suits controlled-environment deployments in healthcare facilities and indoor security operations where cellular coverage is unreliable or prohibited.
- 4G LTE:Mature cellular infrastructure supports store-and-forward workflows in jurisdictions with incomplete 5G rollout.
- Bluetooth:Short-range pairing protocols enable peripheral connectivity for body-worn sensors and secondary audio capture devices.
Wi-Fi retains installed-base dominance in facility-bound applications while 5G is gaining share fastest in field-deployed law enforcement units.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CMOS sensor fabrication clusters in Taiwan and South Korea concentrate upstream supply, while procurement demand fragments across metropolitan police departments and federal security contracts in North America, European compliance-driven markets, and German industrial safety applications.
United States
Metropolitan police departments in California and New York drive institutional procurement volumes under state-level transparency statutes mandating body-worn camera deployment. FCC Part 15 certification requirements for radio-frequency emission testing extend product launch timelines by four to six months for municipal contracts. Texas and Florida police departments are fast-tracking trials of shirt-clip and eyeglass-integrated form factors that eliminate traditional chest-mounted harnesses.
Germany
National occupational safety frameworks are mandating hands-free documentation in factory inspection protocols, accelerating smart glasses penetration in manufacturing quality assurance. GDPR and the EU AI Act constrain biometric analytics and automated facial recognition, forcing localized processing architectures in public-sector tenders. Industrial clusters in Bavaria and Baden-Württemberg are specifying on-device redaction as a mandatory technical requirement for procurement cycles.
United Kingdom
Police oversight bodies are expanding body-worn camera programs under judicial review panel mandates, creating non-discretionary procurement pipelines for law enforcement agencies. Reveal Media Limited specializes in navigating divergent national data-retention mandates across EU member states from its UK base. London metropolitan procurement officers are consolidating vendor relationships through multi-year evidence-management subscriptions rather than transactional hardware purchases.
China
Domestic manufacturers supply cost-optimized CMOS sensors and encoding chipsets to global camera assemblers, though geopolitical transit risks expose supply chains to foundry allocation constraints. MIIT certification governs radio-frequency transmission standards for devices manufactured and deployed domestically. Shenzhen and Dongguan industrial clusters concentrate final assembly operations for export-oriented action camera production.
France
CNIL enforcement of GDPR provisions is redirecting R&D investment toward privacy-preserving edge analytics in public-sector camera deployments. French procurement tenders increasingly specify on-device processing as mandatory, disadvantaging cloud-native hardware architectures. The Île-de-France region anchors demand from federal security contracts requiring hybrid edge-to-cloud architectures with automated bystander face blurring before transmission.
Wearable IP Camera Market Competitive Landscape
Concentration sits with integrated-stack providers bundling hardware, evidence-management software, and cloud storage subscriptions. The vendor base stratifies across three tiers: captive ecosystem players with end-to-end platform control, ruggedized electronics specialists leveraging consumer brand recognition for industrial crossover, and regional compliance specialists navigating jurisdiction-specific data-retention mandates. Dominant competitive moves include direct-to-agency digital distribution bypassing traditional security equipment distributors, and strategic partnerships with telecommunications infrastructure providers for 5G-enabled real-time streaming integration.
Within the integrated-stack tier, Axon Enterprise anchors the body-worn segment through captive software-hardware integration. Among ruggedized electronics specialists, GoPro Inc. occupies a position exemplifying consumer brand recognition leveraged for industrial crossover designs. On the regional compliance vector, Reveal Media Limited represents specialists navigating divergent national data-retention mandates across European member states. These three players collectively illustrate the strategic archetypes reshaping competitive positioning: platform lock-in through evidence-management ecosystems, brand-driven category expansion, and regulatory-navigation specialization.
| Leading Market Players |
|---|
| Axon Enterprise, Inc. |
| GoPro Inc. |
| Sony Corporation |
| Panasonic Corporation |
| Garmin Ltd. |
| Xiaomi |
| Arlo |
| Nest |
| Reveal Media Limited |
| Others |
Pricing and Supply Chain Analysis
Foundry-scale economies in CMOS sensor fabrication concentrate cost leverage among Taiwan and South Korean producers, compressing margin floors for camera assemblers while elevating pricing power for component suppliers. Municipal procurement officers and federal security contractors face divergent cost structures as volume-tiered software subscriptions displace transactional hardware purchases.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates evidence-management ecosystem bundles from standalone hardware and consumer-grade action units. Price differentiation hinges on FCC certification grade for US municipal contracts and GDPR-compliant edge-processing architectures for European tenders. Pricing pressure stems from lithium-polymer battery cost volatility in cobalt and nickel inputs, tightening margins on 5G-enabled field units. Federal security contractors exhibit lowest price sensitivity due to mission-critical mandates, while county-level police departments face strict fiscal-year constraints.
Supply Chain Analysis
Strategic stockpiling of CMOS sensors and encoding chipsets dominates procurement strategy among camera assemblers seeking insulation from foundry allocation constraints. Supply concentrates in Taiwan and South Korea for advanced image sensors, with China anchoring final assembly operations and domestic component supply. Raw material dependencies include cobalt and nickel for battery cells, rare earth elements for magnet assemblies, and multi-layer ceramic capacitors for power management modules. Single-source vulnerability in Taiwanese foundry capacity exposes assemblers to geopolitical transit risks. Distribution runs through manufacturer-hosted procurement portals and traditional security equipment distributors serving municipal IT departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: evidence-management ecosystem lock-in creates prohibitive switching costs for law enforcement agencies migrating legacy chain-of-custody systems.
For Market Incumbents: Consolidate through captive software-hardware integration deepening evidence-authentication moats against consumer-electronics crossovers. Axon Enterprise's platform model demonstrates how vertical integration into cloud storage and audit-trail software displaces best-of-breed component assembly. Prioritize API development resources for legacy county prosecutor system integration, as migration friction anchors multi-year subscription renewals. For New Entrants and Emerging Players: Differentiate on privacy-preserving edge analytics compliant with GDPR and EU AI Act biometric prohibitions, where cloud-native incumbents face architectural disadvantage. German industrial safety mandates for hands-free factory documentation represent the most penetrable white-space segment, with smart glasses penetration accelerating under national occupational safety frameworks. Pursue direct-to-agency digital distribution bypassing traditional security equipment channels to capture margin and accelerate firmware deployment cycles. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated-stack providers bundling hardware, evidence-management software, and cloud storage subscriptions. Long-term viability over a multi-year horizon favors vendors with telecommunications infrastructure partnerships enabling 5G-enabled real-time streaming integration. Target acquisition profiles center on regional compliance specialists navigating divergent national data-retention mandates across European member states. The signal to watch is municipal procurement consolidation toward single-source contracts, which accelerates vendor attrition and platform concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Evidence-management ecosystem lock-in displaces standalone hardware procurement in California and New York metropolitan police departments. |
| Regulatory Compliance Investment | GDPR and EU AI Act-aligned edge-processing architectures command premium positioning in German and French public-sector tenders. |
| Telecommunications Partnership | 5G infrastructure integration enables sub-100-millisecond latency for real-time command-center streaming in tactical law enforcement scenarios. |
| Direct-to-Agency Distribution | Manufacturer-hosted procurement portals capture margin and accelerate firmware update deployment cycles bypassing traditional distributors. |
| Geographic Manufacturing Footprint | Taiwanese and South Korean foundry relationships secure CMOS sensor allocation amid geopolitical transit risk exposure. |
Research Methodology
Desk research of FCC certification filings, SEC 10-K hardware segment disclosures, and European public-sector tender databases preceded structured interviews with municipal procurement officers, evidence-management software architects, and telecommunications infrastructure planners. Primary fieldwork with body-worn camera program administrators in Texas and Florida police departments, plus smart glasses adoption leads in German manufacturing quality-assurance roles, validated secondary demand signals. Bottom-up unit shipment modeling across product type, deployment model, and end-user segments triangulated against top-down addressable market sizing from law enforcement agency headcount and mandatory deployment statute coverage.
Variance decomposition across the projection horizon isolates volume drivers from pricing and mix effects, with CAGRs derived from segment-level growth rate reconciliation. Segmentation dimensions modeled include product architecture, connectivity standard, deployment model, and end-user specialization. Industry-specific forecast inputs incorporate 5G network densification timelines and municipal fiscal calendar alignment for procurement cycle recognition.
Forecasts assume regulatory continuity in FCC Part 15 certification regimes and GDPR enforcement patterns; material policy shifts in biometric analytics prohibitions or radio-frequency emission standards would require re-modeling. Revision becomes warranted when lithium-polymer battery cost volatility or foundry allocation constraints cross thresholds that compress hardware margins below sustainable municipal contract pricing floors.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
North America Digital Camera Market
Imaging
360-Degree Camera Market
Imaging
Asia Pacific IP Camera Market
Imaging
Global in Ceiling Camera Market
Imaging
Ent Cameras Market
Imaging
Multimodal Imaging Market
Imaging
Global Trail Camera Market
Imaging
Global AI in Computer Vision Market
Imaging
Europe Hyperspectral Imaging Market
Imaging
China Electron Microscopy Market
Imaging
Camera Lens Market
Imaging
Microscopic Camera Market
Imaging
Frame Grabber Market
Imaging
Compact Camera Module Market
Imaging
Near Infra-Red Imaging Market
Imaging
Microwave Imaging Market